
 Homeopathy Products Market | 2026-2036
Homeopathy Products Market Size, Share, and Industry Trends Forecast 2026-2036
Homeopathy Products Market Intelligence
The FDA's risk-based enforcement policy for unapproved homeopathic drugs is pivoting the industry toward more rigorous evidence standards and transparent consumer labeling. Boiron leverages its extensive global distribution network to navigate these diverse regulatory environments. Hyland’s Inc. specializes in products for pediatric and family wellness, building strong brand loyalty. Dr Reckeweg & Co differentiates through its portfolio of specific combination remedies.
Homeopathy products are therapeutic preparations derived from natural substances through a process of serial dilution and succussion. These formulations operate on the principle of 'like cures like' to address health issues by stimulating the body’s healing response. Pellets and liquid dilutions represent the most established product types, forming the backbone of practitioner and consumer use. Demand is particularly strong for applications in mental wellness and respiratory disorders, driven by consumer preference for alternative treatments.
Regulatory oversight is highly fragmented, with the US FDA, European Medicines Agency (EMA), and India's Ministry of AYUSH each enforcing distinct rules. These national frameworks govern everything from manufacturing practices to the health claims permitted on product labels. Successfully scaling operations depends on a company's ability to manage this complex and often contradictory compliance landscape.
Market Dynamics
The homeopathy products market is defined by the tension between rising consumer demand for natural wellness alternatives and intensifying regulatory pressure for evidence-based claims. This dynamic forces manufacturers to balance traditional principles with modern standards for safety and transparency.
Growth Catalysts
- Government Support in India:India's Ministry of AYUSH actively promotes traditional and alternative medicine systems, including homeopathy, through public funding and integration into the national healthcare framework, sustaining high domestic consumption.
- Consumer Shift to Alternative Wellness:A growing consumer preference for non-pharmaceutical approaches, particularly for chronic conditions, mental wellness, and respiratory ailments, drives adoption as a complementary or primary treatment option.
- E-commerce Channel Expansion:The proliferation of online pharmacies and direct-to-consumer websites makes homeopathic products more accessible to a broader audience, bypassing the need for specialized physical retail stores.
Market Restraints
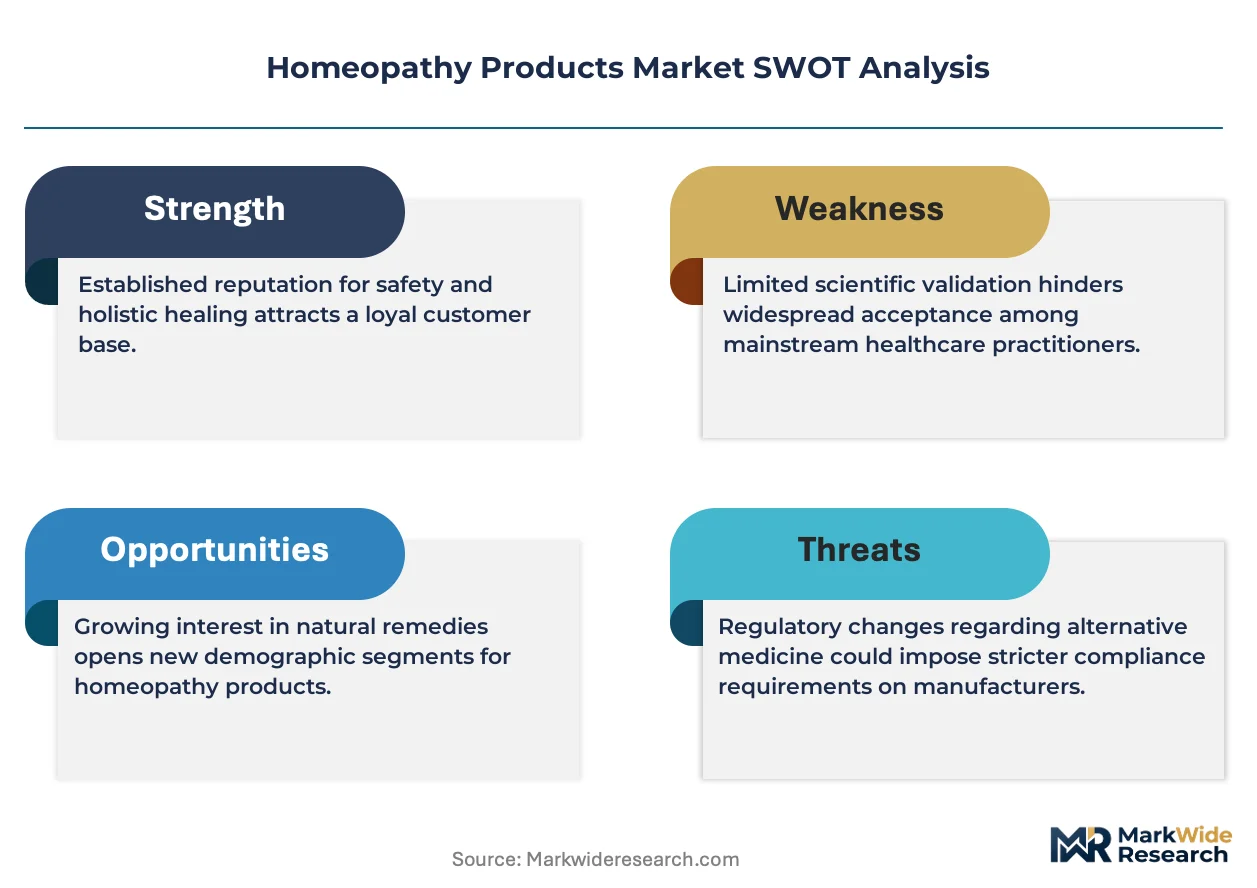
- Scientific Skepticism:Widespread skepticism within the conventional medical community regarding the mechanism of action of highly diluted remedies limits mainstream acceptance, physician referrals, and insurance coverage.
- Stringent Regulatory Scrutiny:The FDA's risk-based enforcement policy for unapproved homeopathic drugs creates significant compliance uncertainty and restricts the health claims manufacturers can make on product labels in the US.
- Competition from Substitutes:The market faces strong competition from evidence-backed herbal supplements, nutraceuticals, and conventional over-the-counter (OTC) medications that offer similar perceived benefits for common ailments.
Strategic Opportunities
- Integration into Preventative Health:Positioning homeopathic products not just for acute treatment but as part of a holistic, preventative wellness routine offers a significant avenue for market expansion, especially within the self-care segment.
- Market Development in Latin America:Countries such as Brazil and Mexico represent underpenetrated markets with a cultural affinity for natural medicine, offering growth potential for established brands from Europe and India.
- Personalized Medicine Formulations:Advances in diagnostic tools and digital health platforms create an opportunity to develop and market personalized homeopathic remedies tailored to an individual’s specific symptoms and constitution.
Industry Challenges
- Fragmented Global Regulations:Manufacturers face the operational challenge of aligning product formulation, labeling, and marketing with disparate and often conflicting rules set by the FDA, EMA, and India's Ministry of AYUSH.
- Lack of Manufacturing Standardization:The absence of universally accepted Good Manufacturing Practices (GMP) specific to homeopathic dilution and succussion processes leads to inconsistencies in product quality and potency.
- Practitioner Skill Gaps:A shortage of formally trained and certified homeopathic practitioners in key Western markets limits professional endorsement channels, hindering deeper market penetration and consumer trust.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Homeopathy Products Market |
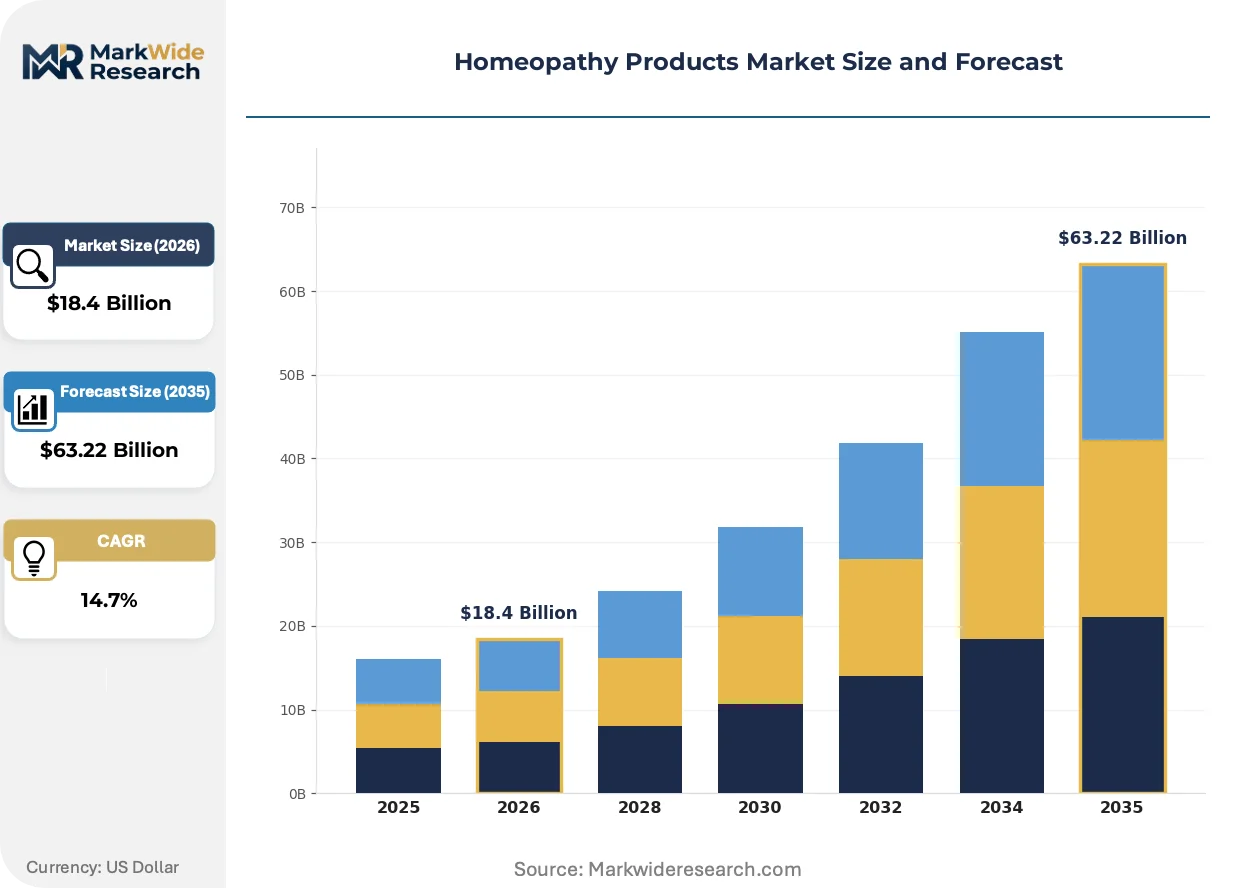
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $63.22 Billion |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pellets, Tablets, Liquid Dilutions, Creams, Gels, Drops Application Area: Respiratory Disorders, Digestive Issues, Skin Conditions, Mental Wellness, Immune Support, Musculoskeletal Pain End User: Home Treatment Users, Wellness Clinics, Complementary Medicine Centers, Alternative Therapy Practitioners Distribution Channel: Pharmacies, Online Retailers, Health Stores, Direct Sales, Specialty Clinics |
| Companies Covered | A Nelson & Co Ltd, Hyland’s Inc., Boiron, Dr Reckeweg & Co, Hevert-Arzneimittel GmbH, Dr Willmar Schwabe GmbH & Co KG, SBL, Homeocan, Biologische Heilmittel Heel GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Homeopathy Products Market Strategic Shifts & Innovations
Digitalization and a push for greater product transparency are fundamentally altering how consumers interact with homeopathy. The industry is moving from a practitioner-centric model toward direct-to-consumer engagement, supported by digital tools and clearer product information.
Digital health platforms designed for symptom analysis and remedy selection are gaining traction. Younger consumers are increasingly adopting these mobile applications for self-guided care, bypassing traditional consultations. This digital-first approach is expanding into personalized wellness programs that integrate homeopathic recommendations with nutrition and lifestyle coaching.
The European Medicines Agency (EMA) continues to refine its guidance for traditional and homeopathic medicinal products, demanding more rigorous quality and safety data. This regulatory pressure compels manufacturers to invest in better documentation and quality control systems for product registration. Combination remedies with specific therapeutic claims are most affected, pushing some producers toward simpler, single-ingredient formulations with less restrictive labeling.
Consumer purchasing behavior is shifting decisively toward online channels. Direct-to-consumer (DTC) websites and third-party e-commerce platforms are displacing traditional pharmacies and practitioner offices as the primary point of sale. This trend disintermediates the practitioner's role as a gatekeeper and is most visible in North American and European markets with mature digital retail infrastructures.
Homeopathy Products Market Segmentation
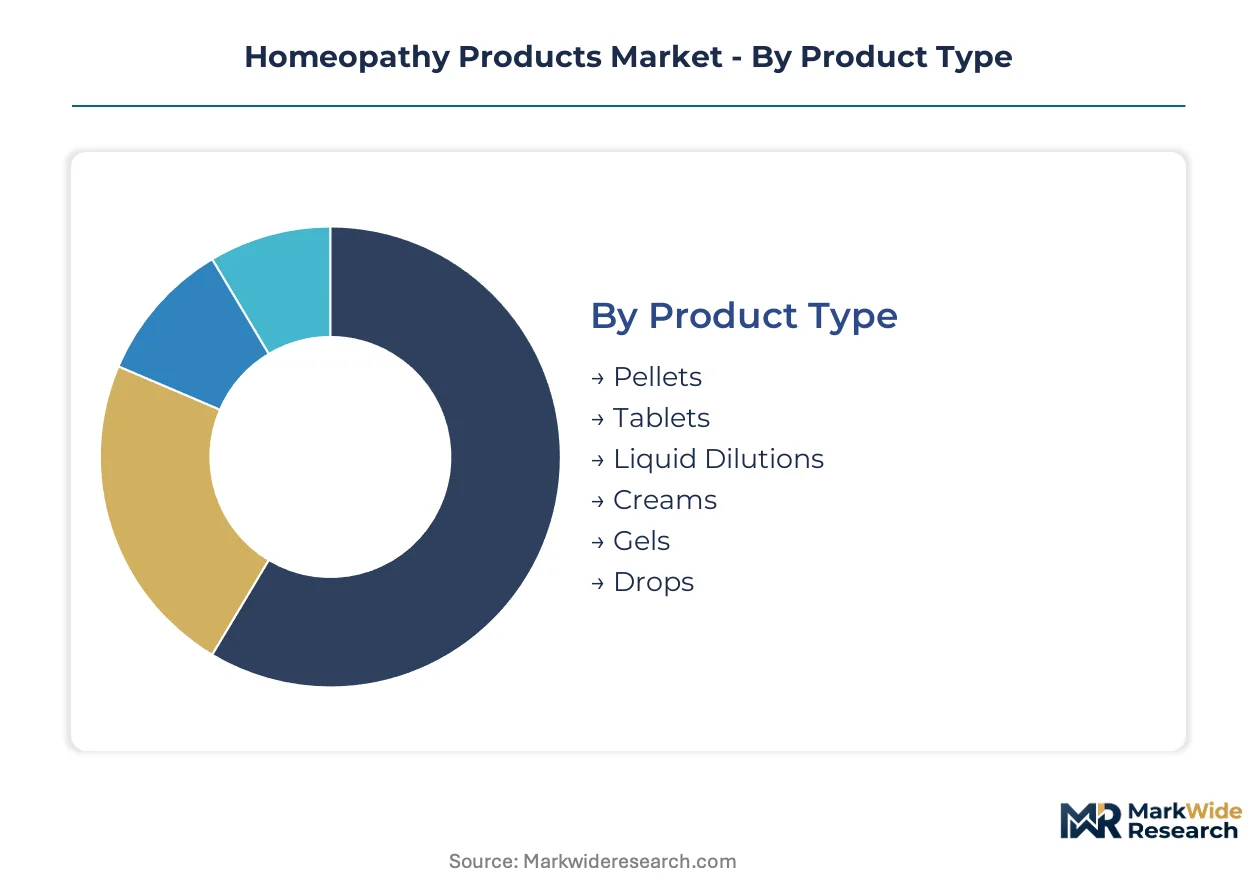
Understanding the distinct segments within the homeopathy products market is crucial for manufacturers to tailor their product development and market penetration strategies effectively. This segmentation highlights the diverse preferences and needs of consumers and practitioners, influencing product formulation, claims, and distribution channels across various geographies.
Product Type:
Consumer preferences for ease of administration and traditional usage patterns define the segmentation by product type.
- Pellets:These small, sugar-based spheres are infused with homeopathic dilutions, representing a traditional and widely accepted form for oral administration. Demand for pellets remains robust in India, where government support sustains their widespread availability and use.
- Liquid Dilutions:Alcohol or water-based preparations, liquid dilutions allow for precise dosing and are often favored by practitioners for customized remedies. Their use is particularly concentrated in Europe, driven by established practitioner networks and historical usage.
- Tablets:Compressed solid forms offer convenience and portability, appealing to consumers seeking easy-to-carry options for daily wellness routines.
- Creams:Topical applications for skin conditions and localized pain relief provide a non-oral option, gaining traction in markets with a focus on external remedies.
- Gels:Similar to creams, gels offer a different texture for topical application, often preferred for their faster absorption and non-greasy feel in specific dermatological uses.
- Drops:Liquid preparations administered in small quantities, drops are suitable for both internal use and for infants or individuals with difficulty swallowing.
Pellets leads on scale; Liquid Dilutions leads on momentum.
Application Area:
The specific health concerns consumers seek to address with homeopathic remedies drive the market's application area segmentation.
- Mental Wellness:Homeopathic remedies for stress, anxiety, and sleep disorders represent a significant and expanding segment, particularly among consumers seeking non-pharmaceutical alternatives. This application area experiences strong demand in North American and European markets as consumer interest in holistic mental health solutions grows.
- Respiratory Disorders:Products targeting coughs, colds, and allergies form a foundational segment, driven by persistent demand for natural symptom relief. The widespread prevalence of respiratory ailments ensures consistent consumption across all major markets.
- Digestive Issues:Remedies for indigestion, bloating, and other gastrointestinal discomforts cater to a broad consumer base seeking gentle interventions.
- Skin Conditions:Homeopathic preparations for eczema, acne, and minor irritations offer alternative care options, attracting users wary of conventional topical treatments.
- Immune Support:Products aimed at strengthening the body's natural defenses appeal to health-conscious individuals prioritizing preventative wellness.
- Musculoskeletal Pain:Remedies for joint pain, muscle aches, and stiffness provide complementary relief, often used by active individuals or those with chronic conditions.
The market sees Mental Wellness as foundational, while Respiratory Disorders drives significant innovation.
End User:
Consumption patterns and access points differentiate the market by end-user categories, reflecting varied engagement with homeopathic products.
- Home Treatment Users:Individuals who purchase homeopathic products directly for self-care and minor ailments without professional consultation constitute the largest end-user group. This segment is particularly robust in countries with strong direct-to-consumer e-commerce channels, such as the United States.
- Wellness Clinics:Facilities offering a range of holistic health services, including homeopathy, integrate these products into broader treatment plans. These clinics serve as important professional endorsement channels in European markets.
- Complementary Medicine Centers:Specialized centers that combine conventional and alternative therapies utilize homeopathic remedies as part of integrated patient care. These centers often cater to patients seeking comprehensive, personalized treatment approaches.
- Alternative Therapy Practitioners:Licensed homeopaths and other alternative medicine professionals prescribe and dispense remedies, guiding patient usage and contributing to product sales.
Demand from Home Treatment Users establishes a baseline, with Wellness Clinics showing dynamic expansion.
Distribution Channel:
Accessibility and purchasing convenience shape the distribution channel landscape for homeopathic products.
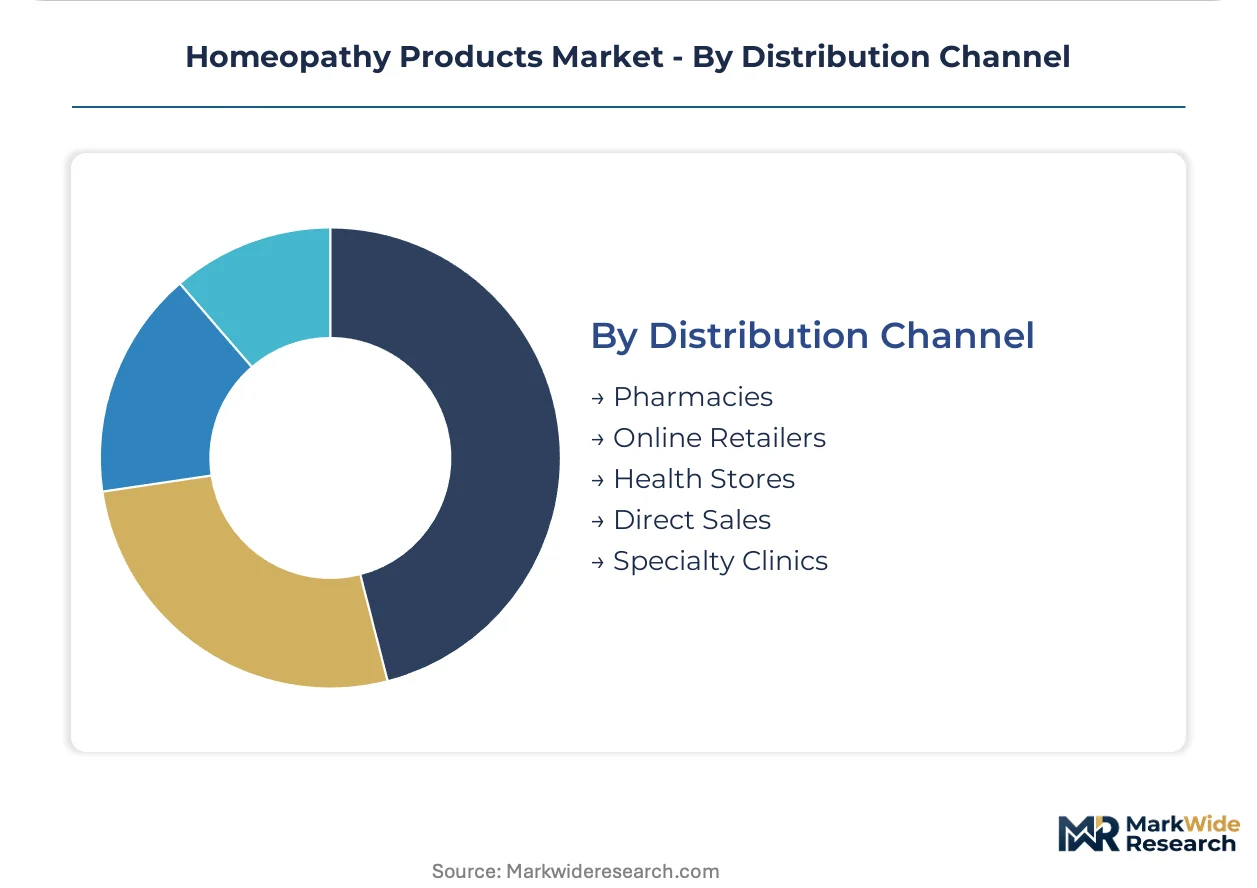
- Online Retailers:E-commerce platforms, including direct-to-consumer websites and third-party marketplaces, offer unparalleled reach and convenience, expanding market access globally. This channel is expanding most quickly in North America, displacing traditional brick-and-mortar sales.
- Pharmacies:Both independent and chain pharmacies provide a trusted retail environment for homeopathic products, often alongside conventional medicines. Pharmacies remain a critical point of sale in Germany and France, benefiting from established consumer habits.
- Health Stores:Specialty health food stores and natural product retailers cater to a health-conscious demographic, providing curated selections of homeopathic remedies.
- Direct Sales:Practitioners or manufacturers selling products directly to consumers facilitate personalized recommendations and build brand loyalty.
- Specialty Clinics:Integrated health clinics and homeopathic practices stock and dispense remedies, serving as a point of purchase for patients receiving treatment.
For market reach, Online Retailers is critical, and Pharmacies offers significant future growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
A significant concentration of skilled homeopathic practitioners anchors the market's global development. These professionals often drive product adoption and influence regional distribution patterns. Their expertise is particularly vital in markets with established traditions of alternative medicine.
India
Demand for homeopathic products in India remains robust, driven by cultural acceptance and affordability. India's Ministry of AYUSH actively promotes homeopathy through public funding and integration into national healthcare. Delhi serves as a central hub for manufacturing and distribution, fostering a competitive local industry.
Germany
European consumers show consistent demand for natural health solutions, supporting traditional homeopathic remedies. The European Medicines Agency (EMA) provides specific guidance for homeopathic medicinal products, influencing quality standards. Munich and Berlin host numerous specialized pharmacies and clinics that dispense these preparations.
United States
Consumers in the United States increasingly seek non-pharmaceutical options for mental wellness and chronic conditions. The FDA's risk-based enforcement policy shapes product claims and marketing strategies for unapproved homeopathic drugs. California's health-conscious population drives innovation in direct-to-consumer digital platforms.
Brazil
Brazil's cultural affinity for natural medicine fuels a growing demand for homeopathic products across diverse applications. ANVISA, the national health surveillance agency, regulates the registration and commercialization of homeopathic medicines. São Paulo represents a major market and distribution center, with a rising number of alternative therapy clinics.
Homeopathy Products Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists, creating a multi-tiered market structure within the homeopathy products market. The landscape features large established brands with extensive global reach alongside numerous smaller, niche players targeting specific health applications. Strategic archetypes include global distributors leveraging broad networks, regional specialists deeply embedded in local markets, and product-specific innovators. Geographic expansion into underpenetrated regions and portfolio diversification across product types represent dominant competitive moves among market participants.
At the scale-driven end, Boiron exemplifies a global leader with an extensive distribution network and broad product portfolio. Hyland’s Inc. occupies a position as a prominent specialist in pediatric and family wellness products within North American markets. Dr Reckeweg & Co represents a European-based entity known for its differentiated portfolio of specific combination remedies, catering to a practitioner-centric model.
| Leading Market Players |
|---|
| A Nelson & Co Ltd |
| Hyland’s Inc. |
| Boiron |
| Dr Reckeweg & Co |
| Hevert-Arzneimittel GmbH |
| Dr Willmar Schwabe GmbH & Co KG |
| SBL |
| Homeocan |
| Biologische Heilmittel Heel GmbH |
| Others |
Cost & Logistics Intelligence
Family-owned mid-caps and diversified conglomerates drive supply behavior, influencing pricing discipline through their production scale and distribution reach. This dynamic shapes how products are introduced and priced across varied regulatory environments.
Pricing Analysis
The bundled-versus-unbundled product split significantly influences pricing in the homeopathy market, with combination remedies commanding different price points than single-ingredient formulations. Per-unit transactional models dominate, reflecting consumer purchase patterns for over-the-counter remedies. Price differentiation stems from quality grade, particularly adherence to specific regulatory standards, and brand premium established through long-standing market presence. Pricing softness stems from intense competition from evidence-backed herbal supplements and conventional OTC medications. Home Treatment Users exhibit the highest price sensitivity, often seeking affordable self-care options.
Supply Chain Analysis
Domestic-content mandates in India, driven by government support for traditional medicine, reshape sourcing strategies for manufacturers. Geographic supply concentrates in India, Germany, and France, reflecting established production hubs and practitioner networks. Raw material dependencies include natural substances, sugar for pellets, and alcohol or water for liquid dilutions. The lack of manufacturing standardization across global markets presents a structural supply chain risk. Distribution runs through a dual model, with online retailers expanding rapidly alongside established pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a geographic-arbitrage play, leveraging India's lower production costs and government support against the higher consumer willingness to pay in European and North American markets.
For Market Incumbents: Hedge against scientific skepticism by investing in rigorous clinical documentation for combination remedies, aligning with EMA guidance. Diversify product portfolios beyond highly diluted single-ingredient formulations to mitigate regulatory scrutiny from the US FDA. This approach strengthens brand credibility against competition from conventional OTC medications and alternative supplements. Capacity addition in India allows for cost-effective production for global distribution.
For New Entrants and Emerging Players: Launch personalized formulations via direct-to-consumer e-commerce platforms, capitalizing on digital health trends for self-guided care. Target Latin American markets, such as Brazil and Mexico, which exhibit cultural affinity for natural medicine and represent underpenetrated white spaces. Focus on a go-to-market angle emphasizing preventative health and holistic wellness programs, appealing to consumers seeking alternative treatments for mental wellness.
For Investors and Strategic Acquirers: Valuations sit cheapest among smaller, regional specialists deeply embedded in local practitioner networks or those with niche product portfolios. The long-term viability hinges on the sustained consumer shift toward natural wellness options and integration into preventative health. Target acquisition profiles include companies with strong e-commerce capabilities or those specializing in specific application areas like pediatric wellness. The signal to watch is increased regulatory clarity from bodies like the EMA or FDA, which could unlock broader market acceptance.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway Investment | Ensures compliance with evolving EMA and FDA standards, expanding market access for complex formulations. |
| Personalized Formulations Launch | Captures demand for tailored health solutions, differentiating offerings in a competitive market. |
| Digital Health Platform Development | Facilitates direct-to-consumer engagement and supports self-guided remedy selection, enhancing accessibility. |
| E-commerce Channel Expansion | Broadens market reach beyond traditional retail, tapping into growing online consumer purchasing behavior. |
| Quality Control System Investment | Addresses manufacturing standardization gaps and builds consumer trust in product consistency and safety. |
Research Approach
Coverage spans India, Europe, North America, and Latin America, with primary inputs from each key region. The analysis combines insights from in-depth interviews with homeopathic practitioners, regulatory affairs leads, product development managers, and e-commerce platform executives. This primary data is rigorously validated against secondary sources, including FDA filings, EMA guidance documents, Ministry of AYUSH publications, and relevant trade association reports, ensuring comprehensive market understanding. Bottom-up and top-down triangulation methods were applied to ensure data accuracy.
The analytical framework models the market's granularity across product type, application area, end user, distribution channel, and key country-level regulatory frameworks. Forecasts are developed across the analysis window, with CAGRs derived from historical growth trends and projected market dynamics. Key industry-specific forecast inputs include consumer preference shifts toward alternative wellness and the impact of evolving regulatory enforcement policies from agencies such as the FDA.
Several conditions sit outside the modeled scope, including specific brand-level sales performance and detailed raw material price fluctuations. Forecasts reflect assumptions regarding the stable evolution of consumer preferences and regulatory environments. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Medicine
Global Homeopathic Product Market
Alternative Medicine
Complementary and Alternative Medicine for Anti Aging and Longevity Market
Alternative Medicine
Global Complementary and Alternative Medicines Market
Alternative Medicine
Traditional Chinese Herbal Medicine Market
Alternative Medicine
Global OTC Herbal and Traditional Medicine Market
Alternative Medicine
Electrotherapy Market
Alternative Medicine
Bio Magnetic Ear Stickers Market
Alternative Medicine
Botanicals & Acupuncture Market
Alternative Medicine
Disposable Acupuncture Needle Market
Alternative Medicine
Homeopathic Medicine Market
Alternative Medicine
Aromatherapy Market
Alternative Medicine
Cold Laser Therapy Market
Alternative Medicine
Biopuncture Treatment Market
Alternative Medicine
Traditional Chinese Medicine Market
Alternative Medicine
Ozone Therapy Units Market
Alternative Medicine
US Chiropractic Market