
 Europe Complementary and Alternative Medicine Market | 2026-2036
Europe Complementary and Alternative Medicine Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Complementary and Alternative Medicine Market Intelligence
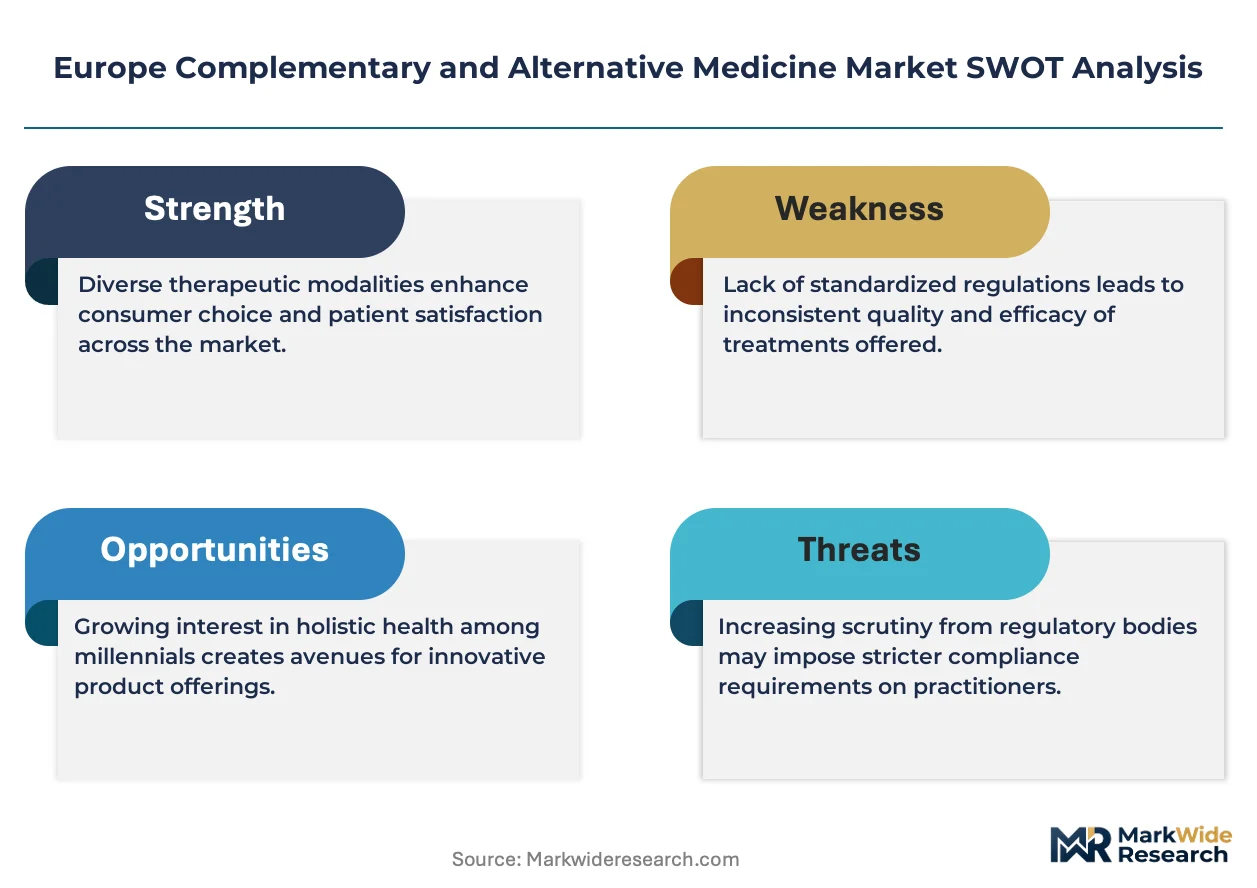
Modular service bundling is decoupling traditional treatment packages into standalone acupuncture sessions, herbal consultations, and aromatherapy add-ons that buyers purchase à la carte. Weleda anchors its position through proprietary biodynamic cultivation networks across Alpine growing regions. Schwabe competes via concentrated investment in standardized herbal extract R&D. Nordic Nutraceuticals differentiates through omega and marine-origin supplement specialization aimed at Scandinavian consumer preferences.
Complementary and alternative medicine encompasses botanical preparations, physical therapy modalities, and mind-body interventions formulated to prevent illness, manage chronic conditions, or support conventional treatment regimens. Herbal supplements require standardized extraction protocols with defined marker compound concentrations to ensure batch-to-batch pharmacological consistency. Pain management applications currently command the largest therapy area footprint due to chronic condition prevalence and opioid-sparing clinical priorities. Mental health represents the fastest-expanding therapy segment as integrative psychiatric protocols gain institutional acceptance. Online sales channels are capturing disproportionate growth in delivery mode share, though retail outlets retain higher average transaction values through guided purchasing interactions.
The European Medicines Agency governs traditional herbal registration under Directive 2004/24/EC, while REACH and the EU Green Deal constrain pesticide residues and solvent use in botanical supply chains. EMA's Committee on Herbal Medicinal Products shapes monograph standards that determine which extracts qualify for simplified registration pathways versus full marketing authorization. National regulators including Germany's Federal Institute for Drugs and Medical Devices and France's ANSM layer additional pharmacovigilance requirements that influence product development timelines. Stakeholders must track how the EU AI Act and impending digital health framework classifications affect software-enabled acupuncture devices and algorithmic treatment recommendation platforms.
Market Dynamics
Modular service unbundling is fragmenting traditional treatment packages across European wellness centers, forcing providers to price acupuncture, herbal consultations, and aromatherapy as standalone SKUs rather than bundled protocols.
Growth Catalysts
- EU Green Deal organic sourcing mandates:Certified botanical supply chains are gaining preferential pharmacy shelf placement in France and Germany, compressing conventional pesticide-dependent ingredient margins.
- Chronic pain management protocols:Opioid-sparing clinical priorities in German hospital networks are expanding acupuncture reimbursement coverage through Federal Institute for Drugs and Medical Devices guidance.
- Integrative psychiatry adoption:Mind-body interventions are securing institutional acceptance in French mental health clinics, creating new prescriber channels for herbal anxiolytics.
Market Restraints
- REACH solvent residue limits:Extraction protocol compliance costs are compressing margins for mid-scale botanical processors unable to finance supercritical CO2 infrastructure upgrades.
- Alpine growing region concentration:Biodynamic cultivation networks face climate volatility risks that threaten year-round supply consistency for standardized extract manufacturers.
- Synthetic pharmaceutical substitution:Conventional analgesics retain formulary dominance in acute care settings, limiting herbal pain management penetration to outpatient chronic protocols.
Strategic Opportunities
- Digital health framework pre-positioning:Software-enabled acupuncture devices can secure early-mover advantage ahead of EU AI Act classification finalization for algorithmic treatment platforms.
- Marine-origin supplement specialization:Nordic consumer preferences for omega fatty acids create white space for algae-derived alternatives to fish oil in Scandinavian pharmacy chains.
- Homeopathic pharmacy integration:French pharmacy chains dedicating shelf space to aromatherapy lines are opening distribution partnerships for certified organic essential oil suppliers.
Industry Challenges
- Herbal pharmacovigilance expertise scarcity:Germany's Federal Institute for Drugs and Medical Devices and France's ANSM impose divergent adverse event reporting timelines that strain cross-border compliance teams.
- Batch-to-batch marker compound consistency:Standardized extraction protocol validation requires capital-intensive HPLC infrastructure that fragments quality tiers between integrated and toll-manufactured supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Complementary and Alternative Medicine Market |
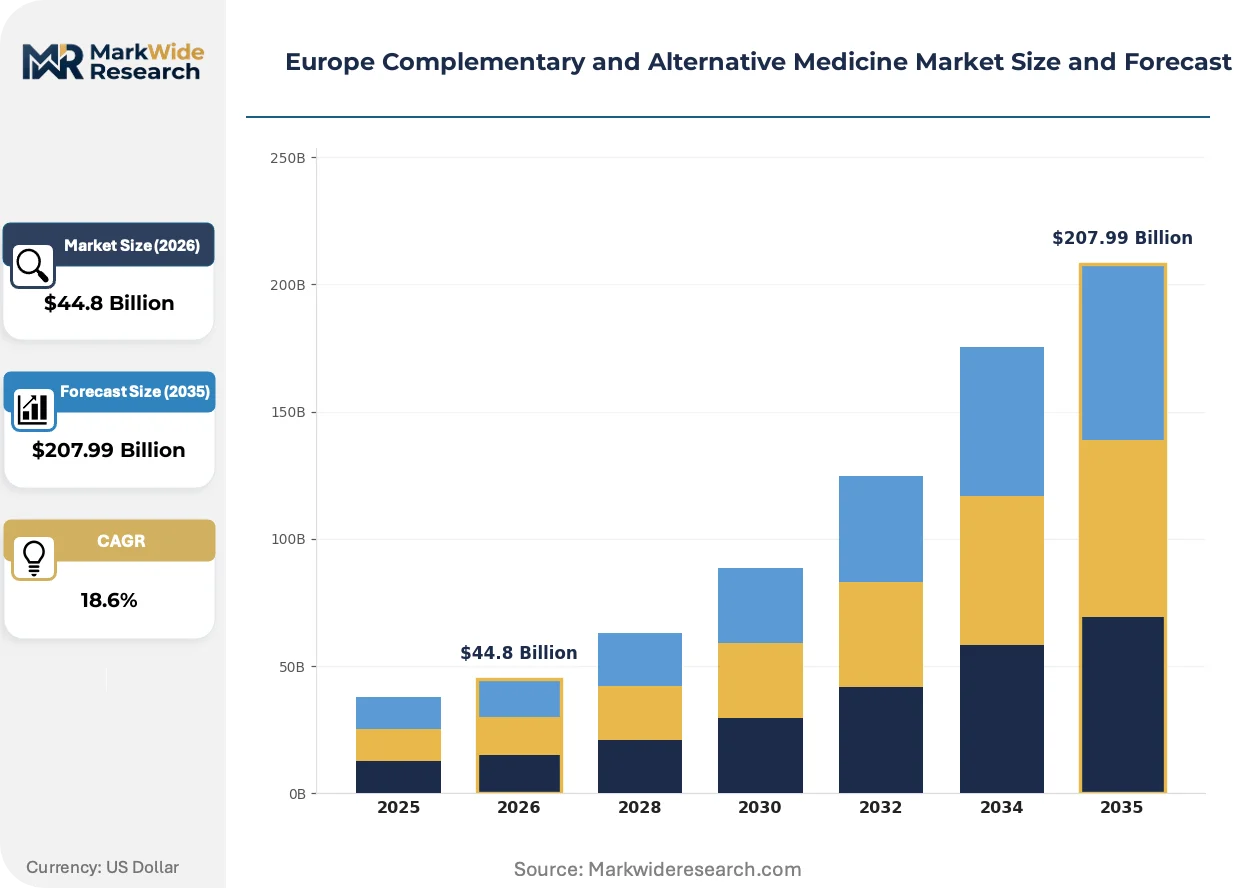
| Market Size in 2026 | $44.8 Billion |
| Market Size in 2035 | $207.99 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbal Supplements, Acupuncture Devices, Homeopathy Products, Aromatherapy Supplies End User: Wellness Centers, Clinics, Home Users, Pharmacies Therapy Area: Pain Management, Mental Health, Digestive Disorders, Immune Support Delivery Mode: Online Sales, Retail Outlets, Direct Mail, Wholesale Distribution |
| Companies Covered | Pure Encapsulations, LLC., Herb Pharm, Weleda, Siddhalepa Ayurveda GmbH, Columbia Nutritional, Schwabe, Nordic Nutraceuticals, BGG Europe SA, Nelsons, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Complementary and Alternative Medicine Market Strategic Shifts & Innovations
Technology convergence with regulatory digitization is compressing traditional herbal registration timelines while reshaping how treatment protocols are prescribed, monitored, and reimbursed across European healthcare systems.
Sensor-embedded acupuncture devices are converging with cloud-based treatment analytics platforms. German physiotherapy chains are piloting these systems for chronic pain protocol documentation. The structural consequence is compressing reimbursement dispute resolution timelines while generating real-world evidence pools that satisfy EMA pharmacovigilance requirements.
REACH and EU Green Deal constraints on pesticide residues are forcing solvent system transitions across botanical extraction facilities. Industrial consequence includes accelerated supercritical CO2 adoption and ethanol substitution in Alpine processing plants. Small-batch artisanal extractors in France face disproportionate compliance cost burdens relative to integrated biodynamic operators with captive cultivation.
Subscription-based herbal supplement replenishment is displacing pharmacy counter purchasing in Scandinavian markets. Digital-native buyers in Denmark and Sweden favor algorithmic personalization over guided retail interactions. This channel rotation is most visible in omega and marine-origin categories where Nordic Nutraceuticals specialization aligns with automated reordering preferences.
Europe Complementary and Alternative Medicine Market Segmentation
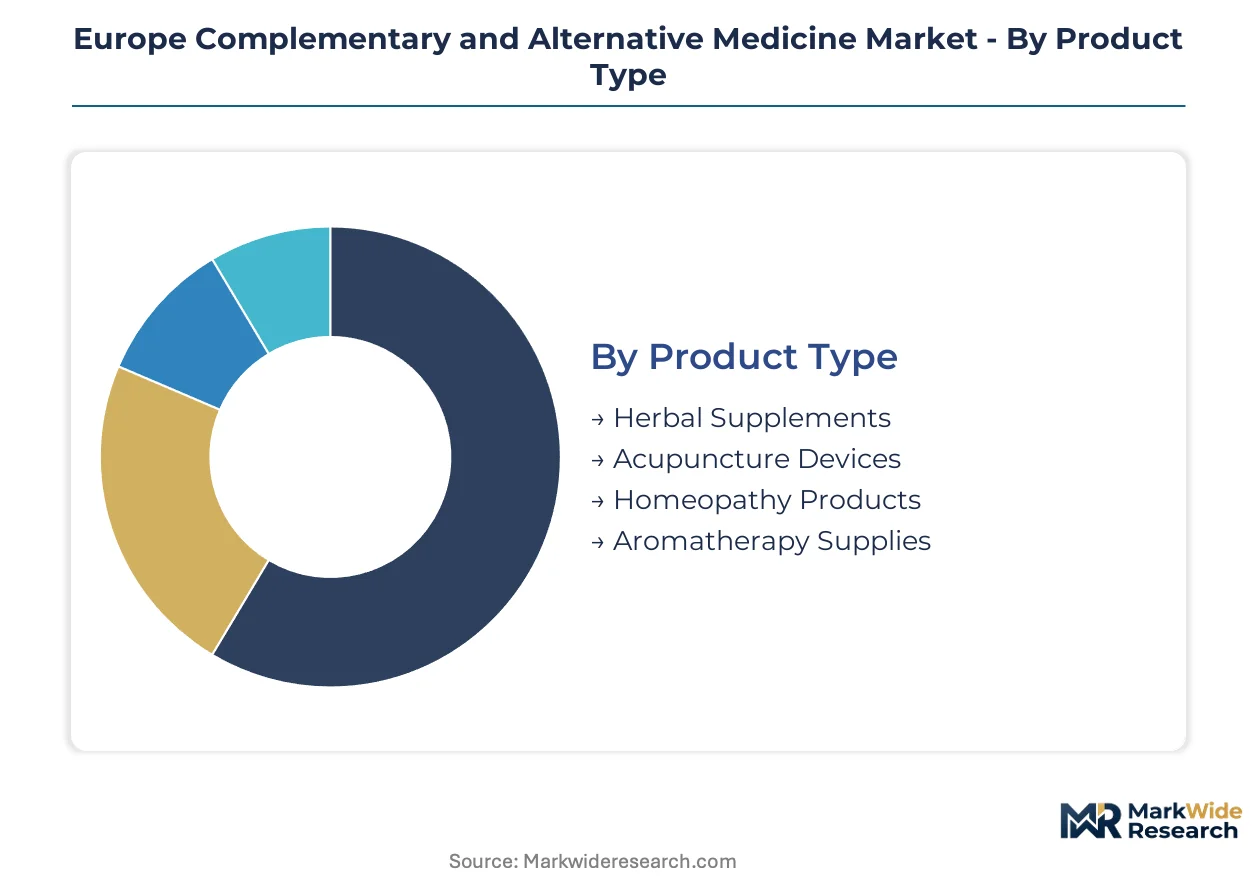
Segmentation in the European complementary and alternative medicine market reveals how regulatory frameworks, reimbursement policies, and consumer purchasing behaviors create distinct competitive arenas. Each dimension—product type, end user, therapy area, and delivery mode—carries unique margin profiles and compliance burdens that shape strategic positioning.
Product Type:
Supply concentration in Alpine biodynamic cultivation networks and standardized extraction facilities creates tiered quality differentiation across product categories.
- Herbal Supplements:Standardized extraction protocols with defined marker compound concentrations ensure batch-to-batch pharmacological consistency. German pharmacy chains and French retail outlets concentrate procurement for chronic condition management, driven by EMA monograph qualification requirements under Directive 2004/24/EC.
- Acupuncture Devices:Sensor-embedded systems with cloud-based treatment analytics platforms are converging with physiotherapy documentation needs. German hospital networks and wellness centers in Bavaria and Baden-Württemberg are expanding device procurement for opioid-sparing pain protocols.
- Homeopathy Products:French pharmacy chains dedicate specific shelf space to these lines, reflecting ANSM registration pathways and consumer familiarity.
- Aromatherapy Supplies:Certified organic essential oils gain preferential placement in German wellness centers following EU Green Deal sourcing mandates.
Herbal supplements absorb the bulk of installed capacity; acupuncture devices are expanding most quickly.
End User:
Cost tier differentiation separates institutional purchasers with reimbursement access from direct-pay consumers navigating out-of-pocket spending decisions.
- Wellness Centers:Modular service unbundling forces standalone pricing for acupuncture, herbal consultations, and aromatherapy add-ons. German centers in Munich and Berlin lead protocol diversification.
- Clinics:Integrative psychiatry adoption in French mental health facilities creates prescriber channels for herbal anxiolytics and mind-body interventions.
- Home Users:Scandinavian subscription-based replenishment models displace pharmacy counter purchasing for omega and marine-origin supplements.
- Pharmacies:French chains dominate homeopathic and aromatherapy distribution, while German outlets emphasize herbal supplement guidance interactions.
Wellness centers command the highest service revenue per interaction; home users are gaining share fastest through digital channel migration.
Therapy Area:
Application urgency and clinical evidence standards create divergent regulatory pathways and prescriber acceptance thresholds across therapeutic domains.
- Pain Management:Chronic condition prevalence and opioid-sparing priorities in German hospital networks expand acupuncture reimbursement coverage. Federal Institute for Drugs and Medical Devices guidance shapes protocol documentation requirements.
- Mental Health:Integrative psychiatric protocols in French clinics secure institutional acceptance for herbal anxiolytics and mindfulness-based interventions. This segment climbs the fastest as prescriber education programs expand.
- Digestive Disorders:Herbal preparations target functional gastrointestinal conditions with established traditional use registrations.
- Immune Support:Seasonal demand concentration in Alpine regions drives botanical ingredient sourcing from certified organic supply chains.
Pain management holds the largest therapy footprint; mental health shows the steepest expansion trajectory.
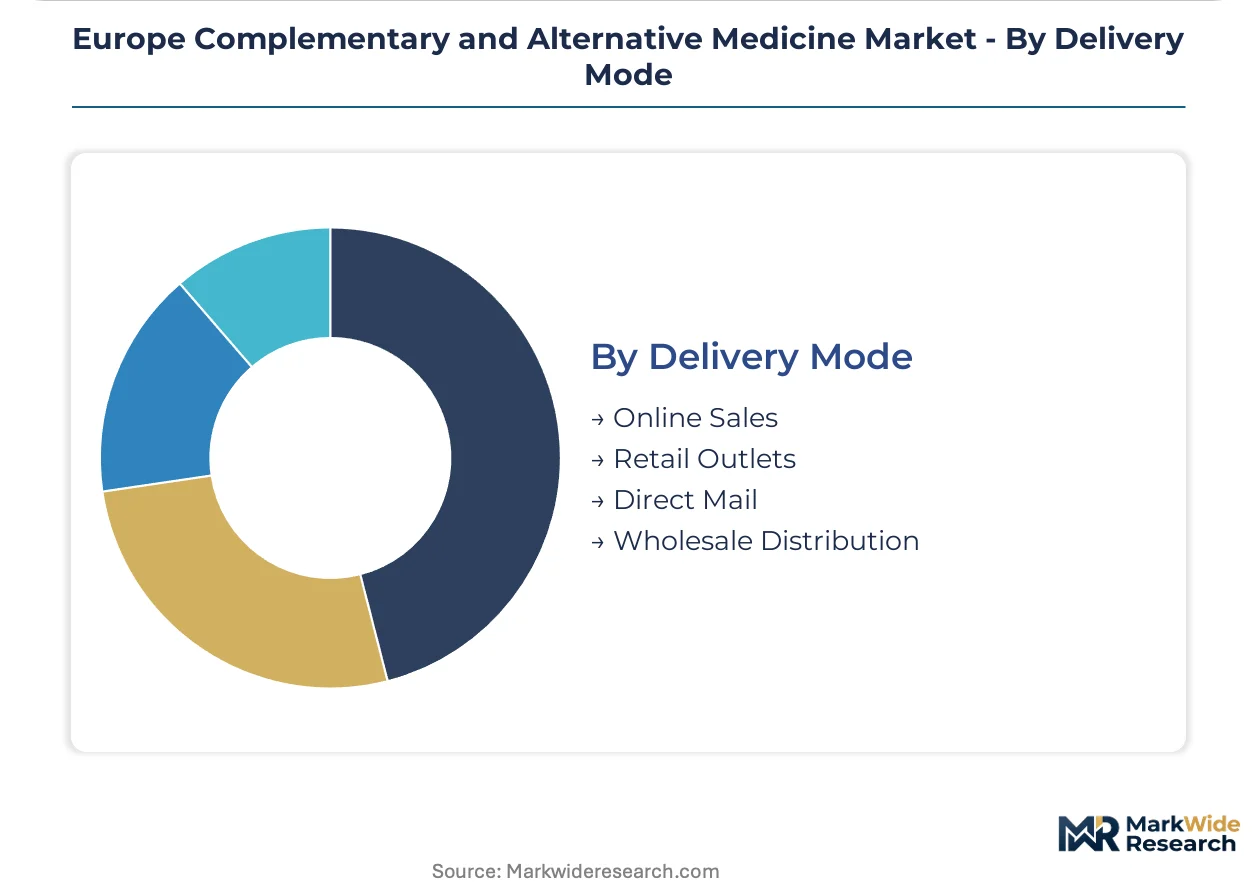
Delivery Mode:
Volume concentration in retail pharmacy networks contrasts with margin compression in digital channels where automated replenishment reduces guided purchasing interactions.
- Online Sales:Algorithmic personalization and subscription models capture disproportionate growth in Scandinavian markets. Nordic Nutraceuticals specialization aligns with Denmark and Sweden consumer preferences for automated omega fatty acid reordering.
- Retail Outlets:Higher average transaction values persist through pharmacist-guided herbal supplement selection in France and Germany.
- Direct Mail:Catalog-based homeopathy distribution retains niche penetration among older demographic segments in rural Alpine regions.
- Wholesale Distribution:Bulk botanical ingredient supply to processing facilities concentrates in biodynamic cultivation networks across Swiss and Austrian Alpine zones.
Retail outlets maintain the highest transaction values; online sales channels are displacing traditional purchasing fastest in Nordic markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of standardized herbal extracts concentrates in Alpine cultivation zones across Switzerland and Austria, while consumption gravity sits in German pharmacy networks and French retail chains. This spatial disconnect shapes logistics costs and regulatory compliance burdens across the value chain.
Germany
Federal Institute for Drugs and Medical Devices guidance expands acupuncture reimbursement in hospital networks for opioid-sparing pain protocols. Munich and Berlin wellness centers unbundle traditional treatment packages into standalone service SKUs. Bavarian physiotherapy chains pilot sensor-embedded acupuncture devices with cloud-based analytics platforms.
France
ANSM registration pathways enable pharmacy chains to dedicate shelf space to homeopathic and aromatherapy lines. Integrative psychiatry protocols in Paris and Lyon mental health clinics create prescriber channels for herbal anxiolytics. Provence-Alpes-Côte d'Azur cultivation clusters face EU Green Deal pesticide residue constraints.
Switzerland
Swissmedic governs traditional herbal registrations alongside EMA monograph standards. Biodynamic cultivation networks in Alpine growing regions supply standardized extract manufacturers. Zurich and Geneva wellness centers emphasize certified organic botanical sourcing mandates.
Sweden
Subscription-based herbal supplement replenishment displaces pharmacy counter purchasing in Stockholm and Gothenburg markets. Algorithmic personalization platforms capture omega fatty acid demand. REACH solvent residue limits pressure mid-scale botanical processors.
United Kingdom
London wellness centers integrate modular acupuncture and herbal consultation services. MHRA registration requirements shape traditional herbal product market entry timelines. Retail pharmacy networks in Southeast England emphasize guided purchasing interactions for supplement categories.
Europe Complementary and Alternative Medicine Market Key Industry Players
The competitive structure tilts toward integrated biodynamic operators with captive cultivation networks. Tiered quality differentiation separates Alpine-based standardized extract manufacturers from toll-processing competitors. Three archetypes dominate: proprietary cultivation network holders, R&D-intensive extract standardization specialists, and marine-origin supplement regionalists. Capacity expansion in supercritical CO2 infrastructure and pharmacy chain distribution partnerships constitute the dominant competitive moves.
Among Alpine-integrated operators, Weleda anchors the proprietary cultivation network archetype through biodynamic growing region control. Schwabe occupies a position exemplifying concentrated investment in standardized herbal extract development. Nordic Nutraceuticals represents the marine-origin specialization vector targeting Scandinavian consumer preferences. These three company structures illustrate how geographic rooting and processing technology choices stratify competitive positioning across the European market.
| Leading Market Players |
|---|
| Pure Encapsulations, LLC. |
| Herb Pharm |
| Weleda |
| Siddhalepa Ayurveda GmbH |
| Columbia Nutritional |
| Schwabe |
| Nordic Nutraceuticals |
| BGG Europe SA |
| Nelsons |
| Others |
Cost & Logistics Intelligence
Supercritical CO2 extraction adoption across Alpine processing plants compresses per-unit production costs while concentrating supply among operators financing capital-intensive infrastructure upgrades. REACH solvent residue limits simultaneously reshape cost economics and supplier consolidation, favoring integrated biodynamic networks over toll-dependent processors.
Pricing Analysis
Margin tightening in standardized herbal extracts reflects REACH compliance cost absorption and supercritical CO2 infrastructure financing burdens. Three-tier pricing structure across premium biodynamic, standard certified-organic, and economy conventional tiers separates Weleda-captive supply from toll-manufactured alternatives. Cost-down pressure on mid-scale French artisanal extractors accelerates because ethanol substitution investments outstrip available capital. Pharmacy chains in Germany exhibit lowest price sensitivity through guided purchasing interactions, while Scandinavian subscription buyers prioritize algorithmic value over brand premium.
Supply Chain Analysis
Dual-sourcing mandates from German pharmacy chains and French retail networks force botanical processors to qualify multiple Alpine cultivation clusters. Supply concentrates in Swiss and Austrian Alpine growing regions, with secondary sourcing from Provence-Alpes-Côte d'Azur cultivation zones. Raw material dependencies center on certified organic botanical inputs, supercritical CO2 solvent systems, and HPLC validation equipment. Single-source vulnerability threatens mid-scale operators lacking captive cultivation. Distribution runs through pharmacy chain procurement in France and Germany, wellness center direct agreements in Munich and Berlin, and algorithmic replenishment platforms in Stockholm and Copenhagen.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supercritical CO2 infrastructure scarcity props pricing power among integrated operators, constraining supply expansion despite reimbursement expansion for acupuncture and herbal protocols.
For Market Incumbents: Cement market position through backward integration into Alpine biodynamic cultivation networks before EU Green Deal sourcing mandates harden. Expand HPLC validation capacity to capture toll-manufacturing demand from REACH-constrained mid-scale competitors. Prioritize pharmacy chain distribution partnerships in France where ANSM registration creates switching costs. For New Entrants and Emerging Players: Algorithmic personalization platforms for Scandinavian omega fatty acid replenishment represent the most penetrable entry vector. Target marine-origin algae-derived alternatives to fish oil where Nordic Nutraceuticals specialization has not saturated automated reordering channels. Pursue white-label supply agreements with French pharmacy chains expanding aromatherapy shelf space. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of Alpine-integrated biodynamic operators with EMA monograph-qualified extract portfolios. Long-term viability hinges on captive cultivation control and supercritical CO2 processing capacity. Watch for Federal Institute for Drugs and Medical Devices reimbursement guidance expansion as inflection signal for acupuncture device demand.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Infrastructure Expansion | REACH solvent compliance secures pharmacy chain procurement preference in Germany and France. |
| Biodynamic Cultivation Network Acquisition | EU Green Deal organic mandates favor captive supply over toll-dependent processors. |
| Sensor-Embedded Acupuncture Device Launch | Federal Institute for Drugs and Medical Devices reimbursement guidance expands hospital network adoption. |
| Algorithmic Personalization Platform Development | Scandinavian subscription preferences displace pharmacy counter purchasing for marine-origin supplements. |
| EMA Monograph Qualification Investment | Traditional herbal registration under Directive 2004/24/EC unlocks simplified pathway versus full marketing authorization. |
Research Approach
Document review covered EMA monograph databases, Federal Institute for Drugs and Medical Devices guidance documents, and ANSM registration filings, complemented by interviews with herbal extract manufacturers, pharmacy chain procurement managers, wellness center operators, and physiotherapy chain clinical directors. Secondary validation drew from REACH compliance records, EU Green Deal implementation reports, and Alpine cultivation network trade data. Bottom-up demand modeling triangulated against top-down regulatory pathway analysis.
Segmentation outputs span product type, end user archetype, therapy area application, and delivery mode channel across the projection horizon. CAGRs derive from installed capacity utilization rates, reimbursement policy trajectory, and channel migration velocity in Nordic markets. Modeled inputs incorporate supercritical CO2 adoption curves, EMA monograph qualification timelines, and pharmacy chain shelf-space allocation shifts.
Revisions become necessary when Federal Institute for Drugs and Medical Devices reimbursement guidance contracts, EU AI Act classification finalization disrupts software-enabled device pathways, or Alpine climate volatility threatens biodynamic cultivation yields. Deviation in REACH solvent residue limit enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Medicine
Global OTC Herbal and Traditional Medicine Market
Alternative Medicine
Complementary and Alternative Medicine for Anti Aging and Longevity Market
Alternative Medicine
US Aromatherapy Market
Alternative Medicine
Ozone Therapy Units Market
Alternative Medicine
Acupuncture Lasers Market
Alternative Medicine
Electrotherapy Market
Alternative Medicine
Global Acupuncture Market
Alternative Medicine
Fire Cupping Market
Alternative Medicine
Disposable Acupuncture Needle Market
Alternative Medicine
US Chiropractic Market
Alternative Medicine
Allergy Immunotherapy Market
Alternative Medicine
Homeopathic Medicine Market
Alternative Medicine
Global Homeopathic Product Market
Alternative Medicine
Orthomolecular Medicine Market
Alternative Medicine
Traditional Chinese Herbal Medicine Market
Alternative Medicine
Flower Essences Market