
 Laser Therapy Devices Market | 2026-2036
Laser Therapy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Laser Therapy Devices Market Intelligence
Post-sale training and certification for practitioners is rewriting profitability models for device manufacturers. Lumenis leverages its extensive installed base to offer tiered training programs for its aesthetic and ophthalmic lasers. Cynosure differentiates through educational partnerships with key opinion leaders in dermatology, while Fotona focuses on specialized workshops for its dental and surgical systems.
Laser therapy devices are medical instruments that utilize non-ionizing, coherent light sources to perform therapeutic or surgical procedures. These systems operate at specific wavelengths, such as 1064 nm for Nd:YAG lasers, to target chromophores like melanin or water in tissue. Demand for cosmetic surgery applications propels the adoption of Nd:YAG and Alexandrite lasers. While hospitals remain a significant end-user, specialized clinics represent the fastest-growing channel for high-end systems.
Device approval pathways, including the FDA's 510(k) process in the United States and CE marking under the MDR in Europe, create significant barriers to entry. Regulators like China's NMPA and Brazil's ANVISA also enforce stringent clinical data requirements that shape product development timelines. Navigating the evolving standards for cybersecurity and data privacy in connected devices is a critical challenge for all manufacturers.
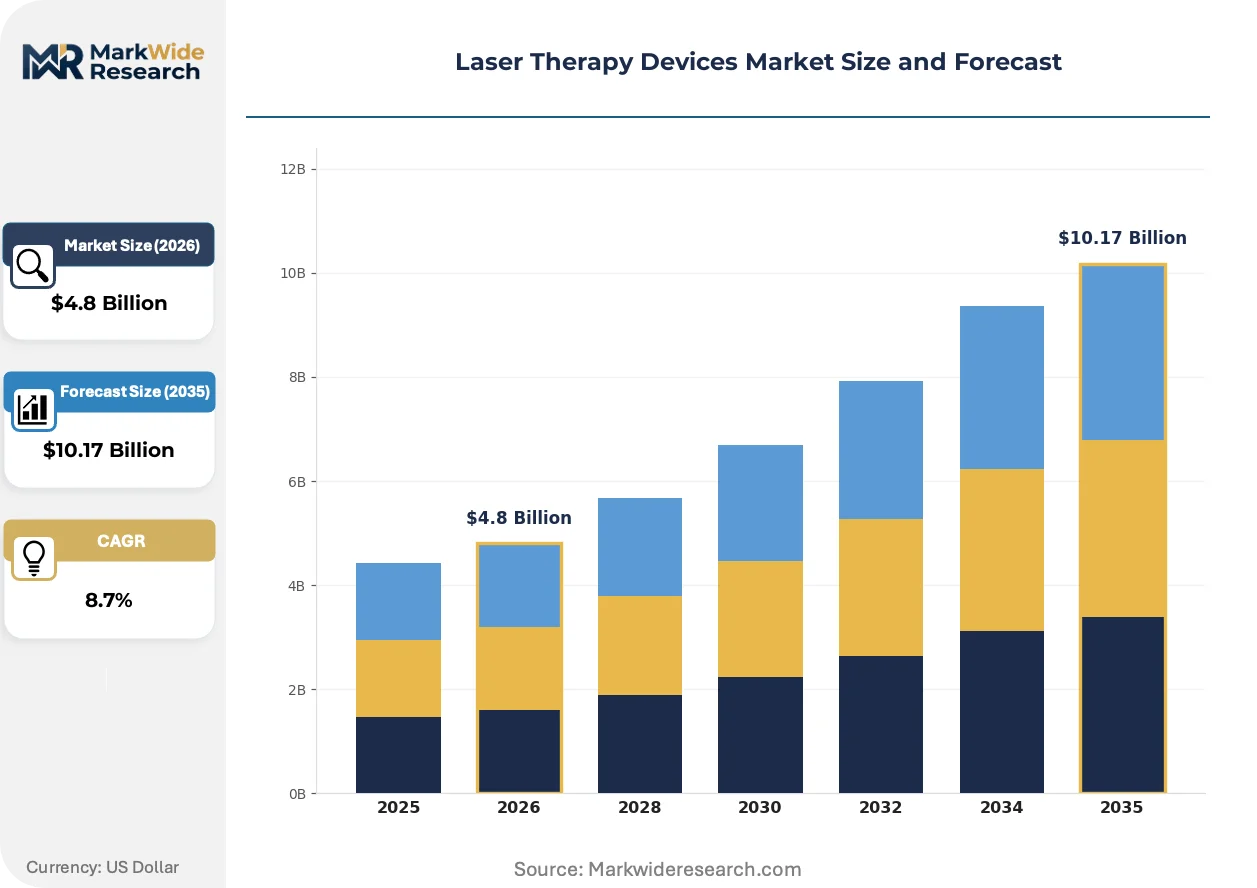
Market Dynamics
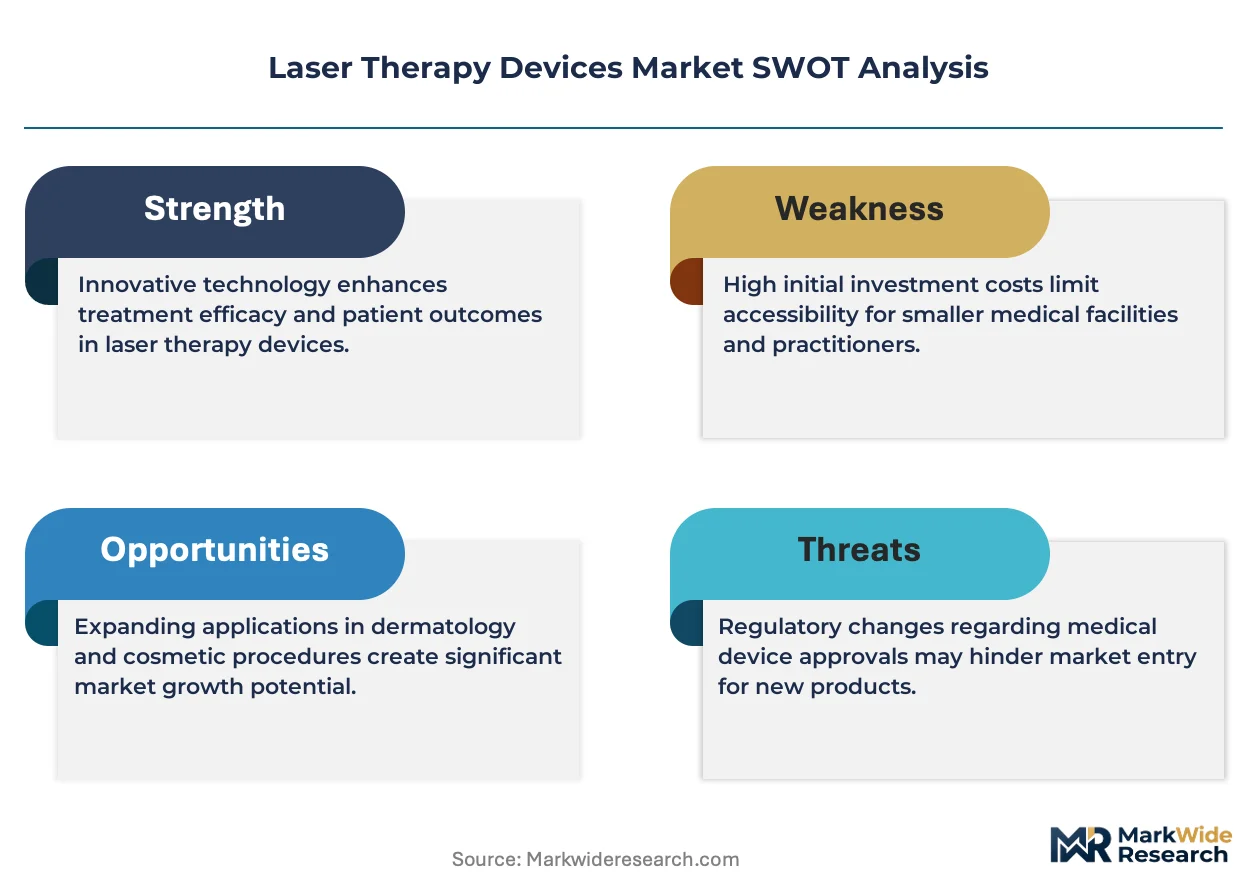
The central dynamic shaping the laser therapy devices market is the friction between the rapid expansion of applications in cosmetic medicine and the increasing stringency of regulatory frameworks like the EU's MDR, which govern device safety and efficacy claims.
Growth Catalysts
- Expanding Aesthetic Applications:Demand for non-invasive procedures such as skin rejuvenation, hair removal, and tattoo removal, particularly among consumers in the United States and Brazil, drives sales of specialized Nd:YAG and Alexandrite laser systems.
- Favorable Reimbursement Policies:Growing insurance coverage for medically necessary laser therapies, including certain dermatological and ophthalmic procedures, encourages adoption within hospital and specialty clinic settings, expanding the addressable patient population.
- Advances in Laser Technology:The development of fractional and picosecond lasers enhances treatment efficacy and patient safety, opening new therapeutic indications and encouraging the replacement of older-generation devices with more capable systems.
Market Restraints
- High Device Cost:The significant capital investment required for high-end laser systems, which can feature expensive components like specialized gain media and cooling units, acts as a major barrier for smaller, independent clinics and practices.
- Stringent Regulatory Hurdles:Navigating the complex and lengthy device approval pathways, such as the FDA's 510(k) process and ANVISA's requirements in Brazil, delays market entry and increases development costs for manufacturers.
- Threat from Alternative Technologies:Competition from other non-invasive energy-based aesthetic treatments, including intense pulsed light (IPL), radiofrequency (RF), and high-intensity focused ultrasound (HIFU), presents a substitution threat in some cosmetic applications.
Strategic Opportunities
- Emerging Therapeutic Fields:Untapped potential exists in applying laser therapy for pain management, wound healing, and physical therapy, creating opportunities for devices designed for these specific clinical, non-aesthetic indications.
- Geographic Expansion:Markets in Southeast Asia and the Middle East represent significant growth opportunities for aesthetic laser device manufacturers, driven by rising disposable incomes and a growing focus on personal appearance.
- Integration with Digital Health:Incorporating AI-driven software for treatment planning and remote monitoring capabilities for connected devices creates new value propositions and service-based revenue streams for manufacturers.
Industry Challenges
- Practitioner Skill Gaps:A persistent shortage of clinicians and technicians with the specialized training required to operate complex, multi-wavelength laser systems safely and effectively limits the full utilization of advanced device capabilities.
- Cybersecurity Compliance:Ensuring that connected laser therapy devices meet evolving data security and privacy standards, such as those related to HIPAA in the US, presents a significant and ongoing operational challenge for manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laser Therapy Devices Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diode Lasers, Nd:YAG Lasers, Alexandrite Lasers, CO2 Lasers End User: Hospitals, Clinics, Home Care, Research Institutions Application: Pain Management, Cosmetic Surgery, Tissue Repair, Dentistry Technology: Solid State, Gas, Fiber Optics, Pulsed |
| Companies Covered | Fotona, BIOLITEC, Lumenis, Asclepion Laser Technologies, Quanta System, Cynosure, Cutera, El.En. Group, Syneron Candela, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laser Therapy Devices Market Strategic Shifts & Innovations
Device intelligence and procedural specificity are defining the next generation of laser therapy systems. The market is shifting from general-purpose platforms toward highly specialized instruments designed for discrete applications, supported by sophisticated software and post-sale educational ecosystems.
Picosecond and femtosecond lasers deliver ultra-short energy pulses that enable precise tissue interaction with minimal collateral thermal damage. High-end aesthetic and ophthalmology centers are rapidly adopting these systems for advanced applications like multi-color tattoo removal and corneal surgery. The market for premium aesthetic treatments is migrating from older nanosecond technologies toward these ultra-short pulse systems for their superior clinical outcomes and safety profiles.
The European Union's Medical Device Regulation (MDR) has fundamentally altered the compliance landscape for manufacturers. It mandates more rigorous clinical evidence, post-market surveillance, and supply chain transparency than the previous directive. Consequently, all device makers, especially those in the aesthetic segment targeting the EU, are compelled to increase investment in clinical studies and quality management systems to secure or maintain CE marking.
A distinct preference shift is occurring among buyers, who now prioritize manufacturers offering comprehensive, hands-on certification and training. This disrupts the traditional sales model, which focused primarily on device hardware, by adding a crucial service and education layer. This dynamic is most visible in competitive aesthetic markets like the United States, where practitioner proficiency is a critical factor for clinic success and patient safety.
Laser Therapy Devices Market Segmentation
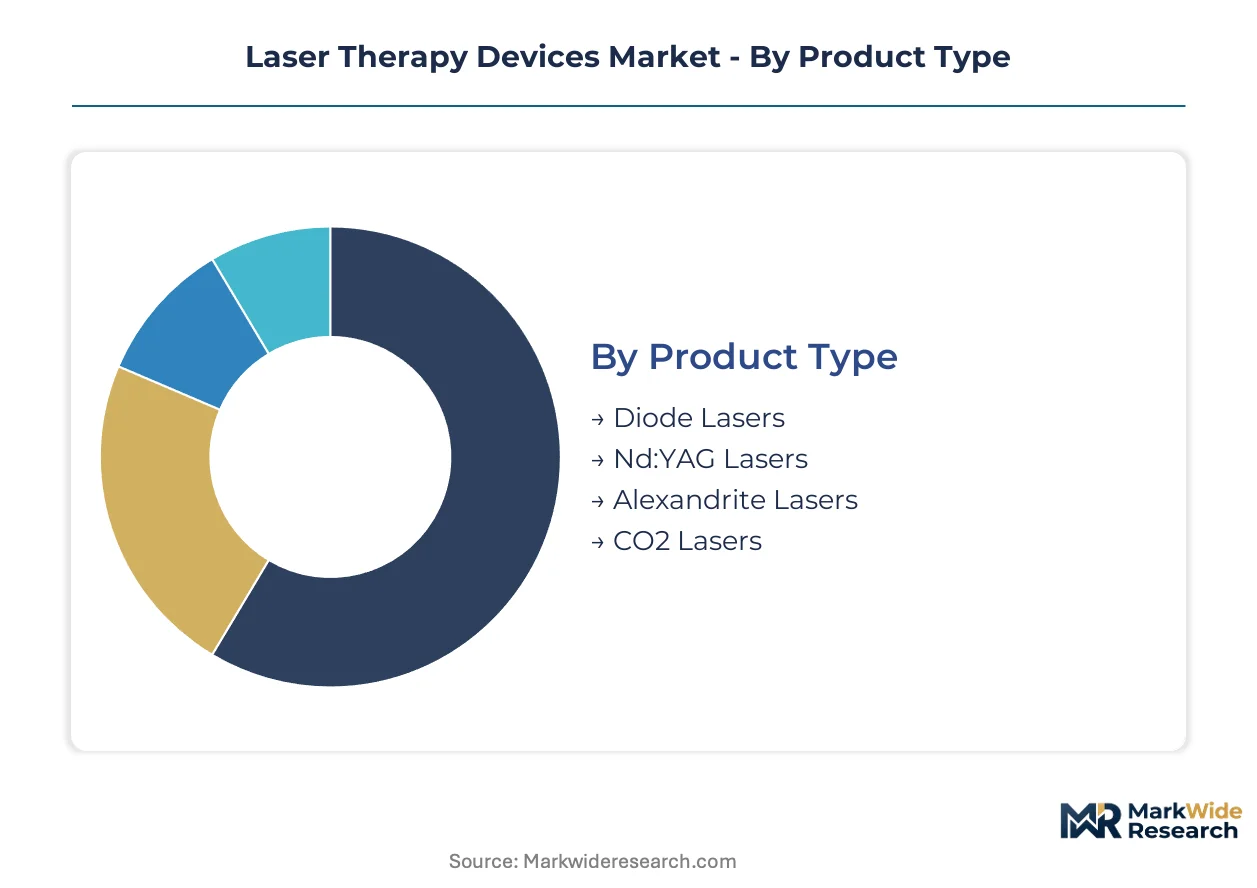
The laser therapy devices market differentiates across various dimensions, reflecting the diverse clinical needs and technological advancements driving its expansion. Understanding these segmentations provides clarity on where development efforts concentrate and where market opportunities are most pronounced.
Product Type:
The use-case spectrum for laser therapy devices spans from targeted tissue ablation to precision aesthetic treatments, each requiring specific laser characteristics.
- Nd:YAG Lasers:These solid-state lasers typically operate at 1064 nm, effectively targeting chromophores like melanin and hemoglobin for hair removal, vascular lesions, and tattoo removal. Demand concentrates in aesthetic clinics across the United States and Brazil, driven by consumer preference for non-invasive cosmetic procedures.
- Alexandrite Lasers:Emitting at 755 nm, Alexandrite lasers are highly absorbed by melanin, making them effective for hair removal and epidermal pigmentary lesions. Specialized dermatology centers in Europe increasingly adopt these systems due to their clinical efficacy and patient safety profiles.
- Diode Lasers:Commonly operating in the 800-980 nm range, diode lasers offer portable and cost-effective solutions for hair removal, pain management, and some surgical applications. Clinics and smaller practices prioritize these devices for their versatility and lower capital investment.
- CO2 Lasers:Operating at 10,600 nm, CO2 lasers are highly absorbed by water, making them ideal for precise tissue cutting, ablation, and skin resurfacing procedures. Hospitals and surgical centers utilize these systems for their broad utility in various medical specialties.
The dominant share belongs to Nd:YAG Lasers, while Alexandrite Lasers are closing the gap fastest.
End User:
The distribution of laser therapy devices varies significantly based on the customer type, influencing purchasing power and service requirements.
- Clinics:Specialized aesthetic and dermatological clinics represent a rapidly expanding channel for high-end laser systems, particularly in the United States and Western Europe. These facilities prioritize devices offering advanced features and comprehensive post-sale support.
- Hospitals:Large hospital systems remain significant purchasers of multi-functional laser platforms for surgical, dermatological, and ophthalmic applications. Procurement often involves rigorous tender processes and a focus on long-term service contracts.
- Home Care:Devices designed for home use, often lower power and simplified, cater to consumers seeking convenient and less expensive alternatives for basic aesthetic treatments like hair removal. Regulatory bodies like the FDA oversee the safety of these consumer-grade products.
- Research Institutions:Academic and private research laboratories utilize advanced laser systems for developing new therapeutic protocols and understanding light-tissue interactions. These institutions often require highly customizable and precise laser sources.
Clinics exhibit significant growth, driven by increasing consumer demand for specialized aesthetic services.
Application:
The volume of procedures performed dictates the adoption patterns for different laser therapy device applications.
- Cosmetic Surgery:This segment encompasses procedures like skin rejuvenation, tattoo removal, and hair reduction, utilizing Nd:YAG and Alexandrite lasers. Demand for these applications propels device sales in markets with high disposable incomes, such as the United States and Brazil.
- Pain Management:Low-level laser therapy (LLLT) devices are used to reduce inflammation and alleviate chronic pain in conditions like arthritis and musculoskeletal injuries. Emerging therapeutic fields are expanding the addressable patient population for these non-invasive treatments.
- Tissue Repair:Laser systems facilitate wound healing, scar revision, and tissue regeneration through precise energy delivery. Hospitals and specialized wound care centers employ these devices to improve patient outcomes and accelerate recovery.
- Dentistry:Dental lasers perform various procedures, including cavity preparation, gum treatment, and teeth whitening, offering less invasive alternatives to traditional methods. Dental practices increasingly invest in these systems for enhanced patient comfort and precision.
Cosmetic Surgery applications drive substantial market expansion, while Pain Management shows promising adoption trends.
Technology:
The maturity and innovation within laser technology define the performance capabilities and clinical utility of different device types.
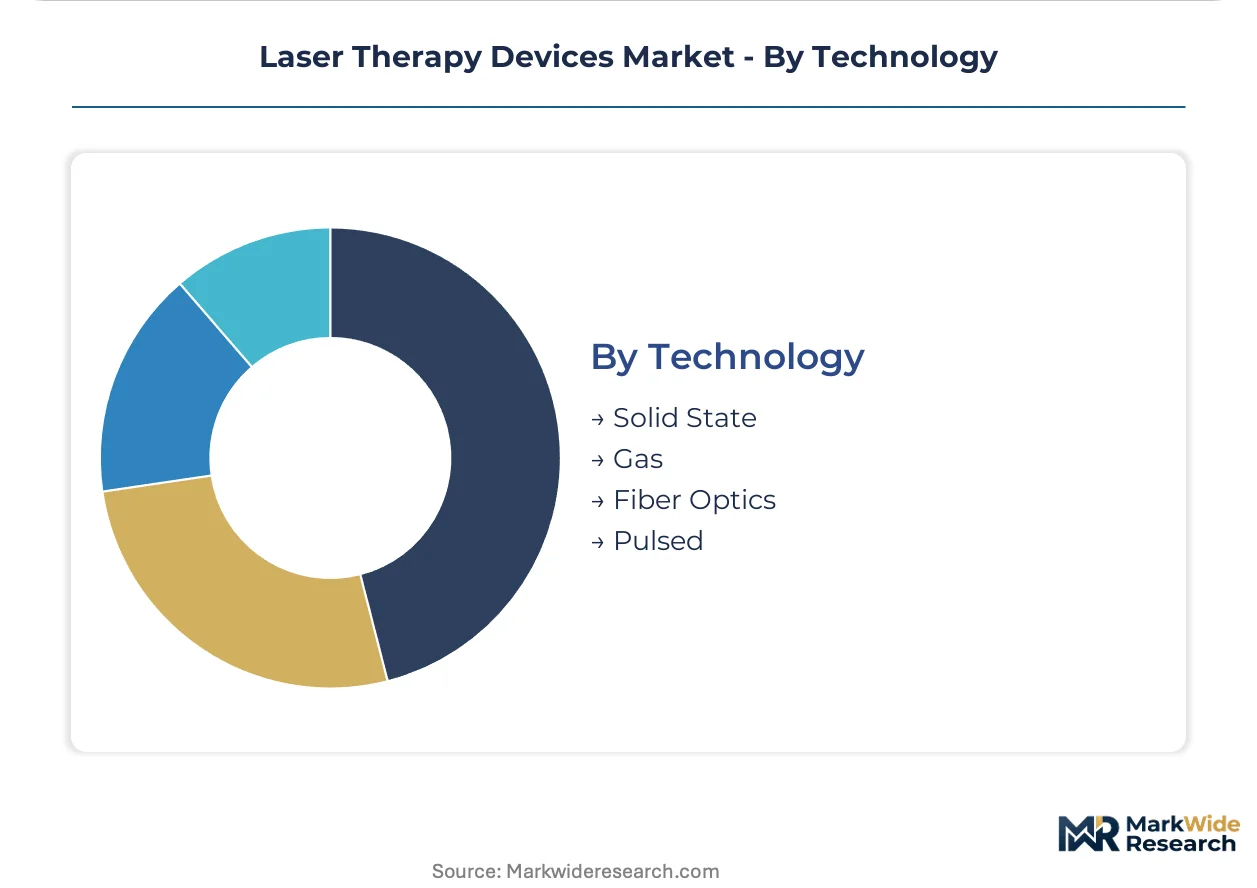
- Pulsed:This category includes picosecond and femtosecond lasers, delivering ultra-short energy pulses for precise tissue interaction with minimal collateral damage. High-end aesthetic and ophthalmology centers increasingly adopt these advanced systems for superior clinical outcomes.
- Solid State:Nd:YAG and Alexandrite lasers fall into this category, using crystalline gain media to produce specific wavelengths. These robust and versatile systems remain foundational for many dermatological and aesthetic applications globally.
- Gas:CO2 and Argon lasers are examples of gas lasers, known for their high power and specific wavelengths suitable for surgical cutting and ablation. Hospitals widely deploy these established technologies for various surgical specialties.
- Fiber Optics:Fiber lasers offer compact designs and efficient beam delivery through optical fibers, making them suitable for endoscopic procedures and precision micro-machining. These systems provide flexibility and enhanced access in complex medical interventions.
Pulsed laser technology represents a significant innovation, driving advancements in precision and patient safety.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Expertise in laser therapy device development concentrates across key global markets, driven by both advanced technological ecosystems and significant clinical demand. These regions also host stringent regulatory bodies that shape product innovation and market access. Strong consumer preference for aesthetic procedures further propels adoption in specific countries.
United States
Demand for cosmetic surgery applications, including skin rejuvenation and hair removal, drives significant sales of Nd:YAG and Alexandrite laser systems. The FDA's 510(k) clearance process rigorously evaluates device safety and efficacy. Major medical device hubs in California, particularly around San Jose, foster innovation in advanced laser system development.
Germany
Specialized dermatology centers in Germany increasingly adopt Alexandrite lasers for their clinical efficacy in epidermal pigmentary lesions. The EU's Medical Device Regulation (MDR) sets comprehensive standards for clinical evidence and post-market surveillance. Bavaria serves as a key region for medical technology manufacturing, housing companies focused on precision laser component production.
China
Rising disposable incomes and a growing focus on personal appearance fuel the market for aesthetic laser devices in China. China's NMPA enforces stringent clinical data requirements, shaping product development timelines. Industrial parks in Shenzhen are becoming centers for advanced medical laser device assembly and distribution.
Brazil
Consumer preference for non-invasive cosmetic procedures, including tattoo and hair removal, propels the adoption of Nd:YAG systems in Brazil. ANVISA's rigorous approval pathways create significant barriers to entry for new laser therapy devices. São Paulo represents a vibrant hub for aesthetic medicine, with numerous clinics investing in high-end laser technology.
Japan
Advanced ophthalmology and high-end aesthetic clinics in Japan show strong demand for picosecond and femtosecond lasers, valuing precision. The PMDA regulates medical devices, requiring thorough clinical data and post-market vigilance. Tokyo's medical technology clusters actively research and develop next-generation ultra-short pulse laser systems.
Laser Therapy Devices Market Key Industry Players
Specialized instrument manufacturers and broader portfolio providers split the laser therapy devices market, creating a tiered competitive landscape. This market structure is characterized by a mix of established players with extensive installed bases and agile innovators focusing on niche applications. Strategic partnerships for technology co-development and portfolio diversification through M&A are common competitive moves. Manufacturers also increasingly invest in post-sale training programs to differentiate their offerings.
Within the high-end aesthetic and ophthalmic segments, Lumenis exemplifies a strategy centered on leveraging an extensive installed base and comprehensive tiered training programs. Cynosure, known for its educational partnerships with key opinion leaders in dermatology, represents manufacturers focused on specialized market differentiation. Fotona further showcases this specialization, providing targeted workshops for its advanced dental and surgical laser systems, highlighting the market's shift towards procedural specificity and post-sale support.
| Leading Market Players |
|---|
| Fotona |
| BIOLITEC |
| Lumenis |
| Asclepion Laser Technologies |
| Quanta System |
| Cynosure |
| Cutera |
| El.En. Group |
| Syneron Candela |
| Others |
Cost & Logistics Intelligence
Trans-Pacific shipping lanes' cost dynamics directly influence the supply concentration of high-end laser components, shaping price differentiation for advanced laser therapy devices. This interplay affects manufacturers' profitability and market accessibility across key regions.
Pricing Analysis
After-sales training and certification programs significantly drive lifetime value for laser therapy device manufacturers. The dominant pricing model is value-based, reflecting device precision and clinical outcomes. Price differentiation stems from FDA/CE certification levels and the breadth of post-sale support offerings. Pricing softness reflects competition from alternative technologies in some aesthetic applications. Smaller, independent clinics exhibit higher price sensitivity compared to large hospital systems.
Supply Chain Analysis
Export controls on advanced laser components, particularly those originating from technologically advanced nations, limit global flows. Supply concentration for specialized optics and gain media resides primarily in Germany, Japan, and the United States. Manufacturers depend on high-precision optical fibers and specialized cooling units. Regulatory restrictions, such as CE marking requirements, pose a structural risk by delaying market entry. Distribution runs through direct sales channels to specialized clinics and hospital procurement departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a service-attach opportunity, as after-sales training and certification programs are expanding faster than hardware sales. This trend creates new profitability models for manufacturers.
For Market Incumbents:
Harden existing customer relationships by deepening post-sale training ecosystems for complex multi-wavelength systems. Invest strategically in cybersecurity compliance for connected devices to mitigate evolving data privacy risks. This defends against competition from alternative aesthetic technologies and secures market share through superior service. Leverage R&D into next-generation picosecond and femtosecond lasers as a key lever for differentiation.
For New Entrants and Emerging Players:
Pursue white-space opportunities in emerging therapeutic fields like pain management and wound healing, which offer less saturated markets. Target the home care segment with lower-power, simplified diode lasers for basic aesthetic treatments, representing a penetrable, cost-sensitive application. A viable go-to-market angle involves direct-to-consumer sales channels or partnerships with physical therapy and rehabilitation clinics.
For Investors and Strategic Acquirers:
Carve-out targets emerge from diversified medical technology conglomerates seeking to divest non-core laser therapy device units. The long-term viability of this market is strong, driven by persistent aesthetic demand and expanding clinical applications. Acquisition target archetypes include niche specialists in ultra-short pulse laser technology or developers of AI-driven software for treatment planning. An acceleration of regulatory approvals for new therapeutic indications serves as a critical signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Post-Sale Training Programs | Boosts customer loyalty and enhances practitioner proficiency for complex systems. |
| Invest in Cybersecurity Compliance | Mitigates data privacy risks for connected devices, meeting evolving regulatory standards like HIPAA. |
| R&D in Ultra-Short Pulse Lasers | Drives market leadership in high-end aesthetic and ophthalmology applications, offering superior clinical outcomes. |
| Geographic Expansion into Southeast Asia | Captures new aesthetic market demand driven by rising disposable incomes and focus on personal appearance. |
| Develop AI-Driven Treatment Planning Software | Creates new value propositions and service-based revenue streams through enhanced device intelligence. |
Research Approach
Initial hypotheses were tested against primary input from aesthetic clinic owners, hospital procurement managers, device R&D leads, and regulatory affairs specialists, and refined through iterative feedback. This involved combining insights from direct interviews with extensive secondary validation. Bottom-up and top-down triangulation ensured data consistency across various sources.
The demand-supply balance for laser therapy devices was critically assessed across the analysis window. Segmentation dimensions modeled included product type, end-user, application, technology, and regional regulatory landscapes. Compound annual growth rates were derived from historical data analysis and projected market dynamics. Industry-specific forecast inputs included technological advancements in laser chromophore targeting and evolving regulatory approval timelines.
Sensitivities concentrate around shifts in regulatory stringency, unforeseen technological breakthroughs, or significant changes in consumer aesthetic preferences. Forecasts reflect assumptions regarding market entry barriers and R&D investment. Material shifts in device approval pathways would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Intraoral Scanners Market
Medical Devices
Saudi Arabia Artificial Organs and Bionic Implants Market
Medical Devices
X-Ray Positioning Devices Market
Medical Devices
Global Wearable Injectors Market
Medical Devices
Remote Magnetic Catheter Systems Market
Medical Devices
Global Walking Assist Devices Market
Medical Devices
ADA Substitute Market
Medical Devices
Brazil Drug Delivery Devices Market
Medical Devices
Steroid Releasing Implant Market
Medical Devices
Meniscal Rasps Market
Medical Devices
Asia-Pacific Ostomy Care and Accessories Market
Medical Devices
Epidural Anesthesia Sets Market
Medical Devices
Partial Ossicular Replacement Prosthesis Market
Medical Devices
Spinal Non-Fusion Technologies Market
Medical Devices
Embolic Protection Systems Market
Medical Devices
Cardiopulmonary Bypass System Market