
 Traditional Chinese Herbal Medicine Market | 2026-2036
Traditional Chinese Herbal Medicine Market Size, Share, and Industry Trends Forecast 2026-2036
Traditional Chinese Herbal Medicine Market Insights
Subscription-based practitioner education and tele-consultation platforms is restructuring how Traditional Chinese Herbal Medicine reaches end-users. Beijing Tongrentang Chinese Medicine Co., Ltd. anchors its position through vertically integrated cultivation-to-dispensing operations across Hebei and Shanxi provinces. Yunnan Baiyao differentiates via proprietary wound-healing formulations that command premium positioning in hospital procurement channels. TSUMURA dominates Japan's Kampo reimbursement landscape through pharmacoeconomic validation of its standardized extract portfolio.
Traditional Chinese Herbal Medicine comprises botanical substances processed through decoction, extraction, granulation, or tableting to yield therapeutically active preparations standardized by marker compound content. These preparations serve clinical treatment protocols, preventive regimens, and wellness maintenance programs across institutional and consumer settings. Decoction and granule formats capture the largest volume pools due to practitioner familiarity and reimbursement alignment, while tincture formulations represent the fastest-expanding segment driven by convenience-seeking younger consumers in digital channels. Composite formula preparations command margin concentration because multi-herb synergies justify premium pricing and create formulation-level intellectual property barriers.
China's NMPA enforces Good Manufacturing Practice for Pharmaceutical Products and Good Agricultural Practice for Crude Drugs, mandating heavy metal and pesticide residue thresholds that filter small-scale suppliers from commercial supply chains. Japan's PMDA maintains Kampo-specific approval pathways requiring equivalence to classical references, creating dual-track regulatory complexity for cross-border manufacturers. China's SAMR and Japan's MHLW coordinate loosely on botanical nomenclature standards, leaving persistent gaps in species authentication that stakeholders must monitor through DNA barcoding investments and third-party certification adoption.
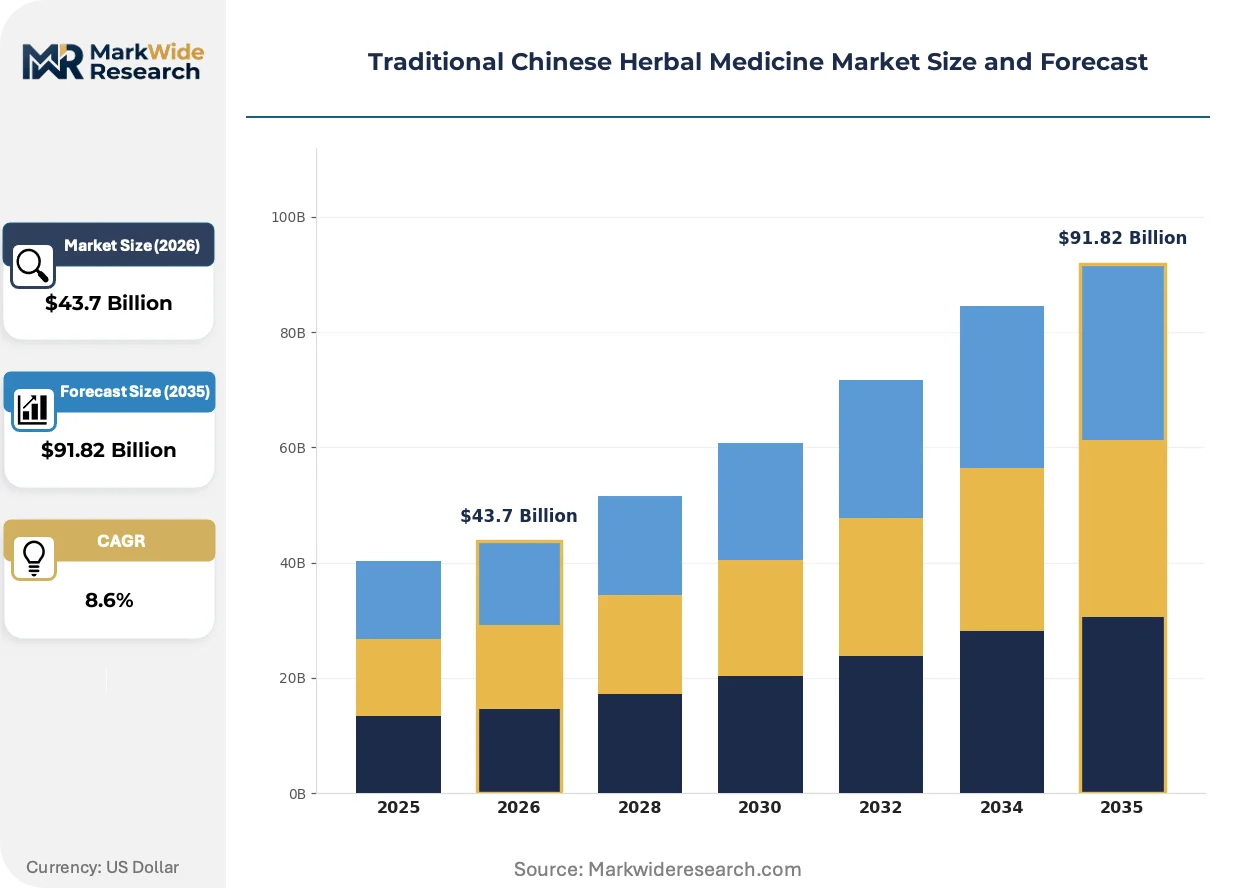
Market Dynamics
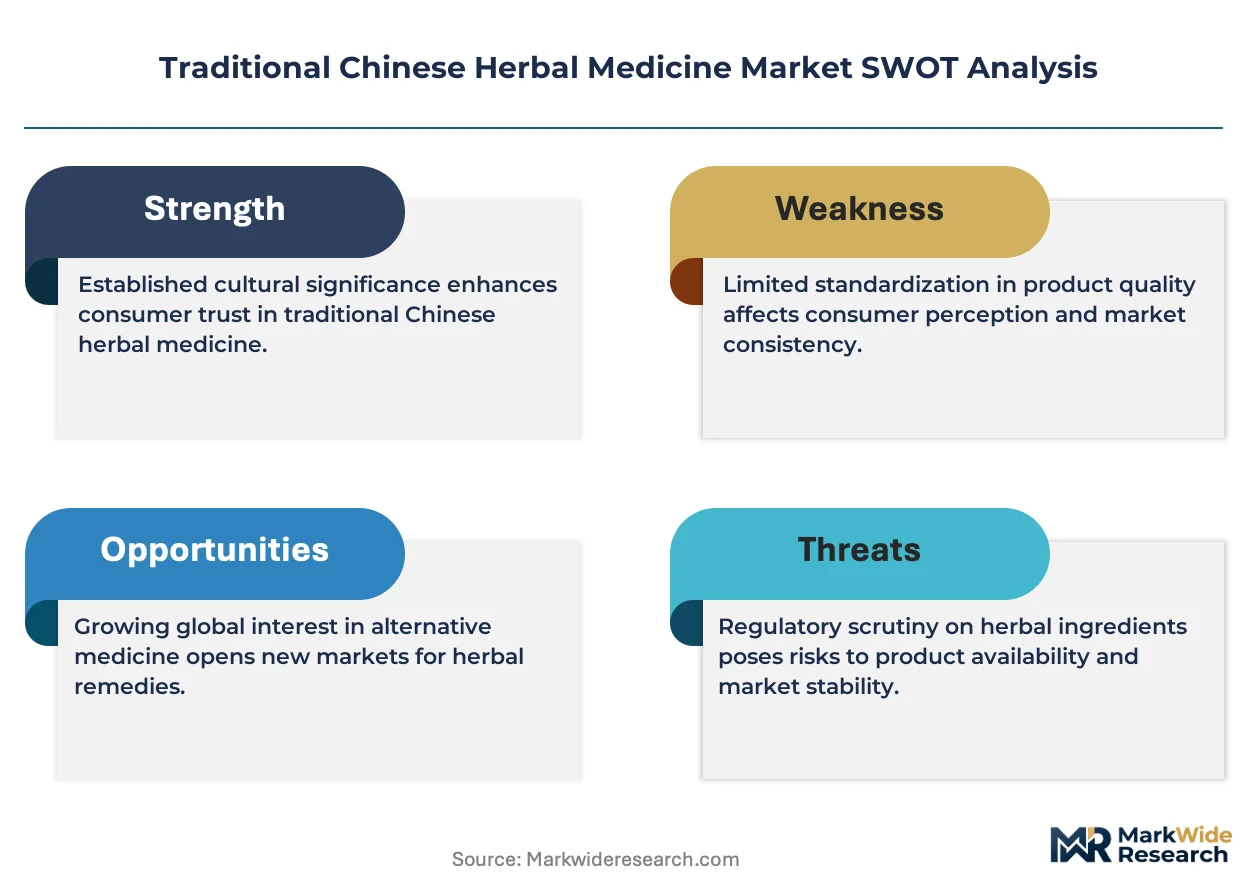
Standardization pressure from Japan's PMDA and China's NMPA is compressing informal supply chains while concentrating procurement authority in hospital networks and reimbursement-aligned dispensaries. This regulatory convergence favors manufacturers with pharmacoeconomic validation capabilities and DNA authentication infrastructure.
Growth Catalysts
- Japan's Kampo reimbursement expansion:PMDA-approved standardized extracts now cover geriatric protocols for chronic conditions, pulling volume through hospital formularies and extending coverage to preventive indications.
- Tele-consultation platforms:Digital channels connect licensed practitioners to patients seeking preventive regimens, bypassing geographic constraints on traditional clinic access.
- Heavy metal testing mandates:China's NMPA Good Agricultural Practice thresholds for cadmium and arsenic are filtering small-scale wild-crafters from commercial supply, consolidating volume with certified cultivation operations.
Market Restraints
- Input cost volatility:Climate-sensitive botanicals including Astragalus and Licorice root face harvest variability across Gansu and Inner Mongolia growing regions, compressing margins for non-integrated processors.
- Dual-track regulatory friction:Japan's PMDA requires classical reference equivalence for Kampo approvals while China's NMPA permits marker-compound standardization, forcing manufacturers to maintain separate formulation dossiers.
- Substitution threat from synthetic peptides:Biopharmaceutical alternatives for wound healing and inflammation are displacing premium herbal extracts in hospital procurement evaluations.
Strategic Opportunities
- Germany's integrative wellness centers:Preventive protocol adoption in Munich and Berlin clinics creates demand for decoction-compatible granule formats outside traditional TCM patient bases.
- Subscription-based practitioner education:Continuous certification platforms lock in prescriber loyalty while capturing data on formula preferences and patient outcomes.
- DNA barcoding convergence with blockchain traceability:Species authentication technology combined with immutable chain-of-custody records commands premium positioning in export markets.
Industry Challenges
- Classical reference sourcing:Kampo manufacturers struggle to locate authenticated texts for PMDA equivalence submissions, extending approval timelines and raising documentation costs.
- Granulation equipment capex intensity:Spray-drying and fluid-bed processing lines require seven-figure capital commitments, excluding mid-scale processors from hospital contract eligibility.
- Cross-border nomenclature gaps:SAMR and MHLW coordinate loosely on Latin binomial standards, creating customs delays and species misidentification risks in multi-origin supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Traditional Chinese Herbal Medicine Market |
| Market Size in 2026 | $43.7 Billion |
| Market Size in 2035 | $91.82 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Decoction, Granule, Pill, Tincture Formulation Type: Single Herb, Composite Formula, Extract, Powder Usage Scenario: Preventive Care, Therapeutic Application, Health Maintenance, Wellness Support Distribution Channel: Retail, Online Store, Herb Shop, Pharmacy |
| Companies Covered | Beijing Tongrentang Chinese Medicine Co., Ltd., China National Pharmaceutical Group Co Ltd., Yunnan Baiyao, Tianjin Tasly Group, Kangmei Pharmaceutical Co., Ltd., Zhangzhou Pien Tze Huang Pharmaceutical Co., Ltd., China Traditional Chinese Medicine Holdings Co., Ltd., Sanjiu, TSUMURA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Traditional Chinese Herbal Medicine Market Trends and Innovations
Digital authentication tools and extraction technology advances are compressing quality variance between traditional decoctions and industrial preparations. These shifts favor manufacturers with laboratory infrastructure over artisanal processors.
Marker-compound quantification via HPLC and mass spectrometry is consolidating quality control standards across previously fragmented supply bases. Hospital procurement departments in Osaka and Shanghai now require batch-level certificates of analysis, compressing acceptance rates for uncertified suppliers. This technology is consolidating procurement authority with integrated manufacturers capable of in-house analytical validation.
China's NMPA revised Good Agricultural Practice standards now mandate pesticide residue thresholds for 226 botanical species. Cultivation operations in Hebei and Yunnan provinces face soil remediation costs or contract farming restructuring. Shanxi-based processors are responding by consolidating backward control over seed stock and drying facilities to ensure compliance documentation.
Younger consumers in digital channels favor tincture and capsule formats over traditional decoction preparation. E-commerce platforms in Japan and Germany now feature Kampo and TCM products in wellness subscription boxes, displacing pharmacy-centric distribution. This behavioral shift concentrates volume with brands possessing direct-to-consumer logistics capabilities and dosage-form versatility.
Traditional Chinese Herbal Medicine Market Segmentation
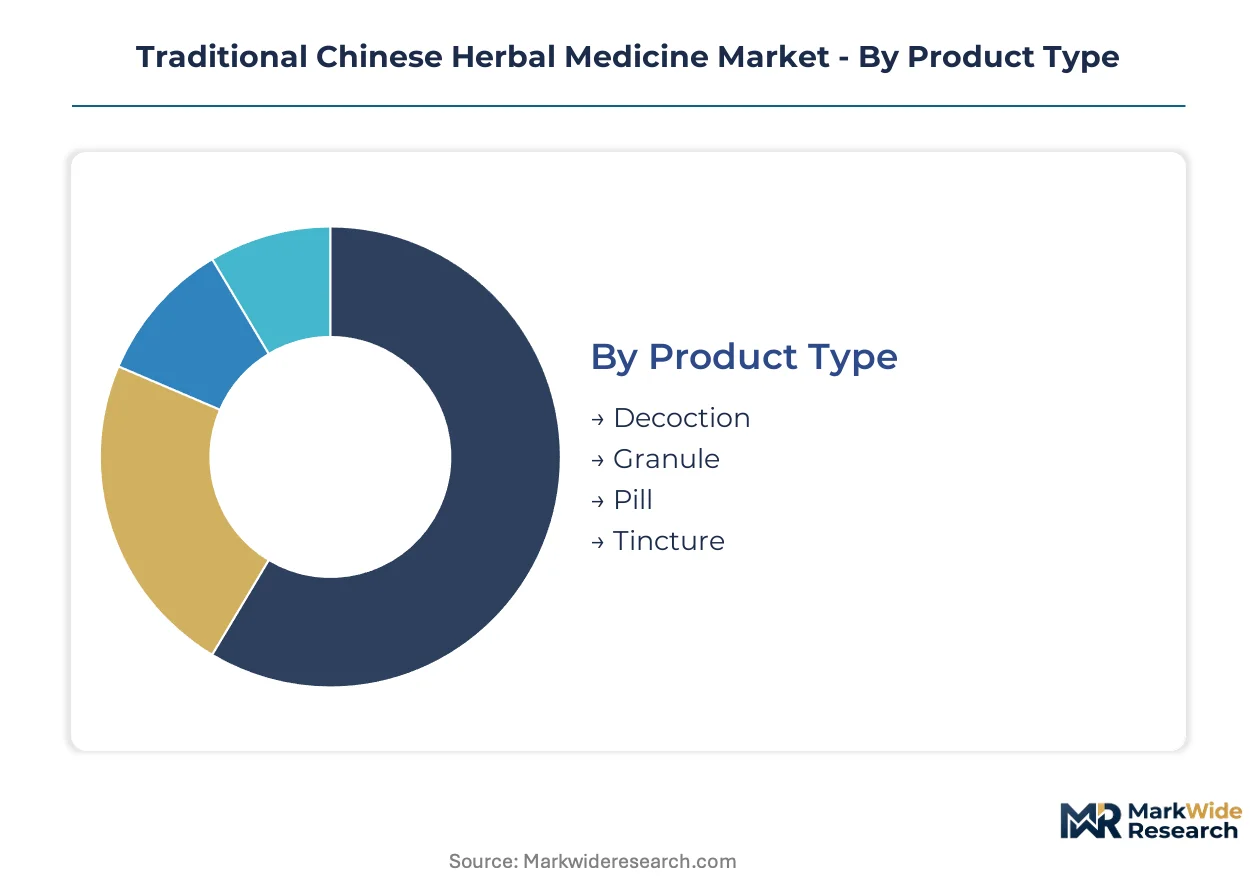
Traditional Chinese Herbal Medicine segments reveal divergent supply chain requirements across preparation formats and distribution pathways. Product type and formulation complexity determine whether manufacturers invest in extraction infrastructure or outsource to contract processors.
Product Type:
Supply concentration in spray-drying and fluid-bed processing equipment favors large-scale manufacturers in Hebei and Shanxi provinces.
- Decoction:Raw botanicals simmered in water to release active constituents, requiring precise temperature protocols and extended preparation time. Hospital dispensaries in Osaka and Shanghai maintain decoction services for chronic condition protocols, though labor intensity limits scalability outside institutional settings.
- Granule:Spray-dried extracts reconstituted with hot water, offering batch-to-batch consistency through marker compound standardization. Japan's PMDA reimbursement alignment pulls volume through hospital formularies, with TSUMURA and domestic Chinese manufacturers competing on pharmacoeconomic validation.
- Pill:Compressed or coated solid dosage forms enabling precise dosing and extended shelf stability. Compact storage requirements suit pharmacy retail channels in Germany's integrative wellness centers.
- Tincture:Alcohol-based extractions concentrating lipophilic compounds with rapid absorption kinetics. Younger consumers in Japanese and German digital channels favor this convenience format, bypassing traditional preparation barriers.
Decoction absorbs the bulk of installed capacity; tincture is expanding most quickly.
Formulation Type:
Margin structures vary sharply between single-species commodities and proprietary multi-herb combinations.
- Single Herb:Individual botanical preparations standardized to marker compound thresholds, functioning as modular inputs for practitioner customization. Astragalus and Licorice root concentrates from Gansu cultivation zones supply compounders across East Asia.
- Composite Formula:Multi-herb synergistic preparations creating formulation-level intellectual property barriers. Yunnan Baiyao's proprietary wound-healing combinations command premium hospital procurement positioning through clinical outcome documentation.
- Extract:Concentrated active fractions produced via solvent extraction or supercritical CO2 processing. China's NMPA heavy metal testing mandates filter small-scale wild-crafters, consolidating supply with certified extraction facilities.
- Powder:Finely milled raw botanicals for encapsulation or direct consumption. Lower processing intensity enables mid-scale processor participation, though batch variability challenges hospital procurement departments.
Composite Formula captures the steepest margin expansion; Extract faces the tightest regulatory compliance costs.
Usage Scenario:
Reimbursement alignment determines whether demand flows through institutional channels or self-pay wellness markets.
- Preventive Care:Regimens targeting subclinical imbalances before disease manifestation. Germany's Munich and Berlin integrative wellness centers incorporate these protocols, creating demand outside traditional TCM patient bases.
- Therapeutic Application:Clinical treatment protocols for diagnosed conditions with documented efficacy. Japan's Kampo reimbursement expansion now covers geriatric chronic conditions, pulling standardized extracts through hospital formularies.
- Health Maintenance:Sustained regimens for vitality preservation in aging populations. China's urban middle-class consumers self-fund these applications through direct-to-consumer e-commerce platforms.
- Wellness Support:Lifestyle-integrated products for stress modulation and immune function. Subscription boxes in Japanese and German digital channels concentrate volume with brands possessing logistics versatility.
Therapeutic Application commands the largest reimbursed volume; Wellness Support is climbing the fastest through digital channels.
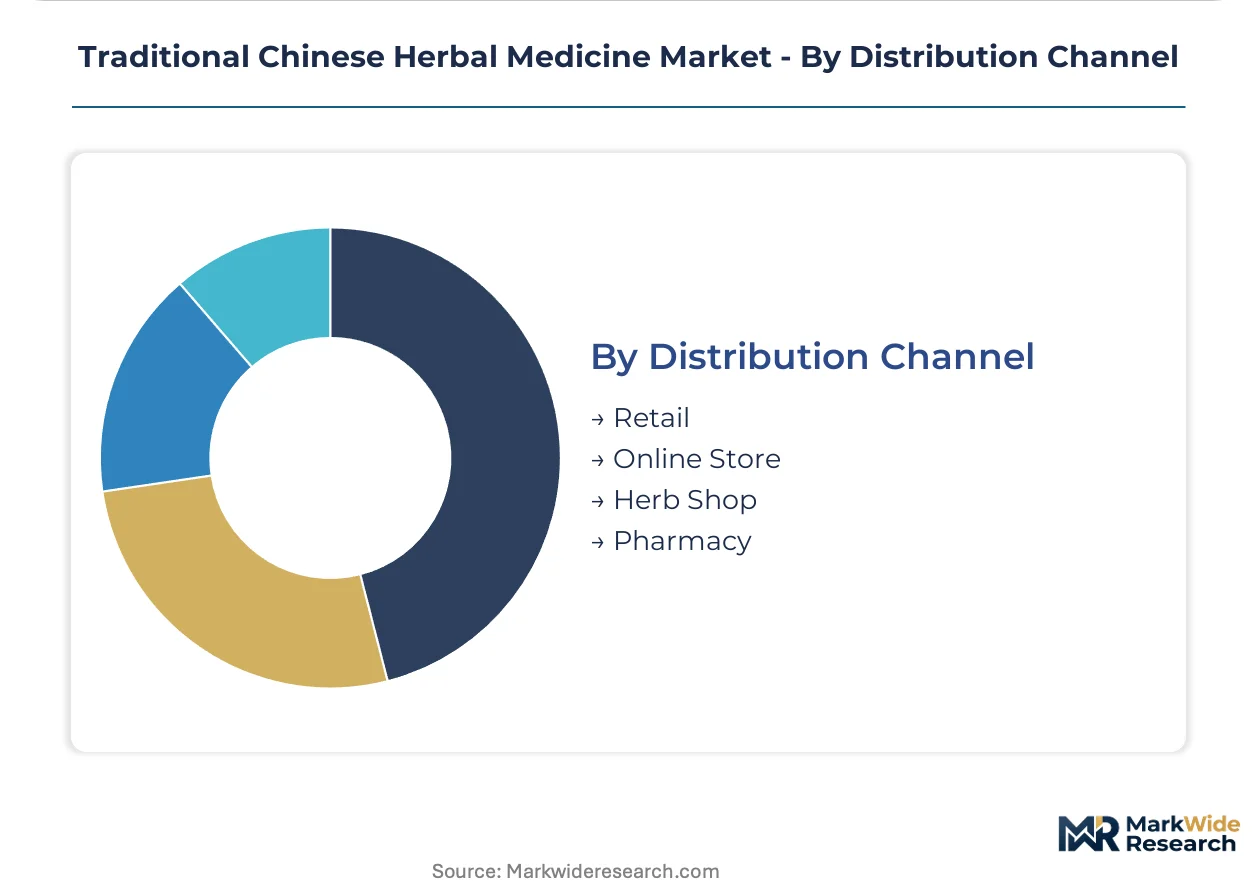
Distribution Channel:
Channel selection determines authentication requirements and margin retention for manufacturers.
- Retail:Physical storefronts including supermarkets and general merchandise outlets. Limited SKU depth and minimal practitioner guidance restrict premium product placement.
- Online Store:Direct-to-consumer platforms and marketplace listings enabling subscription models. DNA barcoding and blockchain traceability claims command premium positioning in export-oriented channels.
- Herb Shop:Specialist retailers with trained staff providing formula consultation. Traditional stronghold for decoction ingredients and custom compounding services in Chinese urban centers.
- Pharmacy:Licensed dispensaries with reimbursement connectivity and pharmacist oversight. Japan's hospital-adjacent pharmacies dominate Kampo standardized extract distribution.
Pharmacy retains the highest-value transactions; Online Store is gaining share fastest among younger demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China dominates production through cultivation clusters in Hebei and Yunnan provinces, while Japan and Germany absorb premium consumption through reimbursement-aligned channels and integrative wellness centers respectively.
China
NMPA's revised Good Agricultural Practice standards mandate heavy metal thresholds for 226 botanical species. Cultivation operations in Hebei and Shanxi provinces consolidate backward control over seed stock and drying facilities. Beijing-Tianjin-Hebei corridor anchors vertically integrated processing infrastructure serving domestic hospital networks.
Japan
PMDA-approved Kampo extracts now cover geriatric protocols for chronic conditions, pulling volume through hospital formularies. METI coordinates loosely with China's SAMR on botanical nomenclature standards. Osaka and Tokyo metropolitan areas concentrate hospital-adjacent pharmacy distribution for standardized extract products.
Germany
Munich and Berlin integrative wellness centers incorporate decoction-compatible granule formats into preventive protocols. EFSA botanical safety assessments influence import documentation requirements. Bavaria and North Rhine-Westphalia host the densest concentration of clinics prescribing TCM formulations outside traditional patient bases.
United States
FDA dietary supplement enforcement prioritizes cGMP compliance for botanical ingredient suppliers. California and New York metropolitan areas drive direct-to-consumer demand through tele-consultation platforms connecting licensed practitioners to patients. Los Angeles and San Francisco Bay Area clusters concentrate wellness-focused e-commerce distribution.
Traditional Chinese Herbal Medicine Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across extraction and formulation tiers. Hospital procurement consolidation favors integrated manufacturers with in-house analytical validation and DNA authentication infrastructure. Three archetypes dominate: vertically integrated cultivation-to-dispensing operators, standardized extract specialists with pharmacoeconomic validation capabilities, and proprietary formula holders commanding premium positioning through clinical outcome documentation. Competitive moves concentrate on backward integration into certified cultivation zones and subscription-based practitioner education platforms that lock in prescriber loyalty.
Within the cultivation-integrated tier, Beijing Tongrentang Chinese Medicine Co., Ltd. exemplifies the vertically integrated archetype through operations spanning Hebei and Shanxi provinces. Yunnan Baiyao occupies a position among proprietary formula holders, while TSUMURA anchors the standardized extract specialist category. These three represent the strategic positioning spectrum from upstream supply control through formulation-level intellectual property to reimbursement-aligned pharmacoeconomic validation.
| Leading Market Players |
|---|
| Beijing Tongrentang Chinese Medicine Co., Ltd. |
| China National Pharmaceutical Group Co Ltd. |
| Yunnan Baiyao |
| Tianjin Tasly Group |
| Kangmei Pharmaceutical Co., Ltd. |
| Zhangzhou Pien Tze Huang Pharmaceutical Co., Ltd. |
| China Traditional Chinese Medicine Holdings Co., Ltd. |
| Sanjiu |
| TSUMURA |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between DNA-authenticated extracts and commodity-grade powders manifests in both hospital procurement premiums and cultivation-zone consolidation patterns. China's NMPA heavy metal mandates compress informal wild-crafting channels while concentrating volume with Hebei and Shanxi operations capable of batch-level analytical documentation.
Pricing Analysis
Margin tightening in granule formats reflects spray-drying equipment capex intensity and PMDA pharmacoeconomic validation requirements. Three-tier pricing structure across premium authenticated extracts, standard certified granules, and economy-grade raw powders separates reimbursement-aligned hospital buyers from self-pay wellness consumers. Cost-down pressure on single-herb commodities accelerates because climate-sensitive Astragalus and Licorice harvests face yield variability across Gansu growing regions. Pharmacy and hospital procurement departments exhibit lowest price sensitivity due to reimbursement connectivity, while direct-to-consumer digital channels drive hardest bargain for convenience formats.
Supply Chain Analysis
Direct-to-hospital channels handle standardized extract demand from Japan's Kampo reimbursement expansion, while herb shops and tele-consultation platforms manage decoction and granule fulfillment. Geographic supply concentration centers on China for cultivation and extraction infrastructure, Japan for PMDA-validated manufacturing, and Germany for integrative wellness center distribution. Raw material dependencies rest on climate-vulnerable botanicals from specific growing zones, solvent extraction chemicals, and analytical reagents for marker-compound quantification. Single-source vulnerability in authenticated classical text sourcing for Kampo approvals creates regulatory friction risk. Distribution runs through hospital-adjacent pharmacies in Osaka and Tokyo, certified dispensaries in Munich and Berlin, and direct-to-consumer platforms in Los Angeles and New York metropolitan areas.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marker-compound quantification via HPLC and mass spectrometry is displacing organoleptic quality assessment, compressing margins for processors lacking laboratory infrastructure while rewarding integrated manufacturers with in-house analytical capabilities.
For Market Incumbents: Lock in prescriber loyalty through subscription-based practitioner education platforms that capture formula preference data and patient outcome metrics. Deepen backward integration into Hebei and Shanxi certified cultivation zones to secure NMPA-compliant supply documentation and buffer against climate-driven input cost volatility. Synthetic peptide substitution threats in wound healing and inflammation applications demand clinical outcome documentation investments to defend hospital procurement positioning. For New Entrants and Emerging Players: Tele-consultation platforms serving preventive care regimens offer the most penetrable entry vector, bypassing geographic constraints on traditional clinic access and capturing younger consumers favoring convenience formats. White-space concentration exists in Germany's Munich and Berlin integrative wellness centers where decoction-compatible granule formats gain traction outside traditional TCM patient bases. Direct-to-consumer subscription models with DNA barcoding and blockchain traceability claims command premium positioning in export-oriented channels. For Investors and Strategic Acquirers: Re-rating potential sits with standardized extract specialists possessing PMDA pharmacoeconomic validation capabilities given Japan's Kampo reimbursement expansion into geriatric chronic conditions. Long-term viability over the next decade hinges on regulatory compliance infrastructure rather than formulation heritage alone. Acquisition target archetypes include mid-scale processors with spray-drying capacity and pending NMPA certification, plus tele-consultation platforms with locked-in practitioner networks. The signal to watch is cross-border coordination between China's SAMR and Japan's MHLW on botanical nomenclature standards, which would reduce dual-track regulatory friction and unlock margin expansion for compliant manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| DNA Barcoding Infrastructure Investment | Species authentication technology commands premium hospital procurement positioning in Japan and Germany export markets. |
| Practitioner Education Platform Launch | Subscription-based certification programs lock in prescriber loyalty while capturing formula preference and outcome data. |
| Backward Cultivation Integration | Hebei and Shanxi seed stock and drying facility control ensures NMPA heavy metal compliance documentation. |
| Tele-Consultation Channel Development | Digital platforms bypass geographic constraints on clinic access and capture preventive care demand from younger demographics. |
| PMDA Pharmacoeconomic Validation | Clinical outcome documentation for standardized extracts secures Kampo reimbursement expansion into chronic geriatric protocols. |
Research Methodology
Independent corroboration across cultivation operation executives, hospital procurement managers, Kampo formulary directors, and regulatory affairs specialists underwrites the qualitative findings. Primary interviews with spray-drying equipment operators, DNA barcoding laboratory directors, and tele-consultation platform engineers combined with secondary validation from NMPA filing databases, PMDA approval registries, Japan's MHLW reimbursement bulletins, and Germany's EFSA botanical safety assessments. Bottom-up volume triangulation across preparation formats and top-down value reconciliation across distribution channels ensure consistency.
Rate-of-change decomposition across the projection horizon segments volume and value by preparation type, formulation complexity, usage scenario reimbursement alignment, and regional regulatory cluster. CAGRs derive from modeled adoption curves for tincture formats among younger consumers, PMDA reimbursement expansion timelines for geriatric Kampo protocols, and NMPA compliance filtration effects on supplier counts. Industry-specific forecast inputs include climate yield models for Gansu and Inner Mongolia growing regions and tele-consultation platform penetration rates in California and New York metropolitan areas.
Caveats apply where regulatory coordination between SAMR and MHLW, synthetic peptide substitution acceleration, or classical text authentication bottlenecks could materially shift the outlook. Forecasts reflect documented assumptions regarding reimbursement policy continuity and cultivation zone climate stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Medicine
Electrotherapy Market
Alternative Medicine
Bio Magnetic Ear Stickers Market
Alternative Medicine
Orthomolecular Medicine Market
Alternative Medicine
Disposable Acupuncture Needle Market
Alternative Medicine
Traditional Chinese Medicine Market
Alternative Medicine
Complementary and Alternative Medicine for Anti Aging and Longevity Market
Alternative Medicine
Cold Laser Therapy Market
Alternative Medicine
Acupuncture Lasers Market
Alternative Medicine
Fire Cupping Market
Alternative Medicine
Flower Essences Market
Alternative Medicine
Global Acupuncture Market
Alternative Medicine
Aromatherapy Market
Alternative Medicine
Europe Complementary and Alternative Medicine Market
Alternative Medicine
US Aromatherapy Market
Alternative Medicine
Global Complementary and Alternative Medicines Market
Alternative Medicine
US Chiropractic Market