
 Electrotherapy Market | 2026-2036
Electrotherapy Market Size, Share, and Industry Trends Forecast 2026-2036
Electrotherapy Market Analysis
Aftermarket service revenue is fragmenting across the electrotherapy landscape as manufacturers diversify beyond hardware sales into subscription-based therapy management platforms. Medtronic leverages its deep implantable neuromodulation portfolio to sustain recurring revenue streams from device monitoring and parameter adjustment services. Boston Scientific Corporation anchors its competitive stance through specialized clinical support programs that extend physician training and patient onboarding capabilities.
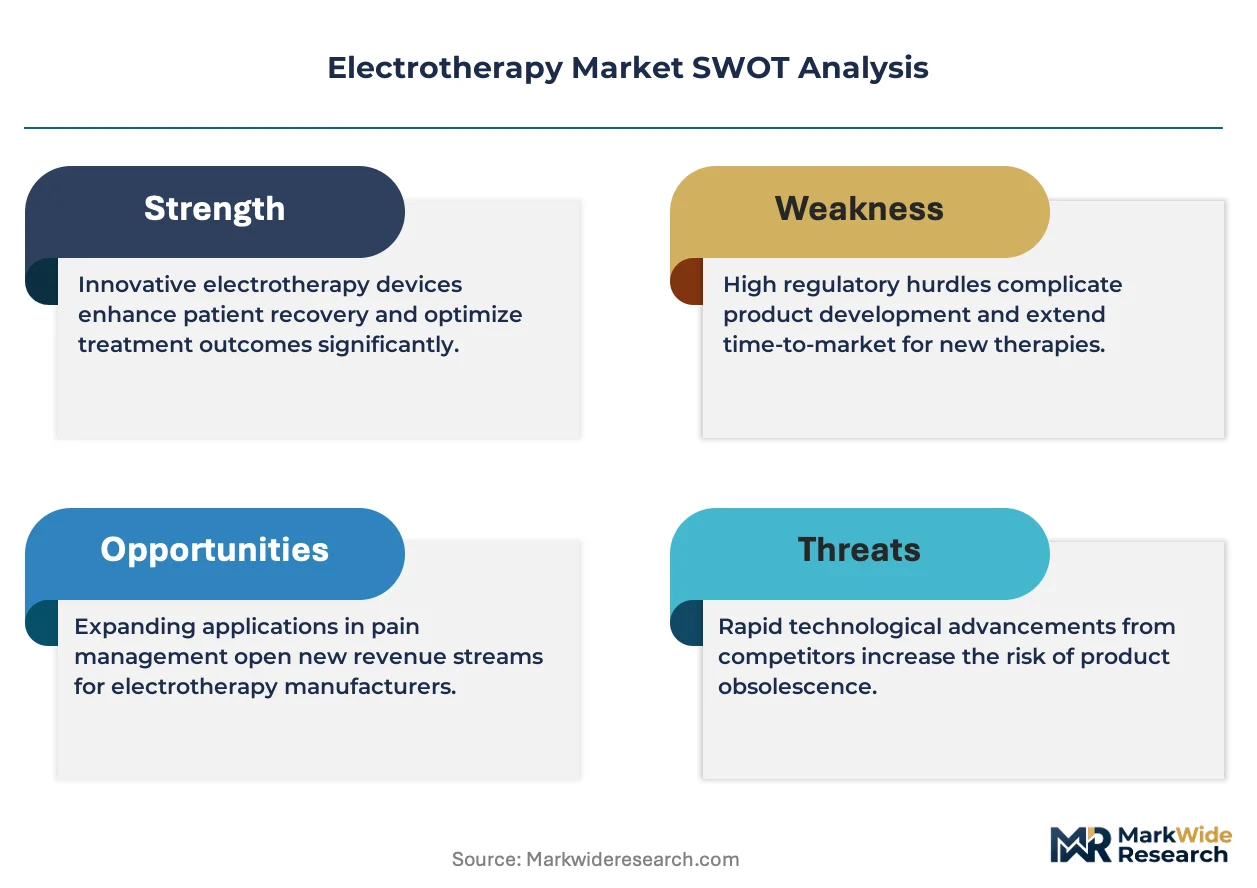
Electrotherapy encompasses the therapeutic application of electrical energy to biological tissue, typically delivered via electrodes at specified frequencies ranging from 0.5 Hz to 120 Hz for pain modulation and 2500 to 4000 Hz for interferential applications, with pulse durations calibrated to activate specific nerve fiber types for analgesic or motor responses. Transcutaneous Electrical Nerve Stimulation devices occupy the most mature product tier with established reimbursement codes, while Pulsed Electromagnetic Field Therapy represents the fastest-growing modality as orthopedic clinics adopt it for post-surgical bone healing protocols. Wireless Devices technology is concentrating margin pools through premium connectivity features that enable remote patient monitoring and real-time dosage adjustment by prescribing physicians.
FDA 510(k) clearances and ISO 13485 quality management standards govern device commercialization in the United States, with the former requiring substantial equivalence demonstrations that lengthen development cycles for novel waveform protocols. The EU MDR framework imposes enhanced clinical evidence requirements on electrotherapy manufacturers seeking CE marking, particularly for implantable spinal cord stimulators classified as Class III devices. Stakeholders must monitor evolving digital health integration requirements as regulators scrutinize cybersecurity protocols for cloud-connected therapy delivery systems.
Market Dynamics
Wireless connectivity architectures are compressing development cycles and fragmenting revenue models as manufacturers pivot from hardware margins to recurring platform fees. This structural shift is reshaping competitive positioning across the electrotherapy value chain.
Growth Catalysts
- FDA 510(k) pathway refinement:Streamlined substantial equivalence demonstrations for incremental waveform innovations are accelerating time-to-market for transcutaneous devices in United States physiotherapy clinics.
- Chronic pain prevalence:Expanding patient pools seeking non-pharmacological interventions are driving device penetration in outpatient rehabilitation settings across Germany and Japan.
- Interferential therapy protocols:Orthopedic post-surgical applications at 2500-4000 Hz frequencies are broadening clinical adoption beyond traditional pain modulation use cases.
Market Restraints
- EU MDR clinical evidence burden:Enhanced requirements for Class III implantable spinal cord stimulators are lengthening CE marking timelines and elevating compliance costs for European market entry.
- Semiconductor supply concentration:Dependence on East Asian foundries for wireless connectivity chipsets creates input volatility for cloud-enabled therapy delivery systems.
- Pharmacological substitution:Sustained-release opioid formulations and non-steroidal anti-inflammatory drug protocols retain physician preference in acute pain management settings.
Strategic Opportunities
- Remote patient monitoring convergence:Integration of electrotherapy parameters with telehealth platforms enables real-time dosage adjustment and recurring subscription revenue streams.
- Post-surgical bone healing protocols:Pulsed Electromagnetic Field Therapy adoption in orthopedic clinics represents underpenetrated application white space with favorable reimbursement trajectories.
- India CDSCO harmonization:Alignment with international quality management standards is reducing regulatory friction for imported neuromodulation devices in South Asian markets.
Industry Challenges
- Embedded systems engineering scarcity:Shortage of firmware developers capable of integrating cybersecurity protocols into Class II and Class III medical devices is compressing product development bandwidth.
- ISO 13485 certification timeline:Extended quality management system audits are delaying commercialization schedules for novel waveform protocols seeking multi-jurisdictional approval.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrotherapy Market |
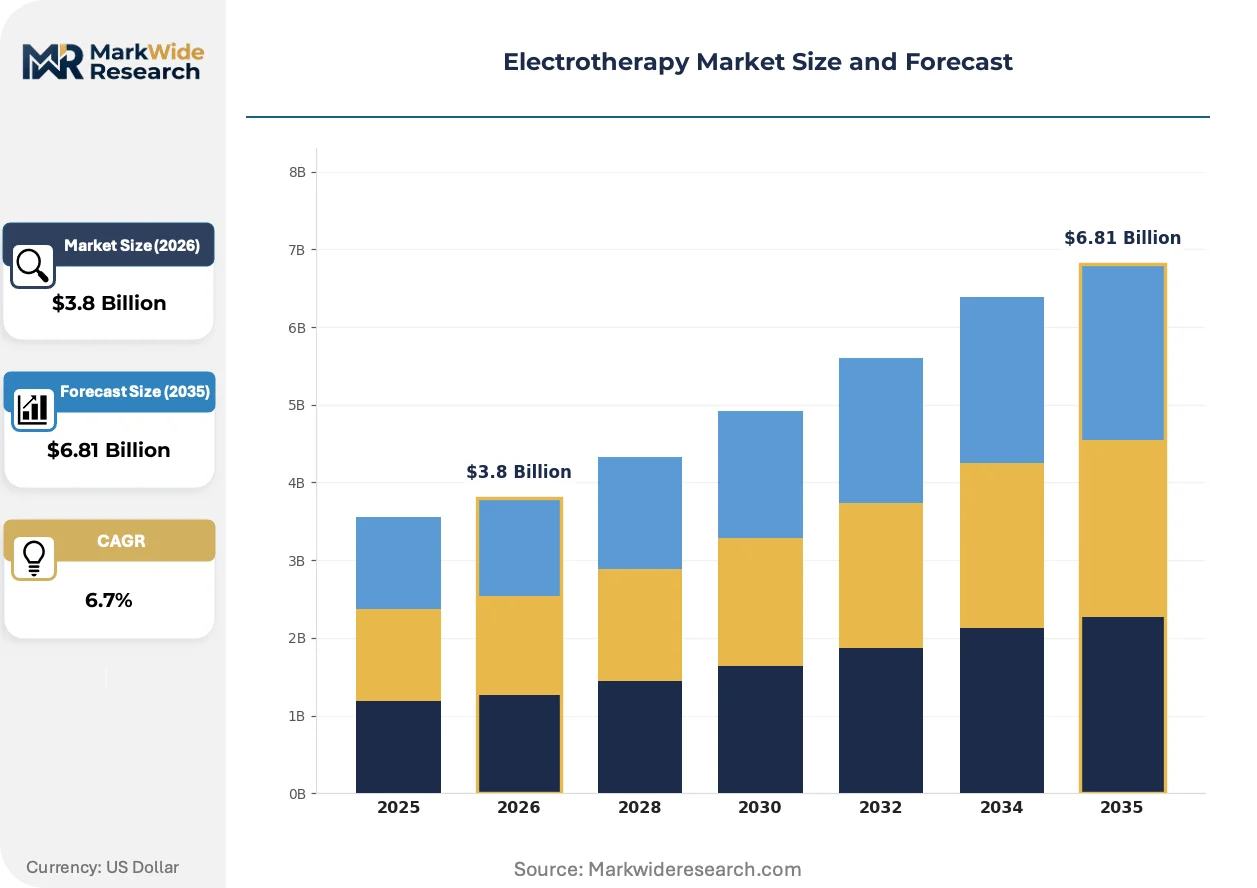
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transcutaneous Electrical Nerve Stimulation, Interferential Current Therapy, Microcurrent Therapy, Pulsed Electromagnetic Field Therapy Application: Physical Rehabilitation, Pain Management, Muscle Strengthening, Wound Healing End User: Hospitals, Physiotherapy Clinics, Homecare Settings, Sports Facilities Technology: Wireless Devices, Rechargeable Units, Portable Systems, Wearable Technology |
| Companies Covered | Medtronic, Boston Scientific Corporation, Abbott Laboratories, BTL Industries, Omron Healthcare, Enovis Corp, Nevro Corp, DJO Global, Zynex Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrotherapy Market Emerging Trajectories
Digital health integration is compressing traditional device-commercialization models and enabling outcome-based reimbursement frameworks. This transformation is manifesting across three distinct vectors reshaping competitive dynamics.
Closed-loop neuromodulation systems incorporating real-time biosignal feedback are enabling automated parameter adjustment without clinician intervention. Pain management centers in the United States are piloting these platforms to reduce manual calibration burden. This technology is digitizing the traditional patient-physician interaction model and compressing service revenue capture toward algorithmic subscription fees.
EU MDR cybersecurity annex requirements are mandating formal threat-risk assessments for cloud-connected therapy delivery systems. Manufacturers must demonstrate secure software development lifecycle protocols to maintain CE marking validity. Implantable spinal cord stimulator portfolios face the steepest compliance burden, with notified bodies scrutinizing wireless transmission encryption standards.
Physician purchasing committees are unbundling device procurement from clinical support services, demanding itemized pricing transparency. Hospital systems in Germany and France are segmenting vendor selection across capital equipment, training, and maintenance contracts. This behavioral shift is most visible in academic medical centers, where value-analysis teams now dominate electrotherapy acquisition decisions.
Electrotherapy Market Segmentation
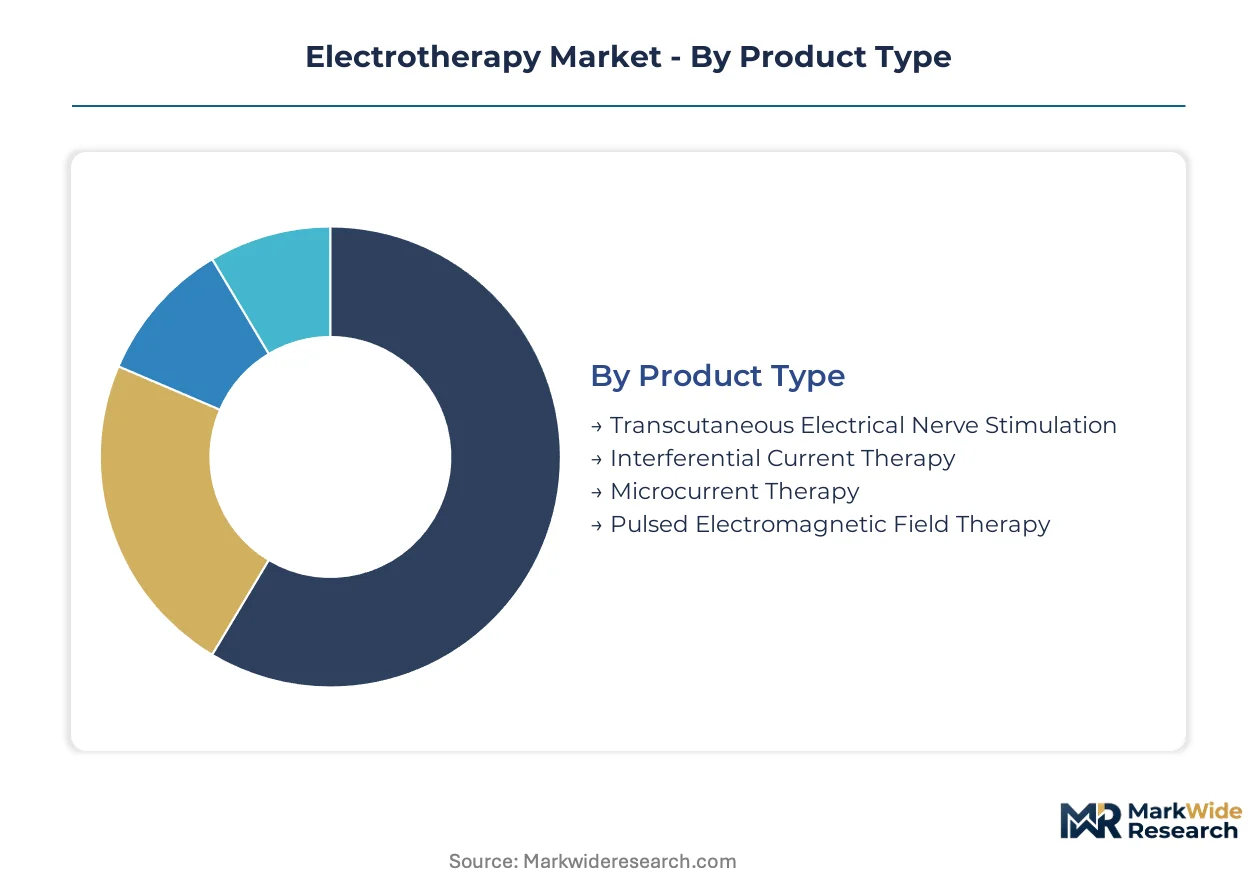
Electrotherapy segmentation reveals distinct technology-adoption curves across clinical and consumer settings. Device specifications, reimbursement pathways, and patient acuity levels create divergent margin structures that manufacturers must navigate strategically.
Product Type:
Pain modulation protocols span frequencies from sub-threshold microcurrent to high-frequency interferential applications, each targeting distinct neural fiber populations and tissue penetration depths.
- Transcutaneous Electrical Nerve Stimulation:Surface electrodes deliver 0.5-120 Hz pulses to modulate nociceptive signaling through gate control mechanisms. Established CPT codes in United States outpatient clinics sustain reimbursement stability, though hardware commoditization pressures margin capture toward consumable electrode sales.
- Pulsed Electromagnetic Field Therapy:Orthopedic post-surgical applications drive adoption as bone-healing protocols expand beyond traditional fracture management. Germany's statutory health insurance framework now covers prescribed PEMF devices for spinal fusion recovery, accelerating clinical penetration.
- Interferential Current Therapy:Crossed 2500-4000 Hz carrier waves achieve deeper tissue penetration than conventional TENS. Physiotherapy clinics in Japan favor this modality for chronic low-back pain protocols.
- Microcurrent Therapy:Sub-sensory amplitude applications target cellular repair mechanisms in wound care and aesthetic medicine. Homecare adoption concentrates among wellness-focused consumers seeking non-invasive facial toning.
The dominant share belongs to Transcutaneous Electrical Nerve Stimulation, while Pulsed Electromagnetic Field Therapy is closing the gap fastest.
Application:
Clinical outcomes and reimbursement density vary sharply across therapeutic intent, with acute intervention commanding premium pricing versus maintenance protocols.
- Pain Management:Non-pharmacological alternatives to opioid protocols concentrate demand in United States pain centers facing prescribing pressure. FDA-cleared devices for chronic lower back and neuropathic pain qualify for durable medical equipment coverage under Medicare Part B.
- Physical Rehabilitation:Post-stroke motor recovery and postsurgical mobility restoration protocols in German rehabilitation hospitals drive institutional procurement cycles. Bundled payment models incentivize device utilization to shorten length-of-stay metrics.
- Muscle Strengthening:Neuromuscular electrical stimulation preserves atrophied tissue during immobilization periods. Sports medicine facilities in Australia integrate these systems into return-to-play protocols for anterior cruciate ligament reconstruction.
- Wound Healing:Electrical stimulation accelerates chronic ulcer closure through enhanced fibroblast migration. Veterans Affairs medical centers deploy these devices for diabetic foot ulcer management.
Pain Management retains the largest addressable base, though Physical Rehabilitation demonstrates the steepest expansion trajectory as bundled care models spread.
End User:
Procurement authority and technical sophistication create four distinct customer archetypes with diverging support requirements and price elasticity.
- Physiotherapy Clinics:Independent practices and franchise networks in France prioritize portable multi-modality systems to maximize treatment room utilization. Leasing arrangements dominate capital-constrained operations.
- Hospitals:Value-analysis committees in United States academic medical centers unbundle device procurement from training and maintenance contracts. ISO 13485 certification gates vendor qualification.
- Homecare Settings:Direct-to-consumer channels bypass clinical gatekeepers for TENS and microcurrent devices. Amazon marketplace penetration concentrates in North American and Western European markets.
- Sports Facilities:Professional team medical staffs and high-performance training centers demand wireless connectivity for real-time dosage monitoring. Bluetooth-enabled systems command 40-60% price premiums over wired equivalents.
Physiotherapy Clinics anchor volume demand, while Homecare Settings are expanding most quickly as wearable form factors reduce clinical dependency.
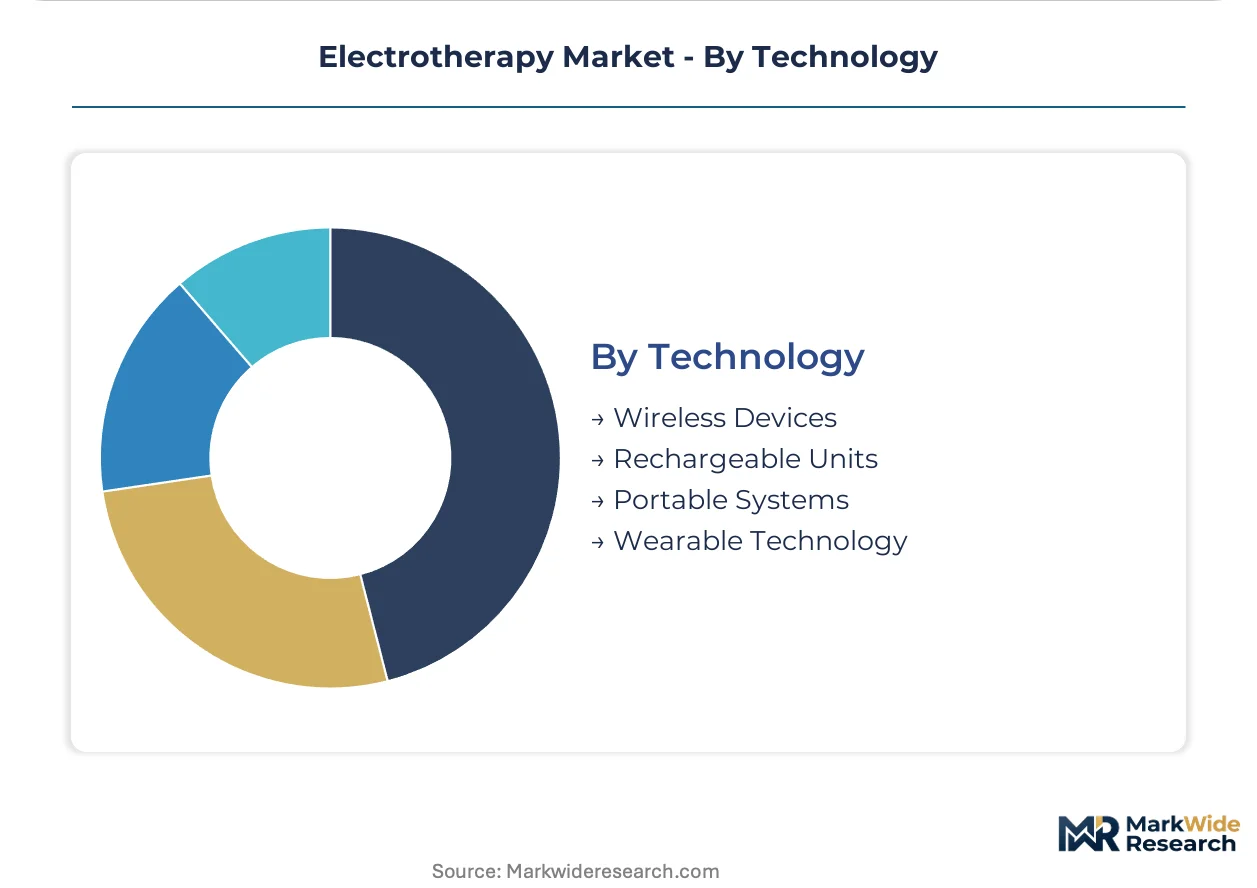
Technology:
Power architecture and connectivity specifications determine regulatory classification, battery lifecycle economics, and remote monitoring capabilities.
- Wireless Devices:Cloud-connected therapy delivery enables real-time parameter adjustment and automated compliance logging. EU MDR cybersecurity annex requirements mandate formal threat-risk assessments for these systems.
- Wearable Technology:Garment-integrated electrode arrays target 24-hour continuous delivery for chronic pain populations. Skin-impedance sensing algorithms auto-adjust output to maintain therapeutic thresholds.
- Rechargeable Units:Lithium-ion battery systems reduce per-treatment operating costs versus disposable cell configurations. Japanese manufacturers lead energy density optimization for implantable neuromodulation applications.
- Portable Systems:Battery-operated devices with preset clinical protocols serve mobile physiotherapy services and home nursing visits. Carry-case design and electrode storage integration influence purchasing decisions.
Wireless Devices command the premium tier, though Wearable Technology is gaining share fastest as consumer aesthetics converge with clinical efficacy requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: United States facilities prioritize implantable neuromodulation systems with remote monitoring, while German and Japanese markets favor non-invasive surface electrotherapy protocols in outpatient rehabilitation settings.
United States
Medicare Part B durable medical equipment coverage and chronic pain prevalence drive institutional procurement of transcutaneous devices. FDA 510(k) pathway refinements for incremental waveform innovations compress commercialization timelines. Minneapolis and Boston medical device clusters concentrate spinal cord stimulator development and physician training infrastructure.
Germany
Statutory health insurance reimbursement for pulsed electromagnetic field therapy in spinal fusion recovery accelerates orthopedic clinic adoption. EU MDR Class III device requirements elevate clinical evidence burdens for implantable systems. Baden-Württemberg and Bavaria host concentrated physiotherapy equipment manufacturing and rehabilitation hospital networks.
Japan
Aging demographics and post-stroke rehabilitation demand expand physical therapy device utilization. PMDA quality management standards align with international harmonization initiatives. Tokyo and Osaka metropolitan areas concentrate interferential current therapy adoption in pain management centers.
India
CDSCO harmonization with ISO 13485 standards reduces import friction for neuromodulation devices. Government hospital procurement programs and private physiotherapy chain expansion create dual demand channels. Maharashtra and Karnataka medical device manufacturing zones attract contract assembly operations for portable electrotherapy systems.
China
Domestic production capacity for rechargeable TENS units scales to serve homecare and institutional segments. NMPA medical device classification rules govern wireless connectivity feature approvals. Yangtze River Delta medical technology clusters integrate electrode manufacturing with domestic brand assembly.
Electrotherapy Market Vendor Landscape
Capability concentration sits with implantable neuromodulation specialists possessing deep firmware and clinical evidence expertise; scale advantage sits with diversified health technology conglomerates leveraging distribution infrastructure across multiple therapy modalities. The competitive structure stratifies across three archetypes: integrated neuromodulation platforms, specialized physiotherapy equipment fabricators, and consumer health electronics manufacturers. Dominant competitive moves include strategic partnerships between device makers and telehealth platforms, plus portfolio diversification into wearable form factors with remote monitoring capabilities.
Within the integrated neuromodulation tier, Medtronic and Boston Scientific Corporation exemplify capability-intensive positioning through deep implantable device portfolios and recurring service revenue architectures. Abbott Laboratories occupies a diversified health technology position spanning cardiac and neuromodulation therapy systems. Among specialized physiotherapy equipment providers, BTL Industries and DJO Global represent the non-invasive device segment with multi-modality platform strategies. Consumer health electronics participation concentrates in Omron Healthcare and Zynex Inc, which sit within the direct-to-consumer and homecare prescription channels respectively.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific Corporation |
| Abbott Laboratories |
| BTL Industries |
| Omron Healthcare |
| Enovis Corp |
| Nevro Corp |
| DJO Global |
| Zynex Inc |
| Others |
Supply Flow & Price Mechanics
East Asian foundry concentration for wireless connectivity chipsets concentrates margin capture in semiconductor-dependent device tiers, pushing electrotherapy manufacturers toward subscription-based revenue models that dilute hardware price sensitivity. Contract structures now separate premium connectivity-enabled systems from basic electrode configurations, with the former commanding recurring platform fees that offset component cost volatility.
Pricing Analysis
Long-term offtake agreements dominate institutional procurement for implantable neuromodulation systems, while spot-market dynamics govern consumable electrode sales to physiotherapy clinics. Pricing stratifies across premium wireless-enabled, standard rechargeable, and economy disposable tiers, with FDA 510(k) certification tier and after-sales clinical support bundling as primary differentiation drivers. Cost compression in standard-tier transcutaneous devices is intensifying as homecare direct-to-consumer channels expand price transparency. Hospital value-analysis committees exhibit lowest price sensitivity due to bundled reimbursement frameworks, whereas independent physiotherapy practices face acute margin pressure from leasing cost escalation.
Supply Chain Analysis
Contract manufacturing capacity for electrotherapy devices concentrates with Foxconn, Jabil, and Flex holding dominant EMS positions for wireless-enabled therapy delivery systems. Component sourcing draws from Taiwan and South Korea for connectivity chipsets, China for lithium-ion battery cells, and Germany for precision electrode fabrication. Single-source vulnerability in semiconductor foundry capacity creates exposure to allocation rationing during demand surges. Distribution runs through specialized medical device distributors in institutional channels, while direct-to-consumer fulfillment bypasses traditional clinical gatekeepers entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrotherapy sits in early-cycle expansion as closed-loop neuromodulation systems and remote patient monitoring integration create new reimbursement pathways that extend device lifecycle value beyond hardware margins.
For Market Incumbents: Pre-empt firmware engineering scarcity by acquiring embedded systems specialists with Class III medical device cybersecurity expertise before talent costs escalate further. Consolidate position in pulsed electromagnetic field therapy protocols through exclusive orthopedic clinic partnerships that lock out competing waveform platforms. Vertical integration into electrode manufacturing reduces input cost volatility from precious metal price swings. For New Entrants and Emerging Players: Establish a beachhead in India's CDSCO-harmonized import pathway before domestic manufacturing scale erodes foreign price advantages. Target post-surgical bone healing applications in German statutory health insurance reimbursement corridors where clinical evidence requirements favor novel entrants over entrenched pain modulation incumbents. Pursue telehealth platform partnerships as primary go-to-market channel to bypass capital-intensive direct sales infrastructure. For Investors and Strategic Acquirers: Capital is best deployed toward firmware-capable neuromodulation platforms with recurring revenue architectures rather than hardware-only electrotherapy fabricators facing commoditization pressure. Acquisition targets should demonstrate ISO 13485 certification progress and at least one FDA 510(k) clearance in pipeline. Monitor FDA digital health guidance evolution as signal for when cloud-connected therapy delivery systems will face accelerated approval timelines versus traditional predicate-device pathways.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission for Novel Waveform Protocols | Streamlined substantial equivalence demonstrations compress commercialization timelines for transcutaneous devices in United States outpatient clinics. |
| CE Marking Pathway under EU MDR Cybersecurity Annex | Formal threat-risk assessments for cloud-connected systems gate European market access for wireless-enabled therapy delivery platforms. |
| Hospital System Partnership for Closed-Loop Systems | Pain management centers piloting automated parameter adjustment reduce manual calibration burden and shift revenue toward algorithmic subscriptions. |
| Software Companion Development for Remote Monitoring | Real-time dosage adjustment capabilities enable recurring platform fees that displace pure hardware margin dependence. |
| Reimbursement Strategy for PEMF Orthopedic Protocols | German statutory health insurance coverage for spinal fusion recovery accelerates clinical penetration beyond traditional fracture management. |
Methodological Framework
A standing panel of biomedical engineers, hospital purchasing committee members, GPO contracts managers, and physiotherapy clinic operators provided ongoing calibration across primary fieldwork phases. Secondary validation drew from FDA 510(k) clearance databases, EU MDR notified body documentation, CMS Medicare Part B durable medical equipment claims data, and hospital procurement system records. Bottom-up device shipment estimates triangulated against top-down reimbursement spend analysis across the analysis window.
Scenario-bracketing anchored projections across conservative, baseline, and expansion cases reflecting regulatory pathway friction and semiconductor supply normalization assumptions. Segmentation dimensions modeled include product type, application intent, end-user procurement authority, and technology architecture across the projection horizon. CAGRs derived from installed base growth rates and replacement cycle compression in wireless-enabled categories, with pricing trajectory inputs reflecting subscription revenue mix shifts.
Sensitivities concentrate around FDA digital health guidance evolution, EU MDR Class III clinical evidence burden escalation, and East Asian foundry allocation disruptions. Forecasts reflect assumptions on chronic pain prevalence trajectories and statutory health insurance reimbursement stability. Quarterly review of FDA 510(k) clearance velocity and notified body audit queue depth is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Medicine
Acupuncture Lasers Market
Alternative Medicine
Biopuncture Treatment Market
Alternative Medicine
Flower Essences Market
Alternative Medicine
Global Complementary and Alternative Medicines Market
Alternative Medicine
Botanicals & Acupuncture Market
Alternative Medicine
Traditional Chinese Herbal Medicine Market
Alternative Medicine
Disposable Acupuncture Needle Market
Alternative Medicine
Global OTC Herbal and Traditional Medicine Market
Alternative Medicine
Europe Complementary and Alternative Medicine Market
Alternative Medicine
Fire Cupping Market
Alternative Medicine
US Aromatherapy Market
Alternative Medicine
Homeopathy Products Market
Alternative Medicine
Global Homeopathic Product Market
Alternative Medicine
Homeopathic Medicine Market
Alternative Medicine
Cold Laser Therapy Market
Alternative Medicine
US Chiropractic Market