
 Global Childhood Absence Epilepsy Treatment Market | 2026-2036
Global Childhood Absence Epilepsy Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Childhood Absence Epilepsy Treatment Market Foresight
A capital-intensity divergence between large-cap pharmaceutical manufacturers and mid-tier generics producers is redrawing competitive boundaries in childhood absence epilepsy therapeutics. Pfizer Inc. leverages its global distribution infrastructure to sustain formulary access across European and North American pediatric hospitals. Teva Pharmaceutical Industries Ltd. anchors its position through generic valproate and ethosuximide portfolios that dominate cost-sensitive procurement channels in Latin America and Southeast Asia. UCB S.A. differentiates via specialized neurology R&D pipelines focused on next-generation antiepileptic mechanisms.
Childhood absence epilepsy treatment encompasses pharmacological and non-pharmacological interventions targeting idiopathic generalized seizure disorders characterized by brief, non-convulsive episodes with 3 Hz spike-and-wave electroencephalographic patterns, primarily administered to patients aged four to fourteen years. The primary commercial purpose centers on seizure freedom achievement with minimal neurocognitive side effect burden to preserve developmental trajectory and educational attainment. Antiepileptic drugs command the dominant value share within therapy area segmentation, though neurostimulation modalities are gaining structural traction as adjunctive options for pharmacoresistant cases. Generic drugs within product type classification occupy the highest volume tier, while brand-name formulations retain margin concentration in newly diagnosed patient segments where physician prescribing loyalty persists.
The FDA's pediatric study requirements under the Pediatric Research Equity Act and the EMA's Paediatric Investigation Plans collectively shape clinical development timelines and label expansion strategies for antiepileptic drug developers. China's NMPA streamlined review pathways for pediatric neurological indications are accelerating local market entry for multinational manufacturers with established adult epilepsy portfolios. India's CDSCO mandatory bioequivalence standards for generic antiepileptics are tightening quality thresholds that filter substandard suppliers from institutional procurement. Stakeholders must monitor evolving reimbursement criteria for combination therapies and digital therapeutics adjuncts as payers reassess value frameworks for chronic pediatric neurological conditions.
Market Dynamics
Pharmacoresistance rates among pediatric patients are forcing treatment centers to layer neurostimulation onto conventional antiepileptic protocols, restructuring referral economics across tertiary hospital networks.
Growth Catalysts
- Orphan Drug Incentives:The FDA's priority review vouchers and tax credits for pediatric neurological indications are accelerating IND filings for next-generation antiepileptic mechanisms.
- Diagnostic Infrastructure Expansion:Pediatric neurology centers in Germany, Japan, and the United States are installing high-density EEG arrays that reduce time-to-diagnosis for absence seizure patterns.
- Emerging Market Referral Pathways:Metropolitan hospital networks across India and China's eastern provinces are formalizing pediatric epilepsy clinics that channel previously undiagnosed patients into treatment protocols.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Valproate and ethosuximide raw material synthesis concentrates in Chinese and Indian chemical manufacturing clusters, exposing formulators to export license volatility.
- Neurocognitive Side Effect Liability:Sodium channel modulators carry FDA black box warnings for developmental impairment that constrain first-line prescribing in newly diagnosed patients aged four to ten years.
- Specialist Workforce Scarcity:Board-certified pediatric epileptologists number fewer than three thousand across all OECD markets, creating diagnostic bottlenecks that delay treatment initiation.
Strategic Opportunities
- Digital Therapeutic Adjuncts:Real-time seizure detection algorithms paired with vagal nerve stimulators are creating reimbursement pathways for device-pharma combination protocols in German statutory health insurance.
- Pharmacogenomic Stratification:CYP2C9 and CYP2C19 polymorphism screening is enabling precision dosing that reduces trial-and-error titration periods in Asian pediatric populations with higher variant prevalence.
- Extended-Release Formulation Gaps:Once-daily ethosuximide preparations for school-age compliance represent an underserved segment where no approved products currently compete against immediate-generic alternatives.
Industry Challenges
- Pediatric Trial Recruitment Friction:The FDA's Pediatric Research Equity Act mandates age-appropriate formulations that require separate safety cohorts, extending development timelines by eighteen to thirty-six months versus adult indications.
- EEG-Pharma Endpoint Harmonization:Disagreement between the EMA and FDA on spike-and-wave burden versus seizure freedom as primary endpoints forces parallel trial designs that duplicate clinical costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Childhood Absence Epilepsy Treatment Market |
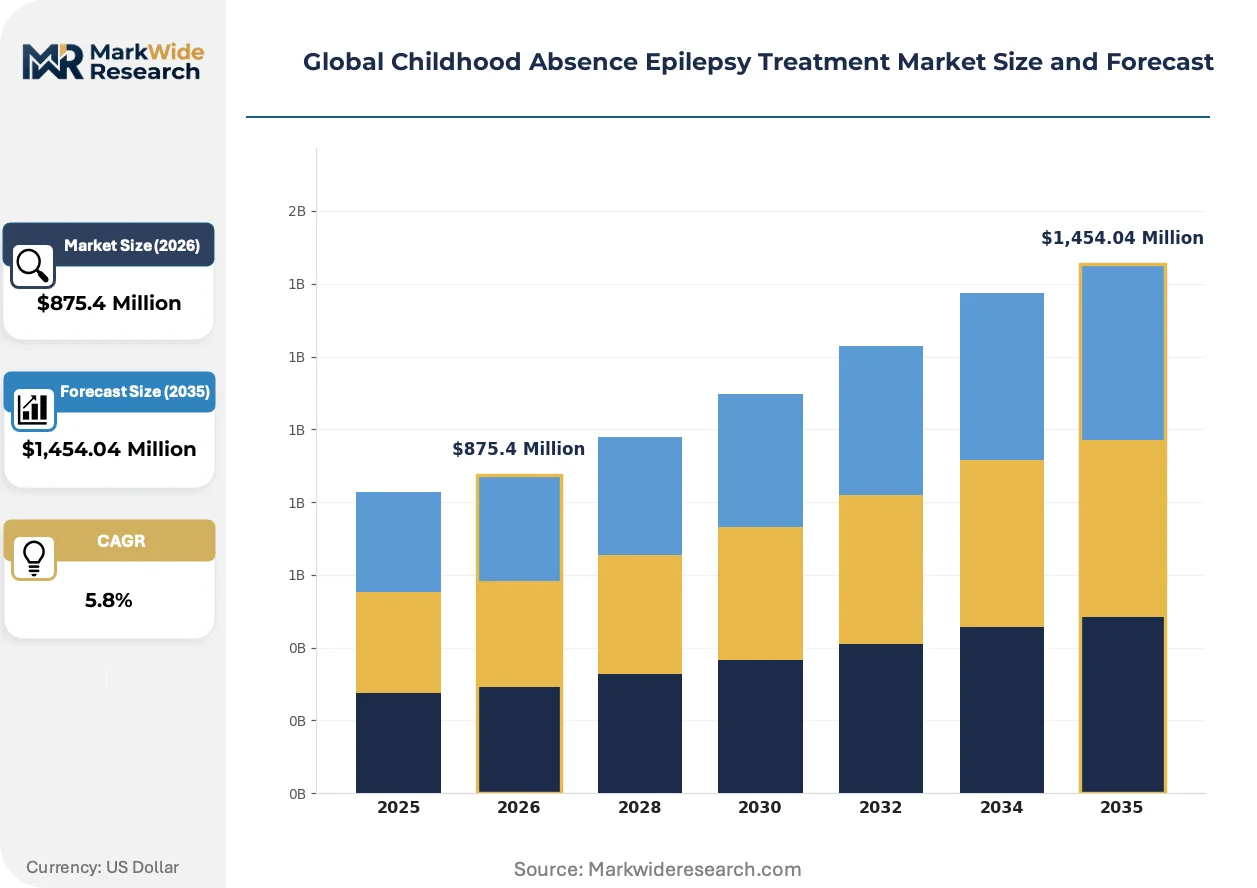
| Market Size in 2026 | $875.4 Million |
| Market Size in 2035 | $1,454.04 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Area: Antiepileptic Drugs, Corticosteroids, Immunomodulators, Dietary Interventions, Neurostimulation Route of Administration: Oral, Intravenous, Intramuscular, Rectal, Sublingual Care Setting: Specialty Clinics, Pediatric Neurology Centers, Outpatient Facilities, Rehabilitation Centers, Diagnostic Labs Product Type: Brand Name Drugs, Generic Drugs, Biosimilars, Combination Therapies, Nutraceuticals |
| Companies Covered | Pfizer Inc., GlaxoSmithKline plc, Teva Pharmaceutical Industries Ltd., AbbVie Inc., Novartis AG, UCB S.A., Sanofi S.A., Johnson & Johnson, Bausch Health Companies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Childhood Absence Epilepsy Treatment Market Shifts & Advancements
Neurostimulation hardware and algorithmic seizure prediction are compressing the boundary between pharmacological and device-based intervention, forcing traditional pharmaceutical developers to build or acquire electrophysiology capabilities.
Responsive neurostimulation systems with intracranial depth electrodes are miniaturizing from implantable pulse generators toward external wearable configurations. Pediatric epilepsy monitoring units at Cleveland Clinic and Great Ormond Street Hospital are piloting these non-invasive variants for pharmacoresistant cases. This miniaturization is collapsing the capital barrier between academic medical centers and community hospital neurology departments, expanding addressable treatment settings.
The EMA's Paediatric Investigation Plans now mandate long-term neurodevelopmental outcome tracking through adolescence, not merely seizure frequency endpoints. This regulatory expansion is requiring sponsors to maintain active surveillance registries that extend five years post-approval. Small and mid-cap developers without existing pediatric infrastructure are partnering with academic consortia in the Netherlands and Scandinavia to satisfy these follow-through obligations.
Hospital procurement committees are unbundling device servicing from capital equipment purchases, forcing neurostimulation manufacturers to compete on per-procedure reimbursement rather than upfront hardware margins. This shift is most visible in French and Italian regional health systems where DRG-based funding compresses total episode costs. Vendors are responding with performance guarantees tied to seizure reduction percentages, transferring outcome risk from providers to suppliers.
Global Childhood Absence Epilepsy Treatment Market Segmentation
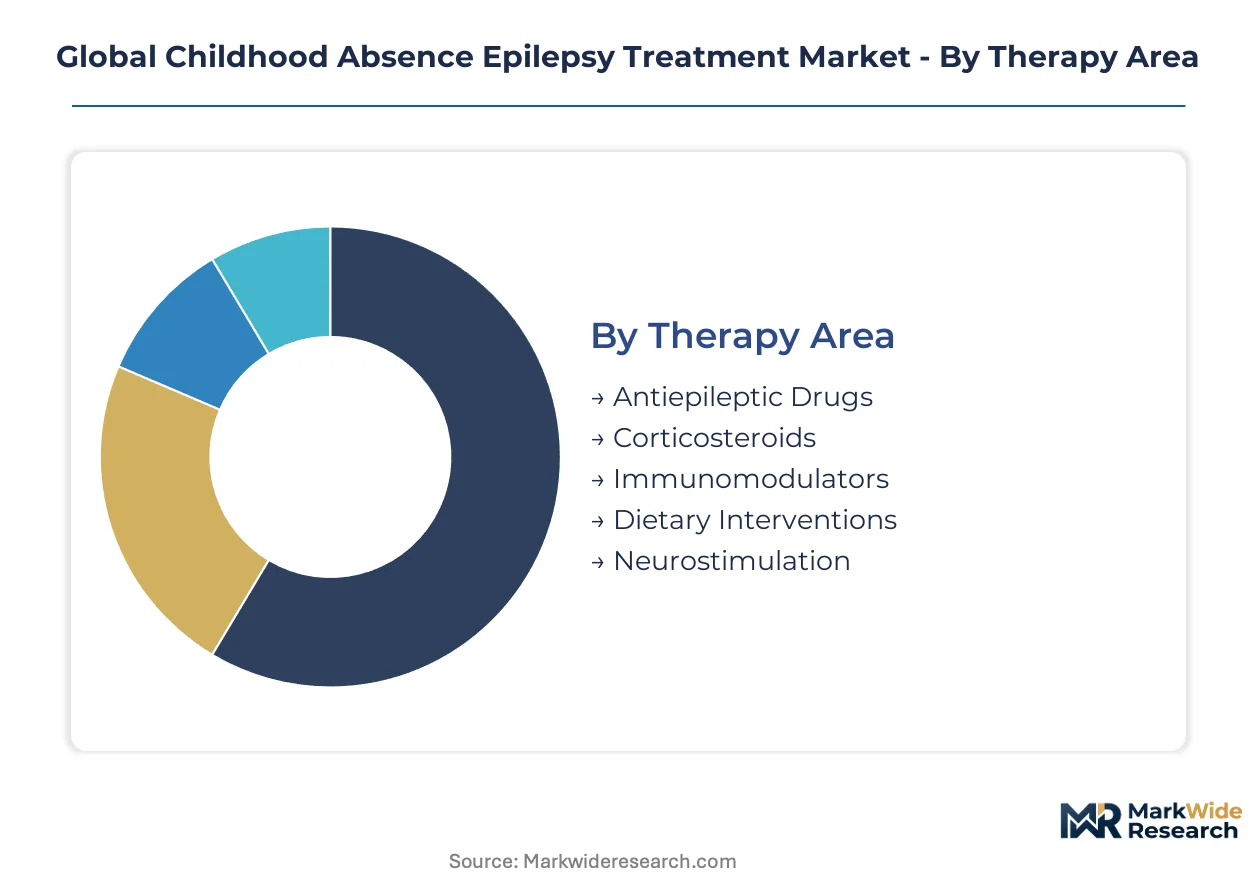
Treatment modalities for childhood absence epilepsy fragment across pharmacological, device-based, and nutritional interventions, each carrying distinct reimbursement codes and prescriber specialization requirements. Segmentation clarity enables stakeholders to map R&D investment against addressable patient populations and regulatory pathway complexity.
Therapy Area:
Antiepileptic drugs dominate domestic prescription volumes across OECD markets, while neurostimulation hardware concentrates in German and Japanese export channels where device reimbursement frameworks are most mature.
- Antiepileptic Drugs:First-line sodium channel blockers and GABA modulators constitute the clinical standard for newly diagnosed patients. Demand clusters in pediatric neurology centers across the United States and Germany, where formulary placement hinges on neurocognitive side effect profiles.
- Neurostimulation:Responsive and vagal nerve stimulation systems serve pharmacoresistant cohorts through implantable or wearable configurations. Japanese statutory health insurance and German DRG systems currently lead reimbursement innovation for device-pharma combination protocols.
- Corticosteroids:Adjunctive steroid pulses address inflammatory seizure substrates in select autoimmune presentations.
- Immunomodulators:Biologic agents target refractory cases with suspected autoimmune etiology.
- Dietary Interventions:Ketogenic and modified Atkins protocols require specialized metabolic monitoring infrastructure.
Antiepileptic drugs hold the largest share; momentum sits with neurostimulation as reimbursement pathways mature.
Route of Administration:
Cost tier stratification separates premium formulation development from commoditized immediate-release generics, with compliance-enhancing delivery mechanisms commanding development priority.
- Oral:Immediate-release tablets and suspensions remain the volume anchor across all markets, though extended-release ethosuximide preparations represent an unmet need for school-age adherence. European and North American pediatric hospitals prioritize palatable liquid formulations for younger cohorts.
- Sublingual:Rapid-dissolve formulations address acute seizure interruption and patients with swallowing difficulties. Development activity concentrates in Israeli and Swiss specialty formulation houses serving orphan drug sponsors.
- Intravenous:Hospital-administered rescue therapy for status epilepticus escalation.
- Intramuscular:Emergency administration where vascular access is compromised.
- Rectal:Community rescue protocols for prolonged seizure events.
Oral administration retains volume dominance; sublingual delivery is climbing the fastest as formulation partnerships accelerate.
Care Setting:
Patient flow patterns concentrate diagnostic volume in metropolitan tertiary centers while shifting stable maintenance therapy toward community-based facilities.
- Pediatric Neurology Centers:Comprehensive epilepsy monitoring units with high-density EEG arrays anchor diagnostic pathways across Cleveland Clinic, Great Ormond Street Hospital, and Tokyo Women's Medical University networks. These centers generate the treatment protocols that propagate to regional practice.
- Specialty Clinics:Focused pediatric epilepsy practices in India's Delhi-Mumbai corridor and China's eastern provinces are formalizing referral pathways that capture previously undiagnosed patients. Expansion depends on specialist workforce availability.
- Outpatient Facilities:Maintenance therapy and drug level monitoring for stabilized patients.
- Rehabilitation Centers:Neurodevelopmental support for comorbid cognitive impairment.
- Diagnostic Labs:EEG interpretation and genetic testing services supporting referral networks.
Pediatric neurology centers hold the largest share; momentum sits with specialty clinics as emerging market networks mature.
Product Type:
Margin concentration separates premium brand-name formulations for newly diagnosed segments from price-pressured generic volumes in maintenance therapy.
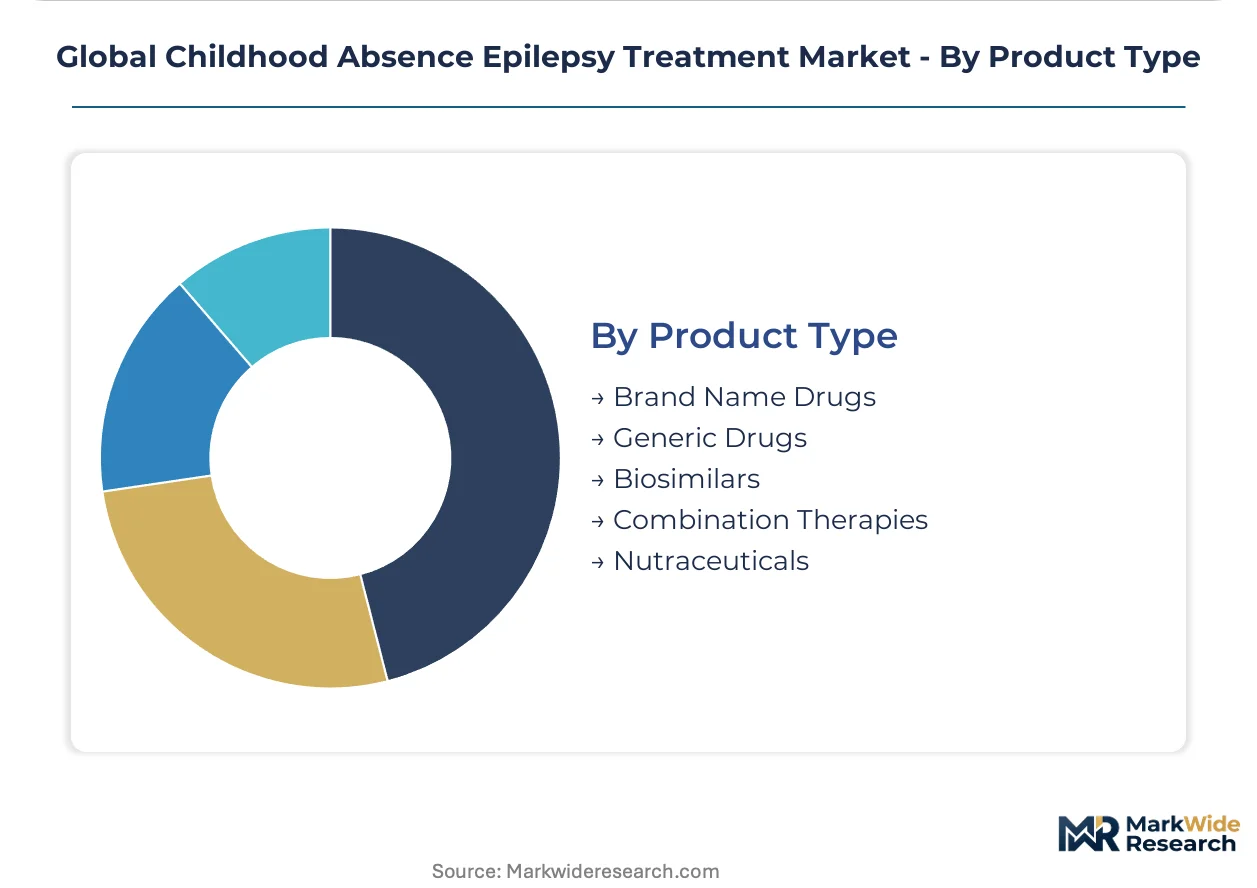
- Generic Drugs:Valproate and ethosuximide copies dominate procurement channels across Latin America and Southeast Asia, where India's CDSCO bioequivalence standards filter substandard suppliers. Teva Pharmaceutical Industries anchors this tier through cost-optimized manufacturing.
- Brand Name Drugs:Novel mechanisms and improved side effect profiles sustain prescriber loyalty in first-line segments across European and North American pediatric hospitals. Pfizer's global distribution infrastructure defends formulary access.
- Biosimilars:Emerging competition for biologic immunomodulators.
- Combination Therapies:Fixed-dose products addressing polypharmacy compliance.
- Nutraceuticals:Supplemental formulations adjacent to ketogenic protocols.
Generic drugs hold the largest share; momentum sits with brand name formulations as next-generation mechanisms advance through FDA orphan pathways.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Japanese tertiary pediatric networks while procurement compression dominates Indian and Southeast Asian institutional channels, creating a bifurcated value capture geography.
United States
FDA orphan drug incentives and accelerated approval pathways channel venture investment toward pediatric neurological indications. The Pediatric Research Equity Act mandates age-appropriate formulations that extend development timelines. Cleveland Clinic and Boston Children's Hospital anchor high-density EEG diagnostic infrastructure that reduces time-to-treatment initiation.
Germany
Statutory health insurance reimbursement innovation for device-pharma combination protocols outpaces other European systems. The EMA's Paediatric Investigation Plans mandate long-term neurodevelopmental outcome tracking through adolescence. Pediatric neurology centers in Munich and Heidelberg expand epilepsy monitoring units with responsive neurostimulation pilot programs.
Japan
PMDA streamlined review pathways for pediatric neurological indications accelerate market entry for multinational manufacturers. METI funding supports wearable neurostimulation miniaturization research. Tokyo Women's Medical University and Osaka University Hospital networks generate treatment protocols that propagate across East Asian referral systems.
China
NMPA regulatory harmonization with ICH standards reduces duplication for sponsors with established adult epilepsy portfolios. The country's national pharmaceutical regulator tightens bioequivalence standards for generic antiepileptics. Pediatric epilepsy clinics in Shanghai and Beijing formalize referral pathways that channel previously undiagnosed patients into treatment protocols.
India
CDSCO mandatory bioequivalence standards filter substandard generic suppliers from institutional procurement. Metropolitan hospital networks in Delhi and Mumbai expand specialty pediatric epilepsy practices. Cost-sensitive procurement channels concentrate demand for valproate and ethosuximide copies from domestic chemical manufacturing clusters.
Global Childhood Absence Epilepsy Treatment Market Competitive Landscape
Concentration sits with large-cap pharmaceutical manufacturers defending formulary access through global distribution infrastructure against mid-tier generics producers competing on cost-optimized manufacturing. The vendor base stratifies across three tiers: multinational innovators with specialized neurology pipelines, integrated generics houses with vertical control over active pharmaceutical ingredient supply, and regional formulators serving price-sensitive procurement channels. Dominant competitive moves include strategic partnerships for pediatric trial infrastructure and portfolio diversification into neurostimulation device-pharma combinations.
Within the large-cap innovator tier, Pfizer Inc. and UCB S.A. exemplify archetypes built on global distribution scale and specialized neurology R&D respectively. Teva Pharmaceutical Industries Ltd. anchors the integrated generics segment through cost-optimized manufacturing positions. These three entities collectively represent the structural poles around which competitive positioning organizes: formulary access defense, mechanism-focused innovation, and procurement channel penetration.
| Leading Market Players |
|---|
| Pfizer Inc. |
| GlaxoSmithKline plc |
| Teva Pharmaceutical Industries Ltd. |
| AbbVie Inc. |
| Novartis AG |
| UCB S.A. |
| Sanofi S.A. |
| Johnson & Johnson |
| Bausch Health Companies |
| Others |
Supply & Pricing Matrix
Extended-release ethosuximide formulations replacing immediate-release generics in school-age compliance protocols are simultaneously concentrating manufacturing investment in Indian and Chinese formulation clusters and compressing margin structures for European and North American originators. This substitution dynamic redistributes pricing power toward cost-optimized producers while forcing brand-name developers to defend position through pediatric-specific regulatory exclusivities.
Pricing Analysis
The customization-premium spread between tailored neurostimulation-device combinations and standard antiepileptic drug regimens defines pricing architecture across German and Japanese statutory health insurance systems. Three-tier pricing structure across premium, standard, and economy levels separates implantable responsive neurostimulation systems from brand-name sodium channel modulators from generic valproate copies. Pricing pressure stems from procurement committee unbundling of device servicing from capital equipment purchases in French and Italian regional health systems. Hospital networks in Latin America and Southeast Asia exhibit highest price sensitivity, while tertiary pediatric neurology centers in Cleveland and Heidelberg maintain lowest sensitivity due to outcome-based reimbursement guarantees.
Supply Chain Analysis
Inventory lead times for valproate and ethosuximide active pharmaceutical ingredients stretch eighteen to thirty-six months due to concentrated synthesis capacity in Chinese and Indian chemical manufacturing clusters. Raw material dependencies center on sodium valproate precursors from Zhejiang province, ethosuximide intermediates from Gujarat chemical parks, and specialized excipients for extended-release matrices from German and Swiss suppliers. Single-source vulnerability in Chinese export license administration creates supply interruption exposure for formulators lacking dual-sourcing arrangements. Distribution runs through hospital procurement committees in OECD markets and government tender systems in emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through pediatric hospital network consolidation across metropolitan India and China's eastern provinces, where tertiary referral systems are absorbing previously fragmented specialty clinic volume.
For Market Incumbents: Secure formulary access through pediatric-specific label expansions and long-term neurodevelopmental outcome registries that satisfy EMA Paediatric Investigation Plan mandates. Deepen backward integration into active pharmaceutical ingredient supply through partnerships with CDSCO-certified Indian manufacturers to buffer Chinese export volatility. Threat exposure centers on wearable neurostimulation miniaturization displacing implantable hardware margins. For New Entrants and Emerging Players: Digital therapeutic adjuncts for real-time seizure detection represent the most penetrable service-layer gap, as incumbent pharmaceutical developers lack electrophysiology algorithm capabilities. Target white-space in extended-release ethosuximide preparations for school-age adherence and pharmacogenomic stratification services for Asian pediatric populations with higher CYP2C9 variant prevalence. Go-to-market angle should leverage academic medical center partnerships for pilot data generation. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed specialty neurology device manufacturers holding responsive neurostimulation miniaturization IP but lacking pediatric trial infrastructure. Long-term viability over a five-to-ten year horizon hinges on successful navigation of FDA Pediatric Research Equity Act timelines and EMA long-term neurodevelopmental outcome tracking requirements. Watch for inflection in German statutory health insurance reimbursement decisions on device-pharma combination protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Pediatric Trial Infrastructure Partnership | EMA and FDA pediatric mandates extend development timelines without academic consortium support. |
| Extended-Release Formulation Development | Once-daily ethosuximide preparations address school-age compliance gaps with no approved competitors. |
| Neurostimulation Device-Pharma Combination | German DRG systems are piloting reimbursement pathways for algorithm-stimulator integrated protocols. |
| Pharmacogenomic Stratification Service | CYP2C9 and CYP2C19 screening reduces trial-and-error titration in Asian pediatric populations. |
| Active Pharmaceutical Ingredient Dual-Sourcing | CDSCO-certified Indian suppliers buffer Chinese export license volatility for valproate and ethosuximide. |
Research Methodology
Desk research of FDA orphan drug filings, EMA Paediatric Investigation Plan submissions, ClinicalTrials.gov pediatric epilepsy protocols, and hospital procurement database records preceded structured interviews with pediatric neurologists, formulary directors at tertiary care networks, regulatory affairs leads at antiepileptic drug developers, and payer access specialists in German and Japanese statutory health insurance systems. Bottom-up patient flow modeling across metropolitan India and China's eastern provinces was triangulated against top-down pharmaceutical sales data.
Variance decomposition across therapy area, route of administration, care setting, and product type segments drove analytical framework construction throughout the projection horizon. CAGRs were derived from segmented volume and value build-ups incorporating pediatric prevalence epidemiology, diagnostic infrastructure expansion rates, and reimbursement pathway maturation timelines. Forecast inputs included specialist workforce growth projections and neurostimulation hardware miniaturization adoption curves.
Forecasts assume regulatory continuity in FDA orphan drug incentive structures and EMA Paediatric Investigation Plan enforcement; material policy shifts in pediatric neurological indication requirements would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Reactive Arthritis Treatment Market
Specialty Medicine
Chronic Urticaria Market
Specialty Medicine
Atopic Dermatitis Market
Specialty Medicine
Hypoactive Sexual Desire Disorder Treatment Market
Specialty Medicine
Animal Hormone Therapy Market
Specialty Medicine
Perennial Allergic Rhinitis Market
Specialty Medicine
Pyoderma Gangrenosum Therapeutics Market
Specialty Medicine
Bronchiectasis Therapeutic Market
Specialty Medicine
Asia-Pacific Sports Medicine Market
Specialty Medicine
Musculoskeletal System Disorders Market
Specialty Medicine
Hereditary Angioedema Market
Specialty Medicine
Global Myeloproliferative Disorders (MPD) Treatment Market
Specialty Medicine
Gouty Arthritis Market
Specialty Medicine
Pemphigus Vulgaris (PV) Treatment Market
Specialty Medicine
Osteogenesis Imperfecta Treatment Market
Specialty Medicine
Infantile Spasms Therapeutics Market