
 Global Acupuncture Market | 2026-2036
Global Acupuncture Market Size, Share, and Industry Trends Forecast 2026-2036
Global Acupuncture Market Intelligence
Chinese needle manufacturers are broadening export capacity to meet European and North American certification requirements. SEIRIN Corporation leverages Japanese precision engineering to dominate premium disposable needle segments. Wuxi Jiajian Medical Instruments Co., Ltd anchors mass-scale production through backward integration into stainless steel wire drawing. 3B Scientific GmbH sustains educational channel control across German-speaking clinical training markets.
Acupuncture encompasses the insertion of filiform needles ranging from 0.12 mm to 0.35 mm diameter into specific anatomical points to modulate neurological and circulatory function. Stainless steel 304 and 316 grades constitute standard needle compositions, with silicone coatings reducing insertion friction by approximately 30 percent in premium variants. Sterile needles command the largest revenue pool across product types, while electrical acupuncture devices capture expanding margins in physiotherapy centers. Pain management leads therapy area demand, though stress relief applications accelerate fastest in wellness clinic settings.
FDA device classification under 21 CFR 880.5580 governs U.S. needle safety standards, while EMA coordination with national European bodies such as Germany's BfArM harmonizes clinical evidence requirements for reimbursement eligibility. China's NMPA enforces GB standard compliance for domestic production and export certification. Japan's MHLW maintains PMDA oversight of needle sterility assurance levels. Stakeholders must monitor evolving WHO traditional medicine strategy implementation and its influence on national insurance coverage decisions.
Market Dynamics
Acupuncture markets reshape around WHO traditional medicine integration protocols, which compress national insurance reimbursement timelines and accelerate clinical standardization across formerly fragmented practitioner networks.
Growth Catalysts
- WHO Traditional Medicine Strategy:National health ministries in Germany, Japan, and Australia accelerate coverage inclusion for chronic pain protocols, expanding addressable patient pools.
- Silicone-coated needle adoption:Premium disposable variants reduce insertion friction measurably, driving replacement cycles in physiotherapy centers and hospital outpatient departments.
- Wellness clinic channel expansion:Stress relief applications attract venture-backed clinic chains in the United States and United Kingdom, diversifying beyond pain management revenue.
Market Restraints
- Stainless steel input volatility:Medical-grade 304 and 316 wire drawing costs fluctuate with commodity markets, squeezing margin on standard needle SKUs.
- Single-source sterilization capacity:Gamma irradiation services concentrate in China and Germany, creating bottleneck risk for export-dependent manufacturers.
- Clinical evidence thresholds:EMA national body coordination demands randomized trial data for reimbursement, delaying market entry for novel electroacupuncture device categories.
Strategic Opportunities
- Underpenetrated Latin American markets:Brazil's ANVISA regulatory pathway harmonization with WHO protocols opens reimbursement discussions for chronic pain indications.
- Telemedicine-guided self-acupuncture:Digital therapeutics platforms integrate with disposable needle subscription models, capturing home-use segments previously served by practitioners alone.
- EU MDR certification alignment:Device manufacturers achieving CE marking under expanded medical device regulations gain preferential access to German and French hospital procurement frameworks.
Industry Challenges
- Practitioner training pipeline gaps:Licensed acupuncturist certification programs in the United States and United Kingdom produce insufficient graduates to match wellness clinic expansion timelines.
- Legacy electrical device interoperability:Physiotherapy centers face integration complexity when connecting new electroacupuncture units to existing EMR and billing systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Acupuncture Market |
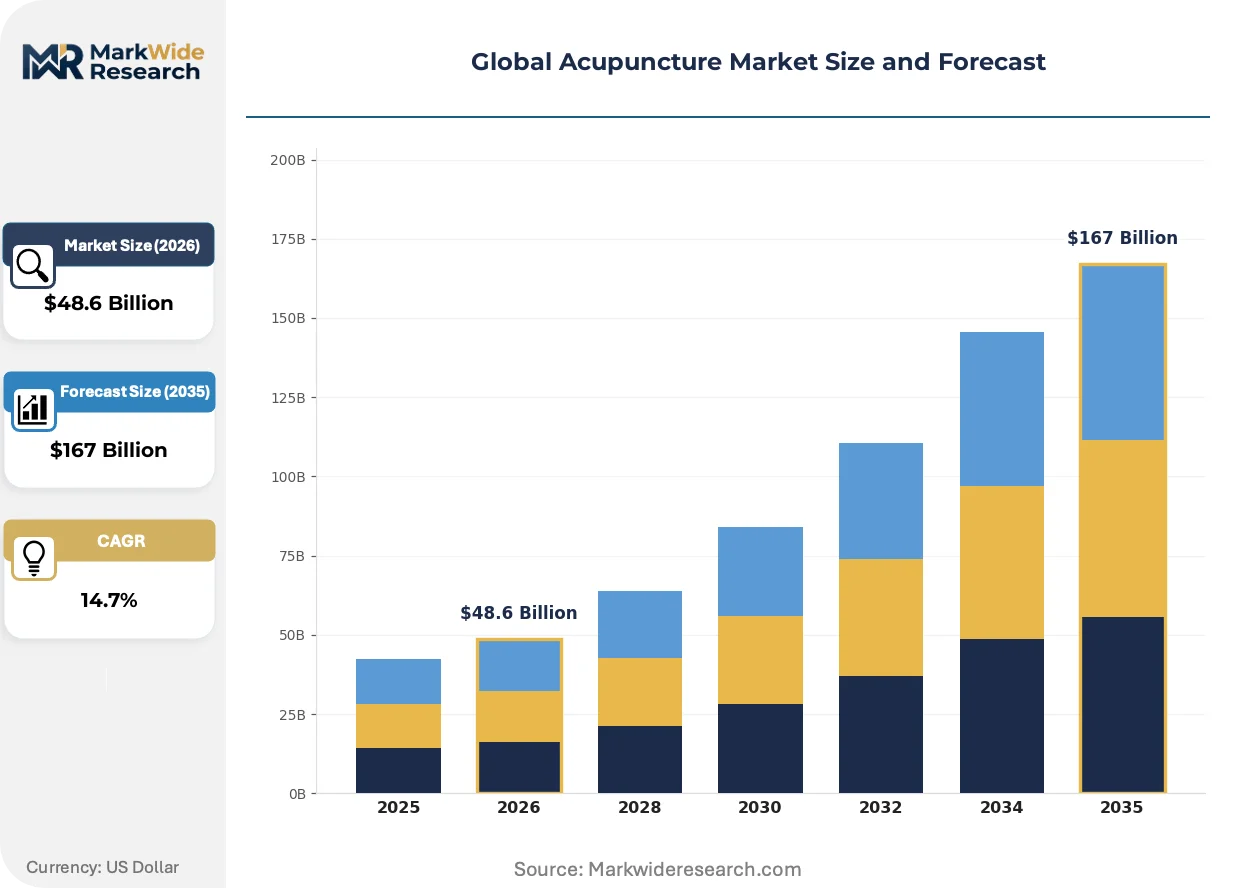
| Market Size in 2026 | $48.6 Billion |
| Market Size in 2035 | $167 Billion |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sterile Needles, Semi-Permanent Needles, Electrical Acupuncture Devices, Acupressure Tools Therapy Area: Pain Management, Neurological Disorders, Musculoskeletal Conditions, Stress Relief, Digestive Disorders End User: Hospitals, Wellness Clinics, Physiotherapy Centers, Alternative Medicine Clinics, Rehabilitation Centers Distribution Channel: Online Retailers, Pharmacies, Specialty Stores, Direct Sales, Medical Device Suppliers |
| Companies Covered | Wuxi Jiajian Medical Instruments Co., Ltd, Asia-Med GmbH, SEIRIN Corporation, AcuMedic Ltd., Qingdao Great Fortune Co., Ltd., 3B Scientific GmbH, Zepter International, Boen Healthcare Co., Ltd, Schwa-medico GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Acupuncture Market Strategic Shifts & Innovations
Digital health integration and materials science advances compress traditional practitioner-patient models while elevating device precision standards across clinical and wellness segments.
Laser acupuncture systems is converging with photobiomodulation protocols in German rehabilitation centers, where physiotherapists adopt needle-free alternatives for needle-phobic patient cohorts. Hospital outpatient departments in Japan pilot combined laser-electro modalities, compressing treatment session duration while maintaining reimbursement code eligibility.
EMA coordination with Germany's BfArM and France's ANSM harmonizes clinical evidence requirements for Class IIa medical device reclassification, forcing manufacturers to consolidate trial data across multiple national submission pathways. Electroacupuncture device producers with existing FDA 510(k) clearances face compressed EU market entry timelines if they leverage prior U.S. safety documentation.
Subscription-based needle procurement models displace traditional distributor relationships in United States multi-site wellness chains, which negotiate direct supply agreements with Chinese manufacturers holding NMPA export certification. Corporate wellness programs in London and New York City bundle acupuncture access into employee benefit platforms, rotating demand toward standardized disposable SKUs and away from practitioner-branded custom needle selections.
Global Acupuncture Market Segmentation
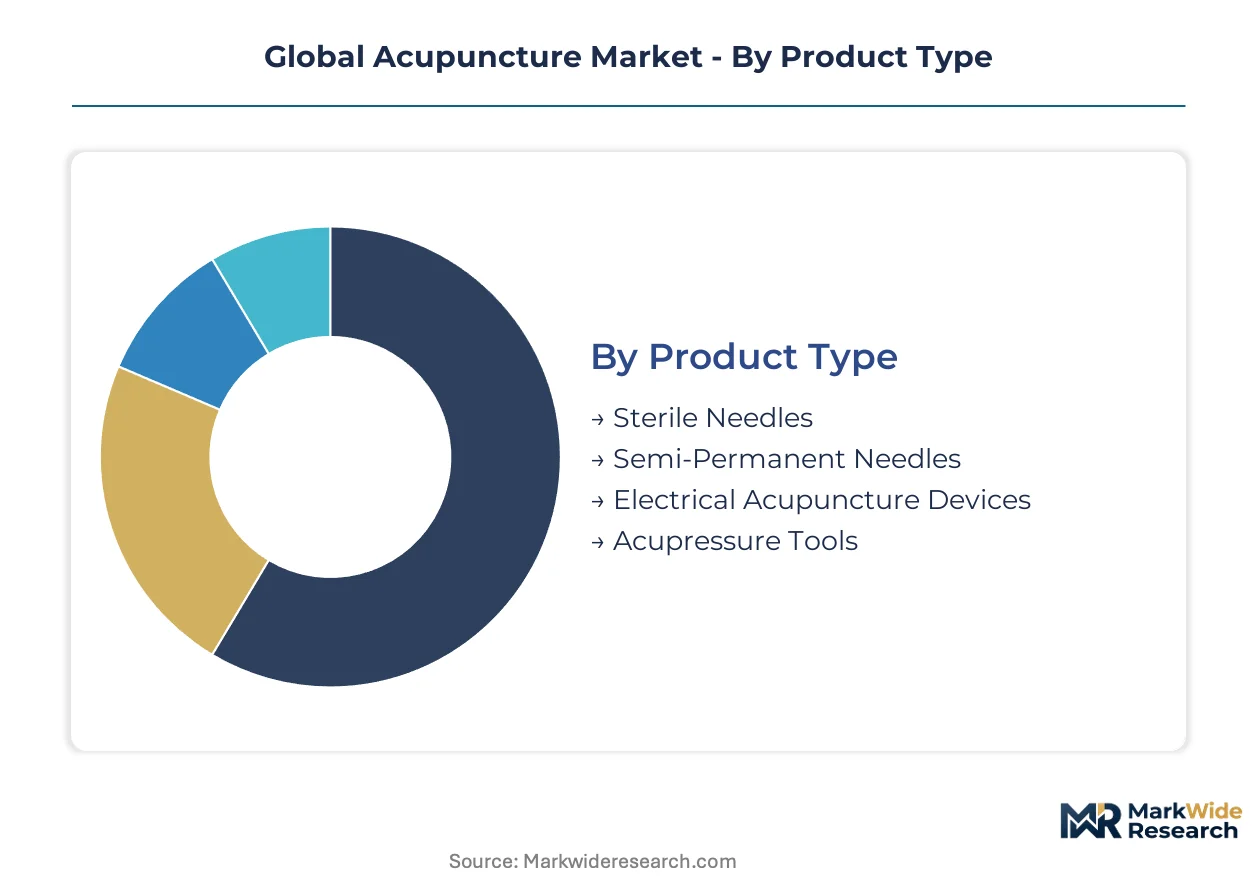
Acupuncture market segmentation reveals divergent margin structures across sterile consumables versus capital equipment, with therapy area specialization driving procurement consolidation in hospital outpatient departments. Understanding specification hierarchies and channel economics enables manufacturers to align production capacity with reimbursement-accessible segments.
Product Type:
Needle engineering specifications and sterilization protocols create distinct cost tiers, with coating technologies and electrical integration defining competitive differentiation.
- Sterile Needles:Single-use filiform needles in 0.12 mm to 0.35 mm diameters dominate procedure volumes across licensed practitioner networks. German physiotherapy centers and Japanese hospital outpatient departments drive demand for silicone-coated variants that reduce insertion friction measurably.
- Electrical Acupuncture Devices:Class IIa medical devices delivering controlled electrical stimulation integrate with EMR systems in clinical settings. China's NMPA and the US FDA maintain divergent safety documentation requirements, compressing market entry timelines for manufacturers with prior 510(k) clearances.
- Semi-Permanent Needles:Intradermal retention needles serve extended treatment protocols in Japanese rehabilitation medicine. Compact SKUs suit home-use subscription models emerging in United Kingdom wellness chains.
- Acupressure Tools:Non-invasive pressure devices target needle-phobic patient cohorts in German laser-acupuncture centers. Consumer-grade variants circulate through online retail channels with minimal regulatory friction.
Sterile needles lead on scale; electrical acupuncture devices lead on momentum.
Therapy Area:
Reimbursement code availability and clinical evidence density determine addressable patient pools across neurological and wellness applications.
- Pain Management:Chronic back and osteoarthritis protocols command established insurance coverage in Germany, Japan, and Australia under WHO traditional medicine integration. Hospital procurement frameworks prioritize disposable needle standardization for high-frequency outpatient procedures.
- Stress Relief:Wellness clinic chains in London and New York City bundle acupuncture into corporate employee benefit platforms. Venture-backed multi-site operators rotate demand toward subscription-based needle procurement and away from practitioner-branded custom selections.
- Neurological Disorders:Migraine and neuropathy applications require randomized trial data for EMA national body coordination on reimbursement eligibility. Evidence thresholds delay market entry for novel electroacupuncture device categories.
- Musculoskeletal Conditions:Sports injury protocols concentrate in Australian physiotherapy centers and German rehabilitation facilities. Treatment session compression through combined laser-electro modalities maintains procedure code compliance.
- Digestive Disorders:Functional gastrointestinal indications lack harmonized reimbursement pathways across major markets. Practitioner networks in China and Japan sustain demand through out-of-pocket payment models.
Pain management leads on scale; stress relief leads on momentum.
End User:
Facility certification requirements and patient volume economics shape procurement authority and SKU standardization pressures.
- Wellness Clinics:Venture-backed chains in the United States and United Kingdom negotiate direct supply agreements with Chinese manufacturers holding NMPA export certification. Corporate wellness program integration drives demand for standardized disposable SKUs at volume pricing.
- Hospitals:Outpatient departments in Japan and Germany pilot combined laser-electro modalities to compress treatment duration while maintaining reimbursement code eligibility. Centralized procurement favors suppliers with EU MDR certification alignment.
- Physiotherapy Centers:German rehabilitation facilities adopt needle-free laser alternatives for specific patient cohorts. Integration complexity with existing EMR and billing systems constrains electrical device replacement cycles.
- Alternative Medicine Clinics:Licensed practitioner networks in Australia sustain demand through WHO traditional medicine strategy implementation. Training pipeline gaps limit expansion timelines relative to wellness clinic growth.
- Rehabilitation Centers:Post-surgical pain protocols in Japanese facilities combine electroacupuncture with conventional physiotherapy. BfArM clinical evidence requirements govern device reimbursement eligibility.
Wellness clinics lead on momentum; hospitals lead on procurement concentration.
Distribution Channel:
Channel economics reflect certification complexity and customer scale, with direct relationships displacing traditional intermediaries in high-volume segments.
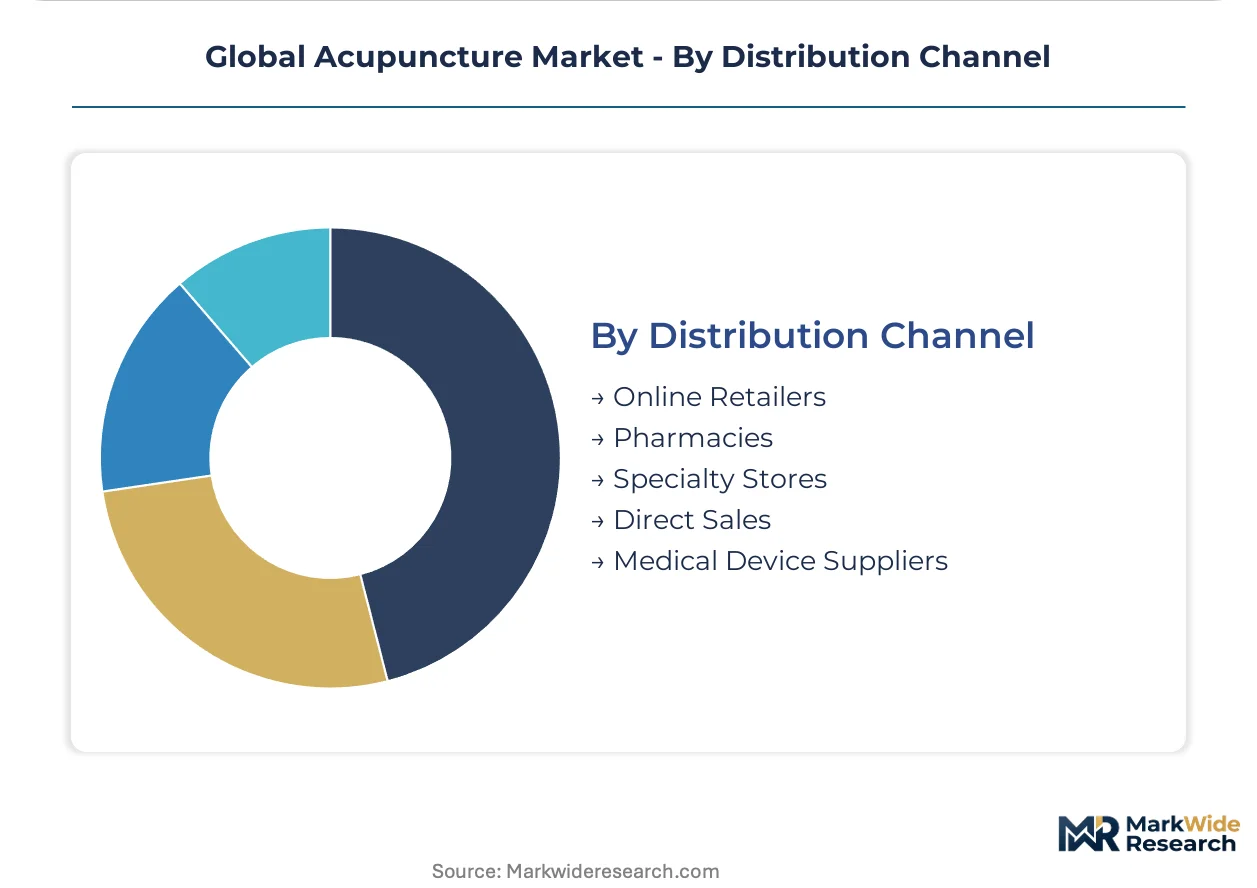
- Direct Sales:Multi-site wellness chains in the United States bypass distributors to secure volume pricing from Chinese needle manufacturers. Subscription-based procurement models compress working capital requirements for clinic operators.
- Medical Device Suppliers:Hospital procurement frameworks in Germany and France require CE marking under expanded EU MDR regulations. Specialized distributors maintain educational channel control across German-speaking clinical training markets.
- Online Retailers:Consumer-grade acupressure tools and home-use needle kits circulate through digital platforms with minimal regulatory friction. Telemedicine-guided self-acupuncture platforms integrate with disposable needle subscription models.
- Pharmacies:Limited SKU availability reflects storage requirements for sterile needle inventory. Japanese pharmacy chains stock premium SEIRIN Corporation products for practitioner referral networks.
- Specialty Stores:Educational supply outlets serve acupuncture training programs in the United Kingdom and Australia. 3B Scientific GmbH maintains channel dominance through anatomical model bundling.
Direct sales leads on momentum; medical device suppliers lead on hospital access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates manufacturing capacity for sterile needles while Germany and Japan drive premium device innovation, creating divergent competitive dynamics across major demand centers.
United States
FDA device classification under 21 CFR 880.5580 governs needle safety standards for wellness clinic chains and hospital outpatient departments. Corporate wellness programs in New York City bundle acupuncture into employee benefit platforms. Venture-backed multi-site operators rotate demand toward subscription-based needle procurement models.
Germany
German physiotherapy centers and rehabilitation facilities adopt silicone-coated needle variants and laser-acupuncture alternatives for specific patient cohorts. EMA coordination with BfArM harmonizes clinical evidence requirements for Class IIa medical device reimbursement eligibility. 3B Scientific GmbH anchors educational channel control across German-speaking clinical training markets.
Japan
Japanese hospital outpatient departments pilot combined laser-electro modalities to compress treatment duration while maintaining reimbursement code eligibility. MHLW maintains PMDA oversight of needle sterility assurance levels for domestic and export markets. SEIRIN Corporation leverages precision engineering to dominate premium disposable needle segments.
China
NMPA enforces GB standard compliance for domestic production and export certification of sterile needle manufacturing. Wuxi Jiajian Medical Instruments Co., Ltd anchors mass-scale production through backward integration into stainless steel wire drawing. Yangtze River Delta manufacturing clusters supply European and North American certification requirements.
Australia
Licensed practitioner networks sustain demand through WHO traditional medicine strategy implementation and chronic pain protocol coverage. TGA oversight aligns with international sterilization standards for imported needle devices. Sydney and Melbourne wellness clinic chains expand faster than domestic training programs can supply certified practitioners.
Global Acupuncture Market Key Industry Players
Chinese producers anchor one tier; German and Japanese specialists hold premium positioning through precision engineering and educational channel control. The vendor base stratifies across mass-scale disposable needle fabricators, precision-engineered premium specialists, and diversified medical device suppliers with educational bundling capabilities. Two dominant competitive moves concentrate competitive tension: direct supply agreement negotiations between Chinese manufacturers and Western wellness clinic chains, and EU MDR certification alignment for hospital procurement framework access.
Among Chinese fabricators, Wuxi Jiajian Medical Instruments Co., Ltd and Qingdao Great Fortune Co., Ltd occupy positions within the mass-production archetype, representing scale-driven supply to export markets. Within the premium-tier vector, SEIRIN Corporation exemplifies Japanese precision engineering specialization, while 3B Scientific GmbH anchors educational channel dominance across German-speaking clinical training markets.
| Leading Market Players |
|---|
| Wuxi Jiajian Medical Instruments Co., Ltd |
| Asia-Med GmbH |
| SEIRIN Corporation |
| AcuMedic Ltd. |
| Qingdao Great Fortune Co., Ltd. |
| 3B Scientific GmbH |
| Zepter International |
| Boen Healthcare Co., Ltd |
| Schwa-medico GmbH |
| Others |
Cost & Logistics Intelligence
Silicone-coating adoption across premium needle SKUs simultaneously elevates manufacturing complexity and concentrates margin capture among Japanese and German precision engineers. This production-method transition reshapes cost economics by adding processing steps while reducing downstream clinical friction, tightening supply relationships between coating technology licensors and sterile needle fabricators.
Pricing Analysis
Capacity additions in China are reshaping price floors for standard stainless steel filiform needles while premium tiers hold firm. Three-tier pricing structure across premium, standard, and economy levels separates silicone-coated Japanese imports from commodity Chinese exports and uncoated domestic alternatives. Cost compression in standard SKUs is intensifying because Yangtze River Delta manufacturers expanded wire-drawing capacity. Wellness clinic chains exhibit highest price sensitivity through subscription procurement negotiations, whereas Japanese hospital outpatient departments absorb premium coatings without volume pushback.
Supply Chain Analysis
Needle return flows for gamma re-sterilization are negligible given single-use regulatory mandates, yet stainless steel scrap recovery from manufacturing offcuts feeds back into wire-drawing feedstock. Production concentrates in China, Germany, and Japan for finished devices, with medical-grade 304 and 316 stainless steel drawing capacity anchored in Wuxi and Qingdao manufacturing clusters. Supply chain risk centers on single-source gamma irradiation services concentrated in China and Germany, creating bottleneck exposure for export-dependent manufacturers. Distribution runs through direct sales agreements for high-volume wellness chains and specialized medical device suppliers for hospital procurement frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on silicone-coating technology licensing and wellness clinic subscription model adoption, compressing working capital needs while elevating per-unit realized prices.
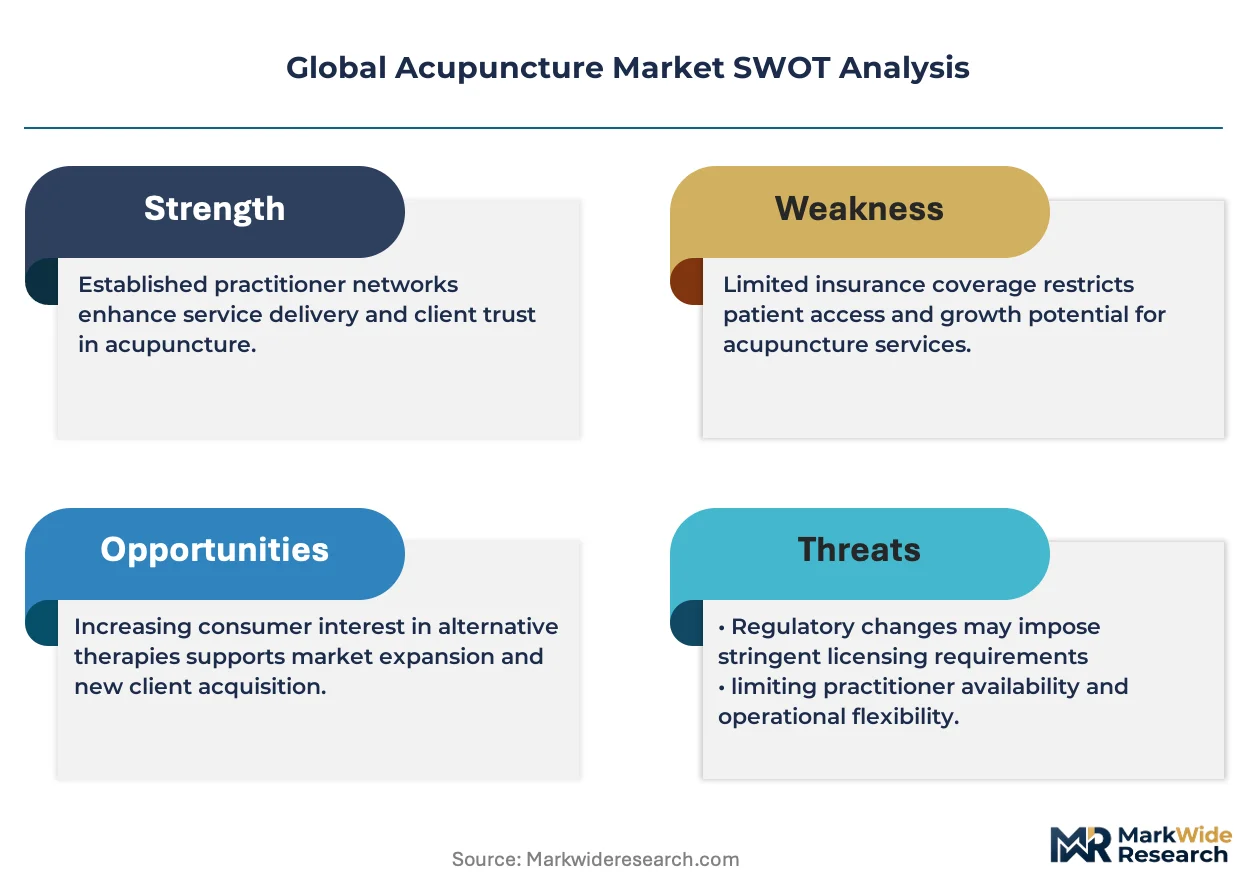
For Market Incumbents: Anticipate electroacupuncture device commoditization by securing EU MDR certification alignment ahead of Class IIa reclassification deadlines. Defensive positioning requires backward integration into stainless steel wire drawing to offset commodity input volatility, alongside educational channel control through anatomical model bundling that locks in training program procurement. For New Entrants and Emerging Players: WHO Traditional Medicine Strategy implementation in Brazil opens a window for chronic pain protocol reimbursement discussions before ANVISA pathway harmonization completes. Target underpenetrated Latin American markets through direct supply agreements with local physiotherapy center networks, leveraging NMPA export certification from Chinese manufacturing partners to bypass distributor markups. For Investors and Strategic Acquirers: Valuations sit cheapest among mass-scale Chinese needle fabricators lacking coating technology licensing, presenting consolidation targets for premium-tier capability acquisition. Long-term viability favors manufacturers with dual FDA 510(k) and EU MDR clearances that unlock hospital procurement frameworks. Monitor WHO traditional medicine insurance coverage decisions in Germany and Australia as inflection indicators for addressable patient pool expansion.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Alignment | CE marking under expanded regulations unlocks German and French hospital procurement frameworks. |
| Silicone Coating Technology Licensing | Japanese precision engineering partnerships elevate margin capture in premium disposable segments. |
| Direct Supply Agreement Negotiation | Chinese manufacturers bypass distributors to secure volume pricing with US wellness clinic chains. |
| Telemedicine Platform Integration | Digital therapeutics capture home-use segments through disposable needle subscription models. |
| Educational Channel Control | Anatomical model bundling locks in German-speaking clinical training market procurement. |
Research Approach
Multiple input streams — licensed acupuncturist interviews, hospital procurement manager discussions, and GPO contracts analysis — were reconciled against secondary validation from NMPA export certification databases, FDA 510(k) clearance records, and WHO traditional medicine strategy implementation documents. Primary fieldwork captured perspectives from Chinese needle manufacturing executives, German physiotherapy center operators, and Japanese hospital biomedical engineers. Bottom-up procedure volume estimates triangulated against top-down market value reconstructions.
Data-stream reconciliation across product type, therapy area, end user facility, and distribution channel dimensions anchored the analytical framework over the projection horizon. CAGRs derived from procedure volume growth trajectories and per-procedure pricing evolution across sterile needles, electrical devices, and semi-permanent retention SKUs. Forecast inputs incorporated WHO coverage expansion timelines, EU MDR implementation pacing, and wellness clinic chain expansion capital deployment patterns.
Revisions become necessary when WHO traditional medicine strategy implementation stalls, EU MDR certification bottlenecks prolong, or stainless steel commodity volatility exceeds historical bands. Forecasts reflect documented assumptions regarding reimbursement code expansion and practitioner training pipeline throughput. Practitioners should monitor ANVISA regulatory harmonization progress and corporate wellness program adoption rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Medicine
Global Homeopathic Product Market
Alternative Medicine
Homeopathic Medicine Market
Alternative Medicine
Europe Complementary and Alternative Medicine Market
Alternative Medicine
Complementary and Alternative Medicine for Anti Aging and Longevity Market
Alternative Medicine
US Aromatherapy Market
Alternative Medicine
Traditional Chinese Herbal Medicine Market
Alternative Medicine
Botanicals & Acupuncture Market
Alternative Medicine
Acupuncture Lasers Market
Alternative Medicine
Ozone Therapy Units Market
Alternative Medicine
Bio Magnetic Ear Stickers Market
Alternative Medicine
Fire Cupping Market
Alternative Medicine
Global OTC Herbal and Traditional Medicine Market
Alternative Medicine
Biopuncture Treatment Market
Alternative Medicine
Disposable Acupuncture Needle Market
Alternative Medicine
Orthomolecular Medicine Market
Alternative Medicine
Homeopathy Products Market