
 Biopuncture Treatment Market | 2026-2036
Biopuncture Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Biopuncture Treatment Market Analytics
Plant-derived metabolite extracts are expanding their share in injectable pain protocols as practitioners shift from synthetic corticosteroid alternatives toward diluted botanical formulations with lower systemic burden. Heel GmbH leverages its Traumeel and Zeel product lines to sustain dominance in European regulatory-compliant biopuncture ampoules. MediNatura, Inc. anchors North American distribution through practitioner-direct channels and homeopathic pharmacy networks. Herb Pharm differentiates via tincture-to-injectable supply chain control, occupying a niche in sustainably sourced raw material inputs.
Biopuncture treatment involves the percutaneous injection of microdosed homeopathic or botanical preparations—typically diluted to D6 or D12 potencies—into specific anatomical points to modulate inflammation and tissue repair. The technique employs ultrafine needles delivering 0.1–0.3 mL per injection site, with formulations containing compounds such as arnica, calendula, or echinacea in ethanol-stabilized solutions. Injectable Solutions command the largest product-type position due to recurring consumption and practitioner protocol standardization, while Acupuncture Needles capture margin pools through premium single-use sterile SKUs. Pain Management leads application demand, though Sports Injuries exhibits the fastest structural growth as professional athletic programs integrate biopuncture into recovery regimens.
The U.S. FDA oversees homeopathic drug manufacturing under current Good Manufacturing Practice (cGMP) guidelines, while the EU MDR reclassifies certain injectable devices and strengthens post-market surveillance for needle-based delivery systems. Germany's national pharmaceutical regulator, the Federal Institute for Drugs and Medical Devices (BfArM), maintains specific registration pathways for homeopathic injectables that shape product development priorities for manufacturers targeting German reimbursement eligibility. Stakeholders must monitor evolving MDR technical documentation requirements and U.S. homeopathic enforcement discretion policies to anticipate market access shifts.
Market Dynamics
The EU Medical Device Regulation (MDR) reclassification of injectable delivery systems is compressing product registration timelines and forcing manufacturers to consolidate technical documentation for homeopathic ampoules across German-speaking markets.
Growth Catalysts
- REACH traceability mandates:The European Chemicals Agency's tightened ingredient disclosure rules are filtering out non-compliant suppliers and concentrating demand among certified German manufacturers with established audit trails.
- Sports medicine protocols:Professional athletic programs in Germany and Austria are embedding biopuncture into tendonitis recovery regimens, creating recurring institutional demand streams.
- Plant-derived metabolite formulations:Practitioner preference for diluted botanical preparations over synthetic corticosteroid alternatives is expanding addressable patient populations with contraindications to conventional anti-inflammatories.
Market Restraints
- Ethanol-stabilized solution costs:Volatility in pharmaceutical-grade ethanol supply from Eastern European refiners is squeezing formulation margins for D6 and D12 potency preparations.
- Single-use needle supply concentration:Sterile ultrafine needle production clusters in Southeast Asian contract manufacturers expose distributors to shipping disruptions and customs clearance delays.
- BfArM registration friction:Germany's Federal Institute for Drugs and Medical Devices maintains distinct homeopathic injectable pathways that extend time-to-market for non-domestic applicants versus established local registrants.
Strategic Opportunities
- Swiss practitioner training networks:Swissmedic's harmonized recognition of German homeopathic certifications opens adjacent market access without duplicate regulatory filings.
- Veterinary sports medicine:Equine tendon recovery protocols present untapped application expansion with lower regulatory barriers than human indications.
- Direct-to-practitioner digital platforms:Telemedicine-integrated supply ordering is disintermediating traditional homeopathic pharmacy distribution in rural German districts.
Industry Challenges
- Microdosing technique certification:The scarcity of accredited training programs for 0.1–0.3 mL per-site injection precision limits practitioner pool expansion.
- MDR technical documentation backlog:Notified body capacity constraints are extending conformity assessment timelines for needle-based delivery system reclassifications.
- Botanical raw material identity testing:DNA barcoding validation for arnica and calendula extracts requires capital-intensive laboratory infrastructure that smaller compounders cannot support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biopuncture Treatment Market |
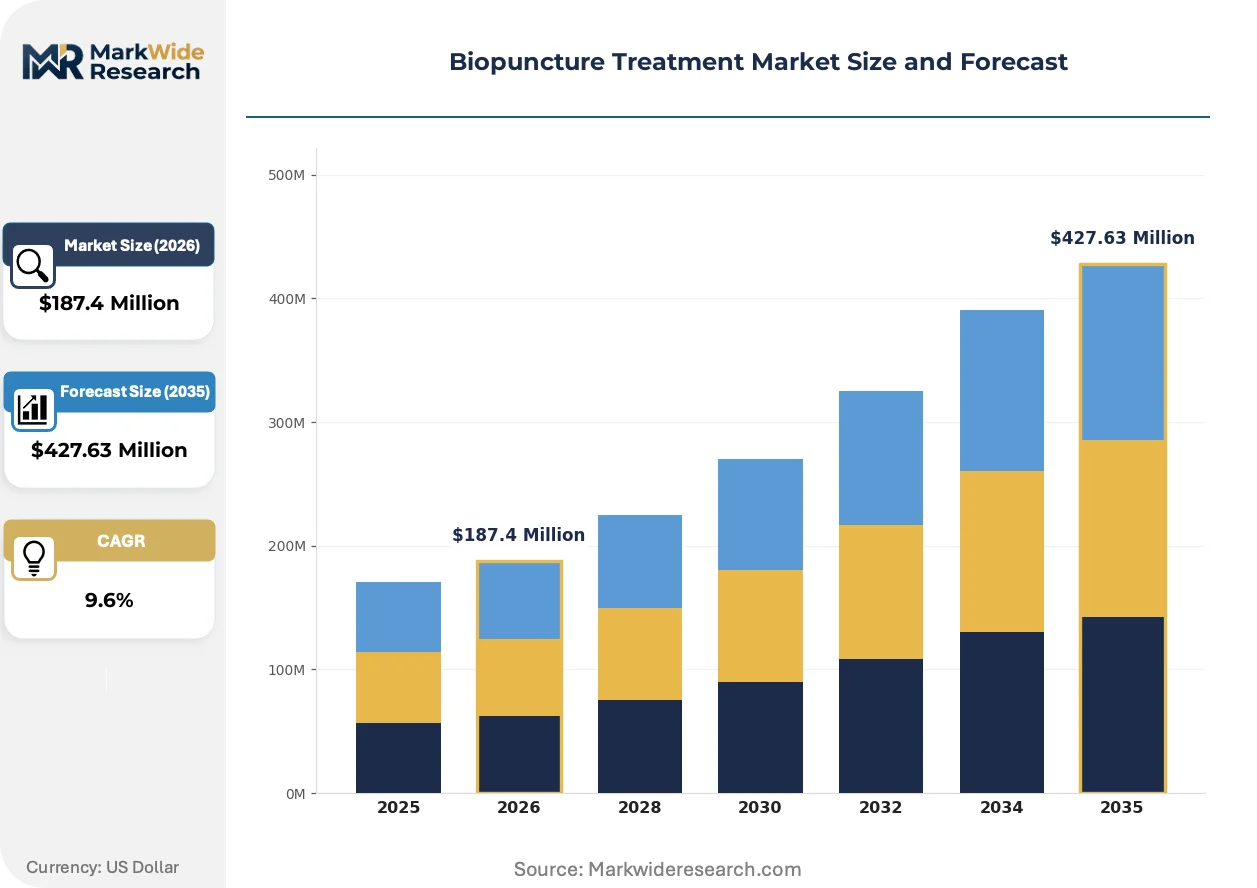
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $427.63 Million |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable Solutions, Devices, Acupuncture Needles, Supplements Application: Pain Management, Sports Injuries, Rheumatic Disorders, Musculoskeletal Conditions End User: Healthcare Providers, Clinics, Rehabilitation Centers, Home Care Delivery Mode: Intramuscular, Subcutaneous, Intra-articular, Perilesional |
| Companies Covered | MediNatura, Inc., Heel GmbH, Lohmann & Rauscher GmbH & Co. KG, Thieme, NaturalMed Therapies, Skin Renewal, Columbia Nutritional, Pure Encapsulations, LLC, Herb Pharm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biopuncture Treatment Market Evolving Landscape
Automation of injection protocol documentation and potency tracking is compressing clinical workflow friction while regulatory digitization accelerates compliance verification across European markets.
Needle-based delivery systems with integrated volume verification sensors are automating the precision of 0.1–0.3 mL microdose administration. Sports medicine clinics in Bavaria and Baden-Württemberg are piloting these devices to reduce technician variability in tendon sheath injections. The technology is automating error-rate reduction and enabling outcome data capture that supports reimbursement negotiations with German statutory health insurers.
REACH substance registration deadlines for ethanol-stabilized botanical extracts are forcing reformulation of legacy homeopathic preparations. The European Chemicals Agency's 2024-2025 dossier requirements are eliminating small-batch compounders lacking toxicology data resources. Injectable Solutions bearing full REACH Article 33 compliance documentation command premium positioning in Austrian and Swiss procurement tenders.
Specialized biopuncture certification is displacing general acupuncture licensure as the prerequisite for insurance reimbursement in German outpatient settings. The Heilpraktiker professional association's 2023 curriculum update mandates 120-hour biopuncture-specific training for new credentialing. This behavioral shift concentrates demand among continuing-education-compliant practitioners in North Rhine-Westphalia and Hamburg metropolitan clusters.
Biopuncture Treatment Market Segmentation
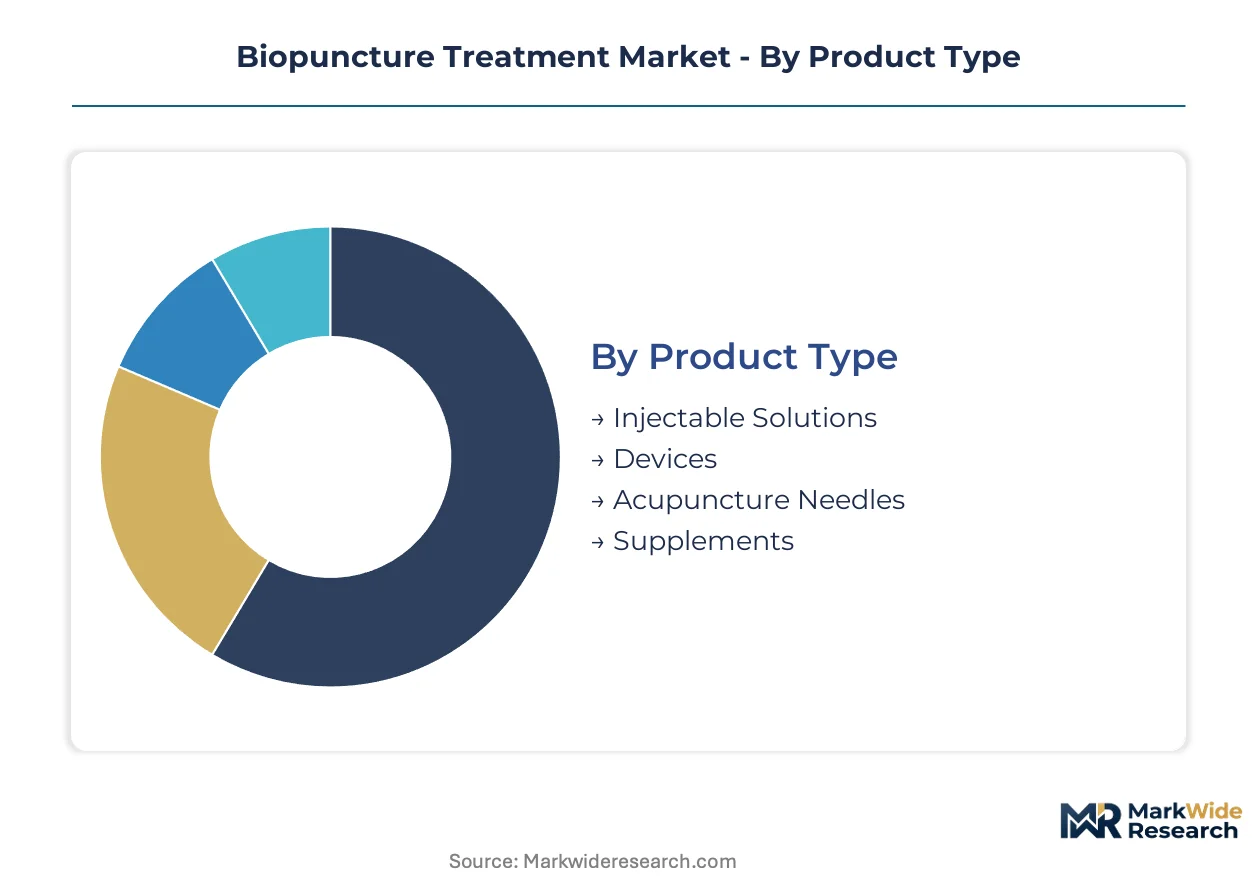
Biopuncture treatment segmentation reveals distinct capital requirements across manufacturing tiers, with sterile injectable production demanding GMP-certified facilities while needle distribution networks require cold-chain logistics infrastructure. Product differentiation concentrates in potency standardization and ethanol-stabilized formulation stability, driving procurement decisions among German and Austrian practitioner networks.
Product Type:
Injectable Solutions command the heaviest upfront capital burden, requiring pharmaceutical-grade cleanroom infrastructure and BfArM-compliant registration dossiers that smaller compounders cannot finance.
- Injectable Solutions:Microdosed homeopathic preparations diluted to D6 or D12 potencies in ethanol-stabilized matrices. Demand clusters in Bavarian sports medicine clinics seeking REACH-compliant botanical formulations for tendonitis protocols. REACH Article 33 documentation requirements are filtering out non-compliant suppliers and consolidating procurement among certified German manufacturers.
- Devices:Volume-verification sensors integrated into needle-based delivery systems automate 0.1–0.3 mL precision dosing. Pilot deployments in Baden-Württemberg clinics are reducing technician variability and capturing outcome data for statutory health insurer negotiations.
- Acupuncture Needles:Single-use sterile ultrafine needles manufactured under EU MDR reclassification requirements. Southeast Asian contract manufacturing concentration exposes distributors to shipping disruptions.
- Supplements:Oral homeopathic preparations supporting injection protocols, distributed through practitioner-direct channels and homeopathic pharmacy networks.
Injectable Solutions absorb the bulk of installed capacity; Devices are expanding most quickly.
Application:
Pain Management generates the highest procedure volume per clinic, creating recurring revenue streams that amortize practitioner training investments across German metropolitan clusters.
- Pain Management:Chronic inflammatory conditions treated with diluted arnica and calendula formulations. North Rhine-Westphalia outpatient settings concentrate demand where specialized biopuncture certification has displaced general acupuncture licensure for reimbursement eligibility.
- Sports Injuries:Tendonitis and ligament recovery protocols embedded in professional athletic programs across Germany and Austria. Institutional procurement contracts create predictable demand streams absent in individual practitioner channels.
- Rheumatic Disorders:Joint inflammation modulation using echinacea-based preparations for patients with synthetic corticosteroid contraindications.
- Musculoskeletal Conditions:Myofascial pain syndromes addressed through perilesional injection techniques requiring 120-hour certified training credentials.
Pain Management dominates procedure economics; Sports Injuries shows the steepest expansion trajectory.
End User:
Clics concentrate purchasing power through centralized procurement of standardized protocol supplies, while Home Care fragmentation elevates distribution logistics costs per unit.
- Healthcare Providers:Individual practitioners operating within statutory health insurance reimbursement frameworks, requiring Heilpraktiker association certification for biopuncture-specific credentialing.
- Clinics:Multi-practitioner facilities in Hamburg metropolitan clusters leveraging direct-to-practitioner digital platforms to disintermediate traditional pharmacy distribution.
- Rehabilitation Centers:Post-surgical recovery protocols integrating biopuncture into physiotherapy regimens, with demand tied to orthopedic procedure volumes.
- Home Care:Self-administered protocols by trained patients, limited by scarcity of accredited training programs for microdosing technique precision.
Clinics anchor procurement volume; Rehabilitation Centers are gaining share fastest.
Delivery Mode:
Intra-articular administration requires the most specialized practitioner training, creating margin premiums that offset lower procedure frequency compared to intramuscular protocols.
- Intramuscular:Deep tissue delivery of anti-inflammatory preparations into skeletal muscle groups, standard in pain management protocols with lower technical barriers to practitioner certification.
- Subcutaneous:Superficial injection for systemic absorption of metabolite extracts, common in rheumatoid arthritis treatment regimens across Austrian outpatient settings.
- Intra-articular:Direct joint space administration requiring fluoroscopic or ultrasound guidance in advanced clinic configurations.
- Perilesional:Circumferential injection around lesion sites for sports injury recovery, demanding highest precision in 0.1–0.3 mL volume control.
Intramuscular protocols capture the majority of procedure volume; Perilesional delivery is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German-speaking Europe concentrates biopuncture treatment demand through established reimbursement pathways and certified practitioner networks. Sports medicine clinics in southern Germany and Austria anchor institutional procurement volumes. Regulatory harmonization across Swiss and Austrian markets extends German product registrations without duplicate filings.
Germany
Bavarian sports medicine clinics drive institutional demand for tendonitis recovery protocols. The Federal Institute for Drugs and Medical Devices maintains distinct registration pathways for homeopathic injectables that shape manufacturer priorities. Hamburg metropolitan clusters leverage direct-to-practitioner digital platforms to disintermediate traditional pharmacy distribution channels.
Switzerland
Swissmedic's harmonized recognition of German homeopathic certifications opens adjacent market access without regulatory duplication. REACH Article 33 compliance documentation commands premium positioning in Swiss procurement tenders. Zurich and Geneva outpatient settings concentrate demand where specialized biopuncture certification has displaced general acupuncture licensure.
Austria
Professional athletic programs in Vienna and Salzburg embed biopuncture into ligament recovery regimens. The country's national pharmaceutical regulator enforces EU MDR technical documentation requirements for needle-based delivery systems. Tyrol rehabilitation centers integrate biopuncture into post-surgical physiotherapy protocols tied to orthopedic procedure volumes.
United States
Practitioner-direct channels and homeopathic pharmacy networks anchor North American distribution infrastructure. The FDA oversees homeopathic drug manufacturing under current Good Manufacturing Practice guidelines. California and New York metropolitan clusters exhibit highest practitioner density for microdosed botanical injection protocols.
Netherlands
Randstad region clinics pilot volume-verification sensors integrated into needle-based delivery systems. The country's national pharmaceutical regulator enforces EU MDR reclassification requirements for injectable devices. Amsterdam and Rotterdam rehabilitation centers capture outcome data to support statutory health insurer reimbursement negotiations.
Biopuncture Treatment Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with sterile injectable production demanding pharmaceutical-grade cleanroom infrastructure that filters out smaller compounders. The vendor base organizes around three archetypes: established German manufacturers with BfArM registration dossiers, North American distributors leveraging practitioner-direct channels, and botanical raw material suppliers controlling tincture-to-injectable supply chains. Competitive moves concentrate on M&A to consolidate technical documentation capabilities and strategic partnerships to secure REACH-compliant ethanol supply.
Within the German manufacturing tier, Heel GmbH and MediNatura, Inc. exemplify divergent geographic anchoring strategies. Heel GmbH represents the established domestic registrant archetype with BfArM-compliant product lines. MediNatura, Inc. occupies a position as the North American distributor archetype leveraging homeopathic pharmacy networks. Herb Pharm sits within the raw material control archetype, emphasizing sustainably sourced botanical inputs.
| Leading Market Players |
|---|
| MediNatura, Inc. |
| Heel GmbH |
| Lohmann & Rauscher GmbH & Co. KG |
| Thieme |
| NaturalMed Therapies |
| Skin Renewal |
| Columbia Nutritional |
| Pure Encapsulations, LLC |
| Herb Pharm |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between BfArM-registered German manufacturers and non-compliant compounders manifests in both procurement premiums and supply chain exclusion. REACH Article 33 documentation requirements concentrate purchasing power among certified suppliers while filtering out smaller ethanol-stabilized formulation producers lacking toxicology data resources.
Pricing Analysis
Volume concentration in Injectable Solutions compresses margins per ampoule while Devices with integrated volume-verification sensors capture premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates BfArM-registered German manufacturers from REACH-compliant Austrian suppliers and non-certified compounders. Price differentiation hinges on registration tier and botanical raw material identity testing capabilities. Pricing pressure stems from pharmaceutical-grade ethanol volatility originating in Eastern European refiners. Clinics exhibit highest price sensitivity due to centralized procurement volumes, while individual practitioners in rural districts show lower elasticity through direct-to-practitioner digital platform adoption.
Supply Chain Analysis
Dual-sourcing requirements for sterile ultrafine needles mandate multi-supplier qualification across Southeast Asian contract manufacturers and emerging European producers. Supply concentrates in Germany for ethanol-stabilized botanical extracts, Austria for echinacea-based preparations, and Switzerland for calendula formulations. Raw material dependencies center on arnica rootstock, pharmaceutical-grade ethanol, and DNA-barcoded calendula extracts. Single-source vulnerability in Southeast Asian needle production exposes distributors to shipping disruptions and customs clearance delays. Distribution runs through practitioner-direct channels and homeopathic pharmacy networks, with digital platforms disintermediating traditional intermediaries in metropolitan clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Volume-verification sensor integration is displacing manual microdosing techniques across German sports medicine clinics, compressing technician variability and enabling outcome data capture for reimbursement negotiations.
For Market Incumbents: To counter REACH compliance documentation requirements eliminating small-batch compounders, Heel GmbH and MediNatura should deepen backward integration into botanical raw material supply chains while consolidating technical documentation capabilities through targeted M&A. Securing captive supply of DNA-barcoded arnica and calendula extracts insulates margin positioning from identity testing cost inflation. For New Entrants and Emerging Players: The price-point gap between premium BfArM-registered devices and economy needle SKUs presents entry opportunity through veterinary sports medicine applications, where equine tendon recovery protocols face lower regulatory barriers than human indications. Tyrol rehabilitation centers and Swiss outpatient settings represent most penetrable geographies given harmonized certification recognition. Go-to-market execution should anchor in telemedicine-integrated supply ordering platforms disintermediating traditional pharmacy distribution. For Investors and Strategic Acquirers: Re-rating potential sits with raw material control archetypes given REACH traceability mandates concentrating demand among certified manufacturers with established audit trails. Long-term viability over the projection horizon favors compounders with in-house DNA barcoding validation infrastructure. The signal to watch is BfArM registration timeline compression for non-domestic applicants, which would accelerate consolidation dynamics among German-speaking manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Article 33 Compliance Certification | Eliminates non-compliant suppliers from Austrian and Swiss procurement tenders. |
| Volume-Verification Sensor Integration | Automates 0.1–0.3 mL precision dosing for Baden-Württemberg tendon sheath protocols. |
| Practitioner Training Network Expansion | Heilpraktiker association credentialing displaces general acupuncture licensure in North Rhine-Westphalia. |
| Botanical Raw Material Backward Integration | Captive arnica and calendula supply secures margin insulation from identity testing cost inflation. |
| Veterinary Sports Medicine Protocol Development | Equine tendon recovery applications bypass BfArM human-indication registration friction. |
Research Methodology
Independent corroboration across regulatory filings, procurement databases, and practitioner training records underwrites the qualitative findings in this study. Primary interviews with sports medicine clinicians, Heilpraktiker association credentialing officers, homeopathic pharmacy procurement managers, and BfArM registration consultants combined with secondary validation from EU MDR technical documentation, REACH substance registration dossiers, and German statutory health insurer reimbursement protocols. Bottom-up procedure volume estimates and top-down manufacturer capacity assessments triangulate market sizing across the analysis window.
Comparable-period anchoring to historical BfArM registration timelines and REACH compliance phase-in schedules structured the forecast framework. Segmentation modeling incorporated product type tier, application protocol, end-user facility scale, and delivery mode complexity throughout the projection horizon. CAGRs were derived from procedure volume trajectories in sports medicine clinics and rehabilitation center expansion patterns, with cross-validation against ethanol-stabilized formulation consumption trends and needle-based delivery system procurement data.
Inputs from ECHA registration databases and BfArM approval records were available through the study window; gaps in real-time practitioner census enumeration introduce uncertainty bands around addressable market estimates. Forecasts reflect assumptions regarding REACH deadline adherence and MDR notified body capacity constraints. A model refresh is warranted upon material change in EU MDR technical documentation requirements or BfArM registration pathway modifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Medicine
Bio Magnetic Ear Stickers Market
Alternative Medicine
Traditional Chinese Herbal Medicine Market
Alternative Medicine
Global Complementary and Alternative Medicines Market
Alternative Medicine
Aromatherapy Market
Alternative Medicine
Traditional Chinese Medicine Market
Alternative Medicine
Orthomolecular Medicine Market
Alternative Medicine
Europe Complementary and Alternative Medicine Market
Alternative Medicine
Global OTC Herbal and Traditional Medicine Market
Alternative Medicine
Natural Cold, Cough, and Sore Throat Remedies Market
Alternative Medicine
Global Acupuncture Market
Alternative Medicine
Homeopathic Medicine Market
Alternative Medicine
Cold Laser Therapy Market
Alternative Medicine
Vacuum Cupping Market
Alternative Medicine
Botanicals & Acupuncture Market
Alternative Medicine
Acupuncture Lasers Market
Alternative Medicine
Global Homeopathic Product Market