

Cold Chain Micro-Fulfillment Hub Networks Market Size, Share, and Industry Trends Forecast 2026-2036
Cold Chain Micro-Fulfillment Hub Networks Market Insights
Software-defined temperature orchestration is broadening what cold chain operators sell beyond cubic footage. Lineage Logistics leverages its automated layer to sustain premium pricing in biologics corridors. Americold anchors North American capacity through controlled atmosphere specialization. Nichirei Corporation dominates Asia-Pacific frozen logistics with precision-temperature last-mile protocols.
Cold chain micro-fulfillment hub networks integrate modular refrigeration, automated retrieval, and real-time telemetry to preserve product integrity within a constrained footprint, typically operating between minus twenty-five and plus two degrees Celsius depending on payload. These systems serve pharmaceutical distributors and fresh grocery platforms that cannot tolerate temperature excursions during final-mile dispatch. Modular hub types occupy the fastest-expanding tier because they deploy in weeks rather than years, letting operators test demand density before committing capital. AI-powered sorting technology leads where labor scarcity intersects with high-SKU pharmaceutical fulfillment, while IoT monitoring functions as the baseline compliance layer across all hub categories.
The US FDA enforces sanitary transportation rules under FSMA that mandate verifiable cold chain continuity, compelling hub operators to embed sensor networks or face market exclusion. China's SAMR and NMPA coordinate on vaccine distribution standards that elevate authentication and thermal logging requirements for biologics handlers. The EU F-Gas Regulation restricts refrigerant chemistries, pushing operators toward cascade systems or CO2-based architectures. Stakeholders must weigh refrigerant transition timelines against modular retrofit cycles when committing capital to hub footprints.
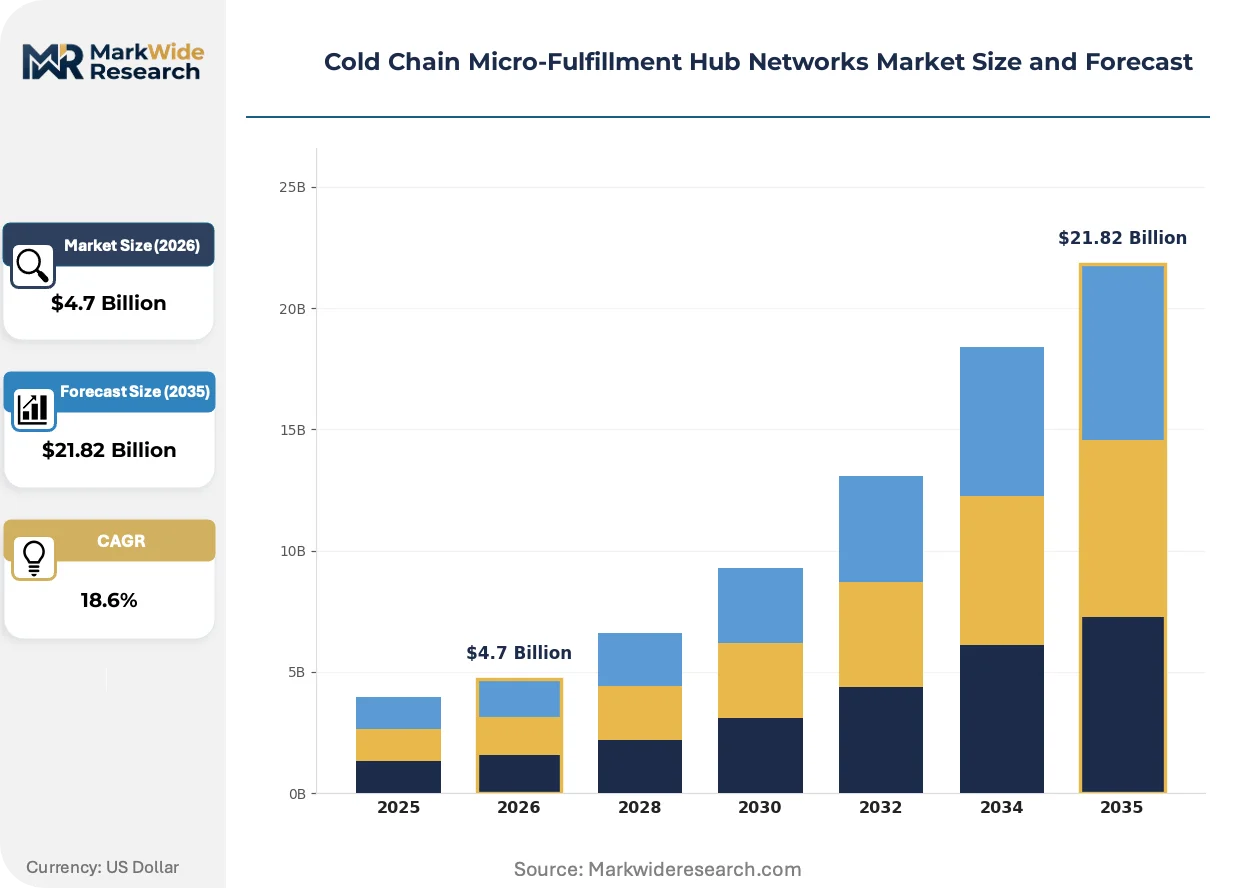
Market Dynamics
FSMA traceability mandates are compressing hub deployment timelines while refrigerant phase-down schedules under EU F-Gas Regulation force simultaneous capital reallocation toward cascade architectures. Operators must now synchronize compliance spend with modular retrofit cycles or face stranded asset risk.
Growth Catalysts
- Biologics corridor expansion:Cell and gene therapy pipelines require minus eighty Celsius staging nodes at distribution points. Pharmaceutical distributors are retrofitting urban hubs with ultra-low temperature vaults to capture this payload category.
- China's grocery e-commerce density:Eastern seaboard cities including Shanghai and Hangzhou sustain same-day fresh delivery promises that demand neighborhood-scale refrigerated nodes. SAMR food safety audits now mandate continuous temperature logging for these facilities.
- Modular refrigeration maturation:Containerized cold rooms deploy in under thirty days versus eighteen months for conventional build-outs. This compression lets operators test demand density before committing permanent infrastructure.
Market Restraints
- Refrigerant input volatility:HFC quota reductions under EU F-Gas Regulation and US AIM Act are inflating R-404A and R-410A replacement costs. Operators face stranded mechanical assets if retrofit cycles misalign with chemistries.
- Compressor supply concentration:Precision scroll and screw compressor manufacturing concentrates in German and Japanese industrial clusters. Geopolitical friction or logistics disruption propagates directly into hub commissioning delays.
- Substation interconnection queues:Electrified refrigeration loads require utility upgrades that queue eighteen to thirty-six months in dense urban jurisdictions. Grid interconnection timelines now exceed modular deployment schedules.
Strategic Opportunities
- Vaccine distribution network gaps:Sub-Saharan African and Southeast Asian last-mile cold chains remain underpenetrated for temperature-sensitive immunization programs. WHO pre-qualification standards create a certification pathway for hub operators entering these markets.
- AI-powered predictive maintenance:Machine learning models trained on compressor vibration and refrigerant pressure telemetry are converging with digital twin architectures. Early adopters compress unplanned downtime by forecasting mechanical failure before temperature excursions occur.
- Direct-to-restaurant channels:Foodservice distributors are bypassing broadline warehouses with urban micro-hubs positioned for chef-procured specialty proteins and produce. This channel innovation captures margin previously allocated to multi-stop delivery routes.
Industry Challenges
- Refrigeration technician scarcity:CO2 transcritical system servicing requires certification pathways that lag deployment timelines. Training program throughput constrains operator expansion in markets adopting natural refrigerant architectures.
- Multi-temperature zone integration:Simultaneous minus twenty-five, two, and fifteen Celsius chambers within constrained footprints demand precision airflow modeling. Design errors propagate into persistent temperature stratification and product loss.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cold Chain Micro-Fulfillment Hub Networks Market Trends and Innovations
Automation architectures are compressing labor dependency while sensor networks transform compliance from documentation exercise into real-time operational signal. These shifts are redefining competitive position around telemetry density rather than cubic footage alone.
Cascade refrigeration systems using CO2 as the low-temperature stage and ammonia or hydrocarbons as the high-temperature stage are consolidating market preference in jurisdictions with aggressive F-Gas phase-down schedules. European hub operators facing 2030 HFC reduction targets are retrofitting existing facilities with these architectures to preserve refrigerant charge compliance. The technology is consolidating vendor relationships around specialists with dual-chemistry service capabilities, compressing the supplier base for mechanical infrastructure.
The EU F-Gas Regulation's quota allocation mechanism is tightening refrigerant supply for conventional direct-expansion systems. Hub operators in Germany, France, and Italy are now specifying natural refrigerant architectures in new build tenders to preempt availability constraints. Biologics handlers with ultra-low temperature requirements face the steepest adaptation curve, as CO2 transcritical systems require redesigned compressor racks and safety protocols.
Hospital and pharmacy buying committees are unbundling storage from logistics services, contracting hub operators for temperature-controlled staging while retaining direct relationships with last-mile couriers. This procurement fragmentation is displacing integrated cold chain contracts in North American and Western European metropolitan markets. The shift is most visible in oncology drug distribution, where specialty pharmacies demand dedicated minus eighty Celsius nodes with audit-ready telemetry independent of carrier selection.
Cold Chain Micro-Fulfillment Hub Networks Market Segmentation
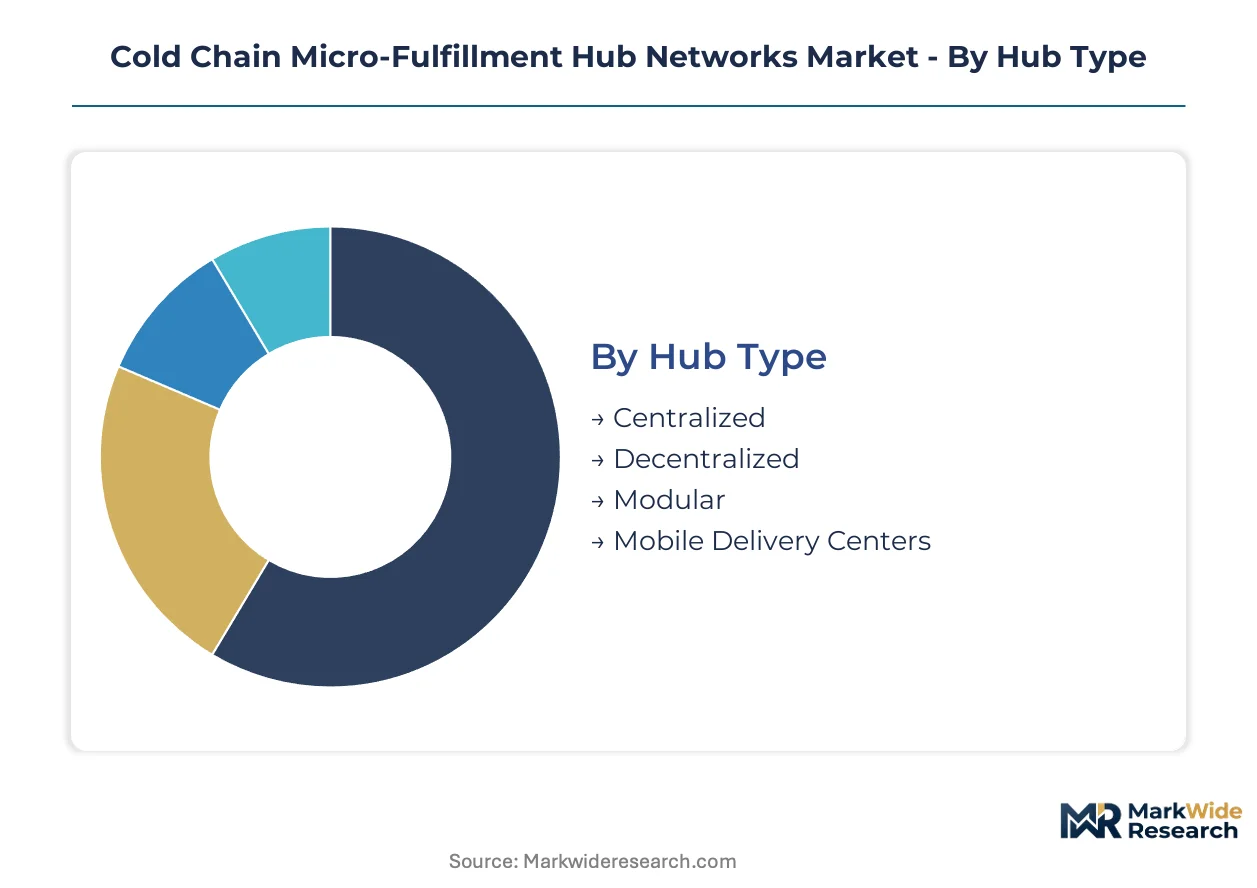
Cold chain micro-fulfillment networks segment across operational topology, automation depth, payload temperature requirements, and procurement relationships. Each dimension carries distinct capital intensity profiles and regulatory exposure that shape operator strategy.
Hub Type:
Customization-to-standardization tension runs deepest here: modular and mobile formats prioritize rapid reconfiguration against fixed infrastructure, while centralized and decentralized models trade efficiency for responsiveness.
- Centralized:Large-scale facilities consolidate multi-temperature inventory for regional distribution, typically serving pharmaceutical wholesalers with minus eighty Celsius vault capacity. Demand concentrates in Germany and the United States where biologics manufacturers require staging nodes near airport cargo terminals. Capital commitments run highest here, with refrigeration loads demanding dedicated substations.
- Modular:Containerized cold rooms deploy in under thirty days versus eighteen months for conventional build-outs. China's eastern seaboard cities including Shanghai and Hangzhou sustain same-day fresh delivery promises that demand neighborhood-scale refrigerated nodes operators can reposition as demand patterns shift.
- Decentralized:Distributed footprints position inventory within final-mile radius of consumption clusters. Japanese convenience chains deploy these for prepared meal replenishment with strict temperature band maintenance.
- Mobile Delivery Centers:Refrigerated vehicle fleets with telemetry-linked staging capability serve event-driven or emergency distribution scenarios. WHO pre-qualification standards create certification pathways for operators entering Sub-Saharan African vaccine campaigns.
Leading the category by volume: Centralized. Growing fastest: Modular.
Technology:
Cost tier stratification separates baseline compliance infrastructure from premium automation that commands service premiums.
- Automated Storage & Retrieval:Vertical lift modules and shuttle systems compress labor dependency in high-SKU pharmaceutical fulfillment. Biologics handlers with ultra-low temperature requirements face the steepest adaptation curve as mechanical infrastructure must maintain precision at minus eighty Celsius.
- AI-Powered Sorting:Machine vision and predictive routing algorithms converge with digital twin architectures to forecast mechanical failure before temperature excursions occur. Demand concentrates where labor scarcity intersects with high-value payload handling.
- IoT Monitoring:Continuous temperature logging functions as the baseline compliance layer across all hub categories. US FDA FSMA traceability rules mandate verifiable cold chain continuity that elevates sensor network density requirements.
- Robotics:Articulated arms and autonomous mobile units handle payload movement in confined footprints where human access disrupts temperature stability. European operators facing EU F-Gas refrigerant phase-down schedules prioritize electrified mechanical systems.
Highest deployment cost tier: Automated Storage & Retrieval. Fastest adoption velocity: AI-Powered Sorting.
Application:
Margin structure varies dramatically across payload categories, with temperature stringency and spoilage risk determining service pricing power.
- Biologics:Cell and gene therapy pipelines require minus eighty Celsius staging nodes at distribution points. Pharmaceutical distributors retrofit urban hubs with ultra-low temperature vaults to capture this highest-margin payload category.
- Fresh Produce:Same-day delivery promises from grocery platforms demand precise humidity and temperature control within two to four Celsius bands. China's SAMR food safety audits mandate continuous temperature logging for these facilities.
- Pharmaceuticals:Conventional vaccine and insulin distribution operates across fifteen to twenty-five Celsius controlled environments. Hospital buying committees increasingly unbundle storage from logistics services in North American metropolitan markets.
- Seafood:Rapid cooling and sustained near-freezing temperatures preserve product integrity for chef-procured specialty channels. Japanese and South Korean urban hubs specialize in tuna and shellfish staging for direct-to-restaurant distribution.
- Frozen Foods:Minus eighteen Celsius baseline requirements align with established mechanical infrastructure and lower compliance documentation intensity. Retail chains anchor volume here with predictable replenishment patterns.
Widest margin capture: Biologics. Steepest volume expansion: Fresh Produce.
End User:
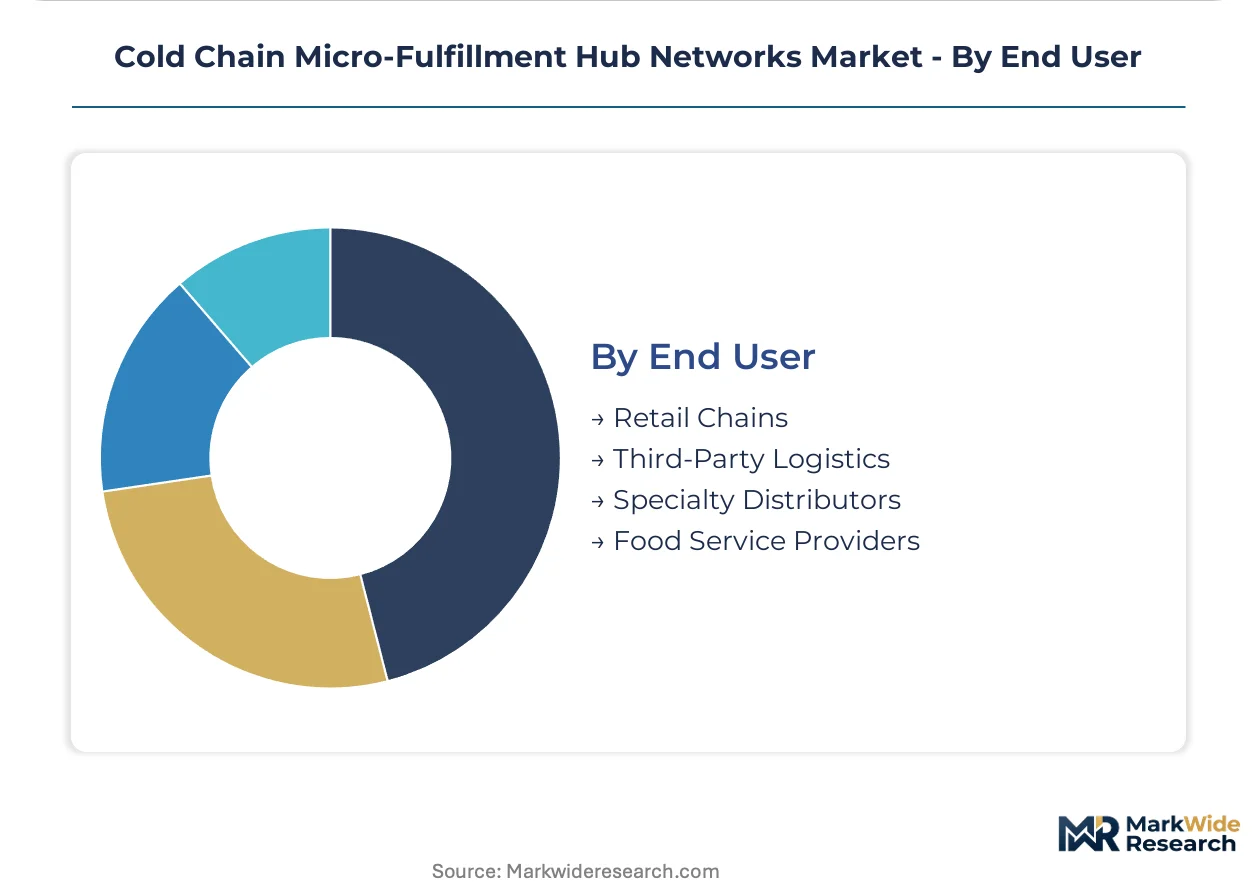
Customer type determines contract structure, with integrated operators seeking captive capacity versus fragmented buyers purchasing transactional cubic footage.
- Third-Party Logistics:Multi-tenant facilities aggregate demand across payload categories to improve refrigeration asset utilization. Lineage Logistics leverages automated layers to sustain premium pricing in biologics corridors through specialized certification.
- Retail Chains:Grocery platforms with same-day delivery mandates deploy proprietary hub networks to preserve margin previously allocated to outsourced fulfillment. China's eastern seaboard penetration drives neighborhood-scale node construction.
- Specialty Distributors:Oncology drug and rare disease therapy handlers require dedicated minus eighty Celsius nodes with audit-ready telemetry independent of carrier selection. Procurement fragmentation displaces integrated cold chain contracts in Western Europe.
- Food Service Providers:Chef-procured specialty proteins and produce bypass broadline warehouses through urban micro-hubs. This channel innovation captures margin previously allocated to multi-stop delivery routes.
Dominant contract volume: Third-Party Logistics. Fastest procurement shift: Specialty Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in Germany and the United States where biologics manufacturers demand staging infrastructure near airport cargo terminals, while consumption gravity tilts toward China's eastern seaboard cities where grocery e-commerce penetration drives neighborhood-scale node deployment.
United States
Pharmaceutical distributors retrofit urban hubs with ultra-low temperature vaults to capture cell and gene therapy payloads. FDA FSMA traceability mandates compress deployment timelines while forcing sensor network density upgrades. The Greater Boston corridor anchors biologics corridor expansion with minus eighty Celsius staging infrastructure.
Germany
EU F-Gas Regulation quota allocations tighten refrigerant supply for conventional direct-expansion systems, pushing operators toward cascade architectures. EMA pharmaceutical distribution standards elevate authentication requirements for biologics handlers. The Rhine-Ruhr industrial cluster hosts retrofit activity targeting 2030 HFC reduction timelines.
China
SAMR food safety audits mandate continuous temperature logging for neighborhood-scale refrigerated nodes serving same-day fresh delivery. NMPA coordinates with SAMR on vaccine distribution standards that elevate thermal logging requirements. Shanghai and Hangzhou sustain the deepest grocery e-commerce penetration, driving modular hub construction.
Japan
Convenience chains deploy decentralized footprints for prepared meal replenishment with strict temperature band maintenance. METI industrial standards shape refrigeration technician certification pathways for natural refrigerant architectures. The Kanto region around Tokyo concentrates precision-temperature last-mile protocol development.
Brazil
Foodservice distributors bypass broadline warehouses with urban micro-hubs positioned for chef-procured specialty proteins. ANVISA pharmaceutical cold chain regulations create compliance benchmarks for temperature-controlled staging. The São Paulo metropolitan corridor anchors South American capacity expansion for direct-to-restaurant channels.
Cold Chain Micro-Fulfillment Hub Networks Market Competitive Landscape
Top-tier vendors anchor biologics corridor specialization, while mid-tier operators compete on modular deployment speed and geographic coverage density. The vendor base stratifies across integrated cold chain operators, automated infrastructure specialists, and regional temperature-controlled logistics providers. Three archetypes dominate: certification-driven biologics handlers, automation-integrated platform operators, and emerging market last-mile specialists. Competitive moves concentrate on M&A for corridor consolidation and strategic partnerships for refrigerant technology transition.
Within the integrated cold chain tier, Lineage Logistics and Americold occupy positions exemplifying divergent strategic emphases—Lineage representing automated layer premium pricing in biologics corridors, Americold anchoring North American capacity through controlled atmosphere specialization. Nichirei Corporation sits within the Asia-Pacific precision-temperature segment, illustrating how regional dominance in frozen logistics translates into last-mile protocol authority. These three entities represent the competitive spectrum from automation-integrated biologics handling to scale-driven regional capacity.
| Leading Market Players |
|---|
| Lineage Logistics |
| Americold |
| United States Cold Storage |
| Burris Logistics |
| NewCold |
| Nichirei Corporation |
| Snowman Logistics |
| Conestoga Cold Storage |
| SuperFrio Logística Frigorificada |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up cold chain specialists have consolidated regional capacity into national networks, compressing vendor diversity while hardening pricing discipline through captive customer relationships and long-term offtake commitments.
Pricing Analysis
Margin tightening in modular hub tiers reflects refrigerant retrofit cycles misaligned with EU F-Gas phase-down timelines. Three-tier pricing structure across premium biologics certification, standard pharmaceutical compliance, and economy frozen-food baselines separates customers by payload temperature stringency and audit documentation intensity. Cost-down pressure on economy tiers accelerates because retail chains internalize fulfillment to preserve margin previously allocated to third-party logistics. Specialty distributors with minus eighty Celsius requirements exhibit least price sensitivity, while foodservice procurement committees negotiating chef-procured protein contracts demonstrate highest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with German and Japanese precision scroll compressor manufacturers, where geopolitical friction or logistics disruption propagates directly into hub commissioning delays. Mechanical refrigeration components concentrate in Germany, Japan, and China, with cascade system architectures drawing from Austrian and Danish CO2 transcritical specialists. Steel enclosure fabrication and IoT sensor modules rest on Chinese and South Korean electronics clusters. Tariff exposure on refrigerant chemistries and compressor assemblies elevates landed cost volatility. Distribution runs through pharmaceutical wholesalers, grocery platform procurement teams, and foodservice broadline distributors with diverging contract structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cold chain micro-fulfillment has become a vertical-integration race, with operators pursuing backward integration into refrigerant technology and forward integration into last-mile courier relationships to capture margin across the temperature-controlled logistics stack.
For Market Incumbents: Anticipate refrigerant chemistry transitions by securing dual-certification service partnerships before EU F-Gas quota allocations tighten further. Anchor capacity in biologics corridors through minus eighty Celsius vault investments near airport cargo terminals. Defend against modular disruptors by accelerating retrofit cycles to match containerized deployment timelines. For New Entrants and Emerging Players: Enter via WHO pre-qualification pathways for vaccine distribution networks in Sub-Saharan African and Southeast Asian markets where last-mile cold chains remain underpenetrated. Target mobile delivery center formats for emergency immunization campaigns and event-driven pharmaceutical staging. Position around natural refrigerant architectures to differentiate from incumbent HFC-dependent infrastructure. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap regional operators in Brazil and Southeast Asia with stranded conventional refrigeration assets and substation interconnection delays compressing valuations. Long-term viability hinges on refrigerant transition execution capability and utility relationship depth. Monitor compressor supply lead times as inflection indicator for sector-wide capacity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Cascade Refrigeration Retrofit | Preserves refrigerant charge compliance under EU F-Gas Regulation quota mechanisms. |
| AI-Powered Predictive Maintenance | Compresses unplanned downtime by forecasting mechanical failure before temperature excursions occur. |
| Modular Hub Rapid Deployment | Tests demand density in China's eastern seaboard cities before permanent infrastructure commitment. |
| Biologics Corridor Specialization | Captures premium pricing from cell and gene therapy pipelines requiring minus eighty Celsius staging. |
| Direct-to-Restaurant Channel Expansion | Bypasses broadline warehouses to capture margin from chef-procured specialty protein procurement. |
Research Methodology
Multi-period observation of modular deployment timelines, refrigerant chemistry transitions, and grocery e-commerce penetration rates anchored the trend analysis, supplemented by interviews with cold chain operations directors, pharmaceutical distribution executives, refrigeration systems procurement managers, and foodservice logistics planners. Secondary validation drew from FDA FSMA guidance documents, EU F-Gas Regulation quota allocation records, SAMR food safety audit protocols, customs data on compressor and refrigeration component trade flows, and SEC filings of publicly traded cold chain operators. Bottom-up hub deployment counts triangulated against top-down pharmaceutical and fresh produce logistics spend estimates.
Segment-weighting across hub type, automation technology depth, payload temperature requirement, and end-user procurement relationship shaped the analytical framework. The projection horizon incorporated biologics pipeline expansion trajectories, grocery platform same-day delivery mandate diffusion, and refrigerant phase-down enforcement schedules across jurisdictions. CAGRs were derived from installed base growth rates, capacity utilization trends, and service pricing dynamics. Forecast inputs included substation interconnection queue lengths, compressor manufacturing capacity constraints, and technician certification program throughput.
Forecast precision tightens around the base case; tail outcomes carry wider variance under refrigerant supply disruption scenarios or accelerated EU F-Gas quota reductions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.