
 Insulated Shipping Boxes Market | 2026-2036
Insulated Shipping Boxes Market Size, Share, and Industry Trends Forecast 2026-2036
Insulated Shipping Boxes Market Outlook
Expanded polystyrene is rebalancing toward bio-based and recyclable alternatives as sustainability mandates tighten across European and North American supply chains. Sonoco ThermoSafe leverages integrated thermal packaging design to sustain premium positioning in pharmaceutical distribution. Cold Chain Technologies anchors its competitive stance through specialized phase-change material engineering for ultra-low temperature payloads. TemperPack differentiates via plant-fiber insulation platforms that compete directly with conventional foam economics.
Insulated shipping boxes are enclosed thermal protection containers engineered with insulating barriers—commonly expanded polystyrene, polyurethane foam, vacuum-insulated panels, or reflective foil composites—to maintain defined temperature ranges for 24–120 hours during transit, primarily serving temperature-sensitive goods in pharmaceutical, food, and biologics logistics. Foam boxes dominate current volume due to established manufacturing scale and cost efficiency in short-haul food distribution. Vacuum-insulated container packs command the highest margin pools where pharmaceutical shippers require extended duration protection for cell therapies and mRNA vaccines.
The EPA regulates refrigerant emissions in insulation blowing agents under SNAP program amendments, while the EU F-Gas Regulation phases down hydrofluorocarbon content in polyurethane foams used for cold chain packaging. FDA validation requirements for pharmaceutical distribution further shape product testing protocols and documentation standards across North American and European markets. Stakeholders must monitor evolving state-level extended producer responsibility laws in California and New York that will mandate recycled content minimums and end-of-life collection infrastructure for single-use thermal packaging.
Market Dynamics
The EU F-Gas Regulation is compressing hydrofluorocarbon use in polyurethane foam blowing agents, forcing material substitution across European pharmaceutical cold chain networks while creating competitive advantage for bio-based insulation developers.
Growth Catalysts
- Biologics pipeline expansion:Cell therapies and mRNA vaccines require ultra-low temperature stability that vacuum-insulated panels deliver, pulling investment into specialized thermal packaging capacity.
- California's extended producer responsibility mandates:State-level recycled content minimums for single-use thermal packaging are accelerating closed-loop material recovery infrastructure investments.
- Phase-change material engineering:Advanced salt hydrate and paraffin formulations now maintain -80°C to +25°C ranges for 96+ hours, enabling direct-to-patient distribution models.
Market Restraints
- Petrochemical feedstock volatility:Expanded polystyrene resin prices fluctuate with benzene and styrene monomer markets, compressing margin predictability for foam-dominant manufacturers.
- Specialized VIP supplier concentration:Vacuum-insulated panel core materials rely on a narrow base of fumed silica and aerogel producers concentrated in Germany and Japan.
- REACH substance restrictions:ECHA evaluations of flame retardants and blowing agent residuals are lengthening reformulation timelines for incumbent polyurethane systems.
Strategic Opportunities
- India's biopharma manufacturing corridor:CDSCO regulatory harmonization with ICH guidelines is attracting cold chain infrastructure investment around Hyderabad and Bangalore.
- Reusable container-as-a-service models:IoT-tracked returnable thermal shippers displace single-use boxes in high-frequency hospital-to-pharmacy lanes.
- Plant-fiber insulation platforms:Mycelium and agricultural waste composites qualify for EU Green Deal procurement preferences while matching EPS thermal performance.
Industry Challenges
- Thermal validation engineering capacity:FDA 21 CFR Part 11 documentation requirements for pharmaceutical distribution strain specialized testing laboratory availability.
- Multi-material separation at end-of-life:Composite constructions combining foam, film, and refrigerant gel packs complicate mechanical recycling streams and EPR compliance.
- Legacy ERP integration:Temperature monitoring data streams from smart containers require API connectivity investments that mid-size logistics providers delay.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insulated Shipping Boxes Market |
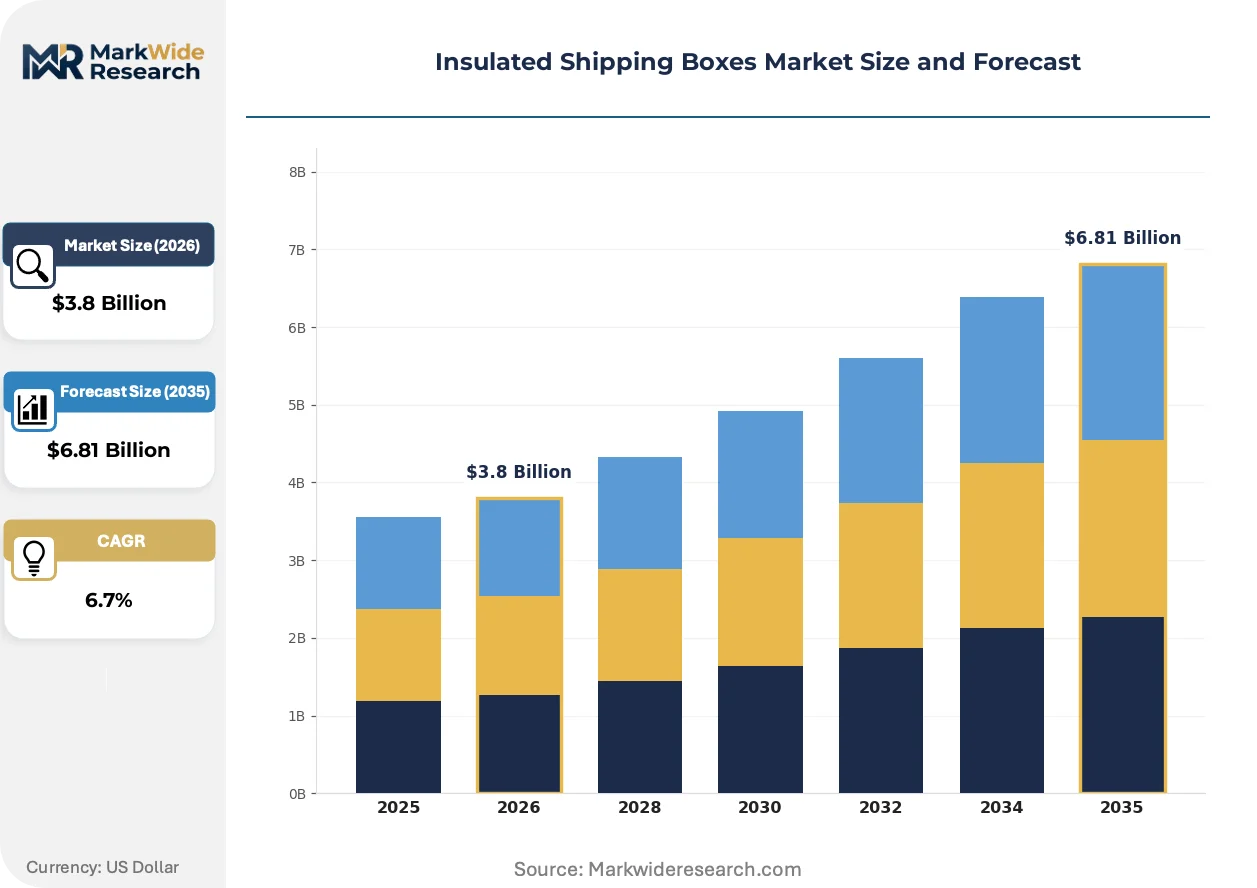
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foam Boxes, Cardboard Boxes, Thermal Bags, Container Packs Insulation Material: Polystyrene, Polyurethane, Vacuum, Reflective Foil End User: Food & Beverage, Pharmaceuticals, Electronics, Cosmetics Distribution Channel: Online Retail, Wholesale, Direct Sales, Distributors |
| Companies Covered | Sonoco ThermoSafe, Cold Chain Technologies, Cryopak, TemperPack, Pelican BioThermal, Softbox Systems, Insulated Products Corporation, Intelsius, ThermoSafe Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insulated Shipping Boxes Market Strategic Shifts
Active thermal management systems and bio-based material platforms are restructuring competitive advantage away from passive insulation commodity supply toward integrated cold chain performance guarantees.
Vacuum-insulated panel technology is electrifying pharmaceutical distribution economics by collapsing payload-to-packaging weight ratios from 3:1 to 8:1. Specialty logistics providers serving gene therapy manufacturers are standardizing on VIP-constructed shippers for international air freight lanes. This density improvement is compressing fuel surcharges and enabling same-cost expansion into longer-duration routes previously served only by active container systems.
REACH authorization procedures for persistent organic pollutants are tightening allowable residual content in recycled polystyrene feedstocks. ECHA's 2024 substance evaluation roadmap specifically targets short-chain chlorinated paraffins found in legacy flame-retardant formulations. German pharmaceutical contract manufacturers are responding by auditing supplier certification documentation and accelerating qualification of bio-based alternatives ahead of sunset date uncertainties.
Hospital pharmacy buyers are consolidating thermal packaging specifications around pre-qualified vendor lists that bundle temperature assurance with disposal compliance. Group purchasing organizations in the US are displacing decentralized procurement by mandating EPA SNAP-compliant blowing agents and verified recycled content thresholds. This concentration is most visible in California and New York health systems where state procurement guidelines embed extended producer responsibility requirements directly into contract terms.
Insulated Shipping Boxes Market Segmentation
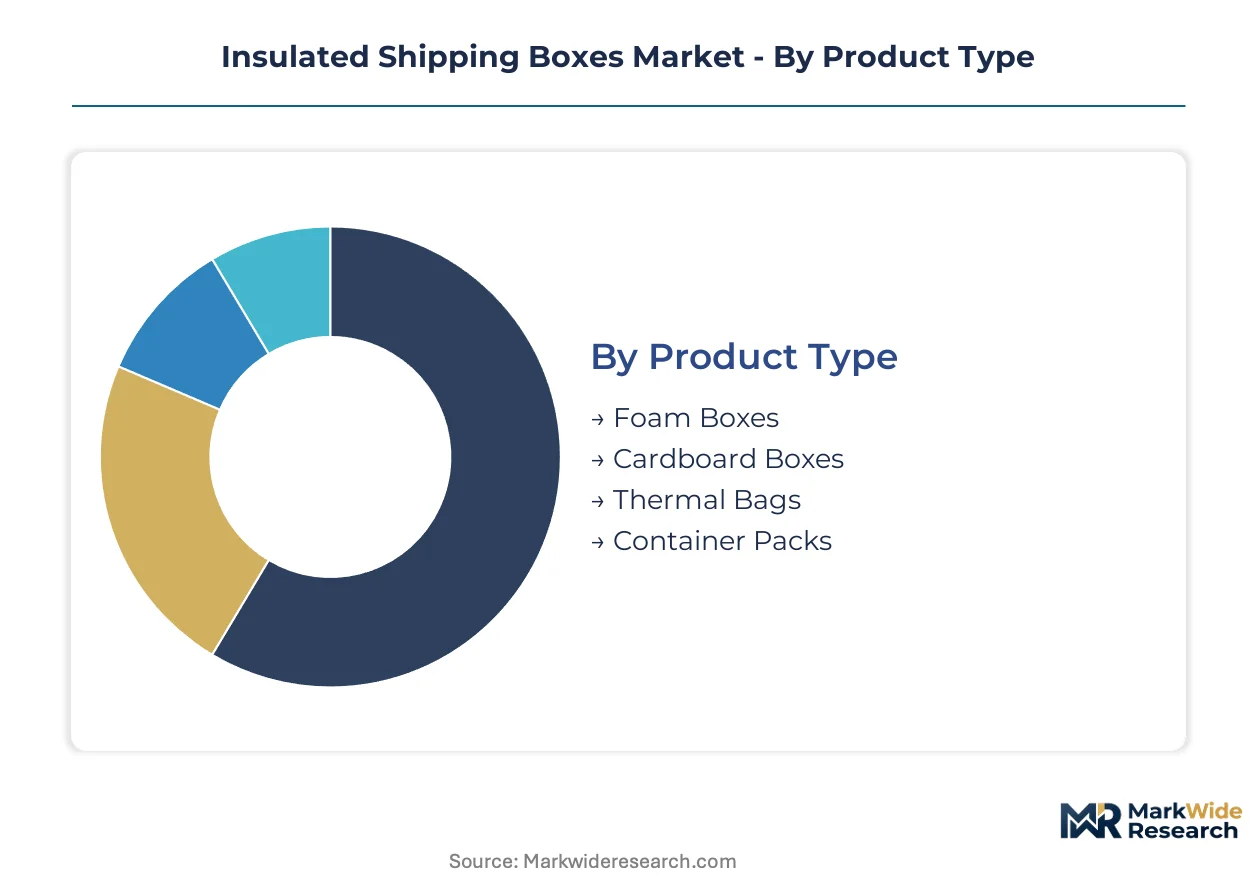
Insulated shipping boxes serve divergent performance requirements across temperature ranges, transit durations, and payload sensitivities. Segmentation reveals where capital deployment concentrates and which material platforms capture margin premiums.
Product Type:
Capital intensity varies sharply across product categories, with vacuum-insulated container packs requiring specialized manufacturing equipment and cleanroom assembly infrastructure.
- Foam Boxes:Expanded polystyrene or polyurethane cores encased in corrugated shells dominate short-haul food distribution. EPS resin extrusion lines scale efficiently, attracting private-label manufacturers serving restaurant supply chains.
- Container Packs:Vacuum-insulated panel construction with phase-change material integration commands premium positioning in pharmaceutical cold chains. German and Japanese fumed silica suppliers anchor the core material base, constraining rapid capacity expansion.
- Cardboard Boxes:Recyclable fiberboard with reflective foil or bio-based liners addresses sustainability mandates in European retail distribution.
- Thermal Bags:Flexible quilted insulation with gel pack pockets serves last-mile meal kit delivery and clinical specimen transport.
Most installed capacity flows through foam box production. Expansion is steepest in container packs.
Insulation Material:
Material selection tracks regulatory pressure on blowing agents and end-of-life disposal requirements across major economies.
- Polystyrene:Molded EPS offers the lowest unit cost for single-use food service applications. California and New York extended producer responsibility laws are forcing reformulation toward recycled content minimums.
- Vacuum:Fumed silica or aerogel cores achieve thermal conductivity below 0.007 W/m·K, enabling 96-hour protection at -80°C for cell therapy distribution.
- Polyurethane:Spray or pour-in-place PUR systems face EU F-Gas Regulation constraints on hydrofluorocarbon blowing agents, accelerating bio-based polyol adoption.
- Reflective Foil:Metallized film composites with bubble or foam substrates provide radiant barrier protection for ambient-sensitive electronics.
Polystyrene retains the largest production footprint. Vacuum insulation is climbing the fastest.
End User:
End-use concentration determines validation requirements and procurement consolidation patterns.
- Pharmaceuticals:FDA 21 CFR Part 11 documentation and temperature mapping protocols dominate vendor qualification. Gene therapy manufacturers standardize on VIP-based shippers for international air freight.
- Food & Beverage:Meal kit services and fresh produce distributors drive demand for recyclable, single-use thermal packaging with 24-48 hour duration.
- Electronics:Semiconductor and battery shippers require moisture barrier integration with thermal control for humidity-sensitive components.
- Cosmetics:Temperature-sensitive active ingredients in prestige skincare drive smaller-format insulated parcel demand.
Food and beverage absorbs the highest box volume. Pharmaceuticals deliver the strongest margin contribution.
Distribution Channel:
Channel structure reflects customer scale and technical support requirements.
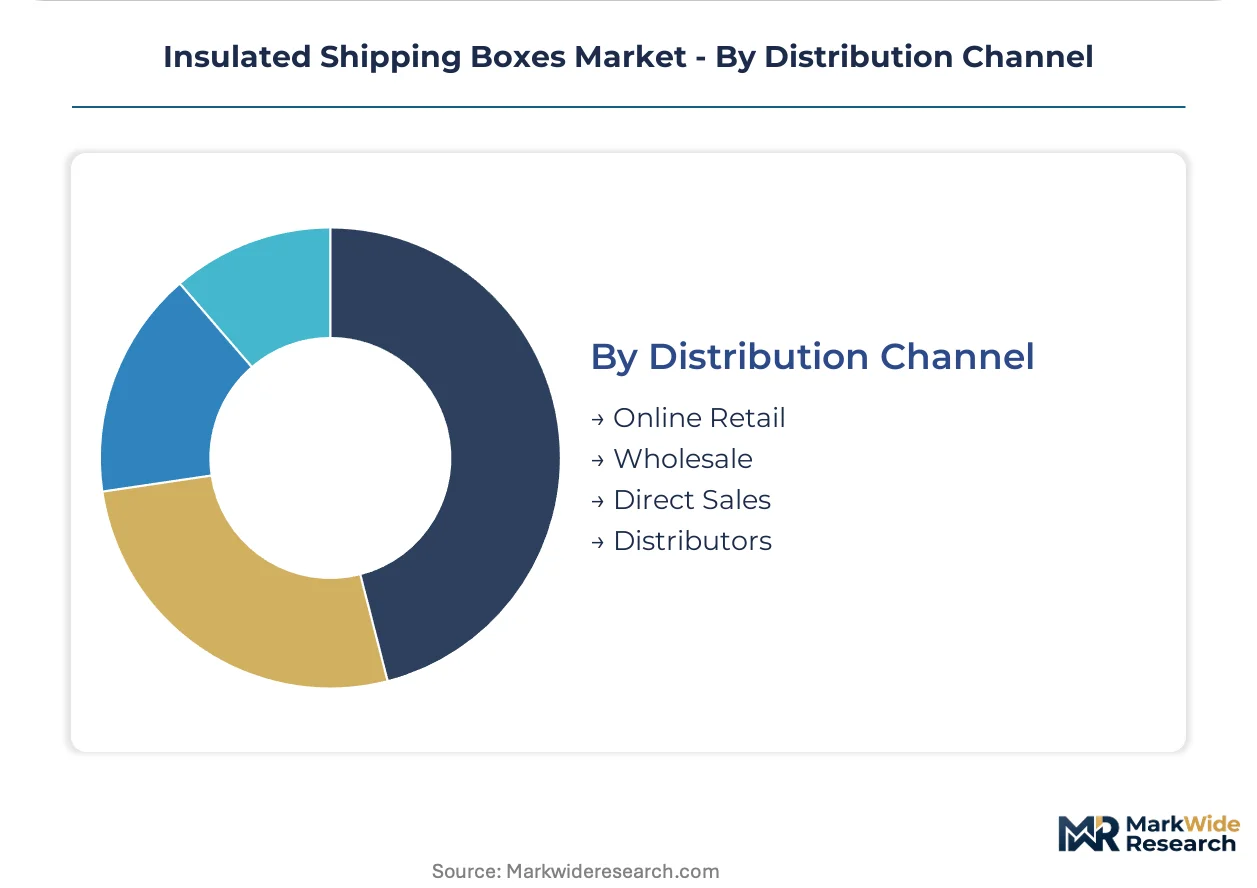
- Direct Sales:Large pharmaceutical manufacturers and contract logistics providers negotiate multi-year thermal packaging agreements with integrated temperature monitoring.
- Distributors:Industrial supply houses stock standard EPS and PUR formats for food service and industrial customers requiring rapid fulfillment.
- Wholesale:Pooled procurement through group purchasing organizations concentrates volume for hospital pharmacy networks.
- Online Retail:E-commerce platforms serve small-scale biotech startups and specialty food producers with configurable shipper configurations.
Direct sales capture the highest-value contracts. Online retail is expanding most quickly among emerging biotech entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's pharmaceutical manufacturing corridor concentrates vacuum-insulated panel demand as cell therapy production scales. The EU F-Gas Regulation and CDSCO harmonization in India are redrawing material qualification requirements across three continents.
United States
Gene therapy manufacturers in Massachusetts and North Carolina drive ultra-low temperature shipper demand for clinical trial distribution. FDA 21 CFR Part 11 validation requirements strain thermal testing laboratory capacity. California's extended producer responsibility laws mandate recycled content minimums that reformulate EPS supply chains serving West Coast food distributors.
Germany
Pharmaceutical contract manufacturers around Frankfurt and Munich standardize on VIP-based shippers for international air freight. The EU F-Gas Regulation phases down hydrofluorocarbon blowing agents in polyurethane foams. BASF and Covestro anchor bio-based polyol development in Ludwigshafen and Leverkusen.
India
CDSCO regulatory alignment with ICH guidelines attracts cold chain investment around Hyderabad and Bangalore. Biopharma manufacturing clusters serving export markets require temperature assurance for mRNA vaccine stability. The PLI scheme for pharmaceuticals accelerates specialized packaging infrastructure deployment.
Japan
PMDA validation protocols for regenerative medicine distribution sustain premium thermal packaging demand in Kanto and Kansai regions. METI carbon neutrality targets pressure material substitution away from fossil-based insulation. Osaka-based logistics providers consolidate procurement around pre-qualified vendor lists.
China
NMPA biologics approval expansion in Shanghai and Suzhou drives cold chain infrastructure investment. Dual carbon goals under MEE supervision accelerate phase-change material engineering for domestic vaccine distribution. Yangtze River Delta pharmaceutical clusters standardize on reusable container-as-a-service models.
Insulated Shipping Boxes Market Competitive Environment
Capacity expansion dominates the current landscape as specialized pharmaceutical demand outstrips VIP core material availability. The market structures around three tiers: integrated thermal packaging designers, material-focused insulation engineers, and regional foam fabricators. Strategic archetypes include temperature-assurance integrators, bio-based material developers, and phase-change chemistry specialists. M&A activity concentrates on PCM formulation capabilities and geographic expansion into India's biopharma corridor.
Among North American temperature-assurance specialists, Sonoco ThermoSafe and Cold Chain Technologies exemplify the integrated design archetype. TemperPack represents the bio-based material development vector. These three anchors illustrate how competitive positioning separates around thermal performance guarantees rather than commodity insulation supply.
| Leading Market Players |
|---|
| Sonoco ThermoSafe |
| Cold Chain Technologies |
| Cryopak |
| TemperPack |
| Pelican BioThermal |
| Softbox Systems |
| Insulated Products Corporation |
| Intelsius |
| ThermoSafe Solutions |
| Others |
Value Chain & Pricing Dynamics
Vacuum-insulated panel premiums diverge from expanded polystyrene commodity economics by a factor of eight to fifteen in unit pricing, and this bifurcation manifests in parallel supply chain configurations where German and Japanese fumed silica producers anchor high-performance tiers while Chinese and Southeast Asian resin extruders dominate foam box volume.
Pricing Analysis
Petrochemical feedstock volatility in benzene and styrene monomer markets passes through directly to expanded polystyrene unit costs, compressing margin predictability for foam-dominant manufacturers while vacuum-insulated panel producers buffer input pressure through long-term offtake contracts with fumed silica suppliers. Pricing stratifies across pharmaceutical-grade VIP certification, standard cold-chain PUR systems, and economy EPS formats for food service. Cost compression in the EPS tier is intensifying because California and New York extended producer responsibility laws mandate recycled content minimums that disrupt legacy virgin resin economics. Hospital pharmacy networks exhibit the lowest price sensitivity due to FDA validation requirements, while meal kit distributors and restaurant supply chains absorb the highest cost pressure.
Supply Chain Analysis
FDA 21 CFR Part 11 qualification and EU F-Gas Regulation compliance certification gate supplier access to pharmaceutical cold chain networks, concentrating qualified capacity among German, Japanese, and North American manufacturers with established validation documentation. Core material dependencies rest on fumed silica from German and Japanese producers, aerogel precursors from specialized chemical suppliers, and bio-based polyol feedstocks emerging from BASF and Covestro facilities. Single-source vulnerability concentrates in VIP core material supply where fumed silica production capacity expansion lags pharmaceutical demand growth. Distribution runs through direct sales contracts for large pharmaceutical manufacturers, industrial distributors for food service accounts, and group purchasing organizations for hospital pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Insulated shipping boxes constitute a late-cycle quality story as gene therapy and cell therapy pipelines force pharmaceutical buyers toward validated, extended-duration thermal protection that resists commoditization pressures affecting food-service segments.
For Market Incumbents: Hedge against bio-based material substitution by accelerating qualification of mycelium and agricultural waste composite platforms ahead of EU Green Deal procurement preference deadlines. Secure captive supply of fumed silica and aerogel precursors through backward integration or long-term offtake agreements with German and Japanese core material producers, insulating margin position from VIP supply concentration risk. For New Entrants and Emerging Players: The price-point gap between pharmaceutical-grade VIP systems and standard PUR formats creates entry space for plant-fiber insulation platforms that match EPS thermal performance while qualifying for sustainability mandates. India's biopharma manufacturing corridor around Hyderabad and Bangalore offers the most penetrable geography as CDSCO regulatory harmonization attracts cold chain infrastructure investment. A direct-to-biotech-startup online retail channel bypasses incumbent distributor relationships. For Investors and Strategic Acquirers: Consolidation pressure builds where specialized phase-change material engineering capabilities concentrate among mid-scale chemistry specialists without sufficient capital to scale manufacturing. Long-term viability favors temperature-assurance integrators with embedded IoT monitoring platforms over commodity foam fabricators facing petrochemical volatility and extended producer responsibility compliance costs. The signal to watch is CDSCO approval velocity for mRNA vaccine manufacturing sites, which would trigger demand inflection for ultra-low temperature distribution infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Phase-Change Material Engineering Scale-Up | Advanced salt hydrate formulations enable -80°C distribution for cell therapy pipelines. |
| Reusable Container-as-a-Service Deployment | IoT-tracked returnable shippers displace single-use boxes in high-frequency hospital-to-pharmacy lanes. |
| Bio-Based Polyol Manufacturing Transition | EU F-Gas Regulation compliance drives substitution away from hydrofluorocarbon blowing agents. |
| Vacuum-Insulated Panel Core Material Integration | Fumed silica supply security determines capacity expansion feasibility for pharmaceutical-grade shippers. |
| Extended Producer Responsibility Infrastructure Buildout | California and New York mandates require closed-loop collection systems for single-use thermal packaging. |
Study Parameters
Direct dialogue with cold chain logistics directors, pharmaceutical packaging engineers, regulatory affairs specialists, and group purchasing organization contract managers grounded this analysis in operational reality across North American, European, and Asia-Pacific distribution networks. Secondary validation drew from FDA 21 CFR Part 11 guidance documents, ECHA substance evaluation roadmaps, CDSCO regulatory circulars, EPA SNAP program amendments, and customs trade data on insulation material flows. Bottom-up and top-down triangulation cross-checked manufacturer capacity announcements against end-user procurement patterns and material input supply constraints.
Bottom-up modeling aggregated segment-level demand from pharmaceutical, food and beverage, electronics, and cosmetics end uses, while top-down analysis calibrated aggregate market scale against macro cold chain infrastructure investment trends across the analysis window. Segmentation dimensions included product type, insulation material platform, temperature range specification, and distribution channel structure. CAGRs were derived from regression analysis of historical shipment data and forward projection of regulatory-driven material substitution timelines, with specific weighting applied to biologics pipeline expansion rates and extended producer responsibility implementation schedules.
Caveats apply where CDSCO regulatory harmonization delays, EU F-Gas Regulation enforcement variability, or petrochemical feedstock price shocks could materially shift the outlook for material platform economics and capacity deployment timing. A model refresh is warranted upon material change in mRNA vaccine manufacturing approval velocity or state-level extended producer responsibility law expansion beyond California and New York.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Packaging
Foam Mesh Sleeves Market
Protective Packaging
North America Insulated Packaging Market
Protective Packaging
Thermal Insulated Bubble Wrap Market
Protective Packaging
Void Fill Pillows Market
Protective Packaging
Thermal Insulated Mailers Market
Protective Packaging
Padded Dividers Market
Protective Packaging
Europe Protective Packaging Market
Protective Packaging
High Pressure Protective Packaging Film Market
Protective Packaging
Corrugated Bubble Wrap Market
Protective Packaging
Molded Fiber Pulp Edge Protectors Market
Protective Packaging
Insulated Packaging Market
Protective Packaging
Insulated Shippers Market
Protective Packaging
Insulated Styrofoam Shipping Boxes Market
Protective Packaging
Fiber Cushioning Market
Protective Packaging
Protective Wrapping Paper Market
Protective Packaging
Global Packaging Inserts and Cushions Market