
 Cryogenic Boxes Market | 2026-2036
Cryogenic Boxes Market Size, Share, and Industry Trends Forecast 2026-2036
Cryogenic Boxes Market Outlook
REACH compliance is broadening the cost-of-entry calculus for European manufacturers seeking CE-marked cryogenic containment solutions. Thermo Fisher Scientific Inc. leverages its integrated cold-chain infrastructure to dominate North American laboratory procurement channels. Corning Incorporated anchors its position through specialized glass-composite material science that extends thermal retention performance in ultra-low environments. BIOLOGIX GROUP LTD competes aggressively on polyurethane molding scale across Asian research laboratory markets.
Cryogenic boxes are vacuum-insulated or foam-filled enclosures engineered to maintain temperatures below minus 150 degrees Celsius for biological specimen preservation, vaccine transport, or aerospace component conditioning. Stainless steel variants command the highest unit margins due to weld-seal durability in liquid nitrogen immersion protocols, while composite materials represent the fastest-expanding material class as pharmaceutical companies seek lighter transport configurations. Laboratory cryogenic boxes lead volume demand from research institutions, though custom cryogenic boxes capture premium pricing from cell therapy manufacturers requiring validated rack geometries.
The EPA governs refrigerant containment and disposal protocols affecting box liner specifications in the United States, while the EU F-Gas Regulation phases down hydrofluorocarbon insulation gases and redirects European procurement toward polyurethane and vacuum-panel alternatives. ISO 9001 and ISO 13485 certifications function as baseline qualification filters for healthcare and pharmaceutical tenders across OECD procurement frameworks. Stakeholders must monitor evolving dual-use export controls on cryogenic technologies that could restrict composite-material box shipments to certain research end users.
Market Dynamics
Biobanking infrastructure expansion and EMA cold-chain validation requirements are compressing procurement cycles and forcing material specification upgrades across pharmaceutical and research end uses.
Growth Catalysts
- Precision medicine biobanking:Clinical sample preservation protocols in the United States are mandating validated cryogenic containment systems for longitudinal genomic studies.
- F-Gas Regulation phase-down:The EU directive is redirecting European manufacturers toward polyurethane and vacuum-panel insulation alternatives, creating material innovation pull.
- Cell therapy manufacturing scale-up:Autologous and allogeneic therapy producers require custom rack geometries that standard laboratory boxes cannot accommodate.
Market Restraints
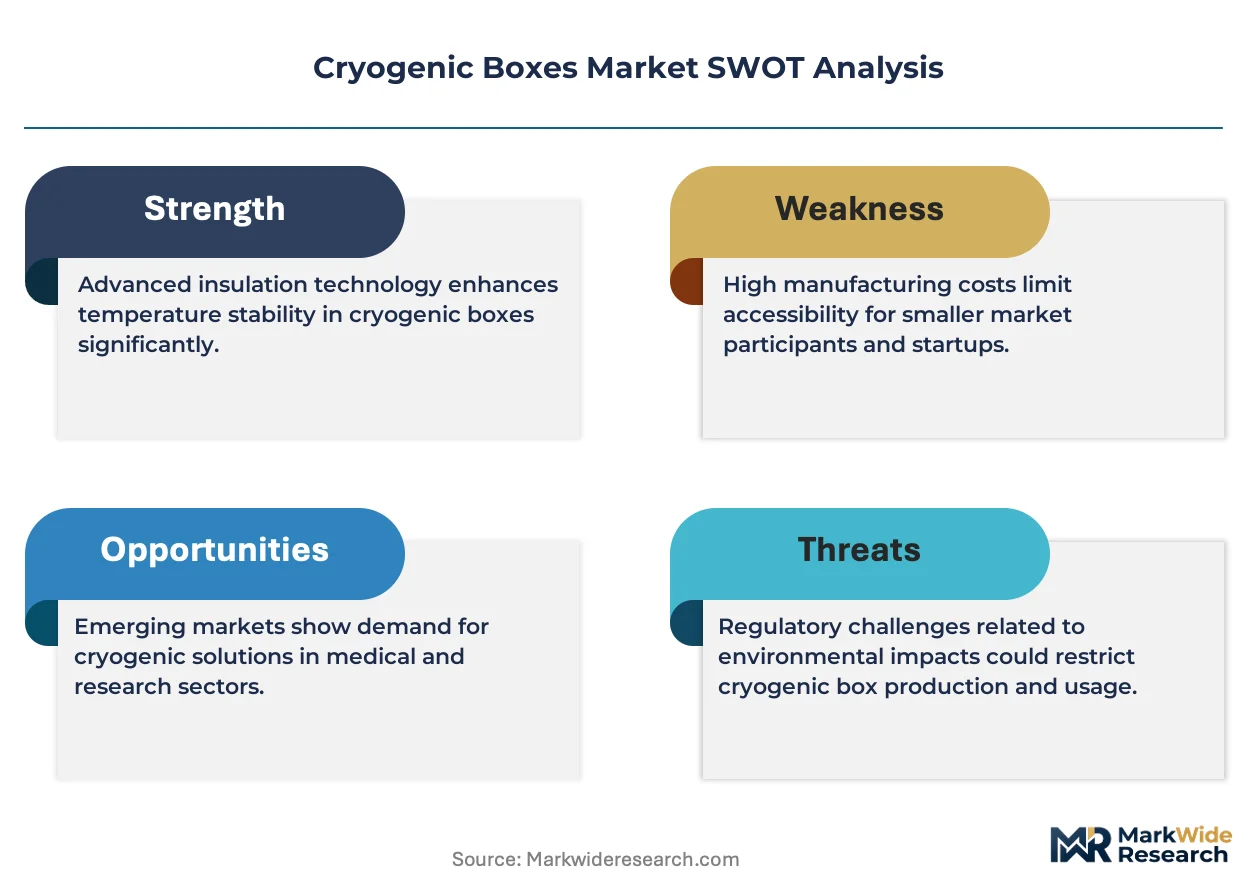
- Stainless steel input cost volatility:Nickel and chromium price swings compress margins on vacuum-insulated variants with liquid nitrogen immersion ratings.
- Supply concentration in aluminum extrusion:German and Austrian mill capacity constraints limit composite-material box production scaling.
- REACH compliance cost escalation:ECHA substance authorization timelines extend product development cycles for CE-marked containment solutions.
Strategic Opportunities
- Indian biopharma cold-chain buildout:CDSCO quality mandate enforcement is creating validated cryogenic storage demand in contract research and manufacturing organizations.
- Aerospace component conditioning:Satellite propulsion system testing protocols require portable ultra-low temperature enclosures for pre-launch thermal cycling.
- Digital temperature logging integration:IoT sensor embedding enables real-time chain-of-custody documentation for high-value cell therapy shipments.
Industry Challenges
- ISO 13485 certification timeline compression:Medical device quality system implementation extends go-to-market schedules for healthcare-focused product lines.
- Weld-seal technician scarcity:Stainless steel vacuum chamber fabrication requires specialized orbital welding expertise concentrated in Central European job markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cryogenic Boxes Market |
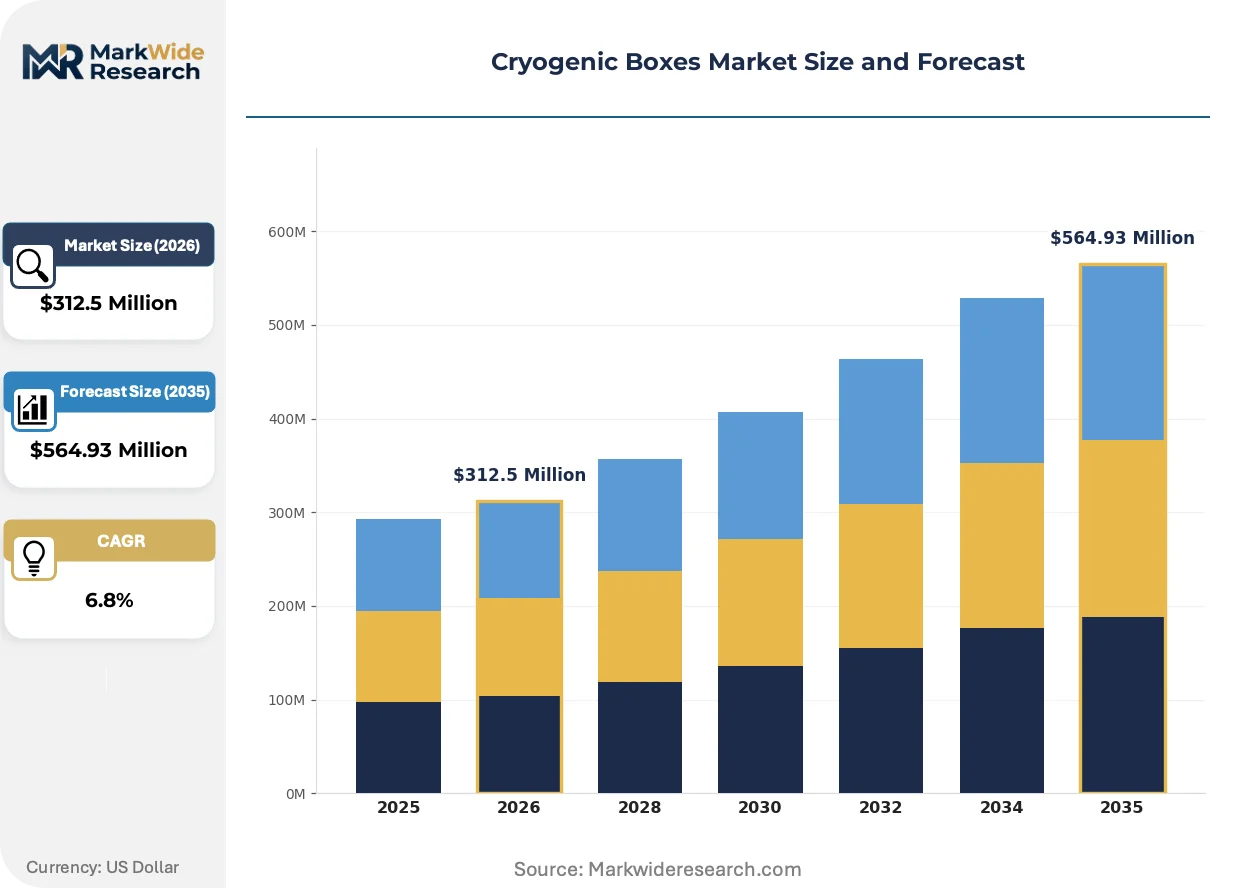
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $564.93 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transport Cryogenic Boxes, Storage Cryogenic Boxes, Laboratory Cryogenic Boxes, Custom Cryogenic Boxes Material: Stainless Steel, Aluminum, Polyurethane, Composite Materials End User: Healthcare Institutions, Research Laboratories, Pharmaceutical Companies, Aerospace Size: Small, Medium, Large, Extra Large |
| Companies Covered | Thermo Fisher Scientific Inc., Corning Incorporated, Tarsons Products Private Limited, BIOLOGIX GROUP LTD, AHN Biotechnologie GmbH, Abdos Labtech Pvt. Ltd., Heathrow Scientific, Merck KGaA, Cole-Parmer Instrument Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cryogenic Boxes Market Strategic Shifts
Material science convergence and regulatory disclosure mandates are reconfiguring competitive advantage around thermal performance documentation and supply chain traceability rather than unit cost alone.
Glass-reinforced composite laminates are absorbing transport weight reduction requirements without sacrificing thermal retention in pharmaceutical distribution networks. Cell therapy logistics providers are specifying these configurations for international air freight lanes where every kilogram carries penalty tariffs. The technology is absorbing premium positioning previously held by aluminum honeycomb constructions.
REACH substance of very high concern screening is forcing reformulation of legacy polyurethane foam blowing agents across European manufacturing footprints. ECHA authorization lists now cover precursor chemicals used in cryogenic insulation cores, compelling suppliers to certify alternative molecular structures. German pharmaceutical corridor buyers are prioritizing boxes with full material disclosure documentation to preempt downstream compliance liability.
Integrated sensor telemetry is displacing manual temperature logging in high-value specimen transport contracts. Biorepository operators now require continuous data streams as a baseline qualification criterion, unbundling hardware procurement from validation services. This pattern is most pronounced in United States precision medicine consortia where FDA guidance on cryopreservation documentation has hardened evidentiary standards.
Cryogenic Boxes Market Segmentation
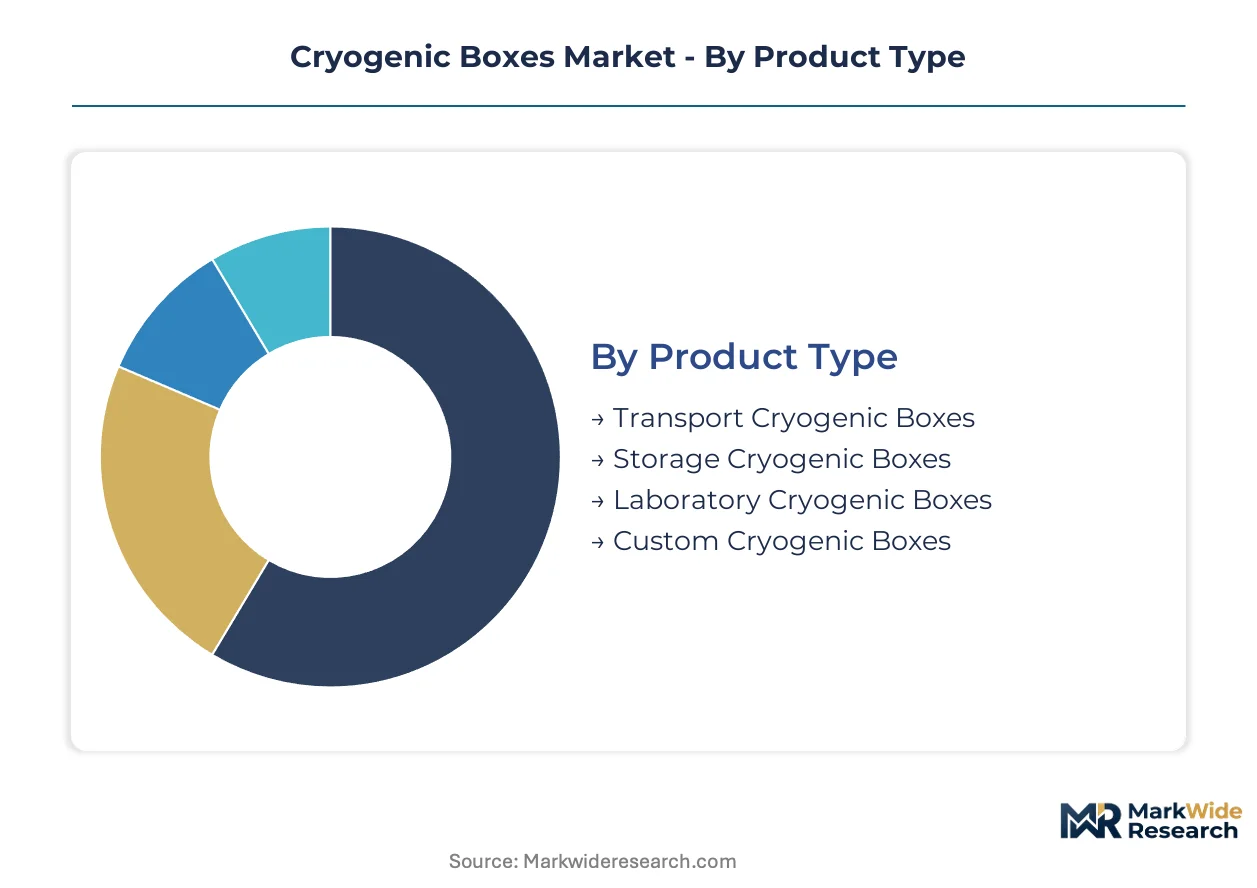
Material specification and end-use validation requirements fragment procurement criteria across biobanking, cell therapy, and aerospace applications. Each segment carries distinct thermal performance thresholds and regulatory documentation burdens that reshape vendor qualification frameworks.
Product Type:
Vacuum-insulation technology and rack geometry customization define competitive differentiation across functional deployment scenarios.
- Transport Cryogenic Boxes:Foam-filled or vacuum-panel enclosures engineered for vaccine distribution and cell therapy logistics where temperature excursion risks trigger chain-of-custody penalties. Pharmaceutical companies in Germany's manufacturing corridor specify these for EMA-validated cold-chain lanes.
- Storage Cryogenic Boxes:Static containment systems with liquid nitrogen immersion ratings for biorepository long-term specimen archiving. United States precision medicine consortia drive specification tightening through FDA cryopreservation guidance.
- Laboratory Cryogenic Boxes:Benchtop units for research protocols requiring frequent access cycles. Research laboratories dominate procurement volume.
- Custom Cryogenic Boxes:Validated rack geometries for autologous therapy manufacturing. Cell therapy producers require configurations standard boxes cannot accommodate.
Mature deployment sits with laboratory cryogenic boxes. Newer deployment is concentrated in custom cryogenic boxes.
Material:
Cost tier and weight-performance tradeoffs redirect sourcing strategies as REACH compliance escalates formulation expenses.
- Stainless Steel:Weld-sealed vacuum chambers with highest durability for liquid nitrogen immersion. Nickel and chromium price volatility compress margins on these premium variants.
- Aluminum:Honeycomb constructions historically dominant in pharmaceutical air freight. German and Austrian mill capacity constraints now limit scaling.
- Polyurethane:Molded foam cores redirecting European procurement as F-Gas Regulation phases down hydrofluorocarbon alternatives. ECHA authorization timelines extend development cycles.
- Composite Materials:Glass-reinforced laminates absorbing transport weight reduction mandates without thermal retention sacrifice. These configurations are climbing the fastest across international cell therapy logistics.
Volume concentration remains with stainless steel. Margin expansion is shifting toward composite materials.
End User:
Customer type determines validation depth and certification requirements that gate vendor participation.
- Healthcare Institutions:Hospital biobanks and clinical laboratories requiring ISO 13485-certified containment for diagnostic specimen preservation. FDA updated guidance pushes procurement toward validated systems.
- Research Laboratories:Academic and government facilities with standardized rack geometries and high access frequency. These buyers dominate unit volume.
- Pharmaceutical Companies:CDMOs and innovators with custom geometry needs and continuous temperature logging mandates. EMA cold-chain requirements compress their procurement cycles.
- Aerospace:Satellite propulsion testing protocols requiring portable ultra-low temperature enclosures for pre-launch thermal cycling. This segment shows steepest expansion trajectory.
Procurement scale sits with research laboratories. Specification complexity is concentrating in pharmaceutical companies.
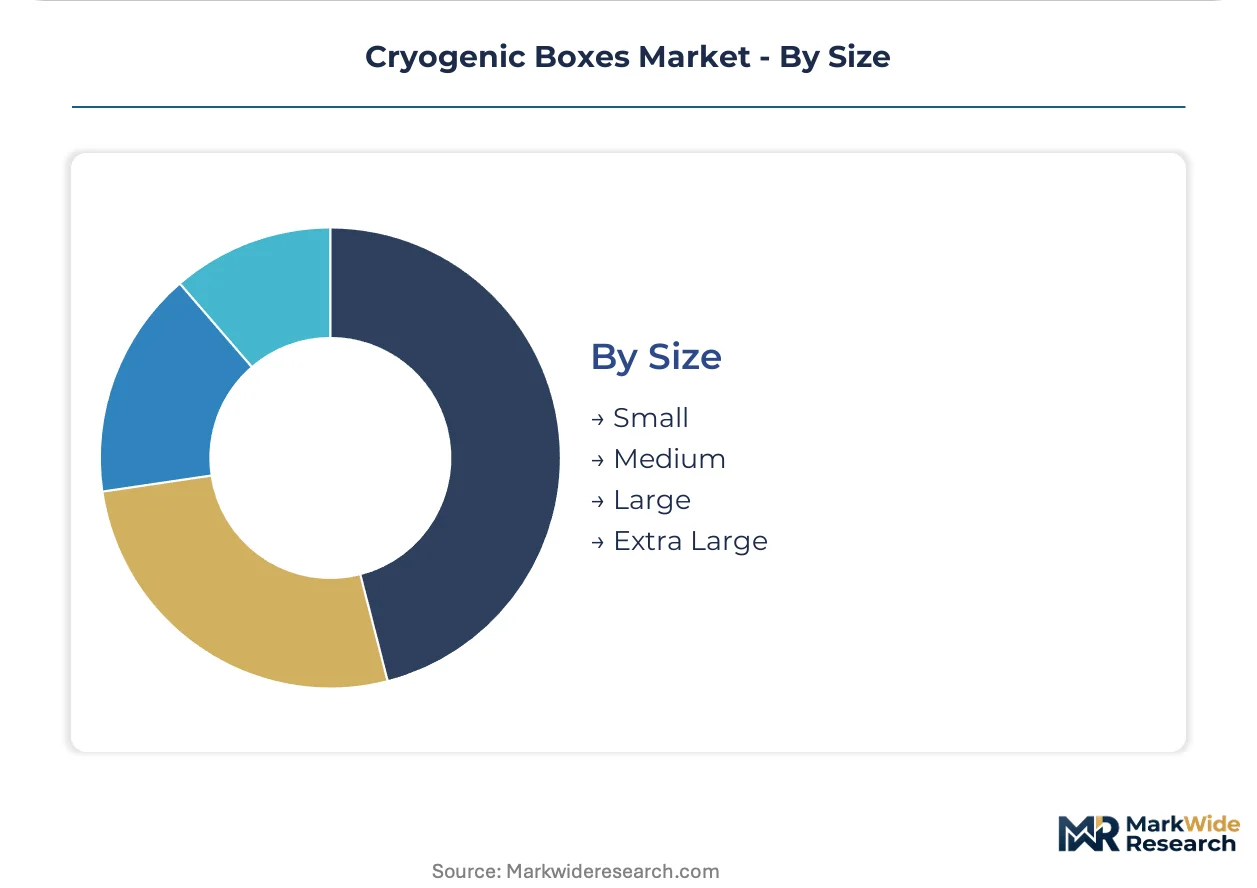
Size:
Volume tier alignment with specimen throughput and storage density requirements shapes facility capital planning.
- Small:Portable units for field collection and courier transport. Cell therapy logistics providers specify these for high-value shipments.
- Medium:Standard biorepository rack configurations. Research laboratories deploy these for routine specimen archiving.
- Large:High-capacity systems for centralized biobanking infrastructure. United States precision medicine facilities drive demand.
- Extra Large:Industrial-scale containment for pharmaceutical manufacturing and aerospace component conditioning. Custom engineering requirements dominate this tier.
Unit volume concentrates in medium sizes. Engineering intensity escalates in extra large configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized pharmaceutical manufacturing zones in Germany and precision medicine clusters in the United States concentrate cryogenic box demand through validated cold-chain infrastructure investments.
United States
Precision medicine consortia and hospital biobanks drive specification tightening for liquid nitrogen-rated containment systems. FDA cryopreservation guidance mandates validated documentation protocols for longitudinal genomic specimen archiving. The Greater Boston biotech corridor anchors procurement volume from cell therapy manufacturers requiring custom rack geometries.
Germany
Contract development and manufacturing organizations prioritize EMA-validated aluminum and composite-material boxes for pharmaceutical distribution. REACH substance authorization timelines extend development cycles for polyurethane insulation alternatives. The Rhine-Main pharmaceutical manufacturing corridor concentrates demand for vacuum-panel configurations meeting cold-chain validation requirements.
India
Contract research organizations and biopharma manufacturers scale cryogenic storage capacity under CDSCO quality mandate enforcement. Central Drugs Standard Control Organization inspections push procurement toward ISO 13485-certified containment systems. Hyderabad and Bengaluru biotech clusters drive validated storage demand from vaccine developers and cell therapy producers.
China
Biorepository infrastructure expansion and aerospace component testing protocols absorb transport and storage cryogenic boxes. National Medical Products Administration standards govern containment system qualification for clinical sample preservation. The Yangtze River Delta pharmaceutical manufacturing belt concentrates demand for stainless steel vacuum-insulated variants.
Japan
Academic research institutions and regenerative medicine developers specify laboratory cryogenic boxes with high access frequency tolerance. Pharmaceuticals and Medical Devices Agency quality system requirements filter vendor participation in healthcare procurement. The Kanto region biocluster around Tokyo anchors volume demand for benchtop containment systems.
Cryogenic Boxes Market Competitive Environment
United States producers anchor the premium-tier integrated systems segment; German specialists hold the precision-fabrication tier; Asian manufacturers compete on molded-component scale. The vendor base organizes around three strategic archetypes: diversified laboratory conglomerates with cold-chain infrastructure, specialized material-science fabricators with composite laminate expertise, and regional molding specialists with polyurethane foam core capabilities. Capacity expansion and strategic technology licensing dominate competitive moves as players address REACH compliance cost escalation and F-Gas Regulation phase-down requirements.
Within the diversified conglomerate tier, Thermo Fisher Scientific Inc. and Corning Incorporated exemplify integrated cold-chain positioning through captive distribution channels and specialized material science portfolios. BIOLOGIX GROUP LTD occupies a position among Asian-scale molding specialists competing on polyurethane component volume across research laboratory markets. These three anchors represent distinct competitive vectors: infrastructure-integrated procurement access, glass-composite thermal retention specialization, and molded-foam manufacturing scale.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Corning Incorporated |
| Tarsons Products Private Limited |
| BIOLOGIX GROUP LTD |
| AHN Biotechnologie GmbH |
| Abdos Labtech Pvt. Ltd. |
| Heathrow Scientific |
| Merck KGaA |
| Cole-Parmer Instrument Company |
| Others |
Value Chain & Pricing Dynamics
Pharmaceutical CDMO procurement concentration in Germany's Rhine-Main corridor anchors contract-based long-term offtake pricing with volume-scaled tiering. Stainless steel vacuum chamber buyers absorb nickel and chromium volatility through indexed contract adjustments, while composite-material purchasers negotiate fixed-price multi-year agreements to lock in aluminum extrusion capacity.
Pricing Analysis
Lead-time premiums compress standard pricing by fifteen to twenty percent for validated stainless steel configurations with sub-eight-week delivery windows. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 13485 certification grade and liquid nitrogen immersion rating. Cost compression in polyurethane foam cores is intensifying because ECHA authorization timelines extend alternative formulation development. Research laboratories exhibit highest price sensitivity due to grant-funded procurement cycles, whereas cell therapy manufacturers prioritize thermal performance documentation over unit cost.
Supply Chain Analysis
Stainless steel feedstock rests on German and Austrian specialty mill capacity, while aluminum honeycomb sourcing draws from Chinese and South Korean rolled metal producers. Nickel cathode supply hinges on Indonesian and Philippine mining operations, with chromium processing concentrated in South Africa and Kazakhstan. Single-source vulnerability in orbital welding technician labor pools constrains vacuum chamber fabrication scaling. Distribution runs through captive cold-chain logistics networks for pharmaceutical end users and laboratory distributor consignment for research institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where backward control over composite laminate formulation and sensor telemetry modules determines margin capture. Players are pursuing downstream integration into validation services and chain-of-custody documentation to unbundle hardware from recurring revenue streams.
For Market Incumbents: Acquire specialized orbital welding technician training programs and captive aluminum extrusion capacity in Central Europe. Consolidate position by locking in EMA-validated cold-chain partnerships before REACH compliance escalates formulation costs for polyurethane alternatives. Certification investment in ISO 13485 medical device quality systems gates hospital biobank procurement and defends against Asian molding specialists encroaching on laboratory segments. For New Entrants and Emerging Players: Aerospace component conditioning buyers remain underserved by incumbent laboratory-focused product portfolios. Penetrate satellite propulsion testing protocols with portable ultra-low temperature enclosures that standard biobanking configurations cannot accommodate. Lead with digital temperature logging integration as a bundled service to differentiate from commodity foam-filled transport boxes. For Investors and Strategic Acquirers: The window for entry favors specialized material-science fabricators with glass-reinforced composite laminate expertise and existing EMA validation relationships. Long-term viability centers on defensible thermal performance documentation capabilities rather than unit cost positioning. Watch for CDSCO enforcement acceleration in Indian contract research organizations as an inflection indicator for validated storage demand scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Composite Laminate Formulation | REACH compliance escalation makes captive material science capabilities a margin defense mechanism against ECHA authorization delays. |
| Sensor Telemetry Module Development | FDA cryopreservation guidance hardens evidentiary standards for continuous data streams in precision medicine consortia. |
| EMA Cold-Chain Validation Partnership | German pharmaceutical corridor buyers compress procurement cycles toward pre-qualified containment system suppliers. |
| Orbital Welding Technician Training Programs | Weld-seal fabrication scarcity in Central European labor markets constrains stainless steel vacuum chamber production scaling. |
| ISO 13485 Quality System Certification | Hospital biobank procurement filters exclude non-certified vendors from healthcare institution tenders. |
Study Parameters
Trade publications, ECHA substance authorization databases, and hospital procurement records formed the secondary backbone for this analysis. Primary interviews with biorepository operations directors, pharmaceutical cold-chain logistics managers, and composite materials procurement leads combined with customs data and SEC filings to validate demand assumptions. Bottom-up segment sizing and top-down macroeconomic triangulation anchored volume and value estimates across the analysis window.
Historical trendline analysis of stainless steel input costs and aluminum extrusion capacity utilization informed the projection framework. Segmentation modeling incorporated material type, end-use validation requirements, and regional regulatory cluster dimensions throughout the forecast period. CAGRs derived from fitted growth curves adjusted for REACH compliance cost pass-through and F-Gas Regulation phase-down timing.
Revisions become necessary when nickel and chromium price volatility exceeds historical bands or when dual-use export controls tighten on composite-material box shipments. Forecasts reflect assumptions about EMA validation timeline stability and CDSCO enforcement continuity. A small set of named triggers warrants ongoing watch: orbital welding labor pool contraction, ECHA authorization list expansion, and aerospace testing protocol standardization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cold Chain Packaging
North America Cold Chain Market
Cold Chain Packaging
Cold Chain Integrity and Shock Monitoring Test Devices Market
Cold Chain Packaging
Reusable Cold Chain Packaging Market
Cold Chain Packaging
Refrigeration Packaging Market
Cold Chain Packaging
Latin America Pharmaceutical Cold Chain Logistics Market
Cold Chain Packaging
Cold Chain Micro-Fulfillment Hub Networks Market
Cold Chain Packaging
Insulated Food Delivery Bags Market
Cold Chain Packaging
Global Cold Chain Tracking and Monitoring Market
Cold Chain Packaging
China Cold Chain Market
Cold Chain Packaging
Fish Boxes Market
Cold Chain Packaging
Cryogenic Capsules Market
Cold Chain Packaging
Cold Box Module Market
Cold Chain Packaging
Cryo Box Market
Cold Chain Packaging
Biopharma Cold Chain Packaging Market
Cold Chain Packaging
Cold Chain Equipment Market
Cold Chain Packaging
Europe Healthcare Cold Chain Logistics Market