
 Europe Healthcare Cold Chain Logistics Market | 2026-2036
Europe Healthcare Cold Chain Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Healthcare Cold Chain Logistics Market Insights
Platform licensing revenue from real-time temperature monitoring systems is reshaping competitive economics in European healthcare logistics. Kuehne + Nagel leverages its pharmaceutical-certified warehouse network across the Netherlands and Belgium to anchor high-value biologics contracts. DHL sustains leadership through dedicated life sciences divisions with GDP-compliant air freight corridors. Marken Ltd specializes in direct-to-patient clinical trial logistics, occupying a defensible niche in personalized medicine distribution.
Europe healthcare cold chain logistics encompasses the temperature-controlled transport and storage of pharmaceutical products, vaccines, blood derivatives, and biologics within strict ranges typically spanning minus eighty degrees Celsius to plus twenty-five degrees Celsius, utilizing validated thermal packaging, continuous data loggers, and redundant refrigeration systems to preserve molecular stability. The biologics segment commands premium logistics fees due to cryogenic requirements and limited handler certification, while courier services for direct-to-patient delivery represent the fastest-expanding delivery mode driven by decentralized clinical trials and specialty pharmacy growth. Refrigerated trucking retains volume dominance for inter-facility distribution across the continent's dense motorway network.
EMA guidelines on Good Distribution Practice, the EU Falsified Medicines Directive, and national health authority inspections collectively mandate serialized tracking, qualified equipment validation, and documented temperature excursions across all member states. These frameworks elevate compliance costs for smaller operators while creating barriers that favor providers with established quality management systems. Stakeholders must monitor the implementation of the EU AI Act's risk classification rules as automated cold chain monitoring systems face new algorithmic transparency requirements.
Market Dynamics
The EU Good Distribution Practice revision is compressing certification timelines while expanding audit scope, forcing logistics providers to rebuild quality management systems around real-time data integrity rather than retrospective documentation.
Growth Catalysts
- Cell and gene therapy commercialization:Cryogenic transport requirements for CAR-T treatments are pulling specialized cold chain capacity into Germany, Belgium, and the Netherlands.
- EMA serialization mandates:The EU Falsified Medicines Directive's track-and-trace requirements are upgrading warehouse management systems across pharmaceutical distribution networks.
- Decentralized clinical trials:Direct-to-patient delivery models are expanding courier networks into secondary European cities previously served only by hospital pharmacies.
Market Restraints
- Dry ice supply concentration:Carbon dioxide capture infrastructure clusters in northern France and the Benelux, creating geographic vulnerability for cryogenic shippers.
- Qualified equipment validation costs:EMA temperature mapping requirements demand capital outlays for thermal packaging qualification that exclude smaller freight forwarders.
- Refrigerant substitution constraints:The EU F-Gas Regulation is phasing down hydrofluorocarbon-based cooling systems before cost-competitive natural refrigerant alternatives achieve scale.
Strategic Opportunities
- Eastern European manufacturing expansion:Poland and Hungary are attracting biologics production facilities that lack adjacent cold storage infrastructure.
- AI Act algorithmic transparency:Automated cold chain monitoring systems face new compliance requirements that favor providers with established data governance frameworks.
- Reusable thermal packaging:Reverse logistics networks for qualified shipping containers are opening service revenue streams beyond single-use parcel economics.
Industry Challenges
- GDP auditor certification scarcity:Qualified persons for pharmaceutical logistics verification are concentrated in Germany and the UK, creating inspection bottlenecks for southern European facilities.
- Legacy warehouse management integration:Serialization data streams from EMA-compliant track-and-trace systems require middleware development that delays real-time visibility deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Healthcare Cold Chain Logistics Market |
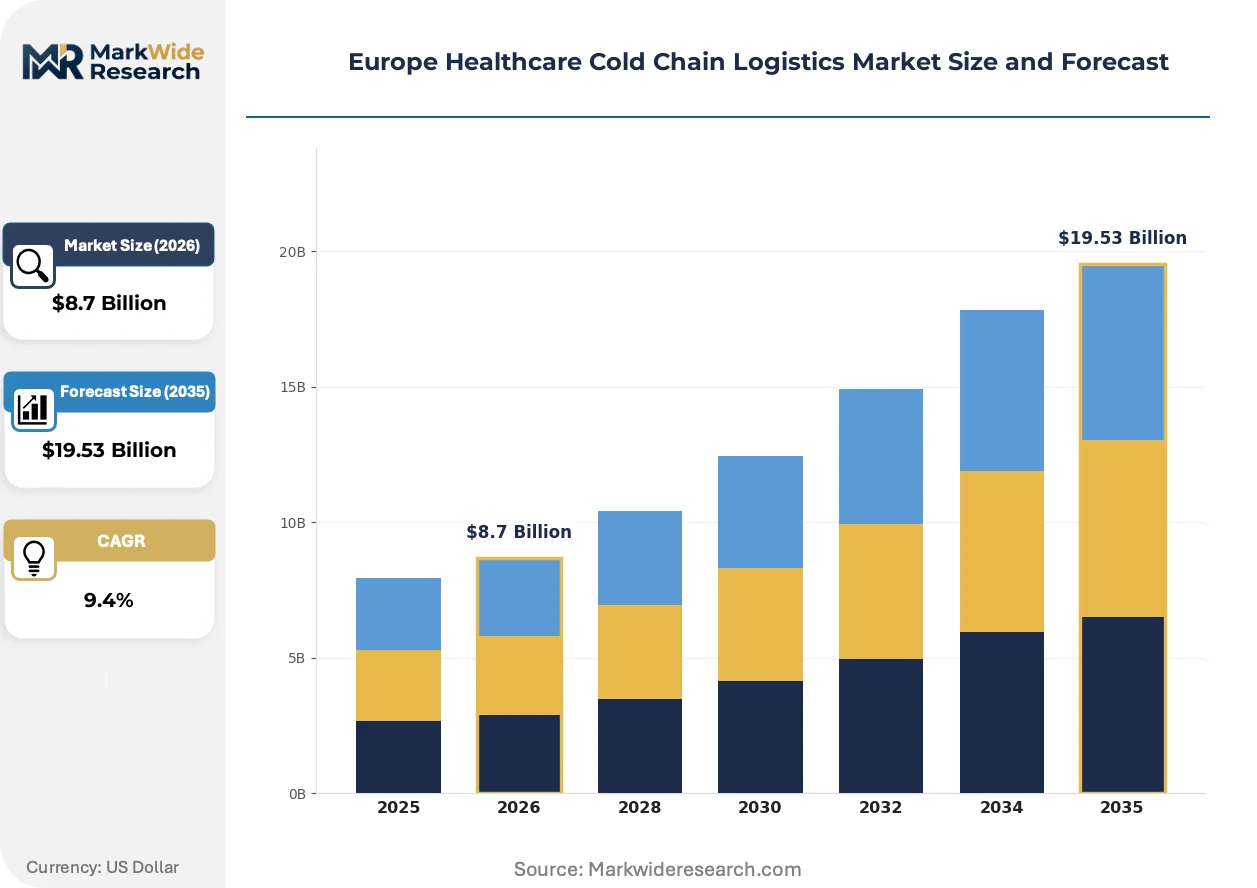
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceuticals, Vaccines, Blood Products, Biologics Delivery Mode: Refrigerated Trucks, Air Freight, Sea Freight, Courier Services Temperature Range: Ambient, Chilled, Frozen, Deep Frozen End User: Hospitals, Clinics, Research Laboratories, Pharmacies |
| Companies Covered | Marken Ltd, PrimaFrio, DB Schenker, Alloga, Biocair, DHL, Carrier Transicold, Cavalier Logistics, Kuehne + Nagel, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Healthcare Cold Chain Logistics Market Trends and Innovations
Digital validation protocols and autonomous monitoring systems are displacing paper-based temperature documentation across European pharmaceutical corridors. Logistics providers are racing to embed compliance automation into operational workflows.
Blockchain-enabled temperature logging is migrating from pilot programs to contractual requirements. Large biopharma manufacturers in Germany and Switzerland are mandating distributed ledger verification for international shipments. This migration from traditional data logger downloads to immutable cloud records is compressing dispute resolution timelines and reducing insurance premiums for high-value biologics.
EMA guidelines on computerized system validation are tightening software qualification requirements for automated monitoring platforms. Warehouse operators must now document algorithmic decision logic for temperature excursion alerts. Cold storage facilities in Belgium and the Netherlands are responding by segregating AI-driven environmental controls from legacy building management systems to isolate validation scope.
Hospital procurement departments are consolidating specialty pharmacy distribution contracts under single-source logistics agreements. Academic medical centers in France and Italy are replacing fragmented courier relationships with integrated cold chain partnerships that bundle clinical trial logistics, commercial drug distribution, and direct-to-patient services. This consolidation is visible most acutely in oncology therapeutic categories where temperature sensitivity intersects with high patient acuity.
Europe Healthcare Cold Chain Logistics Market Segmentation
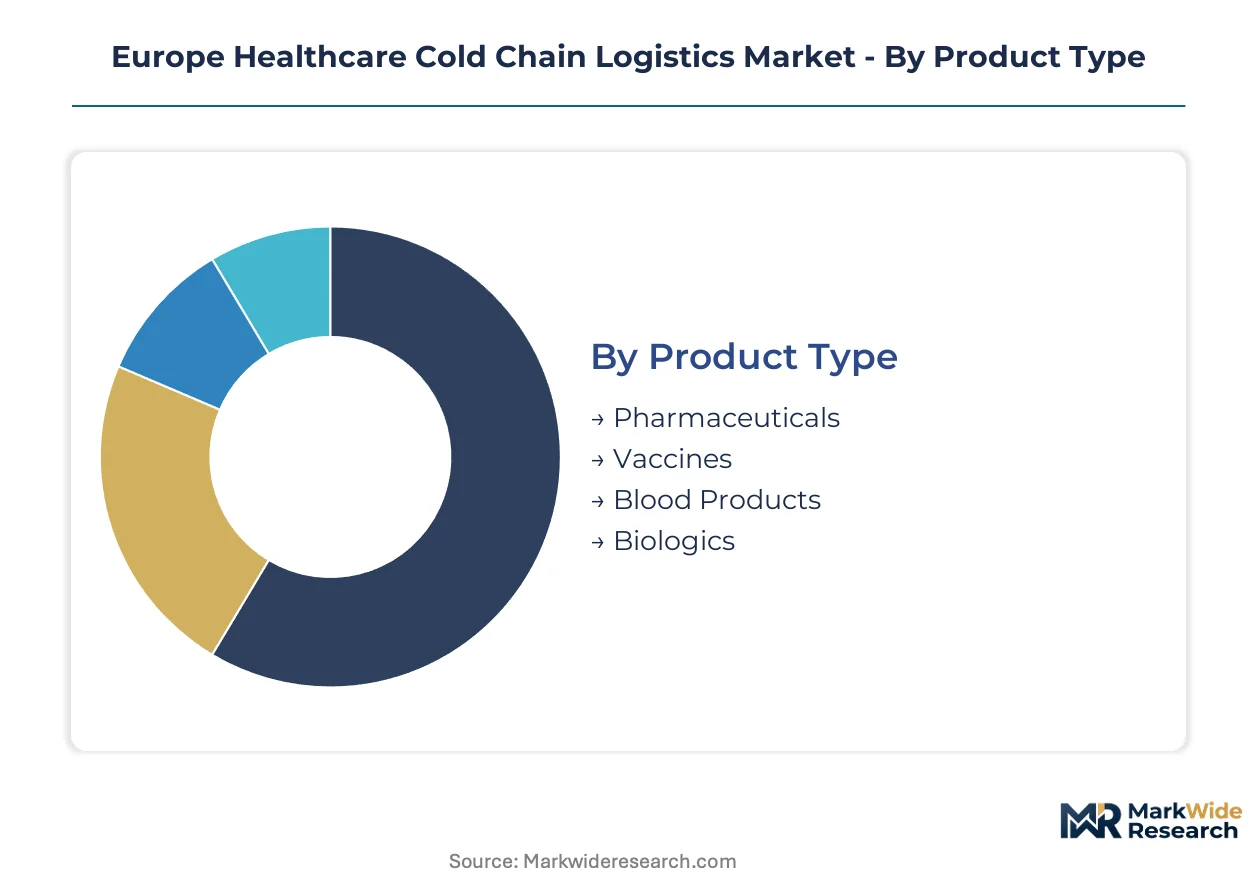
Healthcare cold chain logistics in Europe demands granular segmentation because temperature requirements, regulatory intensity, and handler certification vary dramatically across product categories. Each segment commands distinct infrastructure investments and compliance protocols that reshape competitive economics for logistics providers.
Product Type:
Temperature sensitivity spans from standard refrigerated stability to cryogenic preservation below minus sixty degrees Celsius, creating tiered service requirements across the pharmaceutical value chain.
- Biologics:Monoclonal antibodies, recombinant proteins, and gene therapies require uninterrupted cryogenic or ultra-low temperature chains with redundant liquid nitrogen backup systems. German biotech clusters around Munich and Heidelberg are pulling specialized capacity from Benelux providers as domestic manufacturing expands.
- Vaccines:mRNA formulations and viral vector products need precision cold chains between minus seventy and plus eight degrees Celsius with strict excursion protocols. Belgian fill-finish facilities serving the European market are driving demand for validated thermal packaging with embedded data loggers.
- Pharmaceuticals:Small-molecule drugs and generic medicines typically require standard two-to-eight-degree Celsius refrigerated transport across Europe's dense motorway network.
- Blood Products:Plasma derivatives and cellular components demand continuous temperature monitoring with EMA-compliant documentation for hospital transfusion services.
The dominant share belongs to Pharmaceuticals, while Biologics is closing the gap fastest.
Delivery Mode:
Transport economics hinge on speed-to-patient requirements versus batch shipment scale, with courier networks expanding fastest where decentralized care models disrupt traditional hospital-centric distribution.
- Courier Services:Direct-to-patient delivery for clinical trials and specialty pharmacy prescriptions utilizes validated parcel shippers with real-time GPS tracking. France and Italy are seeing courier network densification as academic medical centers consolidate logistics contracts under single-source agreements.
- Refrigerated Trucks:Full-truckload and less-than-truckload movements dominate inter-facility distribution, leveraging Europe's cross-border motorway infrastructure for pharmaceutical hub-to-hospital flows.
- Air Freight:GDP-compliant temperature-controlled air corridors connect European manufacturing sites to global markets, with dedicated life sciences terminals at Amsterdam Schiphol and Frankfurt airports.
- Sea Freight:Reefer container movements serve lower-value pharmaceutical bulk shipments where extended transit times remain acceptable for stable formulations.
Refrigerated Trucks retain volume leadership, though Courier Services are expanding most quickly.
Temperature Range:
Equipment validation costs escalate nonlinearly with cooling depth, fragmenting provider capabilities across thermal tiers and concentrating cryogenic expertise among certified specialists.
- Deep Frozen:Minus sixty to minus eighty degrees Celsius chains for cell therapies and certain viral vectors require liquid nitrogen vapor phase shippers with limited qualified handler pools. The EU F-Gas Regulation is accelerating refrigerant substitution investments in this tier.
- Frozen:Minus twenty to minus forty degrees Celsius stability for plasma proteins and some vaccines utilizes mechanical refrigeration with validated cold storage warehousing.
- Chilled:Two to eight degrees Celsius represents the most common pharmaceutical transport requirement, with extensive qualified packaging options and established handler training protocols.
- Ambient:Fifteen to twenty-five degrees Celsius controlled room temperature for stable small-molecule tablets requires protection against heat excursions during summer transit.
Chilled dominates shipment volumes, yet Deep Frozen commands the steepest expansion trajectory.
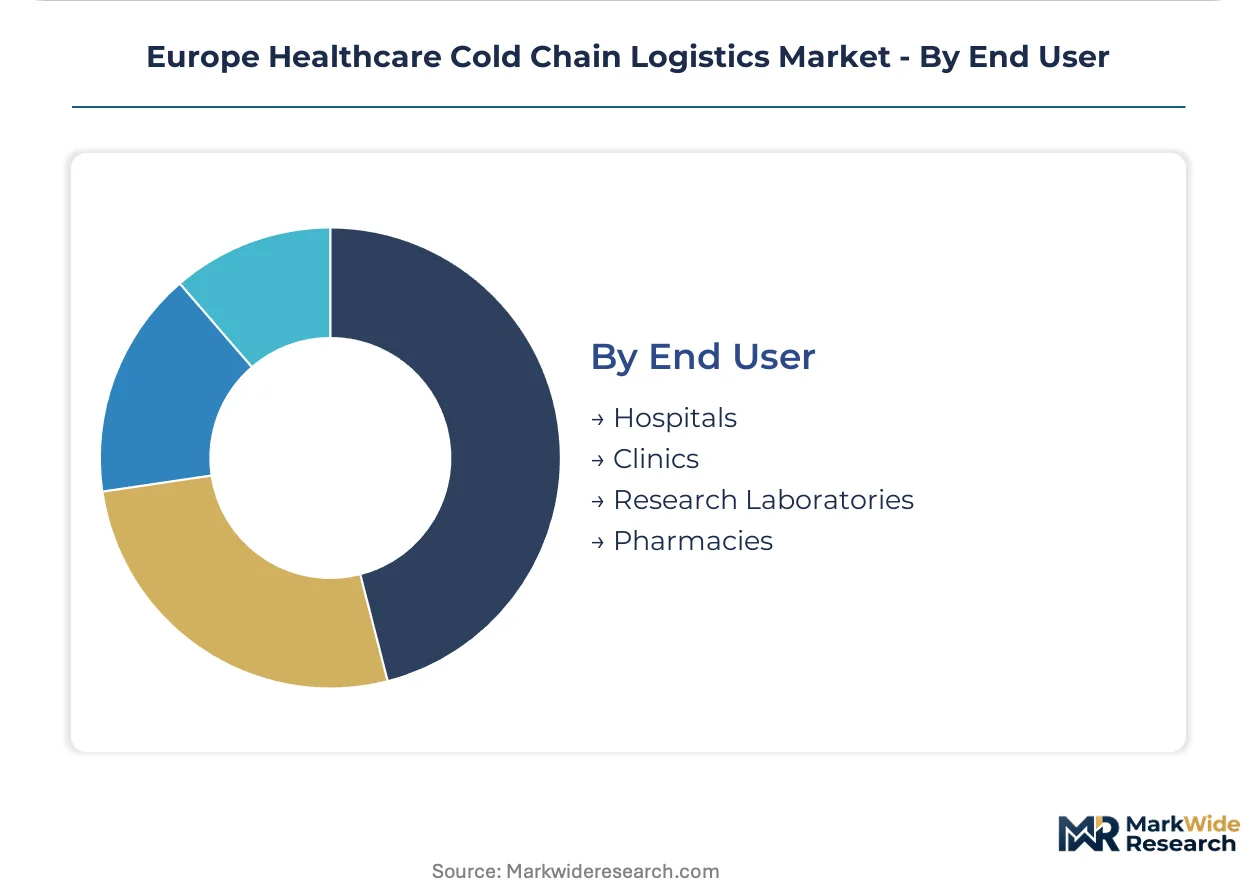
End User:
Procurement centralization varies sharply across customer types, with hospital systems consolidating vendor relationships while research laboratories maintain fragmented, protocol-specific logistics requirements.
- Hospitals:Academic medical centers in Germany, France, and Italy are bundling clinical trial logistics, commercial distribution, and direct-to-patient services under integrated cold chain partnerships, displacing fragmented courier relationships.
- Research Laboratories:Cell and gene therapy development sites require specimen transport with chain-of-custody documentation and rapid recovery protocols for temperature excursions.
- Pharmacies:Hospital and specialty pharmacy dispensaries need just-in-time inventory replenishment with serialized tracking under the EU Falsified Medicines Directive.
- Clinics:Outpatient infusion centers and dialysis facilities receive smaller shipment quantities with higher frequency, favoring regional distribution hubs over central warehouse models.
Hospitals anchor demand volume, while Research Laboratories are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across European healthcare logistics buyers. Hospital procurement departments in Germany and Switzerland negotiate with limited sensitivity to freight costs given patient acuity and product value. Academic medical centers in southern Europe face tighter budget constraints and demonstrate greater willingness to switch providers on rate differentials.
Germany
Pharmaceutical manufacturing clusters around Frankfurt and Munich drive specialized cold storage investment. The country's national pharmaceutical regulator enforces GDP compliance through unannounced facility inspections. Heidelberg's cell therapy production sites are pulling cryogenic logistics capacity from neighboring Benelux providers.
Netherlands
Amsterdam Schiphol's dedicated life sciences cargo terminal anchors temperature-controlled air freight corridors. The EU Falsified Medicines Directive mandates serialized tracking for all pharmaceutical imports. Rotterdam's port reefer infrastructure serves lower-value bulk pharmaceutical shipments with established GDP-compliant handling protocols.
Belgium
Fill-finish facilities near Brussels generate demand for validated thermal packaging with embedded data loggers. EMA guidelines on computerized system validation are tightening software qualification requirements for warehouse operators. The Antwerp logistics corridor concentrates European vaccine distribution capacity with redundant liquid nitrogen backup systems.
France
Academic medical centers in Paris and Lyon are consolidating fragmented courier relationships under single-source cold chain partnerships. ANSM inspection protocols for pharmaceutical logistics facilities exceed baseline EU requirements. The Île-de-France region is seeing courier network densification as decentralized clinical trials expand direct-to-patient delivery.
United Kingdom
Post-Brexit customs complexity has redirected some biologics flows through continental hubs while preserving specialized clinical trial logistics demand. MHRA alignment with EMA GDP standards maintains regulatory continuity for cross-border shipments. London's research hospital concentration sustains premium pricing for specimen transport with chain-of-custody documentation.
Europe Healthcare Cold Chain Logistics Market Competitive Landscape
Capability concentration sits with specialized pharmaceutical-certified providers; scale advantage sits with diversified freight networks with dedicated life sciences divisions. The market structures around three tiers: global integrators with GDP-compliant air corridors, regional specialists with certified warehouse networks, and niche operators focused on direct-to-patient clinical trial logistics. Dominant competitive moves include strategic partnerships with biopharma manufacturers for integrated distribution contracts and technology licensing for real-time temperature monitoring platforms.
Within the specialized clinical trial tier, Marken Ltd exemplifies the direct-to-patient logistics archetype. Among diversified global integrators, DHL and Kuehne + Nagel occupy positions that bridge pharmaceutical certification with network scale. DB Schenker represents the European regional specialist archetype with established GDP-compliant ground distribution infrastructure.
| Leading Market Players |
|---|
| Marken Ltd |
| PrimaFrio |
| DB Schenker |
| Alloga |
| Biocair |
| DHL |
| Carrier Transicold |
| Cavalier Logistics |
| Kuehne + Nagel |
| Others |
Pricing and Supply Chain Analysis
Dry ice supply concentration in northern France and the Benelux anchors margin pools downstream with cryogenic logistics providers, while EMA temperature mapping requirements compress returns for uncertified handlers. Carbon dioxide capture infrastructure scarcity feeds directly into pricing power for qualified cold chain operators serving cell therapy manufacturers.
Pricing Analysis
After-sales revenue from reusable thermal packaging reverse logistics and extended GDP compliance service contracts drives lifetime value for specialized European providers. Three-tier pricing structure across GDP-certified premium, standard freight, and economy ambient tiers reflects handler certification grade and real-time monitoring capabilities. Pricing pressure stems from qualified equipment validation costs excluding smaller freight forwarders from cryogenic tiers. Hospital procurement departments in Germany and Switzerland demonstrate limited price sensitivity, while academic medical centers in southern Europe switch providers on rate differentials.
Supply Chain Analysis
Supplier-financing facilities with extended payment terms are emerging as competitive tools for logistics providers securing biopharma manufacturing contracts. Dry ice production concentrates in France, Belgium, and the Netherlands, while liquid nitrogen vapor phase equipment draws from German and Swiss specialized fabricators. Carbon dioxide capture infrastructure and qualified handler certification pools represent single-source vulnerabilities. Distribution runs through pharmaceutical-certified warehouse networks in the Benelux and Germany, with courier densification into secondary European cities accelerating.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified GDP auditor scarcity constrains quality management system expansion, creating a capability bottleneck that favors incumbents with established inspection relationships across Germany and the UK.
For Market Incumbents: Insulate cryogenic logistics margins by securing exclusive liquid nitrogen supply agreements with northern French carbon dioxide capture facilities before F-Gas Regulation phase-down accelerates. Pursue backward integration into reusable thermal packaging fabrication to capture reverse logistics revenue streams and lock out emerging competitors from qualified container pools. For New Entrants and Emerging Players: Eastern European biologics manufacturing clusters in Poland and Hungary represent the most penetrable entry point, as these production facilities lack adjacent cold storage infrastructure and GDP-certified warehouse networks. Target direct-to-patient courier services for decentralized clinical trials in secondary French and Italian cities, where academic medical centers are consolidating fragmented logistics relationships under single-source agreements. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional pharmaceutical logistics specialists with certified warehouse networks but limited technology platforms. Long-term viability hinges on AI-driven monitoring system deployment and EU AI Act compliance infrastructure. Watch EMA serialization mandate implementation timelines as the signal for consolidation acceleration among mid-tier providers lacking middleware development capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| GDP Certification Expansion | EMA audit readiness separates qualified providers from commodity freight forwarders in biologics distribution. |
| AI-Driven Monitoring Platform Deployment | Algorithmic transparency requirements under EU AI Act favor providers with established data governance frameworks. |
| Reusable Thermal Packaging Network Buildout | Reverse logistics for qualified containers opens service revenue beyond single-use parcel economics. |
| Eastern European Hub Establishment | Poland and Hungary biologics manufacturing lacks adjacent cold storage, creating first-mover infrastructure opportunities. |
| Direct-to-Patient Courier Densification | Decentralized clinical trials in France and Italy consolidate fragmented hospital pharmacy relationships. |
Research Methodology
Initial hypotheses were tested against primary input from pharmaceutical logistics operations directors, EMA-qualified GDP auditors, biopharma supply chain managers, and hospital procurement officers and refined through secondary validation. Regulatory filing databases including EMA inspection records, EU Falsified Medicines Directive implementation reports, and national health authority enforcement actions anchored top-down market sizing. Trade flow data from pharmaceutical reefer movements and cold storage capacity registries provided volume triangulation against bottom-up segment builds.
Demand-supply-balance framing structured the analytical approach across the projection horizon. Segmentation dimensions modeled include product temperature sensitivity tier, delivery mode economics, end-user procurement centralization patterns, and regional regulatory cluster stringency. CAGRs were derived from segment-level growth drivers cross-referenced with biologics manufacturing capacity expansion pipelines and cell therapy commercialization timelines.
Macroeconomic conditions sit as an overlay; deviation in energy costs affecting dry ice production, carbon credit pricing under EU ETS, and pharmaceutical R&D investment cycles would shift the trajectory. Forecasts reflect documented assumptions about EMA GDP revision implementation pace and EU AI Act enforcement intensity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cold Chain Packaging
Cold Chain Micro-Fulfillment Hub Networks Market
Cold Chain Packaging
North America Cold Chain Market
Cold Chain Packaging
Cold Chain Temperature Monitoring Market
Cold Chain Packaging
Biopharma Cold Chain Packaging Market
Cold Chain Packaging
China Cold Chain Market
Cold Chain Packaging
Latin America Pharmaceutical Cold Chain Logistics Market
Cold Chain Packaging
Pharmaceutical Cold Chain Packaging Market
Cold Chain Packaging
Cryogenic Boxes Market
Cold Chain Packaging
Cold Box Module Market
Cold Chain Packaging
North America Passive Temperature Controlled Packaging Market
Cold Chain Packaging
Europe Cold Chain Tracking and Monitoring Market
Cold Chain Packaging
Middle East and Africa Frozen Food Packaging Market
Cold Chain Packaging
Cryo Box Market
Cold Chain Packaging
Ice Boxes Market
Cold Chain Packaging
Insulated Food Delivery Bags Market
Cold Chain Packaging
Cold Chain Packaging Pooling and Reverse Logistics Services Market