
 Insulated Food Delivery Bags Market | 2026-2036
Insulated Food Delivery Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Insulated Food Delivery Bags Market Foresight
Modular thermal delivery bags with detachable insulation panels is consolidating buyer preference across restaurant chains and third-party logistics fleets. Cambro Manufacturing leverages its commercial kitchen heritage to anchor institutional catering contracts. Packir competes through specialized last-mile configurations for Asian delivery platforms. Huhtamaki extends its food packaging portfolio into insulated formats for European quick-service restaurants.
Insulated food delivery bags are fabricated from multi-layer constructions typically pairing an outer shell of polyester or nylon with internal insulation foam or reflective metallized films, engineered to maintain food temperatures between 140°F and 165°F for 45-90 minutes during transport. Soft bags dominate volume due to foldability and driver convenience, while hard cases command premium positioning in pharmaceutical-adjacent meal programs where temperature integrity is non-negotiable. Thermal delivery bags represent the fastest-growing configuration as delivery services expand into grocery and alcohol categories requiring extended cold-chain performance. Capacity segmentation clusters around 10-15 liter formats for single-order restaurant delivery, with 20+ liter units gaining traction in catering and bulk grocery channels.
FDA food-contact material regulations govern insulation foam and interior lining substrates in the United States, while REACH compliance in Europe restricts certain flame retardants and phthalates used in nylon and polypropylene components. The EU F-Gas Regulation indirectly shapes insulation material selection by pressuring manufacturers away from hydrofluorocarbon-based foam toward vacuum-insulated panels or aerogel alternatives. Stakeholders must monitor evolving extended producer responsibility frameworks in California and the EU, which will likely impose recovery and recycling obligations on thermal packaging fleets within the forecast horizon.
Market Dynamics
Modular thermal delivery bags with detachable insulation panels are consolidating buyer preference across restaurant chains and third-party logistics fleets. Cloud kitchen operators across Southeast Asia are scaling thermal packaging procurement as food delivery platforms expand into secondary cities.
Growth Catalysts
- EU Single-Use Plastics Directive:This regulatory pressure is forcing manufacturers toward reusable polyester and recycled nylon substrates, accelerating substrate innovation cycles.
- Gig-economy delivery fleet expansion:Vietnam and Indonesia are experiencing concentrated demand multiplication as platform logistics networks penetrate secondary urban centers.
- Vacuum-insulated panel technology:Advanced thermal barrier materials are extending cold-chain performance windows, enabling entry into grocery and alcohol delivery categories.
Market Restraints
- REACH compliance costs:European chemical restrictions on flame retardants and phthalates in nylon and polypropylene components inflate raw material qualification expenses.
- Foam insulation supply concentration:Hydrofluorocarbon-based thermal barriers face phase-out pressure under EU F-Gas Regulation, constraining legacy supplier options.
- Extended producer responsibility frameworks:California and EU recovery and recycling obligations are approaching imposition, threatening fleet operator cost structures.
Strategic Opportunities
- Pharmaceutical-adjacent meal programs:Hard-case thermal containers command premium positioning where temperature integrity is non-negotiable, opening high-margin verticals.
- Indonesian secondary city penetration:Underpenetrated urban logistics networks present first-mover advantages for localized thermal packaging procurement.
- Aerogel insulation convergence:Combining nanostructured thermal barriers with flexible bag formats enables ultra-lightweight extended-duration performance.
Industry Challenges
- Thermal engineering talent scarcity:Cross-functional expertise combining materials science and food safety compliance remains concentrated among specialized consultancies.
- FDA food-contact certification timelines:Multi-month approval cycles for insulation foam and interior lining substrates delay product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insulated Food Delivery Bags Market |
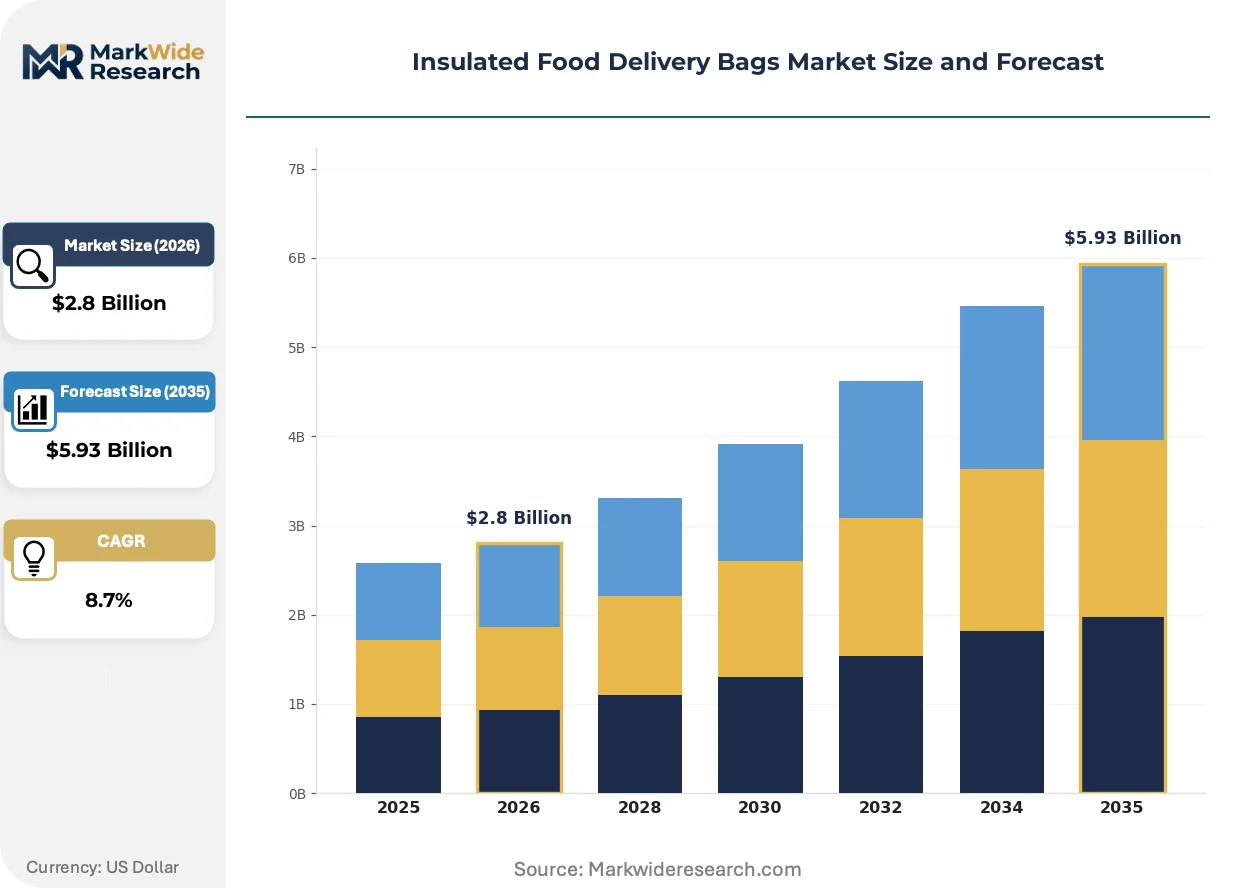
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soft Bags, Hard Cases, Thermal Delivery Bags, Coolers Material: Polyester, Nylon, Polypropylene, Insulation Foam Capacity: 5-10 Liters, 10-15 Liters, 15-20 Liters, 20+ Liters End User: Restaurants, Catering Services, Grocery Stores, Delivery Services |
| Companies Covered | Grubhub Gear, Packir, Cambro Manufacturing, Delivery Bags USA, American Aerogel, Huhtamaki, Zojirushi America Corporation, Carlisle FoodService Products, Thermos LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insulated Food Delivery Bags Market Shifts & Advancements
Active material substitution and regulatory compliance automation are reshaping competitive positioning in thermal packaging fabrication. Delivery platform procurement specifications are tightening performance thresholds while sustainability mandates accelerate substrate turnover.
Phase-change material integration is automating temperature maintenance in last-mile configurations. European quick-service restaurants are adopting these smart thermal buffers at accelerated procurement cycles. The technology is automating compliance with stricter holding-time specifications without driver intervention.
REACH restrictions on flame retardants and phthalates are eliminating legacy nylon formulations from EU-bound production lines. Manufacturers are requalifying polypropylene alternatives under compressed timelines. Vacuum-insulated panel adoption is concentrating in pharmaceutical-adjacent meal programs where F-Gas Regulation pressure is most acute.
Platform-direct procurement is compressing distributor margins across Asian delivery networks. Restaurant chains are negotiating master service agreements with thermal bag fabricators, disintermediating traditional packaging distributors. Vietnam and Indonesia exhibit the most visible channel consolidation as gig-economy fleet operators centralize specification authority.
Insulated Food Delivery Bags Market Segmentation
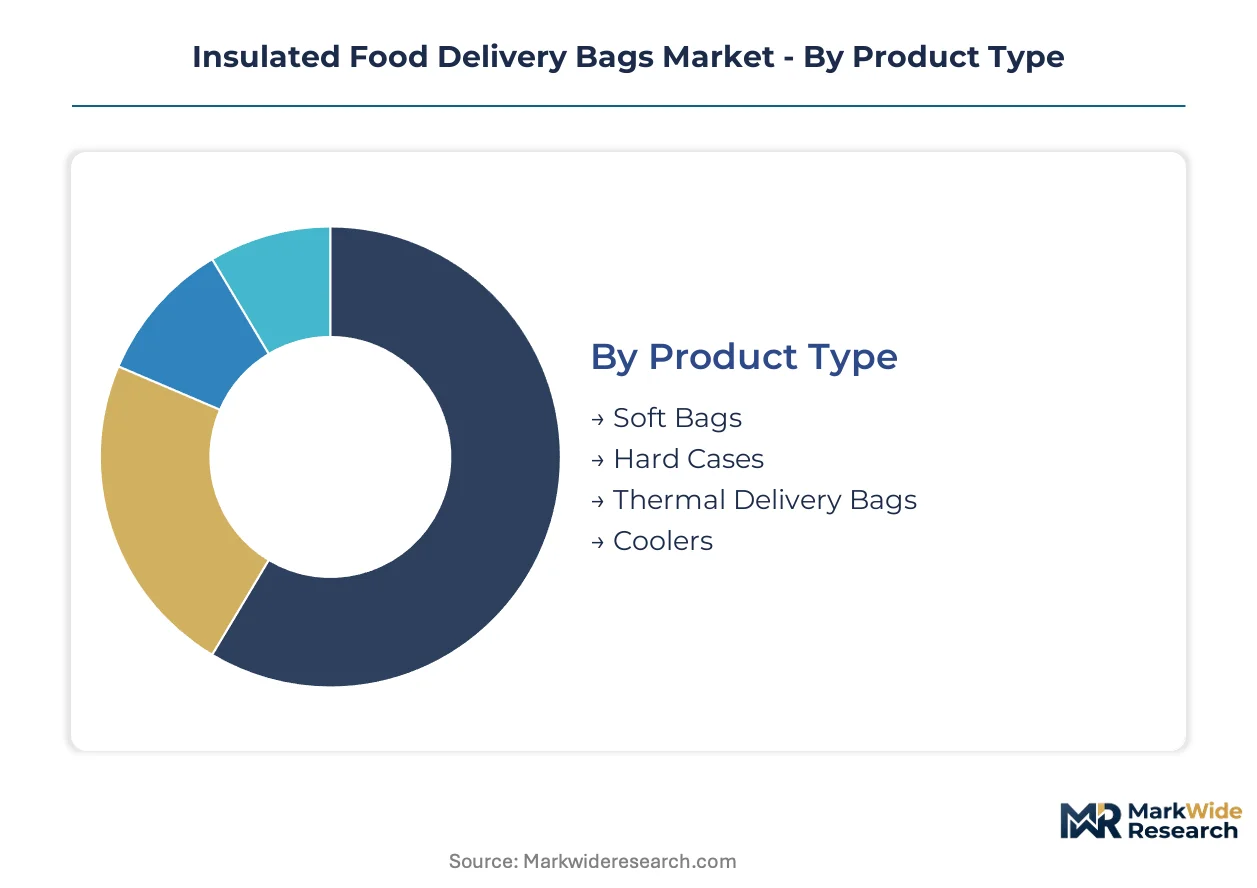
Segmentation in insulated food delivery bags reveals distinct performance requirements across thermal retention duration, payload flexibility, and regulatory compliance. Each category maps directly to operational constraints faced by cloud kitchen operators, third-party logistics fleets, and institutional foodservice providers.
Product Type:
Soft bags function as standalone thermal barriers for gig-economy drivers requiring foldable storage between deliveries, while hard cases embed into pharmaceutical-adjacent meal programs where temperature integrity cannot degrade.
- Soft Bags:Multi-layer polyester or nylon shells with internal foam insulation achieve 45-90 minute thermal maintenance. Demand clusters in Vietnam and Indonesia where delivery platforms multiply gig-fleet density fastest. Foldability prioritizes driver convenience over extended-duration performance.
- Thermal Delivery Bags:Vacuum-insulated panel integration extends cold-chain windows for grocery and alcohol categories. Cloud kitchen operators across Southeast Asia scale procurement as platforms penetrate secondary cities. F-Gas Regulation pressure accelerates substrate migration from hydrofluorocarbon foam.
- Hard Cases:Rigid polypropylene shells with phase-change material buffers serve institutional catering contracts. REACH compliance restricts legacy flame retardant formulations.
- Coolers:Expanded polystyrene or polyurethane core constructions target bulk beverage and frozen food transport. FDA food-contact certification governs interior lining substrates.
Volume placements concentrate in Soft Bags; the faster expansion belongs to Thermal Delivery Bags.
Material:
Substrate selection balances thermal performance against EU Single-Use Plastics Directive mandates, with cost tiers separating commodity synthetics from advanced barrier technologies.
- Polyester:Recycled PET woven shells dominate soft bag fabrication. Extended producer responsibility frameworks in California and the EU threaten fleet operator cost structures through impending recovery obligations.
- Insulation Foam:Polyurethane and expanded polystyrene cores provide compressible thermal mass. Hydrofluorocarbon-based variants face phase-out pressure under EU F-Gas Regulation, constraining legacy supplier options.
- Nylon:High-denier woven substrates resist abrasion in last-mile configurations. REACH restrictions eliminate formulations containing restricted phthalates and flame retardants from EU-bound production.
- Polypropylene:Injection-molded hard case shells and non-woven interior linings. Manufacturers requalify alternatives under compressed timelines as REACH compliance costs inflate.
Procurement volume tilts toward Polyester; steepest expansion trajectory tracks Insulation Foam as aerogel and vacuum-panel alternatives penetrate.
Capacity:
Format sizing aligns with order aggregation patterns—single-item restaurant delivery versus bulk catering and grocery consolidation.
- 10-15 Liters:Standard single-order restaurant delivery format. Platform-direct procurement across Asian networks compresses distributor margins.
- 20+ Liters:Catering and bulk grocery channel configurations. Restaurant chains negotiate master service agreements disintermediating traditional packaging distributors.
- 5-10 Liters:Compact formats for beverage-only or dessert-specialized delivery. Limited penetration outside premium quick-service segments.
- 15-20 Liters:Mid-capacity bridging single-order and small-catering use. Modest share as operators prefer polarized sizing.
Placement density peaks at 10-15 Liters; 20+ Liters climbs fastest as grocery and alcohol delivery categories mature.
End User:
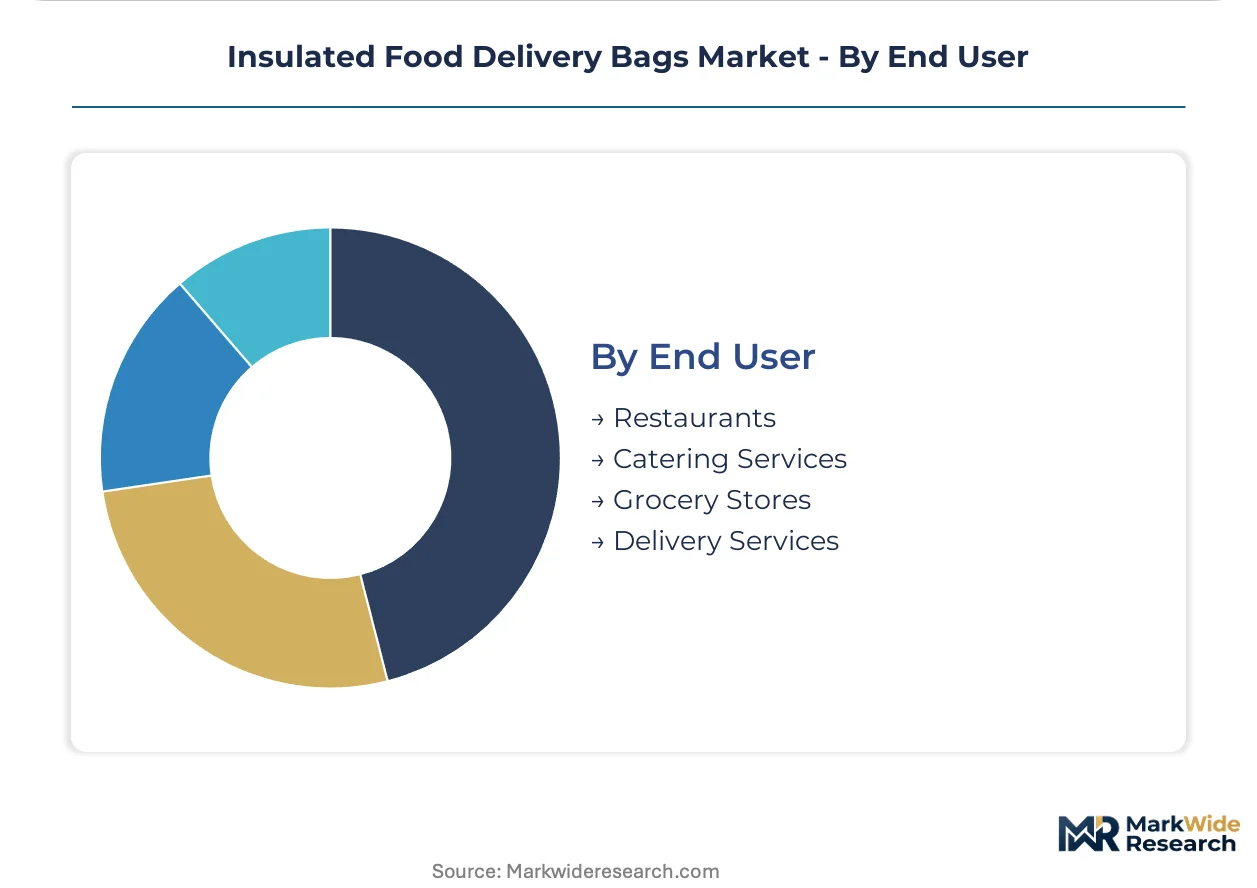
Customer type determines specification authority—restaurant chains centralize procurement while delivery platforms impose performance thresholds on fleet operators.
- Delivery Services:Third-party logistics fleets and platform-owned operations specify modular bags with detachable insulation panels. Gig-economy expansion in Vietnamese and Indonesian secondary cities concentrates demand multiplication.
- Restaurants:Quick-service and full-service chains standardize thermal packaging across franchise networks. European quick-service restaurants adopt phase-change material integration at accelerated procurement cycles.
- Catering Services:Institutional and event-focused operators prioritize hard-case temperature integrity. Cambro Manufacturing anchors contracts through commercial kitchen heritage.
- Grocery Stores:Supermarket chains entering delivery specify extended cold-chain performance. Vacuum-insulated panel adoption concentrates where F-Gas Regulation pressure is most acute.
Current procurement volume centers on Delivery Services; Catering Services expands most quickly as pharmaceutical-adjacent meal programs proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentration for insulated food delivery bags clusters in China and Vietnam, while consumption tilts toward North America and Europe where food delivery platform density drives replacement cycles. Southeast Asian cloud kitchen operators import thermal packaging at scale as domestic fabrication capacity lags demand multiplication. Regulatory divergence between FDA food-contact standards and REACH chemical restrictions fragments substrate qualification pathways.
United States
Platform-owned logistics fleets and third-party delivery services drive procurement volume across major metropolitan markets. FDA food-contact material regulations govern insulation foam and interior lining substrates, extending certification timelines for new substrate introductions. Chicago and New York City anchor demand concentration as gig-economy driver density peaks in these urban corridors.
Germany
European quick-service restaurant chains standardize thermal packaging specifications across franchise networks, creating consolidated procurement volumes. REACH compliance restricts flame retardants and phthalates in nylon and polypropylene components, forcing substrate requalification cycles. The Rhine-Ruhr industrial corridor hosts fabrication facilities serving EU-wide distribution networks.
Vietnam
Cloud kitchen operators scale thermal packaging procurement as food delivery platforms expand into secondary cities including Da Nang and Can Tho. The country's national food safety regulator aligns with ASEAN harmonized standards for food-contact materials. Ho Chi Minh City and Hanoi concentrate gig-economy fleet multiplication, driving modular bag adoption with detachable insulation panels.
Indonesia
Underpenetrated urban logistics networks in secondary cities present first-mover advantages for localized thermal packaging procurement. Extended producer responsibility frameworks approach imposition, threatening fleet operator cost structures through impending recovery obligations. Jakarta and Surabaya anchor platform-direct procurement channel consolidation.
United Kingdom
Quick-service restaurant chains negotiate master service agreements with thermal bag fabricators, disintermediating traditional packaging distributors. The EU F-Gas Regulation indirectly shapes insulation material selection by pressuring manufacturers toward vacuum-insulated panel alternatives. Greater London concentrates specification authority for national franchise networks.
Insulated Food Delivery Bags Market Competitive Landscape
The competitive structure tilts toward specialized fabricators with commercial kitchen heritage and platform-direct suppliers with last-mile optimization expertise. Market concentration remains moderate, with no single participant commanding dominant share across all substrate and format categories. Three archetypes define positioning: heritage commercial foodservice equipment manufacturers, Asian platform-specialized suppliers, and diversified packaging conglomerates extending into thermal formats. Capacity expansion and substrate innovation cycles constitute the dominant competitive moves as regulatory pressure accelerates material turnover.
Among heritage commercial foodservice manufacturers, Cambro Manufacturing anchors institutional catering contracts through its commercial kitchen equipment lineage. Packir occupies a position exemplifying platform-specialized configuration expertise for Asian delivery networks. Huhtamaki represents the diversified packaging conglomerate archetype, extending its food packaging portfolio into insulated formats for European quick-service restaurants.
| Leading Market Players |
|---|
| Grubhub Gear |
| Packir |
| Cambro Manufacturing |
| Delivery Bags USA |
| American Aerogel |
| Huhtamaki |
| Zojirushi America Corporation |
| Carlisle FoodService Products |
| Thermos LLC |
| Others |
Supply & Pricing Matrix
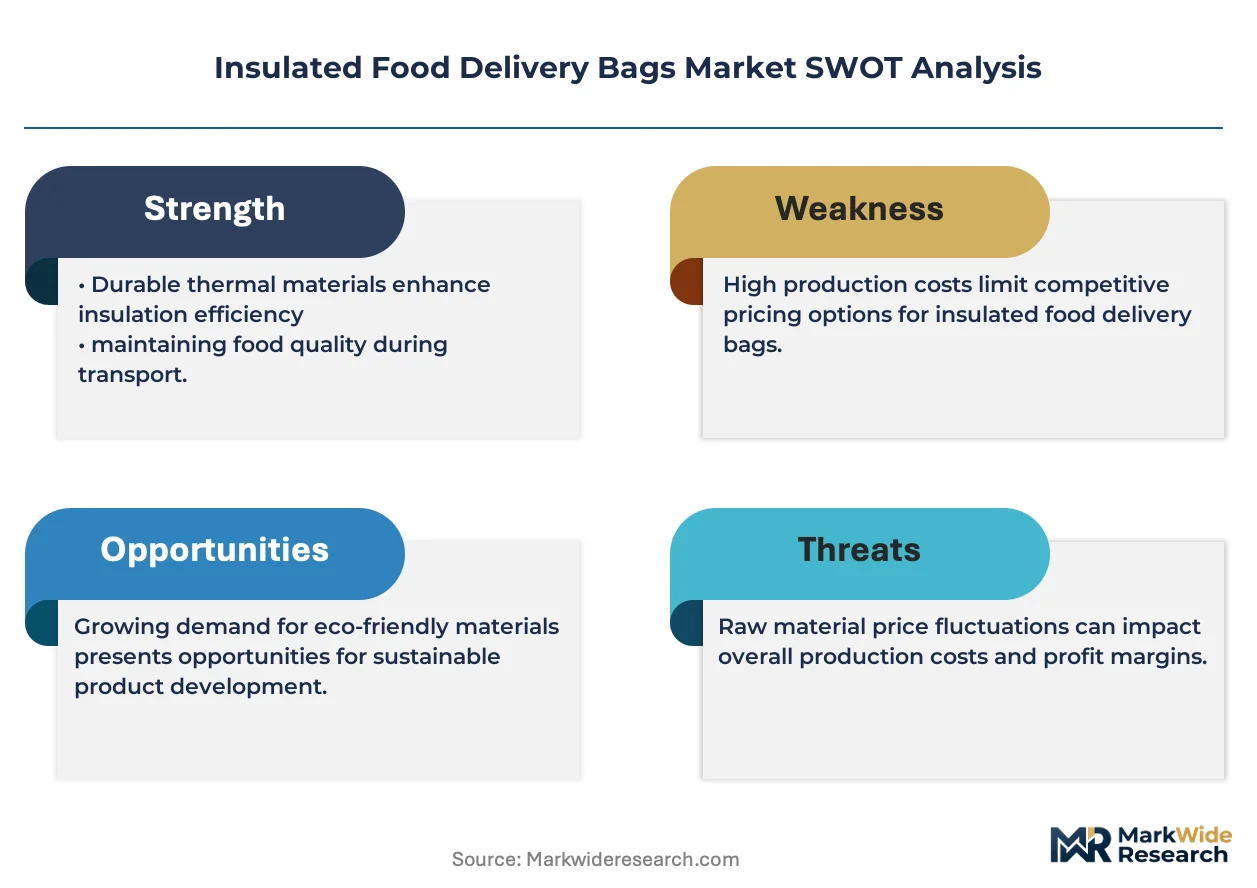
Platform-direct procurement consolidation across Vietnamese and Indonesian delivery networks is compressing distributor margins and forcing fabricators toward volume-tiered contract structures that sacrifice unit economics for fleet-scale commitments.
Pricing Analysis
Cost-down pressure on standard soft bag tiers accelerates because platform procurement teams centralize specification authority and benchmark quotes across Southeast Asian suppliers. Pricing stratifies across premium vacuum-insulated panels, standard polyurethane-foam configurations, and economy-grade expanded polystyrene alternatives. REACH compliance costs and F-Gas Regulation-driven substrate migrations inflate raw material qualification expenses, squeezing mid-tier fabricators hardest. Third-party logistics fleets exhibit acute price sensitivity, while pharmaceutical-adjacent meal programs absorb premiums for hard-case temperature integrity.
Supply Chain Analysis
Domestic-content incentives in Vietnam and Indonesia are reshaping sourcing patterns as cloud kitchen operators seek localized fabrication to avoid import duty exposure and logistics chokepoints. Manufacturing gravity centers on China, Vietnam, and Bangladesh for polyester woven shells and insulation foam core production. Raw material supply draws from petrochemical feedstocks for polyurethane and recycled PET streams for sustainable polyester alternatives. Single-source vulnerability concentrates in hydrofluorocarbon-based foam substrates facing EU phase-out timelines. Distribution runs through platform-direct master service agreements disintermediating traditional packaging distributors across Asian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Substrate innovation capacity is the binding constraint propping pricing power for qualified suppliers, as REACH requalification timelines and FDA certification cycles delay new entrant ramp-up.
For Market Incumbents: Anticipate margin compression from aerogel insulation convergence by securing backward integration into vacuum-insulated panel supply or captive polyurethane foam production in Vietnam. Defend position by anchoring institutional catering contracts through phase-change material integration and commercial kitchen heritage positioning. Prioritize certification investment for EU F-Gas Regulation-compliant substrates before legacy hydrofluorocarbon stocks deplete. For New Entrants and Emerging Players: Begin with underpenetrated Indonesian secondary cities where localized fabrication capacity lags platform fleet expansion. Target grocery and alcohol delivery categories requiring extended cold-chain performance as the most penetrable application vertical. Pursue white-label manufacturing partnerships with established polyester shell suppliers to compress time-to-market for modular bag configurations. For Investors and Strategic Acquirers: The window for entry favors platform-specialized fabricators with last-mile optimization expertise and existing master service agreements. Long-term viability hinges on substrate innovation pipelines capable of spanning regulatory transitions from foam to aerogel and vacuum-panel alternatives. Monitor EU extended producer responsibility framework implementation timelines as the critical inflection signal for fleet operator cost structure disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Aerogel Insulation Convergence | Enables ultra-lightweight extended-duration performance for grocery delivery expansion. |
| Backward Integration into Foam Substrates | Captures margin from REACH-driven substrate turnover and F-Gas Regulation compliance. |
| Platform-Direct Master Service Agreements | Locks volume commitments across Vietnamese and Indonesian gig-economy fleet procurement. |
| Phase-Change Material Integration | Automates temperature compliance for European quick-service restaurant specifications. |
| Domestic Fabrication Footprint Expansion | Mitigates tariff exposure and logistics chokepoints in Indonesian secondary cities. |
Research Methodology
Trade association filings, customs import records, and EU regulatory databases formed the secondary backbone, supplemented by primary interviews with thermal packaging procurement managers at third-party logistics platforms, substrate R&D directors at insulation foam suppliers, cloud kitchen operations leads, and food safety compliance officers. Bottom-up and top-down triangulation validated volume estimates across product type, material, capacity, and end-user segmentation dimensions.
Bottom-up modeling aggregated unit economics from fabricator cost structures and platform procurement contract terms, while top-down approaches cross-referenced food delivery platform fleet expansion data against replacement cycle assumptions. Segmentation dimensions spanned soft bag versus hard case formats, polyester versus advanced insulation substrates, single-order versus bulk capacity tiers, and delivery service versus institutional catering end users. CAGR derivation incorporated substrate substitution elasticity and regulatory compliance cost pass-through assumptions.
Regulatory timeline acceleration, platform procurement centralization, and aerogel manufacturing scale-up delays are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding REACH requalification timelines and F-Gas Regulation phase-out schedules. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cold Chain Packaging
Fish Boxes Market
Cold Chain Packaging
Cold Chain Temperature Monitoring Market
Cold Chain Packaging
Biopharma Cold Chain Packaging Market
Cold Chain Packaging
Food Cold Chain Market
Cold Chain Packaging
Cryogenic Boxes Market
Cold Chain Packaging
Cooling Boxes Market
Cold Chain Packaging
Reusable Cold Chain Packaging Market
Cold Chain Packaging
Cold Chain Micro-Fulfillment Hub Networks Market
Cold Chain Packaging
Ice Boxes Market
Cold Chain Packaging
Cold Box Module Market
Cold Chain Packaging
Cold Chain Integrity and Shock Monitoring Test Devices Market
Cold Chain Packaging
Middle East and Africa Frozen Food Packaging Market
Cold Chain Packaging
Cold Chain Packaging Market
Cold Chain Packaging
Cryo Box Market
Cold Chain Packaging
Cryogenic Capsules Market
Cold Chain Packaging
Foam Cooler Box Market