
 Middle East and Africa Frozen Food Packaging Market | 2026-2036
Middle East and Africa Frozen Food Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Frozen Food Packaging Market Foresight
Supermarket chain consolidation across the Gulf Cooperation Council is restructuring procurement leverage for frozen food packaging suppliers. Amcor plc leverages its multi-material platform to serve pan-regional retail contracts from manufacturing bases in Dubai and Cairo. Sealed Air Corporation anchors its position through cryovac and vacuum skin technologies tailored to halal meat export requirements. Berry Global, Inc. competes on high-barrier pouch formats designed for extended shelf-life dairy and ready-meal applications in Nigeria and Kenya.
Frozen food packaging encompasses engineered barrier structures—typically multilayer films incorporating ethylene vinyl alcohol or metallized polyethylene terephthalate—manufactured to withstand temperatures from minus forty degrees Celsius through microwave reheating, preserving organoleptic quality across supply chain interruptions. Modified atmosphere packaging dominates premium protein segments where oxygen scavenging extends retail case life, while vacuum packaging leads volume in bulk institutional formats serving hotel and airline catering operations. Composite materials capture margin pools in resealable stand-up pouches for frozen fruit and vegetable lines targeting South African and UAE retail channels.
Saudi Food and Drug Authority and Emirates Authority for Standardization and Metrology enforce migration limits and halal certification protocols that determine market access for imported packaging substrates. South Africa's National Regulator for Compulsory Specifications mandates specific testing regimes for frozen food contact materials that filter out non-compliant Asian and European suppliers. Stakeholders must monitor evolving extended producer responsibility frameworks across the Gulf and East Africa, as post-consumer plastic regulations will reshape material specifications and recycling infrastructure investments.
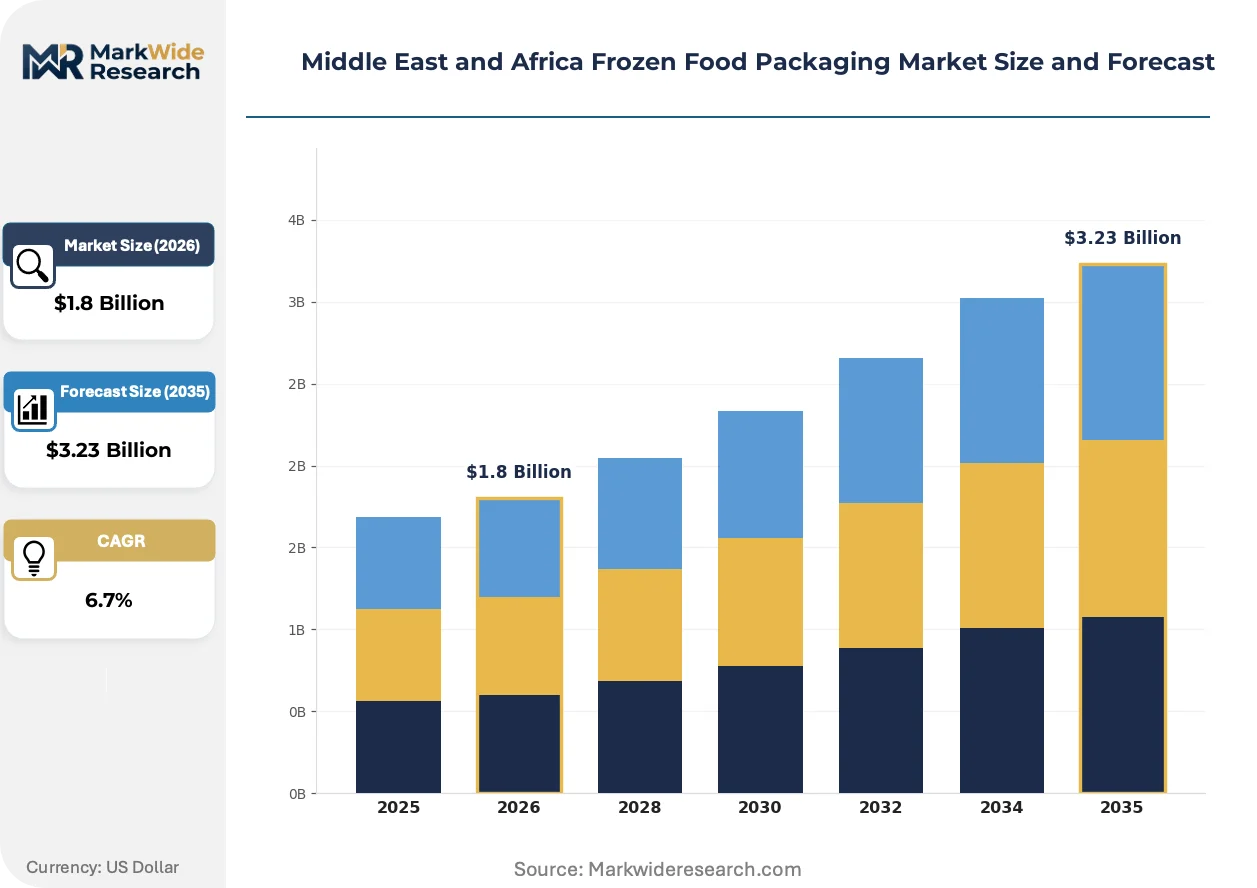
Market Dynamics
Quick-service restaurant chains across the Gulf Cooperation Council are consolidating frozen food procurement into pan-regional contracts, forcing packaging suppliers to reconfigure manufacturing footprints and certification portfolios around halal compliance and cold-chain reliability.
Growth Catalysts
- SFDA Halal Certification Mandates:Saudi Food and Drug Authority protocols for food-contact materials are creating certified supplier pools that lock out uncertified competitors and secure contract volumes for compliant converters.
- Ethylene Vinyl Alcohol Barrier Films:Multi-layer structures incorporating EVOH are extending frozen protein shelf life from six to eighteen months, enabling export-grade halal meat shipments from UAE and Saudi processing hubs.
- Riyadh-Jeddah Corridor Concentration:Saudi Arabia's retail distribution infrastructure investments are clustering cold-storage capacity around these two cities, generating packaging demand density unmatched elsewhere in the region.
Market Restraints
- Metallized PET Input Volatility:Raw material costs for high-barrier packaging fluctuate with petrochemical feedstock prices, compressing converter margins on fixed-price annual contracts with retail chains.
- Asian Supplier Concentration:Substrate sourcing for multilayer films depends heavily on South Korean and Chinese resin producers, exposing regional converters to shipping disruptions through the Strait of Hormuz.
- Emirates Authority for Standardization Migration Limits:ESMA's evolving testing regimes for heavy metals and plasticizers in food-contact materials are filtering out legacy substrate formulations and forcing costly reformulation cycles.
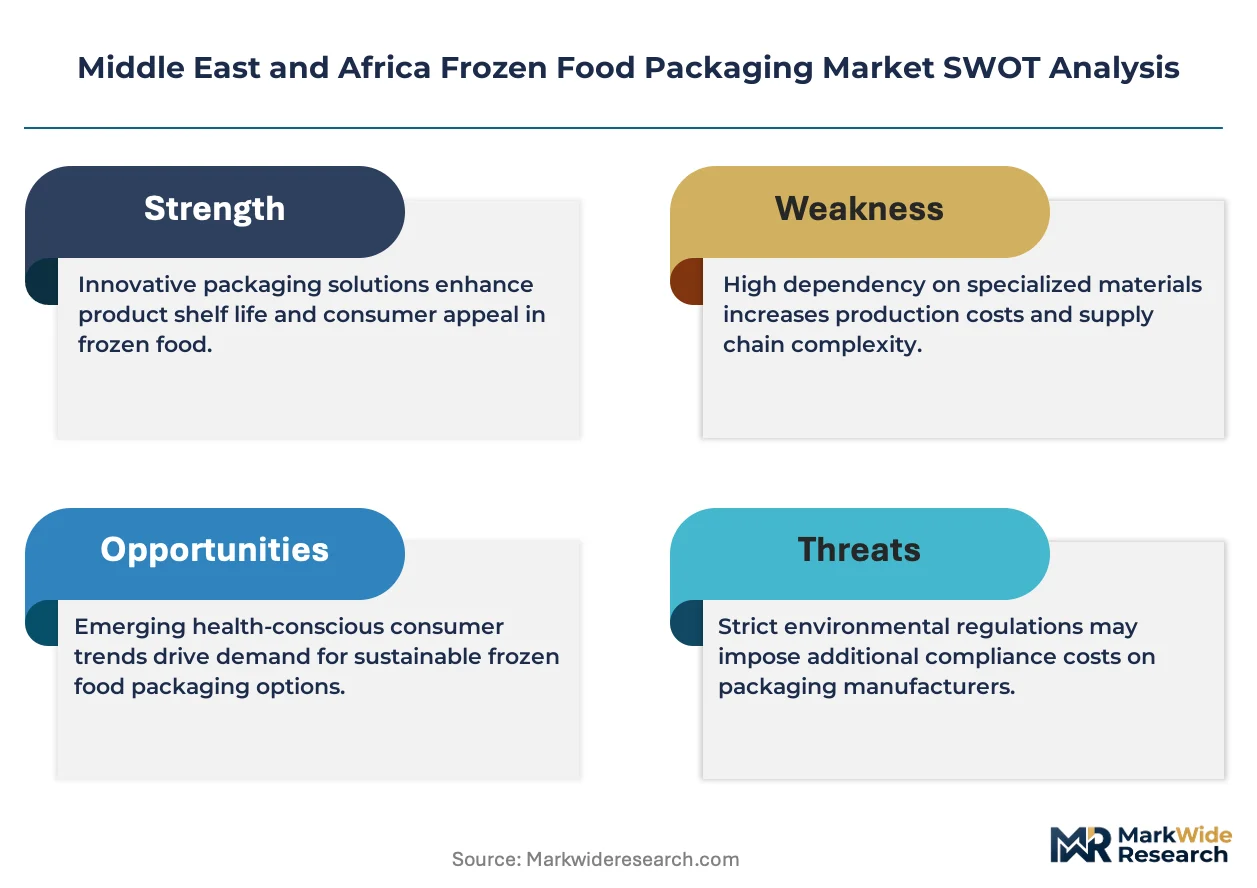
Strategic Opportunities
- Kenya and Nigeria Dairy Expansion:High-barrier pouch formats for extended shelf-life frozen dairy remain underpenetrated in East and West African retail channels, offering first-mover positioning for compliant suppliers.
- Extended Producer Responsibility Frameworks:Post-consumer plastic regulations under development across the Gulf will reshape material specifications and create recycling infrastructure partnerships for forward-integrated packaging producers.
- Modified Atmosphere and Vacuum Skin Convergence:Combining MAP oxygen scavenging with vacuum skin technology for premium protein retail packs is opening margin pools in South African and UAE supermarket channels.
Industry Challenges
- Halal Certification Timeline Compression:Saudi and UAE authorities are accelerating audit frequencies for food-contact material facilities, stretching quality assurance staffing and documentation systems.
- Cold-Chain Integration Complexity:Packaging engineered for minus forty degrees Celsius through microwave reheating must interface with legacy refrigeration infrastructure in South Africa and Nigeria that lacks temperature logging capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Frozen Food Packaging Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Bags, Boxes, Pouches, Trays Material: Plastic, Paper, Aluminum, Composite Technology: Modified Atmosphere Packaging, Vacuum Packaging, Resealable Packaging, Active Packaging End User: Retail, Food Service, Households, Industrial |
| Companies Covered | Amcor plc, Sealed Air Corporation, Berry Global, Inc., Mondi Group, Sonoco Products Company, Smurfit Kappa Group, Huhtamaki Oyj, Constantia Flexibles, Winpak Ltd., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Frozen Food Packaging Market Shifts & Advancements
Active and intelligent packaging technologies are penetrating frozen food applications as retail chains demand traceability and shelf-life transparency that static barrier structures cannot deliver.
Retort-compatible multilayer pouches are modularizing frozen ready-meal packaging architectures across GCC retail channels. Hotel and airline catering operators are adopting these formats at pace to consolidate frozen and ambient lines under single supplier relationships. The technology is modularizing procurement categories that previously separated frozen, chilled, and shelf-stable packaging specifications.
South Africa's National Regulator for Compulsory Specifications is tightening food-contact material testing regimes for frozen applications. Industrial consequence includes mandatory migration testing for plasticizers and heavy metals that filters out uncertified Asian and European substrate suppliers. Frozen protein exporters to South Africa are responding by qualifying alternative resin grades and accelerating local converter partnerships.
Buyer concentration among consolidated supermarket chains is compressing supplier switching cycles across the Gulf. Regional retail procurement teams are displacing fragmented local distributor networks with direct manufacturer contracts. This pattern is most visible in Saudi Arabia where Savola and Al Othaim are centralizing frozen food packaging specifications under single-source frameworks.
Middle East and Africa Frozen Food Packaging Market Segmentation
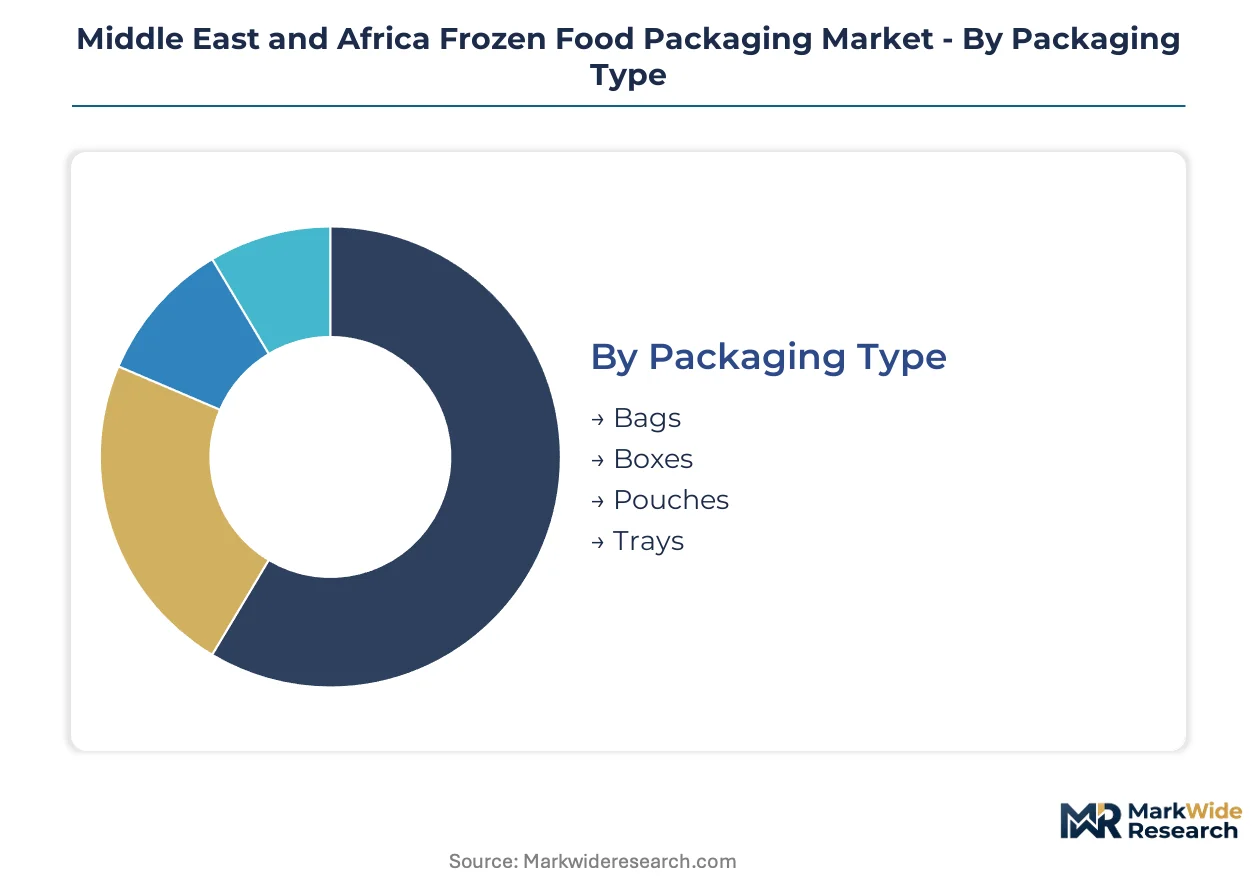
Frozen food packaging purchasing decisions across the Middle East and Africa hinge on barrier performance under thermal stress, halal certification compatibility, and cold-chain infrastructure maturity. Procurement managers weight material specifications against distribution reach, with Riyadh-Jeddah corridor buyers demanding eighteen-month shelf-life assurance while Nigerian retailers prioritize cost-efficient formats for intermittent refrigeration.
Packaging Type:
Purchasing volume concentrates on formats that balance unit economics with protein protection requirements across GCC quick-service restaurant chains and South African supermarket consolidation.
- Bags:Multi-layer polyethylene structures with ethylene vinyl alcohol cores dominate bulk frozen vegetable and seafood shipments to UAE hotel and airline catering operations. Saudi Arabia's Savola Group procurement specifications favor gusseted formats for pallet optimization in Riyadh-Jeddah distribution centers.
- Pouches:Stand-up configurations with resealable zipper closures capture premium frozen fruit and ready-meal lines in South African retail channels. High-barrier metallized polyethylene terephthalate laminations extend case life for dairy exports from Kenya to COMESA markets.
- Boxes:Folding carton formats with polyethylene-coated interiors serve institutional frozen bakery and prepared meal segments where stacking strength matters more than oxygen exclusion.
- Trays:Crystallized polyethylene terephthalate and expanded polystyrene structures carry marinated halal proteins for UAE and Saudi retail display cases, with lidding film compatibility determining supplier qualification.
Pouches lead on scale; resealable and high-barrier variants lead on momentum.
Material:
Raw material selection tracks regulatory migration limits enforced by Saudi Food and Drug Authority and South Africa's National Regulator for Compulsory Specifications, filtering substrate sourcing strategies.
- Plastic:Polyethylene, polypropylene, and polyethylene terephthalate films constitute the volume base, with multilayer coextrusions incorporating ethylene vinyl alcohol barrier layers qualifying for SFDA-certified halal meat exports from Dubai processing hubs.
- Composite:Paperboard-polyethylene-aluminum laminations bridge frozen and ambient distribution requirements for GCC hotel catering procurement consolidation. Retort-compatible variants enable single-supplier contracts covering frozen, chilled, and shelf-stable lines.
- Aluminum:Foil laminations and semi-rigid trays serve premium protein segments where complete light and oxygen exclusion justifies material cost premiums in UAE supermarket channels.
- Paper:Grease-resistant coatings and polyethylene extrusions capture frozen bakery and confectionery applications with shorter distribution radii and lower barrier demands.
Plastic leads on scale; composite structures lead on momentum.
Technology:
Technology adoption correlates with retail consolidation intensity and export orientation, with traceability requirements driving intelligent packaging penetration in South Africa and the UAE.
- Modified Atmosphere Packaging:Oxygen scavenging systems and nitrogen flushing extend retail case life for premium halal beef and lamb cuts in Saudi Arabia's consolidating supermarket sector. Gas mixture precision determines supplier qualification for Al Othaim direct contracts.
- Vacuum Packaging:Cryovac and thermoformed skin technologies dominate bulk institutional formats serving GCC airline catering and Nigerian hotel chains, with film clarity and seal integrity under minus forty degrees Celsius storage determining converter selection.
- Resealable Packaging:Zipper and slider mechanisms on stand-up pouches target household frozen fruit and vegetable segments in South African retail, with opening force consistency influencing repeat purchase rates.
- Active Packaging:Time-temperature indicators and freshness sensors penetrate traceability-sensitive protein exports from UAE and Saudi processing hubs to European halal markets.
Vacuum packaging leads on scale; active packaging leads on momentum.
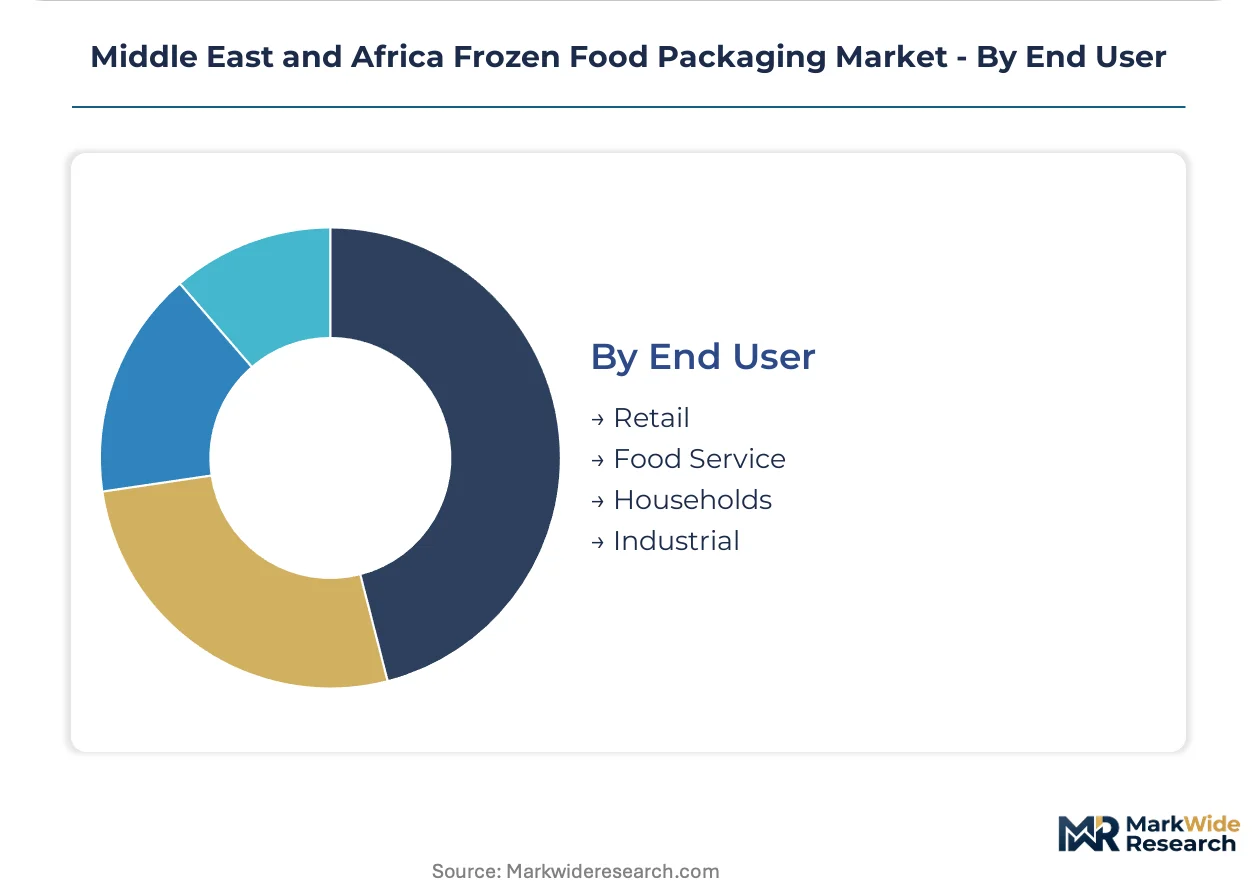
End User:
Customer type shapes order configuration, certification burden, and technical service intensity, with food service procurement consolidation driving pan-regional contract structures.
- Food Service:Quick-service restaurant chains across the Gulf Cooperation Council consolidate frozen protein and ready-meal procurement into multi-country agreements. Packaging specifications must satisfy halal certification, bilingual labeling, and minus eighteen degrees Celsius distribution reliability across Saudi Arabia, UAE, Kuwait, and Qatar.
- Retail:Supermarket chain consolidation in Saudi Arabia and South Africa compresses supplier bases and standardizes barrier specifications. Direct manufacturer relationships displace fragmented distributor networks, with private-label frozen lines demanding customized print and format flexibility.
- Industrial:Frozen ingredient suppliers to bakery and confectionery manufacturers prioritize unit cost and pallet density over shelf-life extension, with bulk bag-in-box formats dominating procurement.
- Households:Individual consumer purchases through e-commerce channels in UAE and South Africa drive small-format pouch demand with convenience-oriented reseal features.
Food service leads on scale; retail consolidation leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized packaging engineers and halal certification specialists cluster around Dubai and Riyadh, anchoring regional technical capability. Cold-chain logistics talent concentrates in Johannesburg and Lagos, supporting distribution network expansion. These workforce patterns shape where packaging converters locate manufacturing and compliance operations.
Saudi Arabia
Quick-service restaurant procurement consolidation drives frozen protein packaging volumes across the Riyadh-Jeddah corridor. Saudi Food and Drug Authority halal certification mandates for food-contact materials filter supplier pools and lock in contract volumes for compliant converters. Cold-storage infrastructure investments cluster around Jeddah Islamic Port, generating packaging demand density for export-grade halal meat shipments.
United Arab Emirates
Hotel and airline catering operators consolidate frozen and ambient procurement under single-supplier frameworks, expanding retort-compatible pouch demand. Emirates Authority for Standardization and Metrology enforces migration limits for heavy metals and plasticizers that reshape substrate qualification requirements. Dubai Industrial City hosts multilayer film manufacturing bases serving pan-regional retail contracts.
South Africa
Supermarket chain consolidation compresses supplier bases and standardizes barrier specifications for private-label frozen lines. National Regulator for Compulsory Specifications mandates specific testing regimes for frozen food contact materials that filter out non-compliant Asian and European substrate suppliers. Gauteng Province anchors retail distribution infrastructure, with Johannesburg cold-storage hubs driving packaging procurement centralization.
Nigeria
Extended shelf-life frozen dairy applications remain underpenetrated in Lagos and Abuja retail channels, offering format innovation opportunities. The country's national food safety regulator enforces evolving food-contact material standards that reshape import compliance obligations for packaging substrates. Kano and Port Harcourt industrial zones concentrate frozen food processing capacity, generating localized packaging demand.
Kenya
High-barrier pouch formats for frozen dairy exports to COMESA markets drive technical specification requirements from Nairobi-based processors. Kenya Bureau of Standards maintains food-contact material protocols that determine market access for imported packaging substrates. Mombasa Port logistics corridors cluster cold-chain infrastructure investments, creating packaging demand nodes for regional trade.
Middle East and Africa Frozen Food Packaging Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across material platforms and certification portfolios. The supplier base organizes around three archetypes: global material science conglomerates with multi-regional manufacturing footprints, regional converters specializing in halal-certified barrier structures, and niche players targeting single-format dominance in resealable or vacuum technologies. Competitive moves center on strategic partnerships with retail procurement teams and backward integration into resin compounding to secure input cost stability.
Within the global conglomerate tier, Amcor plc and Sealed Air Corporation exemplify scale-driven positioning through multi-material platforms and cryovac technologies respectively. Berry Global, Inc. occupies a specialist position in high-barrier pouch formats. These three anchors represent divergent strategic postures: pan-regional contract service, technology-led protein protection, and format-specific dairy and ready-meal applications.
| Leading Market Players |
|---|
| Amcor plc |
| Sealed Air Corporation |
| Berry Global, Inc. |
| Mondi Group |
| Sonoco Products Company |
| Smurfit Kappa Group |
| Huhtamaki Oyj |
| Constantia Flexibles |
| Winpak Ltd. |
| Others |
Supply & Pricing Matrix
Quick-service restaurant chains consolidating procurement across the Gulf Cooperation Council operate on contract-based long-term offtake agreements that lock in volume commitments and compress spot-market pricing flexibility for converters.
Pricing Analysis
Packaging procurement splits between bundled halal-certification-plus-logistics contracts and unbundled substrate-only transactions. Three-tier pricing structure across premium, standard, and economy levels tracks barrier performance and certification grade, with SFDA-compliant multilayer films commanding premiums over uncertified alternatives. Cost compression in standard-tier polyethylene structures is intensifying because Asian resin oversupply filters into regional spot markets. Food service procurement teams exhibit lowest price sensitivity due to halal compliance non-negotiability, while Nigerian retail distributors prioritize economy-tier formats.
Supply Chain Analysis
Single-source vulnerability sits with South Korean and Chinese ethylene vinyl alcohol resin producers that feed multilayer film extrusion lines in Dubai and Cairo. Raw material dependencies center on petrochemical feedstocks, metallized polyethylene terephthalate substrates, and oxygen scavenger additives. Shipping disruptions through the Strait of Hormuz constitute the dominant structural risk. Distribution runs through Riyadh-Jeddah corridor cold-storage hubs for Saudi retail, with Mombasa and Lagos port clusters serving East and West African markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa frozen food packaging market functions as a stable compounder, with Gulf quick-service restaurant procurement consolidation generating recurring volume commitments that smooth demand volatility.
For Market Incumbents: Anticipate margin compression from Asian substrate suppliers achieving SFDA certification parity by securing backward integration into resin compounding and expanding manufacturing footprints in Jeddah Industrial City. Halal audit frequency acceleration threatens quality assurance staffing ratios; automated documentation systems represent the priority defensive investment.
For New Entrants and Emerging Players: Launch via direct-to-retail relationships in Kenya and Nigeria's underpenetrated frozen dairy pouch segments, bypassing established distributor networks that incumbent conglomerates control. COMESA export qualification requirements create a certification moat that first movers can exploit before regional converters achieve compliance scale.
For Investors and Strategic Acquirers: Pan-regional food service packaging conglomerates are the most active acquirer in this space, targeting halal-certified converters with established Savola or Al Othaim contract relationships. Five-to-ten year viability hinges on extended producer responsibility framework positioning; the signal to watch is Gulf recycling infrastructure partnership announcements that reshape material specification roadmaps.
| Strategic Initiative | Industry Significance |
|---|---|
| Halal Certification Acceleration | SFDA audit readiness secures contract eligibility with Saudi retail procurement teams. |
| Backward Integration into Resin Compounding | Captive EVOH supply stabilizes input costs for multilayer barrier film production. |
| Retort-Compatible Pouch Platform Launch | Modular formats capture GCC hotel catering procurement consolidation opportunities. |
| Recycling Infrastructure Partnership | Extended producer responsibility positioning anticipates Gulf post-consumer plastic regulations. |
| Direct Manufacturer Contract Conversion | Displacing fragmented distributors aligns with Saudi and South African retail consolidation. |
Research Methodology
Bottom-up quick-service restaurant and retail procurement modeling reconciled against top-down multilayer film capacity tracking forms the analytical core of this study. Primary interviews with packaging procurement managers at Saudi supermarket chains, technical directors at Dubai-based converters, cold-chain logistics operators in Johannesburg, and halal certification auditors supplied operational data. Secondary validation drew from SFDA regulatory filings, Emirates Authority for Standardization and Metrology technical bulletins, South Africa's National Regulator for Compulsory Specifications testing protocols, and customs trade records for ethylene vinyl alcohol resin imports.
Historical trendline analysis of frozen protein export volumes and packaging substrate consumption patterns established baseline growth trajectories across the analysis window. Segmentation modeling incorporated packaging type, material platform, barrier technology, and end-user procurement channel dimensions. CAGRs were derived from elasticity-adjusted demand projections that weight cold-chain infrastructure investment schedules against halal certification penetration curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Strait of Hormuz shipping disruption scenarios or accelerated extended producer responsibility implementation. Forecasts reflect documented assumptions about SFDA audit timeline compression and South African testing regime stringency. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cold Chain Packaging
Cold Chain Market
Cold Chain Packaging
Freezer Liner Market
Cold Chain Packaging
Cryogenic Boxes Market
Cold Chain Packaging
China Cold Chain Market
Cold Chain Packaging
Reusable Cold Chain Packaging Market
Cold Chain Packaging
Europe Cold Chain Tracking and Monitoring Market
Cold Chain Packaging
Global Cold Chain Tracking and Monitoring Market
Cold Chain Packaging
Europe Healthcare Cold Chain Logistics Market
Cold Chain Packaging
Latin America Pharmaceutical Cold Chain Logistics Market
Cold Chain Packaging
Pharmaceutical Cold Chain Packaging Market
Cold Chain Packaging
Fish Boxes Market
Cold Chain Packaging
Cold Storage Insulated Market
Cold Chain Packaging
Insulated Food Delivery Bags Market
Cold Chain Packaging
Cold Chain Integrity and Shock Monitoring Test Devices Market
Cold Chain Packaging
Cold Chain Equipment Market
Cold Chain Packaging
Cryo Box Market