
 Global Cold Chain Tracking and Monitoring Market | 2026-2036
Global Cold Chain Tracking and Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cold Chain Tracking and Monitoring Market Foresight
Buyer concentration among pharmaceutical logistics providers is expanding as vaccine and biologics distributors consolidate their vendor relationships around full-stack monitoring platforms. Carrier Global Corporation leverages its refrigeration heritage to anchor integrated hardware-software offerings across North American and European pharmaceutical corridors. Sensitech Inc. specializes in precision temperature data loggers that meet FDA validation protocols for blood product transit. ORBCOMM Inc. competes through satellite-terrestrial hybrid connectivity that sustains tracking continuity in remote distribution lanes.
Cold chain tracking and monitoring encompasses sensor networks, telemetry devices, and software platforms that record, transmit, and analyze temperature, humidity, location, and shock parameters across temperature-sensitive supply chains. These systems typically operate within calibrated ranges from deep-frozen minus 80 degrees Celsius through controlled room temperature, with alarm thresholds configurable to product-specific stability data. Pharmaceutical applications command the dominant margin pool due to GDP validation requirements and batch-release dependencies on continuous temperature records. IoT-enabled Devices represent the fastest-expanding technology segment as cellular LPWAN modules displace standalone loggers with real-time exception alerting. Cloud-based Platforms lead deployment architecture by centralizing multi-site visibility for contract warehouses managing diverse client product portfolios.
The FDA enforces 21 CFR Part 11 electronic records standards that shape software validation investments by vendors serving US pharmaceutical distribution. EMA's GDP Chapter 9 on transportation mandates qualified equipment with mapping studies, directing European logistics providers toward calibrated, certifiable monitoring hardware. Japan's PMDA aligns with ICH Q1A stability guidelines that require documented temperature history for imported biologics. Stakeholders must weigh satellite connectivity premiums against cellular coverage gaps when designing lane-specific monitoring architectures for emerging distribution corridors.
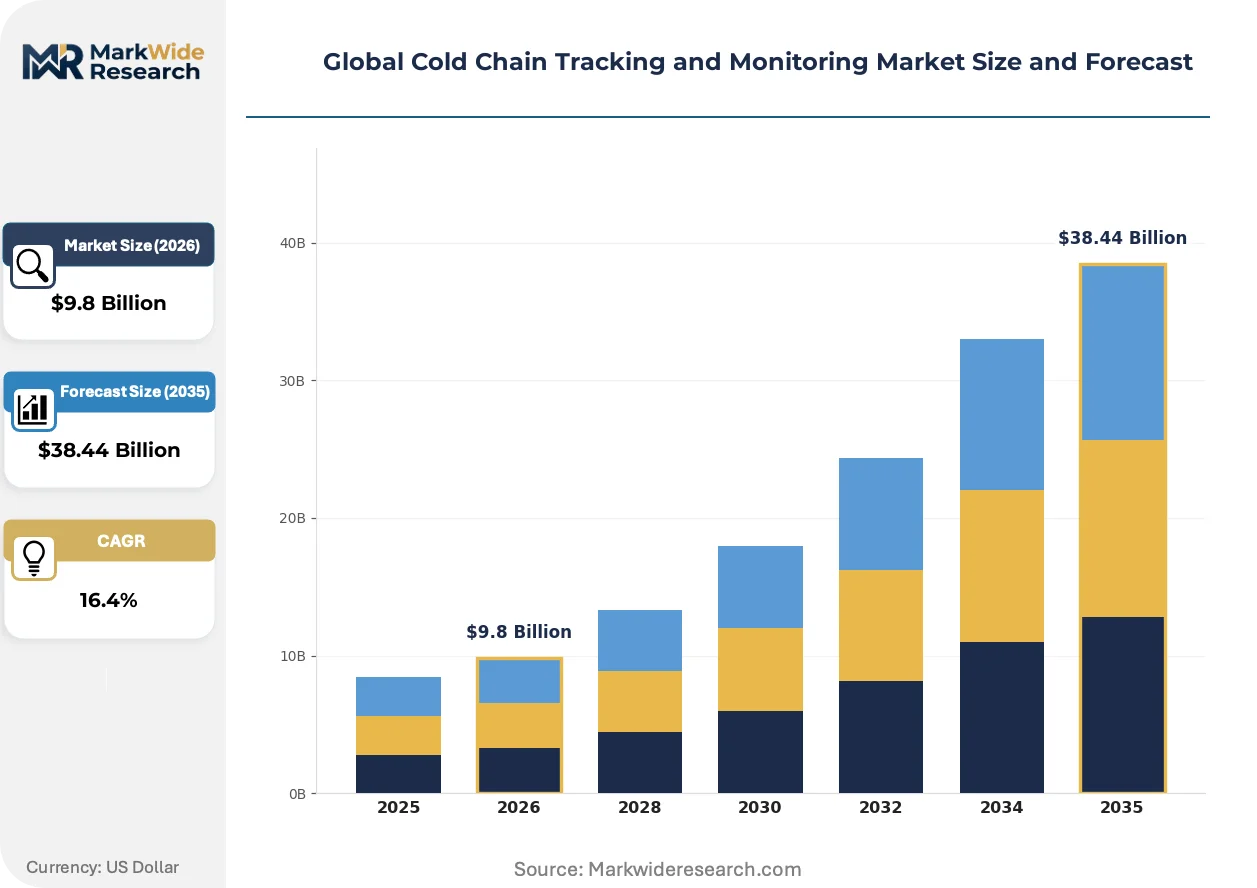
Market Dynamics
Pharmaceutical logistics consolidation is compressing vendor relationships toward integrated monitoring platforms capable of spanning GDP-validated corridors from manufacturing through last-mile delivery.
Growth Catalysts
- EMA GDP Chapter 9:European transportation mandates for qualified equipment with mapping studies are directing logistics providers toward certifiable hardware investments.
- Cellular LPWAN modules:Real-time exception alerting capabilities are displacing standalone loggers in vaccine distribution networks across Germany and Japan.
- Biologics batch-release dependencies:Continuous temperature record requirements for imported therapeutics are anchoring monitoring infrastructure in United States pharmaceutical hubs.
Market Restraints
- Satellite connectivity premiums:Hybrid satellite-terrestrial architectures impose recurring cost burdens on lanes serving remote distribution corridors with cellular coverage gaps.
- Sensor calibration drift:Deep-frozen minus 80 degrees Celsius applications require quarterly recertification cycles that compress hardware utilization rates.
- Lithium battery supply concentration:Telemetry device manufacturers face input volatility from concentrated East Asian cell production.
Strategic Opportunities
- Indian vaccine export expansion:CDSCO-aligned cold chain infrastructure investments are creating hardware-software integration demand for international distribution compliance.
- WHO prequalification pathways:Temperature monitoring documentation requirements for donor-funded immunization programs are opening certified data logger markets across Sub-Saharan Africa.
- Cloud-platform channel convergence:Contract warehouse operators are consolidating multi-client visibility through centralized SaaS architectures replacing on-premise deployments.
Industry Challenges
- 21 CFR Part 11 software validation:FDA electronic records standards impose documentation burdens that extend vendor qualification timelines for US pharmaceutical distributors.
- Multi-modal handoff integrity:Air-to-ground transfer points in international lanes create data continuity risks requiring redundant sensor overlap.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cold Chain Tracking and Monitoring Market |
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $38.44 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: GPS Tracking, RFID Sensors, IoT-enabled Devices, Bluetooth Beacons, Temperature Data Loggers Application: Pharmaceuticals, Perishable Food, Chemical Products, Floral Logistics, Blood Products End User: Logistics Providers, Contract Warehouses, Food Distributors, Research Laboratories, Medical Suppliers Deployment: Cloud-based Platforms, On-Premise Systems, Hybrid Solutions, Edge Computing, Mobile Applications |
| Companies Covered | Carrier Global Corporation, Emerson Electric Co., Americold Logistics LLC, Lineage Logistics LLC, ORBCOMM Inc., Sensitech Inc., Berlinger & Co AG, ELPRO-BUCHS AG, Controlant, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cold Chain Tracking and Monitoring Market Shifts & Advancements
Sensor hardware is fragmenting into interoperable components while regulatory validation requirements harden around software audit trails. Platform economics are compressing standalone logger margins.
Bluetooth Low Energy tags paired with cellular gateways are modularizing cold chain architectures. Pharmaceutical 3PLs in the United States are deploying these hybrid configurations to reduce per-shipment hardware costs. The technology is modularizing procurement patterns away from dedicated single-use devices toward reusable infrastructure with disposable sensing endpoints.
REACH chemical restrictions on battery substances are reshaping European telemetry device supply chains. Manufacturers must reformulate power systems to maintain CE marking compliance for data loggers. German logistics corridors serving temperature-sensitive pharmaceuticals are absorbing extended hardware qualification cycles as vendors revalidate redesigned cell chemistries.
Consolidated buying by vaccine distributors is compressing vendor switching cycles. Full-stack platform contracts spanning hardware, connectivity, and software are displacing point-solution procurement in Japan and the United States. Biologics shippers with GDP-validated supplier lists are locking in multi-year monitoring partnerships to reduce qualification overhead.
Global Cold Chain Tracking and Monitoring Market Segmentation
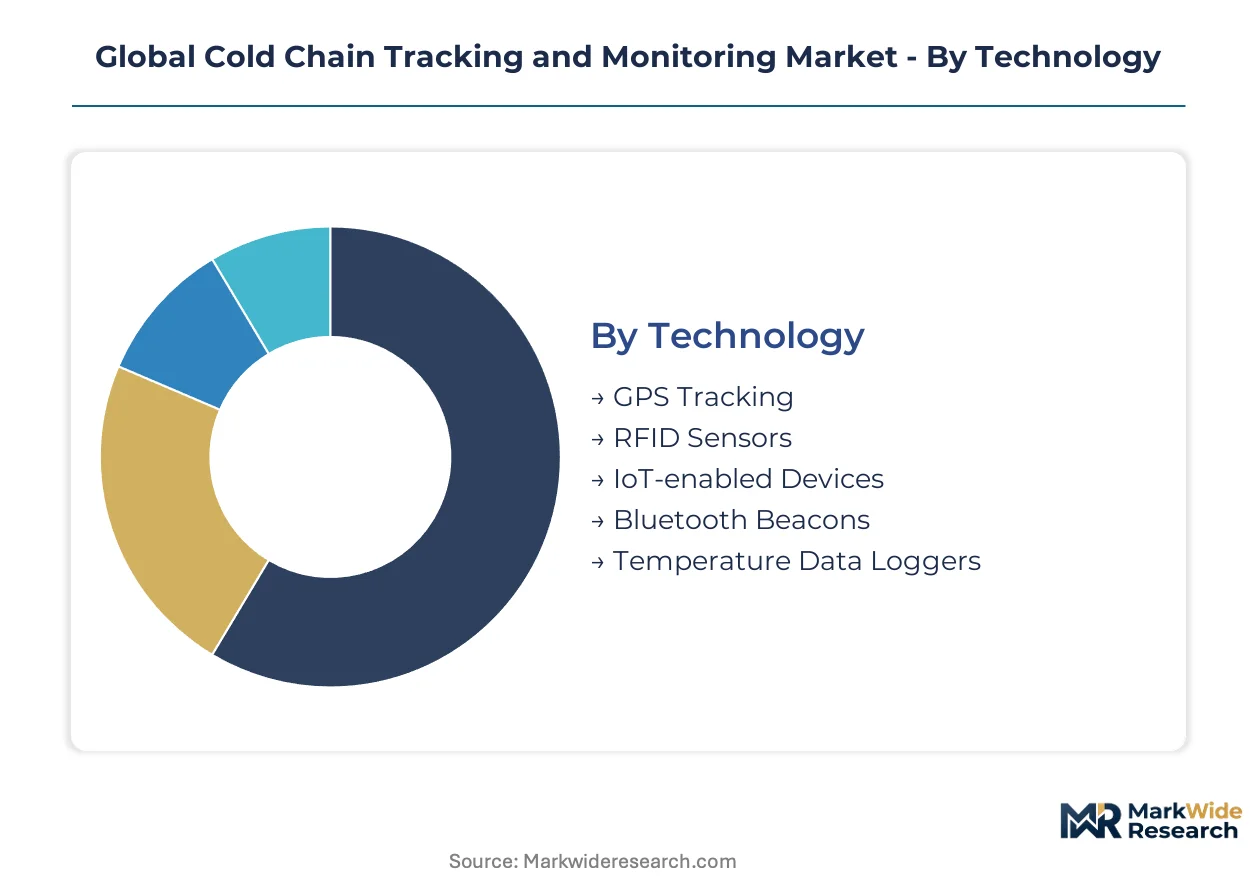
Cold chain tracking and monitoring segments diverge sharply by integration depth. Standalone hardware dominates legacy installations while embedded sensor networks reshape new deployments.
Technology:
Integration depth separates standalone loggers from networked telemetry systems that feed centralized platforms.
- GPS Tracking:Satellite-based location engines provide lane-level visibility across international pharmaceutical corridors. Demand concentrates among logistics providers managing cross-border vaccine shipments where cellular coverage gaps require redundant positioning.
- IoT-enabled Devices:Cellular LPWAN modules transmit temperature, humidity, and shock data in real-time through cloud gateways. German pharmaceutical distributors are displacing standalone loggers with these systems to meet EMA GDP Chapter 9 exception alerting requirements.
- RFID Sensors:Passive and active radio-frequency tags enable automated inventory reconciliation at warehouse chokepoints.
- Bluetooth Beacons:Short-range wireless tags pair with cellular gateways to modularize last-mile monitoring architectures.
- Temperature Data Loggers:Calibrated standalone recorders remain essential for blood product transit validation under FDA 21 CFR Part 11 protocols.
Temperature Data Loggers lead volumes today; IoT-enabled Devices are gaining share fastest.
Application:
Margin concentration follows regulatory validation burden rather than shipment volume alone.
- Pharmaceuticals:GDP-validated temperature documentation anchors the highest-margin segment. Continuous monitoring infrastructure serves batch-release dependencies for biologics imported into Japan under PMDA-aligned ICH Q1A guidelines.
- Perishable Food:Fresh produce and protein distributors drive volume demand through high-frequency lane utilization. United States food distributors are consolidating visibility platforms to manage diverse supplier temperature requirements.
- Blood Products:FDA-validated data loggers support therapeutic plasma and platelet distribution with strict chain-of-custody records.
- Chemical Products:Temperature-sensitive industrial formulations require monitoring for stability maintenance during transit.
- Floral Logistics:High-value cut flower shipments utilize humidity-tracking sensors to preserve shelf life.
Perishable Food dominates shipment volumes; Pharmaceuticals commands the steepest expansion trajectory.
End User:
Procurement sophistication separates enterprise-scale platform buyers from point-solution purchasers.
- Logistics Providers:Full-stack monitoring platforms span GDP-validated corridors from manufacturing through last-mile delivery. Carrier consolidation in the United States and Japan is compressing vendor relationships toward integrated hardware-software contracts.
- Contract Warehouses:Multi-client visibility requirements drive cloud-platform adoption to replace on-premise deployments. Centralized SaaS architectures enable simultaneous monitoring of diverse pharmaceutical and food portfolios.
- Food Distributors:High-volume perishable networks prioritize cost-efficient reusable sensing infrastructure over disposable loggers.
- Research Laboratories:Clinical trial material shipments demand calibrated, certifiable monitoring hardware with audit-ready documentation.
- Medical Suppliers:Hospital and clinic distribution networks require validated cold chain records for regulatory inspection readiness.
Logistics Providers anchor current demand; Contract Warehouses are expanding most quickly.
Deployment:
Architecture choices reflect trade-offs between data sovereignty, latency requirements, and scalability.
- Cloud-based Platforms:Centralized visibility systems aggregate multi-site sensor feeds for distributed warehouse networks. European logistics providers favor these architectures to harmonize GDP compliance documentation across national borders.
- Hybrid Solutions:Edge processing with cloud synchronization balances real-time alerting against bandwidth constraints. Remote distribution corridors with intermittent connectivity depend on local data buffering with periodic upload.
- On-Premise Systems:Air-gapped deployments serve data-sensitive pharmaceutical manufacturers with strict IT security policies.
- Edge Computing:Localized analytics reduce transmission latency for time-critical temperature excursions.
- Mobile Applications:Smartphone-based interfaces provide driver and field personnel access to shipment status.
Cloud-based Platforms dominate current deployments; Hybrid Solutions are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled pharmaceutical logistics engineers and GDP compliance specialists concentrate in Germany, the United States, and Japan, anchoring the dominant cold chain monitoring corridors. These talent pools support vaccine export infrastructure and biologics distribution networks that drive regional technology adoption.
United States
FDA-validated pharmaceutical distribution networks and biologics batch-release dependencies anchor demand for continuous temperature monitoring infrastructure. The FDA enforces 21 CFR Part 11 electronic records standards that shape software validation investments by domestic vendors. The Boston-Cambridge biotech corridor and New Jersey pharmaceutical logistics hub absorb calibrated data logger deployments for blood product transit.
Germany
EMA GDP Chapter 9 transportation mandates for qualified equipment with mapping studies direct logistics providers toward certifiable hardware investments. REACH chemical restrictions on battery substances reshape telemetry device supply chains, forcing reformulated power systems to maintain CE marking compliance. The Rhine-Main pharmaceutical logistics cluster around Frankfurt sustains real-time exception alerting infrastructure for cross-border vaccine shipments.
Japan
PMDA-aligned ICH Q1A stability guidelines require documented temperature history for imported biologics, anchoring monitoring infrastructure in pharmaceutical hubs. METI industrial policy supports IoT-enabled cold chain investments through standardization initiatives. The Kanto region around Tokyo and the Kansai corridor through Osaka concentrate contract warehouse operators consolidating multi-client visibility through centralized SaaS architectures.
India
CDSCO-aligned cold chain infrastructure investments create hardware-software integration demand for international distribution compliance. WHO prequalification pathways for donor-funded immunization programs open certified data logger markets across vaccine export corridors. The Pune-Nashik pharmaceutical manufacturing belt and Hyderabad vaccine production cluster deploy real-time monitoring to meet European and American import standards.
Switzerland
Swissmedic pharmaceutical regulations and precision logistics heritage sustain demand for high-integrity temperature monitoring across Alpine distribution lanes. The country's central European position anchors cross-border pharmaceutical transit monitoring between German manufacturing and Italian distribution points. The Basel pharmaceutical cluster and Zurich logistics corridor absorb GDP-validated tracking infrastructure for biologics exports.
Global Cold Chain Tracking and Monitoring Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across hardware, connectivity, and software layers. The vendor base organizes around three strategic archetypes: refrigeration heritage players extending into integrated platforms, precision sensor specialists serving FDA validation protocols, and satellite-terrestrial hybrid connectivity providers. Consolidated buying by vaccine distributors compresses vendor switching cycles toward multi-year platform contracts. Geographic expansion and technology licensing represent the dominant competitive moves as firms seek GDP-validated corridor coverage.
Within the integrated platform tier, Carrier Global Corporation exemplifies refrigeration-to-software diversification across North American and European pharmaceutical corridors. Sensitech Inc. occupies a specialist position in precision temperature data loggers aligned with FDA validation requirements. ORBCOMM Inc. anchors the satellite-terrestrial hybrid connectivity segment, sustaining tracking continuity in remote distribution lanes with cellular coverage gaps.
| Leading Market Players |
|---|
| Carrier Global Corporation |
| Emerson Electric Co. |
| Americold Logistics LLC |
| Lineage Logistics LLC |
| ORBCOMM Inc. |
| Sensitech Inc. |
| Berlinger & Co AG |
| ELPRO-BUCHS AG |
| Controlant |
| Others |
Supply & Pricing Matrix
Backward integration into sensor manufacturing by German and Japanese telemetry specialists anchors both supply security and pricing power for GDP-validated hardware tiers. This captive production of calibrated temperature modules insulates premium vendors from lithium cell volatility while compressing margins for non-integrated competitors serving price-sensitive food distribution segments.
Pricing Analysis
Capacity additions in South Korean and Taiwanese electronics manufacturing are reshaping price floors for cellular LPWAN modules. SaaS-tiered subscription models dominate pharmaceutical logistics contracts, with GDP certification grade and real-time alerting latency as primary price differentiation drivers. Cost compression in standard-tier hardware is intensifying because Bluetooth beacon commoditization accelerates per-shipment economics. Food distributors exhibit highest price sensitivity; biologics shippers with batch-release dependencies accept premium pricing for validated audit trails.
Supply Chain Analysis
Lithium battery supply rests on concentrated East Asian cell production in China, South Korea, and Japan. Sensor fabrication draws from Taiwanese semiconductor foundries and German precision engineering clusters. Single-source vulnerability in rare earth magnet supply for telemetry device motors poses structural risk. Distribution runs through pharmaceutical 3PLs and contract warehouse operators consolidating multi-client platform contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Cold Chain Tracking and Monitoring Market operates as a stable compounder anchored by non-discretionary pharmaceutical compliance spending that resists cyclical compression.
For Market Incumbents: Anchor platform stickiness through deep EMA GDP Chapter 9 validation investments that extend vendor switching costs for European pharmaceutical logistics providers. Consolidate sensor calibration service networks to defend against modular Bluetooth beacon entrants eroding hardware attach rates. Prioritize captive lithium cell supply agreements to mitigate East Asian production concentration risks. For New Entrants and Emerging Players: Mid-tier contract warehouses in India and Sub-Saharan Africa represent underserved buyer archetypes with unmet demand for WHO-prequalified data logger solutions. Target CDSCO-aligned vaccine export corridors where international compliance documentation creates hardware-software integration entry points. Pursue certified calibration partnerships as primary go-to-market angle to bypass incumbent GDP validation moats. For Investors and Strategic Acquirers: Roll-up economics work for regional IoT platform specialists because fragmented contract warehouse operators demand localized SaaS support that global incumbents underserve. Five-to-ten year viability hinges on cellular LPWAN module cost curves and satellite-terrestrial hybrid coverage expansion. Monitor Indian vaccine export volume inflection as signal for emerging corridor infrastructure investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| EMA GDP Chapter 9 Certification Investment | Qualifies hardware for European pharmaceutical corridors requiring mapped temperature validation. |
| Cellular LPWAN Module Integration | Enables real-time exception alerting that displaces standalone loggers in German vaccine networks. |
| Bluetooth Beacon Gateway Deployment | Modularizes last-mile architectures for United States food distributors reducing per-shipment costs. |
| Satellite-Terrestrial Hybrid Connectivity | Sustains tracking continuity across remote Sub-Saharan African distribution lanes with cellular gaps. |
| Cloud Platform SaaS Consolidation | Centralizes multi-client visibility for contract warehouses managing diverse pharmaceutical portfolios. |
Research Methodology
Bottom-up pharmaceutical logistics modeling reconciled against top-down sensor hardware production tracking forms the analytical core of this study. Primary interviews with cold chain operations directors, GDP compliance officers, contract warehouse procurement managers, and telemetry device R&D heads combined with secondary validation from FDA 21 CFR Part 11 guidance documents, EMA GDP Chapter 9 transportation mandates, PMDA ICH Q1A stability guidelines, and customs trade data for temperature monitoring equipment. Triangulation across these sources ensures segmentation integrity.
Input-output matrices map sensor unit shipments through deployment architecture tiers and end-user procurement patterns across the projection horizon. Segmentation dimensions include technology integration depth, application regulatory burden, end-user sophistication tier, and regional compliance cluster. CAGRs derive from calibrated adoption curves for cellular LPWAN modules and cloud platform migration rates among contract warehouse operators. Forecast inputs incorporate lithium battery supply constraints and REACH chemical restriction timelines affecting European hardware qualification cycles.
Underlying measurement precision varies by segment; pharmaceutical applications carry tighter precision than perishable food given documented batch-release dependencies and GDP validation requirements. Forecasts reflect assumptions around EMA enforcement consistency and cellular network coverage expansion in emerging distribution corridors. Material deviation in Indian vaccine export volumes or lithium supply disruption triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cold Chain Packaging
Insulated Food Delivery Bags Market
Cold Chain Packaging
Cold Chain Market
Cold Chain Packaging
Temperature Controlled Packaging Boxes Market
Cold Chain Packaging
Cold Storage Insulated Market
Cold Chain Packaging
Cold Chain Temperature Monitoring Market
Cold Chain Packaging
Food Cold Chain Market
Cold Chain Packaging
North America Food Cold Chain Logistics Market
Cold Chain Packaging
Ice Boxes Market
Cold Chain Packaging
Foam Cooler Box Market
Cold Chain Packaging
Europe Cold Chain Tracking and Monitoring Market
Cold Chain Packaging
Insulated Coolers Market
Cold Chain Packaging
Cold Chain Packaging Pooling and Reverse Logistics Services Market
Cold Chain Packaging
Cold Chain Micro-Fulfillment Hub Networks Market
Cold Chain Packaging
China Cold Chain Market
Cold Chain Packaging
Reusable Cold Chain Packaging Market
Cold Chain Packaging
Latin America Pharmaceutical Cold Chain Logistics Market