
 Insulated Coolers Market | 2026-2036
Insulated Coolers Market Size, Share, and Industry Trends Forecast 2026-2036
Insulated Coolers Market Outlook
The insulated coolers category is recalibrating around a sharp split between premium performance tiers and commodity alternatives. YETI Holdings dominates the high-end segment through brand strength and direct-to-consumer channel control. Igloo Products Corp. competes across mass retail with broad distribution leverage. Engel Coolers anchors the marine and overland specialty niche with purpose-built durability.
Insulated coolers are thermally insulated enclosures engineered with polyurethane foam cores, rotomolded polyethylene shells, and gasket-sealed lids to maintain sub-ambient temperatures for perishable goods. Hard coolers command the largest revenue pool due to extended ice retention and structural longevity, while soft coolers represent the fastest-expanding segment among urban consumers seeking collapsible portability. Stainless steel variants capture outsized margins in commercial foodservice and contractor end-use despite smaller volumes.
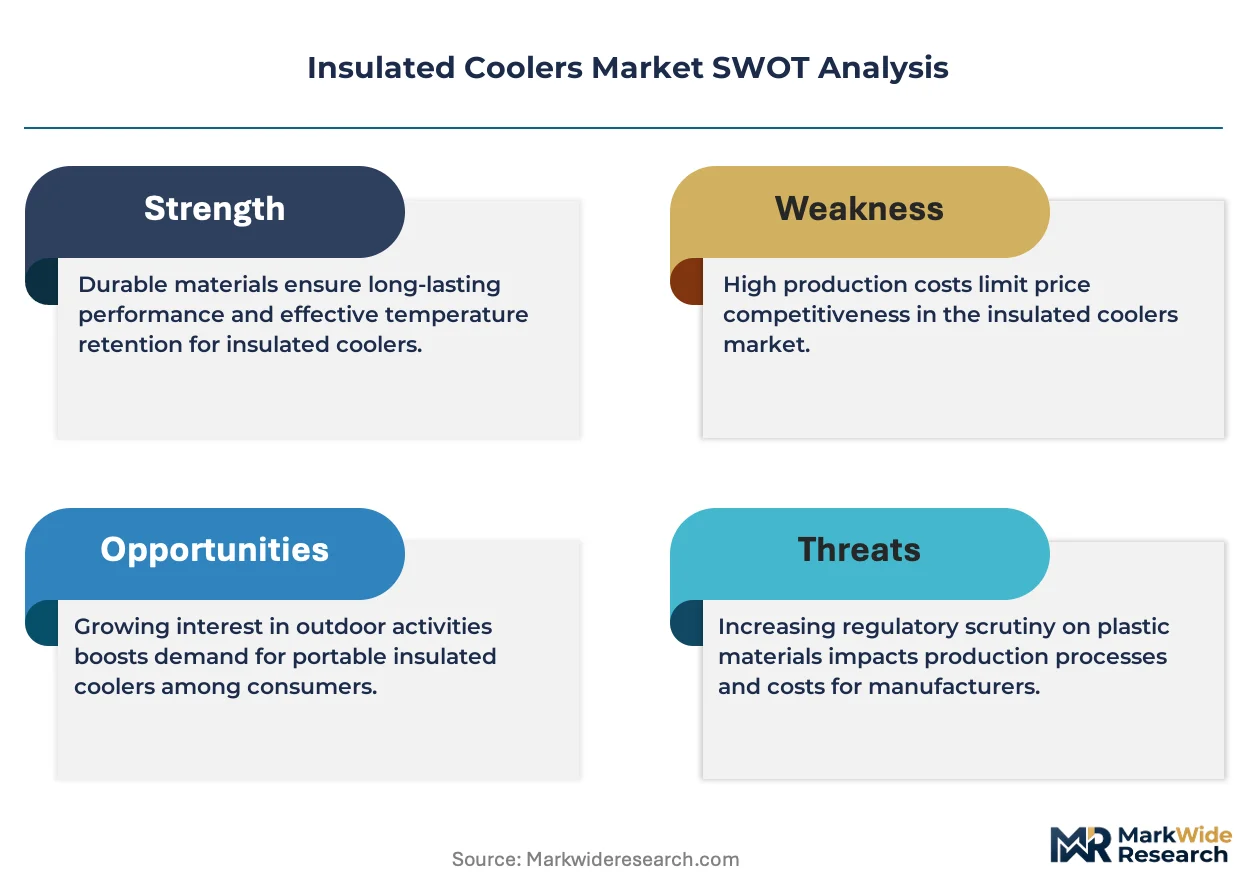
The US EPA regulates foam-blowing agents under SNAP, while the EU F-Gas Regulation constrains synthetic insulation gases, and California's CARB imposes additional VOC limits on adhesive and coating processes. These frameworks elevate compliance costs for multinational manufacturers but simultaneously create market access barriers that favor established suppliers with certified supply chains. Stakeholders must monitor evolving state-level refrigerant restrictions and biobased material certifications as the next axis of product differentiation.
Market Dynamics
The EPA's SNAP program is forcing hydrocarbon-based insulation transitions while marine and overland recreation segments demand rotomolded durability upgrades. Manufacturers face compressed margins from foam-blowing agent compliance costs.
Growth Catalysts
- Refrigerant phase-down mandates:The EPA SNAP program and EU F-Gas Regulation are accelerating hydrocarbon foam adoption. Certified suppliers gain market access barriers against uncertified imports.
- Marine recreation expansion:Coastal boating registrations in Florida and Gulf states sustain replacement cycles for corrosion-resistant hardware. Saltwater-grade gasket systems command premium positioning.
- Tailgating culture maturation:Stadium-adjacent entertainment precincts in Texas and Southeastern states normalize multi-day ice retention as baseline expectation. Rotomolded construction displaces injection-molded alternatives.
Market Restraints
- Polyurethane feedstock volatility:MDI and polyol pricing swings compress margin predictability for mid-tier manufacturers. Long-term supply agreements favor integrated chemical producers.
- Rotomolding capacity concentration:Domestic rotational molding infrastructure clusters in Ohio and Iowa, creating geographic supply risk. Tooling lead times extend 14-20 weeks during peak season.
- Soft-sided substitution threat:Advanced fabric laminates with aerogel insulation challenge hard-shell portability advantages. Urban consumers prioritize collapsible storage over ice duration.
Strategic Opportunities
- Commercial foodservice white space:NSF-certified stainless steel variants remain underpenetrated in mobile catering and construction site provisioning. Health department compliance creates specification stickiness.
- Biobased certification tailwinds:USDA BioPreferred and emerging state procurement mandates favor plant-derived foam feedstocks. Early certifiers access institutional purchasing channels.
- Direct-to-consumer channel maturation:Owned e-commerce platforms bypass retail margin stacking. Subscription-based accessory replenishment locks in recurring cooler ecosystem revenue.
Industry Challenges
- Thermal engineering talent scarcity:Computational fluid dynamics expertise for optimized air-gap design concentrates among appliance and aerospace migrants. Compensation inflation hits mid-cap specialists hardest.
- Multi-certification timeline compression:Concurrent EPA SNAP, California CARB VOC, and EU REACH compliance extends product development cycles. Testing queue bottlenecks delay seasonal launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insulated Coolers Market |
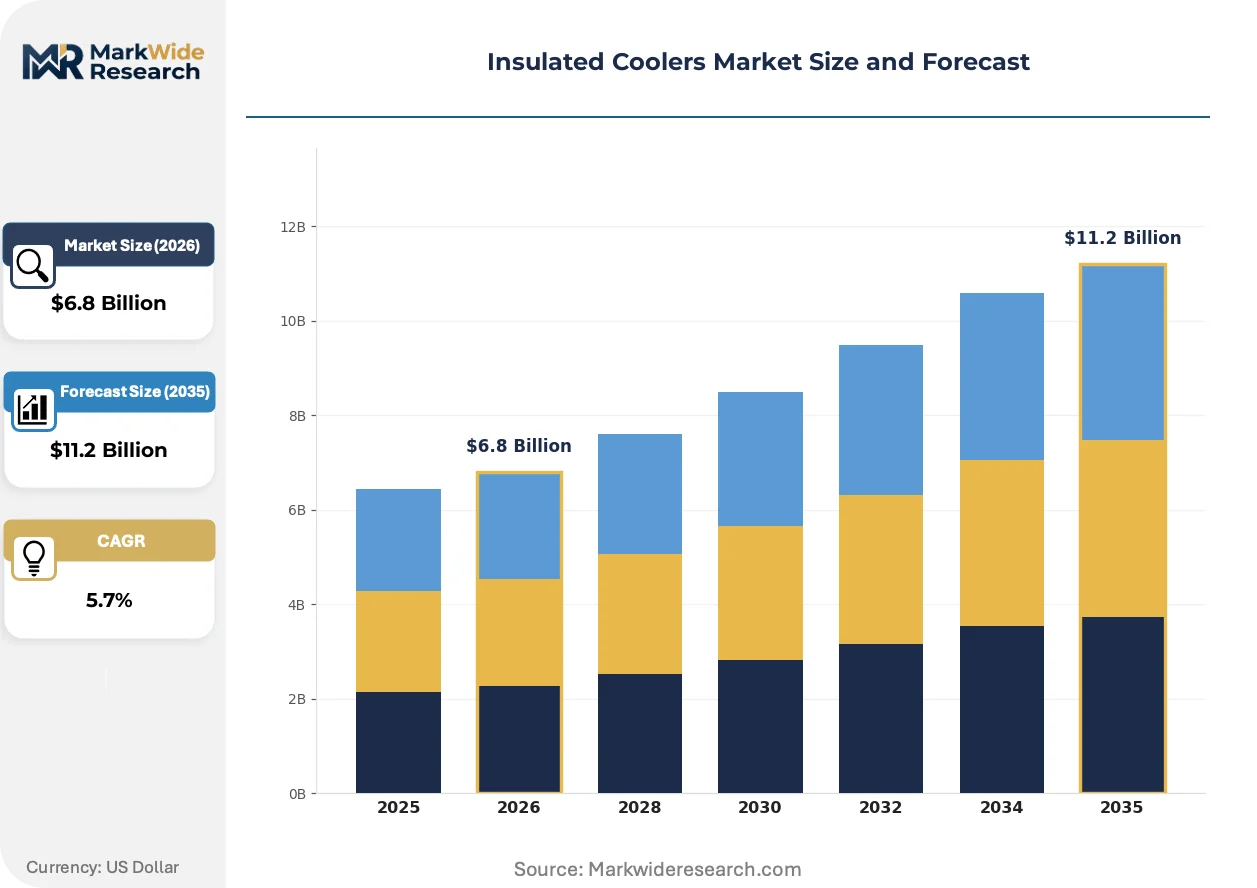
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hard Coolers, Soft Coolers, Ice Chests, Beverage Dispensers Material: Polyethylene, Foam, Stainless Steel, Rubber Application: Camping, Sports Events, Fishing, Picnics End User: Consumers, Retailers, Event Organizers, Contractors |
| Companies Covered | YETI Holdings, Igloo Products Corp., The Coleman Company, Pelican Products, Engel Coolers, Grizzly Coolers, Dometic Group AB, Stanley Black & Decker, Orca Coolers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insulated Coolers Market Strategic Shifts
Active insulation chemistry, regulatory compliance architecture, and channel restructuring are converging to redefine product specifications and go-to-market economics. Material science advances now outpace traditional durability marketing.
Vacuum-insulated panel technology is overtaking conventional polyurethane foam in premium expedition-grade units. Alpine guides and remote medical transport operators specify VIP cores for 7-10 day passive temperature maintenance. The structural consequence is a bifurcation where foam-based products compress toward commodity positioning while vacuum systems capture expedition and pharmaceutical cold chain adjacencies.
The EU F-Gas Regulation's escalating GWP restrictions are forcing reformulation of blowing agents across European manufacturing footprints. Hydrocarbon and HFO alternatives require retooling of pressurized dispensing systems and fire suppression infrastructure. Marine and overland specialty producers with EU export exposure are consolidating certification under single notified bodies to streamline cross-border compliance.
Buyer preference for specification transparency is fragmenting traditional retail relationships. Independent testing laboratory certifications and documented ice-retention protocols now precede brand consideration in commercial procurement. This pattern concentrates among Texas and California-based catering operators who face liability exposure from temperature excursions in outdoor foodservice environments.
Insulated Coolers Market Segmentation
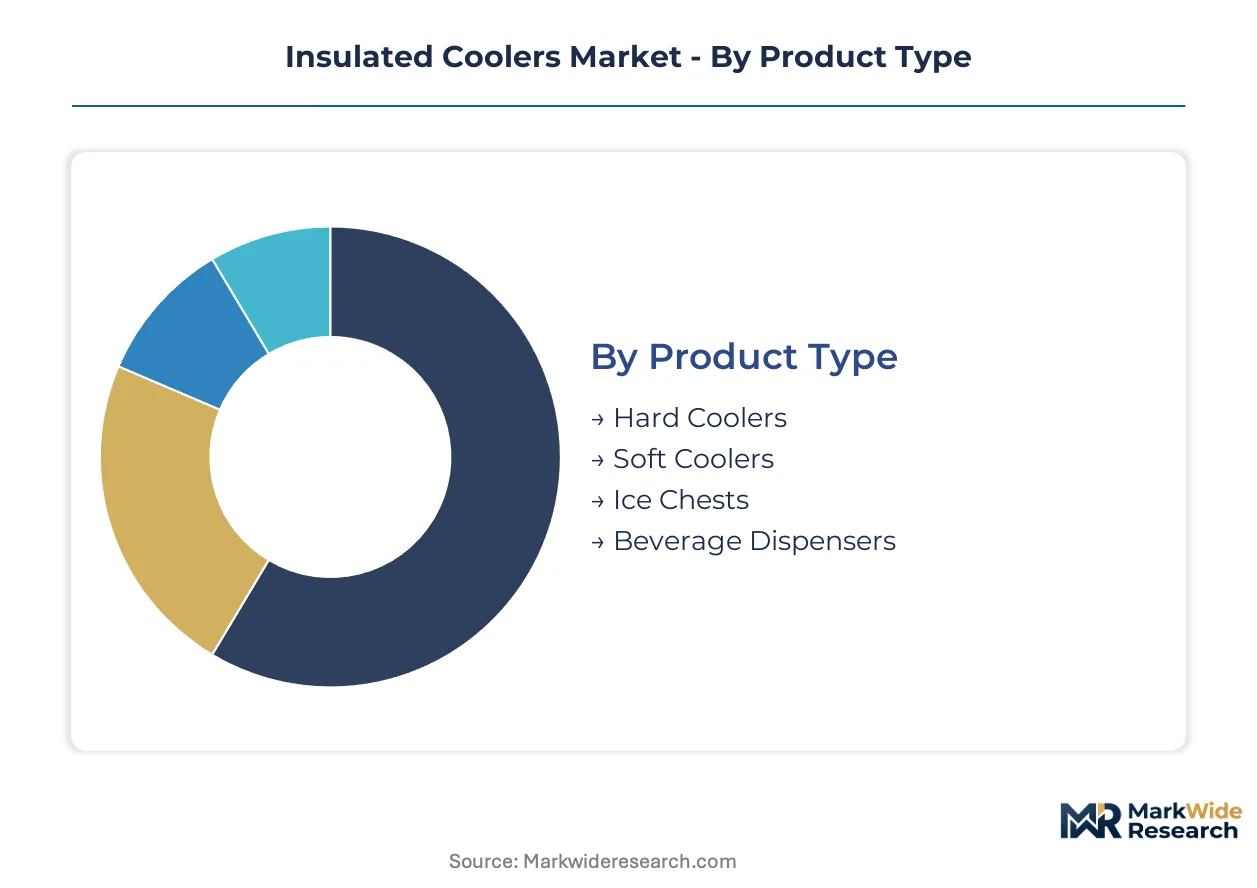
Segmentation in the insulated coolers market reveals divergent engineering priorities across use cases. Hard-shell durability competes against collapsible portability, while material selection determines regulatory compliance pathways and thermal performance ceilings.
Product Type:
The customization-to-standardization spectrum spans from expedition-grade rotomolded units to commodity injection-molded disposables, with portability requirements driving the middle ground.
- Hard Coolers:Rotomolded polyethylene shells with polyurethane foam cores deliver structural rigidity for multi-day ice retention. Demand clusters among Florida and Gulf Coast boating operators seeking saltwater-grade corrosion resistance. EPA SNAP-compliant hydrocarbon foam transitions elevate manufacturing costs but create specification barriers against uncertified imports.
- Soft Coolers:Fabric-laminated constructions with closed-cell foam or aerogel insulation prioritize collapsible storage over thermal duration. Urban consumers in Texas metropolitan areas favor these for stadium-adjacent tailgating where space constraints outweigh ice-retention demands. Advanced textile barriers now challenge hard-shell portability advantages.
- Ice Chests:Injection-molded commodity variants serve price-sensitive bulk purchasers with single-day thermal performance.
- Beverage Dispensers:Insulated reservoir systems with tap mechanisms target mobile catering and construction site hydration stations requiring NSF certification compliance.
Most installed capacity flows through Hard Coolers. Expansion is steepest in Soft Coolers.
Material:
Cost tier stratification separates premium thermal performance from mass-market accessibility, with certification requirements reshaping supplier qualification.
- Polyethylene:Rotomolded and injection-graded resins form the dominant shell substrate, with linear low-density variants balancing impact resistance against weight. Rotomolding infrastructure concentrates in Ohio and Iowa, creating geographic supply risk during seasonal demand surges.
- Foam:Polyurethane systems with hydrocarbon or HFO blowing agents constitute the thermal barrier, with EU F-Gas Regulation compliance forcing European manufacturing retooling. USDA BioPreferred certification for plant-derived feedstocks is emerging as a procurement differentiator in institutional channels.
- Stainless Steel:Marine-grade 304 and 316 alloys command outsized margins in commercial foodservice despite smaller volumes, with NSF certification creating specification stickiness among health department-regulated operators.
- Rubber:EPDM and silicone gasket compounds seal lid interfaces, with saltwater-grade formulations capturing premium positioning in coastal marine segments.
Volume leadership sits with Polyethylene. Stainless Steel claims the steepest margin expansion trajectory.
Application:
Customer type differentiation separates recreational enthusiasts from commercial operators, with liability exposure driving specification divergence.
- Camping:Multi-day backcountry expeditions demand expedition-grade vacuum-insulated panels or high-density foam systems. Alpine guide services and remote medical transport operators specify 7-10 day passive temperature maintenance for pharmaceutical and biological sample preservation.
- Sports Events:Stadium-adjacent entertainment precincts in Texas and Southeastern states normalize rotomolded construction as baseline expectation for multi-day ice retention. Team equipment managers prioritize durability over weight in transport scenarios.
- Fishing:Saltwater and freshwater angling segments require corrosion-resistant hardware with fish-ruler integration and tie-down compatibility for vessel deck mounting.
- Picnics:Day-trip recreational use favors collapsible soft-sided alternatives or lightweight injection-molded units with minimal thermal duration requirements.
Replacement cycle frequency peaks in Sports Events. Technical specification intensity concentrates in Camping.
End User:
Margin structure varies sharply across procurement sophistication, with institutional buyers leveraging certification requirements against fragmented consumer price sensitivity.
- Consumers:Direct purchasers exhibit brand loyalty toward direct-to-consumer platforms, with subscription-based accessory replenishment models locking in recurring ecosystem revenue. Independent testing laboratory certifications now precede brand consideration in premium segments.
- Retailers:Mass merchandisers and specialty outdoor channels demand broad SKU coverage with seasonal inventory flexibility, compressing manufacturer margins through volume commitments and promotional funding requirements.
- Event Organizers:Mobile catering operators in California and Texas face liability exposure from temperature excursions, driving procurement toward documented ice-retention protocols and NSF-certified stainless steel variants.
- Contractors:Construction site provisioning requires jobsite durability with health department compliance, favoring specification stickiness among institutional purchasers with recurring replacement schedules.
Procurement volume aggregates through Retailers. Specification-driven margin capture concentrates among Event Organizers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rotational molding technicians and polyurethane foam chemists cluster disproportionately in the American Midwest and coastal manufacturing corridors, anchoring production capacity near raw material suppliers and recreational demand centers.
United States
Florida and Gulf Coast boating registrations sustain replacement demand for saltwater-grade hardware, while Texas stadium-adjacent entertainment precincts normalize multi-day ice retention as baseline expectation. EPA SNAP program mandates on hydrocarbon foam-blowing agents elevate compliance costs but create specification barriers against uncertified imports. Ohio and Iowa host concentrated rotational molding infrastructure, with tooling lead times extending 14-20 weeks during seasonal surges.
Canada
Remote wilderness guiding operations and northern resource extraction camps drive expedition-grade vacuum-insulated panel specification for pharmaceutical and biological sample preservation. Health Canada and PMRA coordinate with EPA on aligned refrigerant phase-down timelines, reducing cross-border product variant complexity. Ontario's chemical corridor supplies polyurethane feedstocks to Midwest US fabricators, creating integrated North American supply chain dependencies.
Germany
EU F-Gas Regulation's escalating GWP restrictions force reformulation of blowing agents across European manufacturing footprints, requiring retooling of pressurized dispensing systems and fire suppression infrastructure. Marine specialty producers with EU export exposure consolidate certification under single notified bodies to streamline cross-border compliance. Bavaria's industrial equipment sector supplies precision molding machinery to global cooler manufacturers.
China
Dual carbon goals and MEE enforcement accelerate domestic hydrocarbon foam adoption, with NMPA-aligned medical cold chain specifications creating quality tier differentiation. Yangtze River Delta fabricators serve as contract manufacturers for Western brands seeking cost-competitive rotomolded shells. GB standards on insulation materials increasingly reference EU F-Gas thresholds, anticipating future export market alignment.
Australia
TGA-regulated pharmaceutical distribution networks specify expedition-grade passive cooling for remote medical transport, overlapping with alpine guide service procurement patterns. Coastal marine recreation in Queensland and Western Australia sustains corrosion-resistant hardware demand comparable to Florida market dynamics. Domestic rotational molding capacity remains limited, creating import dependency on US and Southeast Asian suppliers.
Insulated Coolers Market Competitive Environment
Capital-heavy producers compete with asset-light designers across a bifurcated structure where premium performance tiers command outsized margins against commodity alternatives. The market consolidates around three strategic archetypes: direct-to-consumer brand builders leveraging subscription ecosystem lock-in, mass retail distributors optimizing seasonal SKU breadth, and marine-specialist fabricators capturing specification stickiness through saltwater-grade certification. Dominant competitive moves include hydrocarbon foam certification consolidation to erect import barriers and direct-to-consumer channel bypass of retail margin stacking.
Within the premium-tier vector, YETI Holdings and Engel Coolers occupy positions anchored by brand equity and purpose-built durability respectively, while Igloo Products Corp. exemplifies mass-market distribution leverage across broad retail footprints. These three entities collectively represent the archetype spectrum from direct-to-consumer control through specialty marine positioning to commodity scale efficiency, with each configuration demanding distinct capital intensity and margin structure trade-offs.
| Leading Market Players |
|---|
| YETI Holdings |
| Igloo Products Corp. |
| The Coleman Company |
| Pelican Products |
| Engel Coolers |
| Grizzly Coolers |
| Dometic Group AB |
| Stanley Black & Decker |
| Orca Coolers |
| Others |
Value Chain & Pricing Dynamics
MDI and polyol feedstock indices cascade through rotomolded shell fabrication into three distinct pricing tiers, with hydrocarbon foam certification costs compressing mid-tier margins while premium vacuum-insulated panels capture expedition-grade premiums. Polyurethane pricing volatility concentrates pricing power among integrated chemical producers with long-term supply agreements, leaving contract manufacturers exposed to spot market swings.
Pricing Analysis
Accessories and warranty extensions bundle with core units at the premium tier, while standard configurations compete on unbundled transactional pricing. Three-tier pricing structure across premium, standard, and economy levels separates NSF-certified stainless steel variants from rotomolded polyethylene workhorses and injection-molded disposables. Price differentiation rests on certification grade and geographic delivery cost, with EPA SNAP compliance elevating hydrocarbon-foam-certified products above uncertified imports. Cost compression in the mid-tier intensifies because MDI feedstock volatility erodes contract manufacturer margins. Mass retail channels exhibit highest price sensitivity, while commercial foodservice operators prioritize specification adherence over unit cost.
Supply Chain Analysis
Inbound freight costs from Ohio and Iowa rotational molding clusters to coastal distribution centers constitute a meaningful landed cost component, with seasonal surge pricing compressing margins during peak demand windows. Manufacturing gravity centers on the United States, China, and Germany, with Yangtze River Delta fabricators supplying contract rotomolded shells to Western brands. Supply chains draw from polyurethane foam systems, polyethylene resins, and marine-grade stainless steel alloys. Single-source vulnerability concentrates in domestic rotational molding infrastructure, where tooling lead time bottlenecks during seasonal peaks create fulfillment risk. Distribution runs through mass merchandisers, specialty outdoor retailers, and owned direct-to-consumer platforms with divergent margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The insulated coolers market functions as a regulatory compounder, with EPA SNAP refrigerant phase-down mandates and EU F-Gas Regulation compliance timelines forcing continuous product reformulation that favors certified incumbents with established testing relationships.
For Market Incumbents: Extend hydrocarbon foam certification coverage across full product portfolios to erect specification barriers against uncertified imports. Consolidate rotational molding capacity in Ohio and Iowa through equipment upgrades that compress tooling lead times. Certification investment serves as the priority lever against emerging fabricators lacking EPA SNAP testing relationships. For New Entrants and Emerging Players: Mobile catering operators in Texas and California represent an underserved buyer archetype with unmet demand for NSF-certified stainless steel variants and documented ice-retention protocols. Expedition-grade vacuum-insulated panels for alpine guide services and remote medical transport offer the most penetrable premium segment. A direct-to-consumer platform with subscription-based accessory replenishment provides the optimal go-to-market angle to bypass retail margin stacking. For Investors and Strategic Acquirers: Asymmetric upside sits with marine-specialist fabricators possessing saltwater-grade certification and established relationships with Florida and Gulf Coast boating operators. Long-term viability hinges on regulatory compliance architecture rather than brand marketing spend across the projection horizon. Acquisition targets should demonstrate consolidated certification under single notified bodies for EU export exposure. The signal to watch is USDA BioPreferred certification adoption rates among institutional procurement channels.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrocarbon Foam Certification Consolidation | EPA SNAP compliance creates specification barriers that exclude uncertified import competition from mass retail channels. |
| Direct-to-Consumer Channel Expansion | Owned e-commerce platforms bypass retail margin stacking and enable subscription-based accessory replenishment revenue. |
| NSF-Certified Stainless Steel Line Extension | Health department compliance creates specification stickiness among California and Texas mobile catering operators. |
| USDA BioPreferred Certification Investment | Plant-derived foam feedstocks unlock institutional purchasing channels with emerging state procurement mandates. |
| Vacuum-Insulated Panel Technology Integration | Alpine guide services and remote medical transport operators specify VIP cores for 7-10 day passive temperature maintenance. |
Study Parameters
Multiple input streams — executive interviews with rotomolded shell manufacturers, procurement discussions with commercial foodservice operators, and regulatory compliance tracking across EPA and EU frameworks — were reconciled against secondary validation. Primary engagement encompassed rotational molding plant managers, polyurethane foam chemists, category buyers at mass retailers, and health department inspectors. Secondary sources included EPA SNAP submissions, EU F-Gas Regulation implementation guidance, customs trade data for polyethylene resin flows, and SEC filings from publicly traded outdoor recreation companies. Bottom-up unit economics triangulated against top-down category sizing from retail audit databases.
Historical shipment patterns cross-referenced against panel input from industry participants anchored the analytical framework across the modeling period. Segmentation dimensions encompassed product type, material composition, application use case, and end-user procurement sophistication. CAGRs derived from curve-fitting approaches applied to disclosed production capacity and replacement cycle frequencies. Industry-specific forecast inputs included Florida and Gulf Coast boating registration trends and Texas stadium-adjacent entertainment precinct development pipelines.
Underlying measurement precision varies by segment; rotomolded hard coolers and NSF-certified stainless steel variants carry tighter precision than commodity injection-molded disposables due to concentrated supplier disclosure. Forecasts reflect assumptions regarding EPA SNAP implementation timelines and EU F-Gas Regulation enforcement intensity that could revise projections if regulatory pacing accelerates or delays. Stakeholders should weight assumptions against their own operating context and supply chain exposure to polyurethane feedstock volatility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cold Chain Packaging
Cold Chain Temperature Monitoring Market
Cold Chain Packaging
Cold Box Module Market
Cold Chain Packaging
Latin America Pharmaceutical Cold Chain Logistics Market
Cold Chain Packaging
Foam Cooler Box Market
Cold Chain Packaging
Food Cold Chain Market
Cold Chain Packaging
Reusable Cold Chain Packaging Market
Cold Chain Packaging
Cold Chain Market
Cold Chain Packaging
Europe Cold Chain Tracking and Monitoring Market
Cold Chain Packaging
Cold Chain Integrity and Shock Monitoring Test Devices Market
Cold Chain Packaging
Fish Boxes Market
Cold Chain Packaging
Biopharma Cold Chain Packaging Market
Cold Chain Packaging
Cold Chain Equipment Market
Cold Chain Packaging
Global Cold Chain Tracking and Monitoring Market
Cold Chain Packaging
Pharmaceutical Cold Chain Packaging Market
Cold Chain Packaging
Cold Chain Packaging Market
Cold Chain Packaging
Cooling Boxes Market