
 Cryo Box Market | 2026-2036
Cryo Box Market Size, Share, and Industry Trends Forecast 2026-2036
Cryo Box Market Intelligence
Cellular therapy workflows are pivoting toward higher-capacity cryogenic storage systems as autologous and allogeneic cell treatments scale. Thermo Fisher Scientific leverages its integrated cold-chain portfolio to anchor institutional procurement contracts across North American biobanks. Greiner Bio-One differentiates through specialized polypropylene formulations optimized for ultra-low temperature mechanical stability. Eppendorf AG competes on precision-molded rack compatibility with automated liquid nitrogen retrieval systems.
A cryo box is a thermally insulated container engineered to maintain biological specimens at cryogenic temperatures, typically constructed from polypropylene or aluminum with integrated grid matrices for vial organization and thermal mass distribution. The product category spans standard, custom, disposable, and portable configurations, with custom variants capturing premium margin pools as cell therapy protocols demand patient-specific rack geometries. Material selection stratifies along thermal conductivity requirements, where polypropylene dominates high-throughput biobanking for its dielectric properties and cost scalability, while stainless steel persists in pharmaceutical distribution for impact resistance during transit.
FDA 21 CFR Part 1271 governs human cells and tissues for cellular therapy applications, directly shaping cryo box validation requirements for temperature excursion documentation. EPA guidelines on fluorinated greenhouse gases constrain insulation gas choices, while ISO 20387 biobanking standards mandate traceable sample storage conditions across healthcare and research facilities. Stakeholders must monitor evolving cell therapy regulatory harmonization between FDA and EMA frameworks, as divergent cold-chain validation protocols will determine product certification investments and market access trajectories.
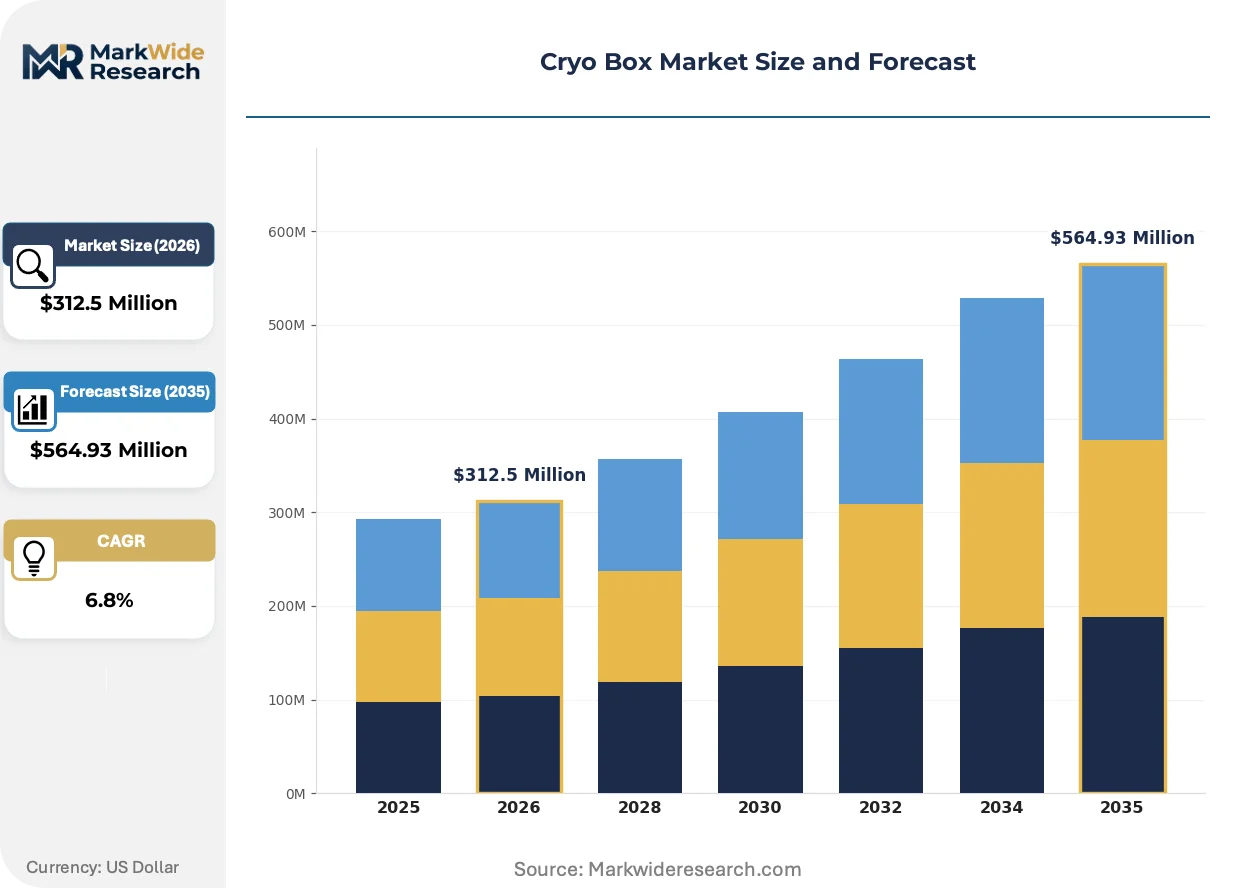
Market Dynamics
Cell therapy manufacturing scale-up is compressing cryo box procurement cycles from annual tenders to multi-year framework agreements as biobanks consolidate vendor relationships around integrated cold-chain validation.
Growth Catalysts
- ISO 20387 biobanking standards:Mandatory traceable storage conditions across healthcare and research facilities are forcing infrastructure upgrades. European biorepositories are prioritizing certified cryogenic systems to maintain accreditation.
- Polypropylene composite engineering:Advanced formulations with ultra-low temperature mechanical stability are extending vial integrity windows. High-throughput biobanking operations in Germany and Japan are standardizing on these materials.
- Autologous cell therapy protocols:Patient-specific manufacturing workflows require dedicated storage geometries. United States-based regenerative medicine centers are driving demand for custom rack configurations.
Market Restraints
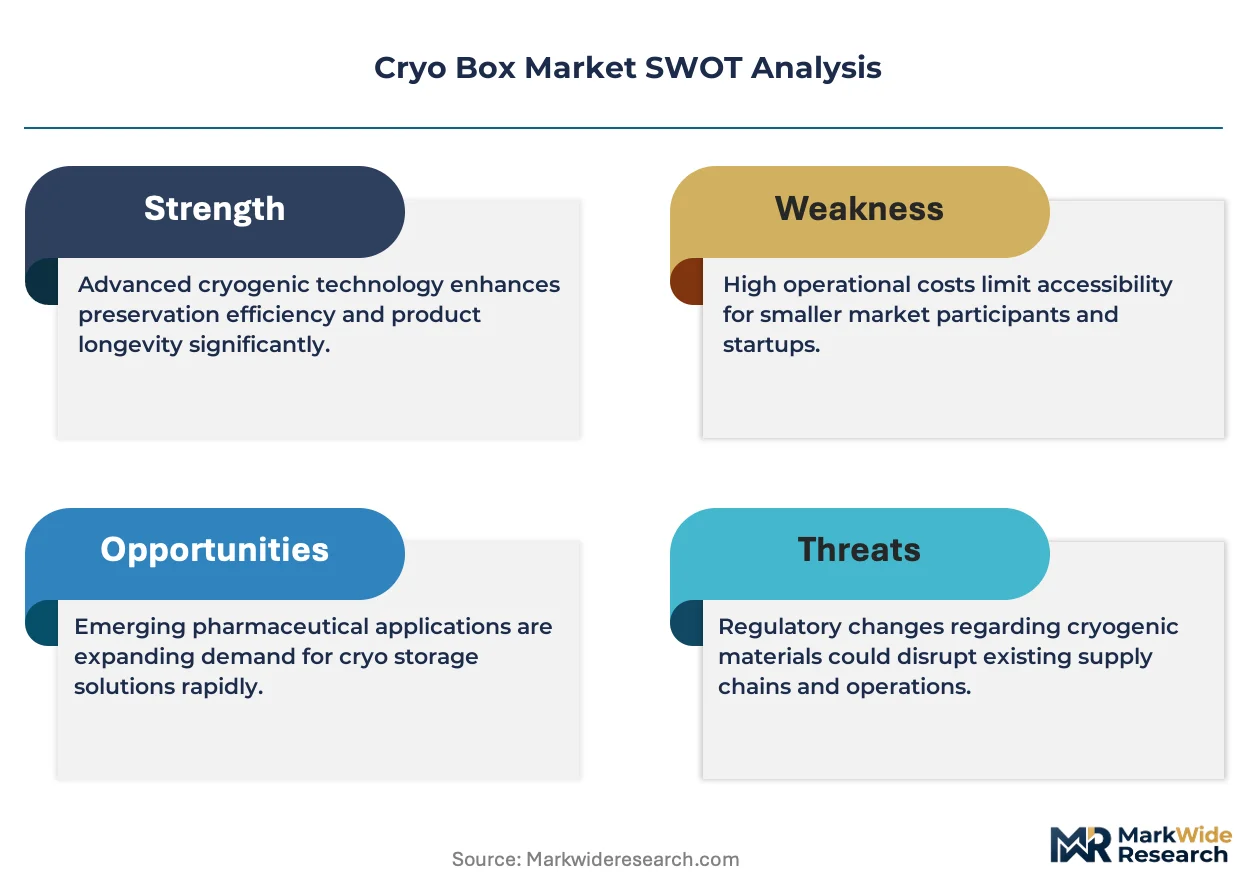
- Specialized polymer supply concentration:Medical-grade polypropylene feedstock is concentrated among a limited set of European chemical suppliers. Disruption risks from energy cost volatility constrain margin flexibility for cryo box manufacturers.
- F-Gas Regulation insulation constraints:EPA guidelines and EU F-Gas Regulation are restricting fluorinated greenhouse gas choices for vacuum panel fills. Thermal performance engineering faces higher compliance costs.
- Liquid nitrogen infrastructure dependency:Cryogenic storage requires proximity to reliable liquid nitrogen supply networks. Geographic gaps in distribution infrastructure limit deployment in secondary research markets.
Strategic Opportunities
- Portable cryogenic systems:Point-of-care cell therapy administration is creating demand for mobile storage units. Japan's decentralized healthcare delivery model offers a testbed for portable configurations.
- Automated retrieval integration:Convergence of precision-molded rack geometries with robotic liquid nitrogen handling systems is opening new procurement channels. Biobanks in the United States are piloting fully automated storage facilities.
- EMA-FDA regulatory harmonization:Converging cold-chain validation protocols between European and American regulators will streamline certification investments. Dual-compliant product lines will capture premium positioning.
Industry Challenges
- Cryogenic engineering talent scarcity:Specialized expertise in ultra-low temperature materials science and thermal modeling is concentrated among a limited pool of professionals. Recruitment competition from aerospace and energy sectors constrains R&D velocity.
- Legacy inventory system integration:Automated cryo box retrieval systems must interface with decades-old biobank sample management databases. Middleware development timelines extend deployment cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cryo Box Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $564.93 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Cryo Boxes, Custom Cryo Boxes, Disposable Cryo Boxes, Portable Cryo Boxes Material: Polypropylene, Polyethylene, Aluminum, Stainless Steel End User: Healthcare Facilities, Research Laboratories, Biobanks, Pharmaceutical Companies Application: Sample Storage, Vaccine Preservation, Biological Research, Cellular Therapy |
| Companies Covered | Merck KGaA, Greiner Bio-One, Thermo Fisher Scientific, Heathrow Scientific, Biocision LLC, Corning Incorporated, VWR International, DWK Life Sciences, Eppendorf AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cryo Box Market Strategic Shifts & Innovations
Materials science breakthroughs and regulatory convergence are redefining performance benchmarks. Three developments are compressing product development cycles and reshaping vendor selection criteria.
Vacuum-insulated panel technology is expanding into pharmaceutical distribution networks as shippers demand extended hold times for international cell therapy shipments. Cold-chain logistics providers in Germany are adopting these panels for lane validation studies. The structural consequence is compression of passive container performance gaps against active refrigeration systems.
EMA's evolving guidance on advanced therapy medicinal products is tightening temperature excursion documentation requirements for cryogenic storage. European cell therapy manufacturers must now validate every thermal container across the distribution chain. Custom cryo box configurations with embedded data loggers are capturing procurement preference.
Biobank procurement committees are consolidating vendor relationships around full cold-chain service providers rather than discrete equipment purchases. Integrated storage, monitoring, and retrieval contracts are displacing component-based buying in the United States. Academic medical centers with limited in-house engineering staff are driving this behavioral shift.
Cryo Box Market Segmentation
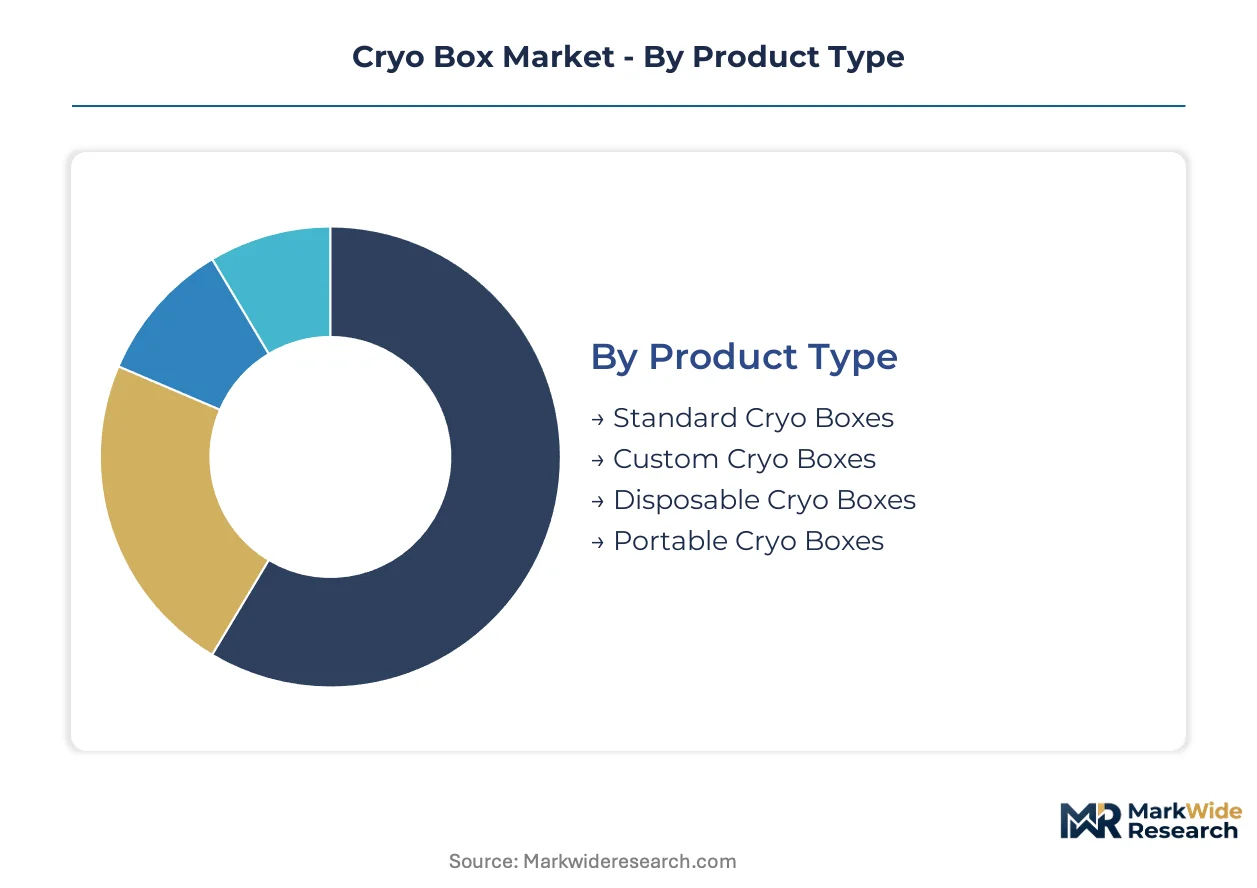
Cryo box procurement patterns diverge sharply across product configurations and end-use contexts. Certification requirements from FDA and EMA vary by intended application, creating tiered compliance burdens that reshape vendor selection criteria and margin structures.
Product Type:
FDA 21 CFR Part 1271 and ISO 20387 impose distinct validation protocols on each configuration, with custom variants facing the most intensive documentation requirements.
- Standard Cryo Boxes:Grid-molded polypropylene containers with fixed rack geometries dominate high-throughput biobanking in Germany. These units face streamlined ISO 20387 certification paths due to established thermal performance benchmarks.
- Custom Cryo Boxes:Patient-specific rack configurations engineered for autologous cell therapy workflows command premium positioning. United States regenerative medicine centers require these geometries to match proprietary vial formats and automated retrieval systems.
- Disposable Cryo Boxes:Single-use polypropylene variants reduce cross-contamination risks in multi-site clinical trials.
- Portable Cryo Boxes:Vacuum-insulated mobile units serve point-of-care cell therapy administration in Japan's decentralized healthcare delivery model.
Standard cryo boxes sit at the top of the volume ranking, with portable configurations climbing the fastest.
Material:
Cost tiers stratify sharply, with medical-grade polymers commanding 3-4x the per-unit pricing of industrial aluminum alternatives.
- Polypropylene:Dielectric properties and ultra-low temperature mechanical stability make this the default for high-throughput biobanking. German and Japanese facilities standardize on advanced composite formulations that extend vial integrity windows during nitrogen vapor phase transitions.
- Polyethylene:Lower thermal conductivity than polypropylene suits short-duration vaccine preservation workflows. Research laboratories in the United States deploy these for intermediate-temperature distribution lanes.
- Aluminum:Lightweight conductive alloys serve portable configurations where mass reduction outweighs thermal retention priorities.
- Stainless Steel:Impact-resistant grades persist in pharmaceutical distribution networks where transit durability dominates specification sheets.
Polypropylene dominates procurement volumes, with stainless steel gaining share fastest in international distribution applications.
End User:
Customer type determines contract structure, with biobanks consolidating around multi-year framework agreements while research laboratories retain spot-buying patterns.
- Healthcare Facilities:Hospital-based cell therapy programs require dual-compliant FDA-EMA configurations for cross-border patient treatments. These buyers prioritize integrated cold-chain service contracts over discrete equipment purchases.
- Research Laboratories:Academic medical centers with limited engineering staff drive demand for vendor-managed storage and monitoring solutions. Procurement committees in the United States favor full-service partnerships.
- Biobanks:European repositories prioritize ISO 20387-certified systems to maintain accreditation.
- Pharmaceutical Companies:Cell therapy manufacturers validate every thermal container across distribution chains per EMA guidance on advanced therapy medicinal products.
Biobanks sit at the top of the volume ranking, with pharmaceutical companies climbing the fastest as commercial cell therapies scale manufacturing.
Application:
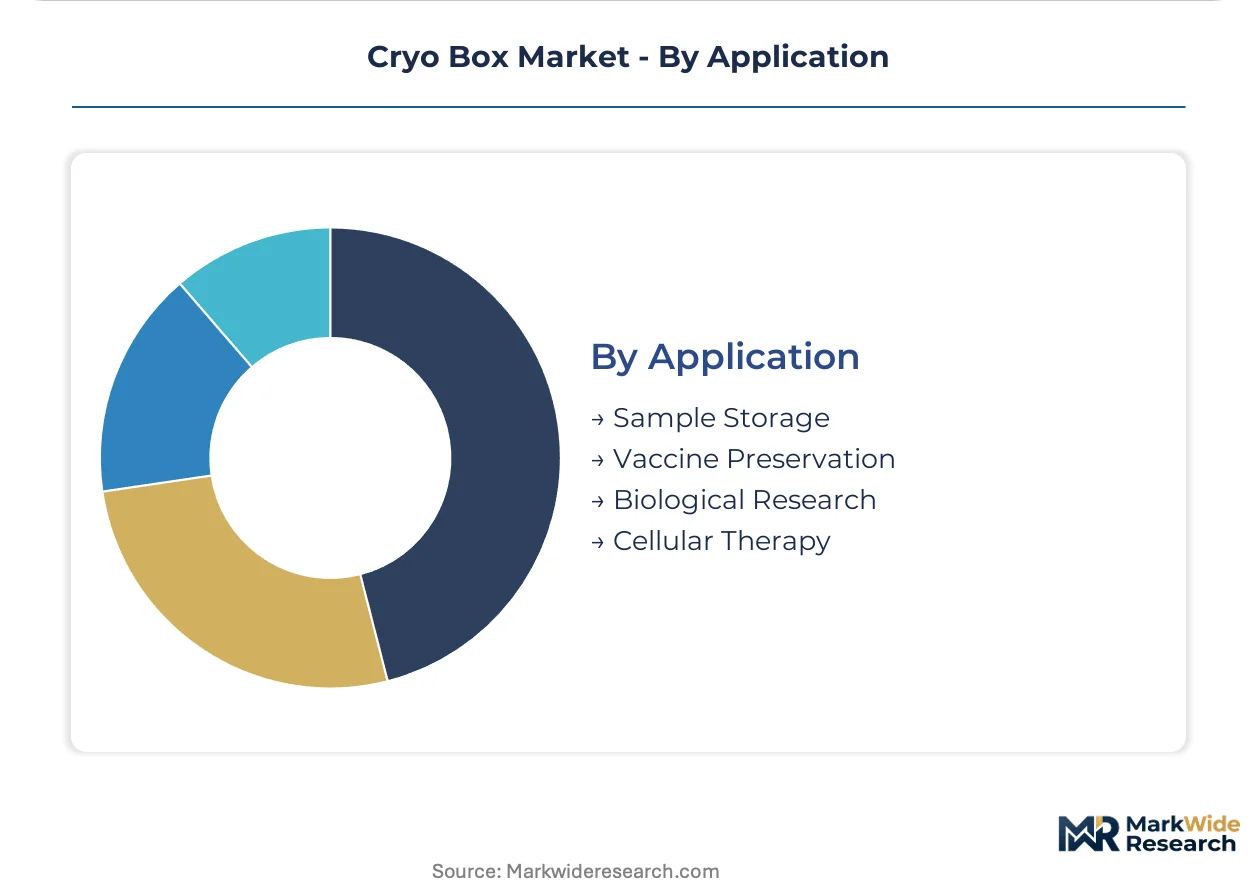
Application context dictates performance thresholds, with cellular therapy demanding the most stringent temperature excursion documentation.
- Sample Storage:Long-term biorepository applications require nitrogen vapor phase stability across decades. German facilities specify polypropylene composites optimized for ultra-low temperature mechanical retention.
- Vaccine Preservation:Intermediate cryogenic lanes for mRNA and viral vector products require shorter hold times with rapid recovery protocols. Distribution networks favor portable configurations with embedded data loggers.
- Biological Research:Academic laboratories prioritize cost scalability over extended thermal performance.
- Cellular Therapy:Autologous and allogeneic treatments mandate patient-specific traceability. Custom rack geometries with integrated monitoring capture procurement preference in the United States.
Sample storage sits at the top of the volume ranking, with cellular therapy climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German biobanking infrastructure anchors cryogenic storage demand in Europe, with ISO 20387 accreditation mandates driving systematic equipment upgrades across research networks.
United States
FDA 21 CFR Part 1271 governs human cells and tissues for autologous cell therapy workflows, compelling regenerative medicine centers in Boston and San Francisco to validate patient-specific cryo box configurations. The National Institutes of Health funds biorepository expansion through its National Cancer Institute programs.
Germany
Advanced polypropylene composite formulations with ultra-low temperature mechanical stability dominate procurement at the Max Planck Institute network and Charité Berlin. The EU F-Gas Regulation constrains vacuum panel insulation choices, elevating compliance engineering costs for domestic manufacturers.
Japan
Point-of-care cell therapy administration drives portable cryogenic system adoption under METI guidance on decentralized healthcare delivery. The Kansai region, centered on Osaka University Hospital, pilots mobile storage units for allogeneic treatment protocols.
United Kingdom
EMA guidance on advanced therapy medicinal products tightens temperature excursion documentation for London-based cell therapy manufacturers. The Francis Crick Institute consolidates vendor relationships around integrated cold-chain service contracts.
China
NMPA biobanking standards accelerate infrastructure investment at Shanghai Zhangjiang Hi-Tech Park, where pharmaceutical cold-chain operations expand cryogenic capacity. Domestic polypropylene feedstock suppliers face quality certification gaps against European medical-grade benchmarks.
Cryo Box Market Key Industry Players
Strategic partnerships dominate the current landscape as biobanks consolidate vendor relationships around integrated cold-chain validation rather than discrete equipment purchases. The vendor base clusters into three tiers: diversified laboratory conglomerates with full cold-chain portfolios, specialized polypropylene fabricators with materials science depth, and precision-molded rack specialists serving automated retrieval systems. Competitive positioning hinges on multi-year framework agreement capture and EMA-FDA dual-compliant certification attainment.
Among diversified laboratory conglomerates, Thermo Fisher Scientific and Merck KGaA occupy positions defined by institutional procurement contract scale. Greiner Bio-One exemplifies the specialized materials science archetype through its polypropylene formulation focus. Eppendorf AG anchors the precision-molded rack specialist tier with automated liquid nitrogen retrieval compatibility. Each archetype faces distinct margin pressures from European polymer supply concentration and escalating regulatory documentation burdens.
| Leading Market Players |
|---|
| Merck KGaA |
| Greiner Bio-One |
| Thermo Fisher Scientific |
| Heathrow Scientific |
| Biocision LLC |
| Corning Incorporated |
| VWR International |
| DWK Life Sciences |
| Eppendorf AG |
| Others |
Cost & Logistics Intelligence
Family-owned German chemical conglomerates anchor medical-grade polypropylene feedstock production, creating disciplined pricing power that ripples through cryo box manufacturing tiers. Their captive control over specialized polymer formulations constrains margin flexibility for downstream fabricators while sustaining premium positioning for ISO 20387-certified configurations.
Pricing Analysis
Distributor markups compress as biobanks consolidate procurement around direct manufacturer relationships. Three-tier pricing structure across premium, standard, and economy levels separates custom patient-specific racks from standard grid-molded units, with certification grade and volume scale as primary differentiation drivers. Cost compression in standard polypropylene configurations is intensifying because European energy volatility feeds raw material price instability. Academic medical centers exhibit highest price sensitivity, while pharmaceutical cell therapy manufacturers prioritize thermal performance over unit economics.
Supply Chain Analysis
Freight cost volatility for temperature-controlled pharmaceutical lanes elevates landed costs for vacuum-insulated panel imports from Germany and Japan. Medical-grade polypropylene feedstock draws from Belgium, Germany, and the Netherlands, with precision-molded rack components sourced from Switzerland and Austria. Single-source vulnerability concentrates in specialized polymer composite formulations certified for ultra-low temperature mechanical stability. Distribution runs through integrated cold-chain service providers rather than discrete equipment distributors, compressing traditional channel margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cryo box demand functions as a stable compounder anchored by irreversible biobank infrastructure buildout for cellular therapy manufacturing. Regulatory mandates for traceable storage conditions create recurring replacement cycles that smooth revenue volatility.
For Market Incumbents: Deploy multi-year framework agreement capture to lock biobank procurement committees before automated retrieval integration decisions crystallize. Deepen backward integration into medical-grade polypropylene compounding to defend margin position against European feedstock supply concentration. Prioritize EMA-FDA dual-compliant certification investment to capture premium positioning as regulatory harmonization converges cold-chain validation protocols.
For New Entrants and Emerging Players: Launch via portable cryogenic system specialization targeting Japan's decentralized healthcare delivery model and point-of-care cell therapy administration workflows. White-space exists in disposable single-use configurations for multi-site clinical trials where cross-contamination risk drives specification. Geographic expansion into Chinese biobanking infrastructure offers penetrable entry, provided NMPA quality certification gaps against European benchmarks are closed through technical partnerships.
For Investors and Strategic Acquirers: Laboratory conglomerates with full cold-chain portfolios are the most active acquirer in this space, seeking precision-molded rack specialists to complete automated retrieval system integration. Long-term viability rests on cell therapy manufacturing scale-up sustaining infrastructure investment across the analysis window. Target acquisition archetype: specialized polypropylene fabricators with materials science depth and established ISO 20387 certification pathways. Signal to watch: biobank procurement committee consolidation velocity around integrated service contracts versus discrete equipment purchasing.
| Strategic Initiative | Industry Significance |
|---|---|
| EMA-FDA Dual Certification Investment | Streamlines market access as regulatory harmonization converges cold-chain validation protocols between jurisdictions. |
| Automated Retrieval System Integration | Captures biobank procurement preference as facilities pilot fully automated liquid nitrogen handling infrastructure. |
| Backward Integration into Polypropylene Compounding | Defends margin position against European medical-grade feedstock supply concentration and energy cost volatility. |
| Portable Configuration Development | Addresses Japan's METI-guided decentralized healthcare delivery model and point-of-care cell therapy administration demand. |
| Multi-Year Framework Agreement Capture | Locks institutional procurement relationships before vendor consolidation around integrated cold-chain service providers completes. |
Research Approach
Multiple input streams — primary interviews with biobank operations directors, pharmaceutical cold-chain logistics managers, and regulatory affairs specialists; secondary validation through FDA 21 CFR Part 1271 guidance documents, EMA advanced therapy medicinal product filings, and ISO 20387 accreditation databases; customs and trade flow data for medical-grade polymer feedstock — were reconciled through bottom-up and top-down triangulation. Cryo box procurement patterns, thermal performance benchmarking studies, and liquid nitrogen infrastructure deployment records provided quantitative anchors.
Data-stream reconciliation applied across product type, material composition, end-user category, and application context dimensions. CAGRs were derived from segment-level volume trajectories and value-per-unit progression curves. Forecast inputs incorporated biobank capacity expansion pipelines, cell therapy manufacturing facility announcements, and regulatory harmonization timelines between FDA and EMA frameworks.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt F-Gas Regulation enforcement shifts or prolonged European polymer feedstock disruption. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cold Chain Packaging
Middle East and Africa Frozen Food Packaging Market
Cold Chain Packaging
Temperature Controlled Packaging Boxes Market
Cold Chain Packaging
Foam Cooler Box Market
Cold Chain Packaging
North America Food Cold Chain Logistics Market
Cold Chain Packaging
Cold Chain Integrity and Shock Monitoring Test Devices Market
Cold Chain Packaging
North America Cold Chain Market
Cold Chain Packaging
Cold Chain Equipment Market
Cold Chain Packaging
Cooling Boxes Market
Cold Chain Packaging
Europe Healthcare Cold Chain Logistics Market
Cold Chain Packaging
Freezer Liner Market
Cold Chain Packaging
Biopharma Cold Chain Packaging Market
Cold Chain Packaging
Latin America Pharmaceutical Cold Chain Logistics Market
Cold Chain Packaging
Cold Chain Packaging Pooling and Reverse Logistics Services Market
Cold Chain Packaging
Insulated Coolers Market
Cold Chain Packaging
Cold Storage Insulated Market
Cold Chain Packaging
Cold Box Module Market