
 Ice Boxes Market | 2026-2036
Ice Boxes Market Size, Share, and Industry Trends Forecast 2026-2036
Ice Boxes Market Foresight
Buyer concentration among outdoor specialty retailers is expanding as REI and Bass Pro Shops consolidate shelf-space allocations toward performance-tier suppliers. YETI Holdings leverages direct-to-consumer channel control and premium positioning to sustain margin density against mass-market entrants. Igloo Products Corp. anchors the mid-tier through private-label partnerships and seasonal volume contracts with big-box retailers. Coleman competes on heritage brand recognition and camping-event sponsorships that reinforce top-of-mind awareness among family recreation segments.
Ice boxes are thermally insulated containers engineered to maintain sub-ambient temperatures for perishable goods, typically constructed with polyurethane or expanded polypropylene foam cores bonded to polyethylene shells and rated by ice-retention duration under standardized load conditions. Their primary commercial purpose spans recreational cold storage, pharmaceutical last-mile transport, and food-service mobile refrigeration where mechanical cooling is unavailable or prohibited. Hard coolers dominate absolute revenue contribution due to durability premiums and gift-market positioning, while electric coolers represent the fastest-expanding product type as lithium-ion power station pairing extends off-grid runtime. Soft coolers capture margin concentration in the fishing and day-hike segments where portability commands price premiums over capacity.
FDA oversight of cold-chain integrity for biologics transport intersects with EPA foam-blowing agent regulations under SNAP program restrictions on HFC-based insulation, pushing manufacturers toward hydrocarbon and water-blown alternatives. ISO 9001 quality certification and CE marking under EU construction product standards govern export access for composite-panel fabricators serving European outdoor distributors. Stakeholders must monitor pending state-level extended producer responsibility laws in California and New York that would mandate recycling infrastructure for end-of-life polymer shells.
Market Dynamics
Outdoor recreation retailers are consolidating procurement volumes toward fewer suppliers, compressing vendor margins while vacuum-insulated panel advances from va-Q-tec and EPP foam breakthroughs reshape thermal performance benchmarks across performance tiers.
Growth Catalysts
- EPA SNAP program restrictions:HFC-based insulation phase-out under US environmental rules accelerates hydrocarbon and water-blown foam adoption, forcing manufacturing upgrades that yield superior thermal retention ratings.
- Camping participation concentration:United States, Australia, and Germany exhibit the highest cold-chain hobbyist standards, driving demand for premium ice-retention performance in recreational applications.
- Lithium-ion power station pairing:Electric cooler compatibility with portable battery systems extends off-grid runtime, expanding addressable use cases beyond traditional passive insulation.
Market Restraints
- Polyurethane feedstock volatility:MDI and polyol price swings compress margin predictability for manufacturers reliant on petroleum-derived foam cores.
- Asian manufacturing concentration:Molded shell and insulation component sourcing clusters in select East Asian production zones expose supply chains to geopolitical disruption risk.
- Mechanical refrigeration substitution:Portable compressor units achieve comparable portability with active cooling, threatening premium passive cooler positioning in vehicle-based recreation.
Strategic Opportunities
- Pharmaceutical last-mile transport:FDA cold-chain integrity requirements for biologics create certified container demand distinct from recreational positioning.
- Extended producer responsibility tailwinds:Pending California and New York state laws mandating polymer shell recycling infrastructure favor early movers with closed-loop material capabilities.
- Direct-to-consumer channel maturation:Premium brands bypassing traditional outdoor specialty retail capture margin density through controlled digital distribution.
Industry Challenges
- ISO 9001 certification timelines:Quality system implementation delays block export access for composite-panel fabricators targeting European outdoor distributors.
- Vacuum-insulated panel integration complexity:VIP assembly requires cleanroom conditions and specialized sealing equipment absent from legacy rotational molding facilities.
- CE marking compliance fragmentation:EU construction product standards interpretation varies across notified bodies, creating inconsistent market entry requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ice Boxes Market |
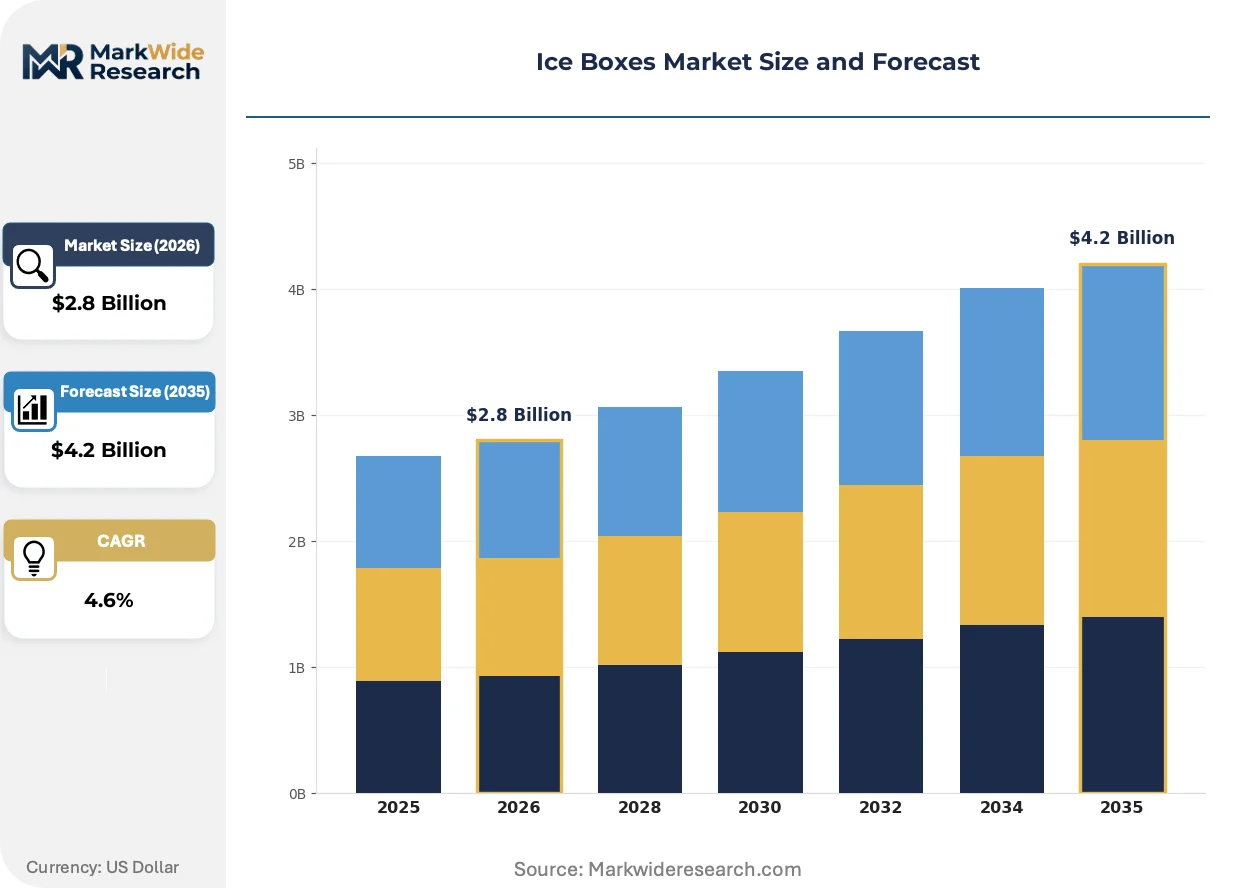
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hard Cooler, Soft Cooler, Electric Cooler, Insulated Carrier End User: Camping Enthusiasts, Fishermen, Outdoor Events, Sports Teams Material: Plastic, Metal, Fabric, Composite Capacity: 20 Quart, 50 Quart, 100 Quart, 150 Quart |
| Companies Covered | YETI Holdings, Igloo Products Corp., Coleman Company, Pelican Products, ORCA Coolers, Bison Coolers, Sonoco ThermoSafe, RTIC Outdoors, va-Q-tec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ice Boxes Market Shifts & Advancements
Vacuum-insulated panel technology and expanded polypropylene foam formulations are redrawing competitive boundaries between mass-market and performance-tier suppliers. Material science advances now enable thinner-wall construction without thermal penalty, compressing shipping cube and retail shelf footprint simultaneously.
EPP foam core construction with co-injection molded polyethylene shells is decentralizing manufacturing location requirements by enabling regional molding facilities to achieve performance parity with centralized production. Mid-tier suppliers in North America and Europe are adopting this technology to reduce transoceanic freight exposure. The shift enables shorter lead times for seasonal replenishment cycles without sacrificing ice-retention ratings.
EU F-Gas Regulation restrictions on high-global-warming-potential blowing agents are forcing insulation formulation changes across export-oriented manufacturers. The industrial consequence is accelerated R&D investment in hydrocarbon-blown polyurethane systems and water-blown alternatives. European outdoor distributors now require documentation of compliant foam sourcing, filtering supplier qualification pools.
Buyer concentration among REI and Bass Pro Shops is compressing vendor counts while elevating performance-tier requirements. Direct-to-consumer brands are capturing shelf-space formerly allocated to traditional wholesale relationships. This pattern concentrates most visibly in the United States, where specialty outdoor retail consolidation has advanced furthest and digital-native cooler brands have achieved highest penetration.
Ice Boxes Market Segmentation
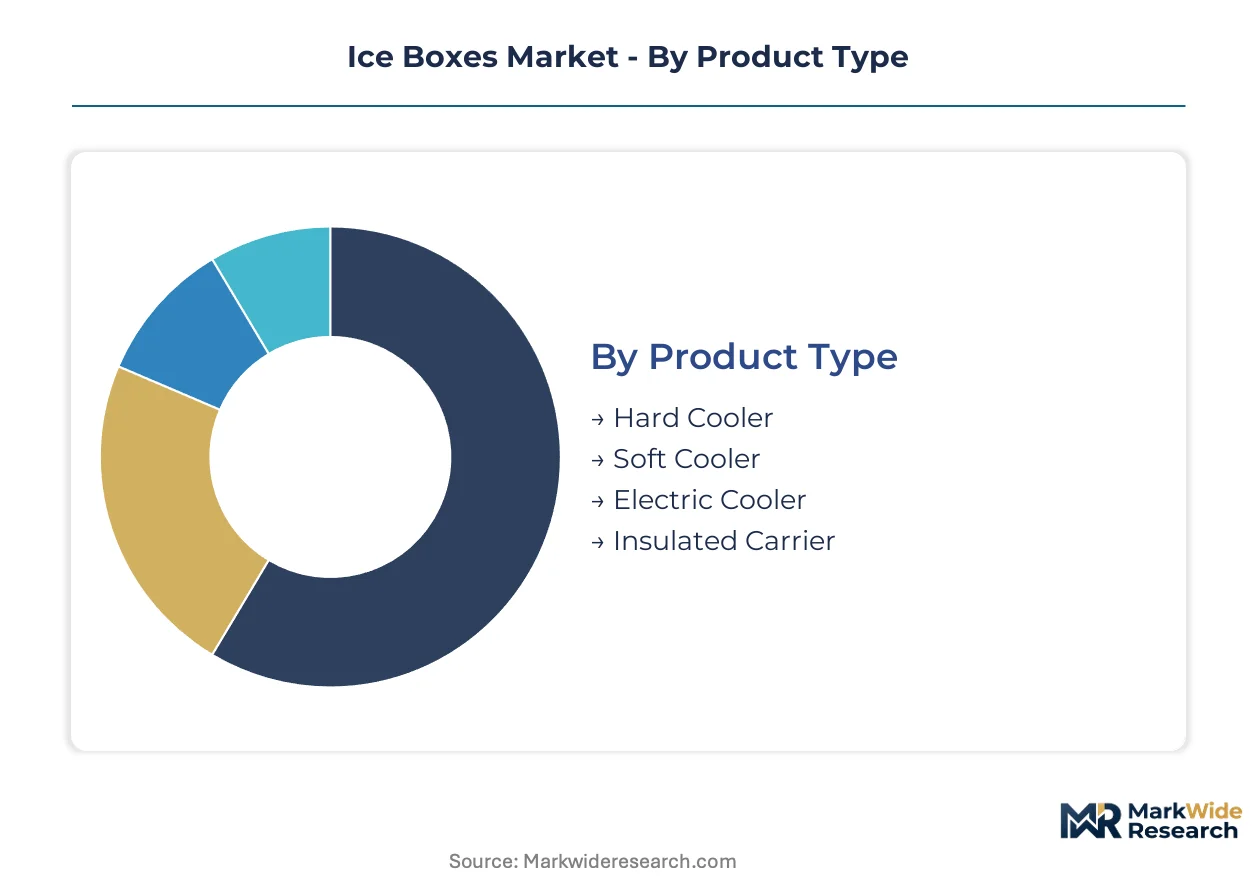
Product differentiation in the ice boxes market tracks closely with end-use intensity and replacement frequency. Upgrade cycles vary dramatically across recreational versus commercial applications, with thermal performance benchmarks driving portfolio decisions at each tier.
Product Type:
Replacement cycles accelerate where thermal technology advances most rapidly, compressing effective product lifespans for performance-tier buyers while extending utility for casual users.
- Hard Cooler:Polyethylene shells bonded to polyurethane or expanded polypropylene foam cores deliver multi-day ice retention for vehicle-based recreation. Demand concentrates in the United States and Australia where extended camping trips and hunting expeditions justify durability premiums over soft alternatives. REI and Bass Pro Shops allocate disproportionate shelf space to rotational-molded units from established suppliers.
- Electric Cooler:Thermoelectric or compressor-based units paired with lithium-ion power stations extend off-grid runtime beyond passive insulation limits. Fishermen and remote workers in Germany and Australia drive adoption where grid-independent cooling commands price premiums over traditional ice dependency. Compatibility with portable battery ecosystems from Jackery and EcoFlow accelerates category expansion.
- Soft Cooler:Fabric exteriors with closed-cell foam insulation prioritize portability for day-hikes and kayak fishing where weight constraints dominate capacity needs.
- Insulated Carrier:Lightweight collapsible designs serve pharmaceutical last-mile transport and food-service catering where temporary thermal protection suffices without structural rigidity.
Hard cooler sits at the top of the volume ranking, with electric cooler climbing the fastest.
End User:
Customer acquisition costs diverge sharply across hobbyist intensity levels, with enthusiasts tolerating premium pricing while occasional users gravitate toward rental or entry-tier ownership.
- Camping Enthusiasts:Multi-day backcountry and vehicle-based campers in the United States, Australia, and Germany demand certified ice-retention ratings under standardized load conditions. Participation rates in these geographies correlate directly with performance-tier procurement volumes and brand loyalty metrics.
- Fishermen:Freshwater and saltwater anglers require specialized features including integrated fish rulers, rod holders, and UV-resistant shells for prolonged deck exposure. Tournament circuits and charter operations in Florida and Queensland drive commercial-grade specifications distinct from recreational camping.
- Outdoor Events:Music festivals, sporting venues, and corporate gatherings generate seasonal bulk demand for standardized capacity units with sponsor-friendly exteriors.
- Sports Teams:Hydration and medical supply transport for amateur and professional athletics requires institutional procurement through sporting goods distributors with volume discount structures.
Camping enthusiasts generate the highest absolute revenue contribution, with fishermen expanding most quickly as specialized feature sets justify premium positioning.
Material:
Raw material selection determines manufacturing location flexibility and regulatory compliance burden across export markets.
- Plastic:Rotational-molded polyethylene dominates mass-market production for impact resistance and cost efficiency in high-volume molding operations.
- Metal:Stainless steel and aluminum shells serve premium positioning and food-service applications where sanitation standards exceed polymer capabilities.
- Fabric:Nylon and polyester exteriors with welded seams enable soft cooler construction for weight-sensitive portability requirements.
- Composite:Vacuum-insulated panels and fiberglass-reinforced shells achieve thermal performance benchmarks previously unattainable in thinner-wall designs, though assembly complexity limits supplier participation.
Plastic commands the volume base, with composite gaining share fastest as va-Q-tec VIP technology penetrates mid-tier price points.
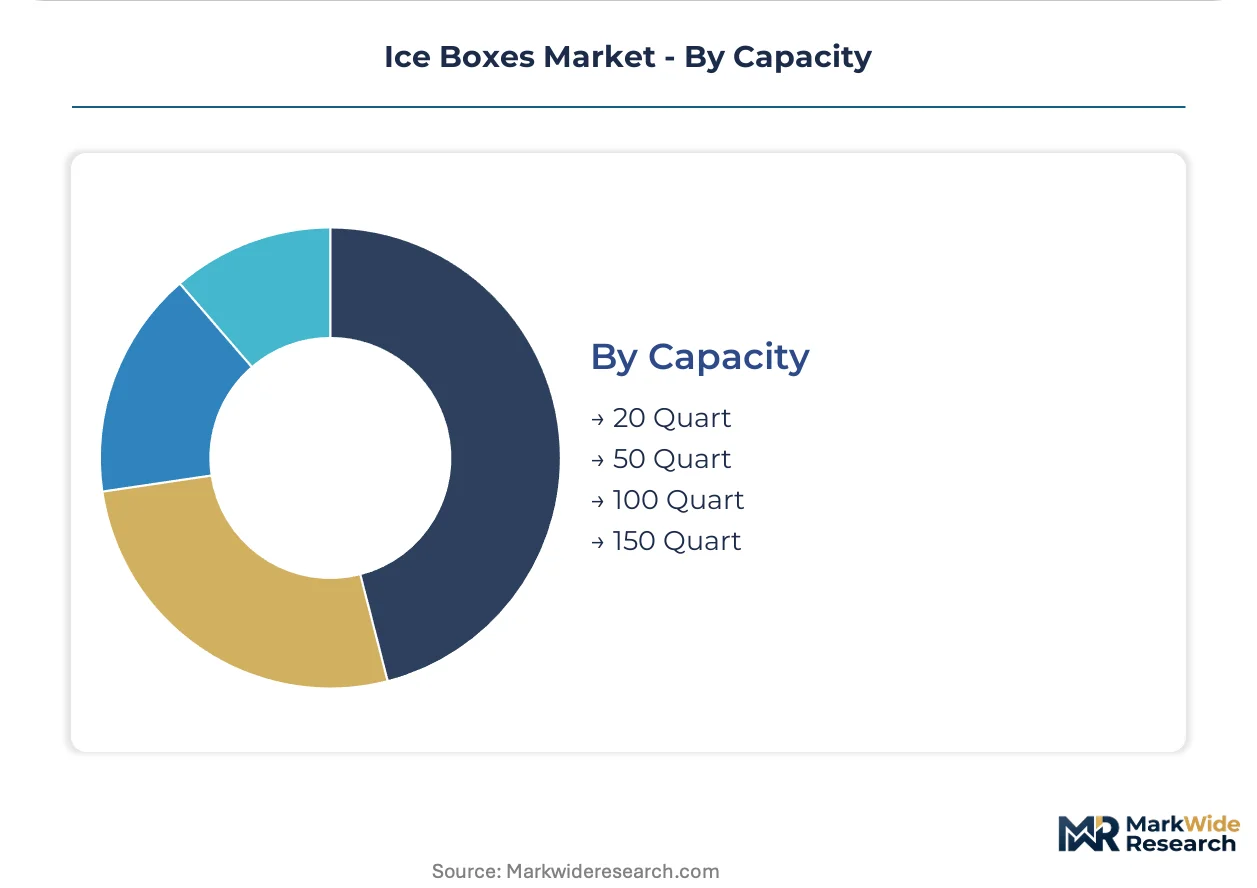
Capacity:
Size selection correlates with trip duration and group composition, creating distinct inventory management challenges for seasonal retail.
- 20 Quart:Personal day-trip capacity for individual anglers and solo hikers where portability outweighs storage volume.
- 50 Quart:Weekend camping standard for two-to-four-person groups, representing the most heavily promoted retail tier with deepest promotional discounting.
- 100 Quart:Extended expedition and hunting party capacity with integrated wheels and tow handles for vehicle-to-camp transport.
- 150 Quart:Commercial fishing and large-group catering applications where stationary deployment eliminates mobility constraints.
50 quart anchors retail volume, with 100 quart expanding most steeply as vehicle-based recreation participation lengthens average trip duration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Camping participation rates in the United States exceed those in Germany by a substantial margin, yet both markets command premium-tier pricing for certified ice-retention performance. Australia completes the triad of highest-value demand concentration, where remote expedition culture sustains durability premiums unavailable in casual-use markets.
United States
Vehicle-based recreation and hunting expeditions drive multi-day cooler replacement cycles, with Bass Pro Shops and REI consolidating procurement toward performance-tier suppliers. EPA SNAP program restrictions on HFC-based insulation accelerate hydrocarbon-blown foam adoption among domestic fabricators. Rotational molding clusters in Texas and the Midwest supply polyethylene shells for national distribution networks.
Germany
EU F-Gas Regulation compliance requirements filter supplier qualification pools for export-oriented manufacturers serving outdoor distributors. TÜV certification and CE marking under construction product standards govern market access for composite-panel fabricators. Vacuum-insulated panel integration capabilities concentrate in Bavarian industrial zones where cleanroom assembly infrastructure supports va-Q-tec technology licensing.
Australia
Remote worker populations and charter fishing operations extend electric cooler adoption beyond recreational camping into commercial applications. TGA cold-chain guidelines for pharmaceutical transport create certified container demand distinct from consumer positioning. Queensland and Western Australia host distribution hubs serving expedition markets across the continent's interior.
China
Molded shell and insulation component sourcing clusters in Guangdong and Zhejiang provinces expose supply chains to geopolitical disruption risk. GB standards and MIIT industrial policy shape domestic manufacturing investment toward hydrocarbon-blown alternatives. Yangtze River Delta facilities supply rotational-molded polyethylene units for North American and European brand owners.
Ice Boxes Market Competitive Landscape
United States producers anchor the premium tier through direct-to-consumer channel control and heritage brand positioning; Asian fabricators hold volume manufacturing through centralized rotational molding operations. The vendor base separates into three strategic archetypes: performance-tier specialists commanding margin density, mid-tier private-label suppliers capturing seasonal volume contracts, and mass-market entrants competing on entry-price positioning. Dominant competitive moves include backward integration into foam core production and strategic partnerships with lithium-ion power station manufacturers for electric cooler ecosystem alignment.
Within the premium-tier archetype, YETI Holdings and ORCA Coolers represent direct-to-native positioning against consolidated outdoor retail procurement. Igloo Products Corp. occupies a position bridging mid-tier private-label partnerships with big-box seasonal contracts. va-Q-tec exemplifies technology-licensing specialists whose vacuum-insulated panel advances reshape thermal performance benchmarks across supplier tiers.
| Leading Market Players |
|---|
| YETI Holdings |
| Igloo Products Corp. |
| Coleman Company |
| Pelican Products |
| ORCA Coolers |
| Bison Coolers |
| Sonoco ThermoSafe |
| RTIC Outdoors |
| va-Q-tec |
| Others |
Supply & Pricing Matrix
Captive foam core production in Texas and the Midwest anchors both supply security and pricing power for domestic rotational molders, insulating them from MDI and polyol volatility that compresses margins for outsourced competitors.
Pricing Analysis
Capacity additions in Guangdong and Zhejiang provinces are reshaping price floors for entry-tier polyethylene shells, forcing mid-tier suppliers toward hydrocarbon-blown foam differentiation to defend position. Three-tier pricing structure across premium, standard, and economy levels stratifies by ice-retention certification and channel control, with REI and Bass Pro Shops extracting volume rebates that intensify cost compression in the standard tier. Camping enthusiasts show lowest price sensitivity, while occasional outdoor event users gravitate toward rental or entry-tier ownership.
Supply Chain Analysis
Single-source vulnerability sits with Chinese rotational molding clusters for polyethylene shell supply, exposing brand owners to tariff exposure and logistics chokepoint risk. MDI and polyol feedstocks draw from petroleum derivatives with volatile commodity pricing, while vacuum-insulated panel technology rests on va-Q-tec licensing from Bavarian cleanroom facilities. Distribution runs through consolidated outdoor specialty retail in the United States and big-box seasonal contracts for mass-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, justified by demand-shift toward certified ice-retention performance among vehicle-based recreation participants in the United States, Australia, and Germany.
For Market Incumbents: Extend direct-to-consumer channel control to capture margin density lost to consolidated retail procurement, while accelerating backward integration into hydrocarbon-blown foam production ahead of EPA SNAP enforcement. Vacuum-insulated panel assembly capabilities in cleanroom conditions represent a defensive moat against mid-tier EPP foam adoption.
For New Entrants and Emerging Players: Lithium-ion power station compatibility offers a technology-first wedge into electric cooler positioning, with pharmaceutical last-mile transport representing the most penetrable white-space segment. Target TGA-certified container demand in Australia through institutional procurement channels distinct from saturated recreational camping.
For Investors and Strategic Acquirers: Roll-up economics work for regional EPP foam molders with captive polyethylene shell supply because transoceanic freight exposure is driving nearshoring mandates from North American brand owners. Watch California and New York extended producer responsibility law implementation as the signal for closed-loop material capability premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foam Core Production | Captive hydrocarbon-blown polyurethane supply insulates margins from MDI feedstock volatility. |
| Vacuum-Insulated Panel Technology Licensing | va-Q-tec partnerships enable thinner-wall construction without thermal performance penalty. |
| Direct-to-Consumer Channel Launch | Bypassing REI and Bass Pro Shops captures margin density through controlled digital distribution. |
| Pharmaceutical Cold-Chain Certification | FDA and TGA compliance opens institutional procurement distinct from recreational positioning. |
| Closed-Loop Recycling Infrastructure | California and New York EPR mandates favor early movers with polymer shell recovery capabilities. |
Research Methodology
Bottom-up camping participation modeling reconciled against top-down rotational molding capacity tracking forms the analytical core, combining primary interviews with outdoor specialty retail buyers, brand procurement directors, foam core suppliers, and regulatory compliance officers with secondary validation from EPA SNAP filings, EU F-Gas Regulation documentation, and customs trade records for polyethylene and MDI flows.
Input-output matrices map hard cooler, electric cooler, and soft cooler volumes against end-use intensity segments, with CAGRs derived from regression analysis of camping participation rates and cold-chain hobbyist expenditure patterns across the projection horizon. Modeled dimensions include product type, capacity tier, material technology, and geographic demand concentration.
The model holds under stable camping participation rates and current EPA regulatory timelines; deviation in lithium-ion power station adoption curves or accelerated EPR implementation would shift volume trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cold Chain Packaging
Middle East and Africa Frozen Food Packaging Market
Cold Chain Packaging
Europe Cold Chain Tracking and Monitoring Market
Cold Chain Packaging
Cryo Box Market
Cold Chain Packaging
Global Cold Chain Tracking and Monitoring Market
Cold Chain Packaging
Insulated Food Delivery Bags Market
Cold Chain Packaging
Biopharma Cold Chain Packaging Market
Cold Chain Packaging
North America Food Cold Chain Logistics Market
Cold Chain Packaging
Cooling Boxes Market
Cold Chain Packaging
Foam Cooler Box Market
Cold Chain Packaging
Cold Chain Integrity and Shock Monitoring Test Devices Market
Cold Chain Packaging
China Cold Chain Market
Cold Chain Packaging
Cryogenic Boxes Market
Cold Chain Packaging
Cold Chain Market
Cold Chain Packaging
Cold Chain Packaging Market
Cold Chain Packaging
Cold Box Module Market
Cold Chain Packaging
Cold Chain Equipment Market