
 China Cold Chain Market | 2026-2036
China Cold Chain Market Size, Share, and Industry Trends Forecast 2026-2036
China Cold Chain Market Insights
Chinese cold storage infrastructure is recalibrating around pharmaceutical-grade capacity after pandemic-era vaccine distribution exposed regional gaps. Sinotrans Ltd. leverages its state-backed port network to dominate bonded cold zone throughput. SF Express Co. Ltd. anchors premium perishable express delivery through proprietary refrigerated air fleet control.
Cold chain denotes temperature-controlled logistics networks maintaining products between minus 25 degrees Celsius and plus 15 degrees Celsius through insulated transport, active refrigeration, and real-time monitoring systems to preserve biochemical stability across food and pharmaceutical supply chains. Frozen food commands the largest product type volume pool though pharmaceuticals generates superior margin density under NMPA traceability mandates. IoT Solutions within the technology dimension attracts disproportionate capital allocation as warehouse operators retrofit legacy facilities with sensor-based compliance automation.
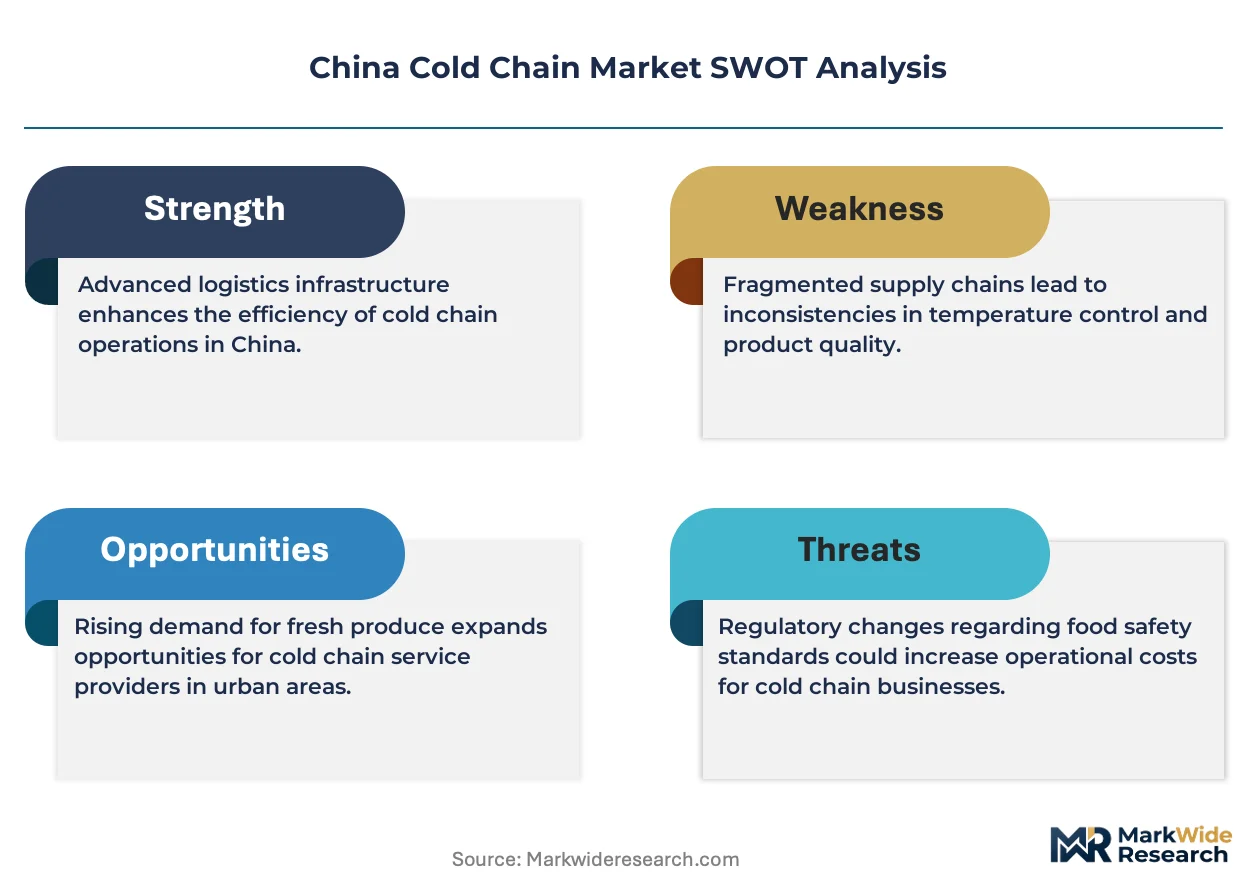
NMPA distribution licensing, MIIT IoT device certification, and SAMR food safety enforcement collectively elevate compliance costs for fragmented cold chain operators while advantaging scaled national platforms. Beijing interprets cold chain resilience as strategic food security infrastructure, directing state capital toward northern corridor expansion. Stakeholders must assess whether pharmaceutical certification premiums justify retrofit investment against food-service volume economics.
Market Dynamics
Pharmaceutical-grade cold storage capacity is recalibrating regional infrastructure investment after pandemic-era vaccine distribution exposed critical gaps in China's temperature-controlled logistics network. Fresh e-commerce platforms are accelerating last-mile refrigerated delivery buildout while NMPA traceability mandates compress compliance timelines.
Growth Catalysts
- NMPA Pharmaceutical Distribution Rules:Traceability mandates for vaccines and biologics are forcing warehouse operators to retrofit facilities with real-time temperature monitoring systems.
- Fresh E-Commerce Expansion:Online grocery platforms are building proprietary refrigerated last-mile networks to capture premium perishable delivery segments.
- Yangtze River Delta Concentration:Demand clustering around Shanghai and Jiangsu province is attracting concentrated cold zone investment and bonded port capacity.
Market Restraints
- MIIT IoT Certification Costs:Device compliance requirements for temperature sensors and tracking hardware elevate capital barriers for fragmented regional operators.
- Energy Input Volatility:Refrigeration-dependent facilities face margin compression from electricity price fluctuations and dual carbon goal compliance costs.
- Northern Corridor Supply Concentration:State-directed infrastructure investment in northeast China is creating geographic dependency risk for national network coverage.
Strategic Opportunities
- Western China Underpenetration:Sichuan and Chongqing cold storage density lags eastern benchmarks, creating whitespace for pharmaceutical distribution hubs.
- IoT-AI Convergence:Predictive maintenance algorithms layered onto sensor networks are enabling autonomous temperature deviation response before product spoilage.
- SAMR Food Safety Enforcement:Stricter cold chain documentation requirements for fresh produce are mandating technology upgrades that favor scaled platform providers.
Industry Challenges
- Pharmaceutical Certification Timelines:GMP-compliant warehouse accreditation requires extended validation periods that delay revenue recognition.
- Legacy System Integration:ERP retrofitting for real-time temperature data streams creates operational friction during multi-month transition windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Cold Chain Market |
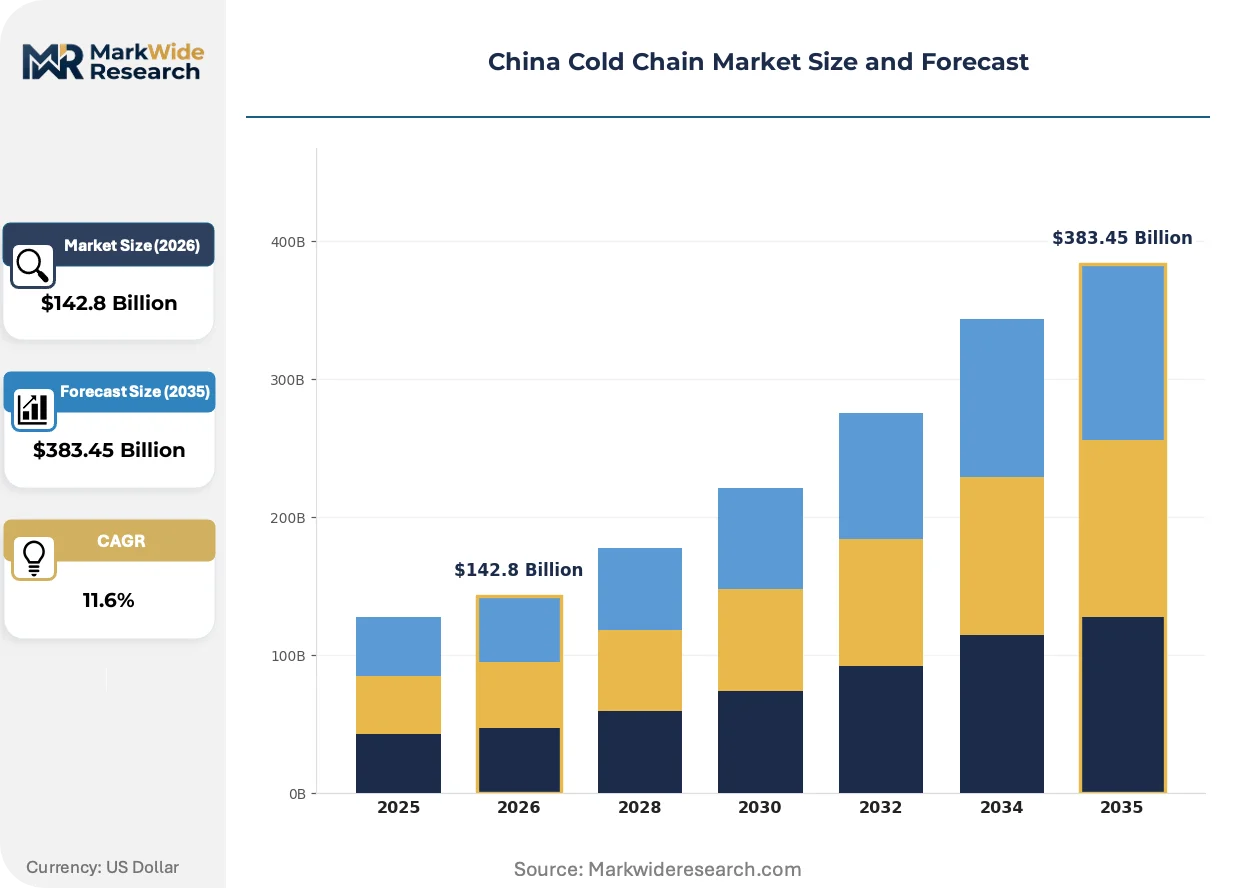
| Market Size in 2026 | $142.8 Billion |
| Market Size in 2035 | $383.45 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Food, Dairy Products, Pharmaceuticals, Healthcare Products Service Type: Transportation, Warehousing, Distribution, Packaging End User: Retailers, Food Manufacturers, Catering Services, Hospitals Technology: Refrigerated Trucks, Cold Storage Facilities, IoT Solutions, Blast Freezers |
| Companies Covered | Sinotrans Ltd., SF Express Co. Ltd., JD Logistics Inc., China Merchants Americold Logistics, Shanghai Jin Jiang International Holdings Co. Ltd., Nichirei Corp., Beijing Shounong Food Group Co. Ltd., Shandong Gaishi International Logistics Group, Beijing Ershang Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Cold Chain Market Trends and Innovations
Automation is compressing labor dependency in temperature-controlled facilities while regulatory data requirements are mandating sensor density increases across transport and storage nodes.
Phase-change materials embedded in insulated packaging are absorbing thermal load during last-mile delivery gaps where active refrigeration fails. Pharmaceutical shippers are adopting these materials fastest for high-value biologics. This absorption capability is compressing acceptable delivery windows and reducing spoilage liability for express operators.
NMPA distribution licensing amendments now mandate end-to-end temperature documentation for all vaccine shipments. Warehouse operators must deploy redundant sensor arrays and blockchain-anchored audit trails. Pharmaceutical-grade facilities face the steepest compliance cost escalation, driving consolidation toward national platforms with captive certification expertise.
Buyer procurement for cold chain services is fragmenting across channel-specific requirements. Fresh e-commerce platforms now demand hourly temperature visibility while traditional food distributors accept daily batch reporting. This bifurcation is most visible in Shanghai, where premium perishable shippers are unbundling express cold delivery from standard warehousing contracts.
China Cold Chain Market Segmentation
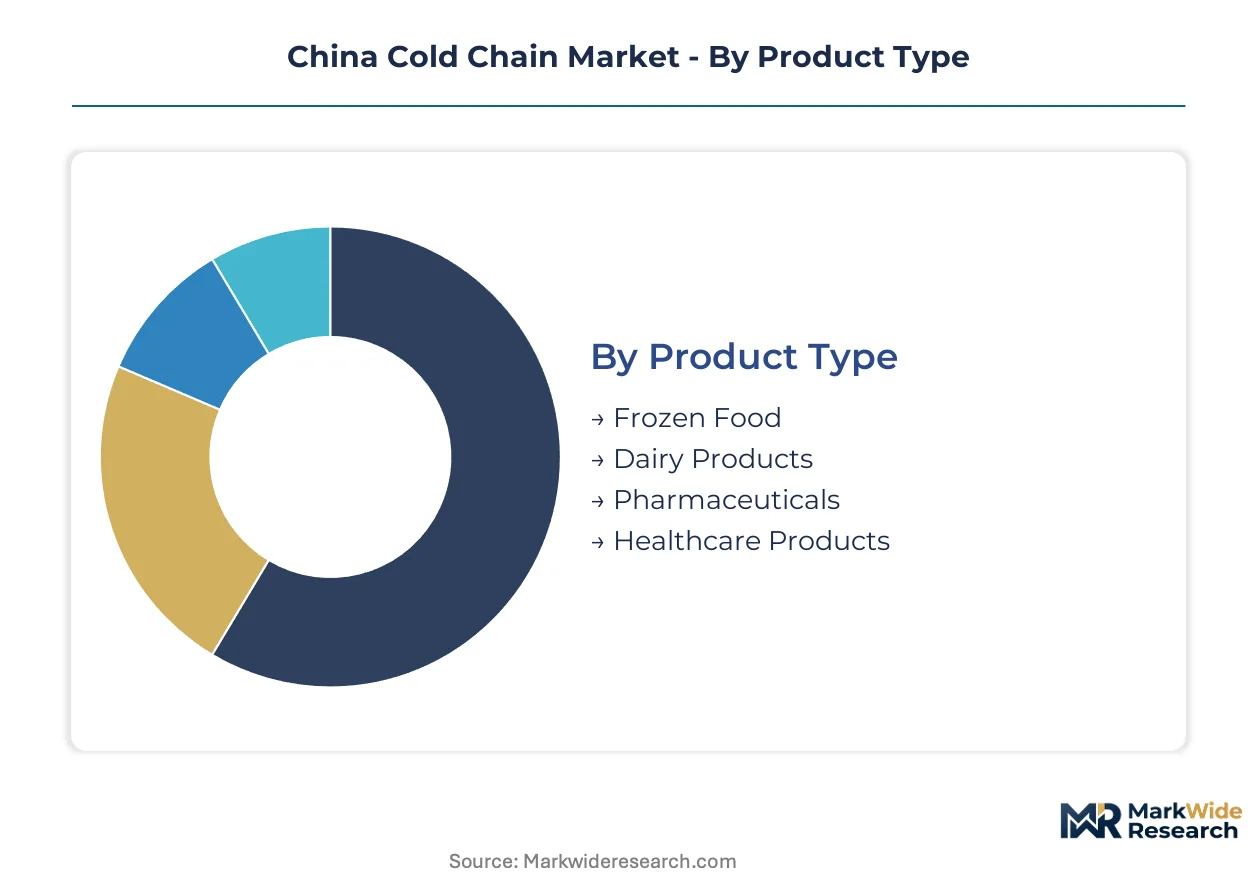
Cold chain segmentation in China reflects divergent compliance burdens and infrastructure investment cycles across product types and service layers. NMPA pharmaceutical mandates and fresh e-commerce expansion are forcing parallel upgrade tracks that fragment procurement patterns.
Product Type:
Facility retrofit cycles are accelerating as operators confront divergent temperature tolerances and traceability requirements across product categories.
- Frozen Food:Temperature maintenance at minus 18 degrees Celsius dominates volume throughput across bonded port zones and inland distribution hubs. Yangtze River Delta cold storage operators prioritize frozen protein corridors connecting Shanghai's Yangshan deep-water port to Jiangsu province processing clusters.
- Pharmaceuticals:GMP-compliant warehouse accreditation demands redundant sensor arrays and blockchain-anchored audit trails for vaccine and biologics distribution. NMPA traceability mandates compress validation timelines while elevating certification premiums for national platform operators.
- Dairy Products:Chilled distribution at 2-8 degrees Celsius requires rapid last-mile turnover to prevent quality degradation.
- Healthcare Products:Temperature-sensitive medical devices and diagnostic reagents command specialized handling protocols.
Volume placements concentrate in Frozen Food; the faster expansion belongs to Pharmaceuticals.
Service Type:
Capital allocation across service layers tracks margin dispersion between commodity logistics and certified pharmaceutical handling.
- Transportation:Refrigerated trucking networks face MIIT IoT device certification requirements for temperature sensors and GPS tracking hardware. SF Express anchors premium perishable express delivery through proprietary refrigerated air fleet control.
- Warehousing:Pharmaceutical-grade capacity expansion concentrates in Shanghai and Jiangsu province after pandemic-era vaccine distribution exposed regional infrastructure gaps.
- Distribution:Last-mile refrigerated buildout accelerates as fresh e-commerce platforms unbundle express cold delivery from standard warehousing contracts.
- Packaging:Phase-change materials embedded in insulated containers absorb thermal load during delivery gaps where active refrigeration fails.
Revenue pools concentrate in Warehousing; the steepest margin compression is hitting Transportation.
End User:
Procurement specifications are bifurcating between hourly temperature visibility demands and traditional batch reporting acceptance.
- Retailers:Online grocery platforms mandate real-time cold chain documentation with sensor-based compliance automation.
- Hospitals:Vaccine distribution networks require end-to-end temperature validation under NMPA distribution licensing amendments.
- Food Manufacturers:Frozen protein processors depend on bonded cold zone throughput through state-backed port networks.
- Catering Services:Restaurant supply chains prioritize cost-efficient chilled distribution with less stringent traceability requirements.
Compliance spending concentrates in Hospitals; the fastest volume growth is emerging from Retailers.
Technology:
Sensor density mandates across transport and storage nodes are driving retrofit investment in legacy facilities.
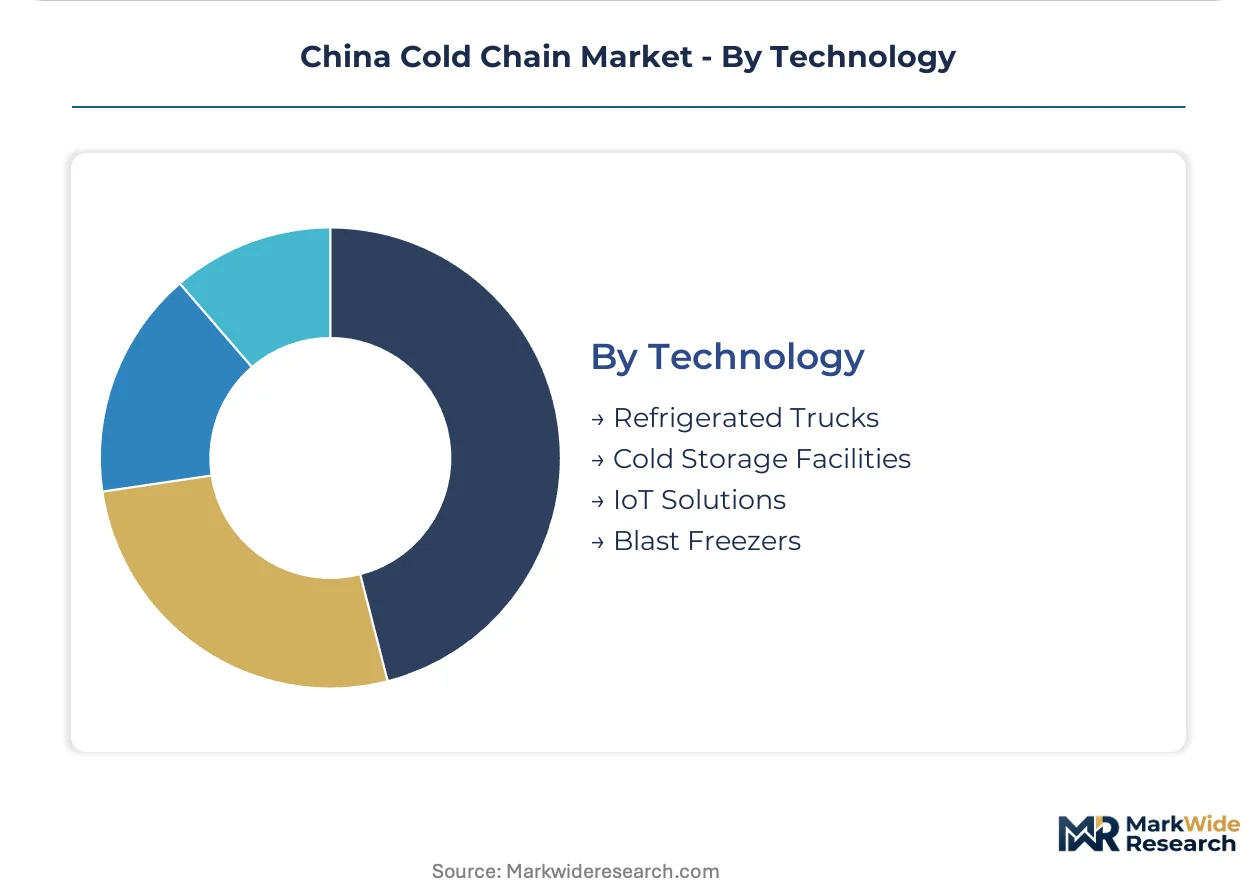
- IoT Solutions:Predictive maintenance algorithms layered onto sensor networks enable autonomous temperature deviation response before product spoilage. MIIT certification requirements elevate capital barriers for fragmented regional operators.
- Cold Storage Facilities:Pharmaceutical-grade retrofitting demands redundant refrigeration systems and real-time monitoring infrastructure.
- Refrigerated Trucks:Fleet operators confront electricity price volatility and dual carbon goal compliance costs.
- Blast Freezers:Rapid temperature reduction systems serve high-throughput protein processing clusters.
Investment flows concentrate in IoT Solutions; the longest replacement cycles persist in Blast Freezers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coastal port infrastructure and inland agricultural processing zones anchor cold chain capacity distribution across China's provincial economies. State-directed investment flows concentrate refrigerated warehousing around major consumption corridors while western provinces present capacity gaps.
Yangtze River Delta
Shanghai's Yangshan deep-water port and Jiangsu province processing clusters command the densest frozen protein throughput volumes. NMPA pharmaceutical distribution licensing mandates accelerate GMP-compliant warehouse accreditation across Suzhou and Nanjing. Bonded cold zone expansion at Shanghai Port connects directly to inland refrigerated rail corridors serving Anhui and Zhejiang distribution nodes.
Pearl River Delta
Guangdong province's fresh e-commerce platforms drive proprietary last-mile refrigerated delivery buildout through Shenzhen and Guangzhou metro corridors. MIIT IoT device certification requirements elevate sensor deployment costs for Hong Kong-crossing freight operators. Dongguan and Foshan cold storage clusters specialize in chilled dairy import handling from Southeast Asian supply sources.
Beijing-Tianjin-Hebei
State capital food security priorities direct subsidized cold chain investment toward northern corridor vaccine distribution resilience. SAMR food safety enforcement mandates real-time temperature documentation for fresh produce entering Beijing's municipal wholesale markets. Tianjin Port bonded cold zones serve as the primary northern entry point for frozen protein imports from South American origins.
Sichuan-Chongqing
Western China's pharmaceutical distribution hub potential remains underpenetrated relative to eastern benchmarks. Dual carbon goal compliance costs constrain refrigerated trucking fleet expansion across mountainous western corridors. Chengdu and Chongqing cold storage density lags Yangtze River Delta standards by approximately 40 percent, creating whitespace for national platform operators.
Shandong Peninsula
Maritime refrigerated export processing concentrates around Qingdao and Yantai port facilities serving Japanese and South Korean demand. Provincial agricultural bureaus coordinate blast freezer capacity expansion for high-throughput vegetable export seasons. Weihai and Rizhao cold chain nodes connect Shandong's intensive farming zones to Dalian and Korean Peninsula shipping lanes.
China Cold Chain Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue pharmaceutical-grade certification premiums. The operator base stratifies across state-backed port logistics platforms, express delivery integrators, and regional cold storage specialists. Three archetypes dominate: bonded zone throughput controllers, proprietary fleet operators, and multi-temperature warehousing specialists. Competitive moves concentrate on GMP-compliant facility acquisition and IoT-enabled sensor network deployment.
Within the state-affiliated logistics tier, Sinotrans Ltd. and China Merchants Americold Logistics occupy positions anchored to port infrastructure control. SF Express Co. Ltd. exemplifies the proprietary fleet archetype through captive refrigerated air and ground transport integration. JD Logistics Inc. represents platform-integrated cold chain buildout, leveraging e-commerce demand density to justify dedicated perishable fulfillment infrastructure. Regional specialists including Beijing Shounong Food Group Co. Ltd. and Shandong Gaishi International Logistics Group sit within province-focused operational footprints serving local agricultural processing clusters.
| Leading Market Players |
|---|
| Sinotrans Ltd. |
| SF Express Co. Ltd. |
| JD Logistics Inc. |
| China Merchants Americold Logistics |
| Shanghai Jin Jiang International Holdings Co. Ltd. |
| Nichirei Corp. |
| Beijing Shounong Food Group Co. Ltd. |
| Shandong Gaishi International Logistics Group |
| Beijing Ershang Group |
| Others |
Pricing and Supply Chain Analysis
IoT sensor retrofitting across legacy cold storage facilities is compressing operating margins while simultaneously consolidating pricing power among scaled national platforms with captive certification expertise. NMPA pharmaceutical distribution mandates force fragmented regional operators to absorb MIIT device compliance costs that national incumbents amortize across bonded port networks and proprietary fleet infrastructure.
Pricing Analysis
Service bundling separates pharmaceutical-grade temperature validation from standard frozen food handling, with GMP-compliant warehouse accreditation commanding substantial premiums over commodity cold storage. Price differentiation hinges on NMPA certification tier and real-time sensor density, with hourly visibility mandates from fresh e-commerce platforms driving cost compression in standard warehousing tiers. Margins are tightening in transportation services due to electricity price volatility and dual carbon goal compliance investments. Food manufacturers exhibit highest price sensitivity, while hospital procurement for vaccine distribution accepts premium pricing for end-to-end traceability guarantees.
Supply Chain Analysis
Single-source vulnerability sits with Yangtze River Delta cold storage concentration, where Shanghai and Jiangsu province control dominant bonded port throughput and pharmaceutical-grade warehouse capacity. Refrigeration equipment draws from German and Japanese compressor manufacturers, while IoT sensor hardware sources from domestic MIIT-certified vendors. Tariff exposure on imported refrigeration components elevates capital costs for facility expansion. Distribution runs through state-backed port logistics platforms connecting coastal bonded zones to inland refrigerated rail corridors, with last-mile fragmentation accelerating as e-commerce platforms build proprietary perishable delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The China cold chain market functions as a cost-of-compliance story where NMPA pharmaceutical distribution licensing creates a barrier-to-entry moat that rewards scaled operators with captive certification expertise and disadvantages fragmented regional players.
For Market Incumbents: Deploy GMP-compliant facility acquisition as the primary lever to capture pharmaceutical certification premiums before validation timelines compress further. Consolidate regional cold storage operators in western China to preempt national platform expansion into Sichuan and Chongqing whitespace. Defend against fresh e-commerce vertical integration by anchoring long-term warehousing contracts with frozen protein processors dependent on bonded port throughput.
For New Entrants and Emerging Players: Fresh e-commerce platforms represent the most penetrable channel partner type for specialized last-mile refrigerated delivery services unbundled from standard warehousing. Target pharmaceutical distribution hub development in Chengdu and Chongqing where cold storage density lags eastern benchmarks by substantial margins. Pursue IoT-AI convergence partnerships with warehouse operators seeking predictive maintenance capabilities without in-house algorithm development.
For Investors and Strategic Acquirers: Re-rating potential sits with pharmaceutical-grade cold storage specialists given NMPA traceability mandate expansion into biologics and cell therapies. Long-term viability favors national platforms with state-backed port access and proprietary fleet integration over regional single-facility operators. Monitor MIIT IoT certification cost trajectories as the inflection signal for consolidation acceleration versus continued fragmentation.
| Strategic Initiative | Industry Significance |
|---|---|
| GMP-Compliant Facility Acquisition | Captures NMPA pharmaceutical certification premiums before validation timelines compress further. |
| IoT Sensor Network Deployment | Enables real-time temperature compliance automation required under MIIT device certification mandates. |
| Western China Hub Development | Addresses Sichuan-Chongqing cold storage underpenetration relative to Yangtze River Delta benchmarks. |
| Refrigerated Fleet Electrification | Aligns with dual carbon goal compliance while reducing electricity price volatility exposure. |
| Phase-Change Material Integration | Absorbs thermal load during last-mile delivery gaps for high-value biologics shipments. |
Research Methodology
Multi-period observation of cold storage capacity expansion, NMPA licensing issuance rates, and fresh e-commerce platform infrastructure investment anchored the trend analysis, supplemented by interviews with cold chain operations directors, pharmaceutical distribution managers, MIIT compliance officers, and refrigerated fleet procurement leads. Secondary validation drew from SAMR food safety enforcement records, NMPA distribution licensing databases, customs bonded zone throughput statistics, and MIIT IoT device certification registries. Bottom-up facility-level capacity modeling triangulated against top-down provincial economic output projections.
Input-output matrices mapped refrigerated warehousing square footage, transportation fleet composition, and technology adoption rates against end-user demand segments across the projection horizon. Segmentation dimensions modeled include product temperature tier, service layer, certification grade, end-user procurement specification, and regional infrastructure density. CAGRs were derived from capacity installation pipelines, regulatory compliance cost trajectories, and e-commerce penetration forecasts. Forecast inputs incorporated electricity price scenarios under dual carbon policy frameworks and pharmaceutical shipment volume assumptions tied to biologics pipeline expansion.
Caveats apply where NMPA regulatory amendments, MIIT certification timeline shifts, or energy policy revisions could materially shift the outlook for facility economics and competitive positioning. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cold Chain Packaging
North America Passive Temperature Controlled Packaging Market
Cold Chain Packaging
Cold Chain Packaging Market
Cold Chain Packaging
Europe Cold Chain Tracking and Monitoring Market
Cold Chain Packaging
North America Cold Chain Market
Cold Chain Packaging
Cold Chain Temperature Monitoring Market
Cold Chain Packaging
Europe Healthcare Cold Chain Logistics Market
Cold Chain Packaging
Biopharma Cold Chain Packaging Market
Cold Chain Packaging
Cryogenic Boxes Market
Cold Chain Packaging
Pharmaceutical Cold Chain Packaging Market
Cold Chain Packaging
Food Cold Chain Market
Cold Chain Packaging
Cold Chain Market
Cold Chain Packaging
Cooling Boxes Market
Cold Chain Packaging
Cryogenic Capsules Market
Cold Chain Packaging
Cold Storage Insulated Market
Cold Chain Packaging
Insulated Coolers Market
Cold Chain Packaging
Ice Boxes Market