
 Pharmaceutical Cold Chain Packaging Market | 2026-2036
Pharmaceutical Cold Chain Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Cold Chain Packaging Market Outlook
Direct-to-patient distribution channels is reshaping how temperature-sensitive pharmaceuticals reach end users. Sonoco ThermoSafe leverages its rental fleet model to control last-mile thermal protection across North America. Nordic Cold Chain Solutions anchors its position through regional manufacturing hubs that reduce lead times for European biologics shippers. CSafe extends its reach via air cargo partnerships that dominate intercontinental vaccine lanes.
Pharmaceutical cold chain packaging comprises engineered thermal protection systems—typically multi-layer insulated containers with phase-change materials maintaining 2-8°C or cryogenic ranges—designed to prevent temperature excursions during transit of heat-labile drugs. Vacuum-insulated panels and expanded polystyrene assemblies with calibrated gel packs constitute the dominant passive architecture for biologics shipments. Passive systems occupy the largest volume share due to lower capital requirements, though active systems with compressor-based cooling command premium positioning for extended-duration clinical trial logistics. RFID solutions represent the fastest-expanding technology segment as real-time traceability becomes mandatory for regulatory compliance.
The FDA enforces strict distribution documentation under 21 CFR Part 211, compelling shippers to validate packaging performance across seasonal stress profiles. EMA's Good Distribution Practice guidelines and WHO's Model Quality Assurance System for temperature-controlled transport collectively raise the compliance threshold for cross-border pharmaceutical movements. Stakeholders must decide whether to build in-house qualification laboratories or outsource thermal mapping to specialized testing providers as regulatory divergence between jurisdictions intensifies.
Market Dynamics
Gene therapy commercialization is compressing qualification timelines for thermal packaging as biologics manufacturers face FDA distribution mandates requiring validated cold chain documentation across seasonal stress profiles.
Growth Catalysts
- EMA Good Distribution Practice:Cross-border pharmaceutical movements within Europe now require temperature-controlled transport validation, forcing packaging upgrades for German and Swiss exporters.
- Phase-change materials:Advances in gel pack chemistry enable longer-duration passive protection, reducing active system dependency for clinical trial logistics.
- Biologics manufacturing concentration:Massachusetts and North Carolina production clusters generate sustained demand for qualified thermal shippers serving cell and gene therapy outputs.
Market Restraints
- Vacuum-insulated panel supply:Core material production concentrates in East Asian manufacturing bases, exposing European packagers to input cost volatility and extended lead times.
- Qualification laboratory capacity:Thermal mapping and seasonal testing bottlenecks delay product launches as in-house validation infrastructure requires multi-year capex commitments.
- Reusable active system economics:Compressor-based cooling units face capital intensity barriers for mid-volume shippers compared to disposable passive alternatives.
Strategic Opportunities
- Direct-to-patient channels:Home infusion and specialty pharmacy distribution creates demand for patient-portable thermal protection systems with simplified handling protocols.
- WHO Model Quality Assurance System:Vaccine export programs to low- and middle-income countries mandate pre-qualified cold chain packaging, opening certified supplier slots.
- RFID-PCM convergence:Real-time temperature logging integrated with phase-change thermal mass enables autonomous excursion alerting without active power.
Industry Challenges
- Thermal engineering talent scarcity:Packaging designers with biologics-specific qualification experience command premium compensation, constraining mid-tier supplier expansion.
- Legacy ERP integration:Track-and-trace data streams from smart packaging require API connectivity with established pharmaceutical distribution systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Cold Chain Packaging Market |
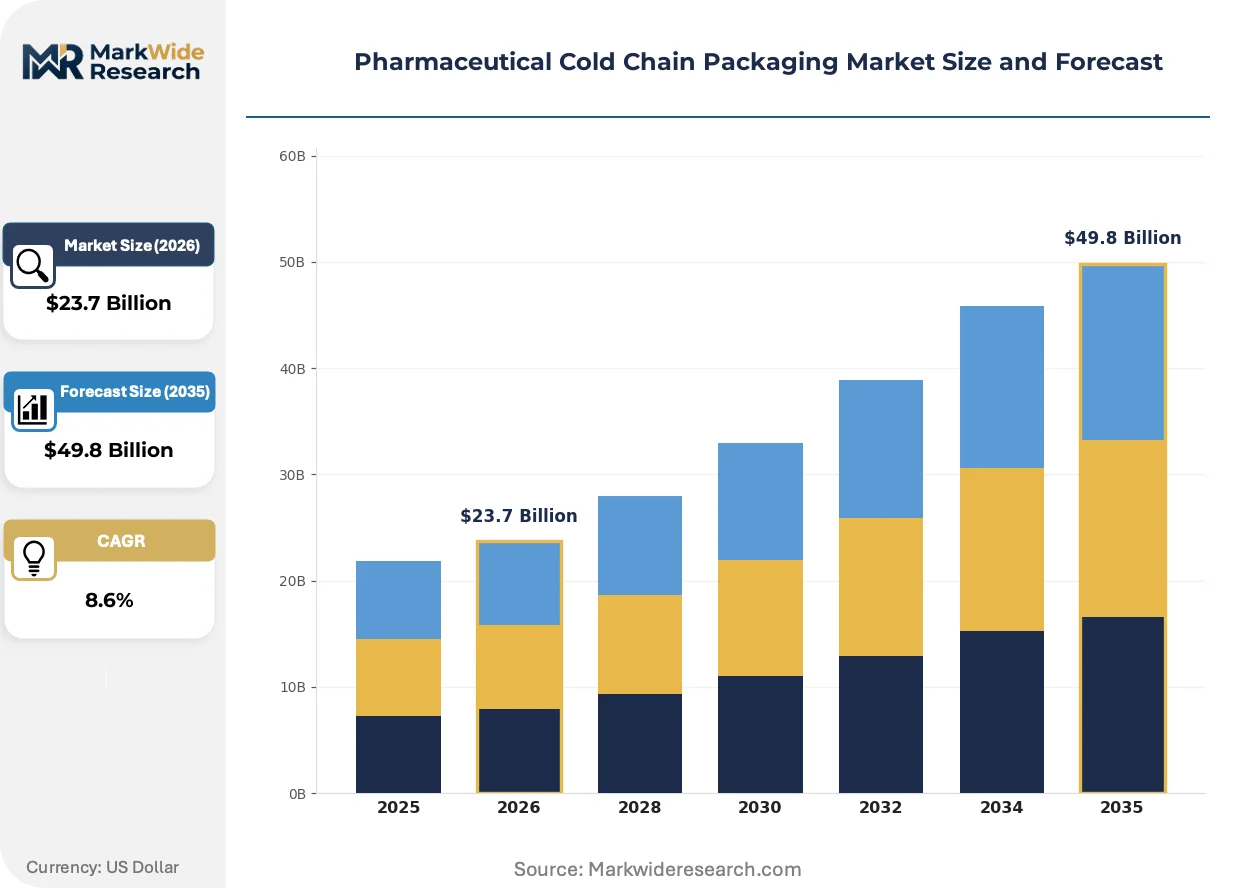
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $49.8 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulated Containers, Refrigerated Trucks, Thermal Blankets, Gel Packs Technology: Active Systems, Passive Systems, Temperature Monitoring, RFID Solutions End User: Pharmaceutical Manufacturers, Logistics Providers, Hospitals, Distributors Application: Vaccines, Biologics, Clinical Trials, Specialty Pharmaceuticals |
| Companies Covered | Sonoco ThermoSafe, Nordic Cold Chain Solutions, Cold Chain Technologies, EMBALL'ISO, Intelsius, CSafe, Cryopak, Chill-Pak, Peli BioThermal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Cold Chain Packaging Market Strategic Shifts
Digital traceability mandates and material science advances are restructuring how thermal protection systems are specified, validated, and deployed across pharmaceutical distribution networks.
Aerogel-based insulation is collapsing the thickness-performance tradeoff in passive cold chain packaging. Gene therapy manufacturers now specify sub-40mm wall profiles previously requiring 80mm expanded polystyrene assemblies. This compression enables higher cube utilization in air freight without sacrificing 96-hour 2-8°C performance.
FDA's tightened gene therapy distribution guidelines under 21 CFR Part 211 now require documented packaging performance across ambient temperature extremes. Biologics shippers must submit thermal qualification data spanning summer and winter lane profiles. Contract packagers in California and Massachusetts have responded by building in-house environmental chambers or outsourcing to specialized testing providers.
Hospital and specialty pharmacy buyers now demand rental fleet models with reverse logistics included rather than capital purchase of thermal shippers. This preference compresses equipment utilization cycles and shifts performance risk to packaging service providers. The model is most visible in North American oncology distribution networks where patient-specific dosing requires rapid container turnaround.
Pharmaceutical Cold Chain Packaging Market Segmentation
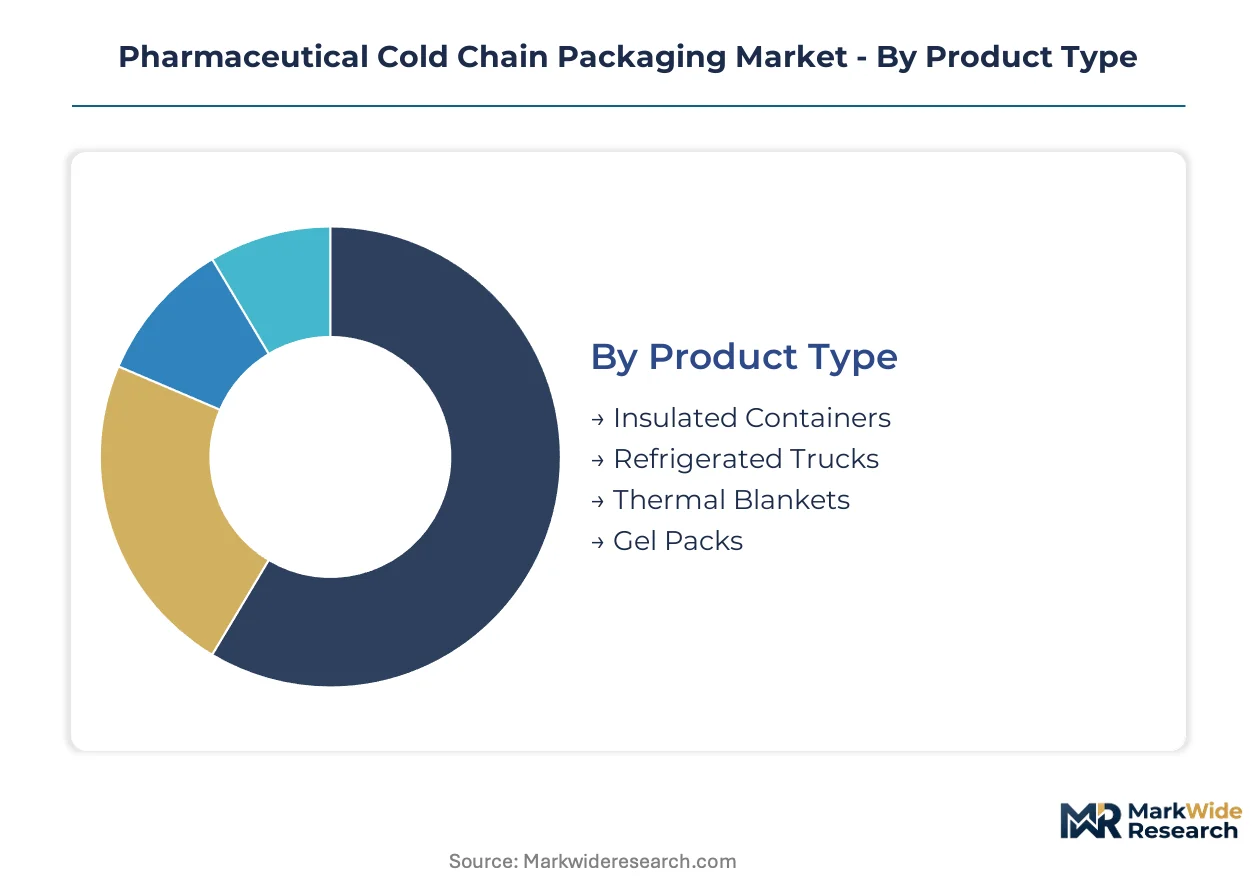
Cold chain packaging procurement patterns diverge sharply across product categories, with disposable passive systems turning weekly versus active compressor units cycling quarterly. Technology selection directly determines qualification burden and capital deployment timelines for biologics shippers.
Product Type:
Cycle times compress from multi-use refrigerated assets down to single-trip gel pack consumables, reshaping inventory management and supplier relationships across the value chain.
- Insulated Containers:Multi-layer assemblies incorporating vacuum-insulated panels or expanded polystyrene with calibrated phase-change materials. Massachusetts and North Carolina biologics clusters drive specification of 96-hour validated systems for cell therapy distribution.
- Refrigerated Trucks:Compressor-based active transport with integrated telemetry and door-open logging. German pharmaceutical exporters under EMA Good Distribution Practice mandates require documented temperature continuity across cross-border lanes into Switzerland and France.
- Thermal Blankets:Flexible quilted insulation for pallet-level protection during air freight transitions. Demand concentrates in specialty pharmacy networks needing rapid deployment for direct-to-patient oncology shipments.
- Gel Packs:Phase-change material cartridges in rigid or flexible formats for last-mile thermal mass. Consumption velocity runs highest among clinical trial logistics providers managing patient-specific dosing protocols.
Insulated containers dominate installed base. Gel packs are where expansion concentrates.
Technology:
Capital intensity separates segments, with passive systems requiring minimal infrastructure versus active platforms demanding fleet management capabilities and reverse logistics networks.
- Active Systems:Compressor-based cooling with battery or vehicle power integration, delivering precise temperature control for extended-duration shipments. WHO Model Quality Assurance System pre-qualification requirements for vaccine export programs favor validated active platforms in low- and middle-income country lanes.
- Passive Systems:Insulated enclosures relying on phase-change materials without external power, comprising vacuum-insulated panels or expanded polystyrene assemblies. FDA 21 CFR Part 211 distribution documentation mandates for gene therapies accelerate specification of qualified passive shippers with seasonal stress profile validation.
- Temperature Monitoring:Digital data loggers and cloud-connected sensors providing excursion alerts and audit trails. Integration with pharmaceutical ERP systems drives procurement decisions among large manufacturers.
- RFID Solutions:Radio-frequency identification tags enabling real-time location and condition tracking without line-of-sight scanning. The segment is expanding most quickly as regulatory compliance mandates autonomous traceability without active power dependencies.
Passive systems anchor volume throughput. RFID solutions are climbing the fastest.
End User:
Stakeholder sophistication varies from integrated manufacturers with in-house qualification laboratories to distributors outsourcing thermal mapping to specialized testing providers.
- Pharmaceutical Manufacturers:Biologics producers with internal cold chain engineering teams specifying custom thermal protection for gene therapy and cell therapy outputs. California and Massachusetts contract packagers have responded to FDA tightened guidelines by building environmental chambers or outsourcing validation.
- Logistics Providers:Third-party operators managing multi-client thermal fleets with rental models and reverse logistics included. North American oncology distribution networks show strongest preference for this asset-light approach.
- Hospitals:Acute care and specialty pharmacy buyers receiving patient-specific shipments requiring rapid container turnaround. Home infusion programs create demand for simplified handling protocols.
- Distributors:Wholesale operators consolidating temperature-controlled pharmaceutical movements across regional networks. EMA cross-border validation requirements force packaging upgrades for German and Swiss exporters.
Pharmaceutical manufacturers control specification authority. Logistics providers are gaining share fastest.
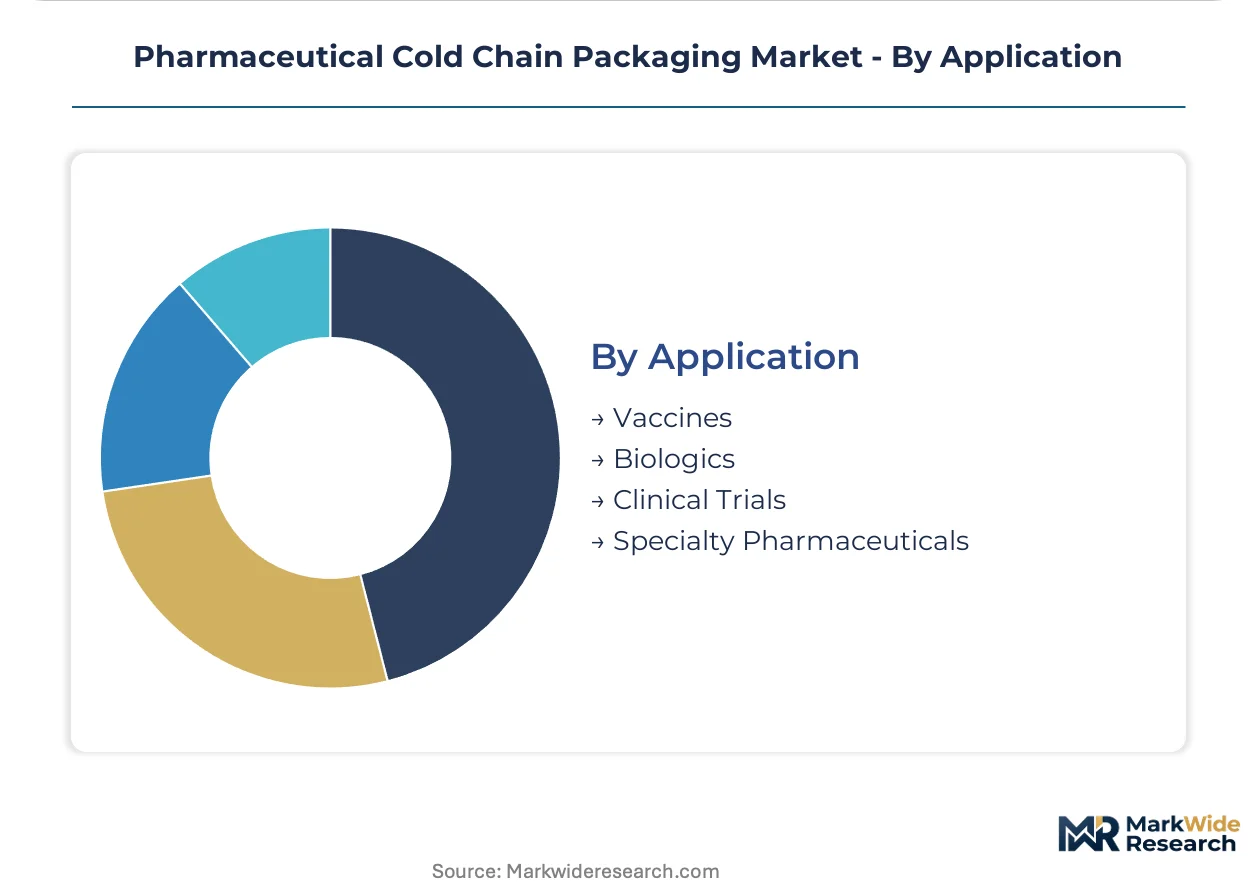
Application:
Thermal performance requirements intensify from standard 2-8°C vaccines through cryogenic gene therapy storage, with qualification timelines compressing for commercial biologics launches.
- Vaccines:Large-volume temperature-controlled distribution with established cold chain infrastructure. WHO pre-qualified packaging mandates for export programs open certified supplier slots.
- Biologics:Heat-labile protein therapeutics and monoclonal antibodies requiring stringent thermal protection. Gene therapy commercialization is forcing compressed qualification timelines for thermal packaging.
- Clinical Trials:Investigational medicinal products with patient-specific dosing and unpredictable demand patterns. Phase-change material advances enable longer-duration passive protection, reducing active system dependency.
- Specialty Pharmaceuticals:High-value orphan drugs and personalized medicines with narrow temperature bands. Direct-to-patient channels create demand for portable thermal protection with simplified protocols.
Vaccines anchor shipment volume. Biologics are where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical logistics corridor underwrites the Netherlands' role as Europe's temperature-controlled distribution gateway, handling validated cold chain documentation for German and Swiss biologics exporters.
United States
Massachusetts and North Carolina biologics manufacturing clusters generate sustained demand for qualified thermal shippers serving cell and gene therapy outputs. FDA's 21 CFR Part 211 distribution mandates require documented packaging performance across seasonal stress profiles. California contract packagers have responded by building in-house environmental chambers or outsourcing thermal mapping to specialized testing providers.
Germany
Pharmaceutical exports to Switzerland and France drive specification of EMA Good Distribution Practice-compliant refrigerated trucks with integrated telemetry. The country's national pharmaceutical regulator enforces cross-border temperature-controlled transport validation. Bavaria's production facilities anchor regional demand for vacuum-insulated panel assemblies with calibrated gel packs.
India
Vaccine export programs to low- and middle-income countries mandate WHO Model Quality Assurance System pre-qualified cold chain packaging, opening certified supplier slots. The country's national pharmaceutical regulator maintains stringent distribution documentation requirements. Maharashtra's pharmaceutical manufacturing belt concentrates domestic demand for passive thermal protection systems.
Switzerland
Gene therapy commercialization compresses qualification timelines as biologics manufacturers face distribution mandates requiring validated cold chain documentation. Swissmedic enforces strict thermal performance standards for cross-border pharmaceutical movements. Basel's biopharmaceutical cluster drives specification of sub-40mm aerogel-insulated wall profiles for air freight cube utilization.
Japan
Monoclonal antibody distribution networks require stringent 2-8°C thermal protection for heat-labile protein therapeutics. PMDA guidelines align with international cold chain validation standards for biologics shipments. The Kanto region's pharmaceutical logistics infrastructure concentrates demand for RFID-integrated temperature monitoring solutions.
Pharmaceutical Cold Chain Packaging Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying phase-change materials and vacuum-insulated panels. The vendor base organizes around three strategic archetypes: rental fleet operators controlling last-mile thermal protection, regional manufacturing hubs reducing lead times for European shippers, and air cargo partnerships dominating intercontinental vaccine lanes. Consolidation pressure intensifies as qualification laboratory capacity constraints force smaller players toward outsourcing relationships or specialized testing provider alliances.
Within the rental fleet archetype, Sonoco ThermoSafe exemplifies the asset-light service model with reverse logistics integration. Nordic Cold Chain Solutions represents the regional hub strategy through proximity manufacturing for European biologics shippers. CSafe anchors the air cargo partnership tier, occupying a position aligned with intercontinental temperature-controlled transport lanes.
| Leading Market Players |
|---|
| Sonoco ThermoSafe |
| Nordic Cold Chain Solutions |
| Cold Chain Technologies |
| EMBALL'ISO |
| Intelsius |
| CSafe |
| Cryopak |
| Chill-Pak |
| Peli BioThermal |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on East Asian vacuum-insulated panel production compresses margin structures across European packaging tiers while simultaneously forcing buyers toward longer-term contract commitments that lock in supply security at the expense of pricing flexibility. This input concentration generates a three-tier market structure where validated active systems command substantial premiums, qualified passive shippers occupy the mid-market, and commodity gel pack consumables compete on unit economics alone.
Pricing Analysis
Volume-discount tiering structures separate enterprise biologics manufacturers purchasing qualified thermal shippers under multi-year service agreements from mid-volume clinical trial operators buying spot quantities and small research institutions sourcing economy-grade expanded polystyrene assemblies. Price differentiation rests on qualification documentation depth and seasonal stress profile validation breadth, with FDA 21 CFR Part 211-compliant systems carrying substantial certification premiums. Pricing pressure stems from qualification laboratory capacity constraints extending validation timelines and inflating compliance costs. Pharmaceutical manufacturers with in-house cold chain engineering teams exhibit lowest price sensitivity, while emerging biotech startups dependent on outsourced thermal mapping face acute cost compression.
Supply Chain Analysis
Supplier-financing facilities from East Asian vacuum-insulated panel producers have become essential liquidity bridges for European packaging assemblers managing extended production cycles. Core material supply concentrates in China, Japan, and South Korea, with calibrated phase-change material chemistry anchored in German and Swiss specialty chemical production. Raw material dependencies span silica aerogel precursors, expanded polystyrene resin grades, and pharmaceutical-grade gel pack polymers. Tariff exposure on imported insulation cores presents structural risk for mid-tier European packagers lacking backward integration into captive material supply. Distribution runs through pharmaceutical logistics providers operating rental fleet models with reverse logistics integration, compressing working capital cycles for downstream buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermal engineering talent scarcity constrains supplier expansion velocity, with packaging designers possessing biologics-specific qualification experience commanding compensation premiums that mid-tier players cannot match. This capability gap creates defensive moats for incumbents with established training pipelines while simultaneously presenting acquisition opportunities for capitalized entrants seeking rapid capability accumulation.
For Market Incumbents: Pre-empt emerging RFID-PCM convergence threats by accelerating in-house development of autonomous excursion alerting systems before specialized sensor providers capture integration value. Secure backward integration into phase-change material chemistry through captive supply agreements with German specialty chemical producers, insulating margin structures from input cost volatility while accelerating qualification timelines for gene therapy launches. For New Entrants and Emerging Players: Establish a beachhead in direct-to-patient portable thermal protection systems where simplified handling protocols and rapid container turnaround requirements have outpaced incumbent rental fleet adaptation. Target specialty pharmacy networks in North American oncology distribution as the most penetrable channel, leveraging asset-light manufacturing partnerships with regional thermoforming specialists to bypass capital-intensive environmental chamber investments. For Investors and Strategic Acquirers: Regional testing laboratories with WHO Model Quality Assurance System accreditation represent the most attractive acquisition archetype, given qualification bottlenecks delaying product launches and forcing biologics manufacturers toward outsourced validation relationships. Long-term viability favors platform integrators controlling both thermal protection hardware and digital traceability software layers. Watch FDA enforcement patterns on gene therapy distribution documentation as the critical inflection signal—accelerated inspection intensity would compress qualification timelines and concentrate demand among pre-validated supplier networks.| Strategic Initiative | Industry Significance |
|---|---|
| Qualification Laboratory Expansion | EMA and FDA validation backlogs force biologics manufacturers toward outsourced thermal mapping partnerships. |
| Aerogel Insulation Integration | Sub-40mm wall profiles enable higher air freight cube utilization for Basel gene therapy exporters. |
| RFID-PCM Convergence Development | Autonomous excursion alerting without active power addresses WHO pre-qualification mandates for vaccine export programs. |
| Regional Manufacturing Hub Establishment | Proximity production for European biologics shippers reduces lead times and EMA cross-border documentation burdens. |
| Rental Fleet Model Scaling | Reverse logistics integration shifts performance risk to packaging service providers in North American oncology networks. |
Study Parameters
A standing panel of cold chain engineering directors, regulatory affairs leads at biologics manufacturers, pharmaceutical logistics procurement managers, and thermal testing laboratory operators provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA 21 CFR Part 211 guidance documents, EMA Good Distribution Practice guidelines, WHO Model Quality Assurance System technical reports, and ClinicalTrials.gov protocol specifications. Bottom-up demand modeling across insulated container, refrigerated truck, thermal blanket, and gel pack categories triangulated against top-down pharmaceutical export value flows from Germany, Switzerland, and the United States.
Scenario-bracketing framed demand projections across the analysis window, with segmentation dimensions spanning product type, technology platform, end-user sophistication tier, and application thermal intensity. Treatment line positioning, dosage form stability requirements, and regional regulatory cluster stringency informed industry-specific forecast inputs. CAGRs were derived from elasticity-adjusted volume trajectories reconciled with capital deployment patterns visible in pharmaceutical logistics provider fleet disclosures.
Stress conditions across vacuum-insulated panel supply disruptions, qualification laboratory capacity constraints, and EMA-FDA regulatory divergence were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on biologics manufacturing cluster expansion rates and gene therapy commercialization velocity. Macroeconomic contraction affecting pharmaceutical R&D budgets, regulatory harmonization accelerating qualification standardization, or breakthrough active cooling miniaturization would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cold Chain Packaging
North America Passive Temperature Controlled Packaging Market
Cold Chain Packaging
Cold Chain Equipment Market
Cold Chain Packaging
Cryogenic Capsules Market
Cold Chain Packaging
Cold Chain Market
Cold Chain Packaging
North America Food Cold Chain Logistics Market
Cold Chain Packaging
Insulated Food Delivery Bags Market
Cold Chain Packaging
Cold Box Module Market
Cold Chain Packaging
Middle East and Africa Frozen Food Packaging Market
Cold Chain Packaging
Foam Cooler Box Market
Cold Chain Packaging
Cold Storage Insulated Market
Cold Chain Packaging
Cold Chain Packaging Market
Cold Chain Packaging
China Cold Chain Market
Cold Chain Packaging
Europe Healthcare Cold Chain Logistics Market
Cold Chain Packaging
Fish Boxes Market
Cold Chain Packaging
Europe Cold Chain Tracking and Monitoring Market
Cold Chain Packaging
Global Cold Chain Tracking and Monitoring Market