
 Fish Boxes Market | 2026-2036
Fish Boxes Market Size, Share, and Industry Trends Forecast 2026-2036
Fish Boxes Market Foresight
Norway is tilting toward expanded insulated box capacity to serve North Atlantic cod and salmon export corridors. Smurfit Kappa leverages its corrugated fiberboard expertise to dominate Nordic retail-ready seafood packaging. DS Smith anchors its position through circular-design reusable containers that align with Scandinavian retailer sustainability mandates. BASF SE competes by supplying high-performance foam formulations that extend thermal protection windows for long-haul seafood logistics.
Fish boxes are rigid or semi-rigid containers engineered from expanded polystyrene, corrugated fiberboard, or biodegradable polymers with wall thicknesses typically ranging from 25 mm to 100 mm to maintain cold chain integrity between minus 2°C and 4°C for fresh product. Their primary commercial purpose is to prevent protein degradation, moisture loss, and microbial contamination during maritime and air transit of perishable seafood. Corrugated fiberboard variants lead volume in European short-haul distribution where single-trip economics dominate, while insulated boxes command margin pools in premium fresh-fish air freight to Asian wholesale markets. Reusable containers represent the fastest-growing product type as Dutch and Danish supermarket chains enforce return-loop packaging protocols.
The EU's Single-Use Plastics Directive and REACH chemical compliance frameworks are reshaping material substitution timelines, with EFSA food-contact approvals becoming gating requirements for novel biodegradable polymer entrants. FDA marine sanitation and HACCP alignment in the United States further fragments product certification burdens for exporters serving multiple regulatory jurisdictions. Stakeholders must monitor how divergent biodegradability testing standards between ECHA and FDA protocols influence R&D allocation and regional production siting decisions.
Market Dynamics
The EU's Single-Use Plastics Directive is forcing material substitution timelines across seafood packaging supply chains, compressing the window for biodegradable polymer validation while insulated corrugated fiberboard gains transitional share.
Growth Catalysts
- EFSA food-contact approvals:Novel biodegradable polymer entrants require EFSA clearance to access European seafood logistics, accelerating R&D investment in polylactic acid and starch-based formulations.
- Iceland's integrated fishery zones:Dense vertical cold chain infrastructure in Icelandic processing clusters concentrates demand for high-performance insulated boxes with extended thermal windows.
- Temperature-controlled packaging expansion:Norwegian seafood processors are scaling insulated box capacity to serve North Atlantic cod and salmon export corridors into Asian wholesale markets.
Market Restraints
- Polystyrene feedstock volatility:Expanded polystyrene resin prices fluctuate with benzene and styrene monomer markets, squeezing margin pools for single-use insulated box manufacturers.
- Divergent biodegradability testing standards:ECHA and FDA protocols lack harmonization, fragmenting certification burdens and forcing regional production siting decisions that limit scale economies.
- Reusable container capex intensity:Dutch and Danish supermarket return-loop protocols require upfront investment in RFID-tracked container fleets and reverse logistics infrastructure.
Strategic Opportunities
- Biodegradable polymer regulatory tailwind:REACH chemical compliance frameworks and EU Green Deal targets create mandated demand pull for compostable alternatives to fossil-based insulation.
- Air freight premium segment:Fresh-fish air freight to Asian wholesale markets commands insulated box margin pools where thermal protection windows determine protein quality premiums.
- Scandinavian retailer sustainability mandates:Circular-design reusable containers align with procurement criteria from Coop Denmark and ICA Sweden, opening closed-loop service contracts.
Industry Challenges
- HACCP alignment complexity:Exporters serving both FDA marine sanitation jurisdictions and EU food-contact frameworks face dual certification timelines that delay product launches.
- Legacy EPS molding asset stranding:Converters with sunk costs in expanded polystyrene tooling face write-down pressure as biodegradable polymer capacity scales.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fish Boxes Market |
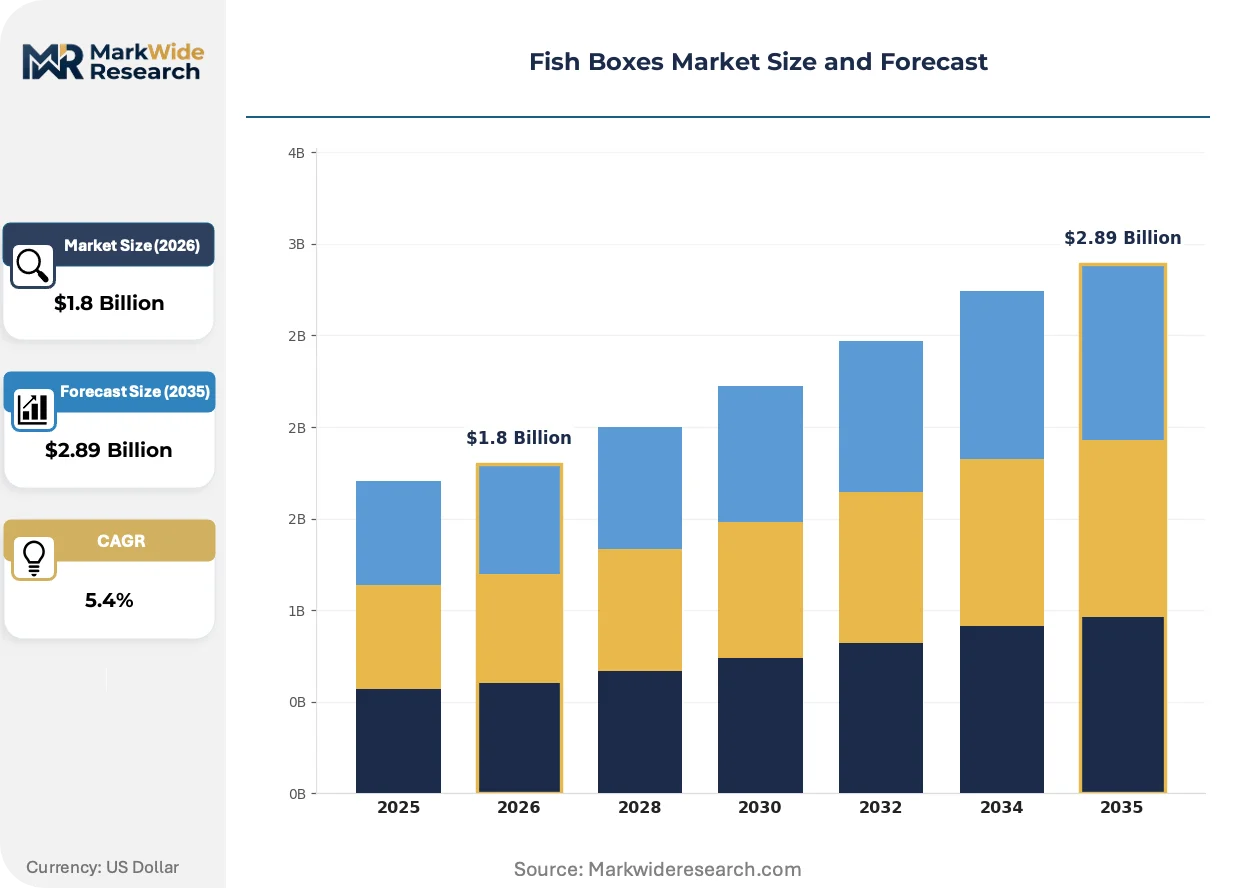
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.89 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Plastic, Corrugated Fiberboard, Foam, Aluminum, Biodegradable Polymers Product Type: Insulated Boxes, Non-Insulated Boxes, Reusable Containers, Disposable Containers, Collapsible Boxes Application: Seafood Transport, Fresh Fish Storage, Frozen Fish Packaging, Aquaculture Shipping, Fish Processing End User: Fishery Collectors, Seafood Processors, Wholesalers, Exporters, Cold Storage Facilities |
| Companies Covered | BASF SE, Smurfit Kappa, Snyder Industries, DS Smith, Sekisui Kasei Co., Ltd., Tri-Core Plastics Containers Ltd., Craemer GmbH, CRT Packaging, Styropack, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fish Boxes Market Shifts & Advancements
Digital twin platforms are virtualizing thermal performance validation, compressing prototyping cycles while regulatory material bans accelerate substitution investment across Nordic seafood corridors.
Phase-change material integration is virtualizing passive cooling performance in fiberboard fish boxes, allowing thinner wall constructions without thermal protection degradation. Norwegian salmon exporters are piloting bio-based PCM formulations at scale. This virtualization is compressing the performance gap between corrugated and molded insulation, eroding polystyrene's historical advantage in long-haul routes.
REACH chemical compliance frameworks are tightening food-contact substance restrictions, forcing converters to reformulate coatings and adhesives ahead of sunset dates. The industrial consequence is accelerated qualification timelines for novel barrier layers. Premium fresh-fish segments serving Asian markets are responding by consolidating supplier bases to reduce audit burden.
Buyer consolidation among Nordic retail chains is compressing switching cycles and unbundling packaging procurement from logistics contracts. ICA Sweden and Coop Denmark now specify return-loop protocols in tender documents, displacing single-trip economics. This shift concentrates most visibly in short-haul distribution corridors where reverse logistics density supports container pooling.
Fish Boxes Market Segmentation
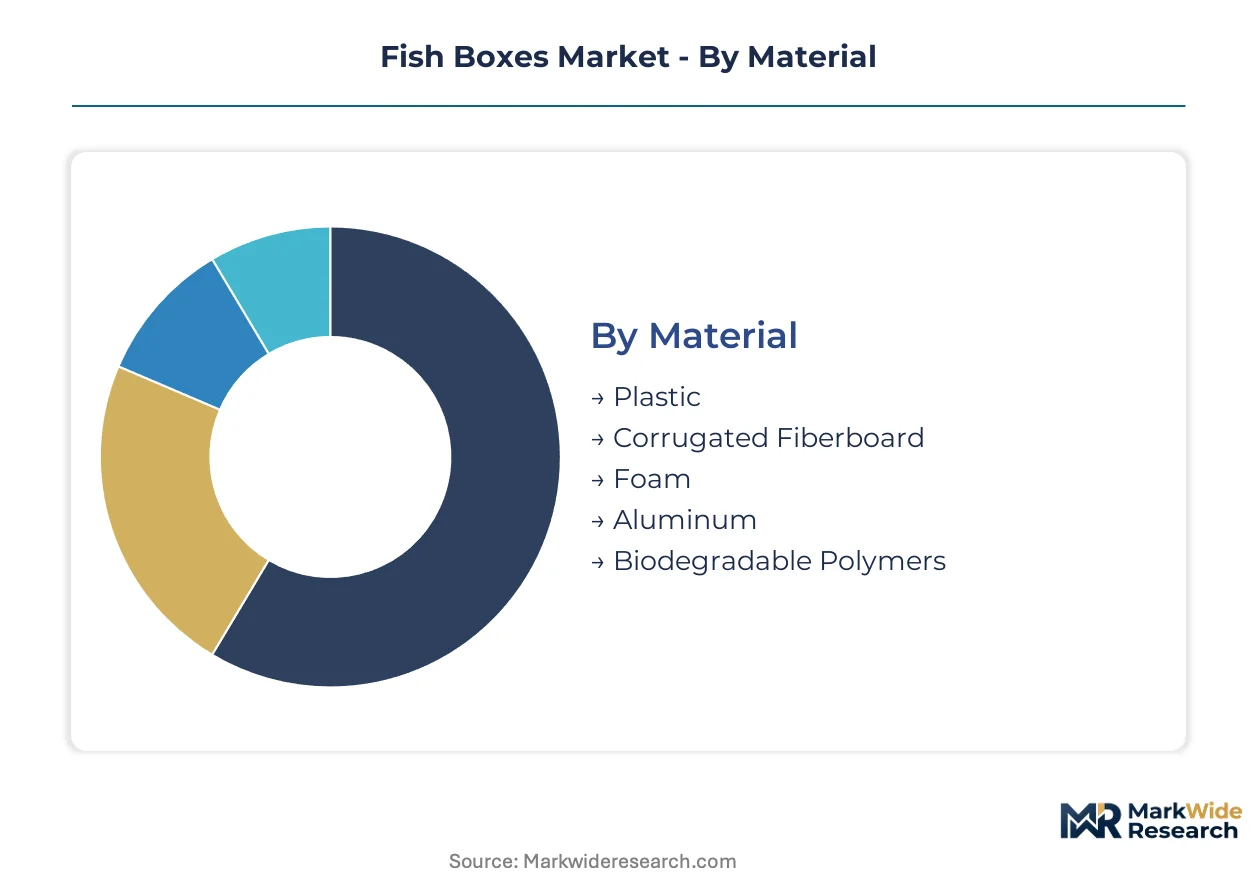
Fish box segmentation maps directly to cold chain economics, where material choice governs thermal performance and product type determines reuse economics across Nordic seafood corridors. Distinct application requirements for fresh versus frozen product create divergent specification clusters that shape procurement patterns.
Material:
Use-case spectrum spans single-trip corrugated fiberboard for domestic distribution through engineered foam systems for transoceanic air freight.
- Plastic:Polyethylene and polypropylene formulations dominate injection-molded reusable containers with RFID tracking integration. Dutch supermarket return-loop protocols concentrate demand for durable polymer boxes that withstand 50+ wash cycles.
- Corrugated Fiberboard:Triple-wall constructions with wax coatings lead European short-haul volume where single-trip economics dominate and EFSA food-contact compliance is straightforward. Smurfit Kappa anchors Nordic supply for retail-ready seafood packaging through this segment.
- Foam:Expanded polystyrene retains share in premium air freight corridors despite EU Single-Use Plastics Directive pressure.
- Aluminum:Lightweight alloy containers serve high-value sashimi-grade tuna shipments requiring rigid impact protection.
- Biodegradable Polymers:Polylactic acid and starch-based formulations are gaining trial placements ahead of REACH sunset dates for fossil-based insulation.
Established volume favors corrugated fiberboard; emerging adoption favors biodegradable polymers.
Product Type:
Cost tier segmentation separates capital-intensive reusable fleets from disposable units optimized for landed cost per kilogram of seafood moved.
- Insulated Boxes:Wall thicknesses from 25 mm to 100 mm maintain minus 2°C to 4°C windows for fresh cod and salmon exports. Norwegian processors are scaling capacity for Asian wholesale markets where thermal protection determines protein quality premiums.
- Reusable Containers:Circular-design units with embedded tracking align with Scandinavian retailer sustainability mandates from Coop Denmark and ICA Sweden. These containers are expanding most quickly as return-loop infrastructure matures in dense vertical cold chain zones.
- Non-Insulated Boxes:Unlined corrugated units serve frozen product where mechanical protection outweighs thermal management.
- Disposable Containers:Single-use molded pulp and fiberboard variants face regulatory compression under EU Green Deal targets.
- Collapsible Boxes:Space-efficient designs reduce backhaul costs for empty container positioning in remote fishing ports.
Capital deployment favors insulated boxes; operational efficiency gains favor collapsible formats.
Application:
Application segmentation follows temperature protocol divergence between fresh and frozen supply chains.
- Seafood Transport:Maritime and air freight corridors from Iceland and Norway into Asian wholesale markets command premium insulated specifications with extended thermal windows.
- Fresh Fish Storage:Short-duration holding in processing plants drives demand for stackable, drain-equipped designs that maintain ice contact.
- Frozen Fish Packaging:Mechanical protection focus allows thinner-wall constructions with vapor barrier coatings rather than full insulation.
- Aquaculture Shipping:Live transport applications require oxygen-permeable materials and specialized interior geometries.
- Fish Processing:In-plant material handling favors washable, chemical-resistant surfaces that withstand sanitation protocols.
Margin concentration sits with seafood transport; standardization pressure weighs on fish processing procurement.
End User:
Customer type segmentation reveals divergent specification authority between integrated processors and fragmented collection points.
- Seafood Processors:Vertically integrated Norwegian and Icelandic operators specify custom thermal profiles and branding requirements that drive value-added box design.
- Exporters:Multi-jurisdiction operators face dual FDA marine sanitation and EU food-contact certification burdens that consolidate supplier relationships.
- Fishery Collectors:Small-vessel operators prioritize low acquisition cost and stackability for deck storage constraints.
- Wholesalers:Intermediate handlers emphasize interchangeability across multiple species and origin points.
- Cold Storage Facilities:Automated warehouse operators specify dimensional standardization for pallet optimization and conveyor compatibility.
Specification authority concentrates with seafood processors; price sensitivity dominates fishery collector procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA food-contact compliance frameworks anchor European seafood packaging demand, with Nordic processing clusters driving insulated box specifications. Norwegian salmon exporters and Icelandic cod processors set thermal performance benchmarks that propagate through North Atlantic supply chains.
Norway
North Atlantic cod and salmon export corridors dominate insulated box procurement, with processors scaling temperature-controlled packaging for Asian wholesale markets. The Norwegian Food Safety Authority enforces HACCP alignment with EU food-contact frameworks. Bergen and Tromsø processing clusters concentrate demand for high-performance foam formulations with extended thermal windows.
Iceland
Vertically integrated fishery zones generate dense demand for premium insulated specifications, where cold chain infrastructure density supports return-loop container protocols. REACH chemical compliance drives coating reformulation timelines for local converters. Reykjanesbær and Akureyri processing hubs anchor domestic production capacity for transoceanic air freight segments.
United States
FDA marine sanitation requirements fragment certification burdens for exporters serving dual-jurisdiction markets, consolidating supplier relationships among multi-regional operators. HACCP alignment with EU frameworks delays product launch timelines. Seattle and Boston seafood processing metros drive demand for standardized dimensional specifications compatible with automated cold storage infrastructure.
Denmark
Scandinavian retailer sustainability mandates from Coop Denmark accelerate circular-design container adoption, displacing single-trip economics in short-haul distribution. The EU Single-Use Plastics Directive compresses material substitution timelines for domestic converters. Esbjerg fishing port infrastructure supports dense return-loop logistics for reusable container pooling systems.
Japan
Premium sashimi-grade tuna shipments command lightweight alloy container specifications requiring rigid impact protection during air freight transit. METI industrial standards influence thermal performance benchmarking for imported seafood logistics. Tokyo and Osaka wholesale markets concentrate specification authority for high-value fresh fish segments.
Fish Boxes Market Competitive Landscape
Capability concentration sits with specialty chemical suppliers and fiberboard engineers; scale advantage sits with integrated packaging converters and multinational materials conglomerates. The vendor base stratifies across three tiers: raw material formulators, structural packaging designers, and logistics-integrated container service providers. Dominant competitive moves include backward integration into bio-based feedstock cultivation and strategic partnerships with Nordic seafood processors for co-developed thermal specifications.
Within the materials-formulator tier, BASF SE anchors high-performance foam chemistry supply for extended thermal protection windows. Among integrated packaging specialists, Smurfit Kappa and DS Smith exemplify divergent strategic positions—corrugated fiberboard volume leadership versus circular-design reusable container systems. These three entities represent distinct competitive archetypes: chemical performance optimization, commodity-scale manufacturing efficiency, and closed-loop service model innovation.
| Leading Market Players |
|---|
| BASF SE |
| Smurfit Kappa |
| Snyder Industries |
| DS Smith |
| Sekisui Kasei Co., Ltd. |
| Tri-Core Plastics Containers Ltd. |
| Craemer GmbH |
| CRT Packaging |
| Styropack |
| Others |
Supply & Pricing Matrix
Bergen and Tromsø processing clusters concentrate Nordic insulated box capacity, giving Norwegian seafood exporters leverage over converters through volume commitments and co-developed thermal specifications that compress margin pools for single-use manufacturers.
Pricing Analysis
Asian wholesale markets command 40-60% premiums over European short-haul corridors for identical insulated specifications, with price differentiation driven by thermal protection duration and EFSA food-contact certification tier. Three-tier pricing structure across premium air-freight, standard maritime, and economy domestic segments is compressing at the bottom as biodegradable polymer scale erodes expanded polystyrene cost advantages. Margins are tightening in single-use fiberboard segments because Dutch and Danish retailer return-loop mandates displace transactional volume. Fishery collectors exhibit highest price sensitivity, while integrated Norwegian processors prioritize thermal performance over unit cost.
Supply Chain Analysis
Smurfit Kappa and DS Smith hold dominant contract-manufacturing positions in European corrugated fiberboard, while BASF SE anchors foam chemistry supply for extended thermal window formulations. Manufacturing concentrates in Norway, Denmark, and Germany, with raw material flows drawing from Swedish timber pulp, German petrochemical feedstocks, and Icelandic fishing port collection points. Single-source vulnerability runs through benzene and styrene monomer markets that govern expanded polystyrene resin pricing. Distribution runs through vertically integrated seafood processors that bundle packaging procurement with logistics contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Single-Use Plastics Directive creates a regulatory inflection that will displace fossil-based insulation faster than biodegradable polymer capacity can scale, compressing substitution timelines and concentrating procurement power among converters with validated compostable formulations.
For Market Incumbents: Harden thermal performance validation capabilities through digital twin platforms that compress prototyping cycles before REACH sunset dates strand legacy EPS molding assets. Prioritize backward integration into bio-based feedstock cultivation to secure polylactic acid supply chains against novel entrant competition. Lock in multi-year service contracts with ICA Sweden and Coop Denmark before return-loop infrastructure matures.
For New Entrants and Emerging Players: Build out biodegradable polymer compounding capacity in Icelandic fishery zones where dense vertical cold chain infrastructure supports premium pricing for compostable alternatives. Target Norwegian salmon exporters seeking EFSA-cleared starch-based formulations for Asian air freight corridors. Lead with closed-loop container pooling services that displace single-trip economics in short-haul distribution.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors converters with validated food-contact approvals and captive bio-feedstock supply. Five-to-ten year viability hinges on regulatory compliance moats rather than manufacturing scale alone. Watch EFSA clearance timelines for novel polymer entrants as the inflection signal that separates viable acquisition targets from stranded capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Polymer Scale-Up | REACH compliance deadlines create mandated demand pull for compostable alternatives to fossil-based insulation. |
| Digital Twin Thermal Validation | Virtual prototyping platforms compress qualification timelines for novel barrier layers ahead of regulatory sunsets. |
| Return-Loop Infrastructure Investment | RFID-tracked container fleets align with Coop Denmark and ICA Sweden sustainability procurement criteria. |
| Backward Integration into Bio-Feedstock | Captive polylactic acid supply secures margin pools against commodity resin volatility and novel entrant competition. |
| Multi-Jurisdiction Certification Investment | Dual FDA marine sanitation and EFSA food-contact clearance opens access to premium Asian wholesale market segments. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with seafood processors, packaging procurement managers, cold chain logistics operators, and regulatory affairs specialists; and secondary validation through customs trade databases, EFSA food-contact approval registers, EU Single-Use Plastics Directive implementation reports, and SEC filings from listed packaging converters. Bottom-up volume modeling triangulated against top-down market sizing across material, product type, and application segments.
Forecast inputs considered biodegradable polymer substitution rates, REACH chemical compliance timelines, and air freight volume growth across Nordic-Asia corridors. Segmentation dimensions modeled include material chemistry tier, thermal protection duration, reuse protocol type, end-user specification authority, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion announcements throughout the forecast period.
Stress conditions across styrene monomer price volatility, EFSA approval delays, and Nordic retailer return-loop adoption speed were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and bio-polymer manufacturing scale. Quarterly review of EFSA novel food-contact clearance timelines and EU member state Single-Use Plastics Directive implementation variance is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cold Chain Packaging
Cold Chain Micro-Fulfillment Hub Networks Market
Cold Chain Packaging
Insulated Coolers Market
Cold Chain Packaging
Foam Cooler Box Market
Cold Chain Packaging
Cold Chain Market
Cold Chain Packaging
Cooling Boxes Market
Cold Chain Packaging
Insulated Food Delivery Bags Market
Cold Chain Packaging
North America Cold Chain Market
Cold Chain Packaging
Middle East and Africa Frozen Food Packaging Market
Cold Chain Packaging
Cold Chain Integrity and Shock Monitoring Test Devices Market
Cold Chain Packaging
Food Cold Chain Market
Cold Chain Packaging
Biopharma Cold Chain Packaging Market
Cold Chain Packaging
Cold Chain Packaging Pooling and Reverse Logistics Services Market
Cold Chain Packaging
Europe Healthcare Cold Chain Logistics Market
Cold Chain Packaging
Cryogenic Capsules Market
Cold Chain Packaging
Europe Cold Chain Tracking and Monitoring Market
Cold Chain Packaging
Latin America Pharmaceutical Cold Chain Logistics Market