
 North America Food Cold Chain Logistics Market | 2026-2036
North America Food Cold Chain Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
North America Food Cold Chain Logistics Market Insights
Last-mile temperature-controlled delivery is reshaping margin distribution across the North America food cold chain logistics sector. Americold Logistics leverages its integrated warehousing and transportation platform to sustain national coverage. Lineage Logistics anchors its position through automated cold storage infrastructure spanning key distribution nodes. Henningsen Cold Storage specializes in regional protein handling, occupying a defensible niche in Pacific Northwest meat and seafood corridors.
Food cold chain logistics encompasses the temperature-managed movement and storage of perishable food products from origin through consumption, requiring continuous maintenance between 0°F and 40°F for frozen and fresh categories respectively through mechanical refrigeration, thermal insulation, and real-time environmental monitoring to prevent spoilage, contamination, and shelf-life degradation. The primary commercial purpose centers on extending viable distribution radius for temperature-sensitive agricultural and protein products while preserving nutritional integrity and safety compliance across extended supply networks. Road Transportation dominates volume movement for domestic produce and dairy given infrastructure density and scheduling flexibility, while Monitoring Solutions represents the fastest-expanding technology category as shippers replace passive data loggers with cloud-connected IoT sensors that enable intervention before threshold breaches occur. Seafood commands premium logistics spend due to strict continuous freezing requirements and short tolerance windows that demand redundant backup systems and expedited handling protocols.
The FDA's Food Safety Modernization Act mandates preventive controls and documented temperature records across all transport modes, compelling fleet operators to upgrade monitoring infrastructure or face enforcement action. The USDA's Agricultural Marketing Service enforces grade standards and inspection protocols that influence handling procedures for meat and produce entering interstate commerce. California's Air Resources Board imposes emissions regulations on refrigerated transport equipment that accelerate diesel-to-electric conversion timelines for fleets operating in the state's corridors. Stakeholders must weigh capital deployment between automated warehouse robotics and electrified fleet infrastructure as regulatory compliance costs diverge across state boundaries.
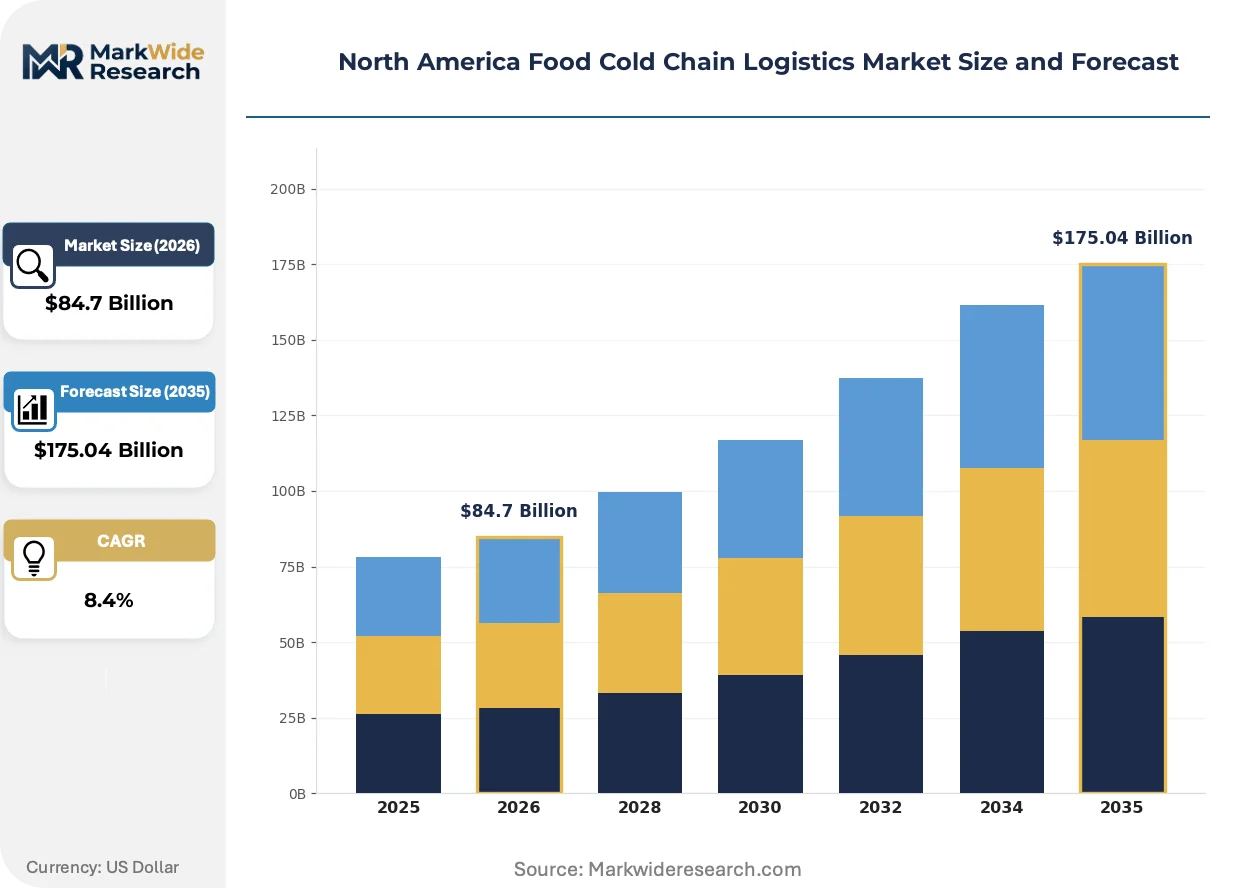
Market Dynamics
California's Air Resources Board mandates for zero-emission refrigerated transport are compressing fleet replacement timelines and forcing capital reallocation toward electric reefer units and charging infrastructure across the Texas-California corridor.
Growth Catalysts
- FDA Food Safety Modernization Act:Mandatory preventive controls and continuous temperature documentation compel fleet-wide monitoring upgrades, expanding demand for cloud-connected IoT sensor networks.
- Frozen seafood distribution:Restaurant chain procurement of premium marine proteins requires redundant freezing systems and expedited handling protocols that sustain premium logistics spend.
- Automated cold storage:Robotics deployment in high-throughput distribution nodes reduces labor dependency and enables 24-hour processing windows for cross-border produce flows.
Market Restraints
- Diesel-to-electric conversion capex:Refrigerated transport electrification demands dual investment in vehicle platforms and depot charging infrastructure, straining mid-size operator balance sheets.
- Specialized technician scarcity:Cryogenic system maintenance and IoT sensor calibration require certified personnel concentrations that lag fleet expansion rates in secondary corridors.
- Cross-border inspection friction:USDA Agricultural Marketing Service grade enforcement at interstate entry points introduces handling delays that compress shelf-life windows for fresh produce.
Strategic Opportunities
- Last-mile temperature-controlled delivery:Direct-to-restaurant and direct-to-retailer models bypass traditional distribution layers, capturing margin previously allocated to intermediary warehousing.
- Texas-California corridor density:Strategic positioning along this axis enables synchronized cross-border produce flows with Mexican agricultural zones and Pacific Northwest protein sources.
- Cloud-connected sensor convergence:Integration of real-time environmental monitoring with predictive analytics platforms enables intervention before threshold breaches, reducing spoilage liability.
Industry Challenges
- Legacy fleet integration complexity:Retrofitting existing refrigerated trailers with electric refrigeration units and telemetry systems requires custom engineering that extends deployment timelines.
- Multi-jurisdiction compliance navigation:Operators must maintain simultaneous adherence to FDA temperature documentation, USDA inspection protocols, and state-level emissions standards with divergent phase-out schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Food Cold Chain Logistics Market |
| Market Size in 2026 | $84.7 Billion |
| Market Size in 2035 | $175.04 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruits, Vegetables, Seafood, Dairy Delivery Mode: Air Freight, Ocean Freight, Road Transportation, Rail Transportation End User: Restaurants, Supermarkets, Wholesalers, Grocery Stores Technology: Refrigeration Systems, Monitoring Solutions, Insulated Containers, IoT Sensors |
| Companies Covered | United States Refrigerated Storage, Henningsen Cold Storage, Americold Logistics, Preferred Freezer, Agro Merchant Group, Lineage Logistics, Tippmann Group, Nordic Logistics, Burris Logistics, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Food Cold Chain Logistics Market Trends and Innovations
Active sensor networks and predictive analytics are compressing response windows for temperature excursions, while regulatory pressure on transport emissions accelerates hardware replacement cycles across the region.
Telematics-enabled reefer units equipped with continuous environmental logging is collapsing the latency between threshold breach and corrective action. Large produce distributors and seafood importers are deploying these systems fleet-wide within 18-month procurement cycles. Real-time visibility is collapsing the insurance risk premiums previously assigned to undocumented temperature gaps.
The FDA's Food Safety Modernization Act preventive controls mandate requires documented temperature records across all transport modes. Fleet operators face enforcement exposure that compels capital deployment toward automated monitoring infrastructure. Frozen protein and dairy segments operating multi-state networks are consolidating supplier relationships to reduce compliance verification burden.
Restaurant chains are consolidating direct procurement relationships with cold chain operators, displacing traditional foodservice distribution intermediaries. Large casual dining and quick-service networks now contract directly for temperature-managed delivery of frozen seafood and prepared proteins. This channel compression is most visible in California and Texas metropolitan zones where warehousing density supports scheduled daily replenishment cycles.
North America Food Cold Chain Logistics Market Segmentation
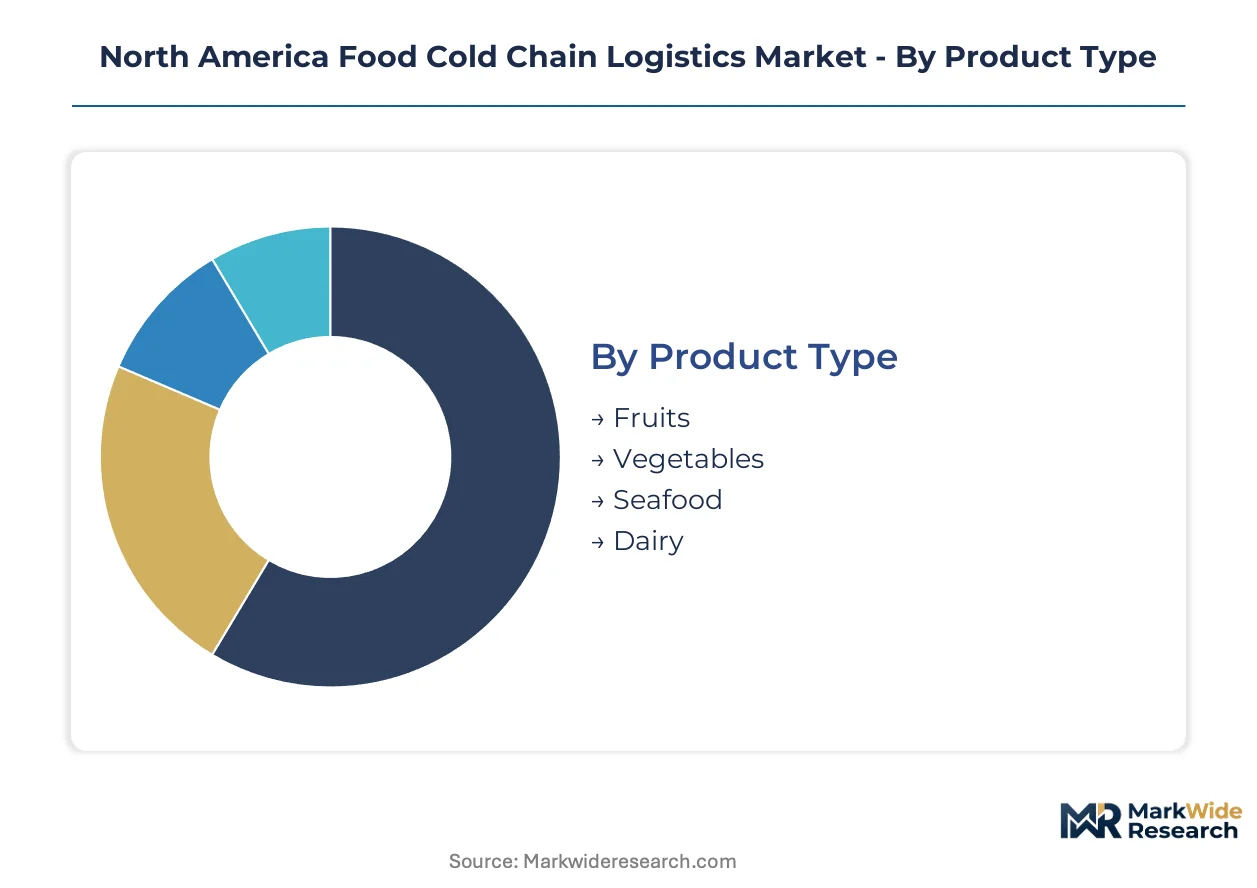
Segmentation in North American food cold chain logistics reveals how temperature requirements, transport economics, and regulatory compliance create distinct operational profiles. Each dimension shapes capital allocation, fleet configuration, and margin structures differently across the value chain.
Product Type:
After-sales service intensity varies sharply by product category, with frozen seafood demanding redundant system maintenance and 24-hour emergency response capabilities that dairy and produce segments rarely require.
- Seafood:Continuous freezing between -10°F and 0°F mandates dual-compressor redundancy and backup power systems. Restaurant chains in California and Texas metropolitan zones drive premium logistics spend through strict zero-defect handling protocols and expedited cross-dock requirements.
- Dairy:Temperature maintenance between 32°F and 40°F with minimal fluctuation tolerance shapes fleet specifications and route scheduling. Fluid milk distribution to supermarket chains concentrates in the Upper Midwest and Northeast corridors where processing plants anchor regional hub networks.
- Fruits:Ethylene-sensitive varieties require controlled atmosphere capabilities and rapid pre-cooling infrastructure. Mexican import flows through Texas border crossings dominate volume movement during seasonal harvest windows.
- Vegetables:Leafy greens and delicate produce categories impose compressed shelf-life windows that favor short-haul road transport over intermodal alternatives. Direct-to-retailer models are displacing traditional wholesale layers in California growing regions.
By volume, fruits lead product flows. By growth pace, seafood is ahead.
Delivery Mode:
Cost tier positioning separates capital-intensive modes from asset-light alternatives, with refrigerated trucking occupying the mid-market sweet spot between premium air freight and economy ocean routes.
- Road Transportation:Diesel and emerging electric reefer fleets provide scheduling flexibility and door-to-door coverage that intermodal combinations cannot match. The Texas-California corridor supports highest asset utilization through dense produce and protein flows.
- Air Freight:Premium temperature-controlled cargo holds serve high-value seafood and specialty produce with sub-24-hour delivery requirements. Per-unit logistics costs run multiples above surface alternatives, limiting deployment to emergency replenishment and luxury foodservice channels.
- Ocean Freight:Containerized reefer vessels handle frozen protein imports from Asian and South American sources through West Coast ports. Extended transit times demand precise container pre-cooling and vessel power reliability.
- Rail Transportation:Intermodal refrigerated units offer fuel efficiency for long-haul bulk movements between major distribution nodes. Chicago and Memphis rail hubs concentrate transload activity for Midwest produce distribution.
Road Transportation dominates domestic volume. Air Freight claims the steepest expansion trajectory for direct-to-restaurant premium channels.
End User:
Customer type determines service level requirements, with restaurant chains demanding scheduled daily replenishment that grocery and wholesale channels structure around weekly or bi-weekly cycles.
- Restaurants:Quick-service and casual dining networks contract directly with cold chain operators for frozen protein and prepared ingredient delivery. California and Texas metropolitan density supports dedicated fleet deployment with multiple daily drops.
- Supermarkets:Large-format retailers operate captive distribution networks or contract dedicated capacity for store replenishment. Regional consolidation among grocery chains is reducing supplier counts and lengthening contract terms.
- Wholesalers:Traditional foodservice intermediaries face margin compression as restaurant chains bypass their warehousing layers. Surviving operators specialize in small-format independent restaurants that lack volume for direct procurement.
- Grocery Stores:Independent and small-chain formats rely on third-party logistics for temperature-managed delivery. Last-mile consolidation platforms are emerging to aggregate fragmented demand in secondary markets.
Supermarkets anchor volume demand. Restaurants are gaining share fastest through channel compression.
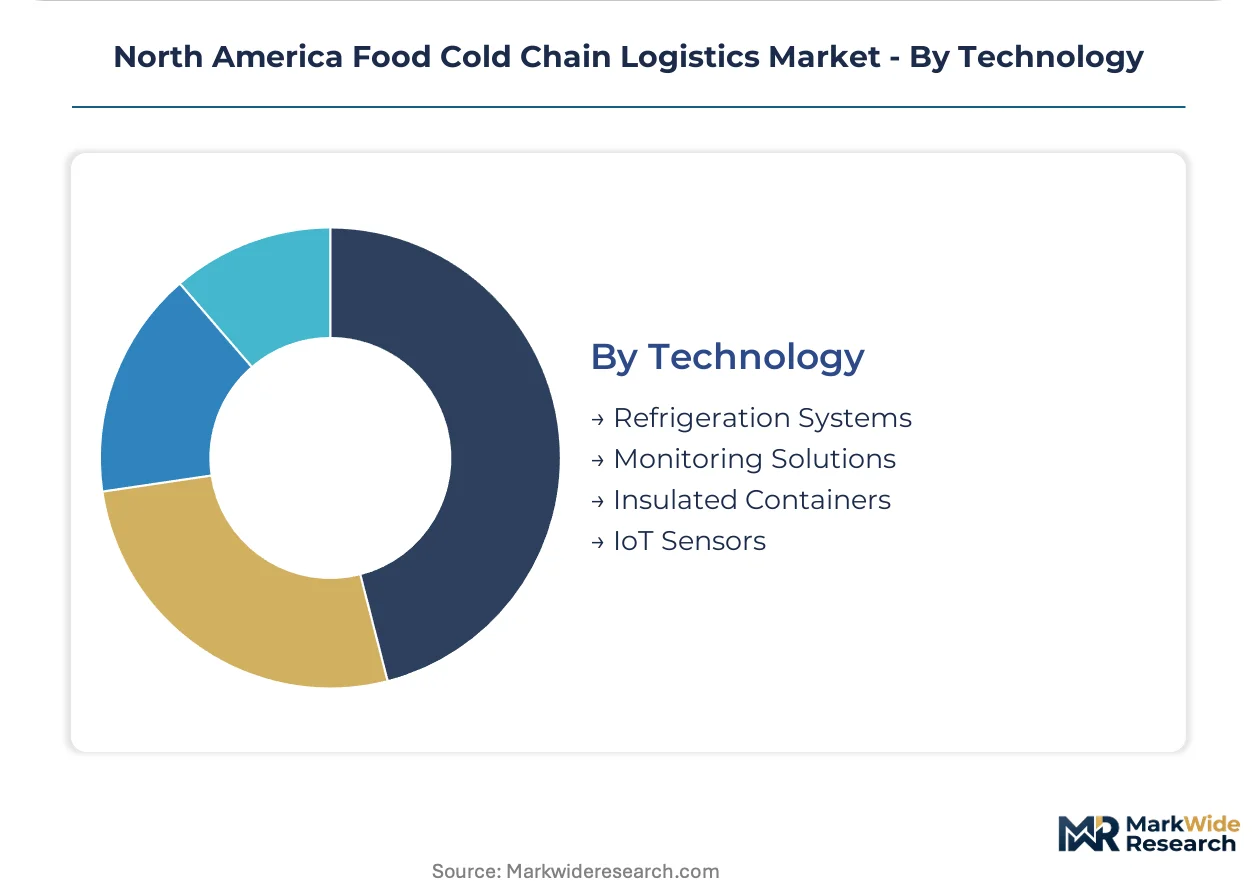
Technology:
Maturity curves separate established mechanical systems from emerging digital platforms, with IoT sensors and predictive analytics representing the steepest investment ramp among technology categories.
- Monitoring Solutions:Cloud-connected environmental logging platforms enable real-time intervention before threshold breaches occur. FDA Food Safety Modernization Act documentation mandates are accelerating fleet-wide deployment across multi-state operators.
- Refrigeration Systems:Diesel-powered transport refrigeration units face California Air Resources Board phase-out timelines that compress replacement cycles. Electric and hybrid alternatives require parallel charging infrastructure investment.
- IoT Sensors:Distributed temperature and humidity probes with cellular connectivity replace passive data loggers. Seafood and dairy segments lead adoption due to strict continuous monitoring requirements and spoilage liability exposure.
- Insulated Containers:Vacuum-insulated panels and phase-change materials provide passive temperature protection for short-haul and last-mile applications. E-commerce grocery delivery expansion is stimulating demand for reusable container fleets.
Refrigeration Systems represents the largest installed base. Monitoring Solutions is climbing the fastest as regulatory documentation requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Mexico exhibit the highest price sensitivity due to fragmented restaurant bases and informal retail channels, while Canadian supermarket chains demonstrate the lowest elasticity through long-term dedicated capacity contracts.
United States
Restaurant chain consolidation and direct procurement expansion drive cold chain demand across Texas and California metropolitan corridors. The FDA's Food Safety Modernization Act mandates continuous temperature documentation that accelerates IoT sensor deployment fleet-wide. Chicago anchors Midwest distribution density through rail-to-road transload infrastructure serving Upper Midwest dairy networks.
Canada
Cross-border protein flows from Alberta and Manitoba processing plants sustain refrigerated transport demand into US Midwest markets. Health Canada enforces inspection protocols at border crossings that influence handling procedures for meat entering interstate commerce. Toronto and Vancouver concentrate warehousing capacity supporting Asian seafood import flows through Pacific ports.
Mexico
Produce export volumes through Texas border crossings surge during seasonal harvest windows for tomatoes, avocados, and berries. The central bank's monetary policy affects fleet financing costs for mid-size operators expanding refrigerated capacity. Nuevo León and Jalisco industrial corridors develop cold storage infrastructure to capture value from agricultural export growth.
North America Food Cold Chain Logistics Market Competitive Landscape
Capability concentration sits with integrated national platforms; scale advantage sits with regional specialists commanding corridor-specific density. The market structures around three tiers: automated warehouse operators, regional protein handlers, and last-mile consolidation platforms. Strategic moves center on electrified fleet conversion and cross-border capacity positioning along the Texas-California axis.
Within the integrated national tier, Americold Logistics and Lineage Logistics represent scale-driven archetypes with automated infrastructure spanning key distribution nodes. Henningsen Cold Storage occupies a defensible regional position in Pacific Northwest protein corridors. These three companies exemplify divergent capital allocation strategies between warehouse robotics and transport electrification.
| Leading Market Players |
|---|
| United States Refrigerated Storage |
| Henningsen Cold Storage |
| Americold Logistics |
| Preferred Freezer |
| Agro Merchant Group |
| Lineage Logistics |
| Tippmann Group |
| Nordic Logistics |
| Burris Logistics |
| Others |
Pricing and Supply Chain Analysis
Chicago's rail-to-road transload infrastructure anchors Midwest dairy distribution density, concentrating refrigerated warehousing capacity that feeds downstream pricing power into Upper Midwest supermarket chains and compresses margins for independent operators lacking corridor positioning.
Pricing Analysis
After-sales service contracts and emergency response agreements drive lifetime value in frozen seafood logistics, where 24-hour compressor redundancy and zero-defect handling protocols command premium rates. Three-tier pricing structure across premium certified, standard compliant, and economy basic levels separates HACCP-validated cold chain operators from commodity transport providers. Cost compression in the economy tier is intensifying because California Air Resources Board diesel phase-out timelines accelerate fleet replacement cycles. Quick-service restaurant chains exhibit lowest price sensitivity through direct procurement consolidation, while independent grocery stores in secondary Mexican markets face highest elasticity.
Supply Chain Analysis
Upstream feedstock flows of diesel refrigeration units, electric reefer compressors, and lithium-ion battery packs draw from manufacturing concentrations in China, South Korea, and domestic US assembly plants. Specialized inputs including cryogenic insulation panels, IoT sensor arrays, and phase-change materials rest on chemical processing capabilities concentrated in Texas and Louisiana petrochemical corridors. Single-source vulnerability sits with compressor manufacturers supplying dual-redundancy systems for seafood transport. Distribution runs through hub-and-spoke refrigerated warehousing networks anchored in Dallas, Los Angeles, and Toronto metropolitan zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through restaurant chain direct procurement consolidation that displaces traditional foodservice distribution intermediaries, fragmenting supplier relationships and compressing contract terms for mid-size cold chain operators.
For Market Incumbents: Build regulatory compliance moats through California Air Resources Board-certified electric fleet conversion and FDA Food Safety Modernization Act-validated temperature documentation systems. Defend against emerging electric-first entrants by securing Texas-California corridor charging infrastructure partnerships and backward integration into automated cold storage robotics that reduce labor dependency in high-throughput nodes. For New Entrants and Emerging Players: Pursue last-mile temperature-controlled delivery white space in secondary Mexican markets and independent grocery consolidation platforms in California Central Valley growing regions. Channel compression in quick-service restaurant procurement creates the most penetrable entry vector through direct-to-restaurant frozen protein handling. Go-to-market positioning should emphasize cloud-connected sensor convergence with predictive analytics intervention capabilities that reduce spoilage liability exposure. For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-utility play because regulatory compliance mandates and electrification capital requirements create durable competitive barriers. Target acquisition archetypes include regional protein handlers with Pacific Northwest or Texas-California corridor density and automated warehouse operators with robotics deployment capabilities. Signal to watch: California Air Resources Board enforcement action timelines that accelerate fleet replacement demand and consolidate supplier relationships toward validated national platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Fleet Conversion | California Air Resources Board mandates compress diesel-to-electric replacement timelines across refrigerated transport corridors. |
| Automated Cold Storage Deployment | Robotics integration in Dallas and Los Angeles hubs enables 24-hour processing for cross-border produce flows. |
| Cloud-Connected Sensor Integration | FDA Food Safety Modernization Act documentation requirements accelerate IoT telemetry fleet-wide deployment. |
| Direct Procurement Relationships | Restaurant chain consolidation bypasses foodservice intermediaries, capturing margin from traditional wholesale layers. |
| Cross-Border Corridor Positioning | Texas-California axis synchronization with Mexican agricultural zones and Pacific Northwest protein sources anchors utilization. |
Research Methodology
Initial hypotheses were tested against primary input from cold chain operations directors, fleet procurement managers, restaurant supply chain executives, and refrigerated warehousing facility managers and refined through secondary validation against USDA Agricultural Marketing Service inspection protocols, FDA Food Safety Modernization Act guidance documents, California Air Resources Board regulatory filings, and customs trade data on cross-border produce flows. Bottom-up capacity modeling triangulated against top-down market sizing across temperature-controlled transport and storage segments.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product type, delivery mode, end user category, and technology tier including monitoring solutions and refrigeration systems. CAGRs were derived through logistic growth curve fitting calibrated against historical electrification adoption patterns and regulatory compliance investment cycles. Industry-specific inputs included California diesel phase-out enforcement schedules and frozen seafood handling protocol standardization.
Sensitivities concentrate around California Air Resources Board timeline acceleration, Mexican central bank monetary policy shifts affecting fleet financing, and FDA enforcement intensity variations. Forecasts reflect documented assumptions on electrification cost curves and corridor infrastructure buildout rates. Cross-checking against USDA cold storage capacity reports and refrigerated transport fleet registration databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cold Chain Packaging
Cold Chain Micro-Fulfillment Hub Networks Market
Cold Chain Packaging
Europe Healthcare Cold Chain Logistics Market
Cold Chain Packaging
Cold Storage Insulated Market
Cold Chain Packaging
Cold Chain Temperature Monitoring Market
Cold Chain Packaging
Cold Chain Market
Cold Chain Packaging
Temperature Controlled Packaging Boxes Market
Cold Chain Packaging
Pharmaceutical Cold Chain Packaging Market
Cold Chain Packaging
Ice Boxes Market
Cold Chain Packaging
Cooling Boxes Market
Cold Chain Packaging
Cryogenic Capsules Market
Cold Chain Packaging
Insulated Food Delivery Bags Market
Cold Chain Packaging
Cold Chain Equipment Market
Cold Chain Packaging
Food Cold Chain Market
Cold Chain Packaging
Biopharma Cold Chain Packaging Market
Cold Chain Packaging
Fish Boxes Market
Cold Chain Packaging
Cold Chain Packaging Pooling and Reverse Logistics Services Market