
 Medical Devices Secondary Packaging Market | 2026-2036
Medical Devices Secondary Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Devices Secondary Packaging Market Foresight
Asset-light leasing models for cleanroom packaging capacity are reshaping competitive entry barriers for mid-tier medical device contract manufacturers. Sonoco Products Company leverages its North American sterilization infrastructure to anchor long-term hospital supply agreements. Smurfit Kappa competes through fiber-based carton specialization that meets EU MDR traceability requirements. Amcor Plc extends its pharmaceutical-grade film portfolio into secondary barrier applications for high-value implants.
Medical devices secondary packaging encompasses the outer protective and informational layer applied after primary sterile barriers, typically comprising printed cartons, aggregated labels, shrink sleeves, or blister cards that incorporate tamper-evidence features and unique device identifiers. This packaging tier serves the dual industrial purpose of preserving sterility assurance through distribution while communicating regulatory traceability data to healthcare providers and patients. Blister packaging dominates margin pools for single-use surgical instruments where visibility and shelf stability prove critical. Cartons sustain volume leadership across diagnostic equipment where printed instructions-for-use and multilingual labeling remain mandatory. Labels represent the fastest-growing structural segment as FDA UDI and EU MDR serialization mandates expand data-carrying requirements on every secondary package.
FDA regulations govern device labeling and unique identification in the United States, while the EU Medical Device Regulation enforces CE marking and enhanced post-market traceability across European Economic Area countries. ISO 11607 standards for sterile barrier systems and GMP guidelines for medical device manufacturing collectively shape material selection, validation protocols, and supplier qualification requirements. Stakeholders must monitor how converging UDI implementation timelines across multiple jurisdictions will reshape print technology investments and regional packaging specification divergence.
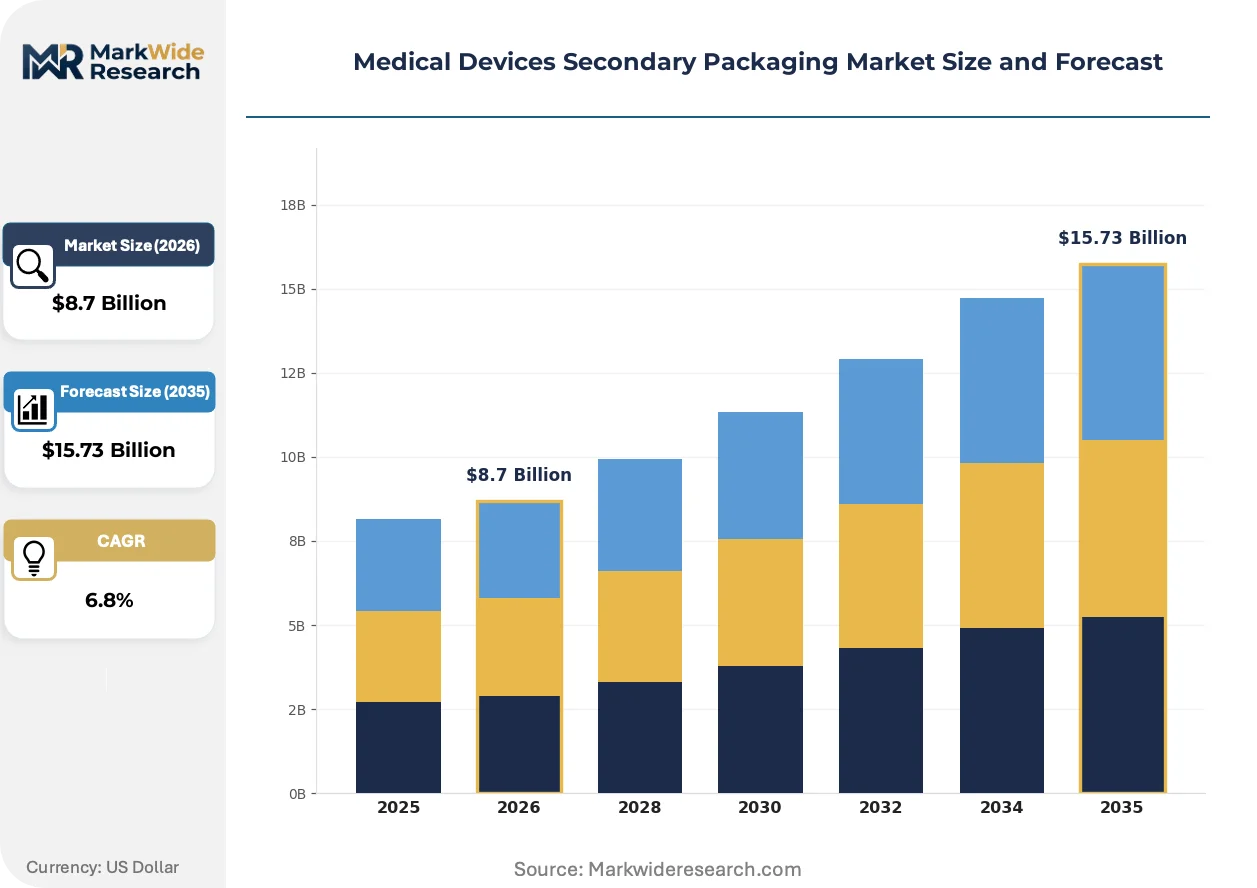
Market Dynamics
Regulatory serialization mandates across the United States, Germany, and Japan are compressing packaging specification timelines while forcing capital redeployment into print infrastructure. Hospital procurement consolidation is simultaneously elevating volume concentration among contract manufacturers serving sterile barrier systems.
Growth Catalysts
- EU MDR traceability expansion:Enhanced post-market surveillance requirements in Germany and France mandate serialized secondary packaging for implantable devices, pulling demand for tamper-evident cartons and aggregated labels.
- Cleanroom leasing proliferation:Asset-light capacity models in the United States lower entry barriers for mid-tier contract manufacturers seeking ISO 11607-compliant sterile barrier production without facility ownership.
- Implantable device volume concentration:Orthopedic and cardiovascular implant procurement by hospital networks in Japan and Switzerland drives specialized secondary packaging with extended shelf-life documentation.
Market Restraints
- Ethylene-vinyl acetate supply concentration:Film resin production clusters in Northeast Asia create input cost volatility for blister and shrink-sleeve manufacturers serving European markets.
- FDA UDI implementation friction:Evolving labeling data format requirements impose validation costs that disproportionately burden small-device manufacturers with limited regulatory affairs capacity.
- Fiber-based substitution ceiling:Moisture-sensitive diagnostic reagents face technical limitations in carton-only secondary packaging, preserving polymer dependence despite sustainability pressures.
Strategic Opportunities
- Brazilian ANVISA alignment:Emerging regulatory convergence with FDA UDI standards creates export pathway expansion for North American packaging converters with existing serialization infrastructure.
- India CDSCO manufacturing incentives:Production-linked incentive schemes for medical device manufacturing clusters in Gujarat and Karnataka pull localized secondary packaging demand.
- RFID-NFC convergence:Near-field communication integration with radio-frequency identification is enabling real-time supply chain visibility for high-value implant shipments to Swiss and German hospital networks.
Industry Challenges
- Validation engineer scarcity:ISO 11607 sterile barrier qualification expertise concentrates among aging specialists in Germany and the United States, constraining new facility commissioning timelines.
- Legacy ERP integration:Serialization data management requirements for FDA UDI and EU MDR collide with outdated manufacturing execution systems at mid-tier contract packaging operations.
- Multi-jurisdiction print standard divergence:Simultaneous compliance with FDA 21 CFR Part 11, EU MDR Annex VI, and Japan PMDA labeling formats fragments production runs and elevates changeover costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Devices Secondary Packaging Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Blister Packaging, Cartons, Shrink Sleeves, Labels Material: Plastic, Paperboard, Metal, Foam End User: Hospitals, Clinics, Pharmacies, Laboratories Regulatory Compliance: ISO Standards, FDA Regulations, CE Marking, GMP Guidelines |
| Companies Covered | Sonoco Products Company, Smurfit Kappa, Steripack Group, Berry Global Group, Inc., Amcor Plc, DuPont, Nelipak Group, Graphic Packaging International, LLC, Oliver Healthcare Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Devices Secondary Packaging Market Shifts & Advancements
Digital print technologies and connected packaging architectures are collapsing traditional batch-size economics while elevating data-carrying capacity on secondary packages. These shifts are compressing specification cycles and rewiring supplier qualification criteria across sterile barrier supply chains.
Laser-etched polymer films with embedded micro-taggants are rendering obsolete conventional ink-based serialization for high-value implant secondary packaging. Swiss orthopedic device manufacturers adopted this technology at pilot scale during 2023 validation windows. The structural consequence is rendering obsolete thermal transfer print infrastructure that dominated FDA UDI Phase 1 implementation.
EU MDR Annex VI serialization mandates are forcing carton converters to deploy aggregation software linking secondary package data to pallet-level identifiers. Industrial consequence includes mandatory hardware upgrades for vision systems and line controllers. German diagnostic equipment manufacturers face the most acute compliance pressure, with many qualifying hybrid print-flexible film configurations ahead of 2026 enforcement windows.
Hospital network procurement consolidation is compressing supplier bases for sterile barrier secondary packaging toward single-source agreements with integrated sterilization-packaging providers. United States health system purchasing organizations are displacing fragmented distributor relationships with direct manufacturer contracts. This concentration is most visible in cardiovascular implant supply chains serving the Cleveland Clinic and Mayo Clinic networks.
Medical Devices Secondary Packaging Market Segmentation
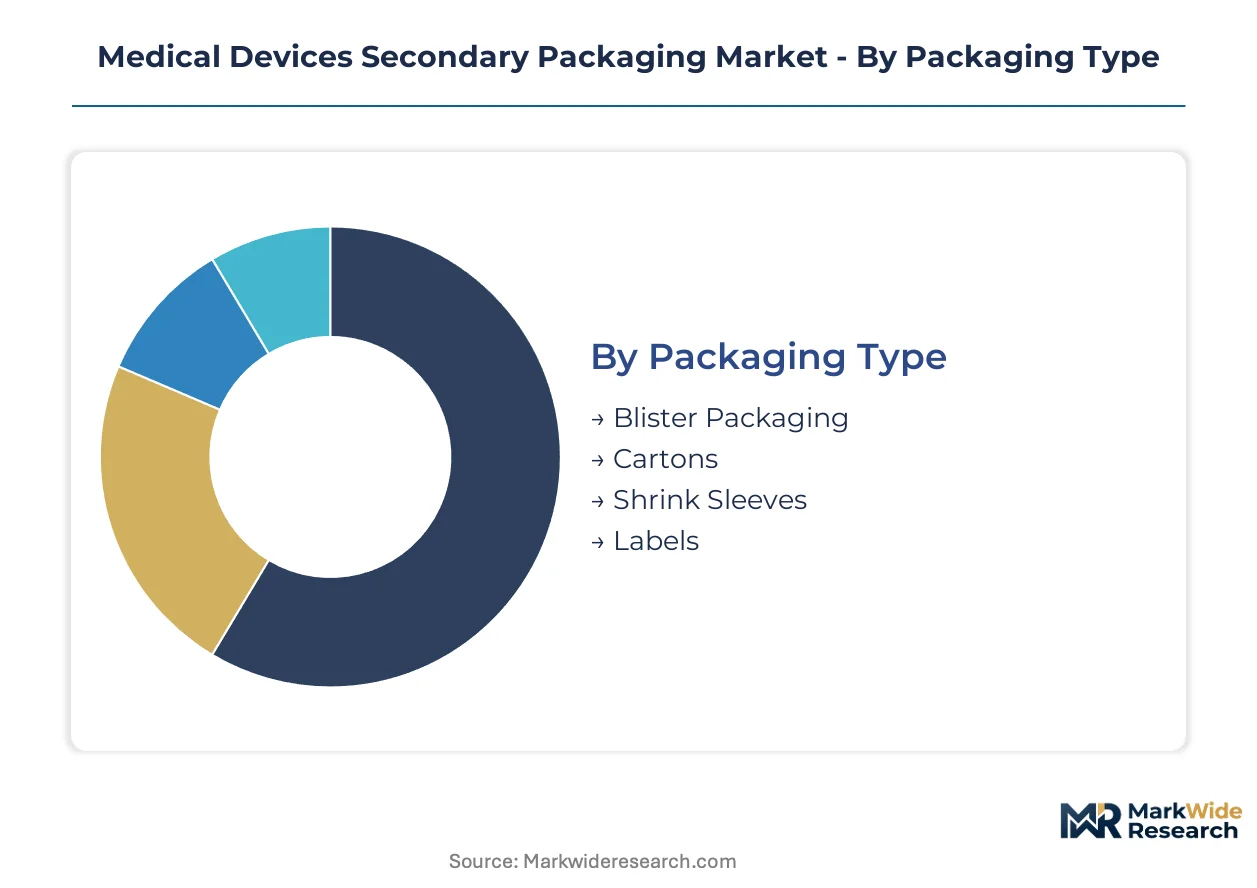
Secondary packaging segmentation in medical devices reflects divergent technical requirements across sterile barrier hierarchies, regulatory traceability mandates, and end-user procurement specifications. Material selection and packaging architecture decisions cascade directly into validation timelines, sterilization compatibility, and supply chain qualification costs.
Packaging Type:
Mature formats dominate hospital procurement volumes while emerging configurations capture specialized implant applications demanding enhanced tamper evidence.
- Blister Packaging:Thermoformed polymer cavities sealed with lidding films provide visibility and shelf stability for single-use surgical instruments. German orthopedic device manufacturers specify high-barrier PVC-PVDC configurations for extended shelf-life implants, driven by EU MDR traceability requirements for sterile barrier integrity documentation.
- Cartons:Fiber-based secondary enclosures aggregate primary sterile barriers with printed instructions-for-use, multilingual labeling, and tamper-evident closures. Swiss diagnostic equipment suppliers source folding carton formats with integrated serialization to satisfy Swissmedic post-market surveillance mandates for lot-level traceability.
- Shrink Sleeves:Polymer film sleeves conform to irregular device geometries for tamper-evident sealing and 360-degree print coverage. Demand concentrates in cardiovascular implant kits requiring full-surface UDI encoding.
- Labels:Pressure-sensitive adhesive substrates carry serialized data matrices, human-readable lot numbers, and handling instructions. FDA UDI Phase 2 implementation is accelerating investment in thermal transfer and digital print infrastructure.
Cartons handle the majority of throughput; labels are expanding most quickly on share.
Material:
Cost tier stratification separates commodity substrates from performance-grade formulations requiring specialized sterilization validation.
- Plastic:Ethylene-vinyl acetate, polyethylene terephthalate, and cyclic olefin copolymer films dominate blister and shrink applications. Japanese cardiovascular device manufacturers specify COC lidding films for gamma sterilization compatibility, constrained by resin supply concentration in Northeast Asia.
- Paperboard:Solid bleached sulfate and coated recycled board grades sustain carton volume leadership. German converters invest in aggregation-capable print lines to meet EU MDR Annex VI serialization deadlines.
- Metal:Aluminum foil laminates provide absolute moisture and light barriers for diagnostic reagents. Applications concentrate in laboratory-grade immunoassay kits with stringent stability requirements.
- Foam:Polyurethane and polyethylene foam inserts cushion delicate instrumentation during distribution. Swiss surgical robot component suppliers specify anti-static formulations for electrostatic-sensitive devices.
Plastic commands the largest material spend; paperboard is climbing the fastest on sustainability-driven substitution.
End User:
Customer type determines packaging complexity, with acute care settings demanding the most stringent sterile barrier documentation.
- Hospitals:Integrated delivery networks in the United States consolidate procurement toward single-source sterilization-packaging agreements. Cleveland Clinic and Mayo Clinic networks specify validated sterile barrier systems with embedded RFID for implant traceability.
- Clinics:Outpatient surgical centers prioritize cost-efficient carton configurations with essential UDI compliance. Brazilian clinic chains drive demand for Portuguese-label secondary packaging as ANVISA aligns with FDA serialization standards.
- Pharmacies:Retail pharmacy distribution requires shelf-ready secondary packaging with consumer-facing labeling. Indian pharmacy chains expanding into medical device retail pull localized carton production under CDSCO manufacturing incentives.
- Laboratories:Diagnostic and research laboratories specify temperature-indicating labels and extended stability documentation. Swiss reference laboratories drive specialized cold-chain secondary packaging for temperature-sensitive reagents.
Hospitals absorb the dominant procurement volume; laboratories are gaining share fastest on precision diagnostics expansion.
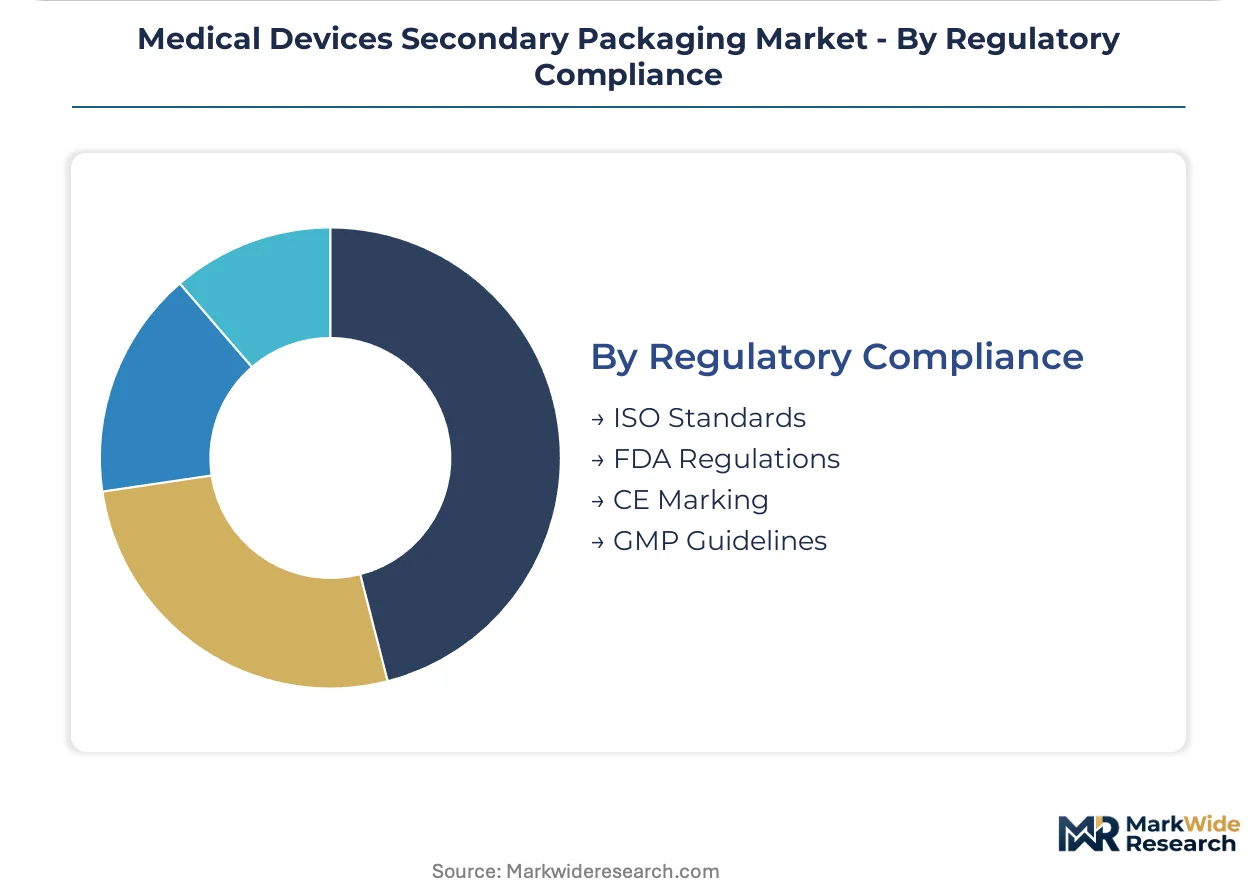
Regulatory Compliance:
Geography-specific validation requirements fragment production specifications and elevate supplier qualification barriers.
- ISO Standards:ISO 11607 sterile barrier system validation governs material selection, seal strength testing, and accelerated aging protocols. German packaging engineers with ISO 11607 expertise command premium consulting rates for facility commissioning.
- FDA Regulations:21 CFR Part 11 and UDI mandates impose electronic records management and machine-readable data matrix requirements. Small-device manufacturers face disproportionate validation cost burdens from evolving labeling data formats.
- CE Marking:EU MDR Annex VI traceability requirements mandate serialized secondary packaging with aggregation to pallet level. French implant manufacturers face acute compliance pressure ahead of enforcement windows.
- GMP Guidelines:Good manufacturing practice protocols for medical device manufacturing shape cleanroom operations and supplier qualification. Indian contract manufacturers pursuing CDSCO registration adopt EU GMP-equivalent standards for export market access.
ISO Standards anchor the broadest compliance baseline; CE Marking is the steepest expansion trajectory on EU MDR implementation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA UDI mandates and EU MDR traceability deadlines are compressing packaging specification timelines across major medical device manufacturing clusters. Hospital procurement consolidation is simultaneously elevating volume concentration among contract manufacturers serving sterile barrier systems in precision manufacturing hubs.
United States
Cleveland Clinic and Mayo Clinic networks are consolidating sterile barrier procurement toward single-source sterilization-packaging agreements with embedded RFID requirements. FDA 21 CFR Part 11 and evolving UDI labeling data formats impose validation costs that burden small-device manufacturers. The Greater Boston corridor hosts contract packaging operations upgrading serialization infrastructure ahead of enforcement windows.
Germany
Precision orthopedic and cardiovascular device manufacturing clusters in Bavaria and Baden-Württemberg drive specialized secondary packaging demand with extended shelf-life documentation. EU MDR Annex VI mandates serialized cartons with aggregation to pallet level, forcing converters to deploy vision systems and line controllers. The Stuttgart-Tübingen corridor concentrates ISO 11607 validation expertise among aging specialists commanding premium consulting rates.
Switzerland
Swissmedic post-market surveillance requirements pull demand for folding carton formats with integrated serialization from diagnostic equipment suppliers. Swiss orthopedic device manufacturers piloted laser-etched polymer films with embedded micro-taggants during 2023 validation windows. The Basel-Zurich corridor anchors high-value implant shipments requiring real-time supply chain visibility through RFID-NFC convergence.
Japan
Cardiovascular device manufacturers specify cyclic olefin copolymer lidding films for gamma sterilization compatibility, constrained by resin supply concentration in Northeast Asia. PMDA labeling format requirements fragment production runs alongside FDA and EU MDR standards. The Tokyo-Osaka corridor concentrates procurement by hospital networks expanding sterile barrier system volumes.
India
CDSCO production-linked incentive schemes for medical device manufacturing clusters in Gujarat and Karnataka pull localized secondary packaging demand. Indian contract manufacturers pursuing export market access adopt EU GMP-equivalent standards. The Ahmedabad-Bengaluru corridor hosts emerging cleanroom packaging capacity serving domestic pharmacy chains expanding into medical device retail.
Medical Devices Secondary Packaging Market Competitive Landscape
Channel-controlling players compete with product-specialist players across sterilization-integrated and material-pure archetypes. The market structure tilts toward consolidation as hospital procurement consolidation elevates volume concentration. Three archetypes dominate: integrated sterilization-packaging providers, fiber-based carton specialists, and pharmaceutical-grade film extenders. Competitive moves center on cleanroom capacity leasing models and aggregation software deployment for serialization compliance.
Within the integrated infrastructure tier, Sonoco Products Company and Amcor Plc exemplify channel-controlling positioning through North American sterilization anchoring and pharmaceutical-grade film portfolio extension. Smurfit Kappa occupies a distinct specialization vector as a fiber-based carton converter meeting EU MDR traceability requirements. These three entities represent divergent strategic bets on sterile barrier integration, sustainability-driven material substitution, and regulatory compliance infrastructure.
| Leading Market Players |
|---|
| Sonoco Products Company |
| Smurfit Kappa |
| Steripack Group |
| Berry Global Group, Inc. |
| Amcor Plc |
| DuPont |
| Nelipak Group |
| Graphic Packaging International, LLC |
| Oliver Healthcare Packaging |
| Others |
Supply & Pricing Matrix
Northeast Asian resin production clusters in Zhejiang and Jiangsu provinces anchor global ethylene-vinyl acetate supply, translating upstream capacity tightness into margin compression for European blister manufacturers. This geographic concentration of film-grade polymer output grants feedstock suppliers outsized leverage over packaging converters serving FDA and EU MDR compliance timelines.
Pricing Analysis
Certification level creates the primary spread between ISO 11607-validated sterile barrier systems and commodity-grade secondary packaging. Three-tier pricing structure separates FDA UDI-compliant serialization infrastructure from CE-marked EU MDR configurations and non-validated economy formats. Cost compression in standard-grade cartons is intensifying because hospital procurement consolidation forces volume discounts. Outpatient surgical clinics exhibit highest price sensitivity; integrated delivery networks absorb premium tiers for traceability-embedded implant packaging.
Supply Chain Analysis
Export control regimes on advanced polymer processing equipment constrain capacity expansion outside established manufacturing corridors. Supply concentrates in Germany for precision carton converting, Japan for cyclic olefin copolymer films, and the United States for sterilization-integrated packaging services. Raw material flows draw from Northeast Asian EVA resin producers, Scandinavian pulp suppliers, and Gulf Coast petrochemical complexes. Single-source vulnerability pervades gamma-sterilization-compatible lidding film supply. Distribution runs through hospital group purchasing organizations consolidating toward direct manufacturer contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
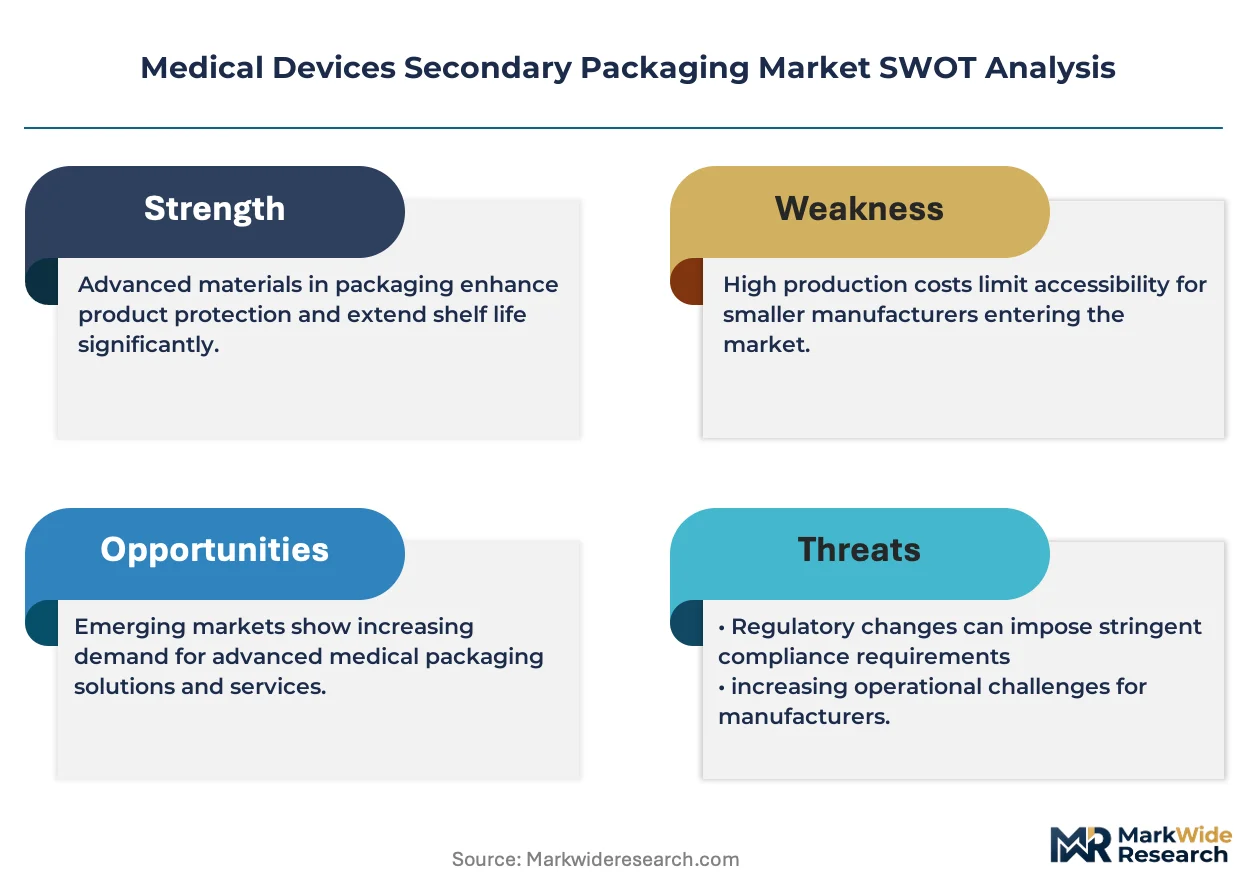
Fiber-based substitution threatens polymer-dependent blister formats as EU sustainability mandates harden, forcing incumbents to defend material positioning through performance validation.
For Market Incumbents: Pre-empt fiber-based displacement by securing ISO 11607 validation for hybrid paperboard-polymer sterile barrier systems before EU Green Deal packaging regulations tighten. Deepen backward integration into sterilization capacity to anchor hospital network single-source agreements against emerging cleanroom leasing competitors. For New Entrants and Emerging Players: Gujarat and Karnataka medical device manufacturing clusters offer underpenetrated secondary packaging demand as CDSCO production-linked incentives attract orthopedic and cardiovascular device assembly. Target contract packaging services for mid-tier manufacturers lacking in-house validation expertise, leveraging asset-light cleanroom leasing models to bypass capital-intensive facility ownership. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory compliance infrastructure play because converging FDA UDI and EU MDR serialization mandates create durable demand for aggregation software and vision system providers. Acquisition focus should center on ISO 11607 validation engineering boutiques with aging specialist knowledge concentrated in Germany and the United States. Watch for ANVISA-FDA regulatory alignment completion as the signal triggering Brazilian export pathway expansion.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Annex VI Compliance Pathway | Serialized carton aggregation mandates force vision system upgrades across German converter operations. |
| Hospital System Partnership | Cleveland Clinic and Mayo Clinic networks consolidate procurement toward RFID-embedded sterile barrier suppliers. |
| Backward Integration into Sterilization | Captive gamma and ethylene oxide capacity anchors long-term supply agreements with integrated delivery networks. |
| Software Companion Development | Aggregation platforms linking secondary package data to pallet-level identifiers satisfy EU MDR traceability mandates. |
| Reimbursement Strategy | UDI-encoded packaging supports hospital claims accuracy for high-value implant procedures under CMS bundled payment models. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA UDI guidance documents, EU MDR implementing acts, and ISO 11607 validation protocols. Conversations with hospital purchasing committee members, GPO contracts managers, biomedical engineers, and sterile barrier validation specialists informed demand-side dynamics. Secondary sources encompassed CMS Medicare claims data, hospital procurement databases, and customs records of medical device packaging material trade flows. Bottom-up facility capacity assessments triangulated against top-down market sizing across packaging type and material segments.
Forecast inputs span sterile barrier system volume trends, regulatory implementation timelines, and hospital network procurement consolidation patterns across the analysis window. Segmentation dimensions modeled include packaging architecture, material grade tier, sterilization compatibility, and regional regulatory cluster. CAGRs derive from regression analysis of historical procurement volumes against projected compliance-driven specification upgrades. Industry-specific inputs incorporate EU MDR enforcement window phasing and FDA UDI Phase 2 label data format evolution.
Macroeconomic conditions sit as an overlay; deviation in resin feedstock pricing, healthcare capital expenditure cycles, or cross-border medical device trade flows would shift the trajectory. Forecasts reflect assumptions regarding regulatory deadline adherence and hospital procurement centralization continuity. Material shifts in EU packaging sustainability regulations or FDA UDI data format requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices Packaging
North America Medical Devices Packaging Market
Medical Devices Packaging
Molded Pulp Clinical Packaging Market
Medical Devices Packaging
Global Medical Devices Packaging Market
Medical Devices Packaging
Middle East and Africa Parenteral Packaging Market
Medical Devices Packaging
Medical Tray Sealers Market
Medical Devices Packaging
Multi-Med Adherence Packaging Market
Medical Devices Packaging
Syringe Trays Market
Medical Devices Packaging
Europe Medical Devices Packaging Market
Medical Devices Packaging
Global Custom Procedure Trays and Packs Market
Medical Devices Packaging
Ophthalmic Packaging Market
Medical Devices Packaging
Asia-Pacific Medical Devices Packaging Market
Medical Devices Packaging
Bio-Medical Packaging Market
Medical Devices Packaging
Sterile and Antiviral Packaging Market
Medical Devices Packaging
Medical Processing Seals (MPS) Market
Medical Devices Packaging
Global Procedure Trays Market
Medical Devices Packaging
Transplant Box Market