
 Coffee Beans Market | 2026-2036
Coffee Beans Market Size, Share, and Industry Trends Forecast 2026-2036
Coffee Beans Market Intelligence
Fair Trade certification is bifurcating the market between suppliers who can meet its stringent ethical and environmental standards and those who cannot. Starbucks Coffee Company leverages its scale to secure certified beans through direct trade programs, ensuring supply chain transparency. Lavazza differentiates through its focus on premium Arabica blends and sustainability storytelling. Meanwhile, Keurig Dr Pepper competes on convenience and accessibility through its single-serve pod ecosystem.
Coffee beans are the seeds of the Coffea plant, primarily from the Arabica and Robusta species. The beans undergo processing methods like washed, natural, or honey processing, which significantly alter the final flavor profile and acidity. The market's value is heavily weighted towards Arabica beans due to their complex aromatics and lower caffeine content, commanding premium prices. Within applications, traditional espresso remains dominant, while the cold brew segment represents the fastest-growing category due to its appeal with younger consumers.
Regulatory compliance, including USDA Organic certification and food safety standards overseen by the European Food Safety Authority (EFSA), governs market access. These regulations mandate traceability and limit pesticide residues, influencing cultivation practices. International Organization for Standardization (ISO) quality standards also provide a framework for grading and trade. Stakeholders must now decide how to invest in traceability technologies to meet evolving climate-related sourcing mandates.
Market Dynamics
The central force shaping the coffee beans market is the mandate for supply chain transparency, driven by regulations like the European Union's Deforestation-Free Regulation. This pressure is compelling stakeholders to invest in traceability from farm to cup, altering procurement and verification processes.
Growth Catalysts
- Cold Brew Application:Demand for smoother, lower-acidity coffee profiles, particularly among younger demographics, is expanding the market for beans suited to cold brew extraction methods, creating a distinct application segment.
- Specialty Coffee Demand:Strong consumer interest in single-origin and artisanal coffee in developed markets like the United States and Japan supports premium pricing and encourages the cultivation of unique varietals.
- Fair Trade Certification:The increasing consumer and corporate focus on ethical sourcing provides a significant catalyst for beans certified under Fair Trade standards, opening access to sustainability-focused retail channels and corporate buyers.
Market Restraints
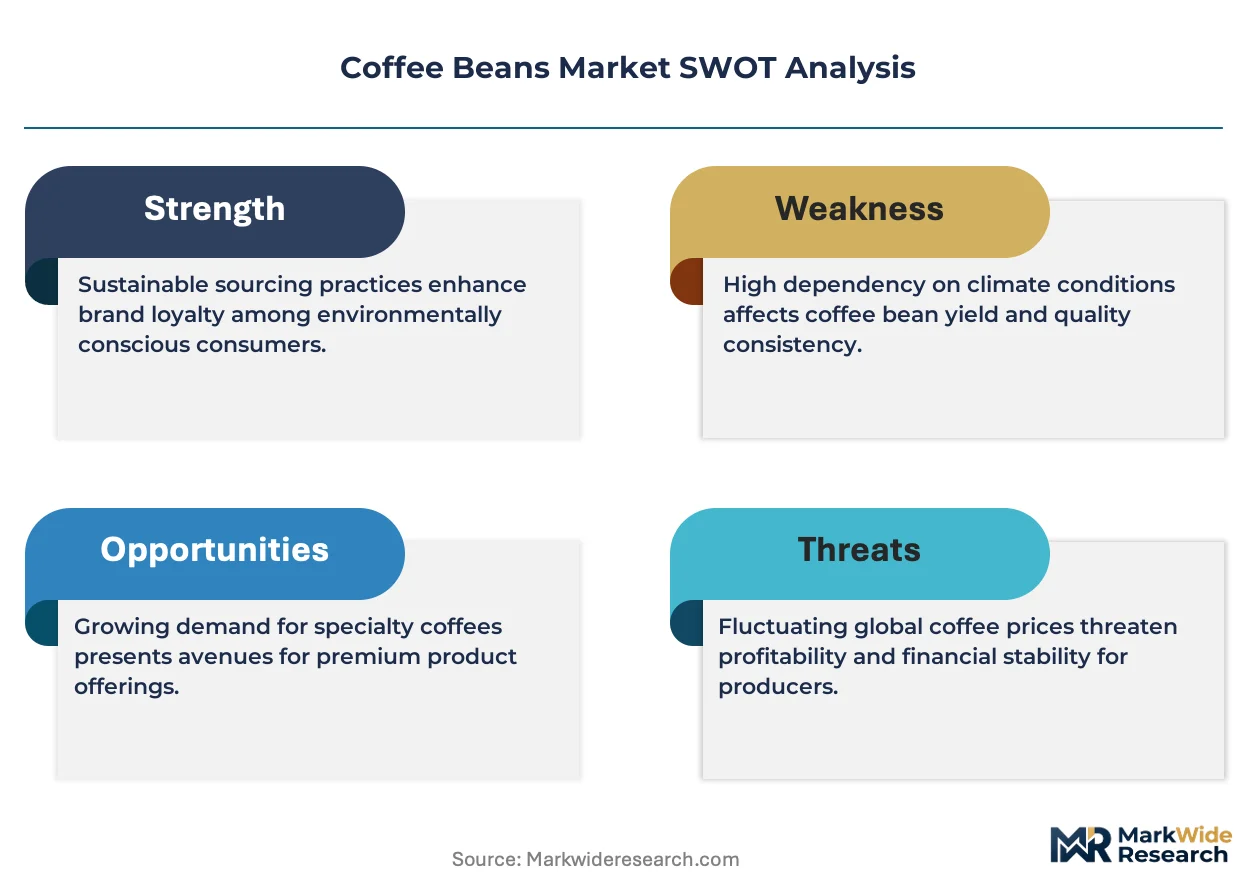
- Climate Change Impact:Increasing weather volatility, including droughts and excessive rainfall in key growing regions like Brazil and Vietnam, creates significant uncertainty in crop yields and price stability for both Arabica and Robusta beans.
- Regulatory Compliance Costs:Adherence to stringent regulations, such as the EUDR and pesticide limits set by the EFSA, imposes substantial costs on producers and exporters for traceability systems and laboratory testing.
- Pest and Disease Pressure:The prevalence of diseases like coffee leaf rust and pests such as the coffee berry borer threatens crop volumes and quality, requiring costly mitigation strategies and development of resistant plant varietals.
Strategic Opportunities
- Geographic Market Expansion:A rising café culture and disposable income in emerging economies across Southeast Asia and Eastern Europe present significant opportunities for market entry and brand development.
- Functional Ingredient Integration:The incorporation of coffee extracts and powders into nutraceuticals, functional foods, and ready-to-drink beverages offers a new value-added revenue stream beyond traditional brewed coffee applications.
- Blockchain for Traceability:Implementing blockchain technology can provide immutable proof of origin and compliance with sustainability standards, enabling producers to command premium prices for fully traceable, certified beans.
Industry Challenges
- Traceability System Implementation:Deploying and integrating robust traceability technologies across fragmented supply chains to meet mandates like the EUDR presents a significant operational and capital investment challenge for smallholders and cooperatives.
- Agronomic Skill Gaps:A shortage of skilled agronomists trained in climate-resilient farming techniques and sustainable practices hinders the industry's ability to adapt to environmental pressures and improve crop quality consistently.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coffee Beans Market |
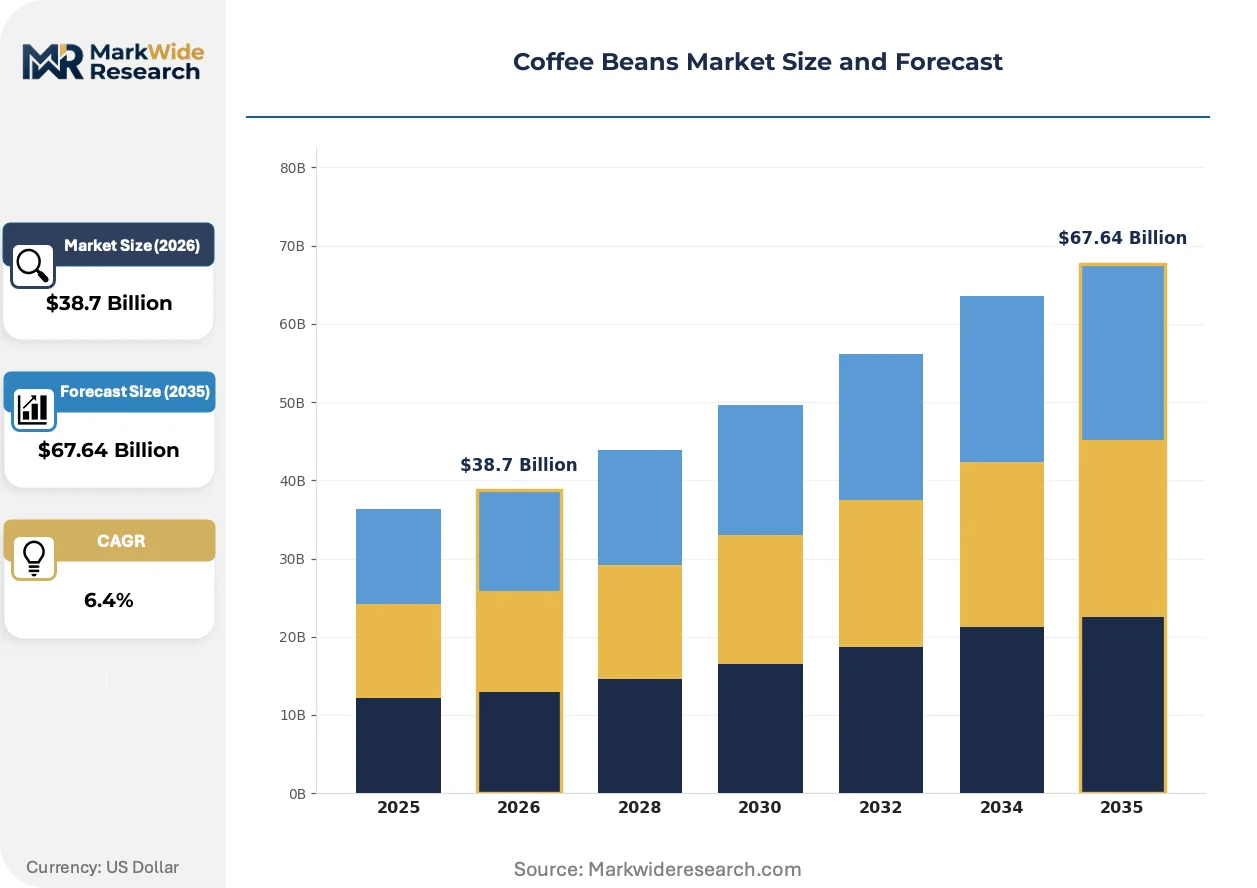
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $67.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Arabica, Robusta, Liberica, Excelsa Processing Method: Washed, Natural, Honey, Semi-washed, Sun-dried Application: Espresso, Drip Coffee, Cold Brew, Instant Coffee, Turkish Coffee End User: Cafes, Restaurants, Offices, Hotels, Foodservice Providers |
| Companies Covered | Keurig Dr Pepper, Peet's Coffee, Starbucks Coffee Company, Dunkin', Tim Hortons, JDE Peet's Coffee and Tea, Lavazza, Costa Coffee, Nestlé (Nescafé), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coffee Beans Market Strategic Shifts & Innovations
Data-driven agriculture and digital traceability are transforming the coffee bean from a simple commodity into a high-value, differentiated product. This shift places a premium on verifiable origin, ethical production, and unique flavor profiles, fundamentally changing sourcing and marketing strategies.
Precision agriculture platforms integrate on-farm IoT sensors to monitor soil moisture, nutrient levels, and micro-climatic conditions. Large plantations and specialty coffee cooperatives are adopting this technology to optimize resource use and improve crop consistency. This technology is miniaturizing the information gap between individual farm lots and global buyers, enabling hyper-traceable sourcing and quality verification at an unprecedented scale.
Regulatory frameworks like the USDA National Organic Program (NOP) are creating distinct, premium market segments. NOP standards, which prohibit the use of synthetic pesticides and fertilizers, force growers to adopt specific cultivation and processing methods. The specialty coffee sector in North America is most affected, with roasters increasingly building their brands around the availability of USDA Organic certified beans.
A fundamental shift toward direct trade models is altering procurement patterns in the specialty segment. This practice involves roasters establishing direct relationships with specific farms or cooperatives, bypassing traditional commodity exchanges and importers. This disintermediation is most visible in high-value markets in North America and Europe, where consumer demand for story and transparency justifies the model.
Coffee Beans Market Segmentation
Understanding the Coffee Beans Market requires a detailed segmentation analysis, revealing distinct consumer preferences, processing impacts, and end-user demands. This granular view helps stakeholders identify specific growth pockets and tailor cultivation, processing, and distribution strategies effectively. Market dynamics vary significantly across these defined segments.
Product Type:
The distribution of coffee beans across various sales channels significantly varies by product type, reflecting diverse consumer preferences and market positioning. Specialty retailers often prioritize single-origin varietals, while mass-market channels blend for consistent flavor profiles.
- Arabica:These beans, derived from the Coffea arabica plant, are known for their complex aromatics, lower acidity, and nuanced flavor profiles. Demand for Arabica beans is particularly strong in developed markets like the United States and Japan, driven by a preference for specialty coffee experiences.
- Robusta:Sourced from the Coffea canephora plant, Robusta beans contain higher caffeine content and exhibit a bolder, more rubbery flavor with less acidity. The robust nature of these beans secures their extensive use in espresso blends and instant coffee production, especially in Europe and Southeast Asia.
- Liberica:Characterized by a smoky, woody, and nutty flavor, Liberica beans offer a distinct profile favored in niche markets, particularly within Southeast Asian countries.
- Excelsa:Often considered a varietal of Liberica, Excelsa beans contribute tart, fruity, and dark notes to blends, finding limited but dedicated use in specific regional coffee preparations.
Arabica dominates the installed base of coffee bean consumption. Robusta is where expansion concentrates for high-volume applications.
Processing Method:
The chosen processing method profoundly influences the final flavor profile and quality tier of coffee beans, directly impacting their suitability for different applications. Each technique extracts unique characteristics from the raw cherry.
- Washed:This method removes the fruit pulp before drying, resulting in cleaner, brighter, and more acidic flavor profiles. Washed beans are highly sought after by specialty roasters in North America for their clarity and consistency in drip and pour-over preparations.
- Natural:Coffee cherries are dried whole with the fruit intact, imparting fruity, sweet, and full-bodied characteristics to the beans. This method is prevalent in regions with dry climates like Brazil and Ethiopia, gaining popularity for its distinctive flavor contributions to espresso blends.
- Honey:A hybrid approach, honey processing leaves some mucilage on the bean during drying, producing a sweet, balanced cup with enhanced body and reduced acidity.
- Semi-washed:Also known as wet-hulled, this method partially dries the beans before removing the parchment, yielding a low-acid, earthy flavor typical of Indonesian coffees.
- Sun-dried:Beans dried directly under the sun, often after washing or pulping, benefit from natural solar energy, contributing to their inherent sweetness and uniform moisture content.
Washed processing commands premium pricing for clarity. Natural processing is gaining significant traction for its unique flavor contributions.
Application:
The volume of coffee beans consumed varies considerably across different preparation methods, reflecting diverse consumer habits and beverage trends. Each application demands specific bean characteristics for optimal taste and extraction.
- Espresso:This method uses finely ground beans and pressurized hot water, creating a concentrated shot with a rich crema. Espresso remains a foundational application in European cafes and forms the base for numerous milk-based beverages, driving demand for specific bean blends.
- Cold Brew:Characterized by a long, slow steeping process in cold water, cold brew produces a less acidic, smoother, and naturally sweeter coffee concentrate. Its appeal to younger demographics in the United States makes it a rapidly expanding segment, influencing bean selection for lower acidity.
- Drip Coffee:A common home and office brewing method, drip coffee involves hot water passing through ground beans in a filter, yielding a clean, consistent cup.
- Instant Coffee:Dehydrated coffee extract dissolves quickly in hot water, offering convenience and widespread accessibility in markets with high on-the-go consumption, such as Southeast Asia.
- Turkish Coffee:Prepared by boiling finely ground coffee with water in a cezve, this traditional method yields a strong, unfiltered brew with a distinctive thick texture, prevalent in the Middle East and Eastern Europe.
Espresso maintains its market dominance in volume. Cold brew demonstrates the steepest expansion trajectory in new product development.
End User:
Margin structures and service requirements differ significantly among various end-user segments, shaping procurement strategies for coffee bean suppliers. Each segment demands tailored product offerings and logistical solutions.
- Cafes:These establishments prioritize high-quality, often specialty-grade beans for direct consumption, focusing on unique flavor profiles and ethical sourcing stories. Cafes command premium pricing for their brewed beverages, enabling investment in diverse bean origins.
- Foodservice Providers:This segment includes large-scale caterers and institutional buyers, requiring consistent supply, competitive pricing, and standardized quality for high-volume service. Their procurement emphasizes reliability and cost-effectiveness for broad distribution.
- Restaurants:Coffee serves as an important complement to meals, with establishments often seeking versatile blends that appeal to a wide customer base, balancing quality with operational efficiency.
- Offices:Workplace coffee consumption emphasizes convenience and consistency, driving demand for easily prepared options like single-serve pods or reliable bulk-brewing solutions.
- Hotels:Offering coffee across various touchpoints, from in-room amenities to breakfast buffets and fine dining, hotels require a range of bean qualities to meet diverse guest expectations.
Cafes lead in premium bean procurement. Foodservice providers drive volume consistency across the commercial sector.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The European Union's Deforestation-Free Regulation (EUDR) is compelling major importers to invest significantly in supply chain traceability, fundamentally altering procurement strategies across key global markets. This regulatory shift, alongside evolving consumer preferences, drives distinct regional growth patterns for coffee beans. Specific countries demonstrate unique demand drivers and regulatory landscapes, influencing investment and cultivation practices.
United States
Consumer preference for smoother, less acidic cold brew coffee fuels demand for specific bean profiles. USDA Organic certification provides a distinct premium market segment for roasters and importers. The Pacific Northwest, particularly Seattle, remains a significant hub for specialty coffee culture and innovation in brewing methods.
Japan
Strong consumer interest in single-origin specialty beans and artisanal coffee experiences drives premium pricing. Japan's stringent food safety standards, overseen by its national food safety authority, influence import and processing requirements. Tokyo's vibrant café scene supports high-end roasters and showcases diverse bean varietals.
Germany
Adherence to the European Union's Deforestation-Free Regulation (EUDR) and European Food Safety Authority (EFSA) standards shapes sourcing practices for major roasters. Demand concentrates on ethically sourced, premium Arabica blends for its established coffee culture. Hamburg functions as a critical port city for coffee imports, housing numerous large-scale roasting and distribution facilities.
Brazil
Global supply chain demands for both Arabica and Robusta beans anchor Brazil's position as a major producer. Environmental protection laws within Brazil increasingly influence sustainable cultivation practices among growers. The Minas Gerais region leads in coffee production, focusing on varietal development and innovative processing techniques like natural drying.
China
A rapidly expanding café culture and increasing disposable income propel demand for diverse coffee bean offerings. China's national food safety regulations and import policies guide market entry for international brands. Shanghai's metropolitan area exhibits significant growth in coffee consumption, attracting global coffee chains and local specialty roasters.
Coffee Beans Market Key Industry Players
Player mix skews toward established global brands with significant market reach, alongside a growing segment of specialty roasters and private labels. The market structure exhibits a tiered approach, where scale players dominate volume while premium brands differentiate through unique sourcing and processing. Key strategic archetypes include large-scale integrators, premium brand innovators, and convenience-focused providers. Competitive moves frequently involve direct trade programs and sustainability storytelling, coupled with ecosystem development.
Within the scale-driven end of the market, Starbucks Coffee Company exemplifies a global presence and extensive direct trade programs, ensuring a consistent supply of certified beans. Keurig Dr Pepper occupies a strong position in the convenience segment through its single-serve pod ecosystem, offering accessibility to a broad consumer base. Lavazza anchors the premium Arabica blend segment, leveraging its heritage and sustainability narratives to differentiate its offerings in European and international markets.
| Leading Market Players |
|---|
| Keurig Dr Pepper |
| Peet's Coffee |
| Starbucks Coffee Company |
| Dunkin' |
| Tim Hortons |
| JDE Peet's Coffee and Tea |
| Lavazza |
| Costa Coffee |
| Nestlé (Nescafé) |
| Others |
Cost & Logistics Intelligence
The increasing preference for specialty Arabica beans over commodity Robusta simultaneously reshapes cultivation geography and influences premium pricing dynamics. This shift encourages investment in specific growing regions and processing methods.
Pricing Analysis
Fair Trade certification level creates the primary spread in coffee bean pricing, segmenting ethical and conventional supply. Commodity spot pricing dominates for bulk Robusta, while contract-based long-term offtake secures specialty Arabica volumes for major roasters. Price differentiation stems from quality grade, processing method, and adherence to certifications like USDA Organic. Pricing softness affects conventional beans due to global supply fluctuations and rising cultivation costs. Foodservice providers exhibit the highest price sensitivity, whereas specialty cafes prioritize quality over cost.
Supply Chain Analysis
Brazil anchors global Arabica production, while Vietnam leads in Robusta output, shaping the global coffee supply chain. Supply chains draw from coffee cherries and require significant water resources for processing. Climate change impact, including unpredictable weather patterns in key growing regions, presents a significant structural risk. Regulatory compliance costs, driven by mandates like the EUDR, impose additional burdens on exporters. Distribution runs through both direct trade models for specialty segments and traditional commodity exchanges for mass-market volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market faces a significant capability gap in climate-resilient agronomy, impacting long-term supply stability and quality. Bridging this skill deficit is essential for sustainable growth.
For Market Incumbents:
Secure long-term supply agreements with certified farms to mitigate EUDR compliance risks and ensure consistent quality. Invest in advanced traceability technologies to demonstrate verifiable origin and ethical sourcing to consumers. Develop climate-resilient coffee varietals through R&D partnerships, addressing the threat of increasing weather volatility. Expanding direct trade programs strengthens relationships with growers and enhances supply chain transparency.
For New Entrants and Emerging Players:
USDA Organic certification offers a fast-track into premium market segments, appealing to health-conscious consumers in North America. Target the rapidly expanding cold brew application segment with beans optimized for smoother, lower-acidity profiles. Focus on emerging economies in Southeast Asia with rising disposable incomes and developing café cultures. Leveraging blockchain technology for immutable proof of origin provides a strong go-to-market angle, justifying premium pricing for fully traceable beans.
For Investors and Strategic Acquirers:
Secondary-cycle assets sit with specialty roasters lacking scale or technology, presenting consolidation opportunities for long-term growth. The market's viability over a 5-10 year window depends on sustainable sourcing and technological adoption. Acquisition targets should include firms with established direct trade relationships and robust traceability systems. Widespread adoption of blockchain in supply chain verification indicates a significant inflection point for investment.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Traceability Technology | Enhances compliance with regulations like EUDR and meets consumer demand for verifiable origin. |
| Develop Climate-Resilient Varietals | Mitigates crop yield volatility caused by extreme weather events in key growing regions. |
| Expand Direct Trade Programs | Secures consistent supply of certified beans and builds stronger relationships with producers. |
| Integrate Functional Ingredients | Opens new revenue streams by incorporating coffee extracts into nutraceuticals and RTD beverages. |
| Obtain Sustainability Certifications | Differentiates products in premium markets and appeals to ethically conscious consumer segments. |
Research Approach
Initial hypotheses were tested against primary input from coffee growers, roasters, importers, and retail buyers and refined through an iterative process. This involved in-depth interviews with industry stakeholders across various value chain points. Secondary validation drew from EUDR compliance reports, USDA Organic standards, EFSA food safety guidelines, and ISO quality standards. The analysis employed both bottom-up and top-down triangulation to ensure data accuracy and comprehensive market coverage.
Variance decomposition informed the analytical framework across the modeling period, dissecting market drivers and restraints. Segmentation dimensions modeled included product type, processing method, application, end-user, and regional regulatory frameworks. Compound annual growth rates were derived from historical trends and future projections, capturing market evolution. Industry-specific forecast inputs incorporated climate change models and consumer preference shifts for cold brew and specialty coffee.
Underlying assumptions cover stable geopolitical conditions and consistent regulatory enforcement, with deviation risk concentrated in extreme weather events and unforeseen trade policy shifts. Forecasts reflect these assumptions, but remain responsive to significant market disruptions. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
North America Ready-To-Drink (RTD) Coffee Market
Coffee
Stove Top Moka Coffee Pot Market
Coffee
Global Coffee Machine Market
Coffee
Coffee Cherry Market
Coffee
Butter Coffee Market
Coffee
Flavored Cold-Brew Coffee Market
Coffee
Asia Pacific Coffee Market
Coffee
Middle East Coffee Market
Coffee
Italy Coffee Market
Coffee
Europe Ready-To-Drink (RTD) Coffee Market
Coffee
Espresso Coffee Market
Coffee
APAC Ready-To-Drink Coffee Market
Coffee
Coffee Capsules Market
Coffee
Coffee Premixes Market
Coffee
Green Coffee Market
Coffee
India Coffee Roaster Market