
 Coffee Cherry Market | 2026-2036
Coffee Cherry Market Size, Share, and Industry Trends Forecast 2026-2036
Coffee Cherry Market Analysis
Direct-trade relationships between origin farms and specialty roasters is reshaping how coffee cherry value gets captured upstream. KonaRed Corporation leverages its Hawaiian estate model to control cascara processing from harvest to packaged goods. Nestlé anchors global volume through its Nespresso AAA Sustainable Quality Program, which binds cherry procurement to agronomic technical assistance. Good Land Organics differentiates by specializing in California-grown coffee cherry, occupying a narrow but defensible terroir niche outside traditional equatorial belts.
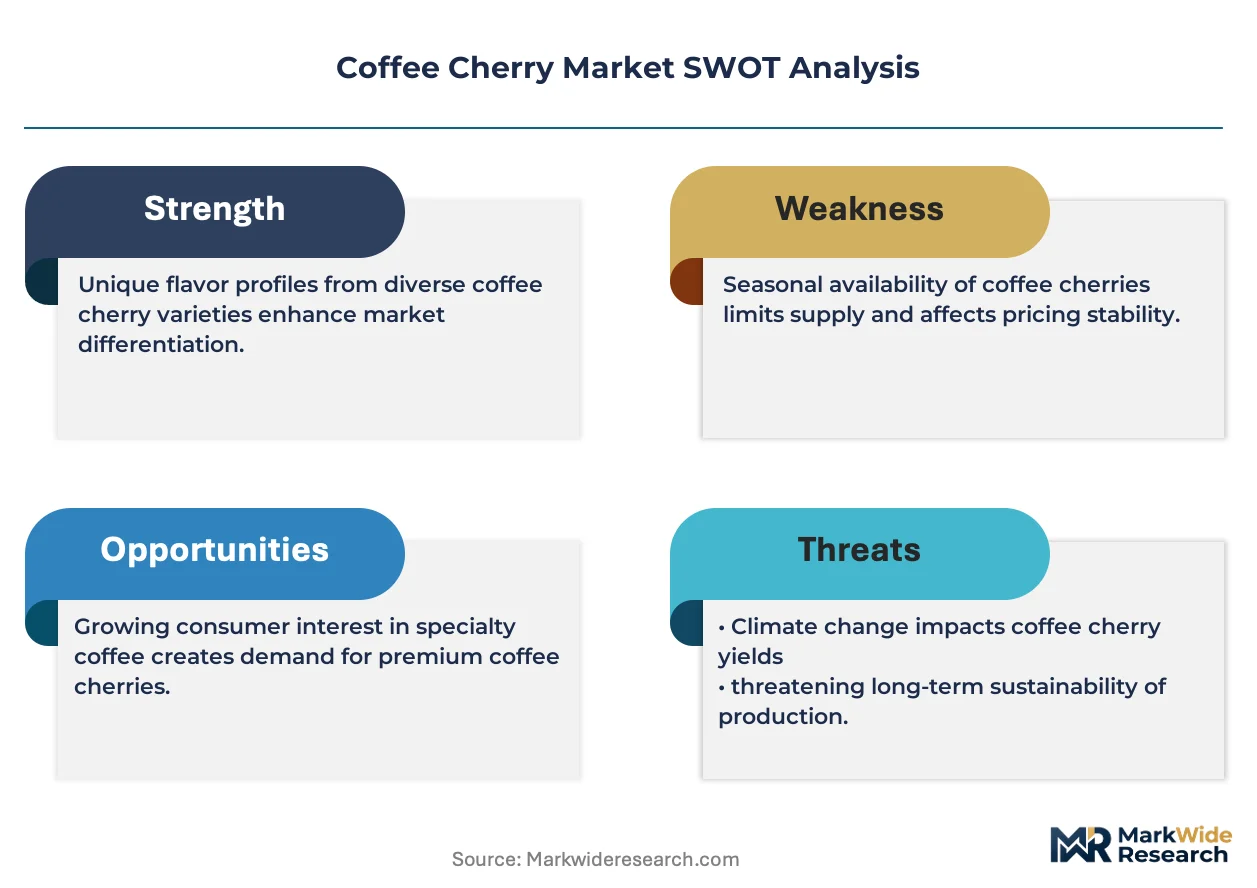
Coffee cherry comprises the fleshy outer fruit surrounding the coffee seed, containing sugars, pectins, and polyphenols that constitute roughly 40-50% of the harvested cherry mass by weight; processors traditionally discard this husk as pulp waste, though innovators now extract cascara tea, flour, and nutraceutical inputs from this previously discarded fraction. Green coffee beans within the product type hierarchy still dominate value capture, yet coffee extracts represent the fastest-expanding margin pool as beverage brands seek concentrated flavor and functional ingredient formats. Among processing methods, natural and honey processes are gaining share as water-scarce origins adopt lower-wash techniques that also preserve more cherry mucilage for secondary product streams.
The USDA's National Organic Program and the EU's deforestation regulation jointly shape market access, with compliance costs favoring vertically integrated estates over fragmented smallholder networks. FDA food additive classifications for cascara and coffee cherry derivatives determine which downstream applications processors can legally pursue in the United States. Stakeholders must monitor how evolving novel food approvals in multiple jurisdictions either unlock or constrain industrial use cases for cherry pulp beyond traditional cascara tea.
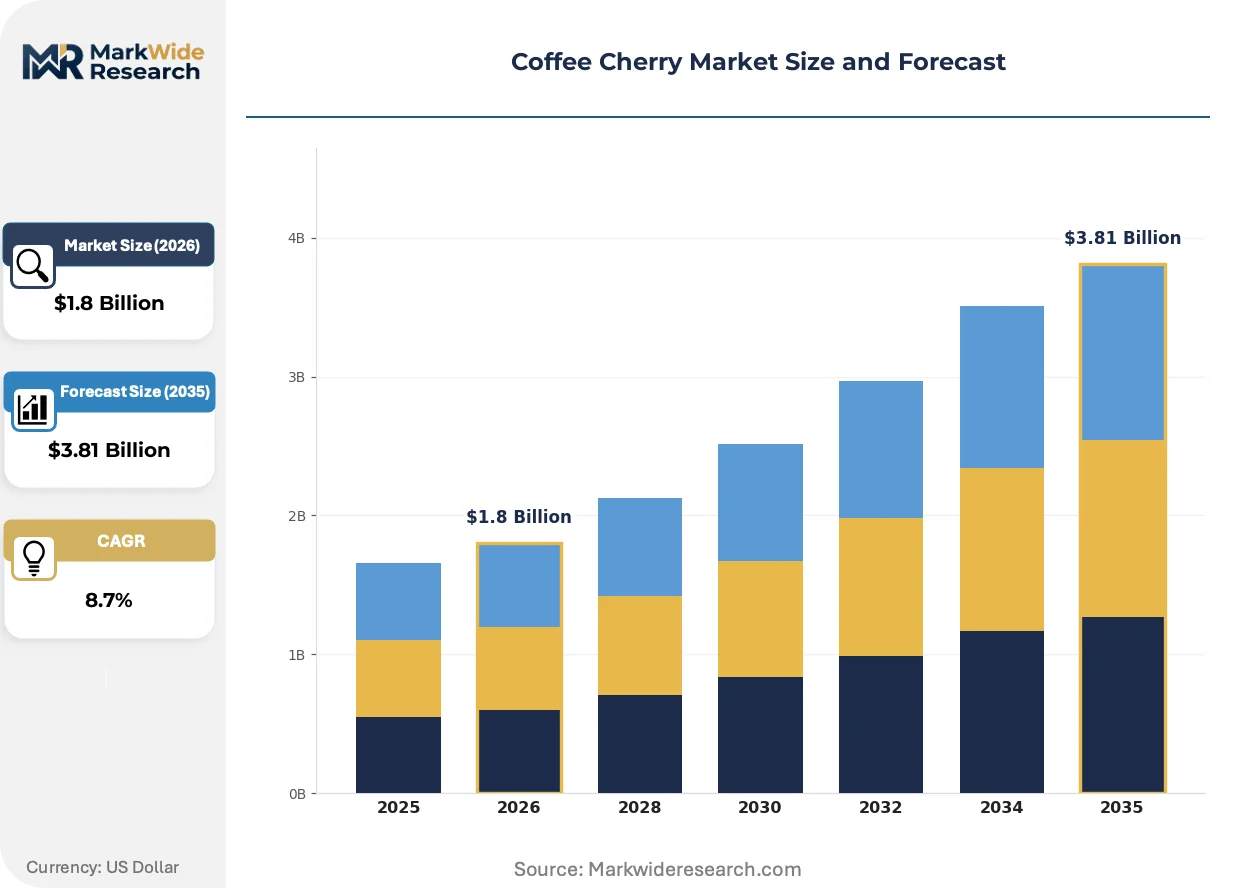
Market Dynamics
The EU Green Deal's deforestation-free supply chain requirements are forcing processors to abandon untraceable spot-market sourcing in favor of farm-level verification systems that document cherry provenance from harvest to export.
Growth Catalysts
- Cascara beverage innovation:Specialty coffee shops in Portland, Oregon and Melbourne, Australia are expanding procurement of dried coffee cherry husks for tea and functional drink formulations.
- REACH-compliant extraction methods:European processors adopting solvent-free supercritical CO2 systems are unlocking food-grade cascara flour for bakery applications.
- Sidama cooperative infrastructure:Ethiopian producer organizations are building direct-export channels that bypass traditional auction systems and capture higher cherry premiums.
Market Restraints
- Water scarcity in key origins:Brazil's Cerrado and Minas Gerais regions face recurring drought cycles that compress cherry maturation windows and degrade pulp quality for secondary processing.
- FDA novel food classification delays:Cascara and coffee cherry derivatives remain in regulatory limbo for broad food additive applications, constraining industrial formulation beyond beverage teas.
- Input cost volatility:Natural gas prices directly impact mechanical drying costs for honey-processed cherries, eroding margins at mid-scale washing stations.
Strategic Opportunities
- California terroir expansion:Good Land Organics and emerging Santa Barbara County growers are demonstrating viable coffee cherry cultivation outside equatorial belts for premium domestic supply.
- EU CSRD-aligned carbon accounting:The Corporate Sustainability Reporting Directive creates procurement preference for verified low-emission cherry processing among European roasters.
- Nutraceutical channel development:Polyphenol-rich cherry pulp concentrates are penetrating supplement formulators seeking antioxidant inputs with clean-label positioning.
Industry Challenges
- Post-harvest processing skill gaps:Washing station operators lack training in mucilage retention techniques that preserve cherry pulp value for cascara extraction.
- Certification timeline compression:USDA National Organic Program and EU organic equivalence requirements demand 36-month conversion periods that strain working capital at cooperative level.
- Legacy wet-mill infrastructure:Conventional depulping equipment designed for seed recovery destroys cherry husk integrity, requiring capital replacement for dual-product output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coffee Cherry Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Green Coffee Beans, Roasted Coffee, Instant Coffee, Coffee Extracts Processing Method: Washed, Natural, Honey, Semi-Washed End User: Retail Consumers, Coffee Shops, Food Service, Industrial Users Quality Grade: Specialty, Premium, Commercial, Others |
| Companies Covered | Mountain Thunder Coffee Plantation, Greenwell Farms Inc., Kona Joe Coffee LLC, Hula Daddy Kona Coffee, Mauka Meadows Coffee Farm, Good Land Organics, KonaRed Corporation, Nestlé, Starbucks Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coffee Cherry Market Emerging Trajectories
Processing technology and regulatory architecture are converging to transform coffee cherry from waste stream to valued input, with implications for equipment design, farm economics, and downstream formulation.
Supercritical CO2 extraction systems are rendering obsolete traditional hot-water cascara brewing methods that leach inconsistent polyphenol profiles. European nutraceutical ingredient houses are adopting these systems to produce standardized extracts for functional beverage brands. The technology is compressing batch-to-batch variation and enabling shelf-stable concentrate formats that penetrate retail channels beyond specialty coffee.
REACH registration requirements for novel food contact substances are tightening specification standards for cascara-derived ingredients entering European markets. Processors must document full supply chain absence of unregistered solvents and contaminants. Smallholder-dependent origins lacking laboratory infrastructure face exclusion from premium export tiers unless they affiliate with vertically integrated estates or cooperative processing hubs.
Direct-trade contracting is displacing auction-based cherry sales in Ethiopia's Yirgacheffe zone as roasters seek lot-level traceability for EUDR compliance documentation. Specialty buyers are locking multi-year purchase agreements with washing stations that maintain segregated processing lines. This pattern concentrates procurement relationships among cooperatives with capital reserves for certification and digital record-keeping infrastructure.
Coffee Cherry Market Segmentation
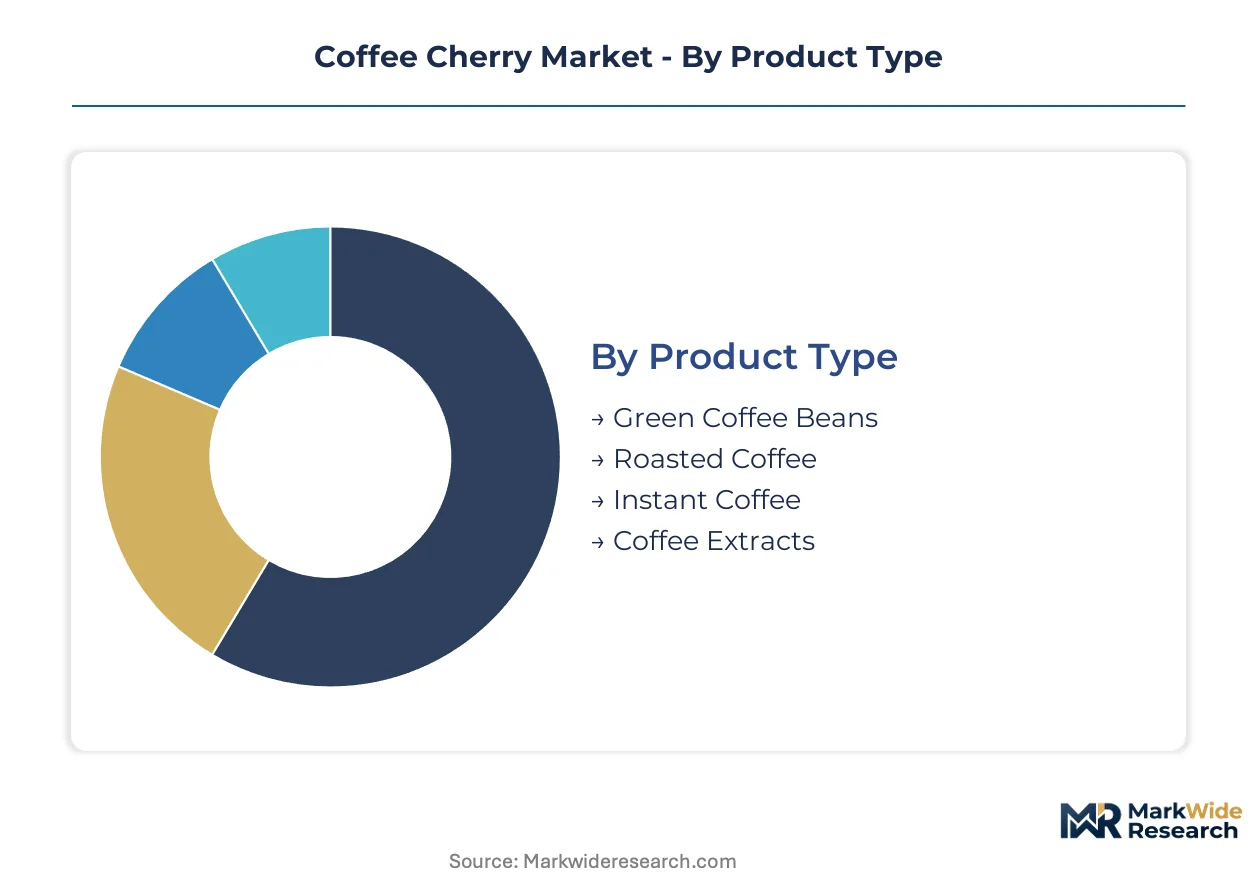
Coffee cherry segmentation reveals how value migrates across processing stages and buyer categories. Distinct technical requirements and margin structures separate commodity-grade pulp from specialty cascara and extract-grade inputs.
Product Type:
End-use applications span from seed-centric coffee production to emerging pulp-derived ingredients, with each tier commanding different processing investments and regulatory pathways.
- Green Coffee Beans:Unroasted seeds remain the dominant mass fraction of cherry processing, with wet-milling infrastructure across Ethiopia's Sidama zone and Brazil's Cerrado optimized for seed recovery rather than pulp valorization. Specialty buyers in Portland and Melbourne now stipulate honey-processed lots that retain mucilage for cascara co-products.
- Coffee Extracts:Concentrated flavor and functional ingredient formats are penetrating beverage formulation and nutraceutical channels. Supercritical CO2 systems in European processing facilities produce standardized polyphenol profiles that REACH registration requirements now govern.
- Roasted Coffee:Traditional value-added segment where cherry provenance documentation is becoming mandatory for EU Green Deal compliance.
- Instant Coffee:Volume-driven category where soluble extraction economics limit upstream cherry premium capture.
The dominant share belongs to Green Coffee Beans, while Coffee Extracts is closing the gap fastest.
Processing Method:
Water intensity and mucilage retention characteristics differentiate methods by cost structure and secondary product viability.
- Honey:Partial mucilage retention creates dual-product streams of seeds and pulp suitable for cascara flour. Drought cycles in Minas Gerais are accelerating adoption as water-scarce origins seek lower-wash alternatives that preserve cherry sugars for fermentation.
- Natural:Dry fermentation concentrates fruit sugars in the husk, yielding cascara with pronounced sweetness profiles favored by Australian specialty tea blenders. Extended drying requirements expose processors to natural gas price volatility that erodes margins at mid-scale washing stations.
- Washed:Conventional depulping equipment destroys husk integrity, requiring capital replacement for operators seeking cascara co-production.
- Semi-Washed:Intermediate water use positions this method for origins transitioning toward pulp valorization without full honey-process infrastructure.
Honey processing holds the dominant operational share among specialty operators, while Natural methods are expanding most quickly in water-constrained origins.
End User:
Procurement scale and traceability requirements fragment demand across consumer-facing and industrial channels.
- Coffee Shops:Specialty outlets in Melbourne and Portland drive cascara beverage innovation through direct-trade relationships with Ethiopian cooperatives. EUDR documentation requirements are compressing supplier lists to washing stations with digital record-keeping infrastructure.
- Industrial Users:Nutraceutical formulators and bakery ingredient houses extract polyphenol concentrates and flour fractions. FDA novel food classification delays constrain US market penetration beyond beverage applications.
- Retail Consumers:Packaged cascara tea and functional drinks reach this segment through specialty grocery and direct-to-ecommerce channels.
- Food Service:Institutional buyers prioritize cost-stable supply over provenance documentation, limiting premium cherry pulp uptake.
Coffee Shops command the dominant procurement volume for traceable specialty grades, while Industrial Users are gaining share fastest as extraction technology matures.
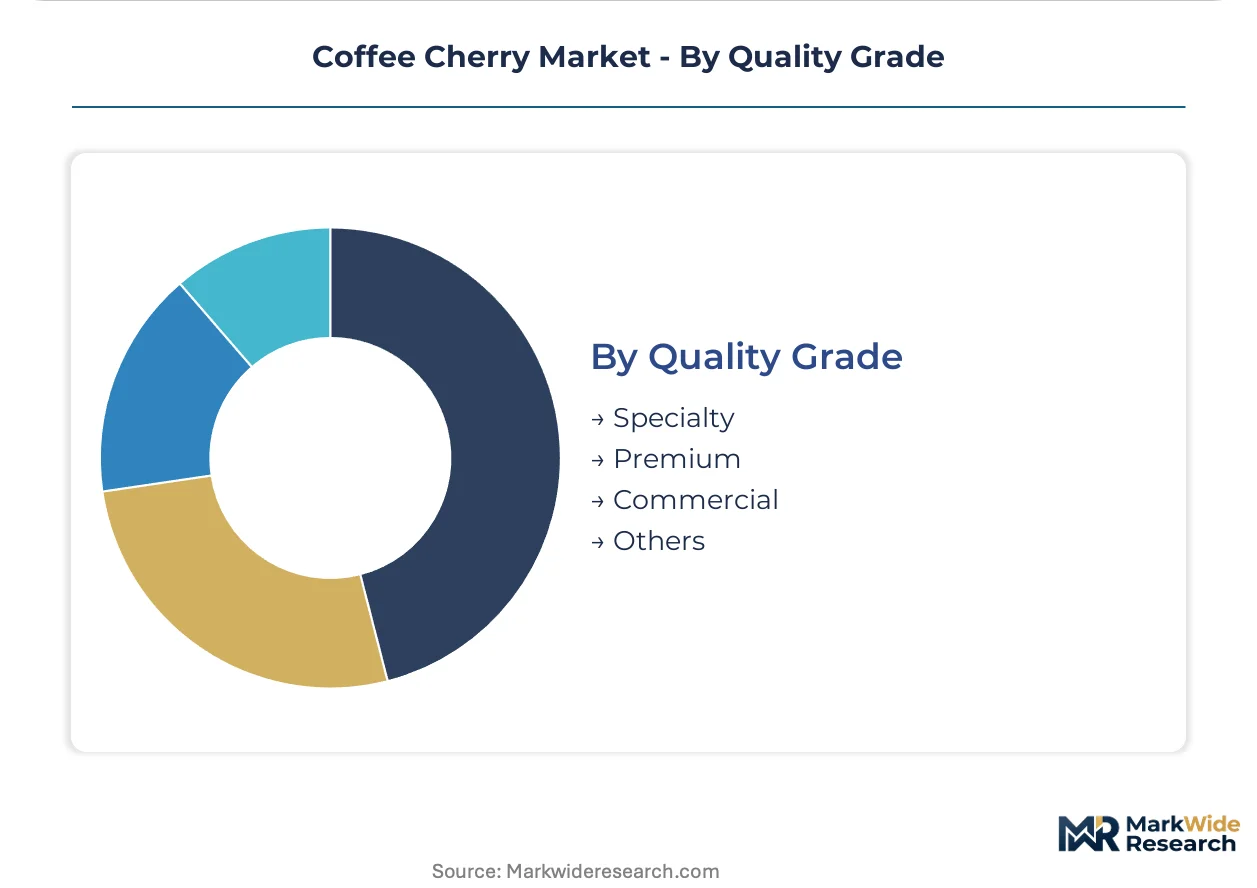
Quality Grade:
Certification tiers and defect thresholds determine market access and price realization across regulatory jurisdictions.
- Specialty:Lot-level traceability and organic certification unlock direct-export premiums. USDA National Organic Program and EU organic equivalence requirements demand 36-month conversion periods that strain cooperative working capital.
- Premium:Segregated processing without full certification captures mid-tier roaster demand for deforestation-free documentation under EU Green Deal rules.
- Commercial:Spot-market aggregation lacks provenance verification, facing exclusion from European premium tiers.
- Others:Sub-commercial grades enter commodity cascara or agricultural input channels with minimal value recovery.
Specialty grade holds the dominant value-capture position, while Premium is climbing the fastest as EUDR compliance spreads beyond certified organic channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ethiopian washing stations command cascara premiums that Brazilian commodity processors cannot match, creating a pricing-power asymmetry that favors traceable East African supply over volume-driven Latin American origins.
Ethiopia
Sidama and Yirgacheffe cooperatives drive specialty cascara demand through direct-export relationships with Melbourne and Portland roasters. The EU Green Deal's deforestation-free requirements accelerate farm-level verification investments. Washing stations in the Gedeo Zone now maintain segregated honey-processed lines for dual-product seed and pulp recovery.
Brazil
Minas Gerais and Cerrado origins dominate green coffee bean volume but struggle to capture cascara premiums due to drought-compressed maturation windows. The national agricultural regulator enforces sanitary standards for pulp-derived food ingredients. São Paulo-based processors pilot mechanical mucilage retention systems to access European nutraceutical channels.
United States
FDA novel food classification delays constrain industrial cascara formulation beyond beverage teas. California's Santa Barbara County hosts Good Land Organics and emerging terroir-focused growers demonstrating viable cultivation outside equatorial belts. Hawaiian estates in Kona leverage controlled processing environments for premium domestic supply.
Australia
Melbourne specialty coffee shops anchor Asia-Pacific cascara beverage innovation through direct-trade Ethiopian procurement. The country's national food standards regulator evaluates novel food approvals for cherry pulp derivatives. Victorian roasting clusters demand REACH-aligned extraction documentation for imported concentrates.
Germany
European nutraceutical ingredient houses adopt supercritical CO2 systems to produce standardized cascara extracts. ECHA REACH registration requirements tighten contaminant documentation for pulp-derived inputs. Hamburg processing facilities serve as distribution hubs for EU CSRD-aligned carbon accounting among roasters.
Coffee Cherry Market Vendor Landscape
Estate-based origin controllers and multinational branded platforms split the market into divergent value-capture models. Hawaiian estate operators dominate traceable premium cascara through controlled harvest-to-package processing. Nestlé anchors global volume through technical assistance-tied procurement programs. Competitive moves concentrate on direct-trade contracting for EUDR compliance documentation and solvent-free extraction technology licensing.
Within the estate-controller archetype, KonaRed Corporation and Good Land Organics exemplify geographic terroir specialization, with the former representing Hawaiian controlled-origin processing and the latter occupying California's emerging domestic cultivation niche. Nestlé sits within the multinational platform tier, leveraging agronomic technical assistance to bind cherry procurement at scale. These three anchors illustrate how vertical control over processing infrastructure separates premium cascara suppliers from commodity-grade pulp aggregators.
| Leading Market Players |
|---|
| Mountain Thunder Coffee Plantation |
| Greenwell Farms Inc. |
| Kona Joe Coffee LLC |
| Hula Daddy Kona Coffee |
| Mauka Meadows Coffee Farm |
| Good Land Organics |
| KonaRed Corporation |
| Nestlé |
| Starbucks Corporation |
| Others |
Supply Flow & Price Mechanics
Djibouti-Port of Mombasa freight corridors carry Ethiopian cascara to European nutraceutical houses, with container rates compressing margins at cooperative washing stations while amplifying price spreads between traceable specialty grades and untraceable commodity pulp. This logistics cost dynamic concentrates procurement power among vertically integrated estates that absorb freight volatility through captive processing, forcing mid-scale operators into honey-processed specialization to capture dual-product premiums.
Pricing Analysis
Direct-trade contract premiums over auction spot pricing now exceed standard differentials as EUDR documentation requirements add compliance layers. Three-tier pricing structure across specialty, premium, and commercial grades reflects certification status and lot-level traceability, with organic-certified Sidama lots commanding maximum premiums. Cost compression in commercial-grade pulp is intensifying because Brazilian drought cycles degrade husk quality for secondary processing. Industrial nutraceutical buyers show least price sensitivity due to polyphenol concentration specifications, while food-service channels remain most elastic.
Supply Chain Analysis
Extended payment terms from European roasters to Ethiopian cooperatives strain working capital during 36-month organic conversion periods, forcing reliance on trade finance facilities. Supply concentrates in Ethiopia, Brazil, and Colombia, with Ethiopian Sidama and Yirgacheffe zones anchoring specialty cascara quality. Raw material flows draw from coffee cherry harvests, mechanical drying infrastructure, and supercritical CO2 extraction equipment. Single-source vulnerability runs through Ethiopian cooperative washing stations lacking redundant processing lines. Distribution runs through direct-trade channels for specialty grades and commodity aggregators for commercial pulp.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cascara's emergence as a co-product platform transforms farm economics from seed-centric to dual-stream value capture, with interoperability between honey-processing infrastructure and nutraceutical extraction standards determining which origins capture upstream margin expansion.
For Market Incumbents: Build traceability infrastructure moats through farm-level digital verification systems that satisfy EUDR documentation requirements. Nestlé's AAA program model offers a template for binding technical assistance to long-term procurement contracts. Hawaiian estate operators should expand controlled-origin processing capacity before California terroir competitors achieve scale. Certification investment in organic and deforestation-free standards protects premium tier access against Brazilian volume challengers.
For New Entrants and Emerging Players: California's Santa Barbara County represents underpenetrated domestic cultivation territory with premium positioning potential outside equatorial supply constraints. Australian and German nutraceutical formulators seeking REACH-compliant cascara extracts present white-space demand for solvent-free processing specialists. Target direct-trade relationships with Portland and Melbourne specialty roasters as anchor customers before scaling to industrial channels. Go-to-market leverage rests on demonstrating lot-level traceability through blockchain-verified harvest documentation.
For Investors and Strategic Acquirers: Estate-controller archetypes with integrated harvest-to-package processing infrastructure offer durable competitive positioning as regulatory compliance costs rise. Long-term viability favors operators with captive supply rather than spot-market dependent aggregators. Processing technology licensors specializing in supercritical CO2 extraction systems represent alternative exposure to cascara value migration. Watch FDA novel food classification timelines as the critical inflection signal for US industrial market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-Trade Contracting | Locks multi-year supply relationships with EUDR-compliant Ethiopian washing stations. |
| Supercritical CO2 Licensing | Enables REACH-registered cascara extract production for European nutraceutical channels. |
| Honey-Process Infrastructure | Preserves mucilage value for dual-product seed and pulp recovery at water-scarce origins. |
| California Terroir Expansion | Demonstrates viable domestic cultivation outside traditional equatorial supply belts. |
| Organic Certification Investment | Unlocks USDA National Organic Program premiums through 36-month conversion compliance. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with cooperative washing station managers, specialty roaster procurement leads, nutraceutical formulators, and European regulatory compliance officers. Secondary validation drew from EU Green Deal implementation guidance, FDA novel food classification dockets, ECHA REACH registration databases, and Ethiopian Coffee & Tea Authority export statistics. Bottom-up triangulation across farm-level production data and top-down reconciliation against trade flow aggregates ensured methodological rigor.
Calibration against historical price realization patterns and processing capacity buildouts anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type hierarchy, processing method water intensity, end-user procurement scale, and quality grade certification tier. CAGRs derived from trend extrapolation of cascara beverage penetration rates and nutraceutical ingredient adoption curves. Forecast inputs incorporated drought frequency projections for Brazilian Cerrado origins and EU CSRD-aligned carbon accounting adoption timelines among European roasters.
Macroeconomic conditions sit as an overlay; deviation in natural gas pricing, container freight rates, or organic certification conversion timelines would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory approval pathways and technology adoption S-curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Global Professional Coffee Machine Market
Coffee
Coffee and Tea Capsule Market
Coffee
Coffee Bags Market
Coffee
Take Out Coffee Market
Coffee
Global Portable Coffee Makers Market
Coffee
Global Automatic Coffee Machines Market
Coffee
Mushroom Coffee Market
Coffee
Europe Coffee Market
Coffee
Freeze Dried Coffee Market
Coffee
Vietnam Coffee Market
Coffee
Drip Coffee Machine Market
Coffee
Coffee Pods Market
Coffee
Asia-Pacific Coffee Franchise Market
Coffee
Italy Coffee Market
Coffee
Global Coffee Machine Market
Coffee
Germany Coffee Market