
 Coffee Capsules Market | 2026-2036
Coffee Capsules Market Size, Share, and Industry Trends Forecast 2026-2036
Coffee Capsules Market Analysis
Variety pack bundling is rebalancing buyer choice in the coffee capsules space, shifting purchasing from single-flavor commitments toward trial-oriented assortment formats. Nestle Nespresso S.A. anchors premium positioning through proprietary system lock-in and boutique retail presence. Keurig Dr Pepper Inc. leverages broad brand licensing to sustain volume leadership in North American households. Jacobs Douwe Egberts competes across multiple pod platforms, navigating interoperability demands in European markets.
Coffee capsules are sealed, pre-portioned containers of ground coffee designed for single-serve extraction in compatible brewing machines, typically constructed from aluminum, plastic, or biodegradable composites with barrier layers preserving aroma and preventing oxidation. Their primary commercial purpose is delivering consistent, convenient espresso-style or filtered coffee without grinding, dosing, or cleanup. Single Serve formats occupy the dominant volume position, while Biodegradable materials represent the fastest-growing structural segment as regulatory pressure on plastic waste intensifies. Specialty Stores channel distribution captures premium margin pools, whereas Online Retail extends reach into subscription-based household replenishment models.
The EU Green Deal and REACH frameworks restrict conventional plastic capsule circulation across Europe, while FDA food-contact regulations govern material safety for US-imported capsules. Germany's national packaging law and Italy's extended producer responsibility schemes further shape compliance costs and material selection for manufacturers. Stakeholders must monitor evolving biodegradability certification standards and interoperability patent expirations to calibrate R&D allocation and geographic prioritization.
Market Dynamics
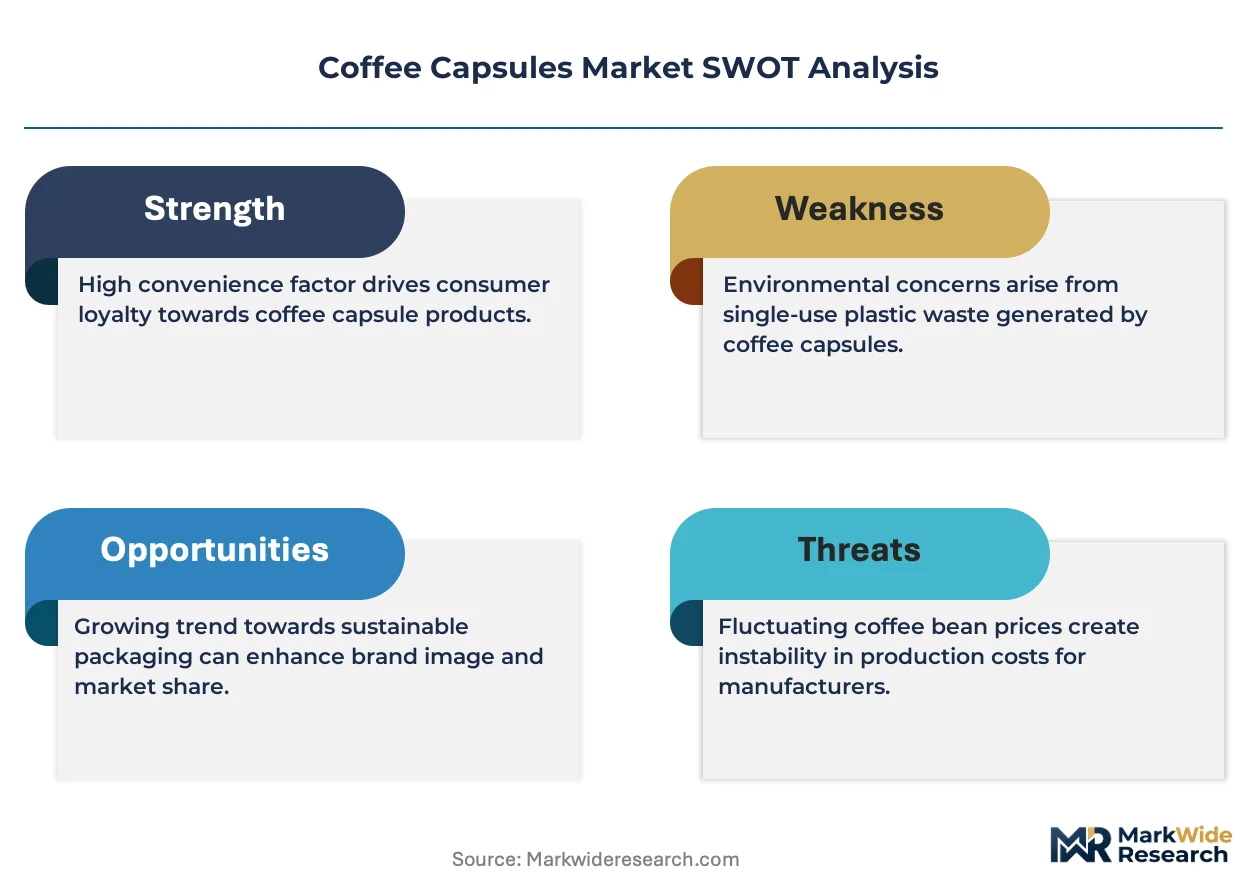
The EU Green Deal's packaging waste directives are compressing manufacturers toward biodegradable material transitions, restructuring R&D allocation and supplier qualification timelines across the European supply base.
Growth Catalysts
- Workplace coffee programs:North American office refreshment services are standardizing single-serve formats as employee amenity infrastructure, pulling volume through B2B procurement channels.
- REACH framework compliance:European chemical safety mandates are accelerating substitution of petroleum-based barrier layers with plant-derived sealants in capsule construction.
- German packaging law:Extended producer responsibility schemes in Germany are forcing closed-loop collection systems that improve brand loyalty through deposit-return mechanisms.
Market Restraints
- Aluminum price volatility:Primary aluminum ingot costs fluctuate with energy-intensive smelter operations in China and Russia, squeezing margin on premium metal capsule lines.
- Interoperability patent thickets:Proprietary brewing system designs create legal barriers to cross-platform pod compatibility, fragmenting addressable markets by machine installed base.
- Compostable certification delays:Industrial composting infrastructure gaps in most municipalities limit actual biodegradation rates versus laboratory claims, creating consumer skepticism.
Strategic Opportunities
- Subscription replenishment models:Direct-to-consumer auto-ship programs bypass retail slotting fees and capture lifetime value through predictable consumption data.
- Specialty coffee tier expansion:Third-wave roasters are entering capsule formats with single-origin, small-lot positioning at 3-4x mass-market price points.
- Office channel digitization:IoT-enabled brewers with usage tracking enable predictive restocking and corporate account expansion in Germany and the Netherlands.
Industry Challenges
- Biodegradability testing capacity:Laboratory backlog for EN 13432 and ASTM D6400 certification extends product launch timelines by 8-14 months.
- Flavor extraction engineering:Matching espresso-quality crema and aromatic release in compostable barrier materials requires specialized polymer science talent that concentrates in Swiss and Italian research clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coffee Capsules Market |
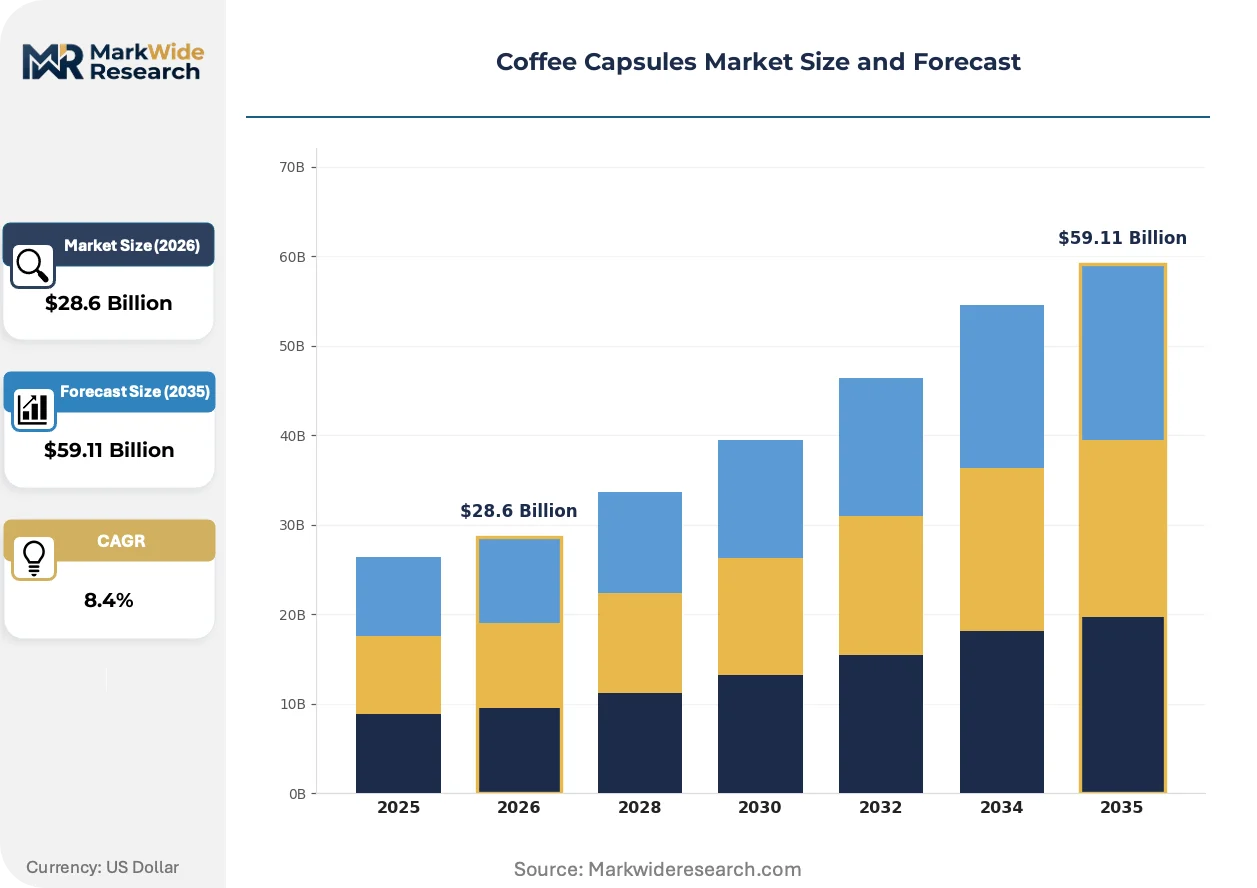
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $59.11 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Serve, Bulk Packs, Variety Packs, Organic Material: Plastic, Aluminum, Biodegradable, Composite Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Vending Machines Customer Type: Household, Office, Café, Institutions |
| Companies Covered | Luigi Lavazza S.p.A., The J. M. Smucker Company, Nestle Nespresso S.A, Jacobs Douwe Egberts, JAB Holding Company, Starbucks Corporation, The Kraft Heinz Company, Illycaffe S.p.A., Keurig Dr Pepper Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coffee Capsules Market Emerging Trajectories
Material science breakthroughs and regulatory compliance automation are converging to reshape competitive advantage in capsule construction and distribution logistics.
Home-compostable capsule shells incorporating polylactic acid and lignin-based barrier layers are integrating into premium product lines. Specialty coffee roasters in Germany and Scandinavia are adopting these materials at pilot scale. This integration is compressing the timeline for industrial composting infrastructure investment decisions by waste management utilities.
REACH SVHC candidate list expansion is restricting bisphenol-derived coatings in plastic capsule manufacturing. European compounders are reformulating internal sealants to maintain oxygen barrier performance. Food-contact notification pathways through EFSA are creating 18-24 month compliance lead times that favor established players with regulatory affairs capacity.
Corporate procurement departments are consolidating coffee service contracts under facility management outsourcing arrangements. Single-serve formats are displacing batch brew equipment in Class A office towers. This concentration is most visible in London and Frankfurt financial districts, where tenant amenity competition drives premium positioning.
Coffee Capsules Market Segmentation
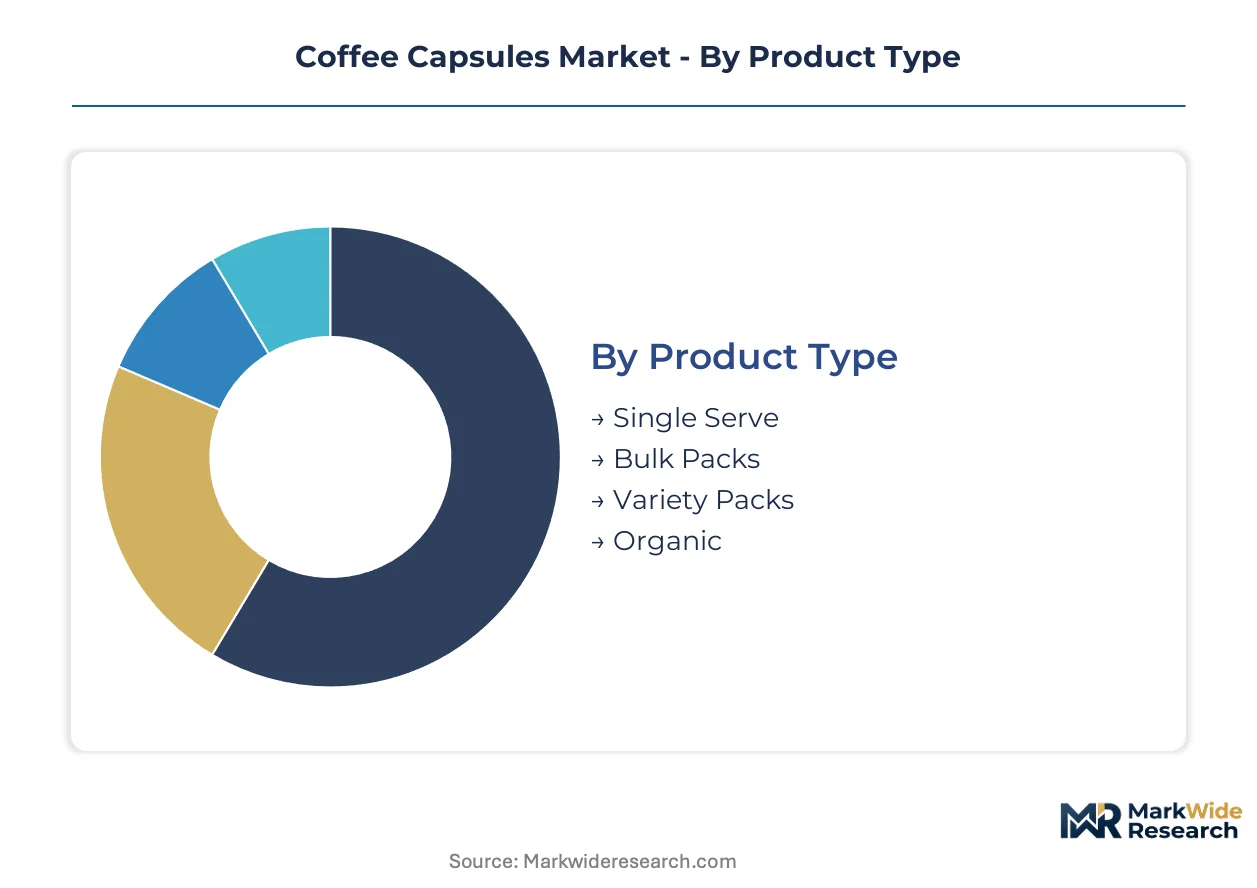
Capsule segmentation reveals divergent margin structures across convenience tiers and sustainability credentials. Material composition and distribution channel choices directly determine compliance burden and pricing power in regulated European markets.
Product Type:
Volume leadership concentrates in single-unit formats while assortment bundling captures trial-driven household penetration.
- Single Serve:Individual hermetically sealed pods designed for one-cup extraction in compatible brewing systems. German office coffee programs and Dutch workplace amenity contracts standardize this format as baseline infrastructure, pulling steady B2B procurement volume.
- Variety Packs:Assorted flavor bundles enabling consumer trial without single-flavor commitment. Scandinavian household subscription services concentrate demand here, driven by preference exploration and reduced purchase risk.
- Bulk Packs:High-count carton formats targeting cost-conscious institutional buyers with predictable consumption patterns.
- Organic:Certified chemical-free capsules commanding shelf space in specialty retail channels with sustainability positioning.
Mature deployment sits with Single Serve. Newer deployment is concentrated in Variety Packs.
Material:
Regulatory pressure is fragmenting supply chains across petroleum-based and bio-derived construction pathways.
- Biodegradable:Compostable shells incorporating polylactic acid, lignin barriers, or molded fiber matrices that decompose in industrial composting conditions. Italian and German municipal waste directives accelerate substitution here, though certification bottlenecks constrain supply expansion.
- Aluminum:Oxygen-impermeable metal capsules with lacquered interiors preserving volatile aromatic compounds. Swiss premium positioning and French boutique retail channels sustain demand despite energy-intensive production footprints.
- Plastic:Polypropylene or polystyrene constructions with multi-layer barrier films. REACH SVHC restrictions are compressing European deployment of this legacy format.
- Composite:Hybrid constructions blending aluminum lids with bio-based bodies, navigating performance-cost tradeoffs in transitional product lines.
Established capacity centers on Aluminum. Steepest expansion trajectory belongs to Biodegradable.
Distribution Channel:
Channel selection determines margin capture versus reach tradeoffs and replenishment predictability.
- Specialty Stores:Curated retail environments with assisted selling and machine demonstration capabilities. Paris, Milan, and Vienna flagship locations anchor premium brand positioning and attach high-margin accessory sales.
- Online Retail:Direct-to-consumer platforms with subscription auto-ship functionality. UK and Netherlands household penetration concentrates here, enabled by predictable consumption data and bypassed retail slotting fees.
- Supermarkets:Mass-market shelf presence with promotional velocity driving volume in France and Spain.
- Vending Machines:Automated point-of-need distribution in transport hubs and corporate lobbies, concentrated in Japanese and South Korean urban corridors.
Volume scale favors Supermarkets. Margin extraction concentrates in Specialty Stores.
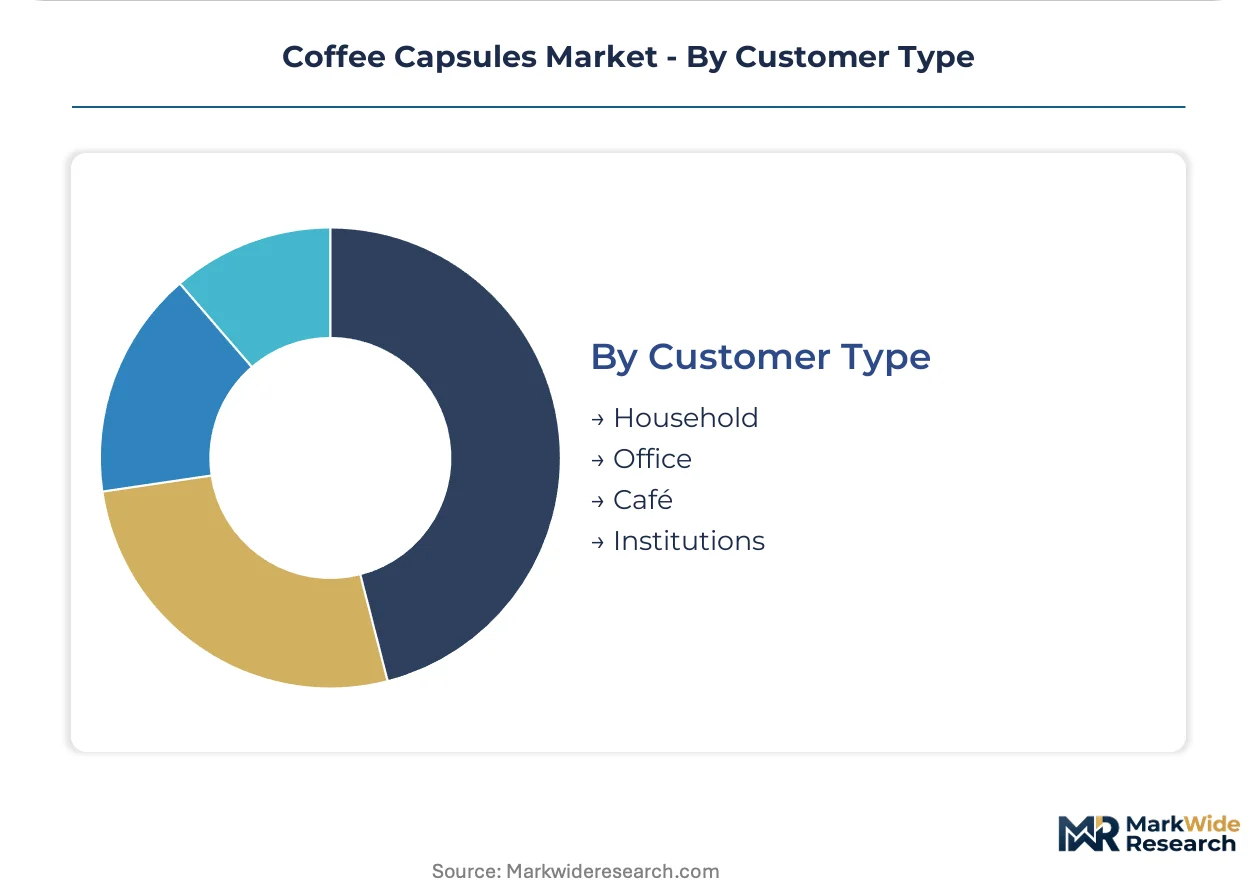
Customer Type:
End-use segmentation separates recurring B2B contract value from discretionary household purchasing.
- Office:Corporate refreshment programs with standardized machine fleets and consolidated procurement. Frankfurt and London financial district tenants compete on amenity quality, pulling premium single-serve adoption.
- Household:Individual consumers with subscription replenishment or promotional trial behavior. German and Belgian residential demand concentrates in variety-seeking purchase patterns.
- Café:Foodservice operations using capsules for consistency in secondary locations or off-peak hours.
- Institutions:Healthcare, education, and government facilities with cost-prioritized tender processes and extended contract terms.
Contract predictability sits with Office. Discretionary volatility concentrates in Household.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Vietnam and duty-free manufacturing corridors in Switzerland concentrate capsule packaging investment. Tax incentives for sustainable materials processing pull facility construction toward these jurisdictions. Regional demand patterns diverge sharply between established European markets and emerging Asian consumption centers.
Germany
Workplace coffee amenity contracts in Frankfurt and Munich financial districts standardize single-serve formats as employee retention infrastructure. The national packaging law mandates extended producer responsibility with deposit-return mechanisms. Hamburg hosts the densest concentration of industrial composting facilities, enabling faster biodegradable capsule validation cycles than elsewhere in Europe.
United States
Office refreshment service consolidation across Class A towers in Manhattan and Chicago drives B2B procurement volume. FDA food-contact regulations govern barrier layer safety for all imported capsules. Seattle and San Francisco specialty roasters pilot home-compostable formats, compressing timelines for municipal composting infrastructure investment decisions.
Italy
Boutique retail channels in Milan and Rome sustain premium aluminum capsule demand through assisted selling environments. REACH framework restrictions on bisphenol-derived coatings force sealant reformulation in domestic manufacturing. The Piedmont research cluster concentrates polymer science talent for compostable barrier engineering, creating capability scarcity elsewhere.
Netherlands
Household subscription penetration in Amsterdam and Rotterdam exceeds European averages through direct-to-consumer platform density. EFSA food-contact notification pathways create 18-24 month compliance lead times. The Eindhoven logistics corridor enables predictive replenishment models with same-day fulfillment radii covering Benelux markets.
France
Supermarket promotional velocity in Paris and Lyon drives mass-market volume for plastic and composite formats. EU Green Deal packaging waste directives accelerate substitution timelines. The Auvergne-Rhône-Alpes region hosts aluminum smelting capacity that buffers premium capsule producers from ingot price volatility elsewhere.
Coffee Capsules Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across material technology and distribution channel dimensions. Nestle Nespresso S.A. anchors premium positioning through proprietary system architecture. Keurig Dr Pepper Inc. sustains volume leadership via broad brand licensing. Jacobs Douwe Egberts navigates multi-platform interoperability demands. Strategic moves concentrate on M&A for compostable material capabilities and capacity expansion in certified production lines.
Among diversified food-and-beverage conglomerates, Nestle Nespresso S.A. and The Kraft Heinz Company exemplify scale-driven archetypes with regulatory affairs capacity to manage EFSA notification timelines. Keurig Dr Pepper Inc. occupies a position bridging licensed brand aggregation with North American household penetration. Luigi Lavazza S.p.A. and Illycaffe S.p.A. represent Italian heritage positioning within premium aluminum capsule segments. The J. M. Smucker Company and Starbucks Corporation sit within the licensed brand extension tier, leveraging consumer recognition from adjacent coffee categories. JAB Holding Company anchors private portfolio consolidation activity across European roasting assets.
| Leading Market Players |
|---|
| Luigi Lavazza S.p.A. |
| The J. M. Smucker Company |
| Nestle Nespresso S.A |
| Jacobs Douwe Egberts |
| JAB Holding Company |
| Starbucks Corporation |
| The Kraft Heinz Company |
| Illycaffe S.p.A. |
| Keurig Dr Pepper Inc. |
| Others |
Supply Flow & Price Mechanics
Biodegradable material transitions in capsule construction are compressing cost economics while concentrating supply qualification among compounders with EFSA notification capacity. German packaging law compliance and REACH framework adherence now determine supplier eligibility, filtering procurement relationships toward vertically integrated producers with in-house polymer science capabilities.
Pricing Analysis
Short lead-time premiums attach to biodegradable capsule lines facing 18-24 month EFSA food-contact notification pathways. Three-tier pricing structure across premium aluminum, transitional composite, and economy plastic tiers reflects certification grade and barrier performance differentiation. Cost compression in plastic formats intensifies as REACH SVHC restrictions accelerate material substitution timelines. Office procurement departments exhibit lowest price sensitivity due to amenity-driven contract structures, while household subscription buyers demonstrate higher elasticity to promotional velocity.
Supply Chain Analysis
Aluminum ingot supply rests on energy-intensive smelter operations concentrated in China, Russia, and the Auvergne-Rhône-Alpes region of France. Polylactic acid feedstock draws from corn starch processors in the US Midwest and Brazilian agricultural corridors, while lignin barrier compounds source from Scandinavian pulp mill byproduct streams. Single-source vulnerability concentrates in Swiss and Italian polymer science talent clusters for compostable barrier engineering. Distribution runs through Eindhoven logistics corridors for Benelux fulfillment and Hamburg industrial composting hubs for biodegradable product validation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's packaging waste directives function as a cost-of-compliance moat, elevating barrier-to-entry economics for biodegradable certification holders while compressing margins for legacy plastic-dependent producers.
For Market Incumbents: To counter interoperability patent expiration threats and emerging compostable specialists, anchor market position through backward integration into polylactic acid compounder networks and capacity expansion in Hamburg-certified production lines. Prioritize regulatory affairs capacity for EN 13432 and ASTM D6400 certification pipeline management. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription platforms targeting Scandinavian household variety-seeking segments with home-compostable pilot lines. Exploit certification bottlenecks constraining incumbent product refresh cycles by securing expedited laboratory testing relationships in German industrial composting clusters. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified food-and-beverage conglomerates seeking biodegradable material capabilities and EFSA notification expertise. Long-term viability favors targets with captive polymer science talent and closed-loop collection infrastructure under extended producer responsibility schemes. Watch EN 13432 certification backlog clearance rates as inflection indicator for supply expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Material Transition | REACH SVHC compliance and EU Green Deal alignment secure European market access against regulatory exclusion. |
| Subscription Platform Launch | Direct-to-consumer auto-ship bypasses retail slotting fees and captures lifetime value through consumption data. |
| Certification Capacity Expansion | EN 13432 and ASTM D6400 testing relationships compress 8-14 month product launch timelines versus competitor delays. |
| Office Channel Digitization | IoT-enabled brewer deployment in Frankfurt and London financial districts enables predictive restocking contracts. |
| Backward Integration into Compounding | In-house polylactic acid formulation secures supply qualification and buffers against raw material price volatility. |
Methodological Framework
Trade association filings, customs records, and EFSA food-contact notification databases formed the secondary backbone for supply chain mapping and regulatory timeline assessment. Primary interviews with sustainability officers at roasting conglomerates, procurement leads at facility management outsourcing firms, polymer science directors at barrier material compounders, and category buyers at German supermarket chains validated material substitution assumptions and pricing elasticity estimates. Bottom-up capsule volume modeling triangulated against top-down coffee consumption trend analysis.
Historical trendline analysis across single-serve, variety pack, and bulk pack formats established baseline consumption patterns before projecting material mix shifts. Segmentation modeling incorporated product type, material composition, distribution channel, and customer archetype dimensions across the projection horizon. CAGR derivation weighted regulatory compliance timelines, certification capacity constraints, and office channel digitization adoption curves against household subscription penetration trajectories in Benelux and Scandinavian markets.
Aluminum price volatility, composting infrastructure deployment delays, and REACH SVHC list expansion are the dominant revision risks to volume and value forecasts. Forecasts reflect assumptions regarding EFSA notification pathway durations and municipal industrial composting facility buildout rates. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Vietnam Coffee Market
Coffee
South America Coffee Market
Coffee
Roast to Order Coffee Market
Coffee
Coffee Grinder Market
Coffee
Take Out Coffee Market
Coffee
Oceania Coffee Market
Coffee
Bioactive Proteins in Coffee Market
Coffee
United States Ready-To-Drink (RTD) Coffee Market
Coffee
Cold Brew Coffee Market
Coffee
Australia Coffee and Tea Capsules Market
Coffee
Coffee Bottle Market
Coffee
Ready to Drink (RTD) Coffee Market
Coffee
Green Coffee Market
Coffee
Canned Coffee Market
Coffee
Espresso Powder Market
Coffee
Decaf Coffee Market