
 Asia Pacific Fish Sauce Market | 2026-2036
Asia Pacific Fish Sauce Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Fish Sauce Market Insights
The gap between artisanal premium fish sauce and mass-market commodity production is realigning procurement strategies across Southeast Asia. Masan Group leverages its integrated supply chain from central Vietnam anchovy fisheries to dominate retail shelf space. Pantainorasingh Manufacturer Co., Ltd. differentiates through small-batch fermentation expertise that commands price premiums in Thai urban markets. Rungroj Fish Sauce Co., Ltd. anchors its position in traditional channels while navigating export certification requirements for North American and European buyers.
Asia Pacific fish sauce is a fermented condiment produced from salt-cured anchovies or mixed small pelagic fish undergoing 12–18 month enzymatic hydrolysis, yielding a liquid seasoning with 20–30% protein content and characteristic glutamate-driven umami intensity. The product serves as a foundational flavor base in Southeast Asian cuisines, industrial food processing, and emerging Western fusion applications. Traditional and premium product types command disproportionate margin pools due to aging premiums and regional provenance branding, while low-sodium variants capture health-conscious households and regulated foodservice segments in Singapore and South Korea. Supermarkets and wholesale distribution channels sustain volume throughput, though online retail is accelerating fastest among diaspora consumers in Australia and North America seeking authentic imported labels.
Vietnam's Ministry of Health sodium-labeling mandates and Thailand's FDA fermentation safety standards shape formulation requirements and export documentation burdens across the production base. BIS certification requirements in India and FSSAI import rules constrain market access for unbranded bulk shipments into South Asian markets. Stakeholders must monitor evolving ASEAN harmonization talks on fermented food standards and decide whether to invest in dedicated low-sodium production lines or rely on blended reformulations.
Market Dynamics
Sodium-labeling mandates from Vietnam's Ministry of Health are forcing reformulation across the entire Asia Pacific fish sauce production base, compressing margins for traditional high-sodium recipes while opening certified low-sodium segments to first movers.
Growth Catalysts
- Thai FDA fermentation safety standards:Standardized documentation accelerates export clearance for Vietnamese and Thai producers entering North American and European retail channels.
- Restaurant chain procurement:Southeast Asian quick-service and full-service chains are consolidating suppliers around traceable, premium-grade anchovy sources for menu consistency.
- Enzymatic hydrolysis monitoring:Real-time pH and protein-degradation sensors are reducing spoilage rates in central Vietnam's aging warehouses.
Market Restraints
- Anchovy supply volatility:El Niño-driven catch fluctuations in the Gulf of Thailand and South China Sea concentrate input cost risk among small-batch producers lacking multi-year supply contracts.
- Sodium-content technical floor:Fermentation biochemistry imposes minimum salt thresholds for shelf-stable hydrolysis, limiting how far reformulation can comply with health mandates without process overhaul.
- Soy sauce substitution:Industrial food manufacturers in South Korea and Japan are blending cheaper hydrolyzed vegetable proteins into formulations historically dependent on fish sauce base notes.
Strategic Opportunities
- Australian diaspora e-commerce:Direct-to-consumer platforms serving Vietnamese and Thai immigrant populations bypass traditional import-distributor markups for authentic aged labels.
- Singapore foodservice low-sodium mandate:Health Promotion Board procurement guidelines for hawker centers and institutional catering create certified-supplier preference for reformulated products.
- Umami extract convergence:Collaboration between fermentation scientists and flavor houses is yielding concentrated fish-derived glutamate isolates for Western savory snack applications.
Industry Challenges
- 12-to-18-month inventory financing:Traditional aging cycles tie up working capital in salt-cured anchovy stockpiles, straining balance sheets when input costs spike.
- Halal and kosher certification timelines:Separate production line requirements for religious compliance extend facility audit cycles and limit contract manufacturing flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Fish Sauce Market |
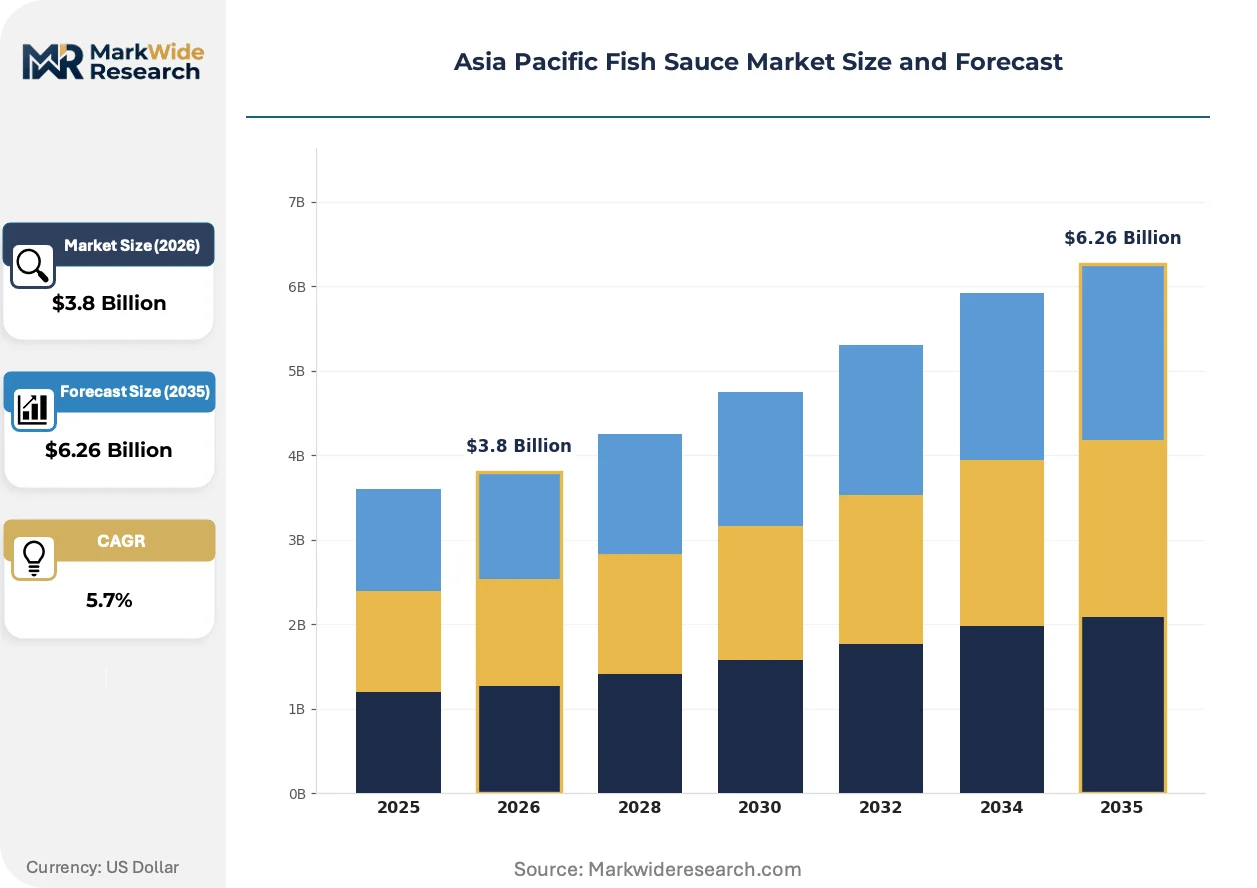
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional, Premium, Low-sodium, Organic End User: Household, Restaurants, Food Processing, Hospitality Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Wholesale Packaging Type: Bottles, Pouches, Tetra Packs, Bulk Containers |
| Companies Covered | Masan Group, Thai Fishsauce Factory (Squid Brand) Co., Ltd., Rayong Fish Sauce Industry Co., Ltd., Pantainorasingh Manufacturer Co., Ltd., Pichai Fish-Sauce Co., Ltd., Rungroj Fish Sauce Co., Ltd., PHETDAMFOODS CO., LTD., Hung Thanh Co., Ltd., Marine Resources Development Co., Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Fish Sauce Market Trends and Innovations
Digital quality control and regulatory compliance automation are compressing the gap between artisanal aging credibility and industrial scale, reshaping how authenticity is verified and priced across export and domestic channels.
Computer-vision systems trained on colorimetric fermentation progression are automating batch-release decisions that previously required master tasters. Thai and Vietnamese mid-scale producers deploying these systems reduce labor dependency in aging warehouses. The technology is automating quality consistency checks that once bottlenecked export certification timelines.
Vietnam's Ministry of Health sodium-labeling rules now require front-of-package disclosure for fermented condiments exceeding threshold limits. Manufacturers face reformulation costs or segmented production lines to serve health-regulated versus traditional markets. Singaporean and South Korean importers are screening suppliers against these disclosure standards, redirecting procurement toward pre-certified Vietnamese facilities.
Diaspora consumers in Australia and North America are bypassing ethnic grocery intermediaries through direct-import subscription models. These buyers prioritize provenance documentation and aging duration claims over price, consolidating demand around heritage-branded labels with traceable central Vietnam or coastal Thailand origin. The channel shift is most visible in Melbourne and Sydney, where Vietnamese-Australian population concentration supports dedicated cold-chain logistics for unpasteurized premium grades.
Asia Pacific Fish Sauce Market Segmentation
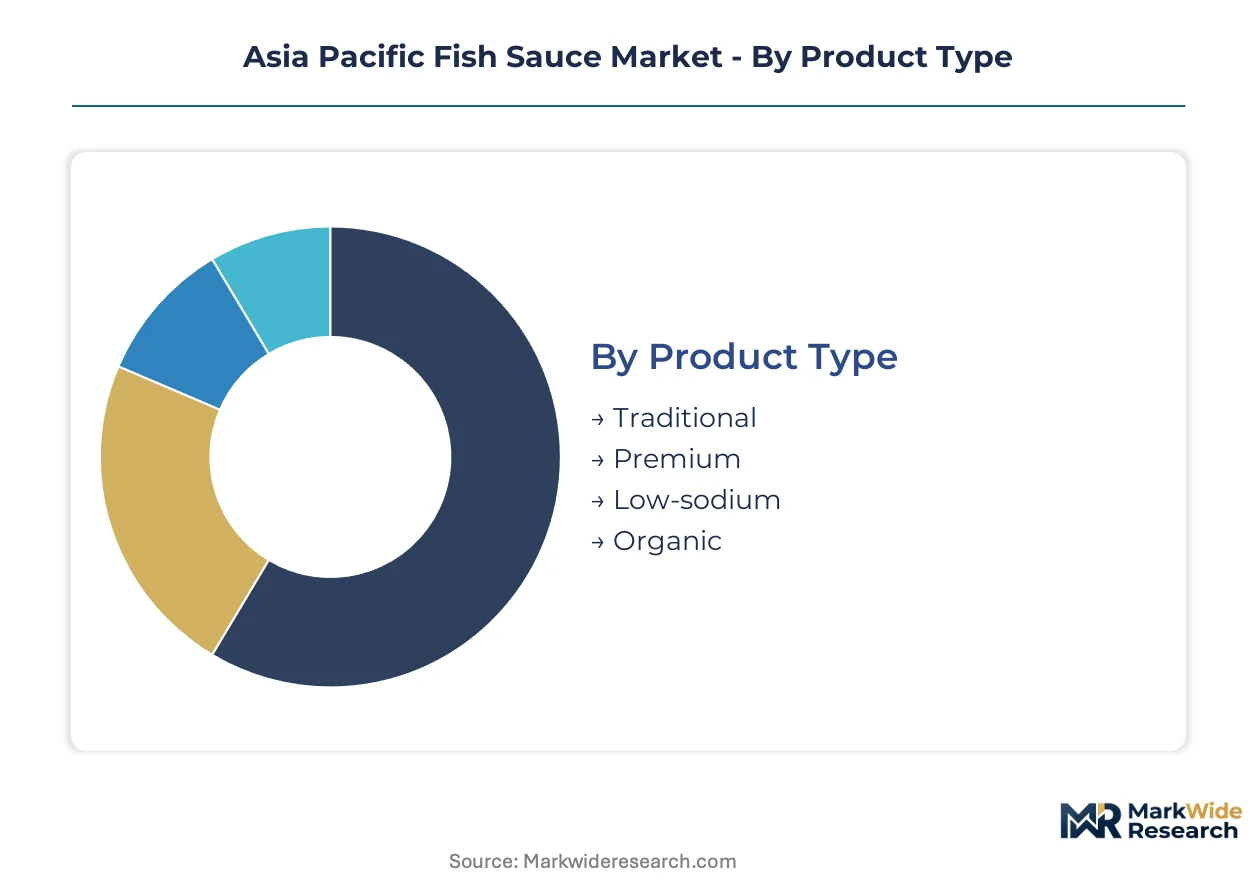
Fish sauce segmentation in Asia Pacific reflects divergent production economics across aging cycles, sodium compliance thresholds, and channel-specific packaging requirements. Procurement managers in Thailand and Vietnam now segment suppliers by fermentation documentation capability and export certification status rather than price alone.
Product Type:
Supply concentration in Vietnam's central plains and Thailand's coastal provinces directly shapes which product tiers achieve scale economies versus artisanal scarcity premiums.
- Traditional:12–18 month salt-cured anchovy fermentation yields 20–30% protein content with no additive intervention. Central Vietnam's Phu Quoc and Phan Thiet aging houses supply bulk of authenticated heritage volume to Vietnamese domestic retail and Thai premium channels.
- Premium:Extended aging beyond 18 months commands price multiples through glutamate concentration and regional provenance branding. Melbourne and Sydney diaspora markets absorb highest per-liter prices for documented single-origin batches.
- Low-sodium:Reformulated variants meeting Vietnam Ministry of Health front-of-package disclosure thresholds require segmented production lines. Singapore Health Promotion Board procurement guidelines favor certified suppliers.
- Organic:Wild-caught anchovy sourcing with certified salt inputs targets Australian and North American export channels. Audit documentation extends facility certification timelines.
Traditional absorbs the bulk of installed capacity; Low-sodium is expanding most quickly.
End User:
Cost tier differentiation separates commodity volume purchasers from traceability-driven premium buyers across institutional and retail channels.
- Household:Price-sensitive daily consumption in Vietnam and Thailand sustains mass-market bottle formats. Supermarket private labels capture volume through central plains manufacturing economies.
- Restaurants:Southeast Asian quick-service and full-service chains consolidate procurement around traceable anchovy sources for menu consistency. Bangkok and Ho Chi Minh City chain expansion drives premium-grade contract growth.
- Food Processing:Industrial manufacturers in South Korea and Japan blend fish sauce base notes with hydrolyzed vegetable proteins for cost reduction. Bulk container procurement emphasizes protein content standardization.
- Hospitality:Hotel and cruise line foodservice in Singapore and Australia specifies halal-certified and low-sodium variants for diverse guest requirements. Separate production line audits constrain supplier flexibility.
Restaurants absorb the bulk of premium volume; Food Processing is climbing the fastest as industrial formulation demand shifts.
Distribution Channel:
Volume throughput concentrates in legacy wholesale networks while margin capture shifts toward direct-to-consumer digital platforms.
- Supermarkets:Masan Group and Pantainorasingh dominate retail shelf space through integrated supply chain control. Modern trade expansion in Vietnamese urban centers sustains case-volume throughput.
- Online Retail:Diaspora consumers in Australia bypass ethnic grocery markups through direct-import subscription models. Cold-chain logistics for unpasteurized premium grades now serve Melbourne and Sydney Vietnamese-Australian concentrations.
- Specialty Stores:Heritage-branded labels with documented provenance target gift and connoisseur segments in Bangkok and Singapore. Aging duration claims command price premiums over mass-market alternatives.
- Wholesale:Traditional distribution to independent restaurants and wet markets remains volume anchor in Vietnam and rural Thailand. Working capital intensity of 12–18 month inventory cycles favors larger distributors.
Wholesale retains the bulk of volume throughput; Online Retail is gaining share fastest among premium-tier transactions.
Packaging Type:
Customer type and application requirements dictate format selection across retail convenience, foodservice efficiency, and industrial scale.
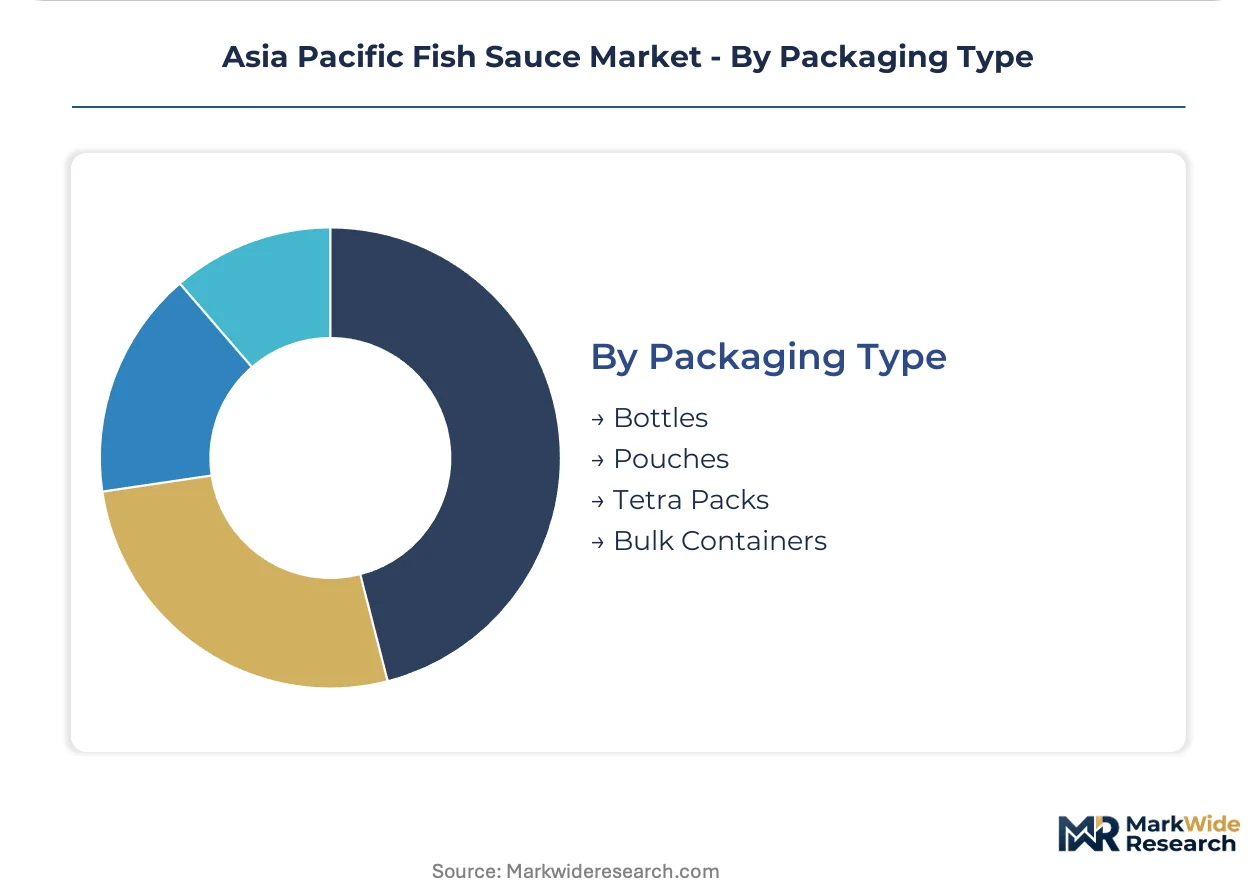
- Bottles:Glass and PET formats dominate household retail with brand visibility and resealability. Vietnamese and Thai supermarkets standardize 500ml–1L SKUs for daily consumption.
- Pouches:Flexible packaging reduces freight cost for export shipments and rural distribution. South Asian markets favor lower unit economics for price-sensitive consumers.
- Tetra Packs:Aseptic formats extend shelf life for premium variants targeting Australian and North American diaspora channels. Cold-chain requirements limit adoption to established logistics networks.
- Bulk Containers:Food processing and hospitality procurement relies on 20-liter pails and drums for manufacturing input. Protein content consistency and batch traceability drive supplier selection.
Bottles command the bulk of unit volume; Tetra Packs show steepest expansion trajectory in export premium segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Phu Quoc Island and Phan Thiet anchor Vietnam's premium fish sauce production, with coastal aging houses supplying authenticated heritage volumes to domestic retail and Thai premium channels across the Asia Pacific region.
Vietnam
Central plains manufacturing clusters in Binh Thuan and Kien Giang provinces drive bulk fermentation capacity for mass-market export. The Ministry of Health's sodium-labeling mandates force reformulation investments among coastal producers. Phu Quoc's protected geographical indication status commands price premiums in Melbourne and Sydney diaspora markets.
Thailand
Bangkok-based restaurant chains consolidate procurement around traceable anchovy sources from Samut Sakhon coastal fisheries. Thai FDA fermentation safety standards accelerate export clearance documentation for North American retail entry. Rayong and Chonburi provinces host integrated processing facilities serving quick-service chain expansion.
Singapore
Health Promotion Board procurement guidelines for hawker centers create certified-supplier preference for low-sodium reformulated products. Port logistics infrastructure enables transshipment of Vietnamese bulk containers to Australian and North American destinations. Institutional catering contracts specify halal-certified variants from audited Thai facilities.
South Korea
Industrial food manufacturers blend fish sauce base notes with hydrolyzed vegetable proteins for cost-reduced formulations. MFDS import screening redirects procurement toward Vietnamese facilities with pre-certified sodium disclosure compliance. Seoul-based flavor houses collaborate on concentrated glutamate isolates for savory snack applications.
Australia
Melbourne and Sydney Vietnamese-Australian population concentrations support dedicated cold-chain logistics for unpasteurized premium grades. Direct-import subscription models bypass traditional ethnic grocery markups for authentic aged labels. Tetra Pack aseptic formats gain traction among diaspora consumers prioritizing provenance documentation.
Asia Pacific Fish Sauce Market Competitive Landscape
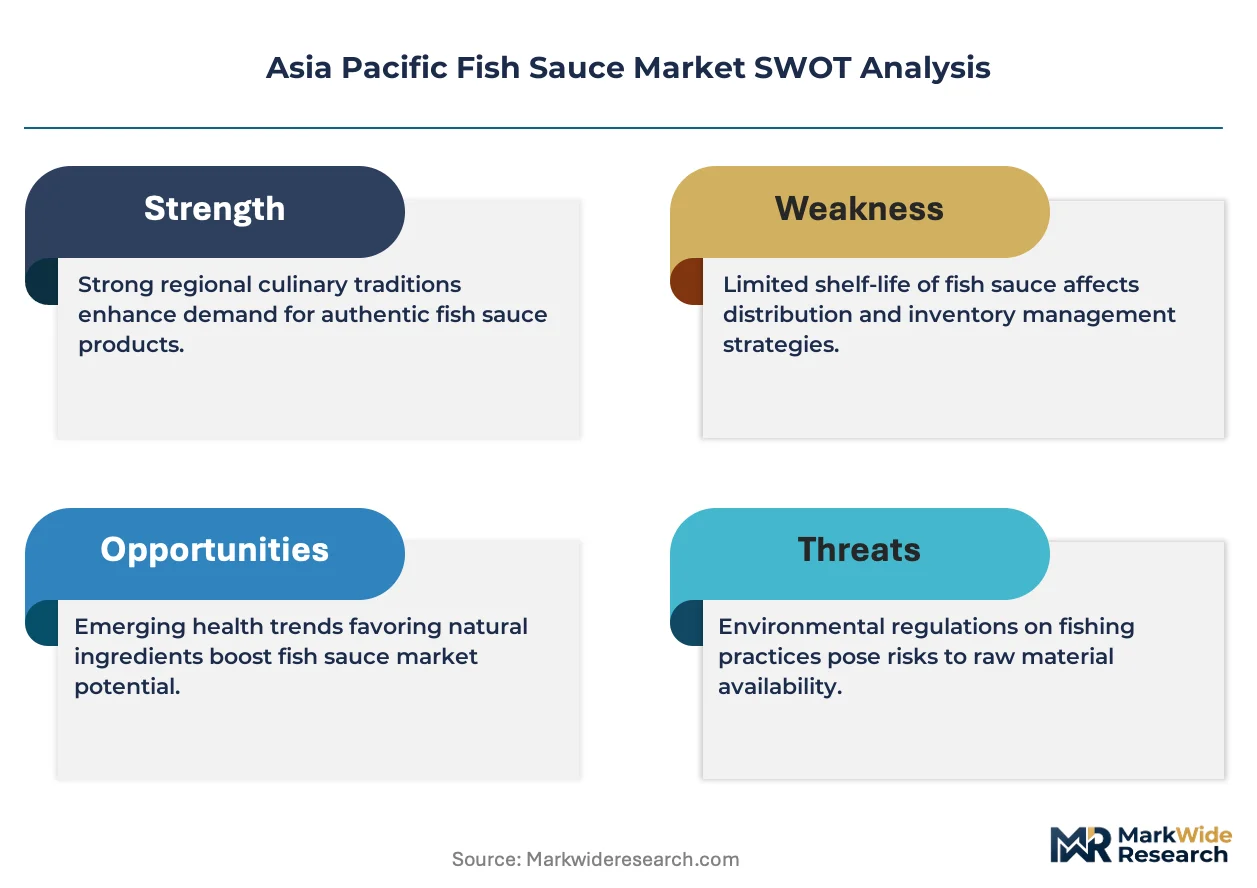
Capital-heavy producers compete with asset-light designers across the Asia Pacific fish sauce market, with integrated supply chain operators controlling retail shelf space against specialized aging houses commanding scarcity premiums. The vendor base separates into three strategic archetypes: conglomerate-backed mass-market suppliers, family-operated heritage fermenters, and export-certified contract manufacturers. Capacity expansion and certification-driven geographic diversification represent the dominant competitive moves as sodium-labeling mandates reshape formulation requirements.
Among Vietnamese integrated producers, Masan Group exemplifies conglomerate-scale supply chain control from central anchovy fisheries through retail distribution. Thai heritage specialists Pantainorasingh Manufacturer Co., Ltd. and Rungroj Fish Sauce Co., Ltd. occupy positions within the small-batch fermentation tier, anchoring premium pricing through documented aging duration and regional provenance claims. These three entities represent distinct competitive archetypes: vertical integration, artisanal scarcity, and traditional channel anchoring respectively.
| Leading Market Players |
|---|
| Masan Group |
| Thai Fishsauce Factory (Squid Brand) Co., Ltd. |
| Rayong Fish Sauce Industry Co., Ltd. |
| Pantainorasingh Manufacturer Co., Ltd. |
| Pichai Fish-Sauce Co., Ltd. |
| Rungroj Fish Sauce Co., Ltd. |
| PHETDAMFOODS CO., LTD. |
| Hung Thanh Co., Ltd. |
| Marine Resources Development Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Computer-vision fermentation monitoring is compressing quality-control labor costs while concentrating production scale among Vietnamese and Thai facilities that can amortize sensor deployment across larger batch volumes. This technology shift simultaneously reduces per-unit aging overhead and widens the gap between capitalized producers and small-batch heritage houses that rely on master tasters.
Pricing Analysis
Aging duration serves as the value-based pricing anchor, with 18-month-plus batches commanding multiples over standard 12-month lines. Three-tier pricing structure across premium, standard, and economy levels separates documented single-origin heritage labels from blended commodity grades and private-label supermarket tiers. Cost compression in the standard tier is intensifying because of sodium-reformulation investments and segmented production line requirements. Household consumers in Vietnam and Thailand show highest price sensitivity, while Australian diaspora buyers prioritize provenance documentation over unit cost.
Supply Chain Analysis
Anchovy supply rests on Gulf of Thailand and South China Sea fisheries concentrated across Vietnam, Thailand, and southern China coastal zones. Salt-cured fish inputs, wooden barrel aging infrastructure, and halal-certified production line capacity constitute critical dependencies. Single-source vulnerability runs through El Niño-driven catch fluctuations that lack multi-year contract hedging among small-batch producers. Distribution runs through wholesale networks anchored in Ho Chi Minh City and Bangkok wet markets, with cold-chain logistics emerging for Australian export channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital quality-control automation is displacing legacy master-taster verification, creating a technology-transition window where capital investment separates scalable producers from artisanal competitors.
For Market Incumbents: Acquire cold-chain logistics capability to capture Australian diaspora direct-import demand before subscription platforms consolidate buyer relationships. Defend against hydrolyzed vegetable protein substitution in South Korean and Japanese industrial formulations by locking multi-year anchovy supply contracts through backward integration into central Vietnam fisheries. For New Entrants and Emerging Players: Australian Vietnamese-Australian households represent an underserved buyer archetype seeking unpasteurized premium grades with documented Phu Quoc or Phan Thiet provenance. White-space targets include halal-certified low-sodium variants for Singapore institutional catering and concentrated umami extracts for Western savory snack flavor houses. A direct-to-consumer subscription go-to-market angle bypasses ethnic grocery intermediary markups. For Investors and Strategic Acquirers: Exit pathways concentrate in conglomerate acquisition of heritage brands for premium portfolio expansion and private-equity rollup of mid-scale Vietnamese facilities with pre-certified export documentation. Long-term viability favors producers with integrated supply chain control from anchovy fisheries through retail shelf space. Watch for ASEAN harmonization talks on fermented food standards as an inflection signal for reformulation investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Anchovy Fisheries | Masan Group's captive supply from central Vietnam reduces input cost volatility and secures traceability documentation for export certification. |
| Low-Sodium Production Line Segmentation | Dedicated facilities serving Singapore Health Promotion Board procurement guidelines capture institutional catering contract preference. |
| Direct-to-Consumer Subscription Launch | Melbourne and Sydney diaspora platforms bypass ethnic grocery markups while cold-chain logistics justify premium pricing. |
| Halal Certification Investment | Separate audited production lines unlock Singapore hotel and cruise line foodservice contracts with diverse guest requirements. |
| Umami Extract Collaboration | Partnerships with Seoul flavor houses yield concentrated glutamate isolates for Western savory snack applications beyond traditional condiment use. |
Research Methodology
Multi-period observation of fermentation batch volumes, sodium-labeling compliance rates, and export certification timelines anchored the trend analysis, supplemented by interviews with Vietnamese aging house operators, Thai FDA regulatory affairs leads, Singaporean institutional catering procurement managers, Australian ethnic grocery distributors, and South Korean industrial food formulation chemists. Secondary validation drew from Vietnam Ministry of Health disclosure filings, Thai FDA fermentation safety standards documentation, Singapore Health Promotion Board procurement guidelines, Australian customs import records, and South Korean MFDS screening protocols. Bottom-up facility capacity estimates triangulated against top-down regional consumption models.
Input-output matrices mapped anchovy catch volumes through salt-cure processing, aging cycle duration, and channel-specific packaging to project volume and value trajectories across the analysis window. Segmentation dimensions modeled include product type tier, end-user category, distribution channel format, and geographic regulatory cluster. CAGRs derived from fitted growth curves applied to baseline consumption data adjusted for diaspora population expansion and health-mandate reformulation adoption curves.
Revisions become necessary when El Niño intensity disrupts anchovy catch cycles, ASEAN harmonization talks alter certification requirements, or hydrolyzed vegetable protein substitution accelerates in Northeast Asian industrial formulations. Forecasts reflect documented assumptions regarding aging cycle duration stability and cold-chain logistics cost curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
Vegan Sauces, Dressings and Spreads Market
Condiments & Sauces
Culinary Sauces Market
Condiments & Sauces
Low Salt Soy Sauce Market
Condiments & Sauces
United States Hot Sauce Market
Condiments & Sauces
Egg-Free Mayonnaise Market
Condiments & Sauces
Vegan Cheese Sauce Market
Condiments & Sauces
Barbeque Sauce Market
Condiments & Sauces
Cocktail Syrups Market
Condiments & Sauces
Soy-Based Sauce Market
Condiments & Sauces
Fat Free Salad Dressings Market
Condiments & Sauces
Prepared Mustard Market
Condiments & Sauces
Europe Pasta Sauce Market
Condiments & Sauces
Vegan Fish Sauce Market
Condiments & Sauces
Asia-Pacific Condiments Market
Condiments & Sauces
United States Pasta Sauce Market
Condiments & Sauces
Chocolate Syrup Market