
 North America Ready-To-Drink (RTD) Coffee Market | 2026-2036
North America Ready-To-Drink (RTD) Coffee Market Size, Share, and Industry Trends Forecast 2026-2036
North America Ready-To-Drink (RTD) Coffee Market Analytics
Market Context
Fragmentation across convenience and foodservice buyers is repositioning procurement leverage toward regional distributor networks. Starbucks Coffee Company leverages its captive retail footprint to control chilled case placement in airports and transit hubs. Nestle S.A. sustains manufacturing scale through co-packing agreements with domestic bottling partners across the Midwest and Southeast.
Technical Definition and Segment Structure
Ready-to-drink coffee comprises brewed coffee extracts, concentrates, or cold-brewed formulations preserved through pasteurization, aseptic filling, or refrigeration, delivered in shelf-stable or chilled formats for immediate consumption without preparation equipment. Cold Brew leads product type value pools due to extended brew-cycle complexity and premium positioning, while Cans dominate packaging type volume through recycling infrastructure compatibility and single-serve portability. E-commerce represents the fastest-growing distribution channel as direct-to-subscription models reduce intermediary markups for recurring pantry replenishment.
Regulatory Frame and Outlook
The FDA governs ingredient disclosure and caffeine content labeling, while state-level regulators in California enforce Proposition 65 warnings for acrylamide exposure in roasted coffee products. USDA Organic certification and Non-GMO Project verification increasingly determine shelf access at natural channel retailers such as Whole Foods and Sprouts. Stakeholders must monitor evolving sugar tax legislation across municipal jurisdictions and adapt formulation portfolios accordingly.
Market Dynamics
Chilled single-serve format expansion across convenience retail is compressing shelf space competition and forcing formulation transparency upgrades ahead of pending state sugar tax legislation.
Growth Catalysts
- California Proposition 65 enforcement:Acrylamide warning requirements are accelerating clean-label roasting process investments and pushing brands toward cold-brew extraction methods that reduce compound formation.
- Metropolitan commuter corridors:Morning traffic density across Texas, Florida, and New York transit hubs sustains grab-and-go velocity for aluminum can formats at premium price points.
- Cold-brew extraction complexity:Extended steep-cycle production creates defendable margin pools through perceived craft authenticity and justifies refrigerated supply chain investments.
Market Restraints
- Arabica futures volatility:Weather-driven harvest uncertainty in Colombian and Brazilian growing regions transmits directly to concentrate input costs with limited hedging visibility beyond six-month windows.
- Midwest co-packing concentration:Nestle's reliance on domestic bottling partnerships across Ohio and Georgia creates single-source vulnerability for aseptic filling capacity during peak summer demand surges.
- Sugar tax legislative friction:Pending municipal discussions in Chicago and Los Angeles impose formulation recalculation costs and force dual-SKU inventory maintenance for taxed versus untaxed jurisdictions.
Strategic Opportunities
- USDA Organic certification acceleration:Natural channel retailers including Whole Foods and Sprouts are gatekeeping shelf access behind verified supply chain documentation, rewarding early compliance investments.
- Direct-to-subscription e-commerce:Recurring pantry replenishment models bypass traditional distributor markups and capture lifetime value through flavor customization portals.
- Illinois sugar tax preparation:Brands with existing low-sugar or zero-sugar portfolios can capture immediate share if Chicago implements beverage taxes before neighboring states.
Industry Challenges
- Aseptic filling technician scarcity:Specialized pasteurization equipment operation requires certified labor pools that concentrate near legacy dairy processing regions, constraining geographic expansion flexibility.
- Refrigerated last-mile integration:Cold-chain handoffs between regional distributors and convenience store coolers introduce temperature excursion risk that degrades sensory quality before consumption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Ready-To-Drink (RTD) Coffee Market |
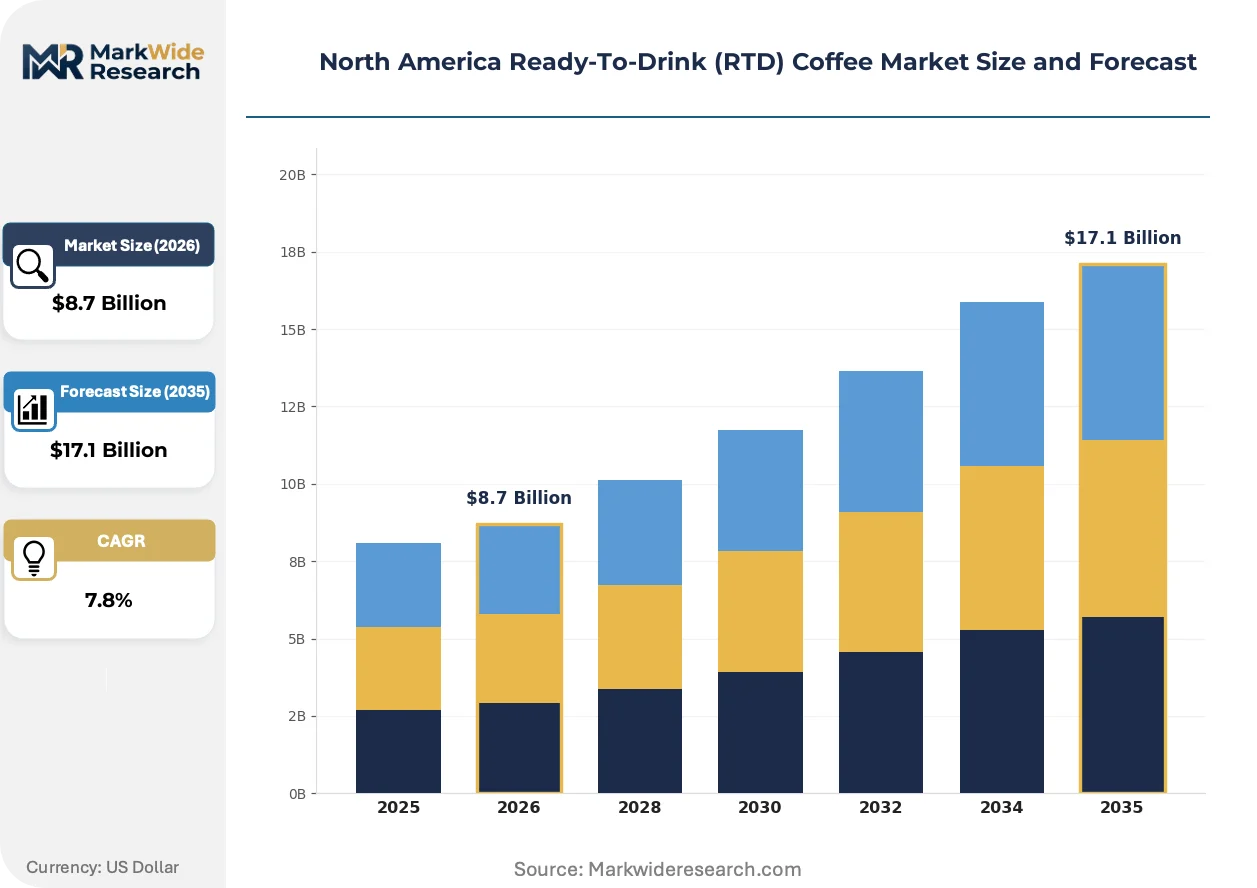
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cold Brew, Espresso, Nitro Coffee, Sweetened Beverages Packaging Type: Cans, Bottles, Tetra Packs, Pouches Flavor Profile: Vanilla, Mocha, Caramel, Dark Roast Distribution Channel: Retail Stores, E-commerce, Cafés, Vending Machines |
| Companies Covered | Keurig Dr Pepper Inc., The Coca-Cola Company, Starbucks Coffee Company, DD IP Holder LLC, Califia Farms LLC, Danone S.A., PepsiCo Inc., Nestle S.A., BRC Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Ready-To-Drink (RTD) Coffee Market Evolving Landscape
Automation across brewing and filling operations is compressing unit economics while regulatory labeling mandates and channel disintermediation reshape competitive access points.
High-pressure processing equipment is automating cold-brew pasteurization without thermal degradation. Mid-sized regional bottlers in the Southeast are adopting these systems to extend shelf life while preserving volatile aromatic compounds. This automation is compressing the cost gap between refrigerated and shelf-stable formats.
FDA updated Nutrition Facts requirements are mandating added sugar disclosure with single-serve reference quantities. Reformulation teams must recalculate entire flavor portfolios to maintain acceptable label claims. Chilled single-serve brands targeting health-conscious commuters in California and New York are responding fastest with monk fruit and allulose substitutions.
Subscription-based replenishment is displacing traditional distributor-led store delivery for pantry-stock occasions. Direct-to-consumer platforms are capturing recurring revenue from suburban households outside major metropolitan cores. This shift concentrates most visibly in Texas corridor markets where e-commerce penetration in beverage categories lags coastal benchmarks.
North America Ready-To-Drink (RTD) Coffee Market Segmentation
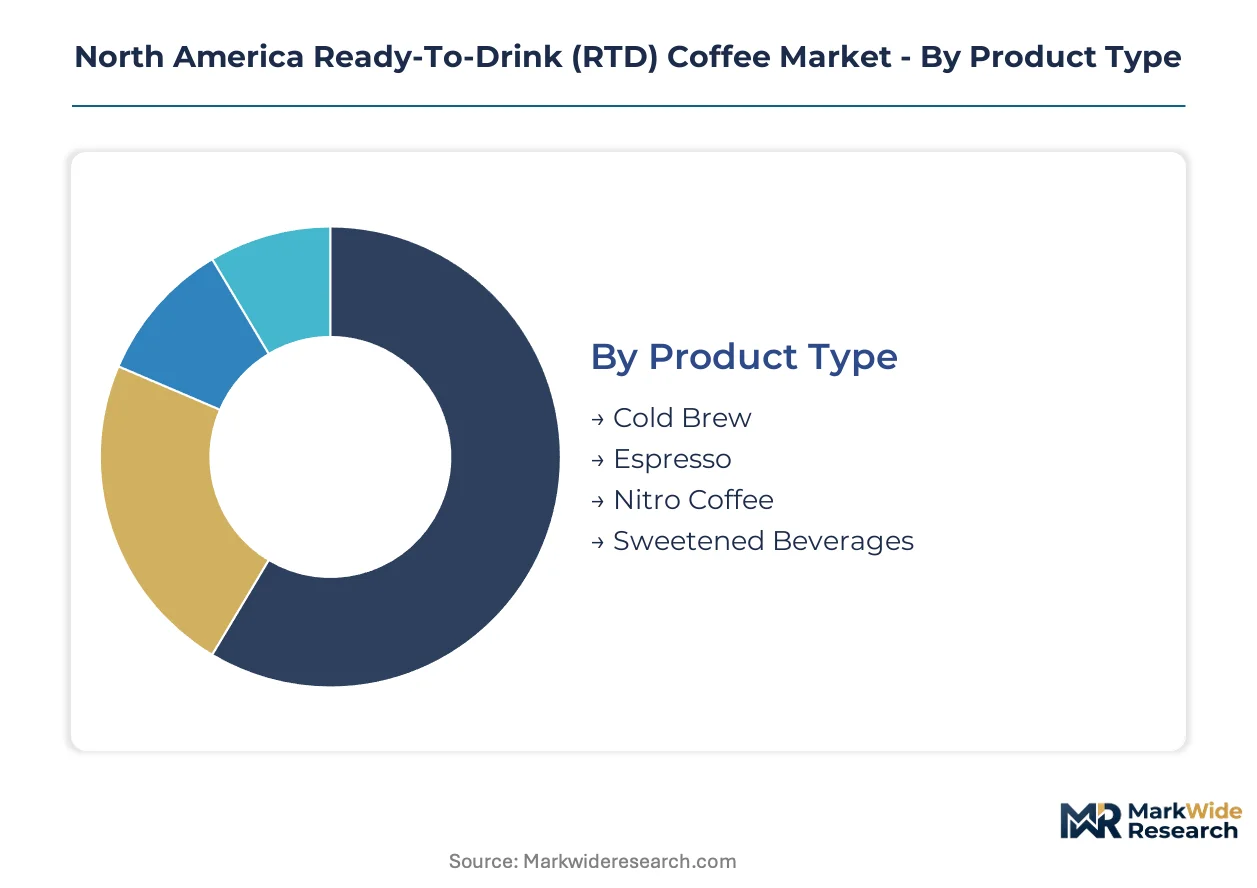
RTD coffee segmentation reveals divergent margin structures across temperature formats and channel economics. Cold-chain investments and sugar tax exposure create distinct competitive moats between segments that reshape portfolio allocation for national brands.
Product Type:
Cold Brew commands premium shelf positioning while Espresso drives mainstream volume velocity across convenience retail.
- Cold Brew:Extended 12-24 hour steep cycles extract lower-acidity compounds with higher caffeine retention. Texas and Florida commuter corridors absorb refrigerated single-serve formats at price points double conventional RTD offerings.
- Espresso:Concentrated extraction through pressurized systems delivers standardized caffeine dosing for mass-market consistency. Nestle's co-packing network across Ohio and Georgia concentrates aseptic filling capacity for this segment.
- Nitro Coffee:Nitrogen infusion creates cascading foam texture mimicking draft beer pour characteristics.
- Sweetened Beverages:Flavored latte formulations face immediate reformulation pressure from California and Illinois sugar tax proposals.
Today's leader: Cold Brew. Tomorrow's challenger: Nitro Coffee.
Packaging Type:
Recycling infrastructure compatibility and single-serve portability determine format selection across metropolitan transit hubs versus suburban pantry stock.
- Cans:Aluminum formats dominate volume through municipal recycling program acceptance and crush-resistant transit durability. Morning commuter traffic across New York corridor transit stations sustains grab-and-go velocity for 12-ounce slim designs.
- Bottles:PET and glass variants enable resealability for multi-occasion consumption patterns in office environments.
- Tetra Packs:Aseptic carton technology extends shelf-stable distribution reach beyond cold-chain constraints.
- Pouches:Flexible film formats reduce shipping cube for direct-to-subscription e-commerce fulfillment.
Current volume dominance rests with Cans. E-commerce expansion favors Pouches.
Flavor Profile:
Clean-label roasting investments and alternative sweetener adoption reshape formulation portfolios ahead of FDA added-sugar disclosure mandates.
- Vanilla:Natural extract sourcing commands price premiums against artificial vanillin alternatives at natural channel retailers.
- Mocha:Cocoa-coffee fusion attracts afternoon consumption occasions beyond traditional morning caffeine windows.
- Caramel:High added-sugar content faces immediate recalculation under pending Chicago and Los Angeles beverage tax frameworks.
- Dark Roast:Extended roasting cycles elevate acrylamide formation risk subject to California Proposition 65 warning requirements.
Mainstay preference: Dark Roast. Reformulation urgency: Caramel.
Distribution Channel:
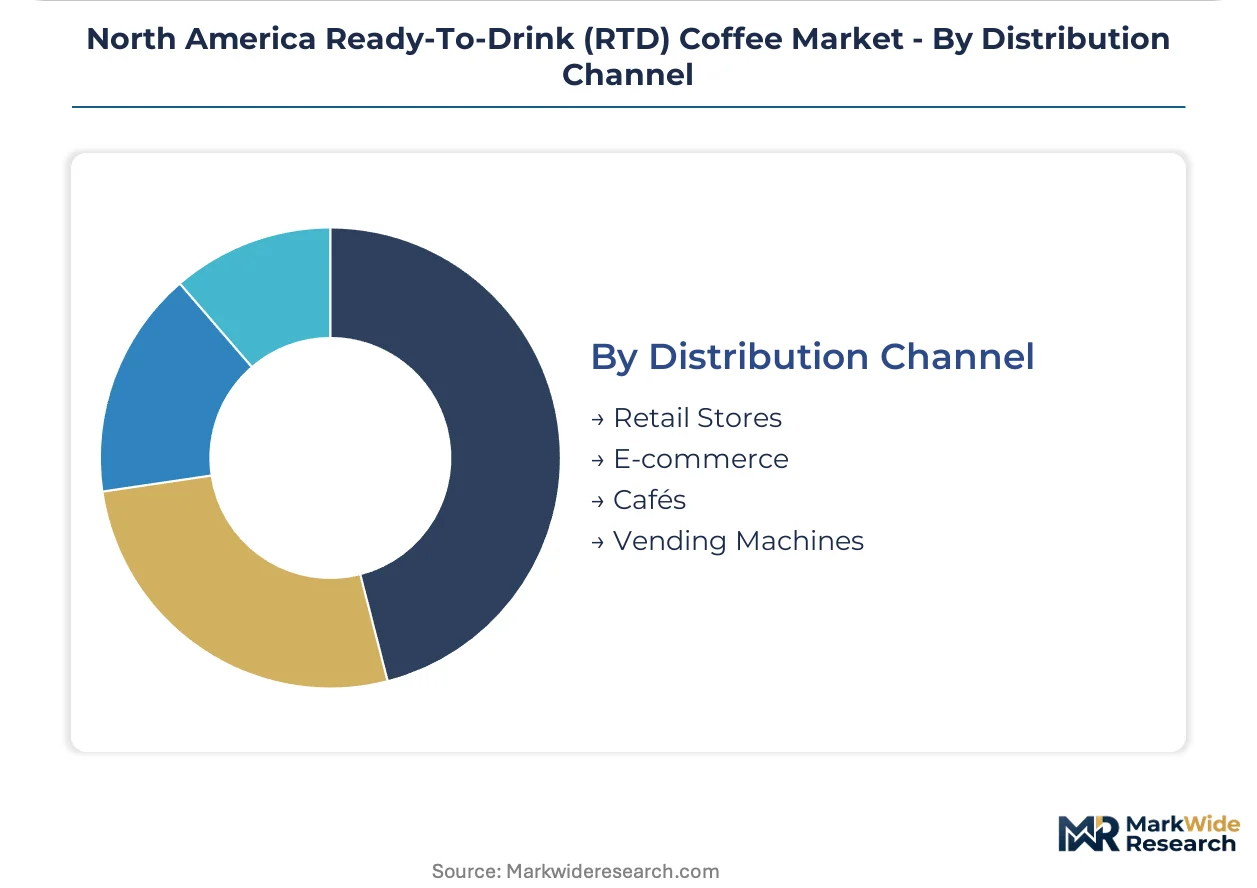
Channel disintermediation concentrates margin capture toward direct relationships while traditional retail maintains velocity scale.
- E-commerce:Subscription replenishment models bypass distributor markups through flavor customization portals. Texas suburban households outside major metropolitan cores show fastest platform adoption in this category.
- Retail Stores:Convenience chains and gas station retailers expand chilled case space for single-serve formats.
- Cafés:Captive consumption occasions enable premium pricing for on-premise brewed alternatives.
- Vending Machines:Refrigerated equipment placement concentrates in employer facilities and educational institutions.
Established infrastructure: Retail Stores. Steepest expansion trajectory: E-commerce.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's regulatory environment encourages clean-label innovation faster than Mexico's emerging retail infrastructure permits. The United States concentrates volume and premium pricing power across distinct metropolitan corridors. Each national market presents divergent channel dynamics and compliance burdens.
United States
Metropolitan commuter density across Texas, Florida, and New York sustains grab-and-go velocity for chilled single-serve formats. The FDA governs ingredient disclosure and caffeine content labeling while California enforces Proposition 65 warnings for acrylamide exposure. Cold-brew production clusters concentrate in the Pacific Northwest and Southeast where extended steep-cycle facilities access both specialty roasters and co-packing infrastructure.
Canada
Health Canada and PMRA oversight drives faster adoption of USDA Organic-equivalent certifications among natural channel retailers. Provincial beverage container deposit programs incentivize aluminum can formats over PET alternatives. Greater Toronto and Vancouver anchor distribution networks that extend refrigerated supply chains into prairie markets with limited cold-chain infrastructure.
Mexico
Rising middle-class consumption in Mexico City and Monterrey expands convenience retail shelf space for imported RTD brands. The national consumer protection agency enforces labeling standards that lag US requirements, creating formulation flexibility for multi-market SKUs. Domestic bottling partnerships in Jalisco and Nuevo León provide aseptic filling capacity for brands seeking North American manufacturing diversification.
North America Ready-To-Drink (RTD) Coffee Market Competitive Landscape
US producers anchor the premium tier through captive retail footprints and direct-to-consumer platforms; Canadian and Mexican specialists hold regional distribution advantages through local bottling relationships. The market exhibits moderate consolidation with multinational beverage conglomerates controlling mass-market shelf space while independent cold-brew specialists capture natural channel velocity. Three archetypes dominate: integrated coffee-roasting retailers, diversified beverage conglomerates with licensed coffee partnerships, and plant-based dairy alternative formulators. Capacity expansion in aseptic filling and cold-chain partnerships represent the dominant competitive moves.
Among diversified beverage conglomerates, Keurig Dr Pepper Inc. and PepsiCo Inc. occupy positions defined by distribution scale and licensed brand portfolios. Starbucks Coffee Company exemplifies the integrated retail-roasting archetype through controlled chilled case placement. Nestle S.A. represents manufacturing-scale players reliant on co-packing networks across Midwest and Southeast bottling facilities.
| Leading Market Players |
|---|
| Keurig Dr Pepper Inc. |
| The Coca-Cola Company |
| Starbucks Coffee Company |
| DD IP Holder LLC |
| Califia Farms LLC |
| Danone S.A. |
| PepsiCo Inc. |
| Nestle S.A. |
| BRC Inc. |
| Others |
Value Network & Pricing Analysis
Aseptic filling technician scarcity in the Upper Midwest and Southeast dairy processing belts widens labor-cost differentials between premium cold-brew tiers and mass-market espresso formats. Cold-chain certification premiums for refrigerated single-serve SKUs compound these spreads, forcing brands to absorb specialized workforce premiums or cede shelf space to shelf-stable alternatives.
Pricing Analysis
Capacity additions in the Pacific Northwest and Southeast are reshaping price floors for cold-brew extraction while compressing margins on conventional heat-pasteurized offerings. Three-tier pricing structure across premium organic cold-brew, standard refrigerated formats, and economy shelf-stable cans separates buyers by certification level and temperature format. Pricing pressure stems from Arabica futures volatility transmitting directly to concentrate input costs with limited hedging visibility. Mass-market convenience retail buyers exhibit highest price sensitivity, while direct-to-subscription households absorb premiums for flavor customization.
Supply Chain Analysis
Regional distribution centers in Ohio, Georgia, and Texas anchor hub-and-spoke patterns that extend refrigerated reach into metropolitan commuter corridors. Raw material flows draw from Colombian and Brazilian Arabica origins, Midwest dairy proteins for latte formulations, and Southeast nitrogen gas supplies for nitro coffee infusion. Single-source vulnerability concentrates in Nestle's co-packing partnerships across Ohio and Georgia aseptic filling facilities. Distribution runs through convenience store chains and gas station retailers expanding chilled case space for single-serve velocity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America RTD coffee market reads as a late-cycle quality story where commuter demand has shifted decisively toward low-acidity cold-brew specifications and clean-label roasting credentials.
For Market Incumbents: Deploy cold-chain partnership expansion to lock in convenience retail chilled case placement ahead of sugar tax implementation in Chicago and Los Angeles. Nestle's co-packing concentration across Ohio and Georgia creates single-source vulnerability that Starbucks and Keurig Dr Pepper can exploit through captive bottling investments. Defend margin pools by accelerating USDA Organic certification to satisfy Whole Foods and Sprouts gatekeeping requirements. For New Entrants and Emerging Players: Direct-to-subscription e-commerce platforms offer the lowest customer acquisition cost pathway for regional cold-brew specialists seeking bypass of distributor markups. Texas suburban households outside Dallas-Fort Worth and Houston metropolitan cores show fastest platform adoption velocity relative to coastal benchmarks. Target nitro coffee penetration in employer facility vending channels where draft-pour differentiation commands premium pricing. For Investors and Strategic Acquirers: Diversified beverage conglomerates are the most active acquirer in this space, seeking licensed coffee partnerships to fill portfolio gaps in morning caffeine occasions. Cold-brew specialists with Pacific Northwest or Southeast extraction facilities and verified organic supply chains present the most defensible acquisition targets. Watch for Illinois sugar tax passage as the signal indicating immediate portfolio advantage for zero-sugar formulations.| Strategic Initiative | Industry Significance |
|---|---|
| USDA Organic Certification Acceleration | Whole Foods and Sprouts gatekeeping rewards early compliance with premium shelf positioning. |
| Direct-to-Consumer Platform Launch | Subscription models bypass distributor markups and capture lifetime value through flavor portals. |
| Cold-Chain Partnership Expansion | Refrigerated last-mile integration reduces temperature excursion risk degrading sensory quality. |
| Zero-Sugar Portfolio Development | Chicago and Los Angeles sugar tax preparation creates immediate share capture opportunity. |
| High-Pressure Processing Equipment Adoption | Southeast mid-sized bottlers extend shelf life while preserving volatile aromatic compounds. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each national market combining executive interviews with brand managers, category buyers at convenience retail chains, cold-brew production facility operators, and regulatory affairs specialists with secondary validation. Secondary sources include FDA labeling guidance documents, Health Canada PMRA oversight filings, Nielsen retail audit data for beverage categories, and SEC 10-K disclosures from diversified beverage conglomerates. Bottom-up volume modeling triangulates against top-down category spend estimates.
Granularity-level framing applies product type, packaging format, flavor profile, and distribution channel dimensions at the metropolitan corridor level for the United States and provincial level for Canada. CAGRs derive from segment-level growth rate reconciliation across the projection horizon. Forecast inputs incorporate commuter traffic density indices, cold-chain infrastructure expansion timelines, and pending sugar tax legislative probability assessments.
Arabica futures volatility, state-level sugar tax passage timing, and aseptic filling capacity constraints are the dominant revision risks that could alter trajectory assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Australia Coffee and Tea Capsules Market
Coffee
Single-Serve Coffee Containers Market
Coffee
Robusta Coffee Beans Market
Coffee
China Ready-To-Drink (RTD) Coffee Market
Coffee
Global Coffee Market
Coffee
Singapore Coffee Roaster Market
Coffee
Flavored Cold-Brew Coffee Market
Coffee
Coffee and Tea Capsule Market
Coffee
Ready to Drink (RTD) Tea and Coffee Market
Coffee
Organic Coffee Market
Coffee
Asia-Pacific Espresso Coffee Market
Coffee
Japan Coffee and Tea Capsules Market
Coffee
Canned Coffee Market
Coffee
South America Coffee Market
Coffee
South Korea Coffee Roaster Market
Coffee
Coffee Bags Market