
 Espresso Coffee Market | 2026-2036
Espresso Coffee Market Size, Share, and Industry Trends Forecast 2026-2036
Espresso Coffee Market Analysis
Pod-to-bean unbundling is repositioning how households and offices acquire espresso, shifting volume from closed systems toward refillable formats and whole bean purchases. Nestle leverages its Nespresso ecosystem to sustain installed-base loyalty through proprietary pod architectures. JDE Peet's anchors European retail shelf presence with ground and whole bean portfolios. Lavazza competes across machine, capsule, and roasting segments with integrated Italian supply chains.
Espresso coffee denotes coffee brewed by forcing near-boiling water through finely ground, compacted beans at approximately nine bars of pressure, yielding a concentrated beverage with distinctive crema. The process demands precise grind calibration, roast profiling, and equipment thermal stability for consistent extraction. Pods currently command the highest margin pools due to recurring consumable revenue and brand lock-in, though whole bean segments are gaining velocity among enthusiast households seeking grind control. Supermarket distribution remains mature and price-competitive, while direct-to-online channels are expanding fastest through subscription replenishment models.
EU Ecodesign regulations and FDA food safety standards govern equipment energy efficiency and bean import sanitation protocols, respectively. The EU Deforestation Regulation tightens traceability requirements for coffee supply chains entering European ports. REACH compliance affects cleaning chemical formulations used in commercial espresso machines. Stakeholders must monitor how evolving sustainability certifications and origin disclosure mandates reshape supplier qualification criteria and consumer willingness to pay.
Market Dynamics
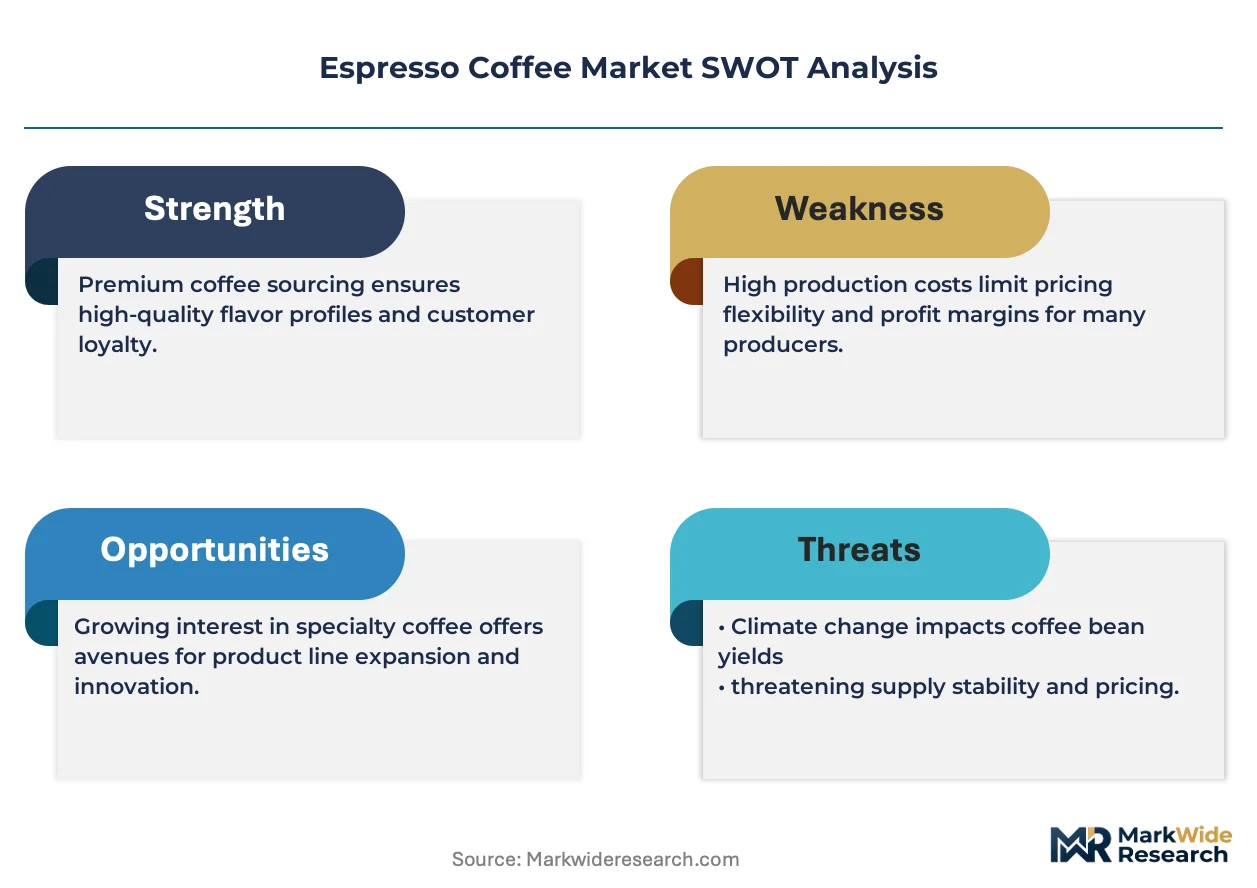
The EU Deforestation Regulation is forcing roasters to rebuild arabica supply chains with farm-level traceability, redirecting procurement spend toward certified cooperatives and away from spot-market intermediaries.
Growth Catalysts
- EU Green Deal mandates:The deforestation-free supply chain requirements are pulling investment into bean origin verification systems and satellite-tracked farm audits.
- Specialty café expansion:Independent and chain cafés in Italy, France, and Spain are broadening espresso-based menus, lifting machine throughput and consumable pull-through.
- Pressure profiling technology:Commercial equipment with programmable extraction curves is enabling baristas to replicate signature shots consistently, driving equipment replacement cycles.
Market Restraints
- Arabica price volatility:Weather shocks in Brazil and Colombia transmit directly to roaster margins, compressing working capital flexibility.
- Pod system lock-in:Proprietary capsule architectures trap households in high-cost consumable ecosystems, limiting price competition and consumer choice.
- REACH compliance burden:Cleaning chemical reformulations for commercial machines require toxicology dossiers that delay new product launches by 8-14 months.
Strategic Opportunities
- Office channel underpenetration:Workplace espresso installations in Germany and the Netherlands remain below saturation, creating whitespace for lease-to-own machine models.
- Subscription replenishment:Direct-to-online whole bean subscriptions with grind-size customization are capturing enthusiast households seeking freshness control.
- CSRD disclosure requirements:Corporate sustainability reporting mandates are creating premium positioning for roasters with verified carbon-negative supply chains.
Industry Challenges
- Barista skill scarcity:Consistent extraction across high-turnover café staff requires training infrastructure that independent operators struggle to maintain.
- Machine thermal stability capex:Dual-boiler and PID-controlled systems demand upfront investment that squeezes independent café cash flows.
- Origin certification backlog:Farm-level audits for EU Deforestation Regulation compliance are creating 6-9 month delays in supplier onboarding.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Espresso Coffee Market |
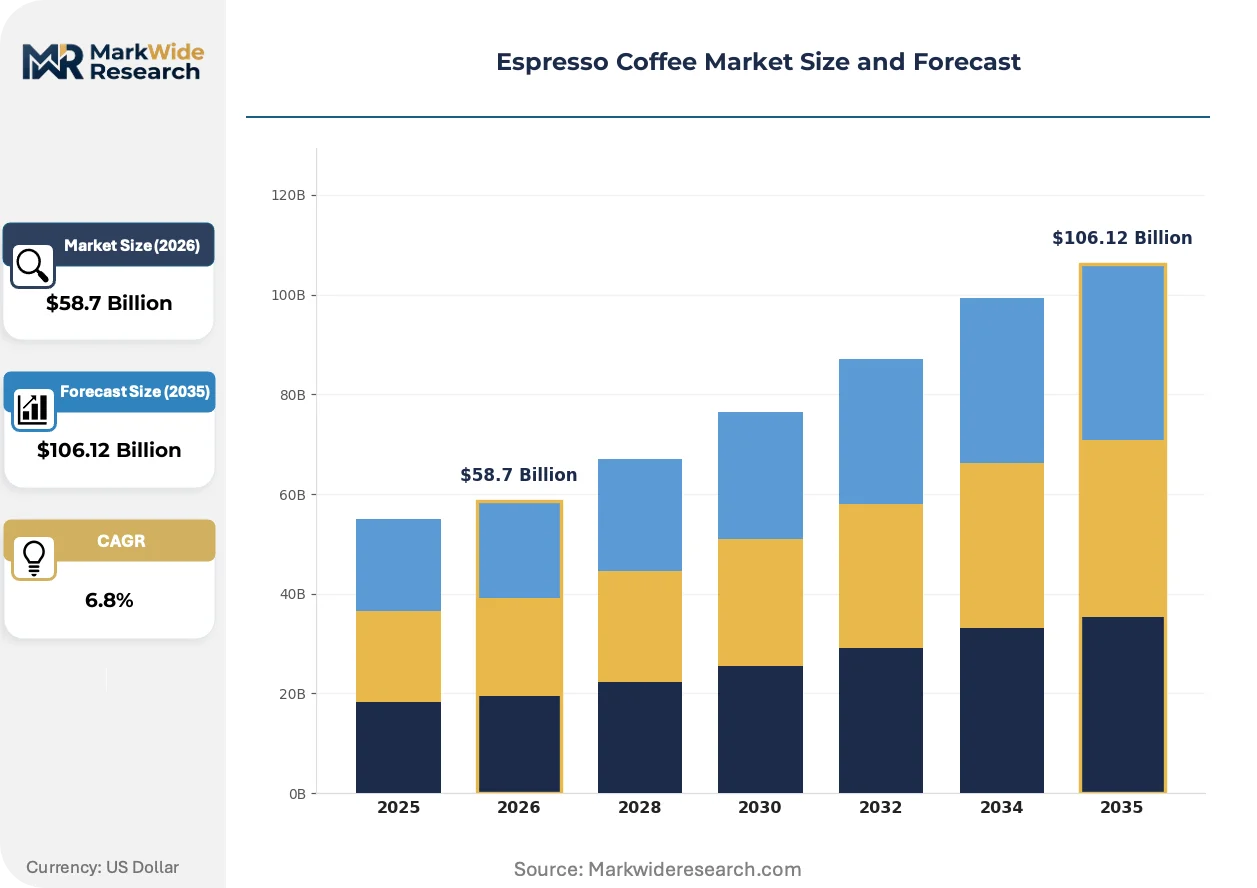
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $106.12 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Bean, Ground Coffee, Pods, Instant Coffee Brewing Method: Espresso Machine, Stovetop, French Press, Aeropress Distribution Channel: Retail Stores, Online, Coffee Shops, Supermarkets Customer Type: Households, Offices, Restaurants, Cafés |
| Companies Covered | Nestle, JDE Peet's, Starbucks, Lavazza, Illy, Kraft Heinz, Peet's Coffee, Dunkin', Tchibo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Espresso Coffee Market Emerging Trajectories
Equipment intelligence and supply chain transparency are converging to reshape how espresso is produced, sourced, and consumed across European and North American markets.
Connected machine telemetry is integrating real-time extraction data with predictive maintenance algorithms. Roaster-operated café chains in Italy and Germany are deploying these systems to reduce downtime and standardize beverage quality across locations. The technology is integrating fleet management capabilities that compress service response times from days to hours.
The EU Deforestation Regulation tightens traceability mandates for coffee entering European ports, requiring geolocation data for every farm above 4 hectares. Roasters must restructure supplier relationships to maintain market access. Italian and German importers are responding by vertically integrating into East African washing stations to secure compliant bean flows.
Enthusiast households are abandoning pod systems for whole bean purchases with grind-size specificity. This rotation is compressing supermarket pod shelf space while expanding direct-to-online subscription volumes. The shift is most visible in France and the UK, where third-wave coffee culture has penetrated suburban markets.
Espresso Coffee Market Segmentation
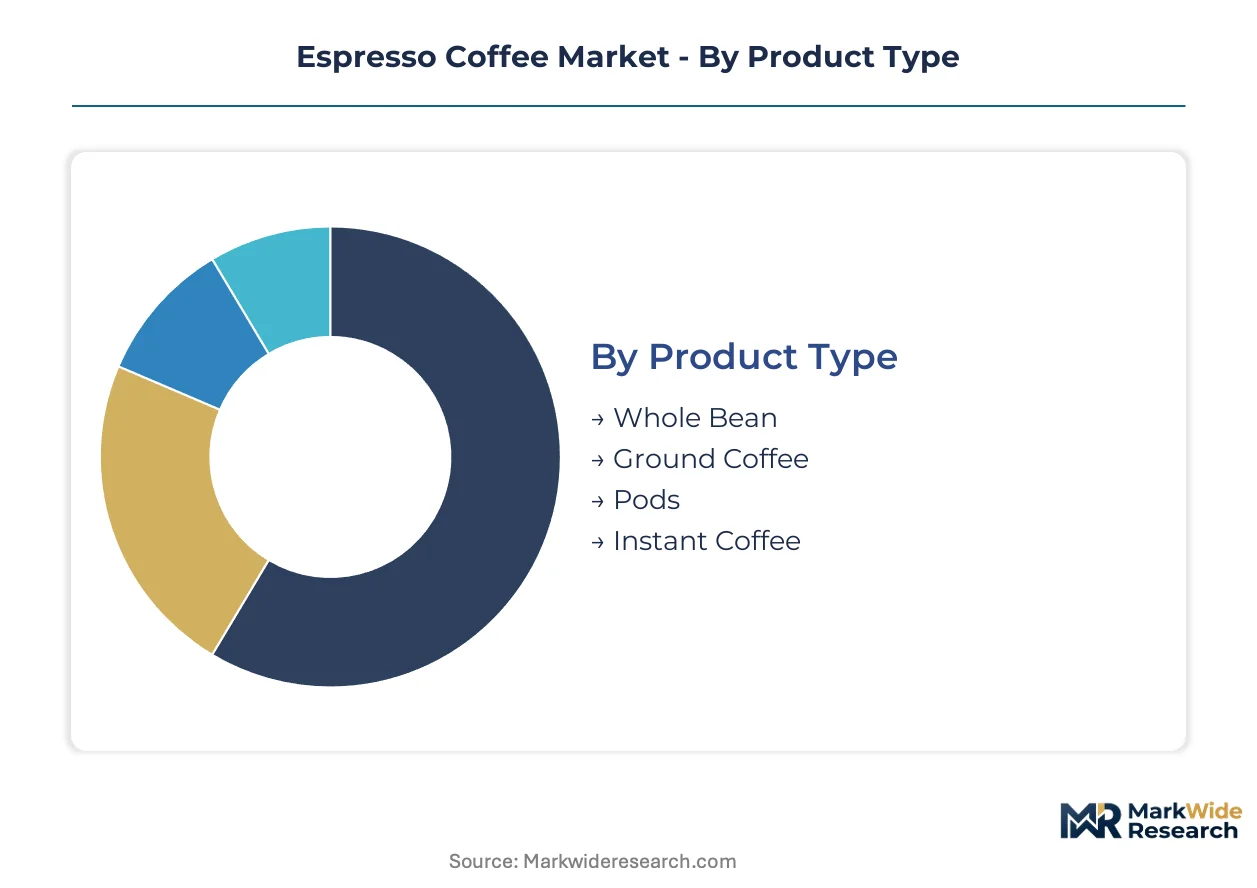
Espresso coffee segmentation reveals how supply chain configuration, equipment requirements, and channel economics fragment purchasing behavior across formats and venues. Understanding these divides exposes where margin pools concentrate and where volume growth is materializing.
Product Type:
Supply concentration in roasting infrastructure and packaging technology shapes competitive dynamics across formats.
- Whole Bean:Unprocessed roasted beans requiring grind calibration before extraction. Demand clusters in Italy and France among enthusiast households seeking origin-specific profiles and freshness control through direct-to-online subscriptions.
- Ground Coffee:Pre-milled particles packaged for immediate brewing convenience. Supermarket shelves in Germany and Spain absorb the majority of volume, driven by price-sensitive households prioritizing speed over customization.
- Pods:Single-serve aluminum or compostable capsules with pre-dosed coffee sealed for pressure extraction. Proprietary system architectures dominate installed bases.
- Instant Coffee:Spray-dried or freeze-dried soluble granules reconstituted with hot water. Limited penetration in espresso-specific consumption due to crema absence.
Ground coffee absorbs the bulk of installed capacity; whole bean is expanding most quickly.
Brewing Method:
Equipment cost tiers and technical complexity stratify user bases from commercial operators to casual home brewers.
- Espresso Machine:Pump-driven or lever-operated systems forcing pressurized water through compacted grounds. Italian cafés and German office installations anchor commercial demand, pressured by EU Ecodesign efficiency mandates and thermal stability requirements.
- Stovetop:Moka pots using steam pressure generation without electrical components. Brazilian and Portuguese households sustain volume through low-cost durability and cultural tradition.
- French Press:Immersion brewing with coarse filtration and extended steep times. Niche positioning among consumers prioritizing body over crema intensity.
- Aeropress:Manual air-pressure devices combining immersion and filtration. Third-wave coffee communities in UK cities and Scandinavian markets drive adoption through portability and experimentation.
Espresso machines command the highest equipment spend; Aeropress shows the steepest expansion trajectory among manual methods.
Distribution Channel:
Channel margin structures and replenishment cadences determine where roasters allocate shelf-space investment and marketing resources.
- Retail Stores:Dedicated coffee shops and specialty grocers with trained staff and tasting infrastructure. Italian cities concentrate premium whole bean transactions through relationship-based selling.
- Online:Direct-to-consumer platforms with subscription replenishment and grind-size customization. UK and French suburban markets show strongest velocity as enthusiast households abandon supermarket pods.
- Coffee Shops:Out-of-home consumption venues with on-premise equipment and barista service. Urban centers in Spain and Portugal sustain high-frequency purchase patterns.
- Supermarkets:Mass-market retail with price-competitive ground coffee and pod selections. German and Dutch chains dominate volume through private-label penetration.
Supermarkets move the greatest unit volume; online channels are climbing the fastest on subscription attach rates.
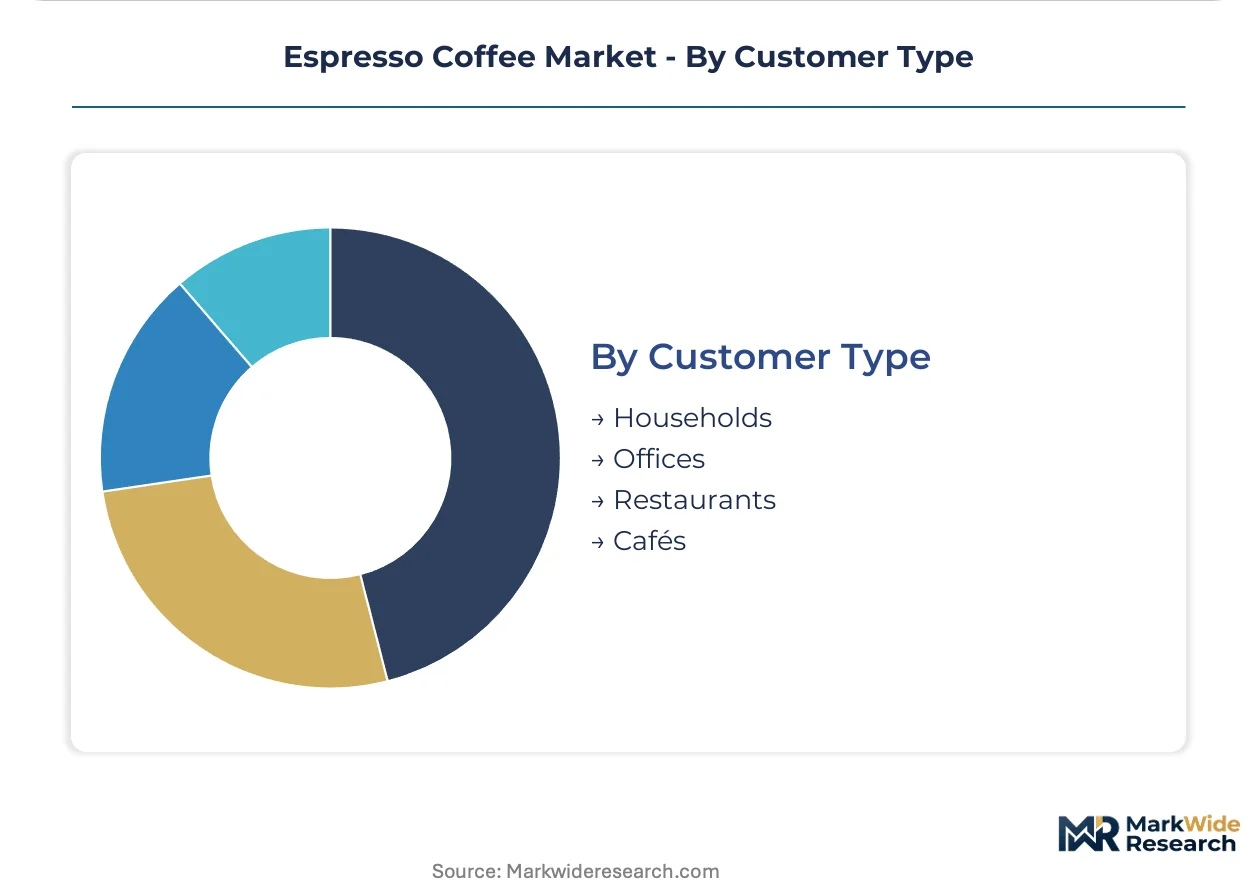
Customer Type:
Purchasing scale and equipment sophistication diverge sharply between individual consumers and institutional operators.
- Households:Individual and family units with single-machine installations and low daily throughput. French and Italian markets show highest per-capita equipment ownership and bean expenditure.
- Offices:Workplace installations serving employee populations with lease-to-own or managed service models. German and Netherlands commercial real estate shows underpenetration relative to Northern European peers.
- Restaurants:Foodservice venues integrating espresso into post-meal service with limited menu depth. Margin pressure from labor costs constrains equipment upgrade cycles.
- Cafés:Dedicated coffee venues with high machine utilization and skilled barista labor. Italian independent operators face thermal stability capex burdens that chain competitors absorb more readily.
Cafés deploy the most intensive equipment configurations; offices are gaining share fastest on lease-model penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil produces the majority of arabica beans entering global espresso supply chains, while European nations consume the highest per-capita volumes. Roasters must bridge this geographic divide through compliant sourcing infrastructure.
Italy
Traditional espresso culture drives premium machine purchases and whole bean consumption across Milan, Turin, and Rome. The EU Deforestation Regulation forces Italian roasters to restructure East African supply chains with farm-level geolocation data. Turin-based equipment manufacturers anchor the country's commercial espresso machine cluster.
Germany
Workplace espresso installations and supermarket ground coffee volumes sustain demand in Berlin, Hamburg, and Munich. REACH compliance mandates toxicology dossiers for commercial machine cleaning chemicals, delaying product launches. Bavaria hosts precision engineering facilities supplying PID-controlled boiler systems to café chains.
United States
Third-wave coffee culture in Seattle, Portland, and San Francisco accelerates whole bean subscription growth and manual brewing equipment sales. FDA food safety standards govern bean import sanitation protocols at West Coast ports. Pacific Northwest roasting clusters are investing in direct-trade relationships with Colombian cooperatives.
France
Suburban households around Paris and Lyon are abandoning pod systems for grind-specific whole bean purchases through direct-to-online channels. The EU Green Deal's deforestation-free mandates redirect procurement toward certified Central American suppliers. Lyon maintains a concentration of specialty café chains deploying pressure-profiling equipment.
Brazil
Weather volatility in Minas Gerais and São Paulo arabica regions transmits price shocks directly to international roaster margins. The country's agricultural ministry enforces phytosanitary export certification aligned with EU port entry requirements. São Paulo anchors South American roasting infrastructure serving both domestic consumption and export markets.
Espresso Coffee Market Vendor Landscape
The competitive structure tilts toward integrated beverage conglomerates with captive pod architectures and recurring revenue streams. Nestle, JDE Peet's, and Lavazza anchor the concentrated tier through proprietary ecosystem control. Three archetypes dominate: ecosystem-locked pod manufacturers, vertically integrated Italian roaster-equipment hybrids, and specialty retail chains with direct-trade sourcing. Competitive moves concentrate on backward integration into washing stations for EU Deforestation Regulation compliance and subscription platform development for enthusiast household retention.
Within the ecosystem-locked tier, Nestle exemplifies proprietary pod architecture strategy through its Nespresso installed base. JDE Peet's occupies the European retail shelf presence position with ground and whole bean portfolios. Lavazza represents the Italian integrated model spanning machine manufacturing, capsule production, and roasting operations with captive supply chain control.
| Leading Market Players |
|---|
| Nestle |
| JDE Peet's |
| Starbucks |
| Lavazza |
| Illy |
| Kraft Heinz |
| Peet's Coffee |
| Dunkin' |
| Tchibo |
| Others |
Supply Flow & Price Mechanics
Pressure profiling technology adoption in commercial equipment is simultaneously elevating thermal stability requirements and concentrating manufacturing among Italian and German engineering clusters with captive boiler system capabilities. This equipment transition feeds back into bean procurement, as cafés absorbing higher machine capex seek volume discounts and origin transparency to justify premium positioning.
Pricing Analysis
Margin tightening in pod systems reflects arabica price volatility transmitting directly from Brazilian and Colombian weather shocks to roaster working capital. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales service bundling, with EU Deforestation Regulation compliance costs pushing differentiation toward verified origin tiers. Cost-down pressure on ground coffee accelerates because supermarket private-label penetration in Germany and the Netherlands compresses branded shelf space. Households in France and Italy show lowest price sensitivity for whole bean subscriptions, while German office procurement teams prioritize lease-model predictability over per-unit bean expenditure.
Supply Chain Analysis
Precision machining workforce availability in Turin and Bavaria anchors commercial espresso machine production, with these regions feeding from East African and Central American washing stations for EU Deforestation Regulation-compliant arabica flows. Raw material dependencies center on aluminum for capsules, copper for boiler systems, and specialty-grade green coffee with phytosanitary certification. Single-source vulnerability concentrates in Brazilian arabica regions where climate shocks disrupt harvest predictability. Distribution runs through Italian port infrastructure for bean imports and German logistics hubs for equipment fulfillment across Northern European office channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The espresso coffee market sits in a technology-transition phase where connected machine telemetry replaces reactive maintenance schedules with predictive algorithms. Legacy equipment fleets face accelerated replacement as café chains standardize extraction quality across locations.
For Market Incumbents: Acquire washing station assets in East Africa to secure EU Deforestation Regulation-compliant bean flows before audit backlogs extend supplier onboarding delays. Nestle's Nespresso ecosystem defense requires reinforcing proprietary pod architecture loyalty through grind-size customization APIs that slow enthusiast household migration to whole bean subscriptions. Capacity addition in precision boiler manufacturing within Bavaria addresses thermal stability capex burdens squeezing independent Italian café operators.
For New Entrants and Emerging Players: EU Green Deal mandates in Germany and the Netherlands open a window for lease-to-own workplace espresso installations where commercial real estate remains underpenetrated relative to Northern European peers. White-space targets concentrate in office channel managed service models and direct-to-online whole bean subscriptions with grind-specific customization for UK suburban households. Go-to-market execution should anchor in sustainability certification storytelling that satisfies CSRD disclosure requirements for corporate procurement committees.
For Investors and Strategic Acquirers: Exit pathways concentrate in integrated roaster-equipment hybrids with captive East African supply chains and subscription platform technology. Long-term viability over the next decade hinges on deforestation-free traceability infrastructure and pressure profiling IP portfolios. The signal to watch is origin certification audit capacity expansion rates relative to EU port entry enforcement timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Washing Stations | Secures EU Deforestation Regulation-compliant arabica flows through farm-level geolocation data capture. |
| Subscription Platform Development | Captures enthusiast household retention with grind-size customization and freshness-controlled replenishment cycles. |
| Connected Machine Telemetry Deployment | Reduces café chain downtime through predictive maintenance algorithms integrated with fleet management systems. |
| Pressure Profiling Equipment Launch | Enables signature shot replication across high-turnover barista staff in Italian and German café chains. |
| Sustainability Certification Repositioning | Aligns roaster portfolios with CSRD disclosure requirements for carbon-negative supply chain verification. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this espresso coffee market assessment, combining primary interviews with café chain operations directors, green coffee procurement managers, equipment manufacturing engineers, and specialty roasting quality leads with validation against EU Deforestation Regulation implementation documents, ECHA REACH dossiers, and Italian coffee trade association export statistics. Bottom-up triangulation across product type, brewing method, distribution channel, and customer type segmentation converged with top-down macroeconomic framing.
Data-stream reconciliation across customs records, equipment shipment manifests, and retail audit databases informed the analytical framework over the projection horizon. Segmentation dimensions modeled include product format, brewing equipment tier, channel margin structure, and regional regulatory cluster. CAGRs were derived through slope analysis of historical volume trajectories adjusted for technology adoption curves and compliance cost pass-through assumptions, with arabica futures price volatility and EU audit capacity expansion serving as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for connected machine telemetry would alter the outlook if café chains delay fleet standardization investments. Forecasts reflect assumptions regarding EU Deforestation Regulation enforcement intensity and REACH compliance timeline adherence. Material deviation in Brazilian climate patterns or origin certification audit throughput warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Instant Coffee Market
Coffee
Coffee Bottle Market
Coffee
Coffee Fruit Extract Market
Coffee
Butter Coffee Market
Coffee
RTD Coffee Market
Coffee
Africa Ready-To-Drink (RTD) Coffee Market
Coffee
Cold Brew Coffee Makers Market
Coffee
Europe Coffee Pods and Capsules Market
Coffee
Global Nespresso Capsules Market
Coffee
Oceania Coffee Market
Coffee
Decaffeinated Coffee Market
Coffee
Mushroom Coffee Market
Coffee
Brazil Ready-To-Drink (RTD) Coffee Market
Coffee
Middle East Coffee Market
Coffee
North America Instant Coffee Market
Coffee
Saudi Arabia Coffee Roaster Market