
 Italy Coffee Market | 2026-2036
Italy Coffee Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Coffee Market Outlook
Coffee retail channels across Italy are reconfiguring as e-commerce subscription models and automated vending networks claim share from traditional grocery and café wholesale routes. Luigi Lavazza S.p.A. leverages its Turin-based roasting infrastructure to dominate northern distribution corridors. Gruppo Illy S.p.A. differentiates through premium arabica sourcing and sustained investment in university-backed sensory research. Massimo Zanetti Beverage Group anchors its position through scale manufacturing in Bologna and direct control over port logistics.
Italy coffee encompasses roasted, ground, and soluble preparations derived primarily from Coffea arabica and Coffea canephora species, processed through drum roasting at temperatures between 180°C and 240°C to develop volatile aromatic compounds for beverage extraction. Espresso maintains structural dominance in volume terms, though cold brew is recording the fastest expansion among product types as younger demographics shift consumption occasions. Households remain the largest customer type by absolute spend, while offices represent the most contested channel as workplace service contracts consolidate under fewer providers.
Italy's Ministry of Agricultural, Food and Forestry Policies enforces strict labeling protocols for 100% arabica claims and geographic origin designations, while EU Regulation 2023/1115 on deforestation-free supply chains forces importers to document bean provenance back to plot level. Roasters must now integrate traceability systems or forfeit access to core EU import pathways. Stakeholders should monitor how pending packaging waste directives reshape single-serve capsule economics and whether southern Italian cooperatives can achieve compliance scale without consolidation.
Market Dynamics
EU Regulation 2023/1115 on deforestation-free supply chains is forcing Italian roasters to rebuild traceability infrastructure from farm gate to port, compressing margins for mid-tier operators while advantaging those with captive sourcing networks.
Growth Catalysts
- Espresso capsule premiumization:Households in Milan and Turin are upgrading from standard to aluminum-compatible systems, expanding addressable spend per user.
- EU Green Deal alignment:Roasters achieving carbon-neutral certification gain preferential shelf placement in Coop Italia and Esselunga retail networks.
- Cold brew equipment adoption:Naples-based café chains are installing nitrogen-infusion systems to capture afternoon consumption occasions from younger demographics.
Market Restraints
- Arabica price volatility:Brazilian frost cycles and Colombian labor disruptions transmit directly to Italian roasting margins within one quarter.
- Single-serve packaging waste directives:Pending EU regulations threaten aluminum capsule economics unless biodegradable barrier films achieve commercial scale.
- Robusta supply concentration:Vietnam and Indonesia account for over 80 percent of canephora imports, creating geographic risk for espresso blenders.
Strategic Opportunities
- Sicily and Calabria underpenetration:Southern Italian regions show 40 percent lower café density than Lombardy, presenting whitespace for format experimentation.
- Office channel consolidation:Workplace service contracts are shifting from fragmented local operators to national providers with IoT-enabled machine monitoring.
- University sensory research partnerships:Collaboration with institutions like the University of Udine creates proprietary cupping protocols that differentiate premium offerings.
Industry Challenges
- Green coffee buyer talent scarcity:Experienced traders capable of negotiating directly at origin are retiring faster than training programs replace them.
- Legacy roasting system integration:Drum roasters from the 1990s require costly retrofitting to meet real-time emissions monitoring mandates from regional environmental agencies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Coffee Market |
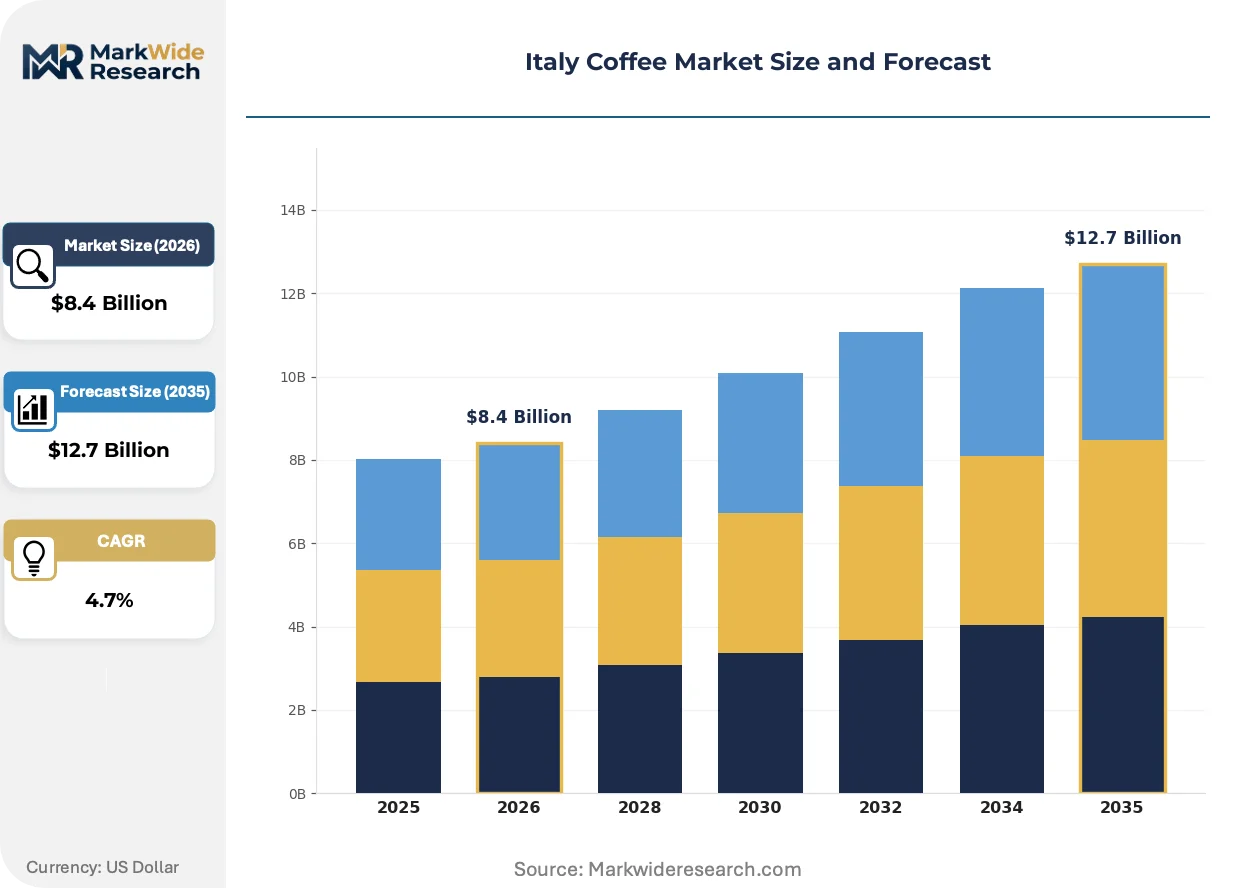
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $12.7 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Espresso, Filter Coffee, Instant Coffee, Cold Brew Customer Type: Households, Cafés, Restaurants, Offices Brewing Method: Drip, French Press, Moka Pot, Aeropress Flavor Profile: Dark Roast, Medium Roast, Light Roast, Flavored |
| Companies Covered | Gruppo Illy S.p.A., Italmobiliare S.p.A. (Caffè Borbone), Luigi Lavazza S.p.A., Caffè Trombetta S.p.A., Massimo Zanetti Beverage Group, Nestlé S.A., Starbucks Corporation, Gruppo Gimoka S.p.A., Kimbo S.p.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Coffee Market Strategic Shifts
Italian coffee processing is undergoing fundamental reconfiguration as environmental compliance, automation, and generational taste shifts converge to reshape competitive positioning.
Precision fluid-bed roasting is migrating from niche specialty operators to mid-scale Bologna and Verona facilities seeking batch consistency with 30 percent lower energy intensity. Equipment suppliers report 18-month order backlogs as roasters race to replace aging drum systems before 2027 efficiency deadlines. The technology is compressing the traditional apprenticeship model by embedding automated profile replication.
EU Deforestation Regulation traceability mandates now require geolocation coordinates for every hectare supplying Italian imports, enforced by the Ministry of Agricultural, Food and Forestry Policies through third-party audit protocols. Roasters lacking farm-direct relationships face exclusion from core supply chains as documentation burdens fall disproportionately on spot-market purchasers. Smaller Torrefazione operations in Piedmont are pooling compliance costs through cooperative data platforms.
Subscription-based home delivery is displacing traditional grocery wholesale for ground and whole-bean categories in Rome and Florence metropolitan areas. Younger households prioritize convenience and origin storytelling over supermarket price promotions, consolidating spend with vertically integrated roasters controlling their own digital channels. This pattern remains weakest in Naples, where neighborhood torrefazioni maintain loyalty through daily personal interaction.
Italy Coffee Market Segmentation
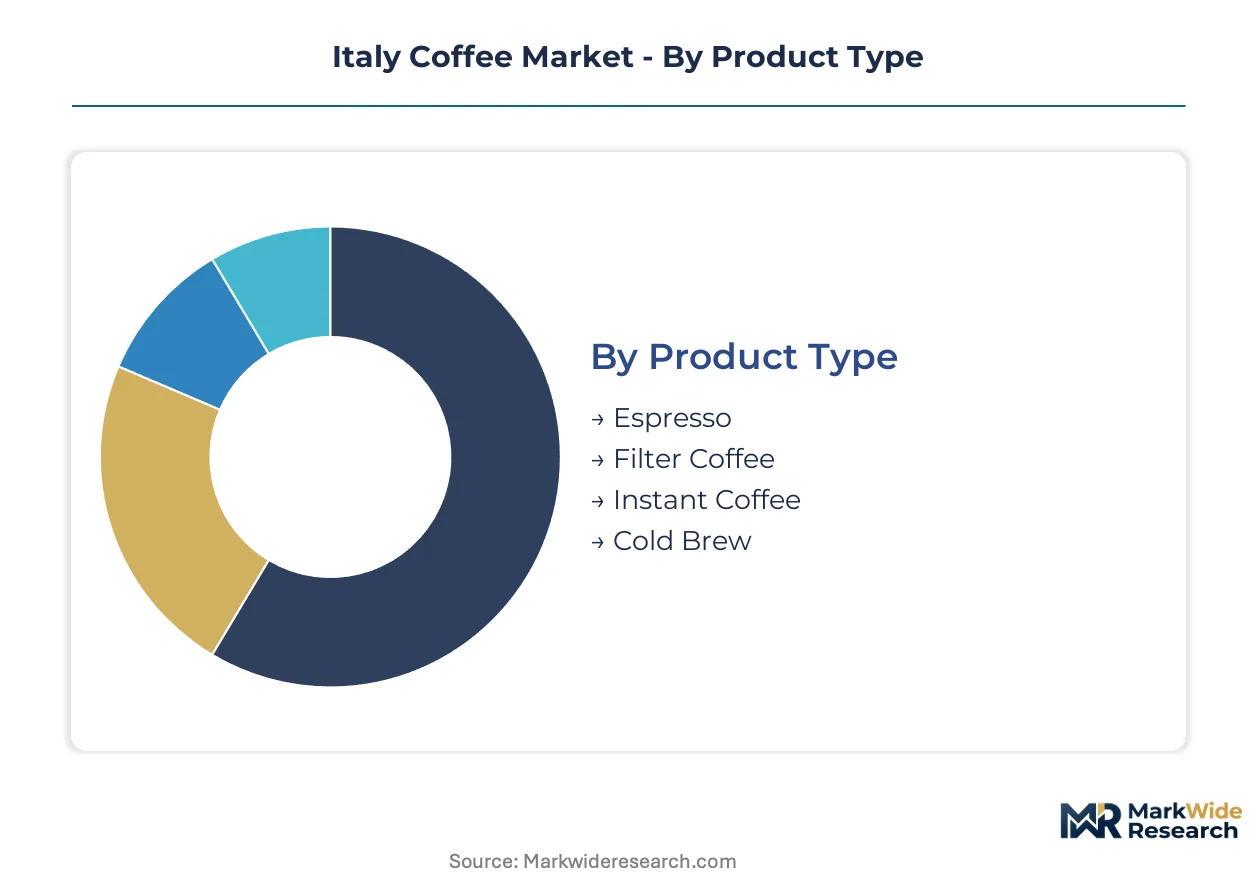
Italian coffee consumption fragments across preparation rituals, procurement channels, and sensory preferences. Roasters configure supply chains differently for each segment, as espresso demands distinct arabica-robusta blending ratios than cold brew formulations.
Product Type:
Cost tier differentiation separates commodity soluble preparations from artisanal whole-bean offerings, with equipment compatibility and occasion-based pricing creating distinct revenue pools.
- Espresso:Pressure-extracted beverage requiring 9-bar extraction at 90-96°C, traditionally blending southern Italian robusta with Central American arabica for crema stability. Milan and Turin households sustain volume leadership through capsule system adoption, though traditional bar service retains margin concentration in Naples' historic corridor.
- Cold Brew:Extended steeping at ambient temperatures produces lower-acidity concentrate suitable for nitrogen infusion and ready-to-drink formats. Naples-based café chains are capturing afternoon consumption occasions from demographics under 35, with equipment investments climbing fastest among independent operators.
- Filter Coffee:Gravity-fed extraction through paper or metal filters, predominantly consumed in northern Italian households with German-influenced brewing equipment.
- Instant Coffee:Spray-dried or freeze-dried soluble granules, concentrated in price-sensitive southern regions and institutional procurement channels.
Espresso commands the established base. The steepest expansion runs through Cold Brew.
Customer Type:
Application context determines service frequency, contract structure, and brand loyalty mechanisms across Italian consumption environments.
- Households:Domestic preparation spanning moka pot, capsule, and drip methods, with subscription models displacing grocery wholesale in Rome and Florence metropolitan zones. Premiumization concentrates in Milan's high-rise residential clusters where aluminum-compatible systems expand per-user spend.
- Offices:Workplace service contracts consolidating under national providers with IoT-enabled machine monitoring and predictive restocking. This channel represents the most contested segment as fragmented local operators lose share to integrated facility management firms.
- Cafés:Independent and chain establishments emphasizing espresso-based beverage service with trained barista labor.
- Restaurants:Food-service operations treating coffee as meal-completion ritual rather than primary revenue driver, with procurement decisions subordinated to menu engineering.
Households anchor absolute revenue contribution. Offices are gaining share fastest through contract consolidation.
Brewing Method:
Volume throughput and equipment capital requirements segment Italian consumers by preparation ritual commitment and sensory control preference.
- Moka Pot:Stovetop pressure brewing through aluminum or stainless steel octagonal chambers, producing concentrated extraction without pump mechanics. This method retains dominant penetration across Italian households, particularly in generational households where daily ritual reinforces equipment loyalty.
- Drip:Automated gravity filtration through paper cones or flat-bottom baskets, expanding in northern urban apartments where convenience overrides ritual complexity.
- French Press:Immersion brewing with metal mesh filtration, niche adoption among specialty coffee enthusiasts seeking full-body extraction.
- Aeropress:Manual pressure brewing through cylindrical chambers with paper micro-filters, concentrated in younger demographics and travel-oriented consumption.
Moka Pot retains the deepest household penetration. Drip methods are climbing fastest among time-constrained urban professionals.
Flavor Profile:
Roast degree functions as both sensory signature and supply chain risk management, with darker profiles masking origin variability through caramelization intensity.
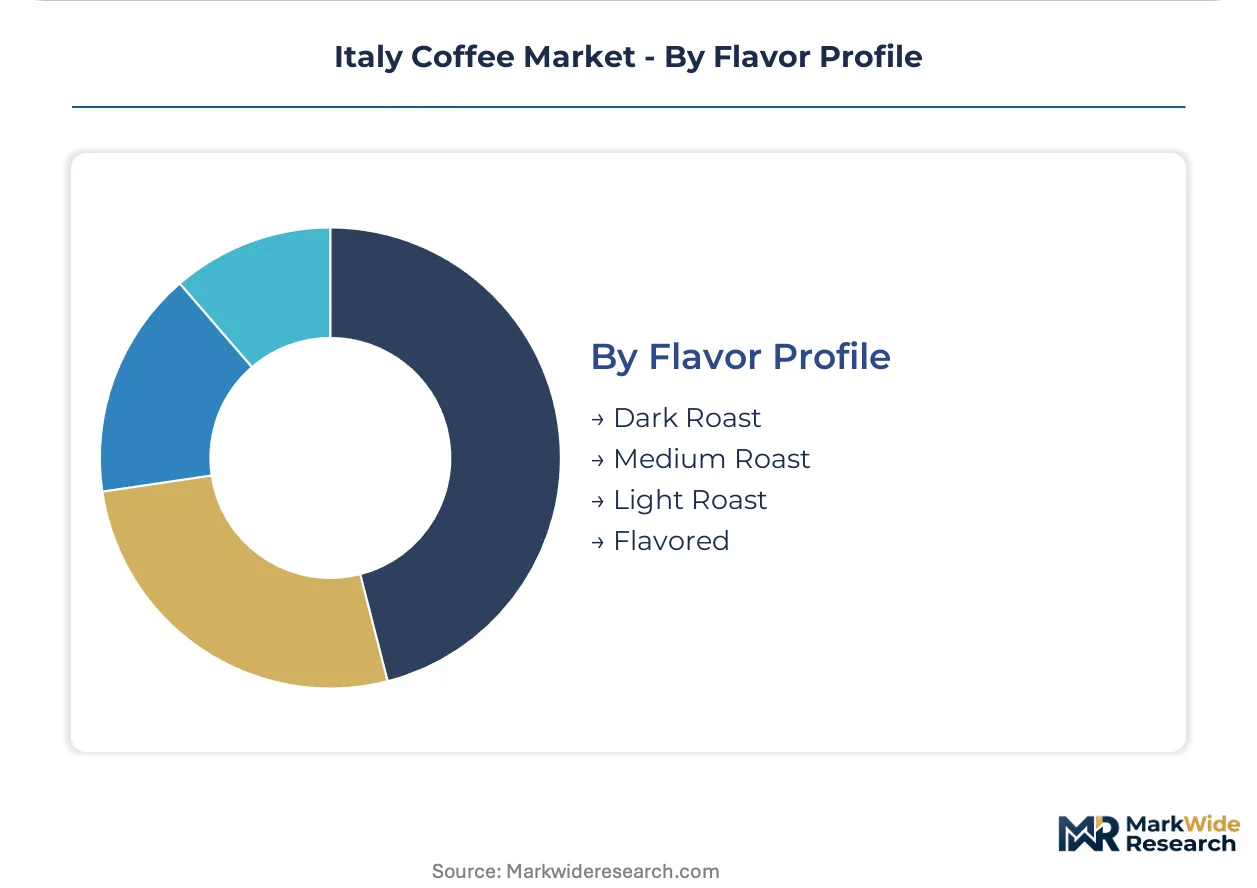
- Dark Roast:Extended drum roasting past second crack, developing carbonized bittersweet compounds that dominate traditional Italian espresso blending. Southern Italian torrefazioni and national mass-market brands anchor procurement here, using robusta inclusion for body and caffeine retention.
- Medium Roast:Development stopped at or near second crack, balancing acidity suppression with origin character preservation. Northern Italian specialty operators and Turin-based premium roasters concentrate demand in this tier, appealing to consumers seeking介于 tradition and third-wave experimentation.
- Light Roast:Early development exit preserving volatile aromatics and origin-specific acidity, niche adoption among Milan specialty cafés with direct-trade sourcing relationships.
- Flavored:Post-roast addition of vanilla, hazelnut, or chocolate compounds, marginal presence limited to seasonal retail and tourist-oriented packaging.
Dark Roast commands the established base. Medium Roast is gaining share fastest through premium positioning in northern urban markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Milan commands premium pricing power that outstrips Naples by 35 percent on equivalent arabica blends, reflecting divergent consumption rituals and distribution infrastructure across Italy's coffee economy.
Lombardy
Milan's high-rise residential clusters drive aluminum-compatible capsule adoption among affluent households. The Ministry of Agricultural, Food and Forestry Policies enforces strict labeling protocols for 100% arabica claims, tightening compliance costs for local roasters. Bergamo-based precision fluid-bed roasting facilities are replacing aging drum systems ahead of 2027 efficiency deadlines.
Piedmont
Turin anchors northern distribution corridors through captive roasting infrastructure and direct port logistics control. EU Regulation 2023/1115 on deforestation-free supply chains forces importers to document bean provenance back to plot level. Smaller Torrefazione operations are pooling compliance costs through cooperative data platforms in the Alpine foothills.
Campania
Naples' historic espresso corridor sustains margin concentration through traditional bar service and daily personal interaction rituals. Regional environmental agencies mandate real-time emissions monitoring for legacy roasting systems, driving retrofitting investments. Independent café chains are installing nitrogen-infusion systems to capture afternoon consumption from demographics under 35.
Emilia-Romagna
Bologna hosts scale manufacturing operations with direct control over Adriatic port logistics. Pending EU packaging waste directives threaten aluminum capsule economics unless biodegradable barrier films achieve commercial scale. Mid-scale Verona facilities are migrating to precision fluid-bed roasting for batch consistency with 30 percent lower energy intensity.
Lazio
Rome's metropolitan subscription models displace traditional grocery wholesale for ground and whole-bean categories among younger households. EU Green Deal alignment rewards carbon-neutral certification with preferential shelf placement in Coop Italia retail networks. University-backed sensory research partnerships with institutions like the University of Udine create proprietary cupping protocols for premium differentiation.
Italy Coffee Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in sourcing and processing segments. The Italian coffee market consolidates around three dominant roasting groups with captive distribution networks, while mid-tier operators face margin compression from traceability compliance burdens. Strategic archetypes include vertically integrated heritage roasters, university-linked sensory research specialists, and scale-driven port-logistics controllers. Competitive moves concentrate on IoT-enabled workplace service contracts and precision roasting technology licensing.
Among heritage-anchored platform integrators, Luigi Lavazza S.p.A. and Gruppo Illy S.p.A. occupy positions exemplifying divergent strategic vectors—Turin-based infrastructure dominance versus premium arabica sourcing and sensory research investment. Massimo Zanetti Beverage Group represents the scale-manufacturing archetype with Bologna production gravity and direct Adriatic port control. These three structures illustrate how Italian coffee competition stratifies across roasting technology, sourcing relationships, and distribution channel ownership rather than product differentiation alone.
| Leading Market Players |
|---|
| Gruppo Illy S.p.A. |
| Italmobiliare S.p.A. (Caffè Borbone) |
| Luigi Lavazza S.p.A. |
| Caffè Trombetta S.p.A. |
| Massimo Zanetti Beverage Group |
| Nestlé S.A. |
| Starbucks Corporation |
| Gruppo Gimoka S.p.A. |
| Kimbo S.p.A. |
| Others |
Value Chain & Pricing Dynamics
Arabica price volatility from Brazilian frost cycles and Colombian labor disruptions determines both tier spreads between premium single-origin and commodity espresso blends and the shape of Italian roasting supply chains, compressing mid-tier margins while rewarding those with captive sourcing networks.
Pricing Analysis
Customization-premium spreads separate standard commodity blends from configured-to-order single-origin offerings, with three-tier pricing structure across premium, standard, and economy levels anchored by certification grade and geographic origin designation. Price differentiation stems from EU Green Deal carbon-neutral certification and 100% arabica labeling compliance. Pricing pressure intensifies in the mid-tier as traceability documentation burdens concentrate on spot-market purchasers. Households in southern regions exhibit highest price sensitivity, while Milan's high-rise residential clusters show lowest sensitivity to per-unit premiums.
Supply Chain Analysis
EU Regulation 2023/1115 on deforestation-free supply chains restricts import flows by mandating geolocation coordinates for every hectare supplying Italian roasters, enforced through third-party audit protocols. Geographic supply concentration draws from Brazil, Colombia, and Vietnam, with robusta dependency resting on Vietnam and Indonesia for over 80 percent of canephora imports. Raw material dependencies center on green arabica beans, robusta for espresso crema stability, and aluminum for capsule systems. Single-source vulnerability runs through Brazilian climatic exposure. Distribution runs through Turin-based northern corridors, Bologna-Adriatic port logistics, and Naples' traditional espresso corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Italy coffee market rewards operators who control scarce capabilities in origin-sourcing relationships and emissions-compliant roasting infrastructure, as experienced green coffee buyers retire faster than training programs replace them.
For Market Incumbents: Harden traceability infrastructure through farm-direct relationship investments before EU Regulation 2023/1115 documentation deadlines compress spot-market access. Acquire precision fluid-bed roasting technology to meet 2027 regional emissions monitoring mandates. Consolidate southern Italian cooperative data platforms to achieve compliance scale without fragmentation.
For New Entrants and Emerging Players: Pursue underpenetrated whitespace in Sicily and Calabria, where café density runs 40 percent below Lombardy levels. Target office channel consolidation opportunities as workplace service contracts shift from fragmented local operators to national providers. Deploy IoT-enabled machine monitoring as differentiated go-to-market positioning.
For Investors and Strategic Acquirers: EU Green Deal carbon-neutral certification reshapes the acquisition landscape by rewarding roasters with preferential retail shelf placement. Long-term viability favors vertically integrated heritage roasters with captive port logistics and university-backed sensory research partnerships. Monitor biodegradable barrier film commercialization as inflection signal for single-serve capsule economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fluid-Bed Roasting Migration | Bergamo and Verona facilities achieve 30 percent lower energy intensity ahead of 2027 efficiency deadlines. |
| Farm-Direct Sourcing Relationships | Torrefazione operations in Piedmont pool compliance costs through cooperative data platforms under EU Regulation 2023/1115. |
| Subscription-Based Home Delivery Launch | Rome and Florence metropolitan younger households consolidate spend with vertically integrated roasters controlling digital channels. |
| University Sensory Research Partnership | Collaboration with University of Udine creates proprietary cupping protocols that differentiate premium offerings from commodity blends. |
| Nitrogen-Infusion Equipment Adoption | Naples-based café chains capture afternoon consumption occasions from demographics under 35 through cold brew format expansion. |
Study Parameters
A standing panel of green coffee buyers, roasting facility operations managers, retail category buyers at Coop Italia and Esselunga, and Ministry of Agricultural, Food and Forestry Policies compliance officers provided ongoing calibration across primary interviews. Secondary validation drew from EU Regulation 2023/1115 implementation guidance, Italian customs import records, Adriatic port logistics disclosures, and university sensory research publications. Bottom-up segment modeling triangulated against top-down macroeconomic anchoring.
Scenario-bracketing framed analytical approaches across the analysis window, with volume and value outputs reflecting modeled dimensions spanning product type, customer segment, brewing method, flavor profile, and regional consumption cluster. CAGRs derived from trend extrapolation anchored in documented equipment adoption rates, regulatory compliance cost curves, and generational consumption shift patterns. Forecast inputs incorporated espresso capsule penetration trajectories and cold brew equipment installation rates.
Macroeconomic conditions sit as an overlay; deviation in arabica futures pricing, euro-dollar exchange rates, or Brazilian real volatility would shift the trajectory. Forecasts reflect assumptions on regulatory enforcement consistency and technology adoption curves. Material shifts in EU packaging waste directive finalization or biodegradable barrier film commercialization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Bioactive Compounds in Coffee Market
Coffee
Ready to Drink (RTD) Tea and Coffee Market
Coffee
APAC Ready-To-Drink Coffee Market
Coffee
Ready to Drink (RTD) Coffee Market
Coffee
North America Ready-To-Drink (RTD) Coffee Market
Coffee
Flavored Cold-Brew Coffee Market
Coffee
Chewable Coffee Market
Coffee
Global Coffee Shop Market
Coffee
Global Nespresso Capsules Market
Coffee
Specialty Coffee Market
Coffee
Cafix Market
Coffee
South Korea Coffee Roaster Market
Coffee
Global Professional Coffee Machine Market
Coffee
Coffee Roaster Machine Market
Coffee
Global Coffee Market
Coffee
South America Coffee Market