
 Asia Pacific Coffee Market | 2026-2036
Asia Pacific Coffee Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Coffee Market Analysis
Asset-light franchising and third-party leaseback arrangements for café real estate is reconfiguring capital deployment across the Asia Pacific coffee landscape. Luckin Coffee Inc. leverages a technology-heavy, low-owned-asset model to saturate Chinese cities with minimal balance-sheet weight. Nestlé S.A. anchors its regional position through deep backward integration into instant coffee manufacturing and soluble product R&D. Starbucks Corporation sustains premium positioning via controlled experiential retail formats in Japan, South Korea, and Australia.
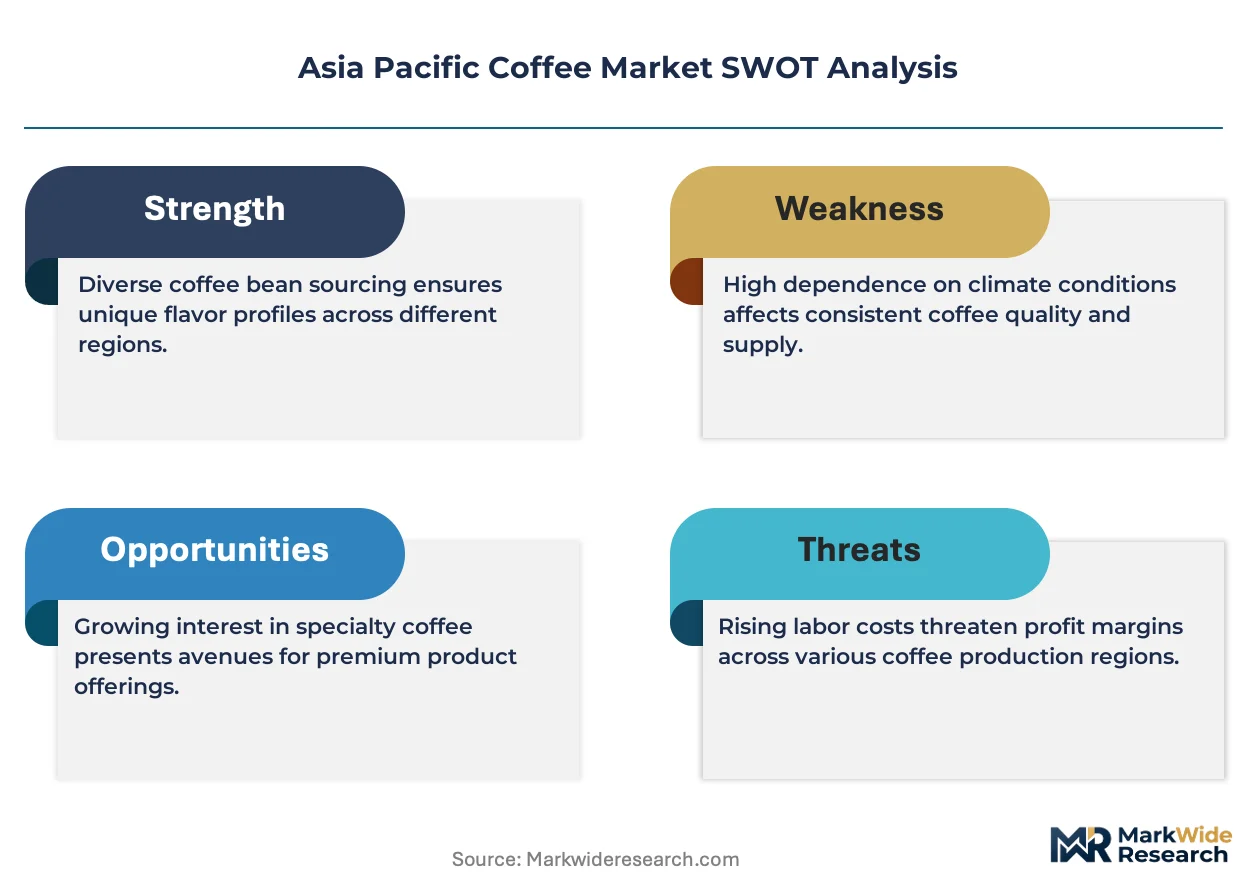
Asia Pacific coffee encompasses roasted and soluble preparations derived from Coffea arabica and Coffea canephora (Robusta) species, typically processed through wet or dry milling followed by roasting to specific colorimetric scales measured in Agtron units for flavor development. The primary commercial purpose spans beverage consumption across household, foodservice, and workplace channels, with soluble instant formats serving cost-sensitive volume demand and roasted whole bean or ground products targeting flavor-oriented buyers. Arabica dominates premium positioning in Japanese and Australian specialty markets, while instant coffee retains structural volume leadership across Southeast Asian household penetration. Online retail distribution is accelerating fastest in China and India as digital native platforms displace traditional supermarket gravity for repeat purchases.
Japan's Ministry of Economy, Trade and Industry (METI) enforces food labeling and quality standards that shape import requirements for roasted coffee, while China's State Administration for Market Regulation (SAMR) governs food safety and green packaging compliance under evolving national standards. India's Food Safety and Standards Authority (FSSAI) mandates contaminant limits and additive rules that filter which processed coffee products enter formal retail channels. Stakeholders must monitor how diverging national packaging and carbon-footprint regulations will fragment compliance costs across the region's production and import nodes.
Market Dynamics
China's dual carbon goals and green packaging mandates are compressing sourcing timelines and forcing roasters to requalify suppliers against carbon-intensity benchmarks and biodegradable material standards.
Growth Catalysts
- Out-of-home consumption pivot:Urban professionals in Shanghai, Tokyo, and Ho Chi Minh City now treat café visits as daily rituals, expanding addressable foodservice volume for premium arabica preparations.
- Digital retail infrastructure:Live-streaming commerce platforms and same-delivery logistics are virtualizing repeat purchase behavior, locking Chinese consumers into subscription-like replenishment cycles for roasted whole bean products.
- SAMR green packaging compliance:China's State Administration for Market Regulation is mandating biodegradable and reduced-plastic formats, creating first-mover advantage for roasters with certified sustainable packaging supply chains.
Market Restraints
- Robusta supply concentration:Vietnamese and Indonesian smallholder harvests dominate global Robusta volumes, exposing price volatility to monsoon timing and regional pest outbreaks.
- Arabica input cost sensitivity:Brazilian frost events and Colombian labor disruptions transmit directly into landed costs for Asia Pacific specialty roasters with limited forward-contract coverage.
- Import tariff fragmentation:Divergent ASEAN member state duties on soluble coffee create arbitrage friction that complicates centralized manufacturing strategies for regional brands.
Strategic Opportunities
- India's underpenetrated café channel:Tier-2 and Tier-3 Indian cities retain minimal out-of-home coffee infrastructure, presenting whitespace for format experimentation beyond metro saturation.
- Workplace channel digitization:Corporate pantry services and office coffee system leasing are displacing traditional vending, creating recurring revenue pools for equipment-plus-consumables bundling.
- Japan's METI carbon labeling:The Ministry of Economy, Trade and Industry is piloting product-level carbon disclosure, rewarding roasters with verified supply chain traceability and low-emission milling partnerships.
Industry Challenges
- Q-Grader talent scarcity:Certified sensory evaluators capable of scoring specialty lots to SCA protocols remain concentrated in Melbourne, Tokyo, and Seoul, constraining quality control scaling in emerging markets.
- Roaster-café equipment integration:Legacy espresso machine fleets lack IoT connectivity for predictive maintenance, forcing operators into costly parallel technology stacks or manual monitoring regimes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Coffee Market |
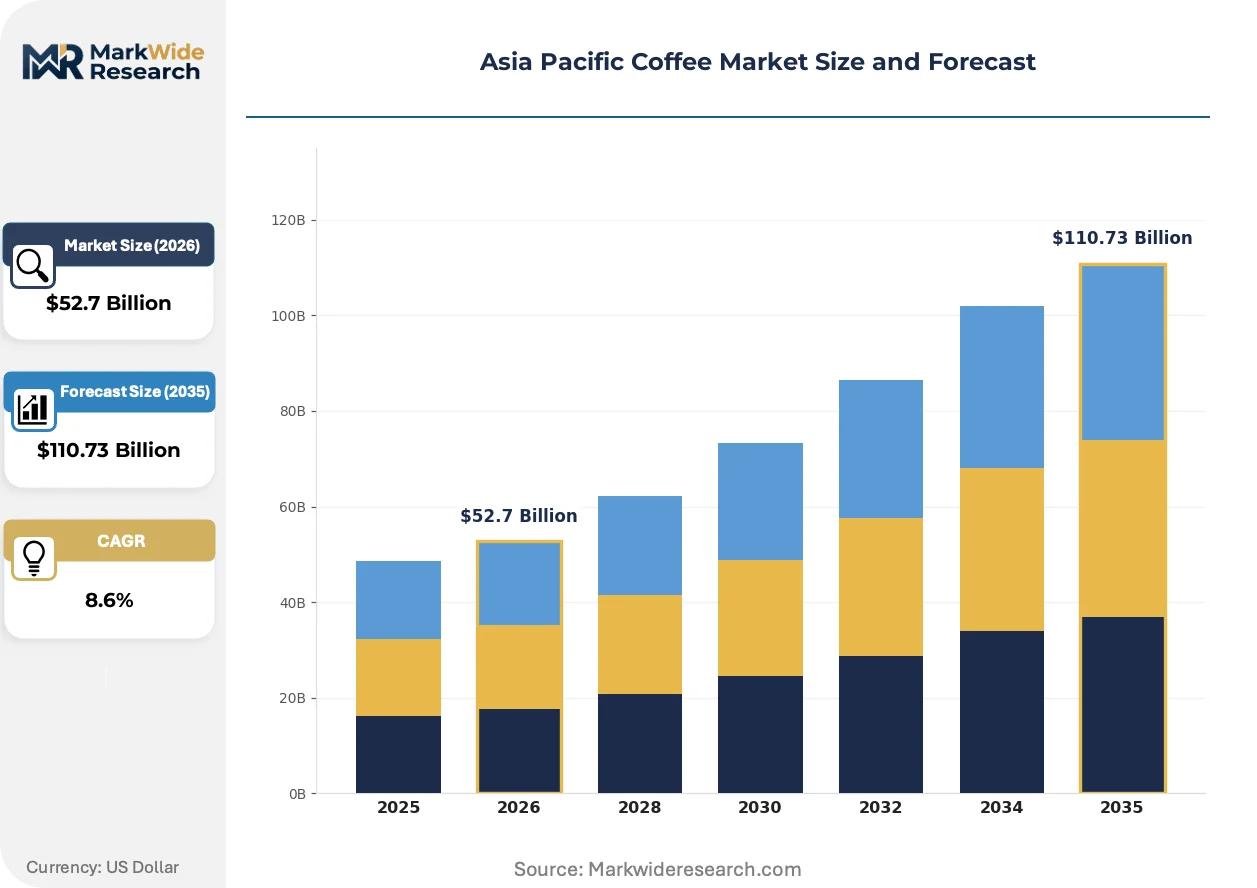
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $110.73 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
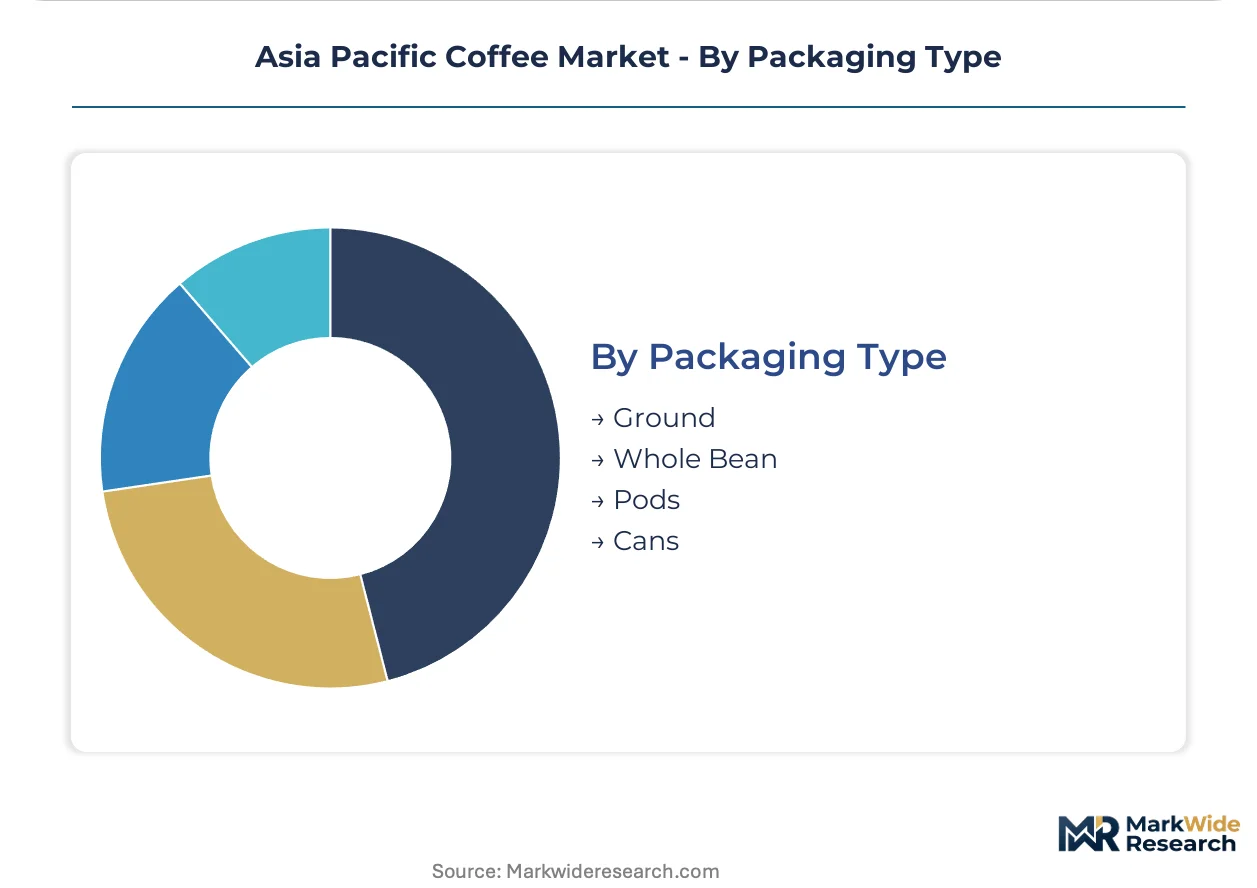
| Segmentation | Product Type: Arabica, Robusta, Espresso, Instant Distribution Channel: Supermarkets, Online Retail, Cafés, Convenience Stores Customer Type: Households, Offices, Restaurants, Hotels Packaging Type: Ground, Whole Bean, Pods, Cans |
| Companies Covered | JDE Peet's, UCC Ueshima Coffee Co., Ltd., Nestlé S.A., Suntory Holdings Limited, Luckin Coffee Inc., Starbucks Corporation, The Kraft Heinz Company, Trung Nguyen Coffee, Luigi Lavazza S.p.A., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Coffee Market Emerging Trajectories
Technology deployment and regulatory compression are rewiring how coffee moves from origin to cup, with digital platforms and carbon accountability now core to competitive positioning rather than peripheral marketing.
Blockchain-enabled lot traceability is virtualizing supply chain transparency for specialty arabica shipments. Japanese and Australian importers now require farm-level provenance verification as a procurement gate. This technology is compressing the information asymmetry that historically advantaged large trading houses over origin cooperatives.
China's evolving GB standards for biodegradable packaging are forcing roasters to requalify film suppliers and retest shelf-life performance. The industrial consequence is accelerated R&D spending on compostable valve bags and water-based inks. Premium retail brands targeting Shanghai and Beijing are responding fastest, using compliance as a positioning wedge against mass-market competitors.
Subscription-based replenishment is displacing supermarket gravity as the dominant repeat-purchase channel for roasted whole bean products. Chinese digital native platforms and Indian quick-commerce apps are capturing urban households that previously bought on weekly grocery trips. This shift is most visible in Seoul and Singapore, where delivery density supports same-day fulfillment economics for perishable coffee formats.
Asia Pacific Coffee Market Segmentation
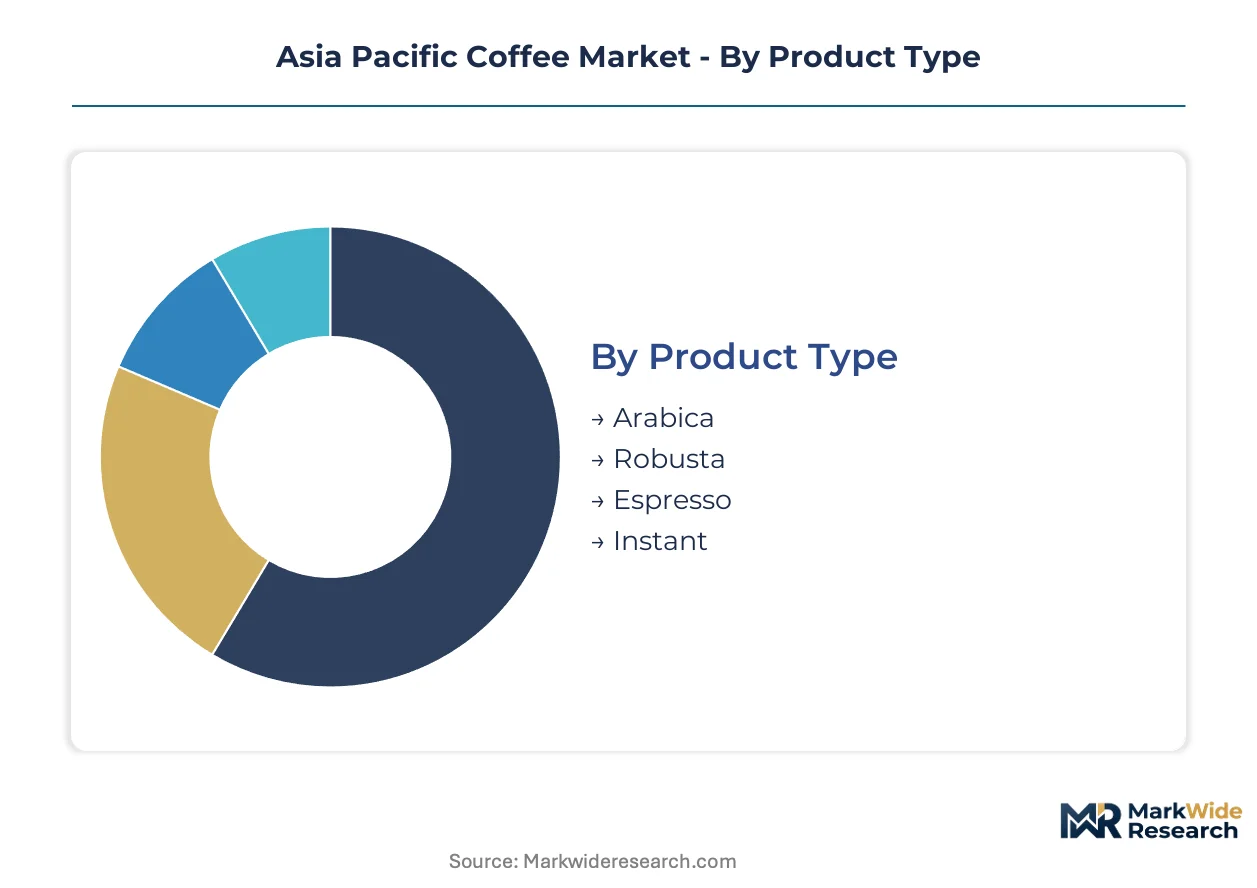
Segmentation reveals how Asia Pacific coffee demand fragments across preparation formats, purchase venues, and end-use contexts. Understanding these divides exposes where margin concentrates and which channels command loyalty investment.
Product Type:
After-sales service intensity varies sharply across product categories—roasted formats demand grinder maintenance and brewing guidance, while instant formats require minimal post-purchase touchpoints.
- Arabica:Higher-altitude cultivation yields complex acidity profiles prized in Japanese and Australian specialty markets. Roasters in Tokyo and Melbourne now source micro-lots with farm-level traceability to justify premium shelf positioning.
- Robusta:Higher caffeine content and crema stability make this species indispensable for Vietnamese espresso traditions and Southeast Asian instant manufacturing. Vietnamese smallholder harvests supply regional soluble processors with cost-competitive volume.
- Espresso:Concentrated extraction format dominates Italian-influenced café cultures across Melbourne, Sydney, and Ho Chi Minh City.
- Instant:Spray-dried and freeze-dried preparations retain structural volume leadership in Indonesian and Philippine household penetration.
By volume, Robusta leads. By growth pace, Arabica is ahead.
Distribution Channel:
Cost tier stratification separates these channels—supermarkets and convenience stores compete on price accessibility, while cafés and online retail extract premium through experience or convenience.
- Supermarkets:Gravity-driven aisle placement still governs mass-market soluble purchases across Indonesian and Philippine retail landscapes. Chained hypermarkets in Bangkok and Jakarta negotiate annual listing fees that filter smaller regional roasters.
- Online Retail:Live-streaming commerce and same-day delivery logistics now capture Chinese and Indian urban households previously loyal to weekly grocery trips. Platform algorithms in Shanghai and Bangalore personalize replenishment timing based on consumption velocity data.
- Cafés:Controlled experiential formats in Osaka and Seoul sustain premium arabica positioning through barista craft theater.
- Convenience Stores:24-hour availability and grab-and-go formats serve commuter demand corridors in Tokyo and Taipei.
By transaction count, convenience stores lead. By margin per unit, cafés are ahead.
Customer Type:
Application context dictates preparation complexity—households and offices favor simplicity, while restaurants and hotels demand equipment integration and staff training.
- Households:Repeat purchase behavior is shifting from supermarket gravity toward subscription replenishment on Chinese and Indian digital platforms. Seoul and Singapore households now expect same-day fulfillment for roasted whole bean orders.
- Offices:Corporate pantry services and leased coffee systems are displacing legacy vending infrastructure across Shanghai and Bangalore business districts. Equipment-plus-consumables bundling creates recurring revenue pools for service providers.
- Restaurants:Menu integration demands consistent extraction quality across multiple locations.
- Hotels:In-room and lobby service expectations vary by star rating and guest origin profile.
By unit volume, households lead. By contract value stability, offices are ahead.
Packaging Type:
Supply concentration shapes competitive dynamics—ground and whole bean formats source from dispersed roasting networks, while pods and cans demand capital-intensive manufacturing partnerships.
- Ground:Pre-milled convenience targets time-constrained urban consumers in Tokyo and Seoul with specified grind calibrations for drip and press methods.
- Whole Bean:Freshness preservation and grinder ownership signal enthusiast commitment in Australian and Japanese specialty markets. Agtron colorimetric scales guide roast level selection for home brewing optimization.
- Pods:Single-serve aluminum and compostable formats require licensed manufacturing agreements with equipment ecosystem owners.
- Cans:Ready-to-drink cold brew and nitro formats compete in Japanese vending and convenience channels.
By household penetration, ground leads. By margin expansion, whole bean is ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's dual carbon goals and SAMR green packaging mandates are reconfiguring sourcing requirements across the region, while Japan's METI carbon labeling pilots reward verified supply chain traceability. Vietnam's smallholder harvests dominate Robusta volumes, exposing price volatility to monsoon timing.
China
Urban professionals in Shanghai and Beijing treat café visits as daily rituals, expanding foodservice volume for premium arabica preparations. SAMR mandates biodegradable and reduced-plastic packaging formats, creating first-mover advantage for roasters with certified sustainable supply chains. The Yangtze River Delta clustering around Shanghai anchors live-streaming commerce platforms that virtualize repeat purchase behavior for roasted whole bean products.
Japan
Specialty markets in Tokyo and Osaka prize complex acidity profiles from higher-altitude Arabica cultivation, with micro-lot sourcing now requiring farm-level traceability. METI enforces food labeling and quality standards that shape import requirements for roasted coffee, while piloting product-level carbon disclosure. The Kanto region's vending and convenience channels sustain ready-to-drink cold brew and nitro format competition.
Vietnam
Espresso traditions in Ho Chi Minh City and Hanoi drive demand for Robusta's higher caffeine content and crema stability. Smallholder harvests supply regional soluble processors with cost-competitive volume, though monsoon timing and regional pest outbreaks transmit price volatility. The Central Highlands concentration around Đắk Lắk Province anchors domestic roasting capacity expansion.
South Korea
Seoul's café density supports same-day fulfillment economics for perishable coffee formats, displacing supermarket gravity with subscription replenishment. MFDS food safety standards govern additive rules and contaminant limits for processed products entering formal retail. The Seoul Capital Area clustering anchors controlled experiential retail formats that sustain premium arabica positioning through barista craft theater.
Australia
Melbourne and Sydney specialty markets demand Agtron colorimetric scale precision for roast level selection, with grinder ownership signaling enthusiast commitment. TGA-equivalent state-level food safety frameworks filter which processed products enter formal channels. The Melbourne coffee cluster concentrates certified sensory evaluators capable of scoring specialty lots to SCA protocols, constraining quality control scaling elsewhere.
Asia Pacific Coffee Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where scale-driven instant manufacturers coexist with experience-focused café operators. The market fragments across three strategic archetypes: technology-heavy low-asset platform operators, backward-integrated soluble product specialists, and controlled experiential retail format owners. Dominant competitive moves include asset-light franchising with third-party leaseback arrangements, and equipment-plus-consumables bundling for workplace channel digitization.
Within the technology-platform archetype, Luckin Coffee Inc. occupies a position exemplifying minimal balance-sheet saturation of Chinese urban markets. Nestlé S.A. anchors the backward-integrated specialist tier through captive supply into instant coffee manufacturing and soluble product R&D. Starbucks Corporation represents the controlled experiential format approach across Japanese, South Korean, and Australian premium positioning.
| Leading Market Players |
|---|
| JDE Peet's |
| UCC Ueshima Coffee Co., Ltd. |
| Nestlé S.A. |
| Suntory Holdings Limited |
| Luckin Coffee Inc. |
| Starbucks Corporation |
| The Kraft Heinz Company |
| Trung Nguyen Coffee |
| Luigi Lavazza S.p.A. |
| Others |
Supply Flow & Price Mechanics
Shanghai-to-Singapore container freight corridors transmit Brazilian frost premiums and Vietnamese monsoon disruptions directly into landed cost spreads for Asia Pacific roasters, compressing margins on Arabica imports while amplifying price differentiation between certified sustainable lots and conventional grades.
Pricing Analysis
Certification level creates the primary spread between farm-level traceability premiums and mass-market commodity pricing across the Asia Pacific coffee landscape. Specialty roasters in Tokyo and Melbourne command tiered pricing structures across premium, standard, and economy levels based on Agtron roast precision and micro-lot provenance verification. Cost compression in instant coffee manufacturing intensifies as Vietnamese Robusta supply volatility transmits into raw material input swings. Foodservice buyers in Shanghai cafés exhibit lowest price sensitivity, while Indonesian household purchasers of soluble formats remain most responsive to shelf-price shifts.
Supply Chain Analysis
Neumann Kaffee Gruppe and Volcafe dominate regional contract milling and export logistics capacity across Vietnam, Indonesia, and Brazil origin nodes. Green coffee supply concentrates in Brazilian Arabica belts, Vietnamese Central Highlands Robusta smallholdings, and Colombian high-altitude zones for premium micro-lots. Roasted product distribution runs through supermarket gravity in Jakarta and Bangkok, live-streaming platforms in Shanghai, and controlled experiential formats in Seoul and Osaka. Single-source vulnerability concentrates in Vietnamese monsoon-dependent harvests, exposing regional soluble processors to crop-year volatility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific coffee market tracks a cyclical recovery anchored in post-pandemic out-of-home consumption normalization and workplace channel reinvestment across Chinese and Indian business districts.
For Market Incumbents: Build certification moats around carbon-labeled supply chains to preempt Japan's METI disclosure mandates and China's SAMR green packaging compliance timelines. Deepen backward integration into Vietnamese and Indonesian origin processing to secure Robusta volume against monsoon volatility. Acquire Q-Grader talent clusters in Melbourne and Tokyo before quality control scaling constraints tighten further.
For New Entrants and Emerging Players: Build out tier-2 and tier-3 Indian city café infrastructure where out-of-home penetration remains minimal and rent economics favor format experimentation. Target workplace channel digitization in Bangalore and Shanghai corporate districts with equipment-plus-consumables bundling models. Leverage quick-commerce platform partnerships for same-day fulfillment rather than competing against established supermarket gravity.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platform operators with asset-light franchising models over capital-intensive roasting infrastructure. Long-term viability rests on digital native customer acquisition and subscription retention mechanics rather than geographic store count. Monitor live-streaming commerce conversion rates as the inflection signal for roasted whole bean demand migration away from traditional retail.
| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Labeling Compliance | METI pilot programs reward verified traceability with premium shelf positioning in Japanese retail. |
| Biodegradable Packaging Transition | SAMR GB standards force requalification of film suppliers for Shanghai and Beijing market access. |
| Workplace Channel Digitization | Corporate pantry services displace legacy vending across Shanghai and Bangalore business districts. |
| Live-Streaming Commerce Integration | Platform algorithms in Seoul and Singapore personalize replenishment timing for perishable formats. |
| Origin Processing Acquisition | Vietnamese Central Highlands milling assets secure cost-competitive Robusta supply against monsoon risk. |
Methodological Framework
Cross-validation between primary interviews with coffee roasting executives, café chain operators, and green coffee traders and secondary validation through customs trade data, SEC filings of listed coffee companies, and METI/SAMR regulatory databases anchors the qualitative findings. Bottom-up demand modeling triangulates against top-down market sizing from soluble manufacturing capacity and foodservice outlet counts across the region.
Calibration against historical volume trajectories and elasticity assumptions shapes the analytical framework across the analysis window. Segmentation dimensions include product type, distribution channel, customer application, and packaging format, with CAGRs derived from trend extrapolation adjusted for regulatory compression effects. Forecast inputs incorporate Arabica futures curve dynamics and green packaging compliance cost pass-through assumptions.
Sensitivities concentrate around Brazilian frost recurrence, Vietnamese monsoon timing, and Chinese regulatory enforcement cadence on biodegradable mandates. Quarterly review of container freight rates, origin differentials, and live-streaming platform GMV disclosure is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Europe Coffee Pods and Capsules Market
Coffee
Reusable Coffee Cup Market
Coffee
Coffee Fruit Extract Market
Coffee
South America Ready-To-Drink (RTD) Coffee Market
Coffee
Saudi Arabia Coffee Roaster Market
Coffee
Coffee Pods and Capsules Market
Coffee
Global Coffee Machine Market
Coffee
Tea and Coffee Bags Market
Coffee
Coffee Premixes Market
Coffee
Encapsulated Caffeine Market
Coffee
Single Origin Coffee Market
Coffee
South Korea Coffee Roaster Market
Coffee
Global Professional Coffee Machine Market
Coffee
United Arab Emirates Coffee Roaster Market
Coffee
India Coffee Roaster Market
Coffee
Global Coffee Market