
 Coffee Premixes Market | 2026-2036
Coffee Premixes Market Size, Share, and Industry Trends Forecast 2026-2036
Coffee Premixes Market Analysis
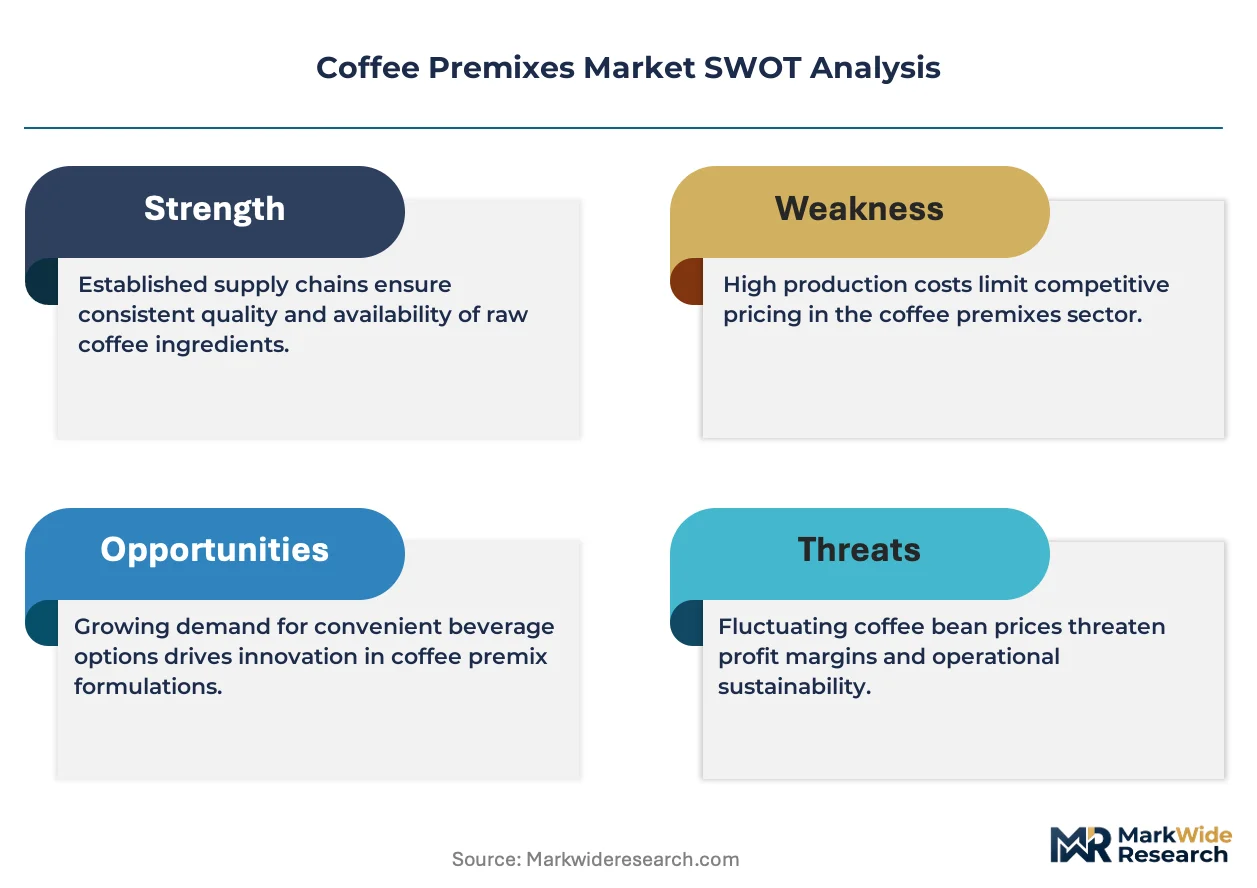
Premium roast profiles and specialty-grade Arabica blends is bifurcating the Coffee Premixes Market into mass-market convenience tiers and artisan-positioned offerings. Nestlé dominates the single-serve pod architecture through captive supply of proprietary brewing systems. Starbucks Corporation anchors its retail-to-home bridge strategy with licensed premix formats mirroring in-store flavor signatures. Tata Coffee leverages its estate-origin sourcing to differentiate in Asian markets where provenance commands shelf placement.
Coffee premixes constitute dry or liquid formulations combining soluble coffee, dairy or non-dairy whiteners, sweeteners, and functional additives, engineered for reconstitution with hot or cold water at specified dilution ratios. The manufacturing process centers on spray-drying or freeze-drying of coffee extract followed by agglomeration with adjunct powders to achieve dispersion stability and flavor retention. Instant Coffee Premix occupies the volume core, while Coffee Pods capture disproportionate margin pools through equipment-locked repeat purchase economics. Ready-to-Drink Coffee is registering the fastest trajectory as refrigerated distribution expands beyond traditional hot-beverage occasions.
The FDA governs nutritional labeling and health claim substantiation for coffee premixes sold in the United States, while the FSSAI mandates additive limits and packaging standards for products distributed across India. The EU Green Deal's packaging waste directives are pressuring European suppliers to eliminate multi-layer sachet constructions in favor of mono-material alternatives. Stakeholders must monitor evolving extended producer responsibility frameworks and decide whether to front-load compliance investment or risk exclusion from regulated channels.
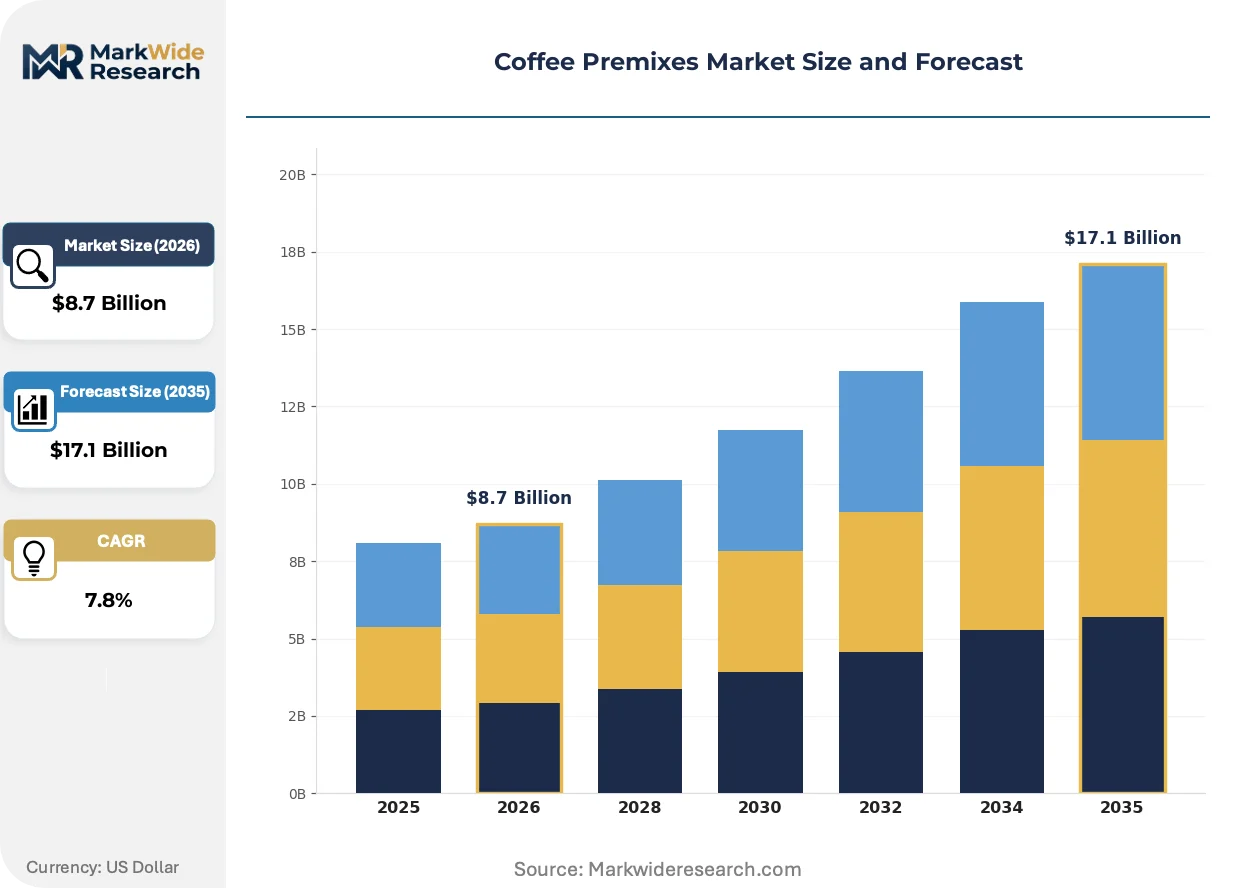
Market Dynamics
Equipment-locked consumption architectures are consolidating buyer loyalty around proprietary brewing systems, while regulatory pressure on added-sugar disclosure forces simultaneous reformulation across North American and European supply bases.
Growth Catalysts
- Single-serve format penetration:Corporate offices and hospitality chains are standardizing pod-based procurement to reduce preparation labor and portion inconsistency in high-volume service environments.
- FSSAI additive standardization:India's tightening packaging and ingredient safety mandates are legitimizing premium premix categories previously constrained by informal supply channels.
- Freeze-drying technology maturation:Advanced lyophilization protocols now preserve volatile aromatic compounds previously lost in spray-dried production, elevating sensory parity with fresh-brewed alternatives.
Market Restraints
- Arabica price volatility:Climate-induced yield compression in Brazilian and Colombian highland growing regions transmits directly to input cost instability for roast-dependent premix formulations.
- Multi-layer packaging dependency:Oxygen-barrier sachet constructions remain technically necessary for shelf stability yet face phased prohibition under EU Green Deal packaging waste directives.
- Equipment captivity risk:Proprietary pod geometries lock consumers into single-supplier ecosystems, creating switching friction that regulators in multiple jurisdictions are scrutinizing under competition frameworks.
Strategic Opportunities
- Ready-to-drink cold expansion:Refrigerated distribution infrastructure in Southeast Asian convenience retail remains underdeveloped relative to latent demand for chilled coffee occasions beyond traditional hot consumption.
- Functional ingredient convergence:Adaptogenic and nootropic additive integration creates hybrid positioning between beverage and supplement categories, accessing pharmacy and wellness retail channels.
- Extended producer responsibility frameworks:Early compliance with emerging take-back mandates in Germany and France secures shelf access ahead of mandatory implementation timelines.
Industry Challenges
- Flavor chemist scarcity:Formulation expertise bridging spray-drying engineering and sensory science commands premium compensation, constraining mid-tier manufacturer R&D throughput.
- Legacy system integration:Established instant coffee production lines require substantial retooling to accommodate pod filling precision and nitrogen-flush sealing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coffee Premixes Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instant Coffee Premix, Ready-to-Drink Coffee, Coffee Mixes, Coffee Pods Packaging Type: Single-Serve Packs, Bulk Packages, Sachets, Bottled Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Convenience Stores End User: Households, Cafés, Restaurants, Offices |
| Companies Covered | Nestlé, The Coca-Cola Company, Starbucks Corporation, Unilever, Tata Coffee, Mondelez International, Dunkin' Brands Group, illycaffè, J.M. Smucker Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coffee Premixes Market Emerging Trajectories
Formulation science and consumption architecture are diverging toward divergent quality tiers, with manufacturing sophistication determining competitive position more than brand equity alone.
Micro-ground suspension technology is bifurcating the soluble coffee category between commodity-grade spray-dried powders and premium offerings incorporating partially insoluble roast particulates. Specialty café chains and airport lounges are adopting these hybrid formats to replicate espresso-body mouthfeel without capital equipment requirements. The technology is bifurcating margin pools: mass-market players compete on unit economics while artisan-positioned suppliers capture disproportionate price realization through sensory differentiation.
REACH chemical registration requirements are compelling European premix manufacturers to audit full additive supply chains for SVHC contamination risk. Industrial consequence includes reformulation of caramel colorants and artificial flavor carriers previously grandfathered under legacy approvals. Ready-to-drink liquid concentrates face the steepest compliance burden due to higher water activity and corresponding preservative load requirements.
Workplace coffee service procurement is consolidating around integrated facility management contracts that bundle equipment, consumables, and technical service under single-source agreements. Traditional distributor networks serving independent offices face displacement by national facilities providers with direct supplier relationships. This pattern is most pronounced in India's technology corridor, where campus-scale deployments favor consolidated billing and predictive replenishment systems over transactional purchasing.
Coffee Premixes Market Segmentation
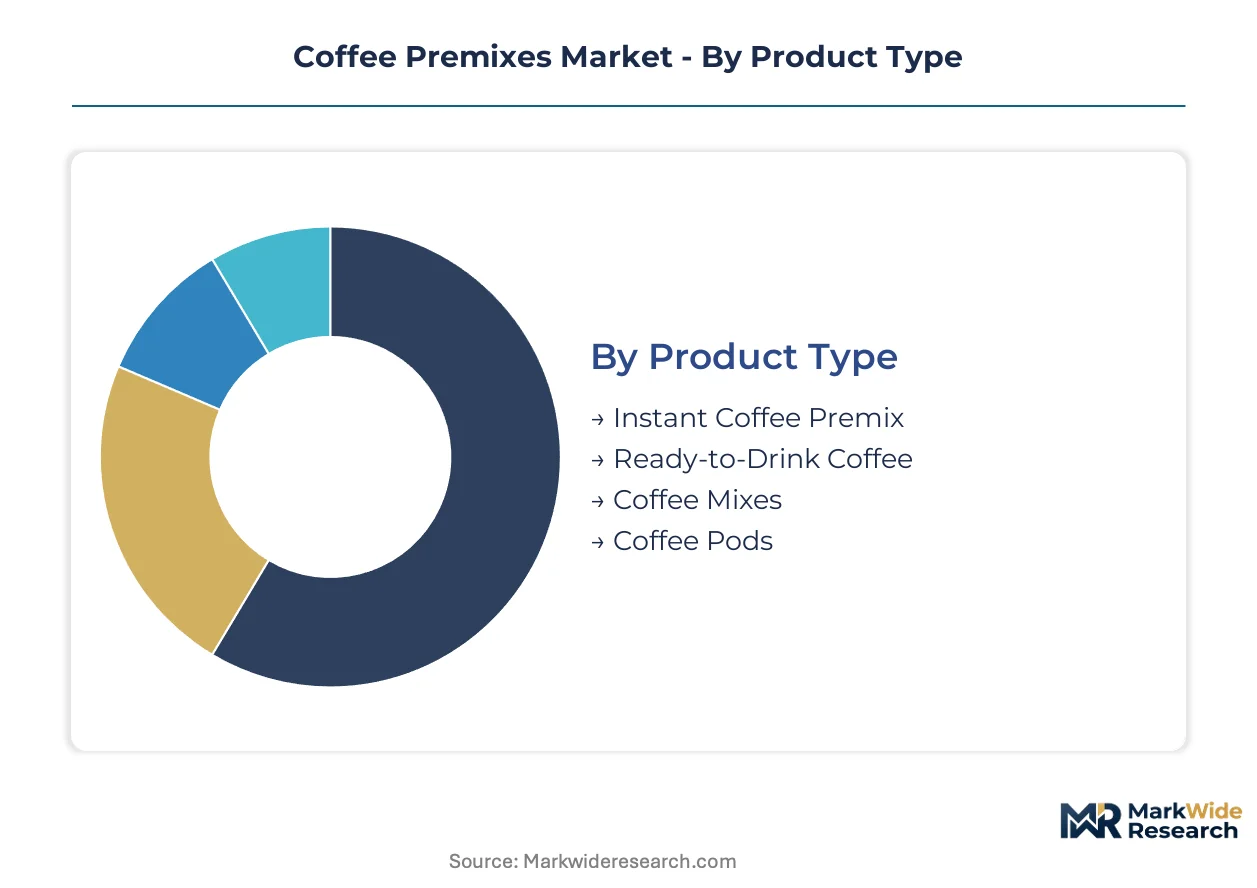
Segmentation in coffee premixes reveals how manufacturing capabilities, packaging constraints, and consumption occasions fragment addressable demand. Each dimension carries distinct margin profiles and regulatory exposure that shape supplier investment priorities.
Product Type:
Domestic production concentrates on instant formats serving price-sensitive household demand across India and Southeast Asia, while export-led growth in pods and ready-to-drink lines targets premium channels in Western Europe and North America.
- Instant Coffee Premix:Spray-dried or agglomerated formulations combining soluble coffee, dairy whiteners, and sweeteners for hot water reconstitution. Indian households and workplace canteens absorb the majority of volume, though Arabica input cost volatility compresses margins for mid-tier suppliers.
- Coffee Pods:Precision-ground coffee sealed in proprietary-format capsules requiring equipment-locked brewing systems. European hospitality procurement and North American office service channels drive demand, with repeat-purchase economics capturing disproportionate lifetime value per installed base.
- Ready-to-Drink Coffee:Pre-brewed liquid formulations in refrigerated or ambient-stable packaging. Latent demand in Southeast Asian convenience retail outpaces current cold-chain infrastructure.
- Coffee Mixes:Dry blends requiring consumer-supplied brewing equipment, spanning flavored and functional additive variants. Specialty store distribution in urban India and premium supermarket placement in Germany.
Instant Coffee Premix commands the established base. The steepest expansion runs through Ready-to-Drink Coffee.
Packaging Type:
Cost tier stratification separates single-unit convenience formats from bulk procurement systems, with regulatory pressure on multi-layer materials forcing capital retooling across European supply bases.
- Single-Serve Packs:Individual-portion sachets or stick packs engineered for precise dosing and portability. Corporate offices in India's technology corridor standardize procurement to reduce preparation labor and portion inconsistency.
- Bulk Packages:Institutional-size containers serving foodservice and workplace brewing stations. Cafés and restaurant chains in Brazil and Mexico favor this format for cost control over high-volume preparation.
- Sachets:Laminated foil pouches providing oxygen and moisture barriers for shelf stability. EU Green Deal packaging directives threaten existing multi-layer constructions.
- Bottled:PET or glass containers for liquid concentrates and ready-to-drink formulations. Refrigerated distribution requirements limit penetration in emerging markets.
Bulk Packages anchor foodservice procurement economics. Single-Serve Packs are gaining share fastest in workplace automation contracts.
Distribution Channel:
Customer type bifurcation splits between planned replenishment through modern retail and impulse acquisition through convenience proximity, with online platforms capturing subscription-driven household loyalty.
- Supermarkets:Multi-brand shelf space commanding slotting fees and promotional investment. Mass-market premix penetration in German and French retail chains.
- Online Retail:Direct-to-consumer platforms enabling subscription replenishment and specialty assortment access. Urban Indian households and North American convenience-seekers drive platform growth.
- Specialty Stores:Curated selection emphasizing provenance, roast profile, and artisan positioning. Premium pod and micro-ground formats in Japanese and South Korean urban centers.
- Convenience Stores:Immediate-need fulfillment for single-serve and ready-to-drink occasions. Underdeveloped cold-chain infrastructure constrains liquid format penetration in Indonesia and Philippines.
Supermarkets retain the volume foundation. Online Retail is climbing the fastest through subscription lock-in mechanics.
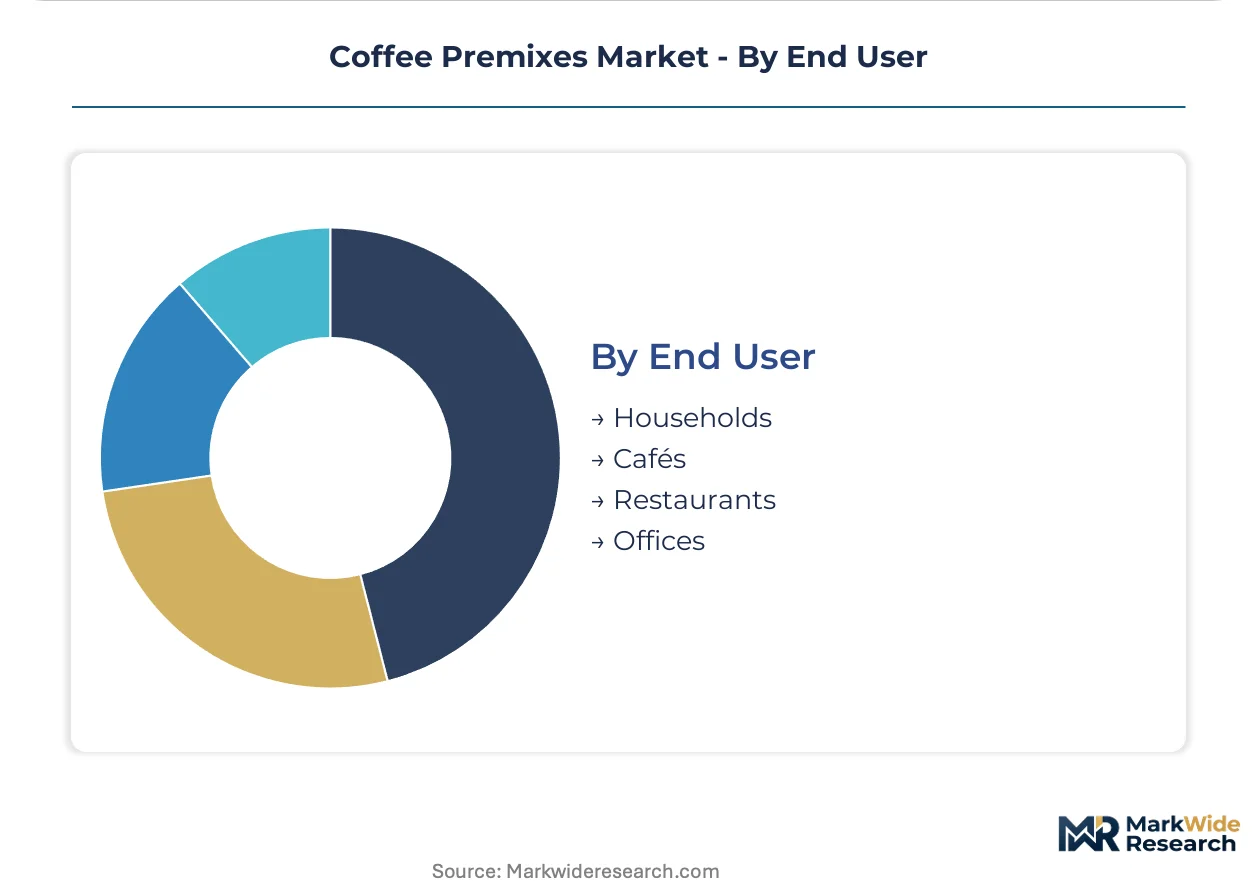
End User:
Application maturity separates established household consumption from institutional procurement consolidation, with integrated facility management contracts reshaping office and hospitality supply relationships.
- Offices:Workplace coffee service bundling equipment, consumables, and technical support under single-source agreements. India's campus-scale technology employers favor predictive replenishment over transactional purchasing.
- Households:Individual consumption spanning instant convenience and pod-based quality tiers. German and Italian households exhibit strongest pod system adoption.
- Cafés:Front-of-house service requiring rapid preparation consistency. Micro-ground suspension technology penetration in airport lounge and specialty chain deployment.
- Restaurants:Back-of-house integration with menu positioning and cost-per-portion targets. Mid-tier chains in the United States balance labor reduction against flavor differentiation.
Households represent the installed consumption base. Offices are expanding most quickly through facilities management consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows from Brazil and Vietnam supply raw coffee inputs to premix manufacturers worldwide, while finished premix consumption concentrates in industrialized economies with established workplace coffee services and refrigerated distribution infrastructure.
United States
Corporate office procurement and hospitality chain standardization drive single-serve pod demand. The FDA's updated added-sugar labeling requirements are forcing reformulation across North American supplier portfolios. Seattle and San Francisco anchor innovation clusters where micro-ground suspension technology penetrates airport lounge and specialty café deployments.
Germany
Workplace coffee service bundling and integrated facility management contracts consolidate procurement around predictive replenishment systems. The EU Green Deal's packaging waste directives are pressuring suppliers to eliminate multi-layer sachet constructions in favor of mono-material alternatives. The Rhine-Ruhr industrial corridor hosts reformulation activity as manufacturers audit additive supply chains for REACH SVHC compliance.
India
Café culture expansion and campus-scale technology employer procurement are scaling demand for instant and pod formats. The FSSAI's tightening additive limits and packaging standards are legitimizing premium premix categories previously constrained by informal supply channels. Bangalore and Hyderabad drive workplace automation contracts favoring consolidated billing over transactional purchasing.
Japan
Specialty store distribution and urban convenience retail sustain premium pod and micro-ground format demand. METI standards and JIS packaging specifications govern quality benchmarks for imported premix formulations. Tokyo and Osaka concentrate vending machine channel innovation and cold-brew ready-to-drink expansion.
Brazil
Domestic Arabica sourcing and roast-dependent formulation capabilities support regional supply integration. ANVISA nutritional labeling mandates align with Mercosur harmonization efforts for cross-border premix trade. São Paulo anchors both coffee commodity trading and downstream premix manufacturing for Latin American distribution.
Coffee Premixes Market Vendor Landscape
Concentration sits with multinational beverage conglomerates controlling proprietary brewing system architectures and captive repeat-purchase economics. The market structure tiered between equipment-locked pod ecosystems, mass-market instant formats, and emerging ready-to-drink liquid concentrates. Strategic archetypes include integrated coffee-to-premix estate operators, licensed brand formatters, and contract manufacturing specialists. Dominant competitive moves encompass M&A to secure roasting capacity and strategic partnerships to access cold-chain distribution infrastructure.
Within the integrated estate operator tier, Nestlé and Tata Coffee exemplify upstream control strategies. Nestlé's Swiss-based structure represents equipment-captive system architecture, while Tata Coffee's Indian incorporation illustrates estate-origin provenance differentiation. Among licensed brand formatters, Starbucks Corporation anchors retail-to-home bridge positioning. These three entities occupy distinct competitive positions without overlapping core competencies.
| Leading Market Players |
|---|
| Nestlé |
| The Coca-Cola Company |
| Starbucks Corporation |
| Unilever |
| Tata Coffee |
| Mondelez International |
| Dunkin' Brands Group |
| illycaffè |
| J.M. Smucker Company |
| Others |
Supply Flow & Price Mechanics
Ninety-day green coffee inventory cycles at Brazilian and Vietnamese export terminals directly shape roast-dependent premix cost structures and supplier pricing power across formulation tiers. This lead-time exposure concentrates margin vulnerability among mid-tier manufacturers lacking forward-contract coverage or estate-origin sourcing.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on Arabica input grade and freeze-drying certification tier. Cost compression in standard-tier spray-dried formulations is intensifying because Brazilian climate volatility transmits directly to spot market exposure. Foodservice procurement teams exhibit highest price sensitivity, while integrated facility management contracts demonstrate lowest sensitivity due to bundled service economics.
Supply Chain Analysis
Inventory concentration at Santos and Ho Chi Minh City export hubs exposes premix manufacturers to maritime logistics chokepoints. Raw material sourcing draws from Brazilian Arabica estates, Vietnamese Robusta cooperatives, and Indian dairy whitener processors. Single-source vulnerability concentrates in proprietary pod geometry licensing from Swiss equipment architects. Distribution runs through integrated facility management consolidators in India's technology corridor and European hospitality procurement networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized flavor chemist expertise bridging spray-drying engineering and sensory science commands premium compensation, constraining R&D throughput for mid-tier manufacturers and creating defensive moats for incumbents with captive formulation talent.
For Market Incumbents: Fortify estate-origin sourcing relationships in Brazilian highland growing regions to hedge Arabica price volatility exposure. Deepen backward integration into freeze-drying capacity ahead of sensory-differentiation competition from micro-ground suspension entrants. Prioritize FSSAI pre-certification investment to secure shelf placement in India's consolidating modern retail channels. For New Entrants and Emerging Players: Workplace predictive replenishment service gaps in Southeast Asian technology corridors offer white-space penetration before cold-chain infrastructure matures for ready-to-drink formats. Target India's campus-scale employer procurement through direct facility management partnerships bypassing traditional distributor networks. Lead with subscription-lock mechanics mirroring established North American platform economics. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across lyophilization equipment deployment as freeze-drying technology displaces commodity spray-dried production. Viable acquisition targets include contract manufacturing specialists with existing FSSAI certification and European REACH compliance infrastructure. Monitor EU Green Deal packaging directive implementation timelines as shelf-access inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Freeze-Drying Capacity Expansion | Elevates sensory parity with fresh-brewed alternatives in premium tier. |
| Mono-Material Packaging Transition | Secures EU market access ahead of Green Deal prohibition deadlines. |
| Integrated Facility Management Partnership | Captures India's campus-scale procurement consolidation wave. |
| Functional Additive Integration | Opens pharmacy and wellness retail channel access beyond beverage. |
| Estate-Origin Provenance Certification | Differentiates shelf placement in Asian markets where sourcing transparency commands premium. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs. Stakeholder roles included roasting facility managers, FSSAI compliance officers, workplace procurement directors at Indian technology employers, European hospitality chain beverage buyers, and flavor formulation chemists. Secondary validation drew from FDA labeling guidance documents, FSSAI additive standard notifications, EU Green Deal packaging directive texts, and Brazilian agricultural export statistics. Bottom-up volume modeling triangulated against top-down category spend estimates.
Across the analysis window, projections incorporate product type segmentation by instant, pod, ready-to-drink, and dry mix formats; packaging tier by single-serve, bulk, and liquid; and distribution channel by retail, online, and institutional procurement. CAGRs were derived from fitted growth curves calibrated to historical penetration rates and regulatory implementation timelines. Forecast inputs include Arabica futures price volatility bands and workplace automation contract adoption curves.
Forecasts assume regulatory continuity in FDA added-sugar disclosure regimes and FSSAI additive standard enforcement; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
India Coffee Roaster Market
Coffee
South Korea Coffee and Tea Capsules Market
Coffee
Coffee Pods Market
Coffee
China Coffee Market
Coffee
Ready to Drink (RTD) Coffee Market
Coffee
South America Coffee Market
Coffee
Coffee Roaster Market
Coffee
Europe Coffee Pods and Capsules Market
Coffee
Caffeine Market
Coffee
Oceania Coffee Market
Coffee
Coffee Grinder Market
Coffee
Freeze Dried Coffee Market
Coffee
Green Coffee Bean Extract Market
Coffee
Green Coffee Market
Coffee
Decaf Coffee Market
Coffee
Japan Coffee and Tea Capsules Market