
 South Korea Organic Food Market | 2026-2036
South Korea Organic Food Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Organic Food Market Insights
Domestic organic vegetable producers in Gyeonggi-do and Jeolla provinces is consolidating around cooperative processing hubs to secure year-round supply. CJ Cheiljedang leverages its refrigerated logistics network to anchor distribution across urban retail. Lotte Group competes through dedicated organic sections within its hypermarket footprint. RE:harvest Co., Ltd. differentiates via direct farm-to-table subscription channels targeting Seoul households.
Organic food denotes agricultural products cultivated without synthetic pesticides, chemical fertilizers, or genetically modified organisms, certified under national or international standards such as MFDS organic labeling or IFOAM equivalency. Cold-chain integrity and soil certification cycles define quality parameters for domestic market acceptance. Fruits and vegetables occupy the largest volume share given perishable logistics and consumer freshness expectations. Online distribution channels represent the fastest structural expansion, driven by platform consolidation and same-day delivery investments in the Seoul Capital Area.
MFDS administers organic certification and labeling enforcement, while the Ministry of Agriculture, Food and Rural Affairs coordinates producer subsidies and conversion programs. KOLAS-accredited testing laboratories verify residue compliance for import and domestic batches. Stakeholders must monitor evolving equivalency agreements with major exporting jurisdictions to anticipate supply cost shifts.
Market Dynamics
MFDS certification cycles and cold-chain infrastructure gaps are compressing margins for domestic producers while accelerating import dependency for processed organic goods.
Growth Catalysts
- MFDS Organic Label Expansion:The Ministry of Food and Drug Safety tightened equivalency standards with EU organic regulations, opening shelf access for certified imports in Seoul hypermarkets.
- Millennial Household Concentration:Dual-income families in the Seoul Capital Area now prioritize pesticide-free produce for children, driving subscription service adoption.
- Smart Cold-Chain Deployment:IoT-enabled temperature monitoring is converging with last-mile logistics, reducing spoilage rates for Jeolla-sourced vegetables reaching Busan retail.
Market Restraints
- Soil Conversion Cost Volatility:Three-year organic transition requirements for farmland in Gyeonggi-do impose capital lock-up that smallholders cannot absorb without cooperative backing.
- Import Concentration Risk:Domestic grain and processed organic categories rely on North American and Australian suppliers, exposing buyers to shipping rate fluctuations and currency swings.
- Certification Bottleneck:KOLAS-accredited laboratories face testing backlogs during harvest peaks, delaying batch release and compressing selling windows for perishables.
Strategic Opportunities
- Busan Retail Penetration:Premium supermarket chains in South Korea's second-largest metro area are expanding organic sections faster than Seoul saturation rates.
- Direct Subscription Channels:Farm-to-table platforms bypass traditional wholesale markups while capturing household data for harvest planning.
- National Eco-Label Integration:Ministry of Agriculture, Food and Rural Affairs subsidies for cooperative processing hubs reduce unit costs for packaged organic goods.
Industry Challenges
- Agronomist Talent Scarcity:Organic soil management expertise concentrates in Jeolla and Gyeongsang provinces, leaving northern cooperatives dependent on seasonal consultant contracts.
- Legacy ERP Integration:Small-scale producers struggle to connect farm management systems with retailer traceability portals, blocking automated purchase order flows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Organic Food Market |
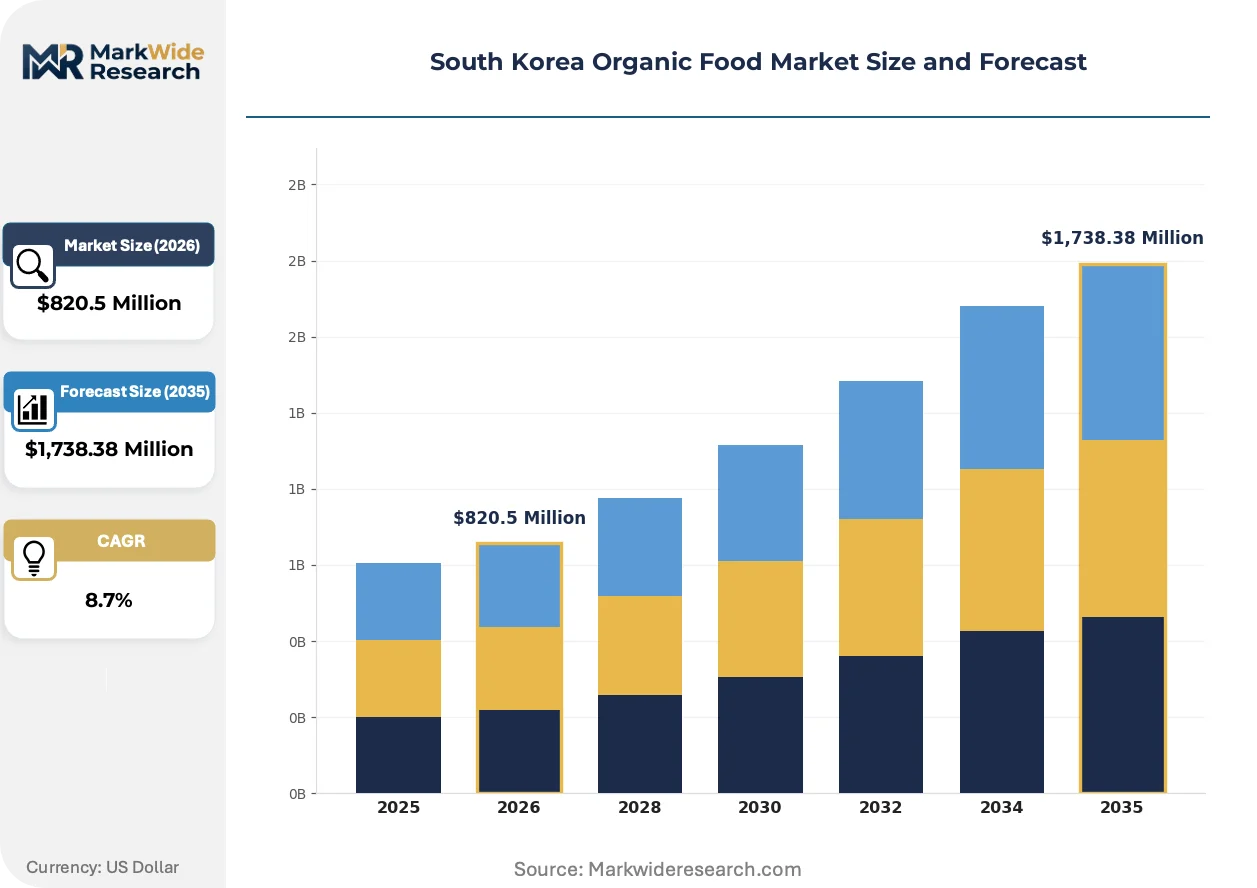
| Market Size in 2026 | $820.5 Million |
| Market Size in 2035 | $1,738.38 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruits, Vegetables, Grains, Dairy Packaging Type: Boxes, Bags, Containers, Jars Distribution Channel: Online, Supermarkets, Farmers' Markets, Health Stores Customer Type: Families, Health Conscious Consumers, Vegetarians, Organic Enthusiasts |
| Companies Covered | joinandjoin, Estee Retail, Lotte Group, Mbiometherapeutics Ltd, RE:harvest Co., Ltd., CJ Cheiljedang, The PlantEAT, Livfarm, Samyang Foods, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Organic Food Market Trends and Innovations
Blockchain traceability and AI-driven demand forecasting are rewriting procurement relationships between regional cooperatives and urban retail chains.
Blockchain-based provenance tracking is converging with retailer loyalty programs, allowing Seoul households to verify farm origin via smartphone scan. Department store chains are piloting this integration to justify premium shelf pricing. The technology is converging with existing cold-chain databases, creating unified compliance records that satisfy both MFDS auditors and export equivalency checks.
MFDS revised its organic processed food labeling rules in alignment with Codex Alimentarius standards, forcing domestic manufacturers to reformulate or lose certification. This regulatory tightening disproportionately affects sauce and condiment producers using imported organic concentrates. Smaller processors in the Seoul Capital Area are responding by consolidating formulation R&D through regional cooperative alliances.
Subscription-based replenishment is displacing discretionary supermarket purchases for core organic vegetables among dual-income households. Direct-to-consumer platforms capture recurring revenue while reducing price sensitivity through fixed-bundle pricing. This behavioral shift is most pronounced in Seoul satellite cities where commute times limit physical shopping frequency.
South Korea Organic Food Market Segmentation
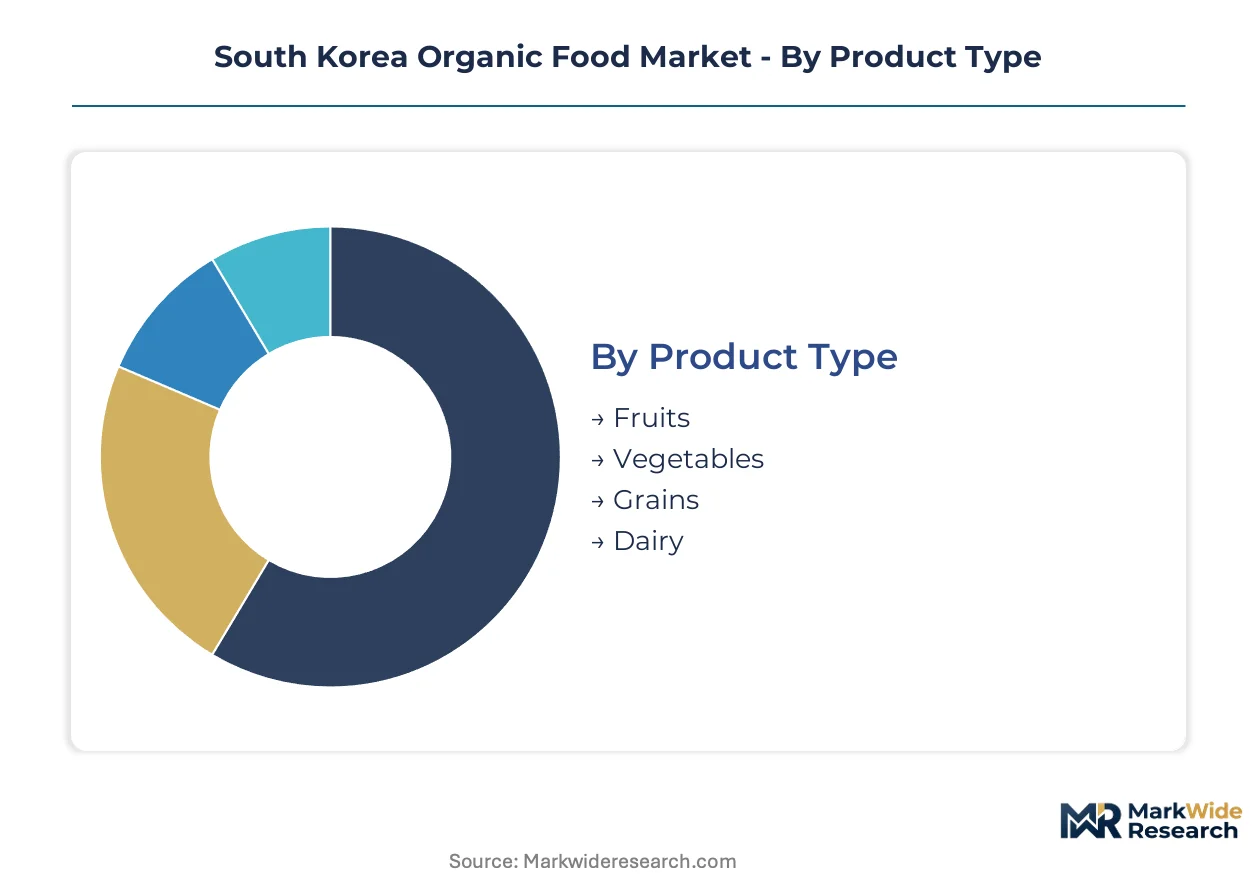
Segmentation in South Korea's organic food market reveals how certification tiers, packaging formats, and channel strategies align with distinct household purchasing patterns across the Seoul Capital Area and secondary metros. Understanding these divisions exposes where margin compression and premium capture opportunities concentrate for producers and retailers.
Product Type:
Standardization dominates at the commodity level, while premium differentiation emerges through certification depth and regional provenance claims within each product class.
- Fruits:Citrus, apples, and pears from Jeolla province orchards carry MFDS organic labels with full traceability documentation. Seoul hypermarkets command shelf premiums for domestically certified stone fruits during summer harvest windows, though import dependency for tropical varieties persists year-round.
- Vegetables:Leafy greens and root vegetables from Gyeonggi-do cooperative networks supply the bulk of institutional and retail volume. Perishable logistics constraints limit northern production expansion, concentrating processing hub investment in Jeolla's milder climate zones.
- Grains:Rice and barley conversion lags behind horticulture due to three-year soil transition requirements and water management complexity.
- Dairy:Organic milk and fermented products face raw material scarcity, with domestic herd conversion proceeding slowly against feed cost volatility.
Most installed capacity flows through Vegetables. Expansion is steepest in Fruits as direct subscription platforms capture household replenishment demand.
Packaging Type:
Cost tier stratification separates bulk commodity formats from premium presentation layers that justify retail markup in department store food halls.
- Boxes:Corrugated and rigid paperboard formats dominate e-commerce fulfillment for subscription vegetable bundles. Temperature-controlled box specifications with phase-change liners have become standard for Seoul same-day delivery services, adding unit cost but reducing spoilage claims.
- Bags:Flexible pouches and woven sacks handle grain and dried produce distribution through traditional wholesale channels. Compostable film investments are rising among processors seeking national eco-label qualification for packaged goods subsidies.
- Containers:Reusable rigid packaging pilots in Busan retail chains test deposit-return systems for prepared organic salads.
- Jars:Glass packaging concentrates in fermented and preserved categories where shelf stability extends selling windows for small-batch producers.
Volume concentrates in Bags for commodity movement. Value capture is climbing fastest in Boxes as last-mile cold-chain requirements harden.
Distribution Channel:
Customer type and geography together determine channel selection, with platform consolidation in Seoul diverging from cooperative-direct models in provincial markets.
- Online:Platform consolidation around major e-commerce players has concentrated same-day delivery investment in the Seoul Capital Area. Subscription bundling reduces price sensitivity while generating harvest planning data for cooperative suppliers.
- Supermarkets:Dedicated organic sections within Lotte and CJ-affiliated hypermarkets anchor mass-market access. Shelf space expansion in Busan outpaces Seoul saturation, drawing processor investment toward the second metro area.
- Farmers' Markets:Direct producer presence persists in Jeolla and Gyeongsang provinces where cooperative infrastructure supports weekend retail logistics.
- Health Stores:Specialized retail concentrates imported organic supplements and processed goods for consumer segments seeking international certification equivalency.
Transaction volume runs deepest through Supermarkets. Share gains are expanding most quickly in Online as millennial household penetration deepens.
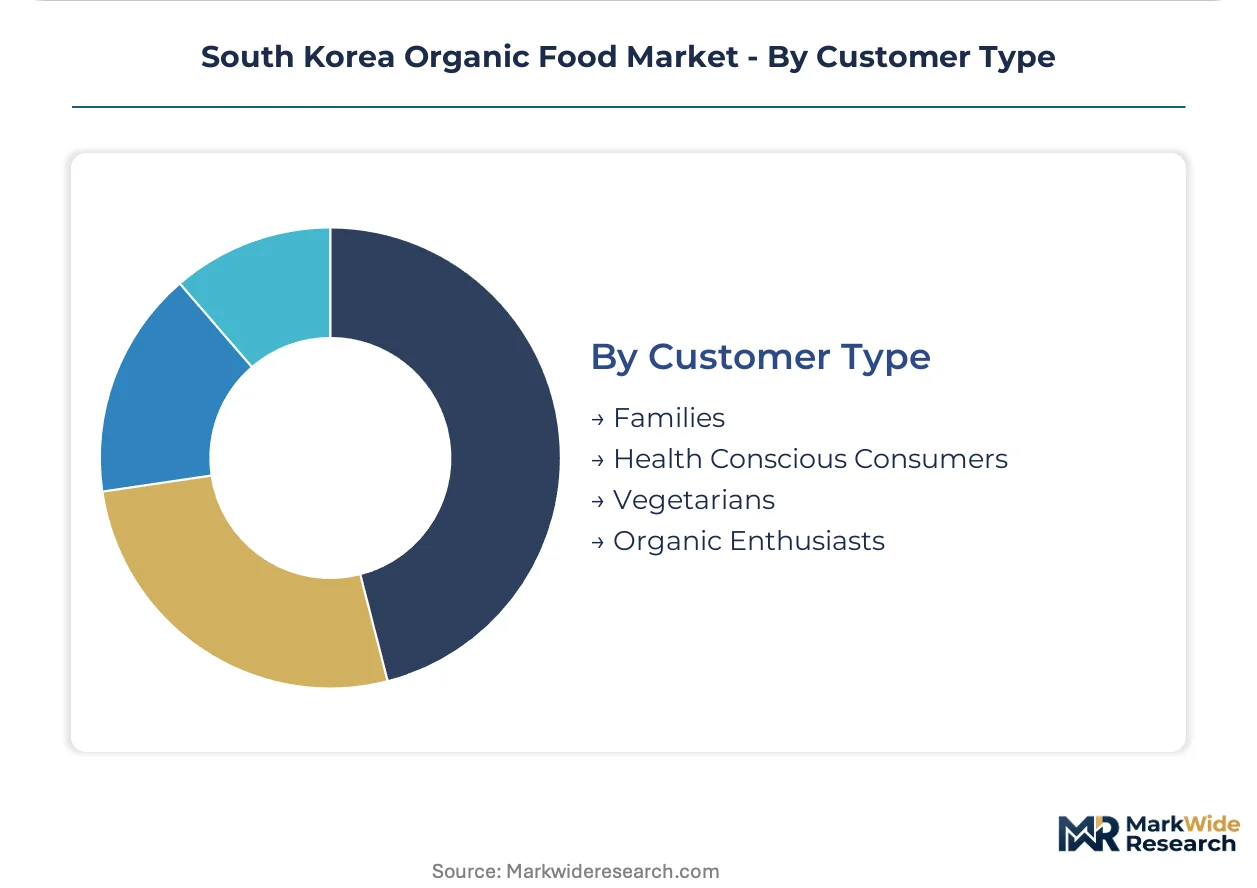
Customer Type:
Application context and purchasing frequency separate one-time trial buyers from locked-in subscription households with predictable replenishment patterns.
- Families:Dual-income households with children in Seoul satellite cities drive core vegetable subscription adoption. Pesticide-free claims for child nutrition justify 30-50% price premiums over conventional produce in purchase decisions.
- Health Conscious Consumers:Fitness-oriented millennials prioritize protein and supplement categories, cross-shopping organic produce with functional food products.
- Vegetarians:Plant-forward dietary commitment elevates organic legume and grain demand above baseline replacement rates.
- Organic Enthusiasts:Certification purists scrutinize MFDS label integrity and equivalency documentation, accepting supply constraints for verified provenance.
Recurring revenue concentrates with Families. Acquisition investment is flowing most heavily toward Health Conscious Consumers as platform marketing pivots toward lifestyle positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting organic production toward provinces where MFDS certification costs and soil conversion timelines compress competitive positioning. Producers in Jeolla and Gyeongsang regions exploit climatic advantages and existing cooperative infrastructure to offset Seoul Capital Area land scarcity.
Seoul Capital Area
Dual-income millennial households in Seoul, Incheon, and Gyeonggi-do drive premium pricing for certified organic vegetables and subscription-based replenishment services. MFDS labeling enforcement concentrates testing laboratory capacity in this corridor, creating compliance bottlenecks during harvest peaks. E-commerce platform consolidation and same-day cold-chain delivery investments cluster in Seoul satellite cities where commute constraints limit physical retail access.
Busan-Ulsan
Premium supermarket chains in South Korea's second-largest metro area are expanding organic shelf space faster than Seoul saturation rates. Gyeongsang province producers leverage Busan port logistics for import-export equivalency documentation. Dedicated organic sections within major retail footprints are drawing processor investment away from the capital corridor.
Daegu-Gyeongbuk
Apple and pear orchard conversion is accelerating in this southeastern cluster as stone fruit producers respond to Seoul wholesale premium pricing. The region's milder climate supports extended growing seasons that reduce perishable logistics pressure. Cooperative processing hubs in Gyeongbuk are consolidating smallholder output to meet MFDS batch certification minimums.
Daejeon-Sejong
Administrative proximity to national regulators positions this central corridor as a policy pilot zone for organic equivalency standard harmonization. Chungcheong province grain producers face delayed conversion timelines due to three-year soil transition requirements and water management complexity. Research institutions in Daejeon are anchoring agronomist training programs to address northern cooperative talent scarcity.
Gwangju-Honam
Jeolla province anchors domestic organic vegetable volume through cooperative networks that supply year-round leafy greens and root crops. Climatic stability and established cold-chain infrastructure reduce spoilage rates for shipments reaching Busan and Seoul retail. National eco-label subsidy programs administered by the Ministry of Agriculture, Food and Rural Affairs concentrate processing hub investment in this southwestern cluster.
South Korea Organic Food Market Competitive Landscape
Seoul Capital Area conglomerates anchor one tier; Jeolla province cooperative specialists hold cost-advantaged supply positions. Market structure bifurcates between diversified food groups with refrigerated logistics networks and subscription-native platforms with direct farm relationships. Three archetypes dominate: legacy conglomerate affiliates leveraging retail footprint, cooperative-backed regional processors, and digital-native direct-to-consumer operators. Competitive moves concentrate on cold-chain infrastructure deployment and subscription platform technology licensing.
Within the diversified food group tier, CJ Cheiljedang and Lotte Group represent integrated distribution archetypes. RE:harvest Co., Ltd. exemplifies the direct subscription model targeting Seoul households. These three entities occupy distinct competitive positions: conglomerate affiliates anchor mass retail access, while the subscription specialist captures recurring revenue through farm-to-table data integration.
| Leading Market Players |
|---|
| joinandjoin |
| Estee Retail |
| Lotte Group |
| Mbiometherapeutics Ltd |
| RE:harvest Co., Ltd. |
| CJ Cheiljedang |
| The PlantEAT |
| Livfarm |
| Samyang Foods |
| Others |
Pricing and Supply Chain Analysis
Certification-tier bifurcation between MFDS organic labels and conventional produce creates parallel pricing architectures that reshape procurement relationships across South Korea. Premium capture concentrates in Seoul Capital Area subscription channels where cold-chain investments justify markup separation from wholesale commodity flows.
Pricing Analysis
Retailer markup layers dominate downstream pricing, with Lotte and CJ-affiliated hypermarkets commanding 25-40% shelf premiums over cooperative direct sales. Price differentiation hinges on MFDS certification depth and last-mile cold-chain integrity, not brand recognition alone. Pricing pressure stems from KOLAS laboratory testing backlogs that compress selling windows for Jeolla-sourced perishables. Health-conscious millennial families show lowest price sensitivity for child-targeted vegetable bundles, while institutional buyers in school feeding programs drive hardest bargain negotiations.
Supply Chain Analysis
Agronomist talent scarcity in Gyeonggi-do and northern provinces forces cooperatives into expensive seasonal consultant contracts that inflate unit economics. Domestic vegetable supply concentrates in Jeolla and Gyeongsang provinces, while processed grain categories draw from Australian and North American organic exporters. Raw material dependencies span three-year soil conversion cycles for domestic rice, imported organic feed for dairy herds, and phase-change cold-packaging for e-commerce fulfillment. Supply chain risk centers on single-source vulnerability for KOLAS-accredited testing capacity during harvest peaks. Distribution runs through platform-consolidated online channels in Seoul and cooperative-direct wholesale networks in provincial markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Korea's organic food market compounds steadily as MFDS regulatory alignment with EU standards locks in certification infrastructure investment. Millennial household formation in Seoul satellite cities provides predictable demand expansion.
For Market Incumbents: Cement cold-chain infrastructure advantages by deploying IoT-enabled temperature monitoring across Jeolla-to-Seoul logistics corridors before subscription-native platforms achieve comparable coverage. Lock in cooperative processing hub partnerships in Gwangju-Honam to defend against RE:harvest-style farm-to-table disintermediation. Prioritize MFDS equivalency documentation investments to maintain shelf access against tightening import standards. For New Entrants and Emerging Players: MFDS organic label expansion in alignment with EU regulations opens a window for specialized import-export arbitrage in processed organic categories where domestic reformulation lags. Target Busan-Ulsan retail penetration where premium supermarket organic sections expand faster than Seoul saturation rates. Pursue direct subscription channel development with fixed-bundle pricing to capture recurring revenue and harvest planning data integration. For Investors and Strategic Acquirers: Consolidation pressure builds where cooperative processing hubs face capital constraints for MFDS batch certification minimums and cold-chain equipment upgrades. Five-to-ten-year viability favors acquisition of Jeolla-based regional processors with established farmer networks and existing eco-label subsidy qualification. Watch KOLAS laboratory capacity expansion announcements as inflection indicator for perishable logistics margin compression relief.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Deployment | IoT temperature monitoring reduces spoilage for Jeolla-sourced vegetables reaching Seoul retail. |
| Cooperative Processing Hub Consolidation | Shared MFDS certification facilities lower unit costs for Gyeonggi-do smallholder networks. |
| Direct Subscription Channel Launch | Farm-to-table platforms capture household data while bypassing Lotte and CJ wholesale markups. |
| MFDS Equivalency Documentation Investment | EU-aligned certification secures import shelf access in Seoul hypermarket chains. |
| Blockchain Traceability Integration | Provenance tracking justifies premium pricing through smartphone-verified farm origin. |
Research Methodology
Coverage spans Seoul Capital Area, Busan-Ulsan, and Jeolla province clusters, with primary inputs from each. The analysis combines structured interviews with cooperative processing managers, MFDS regulatory affairs specialists, hypermarket category buyers, cold-chain logistics operators, and agronomist consultants. Secondary validation draws from MFDS certification registry data, Ministry of Agriculture subsidy disbursement records, KOLAS laboratory accreditation filings, and customs import documentation for organic grain categories. Bottom-up cooperative volume aggregation and top-down retail channel revenue estimates undergo triangulation against national eco-label program participation statistics.
Rate-of-change decomposition separates volume expansion from price-mix effects across the projection horizon. The analytical framework models five segmentation dimensions: product type, packaging format, distribution channel, customer archetype, and regional production cluster. CAGRs derive from logistic curve fitting to historical certification growth rates and household penetration benchmarks. Industry-specific forecast inputs include MFDS equivalency agreement negotiation timelines and cold-chain infrastructure investment pipelines from major logistics affiliates.
Revisions become necessary when MFDS regulatory harmonization delays, KOLAS laboratory capacity constraints, or cooperative financing disruptions materialize beyond modeled scenarios. Material deviation in these named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Food and Beverages
UAE Organic Food Market
Organic Food and Beverages
Organic Ice Cream Market
Organic Food and Beverages
Germany Organic Food Market
Organic Food and Beverages
Spain Organic Food Market
Organic Food and Beverages
Global Organic Food Market
Organic Food and Beverages
Australia Organic Food Market
Organic Food and Beverages
Organic Coconut Sugar Market
Organic Food and Beverages
Global Organic Chocolate Spreads Market
Organic Food and Beverages
Organic Rice Syrup Market
Organic Food and Beverages
India Organic Food Market
Organic Food and Beverages
Organic Dry Yeast Market
Organic Food and Beverages
South Africa Organic Food Market
Organic Food and Beverages
Organic Food and Beverages Market
Organic Food and Beverages
Global Natural and Organic Food Market
Organic Food and Beverages
Global Organic Coconut Water Market
Organic Food and Beverages
Asia-Pacific Organic Food Market