
 Global Coffee Machine Market | 2026-2036
Global Coffee Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Coffee Machine Market Analysis
The HoReCa vertical is pivoting toward fully automatic systems with integrated grinder-doser units to reduce labor costs during peak morning rushes. De'Longhi Group leverages its Italian manufacturing heritage to dominate the prosumer segment with dual-boiler thermal architectures. Nestlé Nespresso sustains its capsule ecosystem through proprietary brewing geometry and direct-to-consumer subscription channels. JURA Elektroapparate anchors the premium office category with pulse extraction process technology and connected fleet management platforms.
A coffee machine is an electromechanical appliance that heats water to precise temperatures, typically between 195°F and 205°F, and forces it through ground coffee under controlled pressure to extract soluble compounds for beverage preparation. The device serves commercial foodservice operations, workplace environments, and residential kitchens where consistency, speed, and flavor profile control determine utility value. Espresso machines command the highest margin pools due to pressure system complexity and maintenance attachment revenue. Single serve machines compete on convenience density but face structural pressure from capsule waste regulations in multiple jurisdictions. Smart coffee makers represent the fastest-expanding technology tier as app-connected scheduling and bean-to-cup telemetry redefine user interaction models.
FDA food-contact material standards govern brew chamber and tubing compositions in the United States, while the EU Ecodesign Directive and F-Gas Regulation constrain refrigerant-based milk cooling systems and standby power consumption across European markets. REACH compliance requirements for nickel and chromium migration from brass boiler components directly influence supplier qualification timelines and material substitution strategies. Stakeholders must monitor evolving extended producer responsibility frameworks for appliance recycling and the interoperability standards that could unlock or fragment IoT platform ecosystems.
Market Dynamics
Hybrid work normalization has fragmented coffee consumption across residential and corporate touchpoints, forcing manufacturers to engineer dual-purpose platforms that bridge premium home brewing with scalable office fleet management.
Growth Catalysts
- EU Ecodesign Directive:Stringent standby power limits accelerate R&D investment in ultra-efficient thermoblock architectures, compressing energy draw during idle states.
- Bean-to-cup telemetry:IoT-enabled consumption tracking allows operators to optimize replenishment cycles and predict maintenance intervals with precision.
- Germany:Dense café culture and high disposable income density sustain replacement demand for prosumer-grade equipment with integrated grinder systems.
Market Restraints
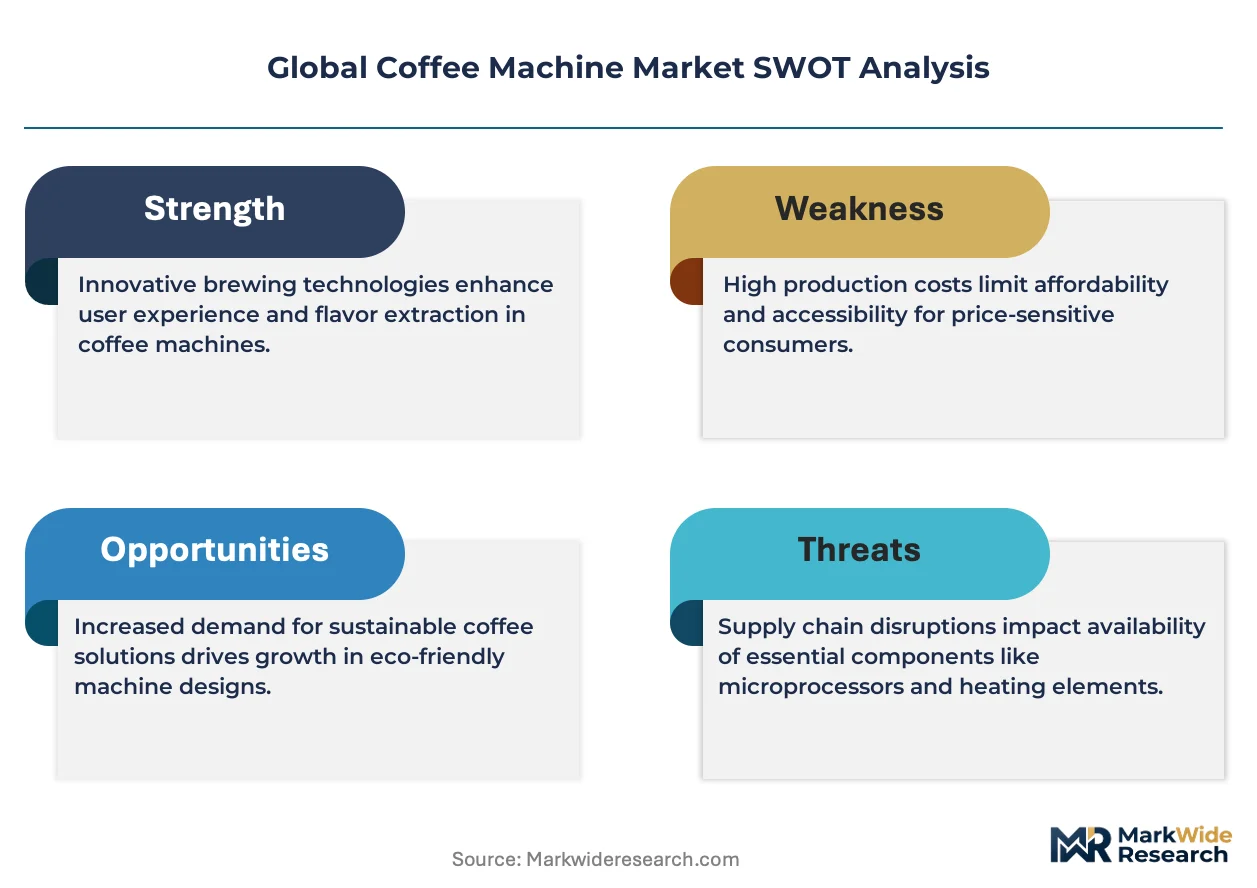
- Brass alloy supply concentration:REACH compliance testing for nickel and chromium migration extends supplier qualification timelines by 8-14 months.
- Capsule waste regulations:Extended producer responsibility frameworks in France and Italy impose end-of-life collection costs that erode single-serve margin structures.
- Refrigerant constraints:EU F-Gas Regulation phases down hydrofluorocarbon availability, complicating integrated milk cooling system design for super-automatic platforms.
Strategic Opportunities
- India:Underpenetrated premium residential segment offers whitespace as urban household appliance penetration accelerates in tier-one cities.
- Direct-to-consumer subscription:Recurring revenue models for consumables and predictive maintenance contracts reduce customer acquisition cost volatility.
- AI-driven grind calibration:Convergence of computer vision and pressure profiling enables real-time extraction optimization without barista intervention.
Industry Challenges
- Mechatronics talent scarcity:Shortage of engineers fluent in both fluid dynamics and embedded systems delays connected platform development cycles.
- Multi-jurisdiction certification:Simultaneous FDA food-contact review and CE marking processes create launch timeline misalignment across Atlantic markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Coffee Machine Market |
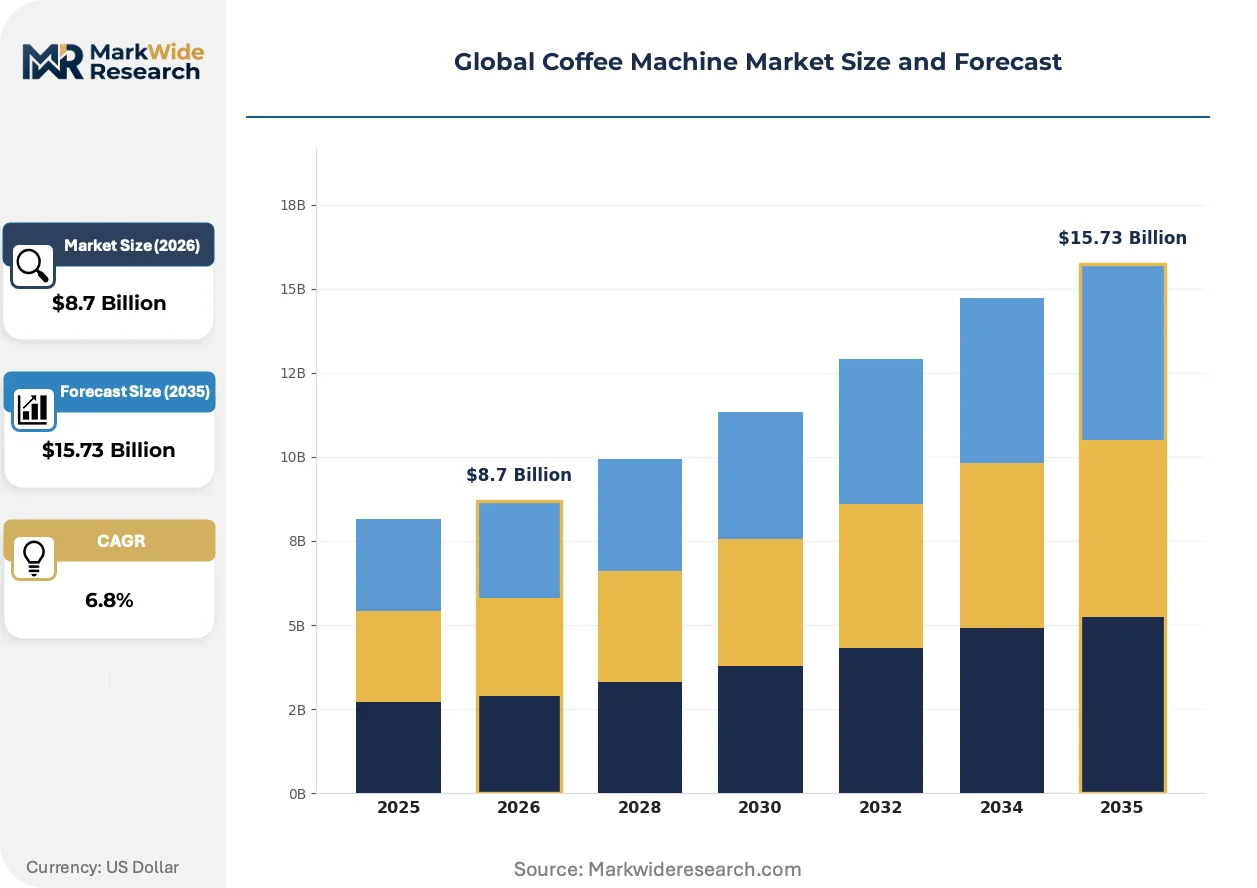
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Espresso Machines, Drip Coffee Makers, Single Serve Machines, French Press Technology: Manual, Semi-Automatic, Fully Automatic, Smart Coffee Makers End User: Households, Commercial, Offices, HoReCa Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Panasonic, Melitta Group, Keurig Dr Pepper, JURA Elektroapparate, Groupe SEB, Nestlé Nespresso, Electrolux, La Marzocco, De'Longhi Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Coffee Machine Market Emerging Trajectories
Electromechanical brewing architectures are converging with digital layer intelligence, compressing the traditional separation between hardware performance and software-mediated user experience.
Pulse extraction process technology is unifying pressure profiling with real-time flow rate modulation to deliver consistent crema density across varying bean roast profiles. Workplace fleet operators in the United States deploy these systems to standardize beverage output across geographically dispersed installations. The capability is compressing differentiation between premium office equipment and entry-level commercial units.
REACH substance restrictions on nickel alloy migration are forcing boiler manufacturers toward stainless steel and coated aluminum alternatives with equivalent thermal conductivity. German component suppliers face extended validation cycles as they recertify material stacks for ECHA compliance. Super-automatic platforms with integrated brewing chambers experience the most acute reformulation pressure.
Service unbundling now separates equipment ownership from maintenance obligation through outcome-based contracts tied to uptime guarantees. Corporate procurement teams in Italy negotiate availability metrics rather than capital expenditure thresholds. The shift concentrates vendor risk while transferring operational complexity to OEM service networks.
Global Coffee Machine Market Segmentation
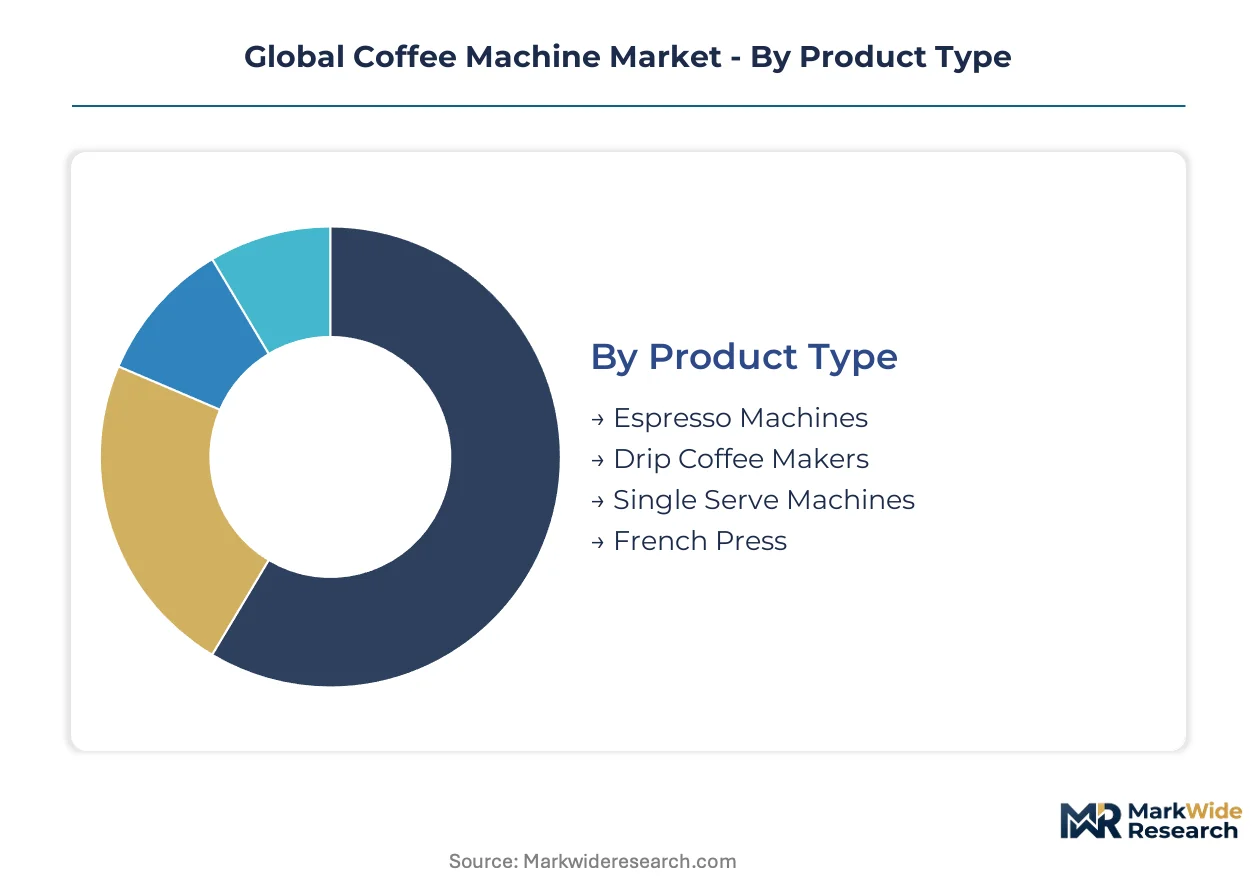
Segmentation in the coffee machine market reveals how brewing technology, purchase context, and user sophistication intersect to create distinct margin pools and loyalty dynamics. Manufacturers must align R&D investment and channel strategy with the specific performance thresholds and service expectations of each slice.
Product Type:
Supply concentration in pump and boiler components favors platforms with standardized pressure architectures that scale across multiple price tiers.
- Espresso Machines:Pressure systems operating at 9-bar extraction with thermoblock or dual-boiler thermal management define this category. Demand concentrates in Italy and Germany where café culture sustains prosumer investment in portafilter-based ritual. REACH compliance on brass alloys extends supplier qualification timelines for boiler manufacturers serving this segment.
- Drip Coffee Makers:Gravity-fed brewing through paper or metal filters with programmable heating elements dominates North American residential kitchens. Volume manufacturing in China supplies the sub-premium tier while German engineering anchors the thermal carafe premium segment.
- Single Serve Machines:Proprietary capsule ecosystems lock consumers into recurring consumables purchases. France and Italy impose extended producer responsibility frameworks that erode margin structures through end-of-life collection mandates.
- French Press:Immersion brewing without electrical components appeals to outdoor enthusiasts and minimalists. Stainless steel and borosilicate glass construction bypasses electronic regulatory complexity entirely.
Today's leader: Espresso Machines. Tomorrow's challenger: Smart-enabled Single Serve platforms with biodegradable capsule alternatives.
Technology:
Automation intensity determines the embedded software content and service revenue potential of each platform tier.
- Manual:Lever-operated spring piston systems demand operator skill for pressure profiling. Artisan coffee bars in Melbourne and Copenhagen deploy these for theatrical brewing rituals that justify premium beverage pricing.
- Semi-Automatic:Electric pump delivery with manual grind dosing and tamping bridges hobbyist control with consistent pressure. This tier captures the largest installed base in the United States residential prosumer segment.
- Fully Automatic:Integrated grinder-doser units with one-touch beverage selection reduce labor costs in German office environments and Italian HoReCa operations during morning rush compression.
- Smart Coffee Makers:IoT-enabled scheduling, bean-to-cup telemetry, and predictive maintenance contracts redefine user interaction models. These platforms are climbing the fastest as workplace fleet operators demand centralized consumption analytics across dispersed installations.
Fully Automatic systems command the highest average selling prices. Smart Coffee Makers are gaining share fastest through subscription-linked revenue models.
End User:
Usage intensity and beverage variety requirements fragment engineering priorities across residential and commercial contexts.
- Households:Compact footprint and aesthetic integration with kitchen design drive purchase decisions. German consumers prioritize integrated grinder systems while Japanese buyers emphasize silent operation for dense urban housing.
- Commercial:High-throughput durability with rapid recovery between extractions serves independent cafés in Rome and São Paulo. NSF certification and local health authority compliance add qualification layers.
- Offices:Hybrid work normalization has compressed daily consumption into narrower windows, demanding faster cycle times. United States corporate procurement teams negotiate outcome-based contracts tied to uptime guarantees rather than capital expenditure thresholds.
- HoReCa:Hotels, restaurants, and catering operations require multi-beverage capability with minimal staff training. Super-automatic platforms with integrated milk cooling dominate this segment despite EU F-Gas Regulation constraints on hydrofluorocarbon refrigerants.
Offices represent the steepest expansion trajectory as hybrid work models stabilize. Commercial remains the most demanding on durability specifications.
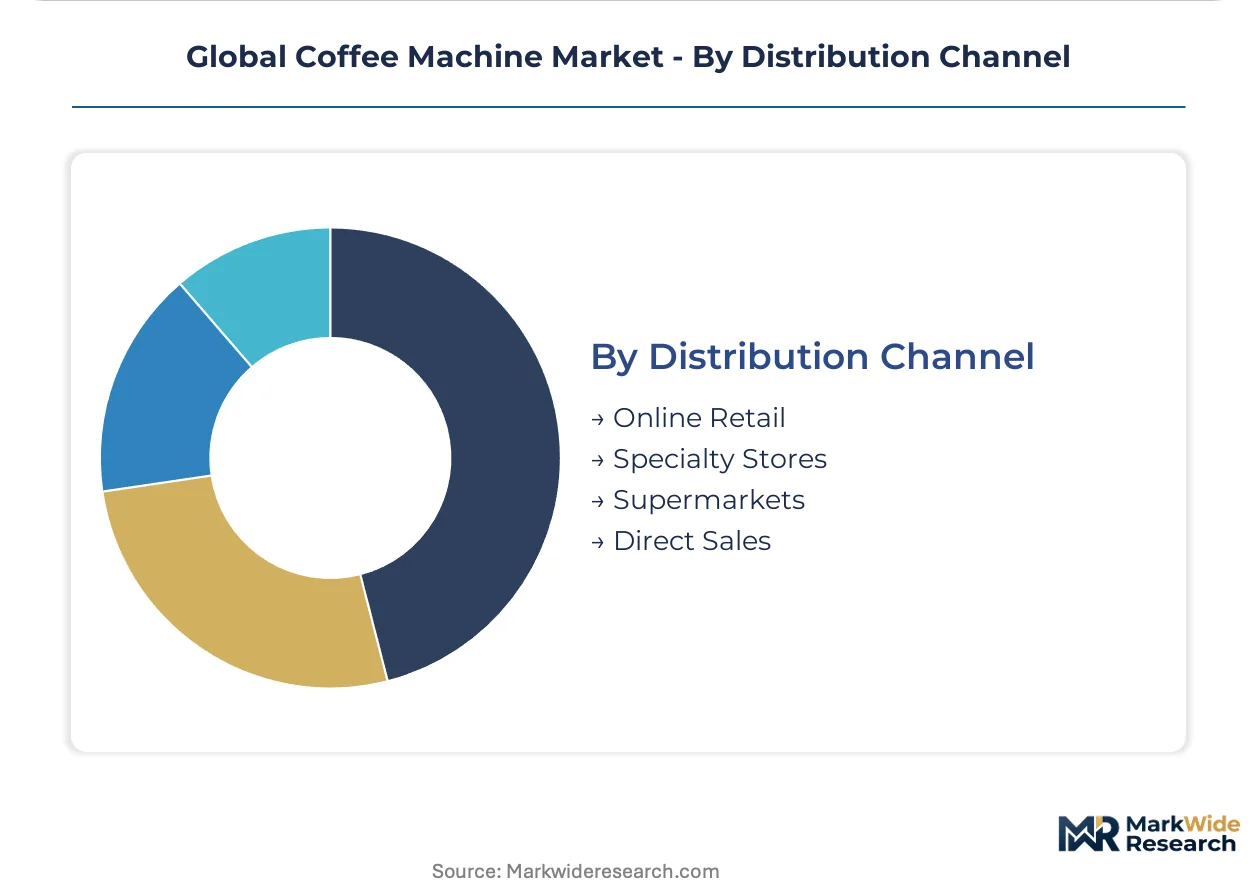
Distribution Channel:
Channel selection shapes margin capture and customer relationship depth through the ownership lifecycle.
- Online Retail:Amazon and direct-to-consumer platforms enable subscription bundling of machines with recurring consumables. This channel is expanding most quickly in India as urban household appliance penetration accelerates.
- Specialty Stores:Curated assortment with hands-on demonstration supports premium positioning. Blue Bottle and Intelligentsia retail locations in Los Angeles and Chicago drive conversion through tasting experiences.
- Supermarkets:Mass-market drip and single-serve machines compete on shelf placement and promotional pricing. Walmart and Target in the United States dominate volume throughput.
- Direct Sales:B2B fleet contracts with integrated service agreements concentrate vendor risk while transferring operational complexity to OEM networks. JURA and Franke deploy this model for workplace installations across Switzerland and Germany.
Direct Sales commands the highest lifetime value per account. Online Retail is disrupting fastest through IoT-enabled replenishment automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian espresso heritage clusters anchor manufacturing excellence across Lombardy and Veneto, where centuries of craft knowledge concentrate pressure-system engineering talent. German thermal engineering dominance in Baden-Württemberg and North Rhine-Westphalia shapes boiler architecture standards. United States workplace fleet operators drive connected platform adoption through outcome-based procurement models.
United States
Corporate procurement teams negotiate uptime-guaranteed service contracts rather than capital expenditure thresholds for workplace installations. FDA food-contact material standards govern brew chamber and tubing compositions, extending qualification timelines for brass alloy suppliers. Seattle and San Francisco clusters concentrate smart coffee maker development as hybrid work models stabilize consumption patterns across residential and office touchpoints.
Germany
Dense café culture and high disposable income density sustain replacement demand for prosumer-grade equipment with integrated grinder systems. EU Ecodesign Directive standby power limits accelerate R&D investment in ultra-efficient thermoblock architectures across Baden-Württemberg engineering centers. REACH compliance testing for nickel and chromium migration from brass boiler components extends supplier qualification timelines by 8-14 months.
Italy
HoReCa operations pivot toward fully automatic systems with integrated grinder-doser units to reduce labor costs during peak morning rushes. Extended producer responsibility frameworks impose end-of-life collection costs that erode single-serve margin structures. Milan and Turin manufacturing clusters dominate prosumer segment engineering through dual-boiler thermal architectures and heritage craft knowledge.
China
Volume manufacturing of drip coffee makers supplies the sub-premium tier for North American residential kitchens. GB standards and SAMR oversight shape domestic appliance safety and energy efficiency requirements. Yangtze River Delta production clusters concentrate component fabrication for global OEM supply chains.
India
Underpenetrated premium residential segment offers whitespace as urban household appliance penetration accelerates in tier-one cities. BIS certification requirements and FSSAI food safety standards govern imported equipment compliance. Mumbai and Bangalore clusters emerge as adoption centers for connected brewing platforms through direct-to-consumer online retail expansion.
Global Coffee Machine Market Vendor Landscape
Portfolio diversification dominates the current landscape as incumbents bridge hardware manufacturing with recurring consumables revenue. The vendor base organizes around three strategic archetypes: heritage European engineering houses with thermal system expertise, Swiss precision manufacturers anchoring premium workplace fleets, and beverage conglomerates with proprietary capsule ecosystems. Competitive intensity concentrates on M&A activity targeting IoT platform capabilities and strategic partnerships linking equipment OEMs with roasted coffee suppliers.
Within the heritage engineering tier, De'Longhi Group and JURA Elektroapparate exemplify divergent specialization strategies. De'Longhi occupies a position bridging Italian manufacturing heritage with prosumer segment accessibility. JURA anchors premium workplace category positioning through connected fleet management platforms. Nestlé Nespresso represents the ecosystem-locked archetype, sustaining proprietary brewing geometry through direct-to-consumer subscription channels.
| Leading Market Players |
|---|
| Panasonic |
| Melitta Group |
| Keurig Dr Pepper |
| JURA Elektroapparate |
| Groupe SEB |
| Nestlé Nespresso |
| Electrolux |
| La Marzocco |
| De'Longhi Group |
| Others |
Supply Flow & Price Mechanics
Pulse extraction process technology is compressing cost economics for premium-tier manufacturers while concentrating supply leverage among thermoblock engineering specialists in Baden-Württemberg. This thermal architecture transition simultaneously elevates R&D amortization pressure on mid-tier competitors and rewards vertically integrated boiler producers with scale advantages in brass alloy substitution cycles.
Pricing Analysis
Input-cost pass-through from REACH-compliant stainless steel boilers and nickel-free alloy components is compressing margins for European manufacturers serving the prosumer segment. Three-tier pricing structure across premium, standard, and economy levels stratifies by automation intensity and connected platform capability, with smart-enabled fleet systems commanding service-bundled premiums. Pricing pressure stems from capsule waste regulations in France and Italy that impose end-of-life collection obligations on single-serve OEMs. Corporate procurement teams in the United States demonstrate lowest price sensitivity through outcome-based uptime contracts, while Indian residential buyers remain most responsive to promotional discounting.
Supply Chain Analysis
Reverse-logistics flows for extended producer responsibility compliance are reshaping distribution economics as French and Italian regulators mandate end-of-life collection infrastructure. Manufacturing concentrates in China for sub-premium drip platforms, Germany for thermoblock engineering, and Italy for pressure-system craft heritage. Component sourcing draws from Vietnamese electronics for IoT modules, Swiss precision pumps, and Brazilian aluminum for thermal carafes. Single-source vulnerability in brass alloy supply creates qualification bottlenecks as ECHA testing extends supplier onboarding timelines. Distribution runs through direct-sales B2B fleets for workplace installations, online retail for residential subscription bundling, and specialty stores for premium prosumer demonstration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The coffee machine market functions as a geographic-arbitrage play where EU Ecodesign Directive compliance costs in Germany and Italy create margin expansion opportunities for manufacturers with established ultra-efficient thermoblock platforms serving lower-regulation export markets.
For Market Incumbents: Anchor premium positioning through captive control over pulse extraction process IP and connected fleet management software stacks. Consolidate supplier relationships with REACH-validated stainless steel boiler manufacturers to compress qualification timelines. Defend against emerging smart-enabled entrants by accelerating R&D in AI-driven grind calibration and bean-to-cup telemetry platforms. For New Entrants and Emerging Players: Tier-one Indian households represent an underserved buyer archetype with accelerating appliance penetration and minimal incumbent loyalty. White-space exists in biodegradable capsule alternatives for single-serve platforms facing regulatory pressure in France and Italy. Target direct-to-consumer online retail with subscription-linked replenishment automation to bypass established specialty store gatekeepers. For Investors and Strategic Acquirers: Roll-up economics work for IoT platform specialists because workplace fleet operators are consolidating vendor relationships around centralized consumption analytics and predictive maintenance contracts. Long-term viability centers on recurring revenue attachment rates rather than hardware shipment volumes. Monitor EU F-Gas Regulation phase-down timelines as inflection indicators for super-automatic platform redesign cycles and integrated milk cooling system substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Thermoblock Manufacturing | Captures margin from REACH-compliant stainless steel boiler production while compressing supplier qualification risk. |
| Direct-to-Consumer Subscription Launch | Locks Indian tier-one households into recurring consumables revenue through app-connected replenishment automation. |
| AI-Driven Grind Calibration Investment | Eliminates barista intervention for HoReCa labor cost reduction during peak morning rush compression. |
| Biodegradable Capsule Ecosystem Development | Preempts extended producer responsibility cost erosion in France and Italy through compostable alternative certification. |
| Connected Fleet Management Platform Expansion | Captures United States corporate procurement shift toward outcome-based uptime contracts and centralized analytics. |
Methodological Framework
Direct dialogue with product development executives at heritage European engineering houses, procurement leads at United States workplace fleet operators, IoT platform engineers, and aftermarket service heads informed primary intelligence synthesis. Secondary validation drew from SEC filings of listed appliance manufacturers, EU Ecodesign Directive implementation reports, ECHA substance restriction databases, and customs records of coffee machine component trade flows. Bottom-up shipment modeling and top-down consumption elasticity estimates were triangulated against regional regulatory filing timelines.
Installed base projections and replacement demand curves were generated across the analysis window by technology tier, end-user segment, and regional adoption cluster. Segmentation dimensions included automation intensity, distribution channel, and thermal architecture type. CAGRs were derived from historical shipment volatility patterns, regulatory implementation schedules, and hybrid work normalization trajectory assumptions. Forecast inputs incorporated brass alloy substitution cycle timelines and smart platform subscription attach rate elasticity.
Underlying measurement precision varies by segment; fully automatic and smart-enabled platforms carry tighter precision than manual lever systems due to established shipment reporting from workplace fleet operators. Forecasts reflect assumptions around EU F-Gas Regulation phase-down adherence and REACH substance restriction expansion timelines. Practitioners should monitor extended producer responsibility framework adoption in additional European jurisdictions and BIS certification pathway streamlining in India for early signals of competitive repositioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Europe Ready-To-Drink (RTD) Coffee Market
Coffee
Philippines Coffee and Tea Capsules Market
Coffee
Coffee Pods and Capsules Market
Coffee
Africa Ready-To-Drink (RTD) Coffee Market
Coffee
Out-Of-Home Coffee Market
Coffee
Take Out Coffee Market
Coffee
Coffee Grinder Market
Coffee
Global Coffee Shop Market
Coffee
Coffee Bottle Market
Coffee
Freeze Dried Coffee Market
Coffee
Global Nespresso Capsules Market
Coffee
Global Portable Coffee Makers Market
Coffee
United States Ready-To-Drink (RTD) Coffee Market
Coffee
Asia Pacific Coffee Market
Coffee
South America Ready-To-Drink (RTD) Coffee Market
Coffee
Reusable Coffee Cup Market