
 Asia-Pacific Vanilla Beans and Extract Market | 2026-2036
Asia-Pacific Vanilla Beans and Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Vanilla Beans and Extract Market Outlook
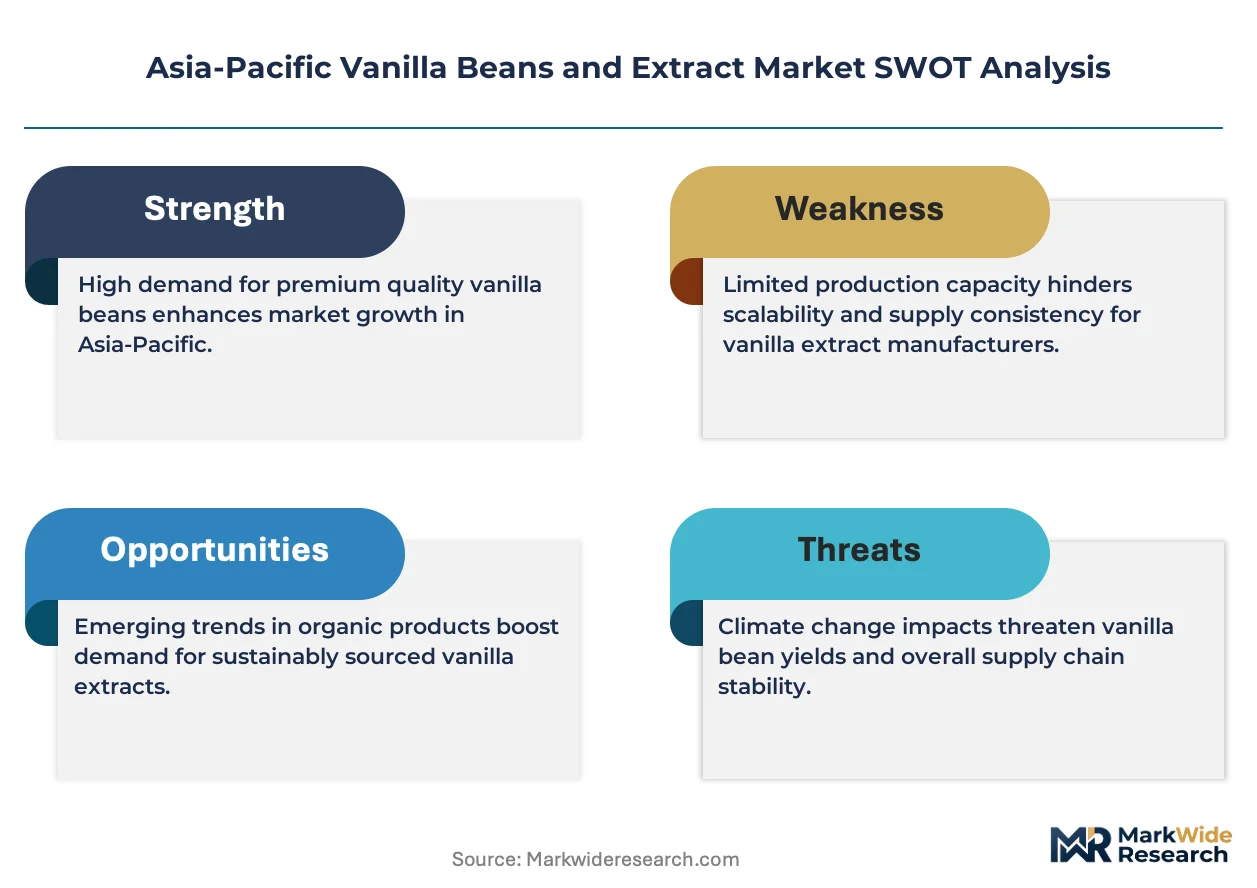
REACH compliance is restructuring the cost-of-entry calculus for European-bound extract exports from Asia-Pacific processors. Kerry Group Plc leverages its integrated flavor technology platforms to sustain premium positioning across Japanese beverage applications. Givaudan anchors its regional supply security through long-term vanilla bean sourcing partnerships in Madagascar and Papua New Guinea. Symrise AG competes on extraction efficiency, differentiating its portfolio with specialized oleoresin and absolute product lines.
Vanilla beans and extract encompass the cured seed pods and derived aromatic concentrates of Vanilla planifolia and Vanilla tahitensis species, containing vanillin concentrations ranging from 1.5% to 2.5% in cured beans and 200-fold concentration in standardized extracts used for flavoring. The primary commercial purpose spans flavor modulation in food systems, fragrance compounding, and pharmaceutical masking applications where heat-stable volatile profiles prove essential. Whole beans and extract categories dominate value capture due to premium positioning in bakery and dairy formulations, while powder formats are gaining traction in convenience-driven beverage premixes. Organic purity classifications command substantial margin premiums as Japanese and Australian clean-label procurement standards tighten.
FSSAI natural flavor mandates in India, Japan's Ministry of Health standards for food additives, and Australia's FSANZ labeling requirements collectively shape product formulation pathways and import documentation burdens across the region. These frameworks elevate compliance costs for synthetic vanillin alternatives while creating preferential market access channels for certified natural and organic supply chains. Stakeholders must monitor evolving extraction technology patents and origin-certification protocols to secure long-term procurement advantages.
Market Dynamics
Natural flavor certification mandates across Asia-Pacific are compressing synthetic vanillin alternatives while redirecting procurement budgets toward traceable Bourbon-type bean supply chains in Indonesia and Papua New Guinea.
Growth Catalysts
- FSSAI Natural Flavor Mandates:India's food safety regulator now requires explicit natural flavor labeling, forcing reformulation away from synthetic vanillin in dairy and confectionery applications.
- Artisanal Confectionery Expansion:Premium ice cream manufacturers in Japan and South Korea are scaling natural vanilla procurement to meet clean-label retail positioning requirements.
- Bourbon-Type Cultivation Intensification:Java and Bali growing regions in Indonesia are expanding cured bean output through improved curing infrastructure and farmer cooperative consolidation.
Market Restraints
- Cyclone-Prone Supply Concentration:Madagascar and Papua New Guinea together account for dominant global vanilla bean volumes, creating catastrophic weather exposure for Asia-Pacific processors.
- Multi-Year Curing Cycle:Vanilla planifolia requires 18-24 months from pollination to commercial curing, preventing rapid supply response to price spikes.
- Synthetic Vanillin Cost Arbitrage:Petrochemical-derived vanillin from guaiacol or lignin maintains 80-90% cost advantage over natural extraction, pressuring commodity-tier pricing.
Strategic Opportunities
- Vietnamese Highland Cultivation:Lam Dong and Dak Lak provinces offer underexploited agroclimatic conditions for Vanilla tahitensis diversification outside Indonesian supply dominance.
- Oleoresin Technology Convergence:Supercritical CO2 extraction is merging with absolute production methods to capture heat-stable volatile profiles for beverage premix applications.
- Australian FSANZ Organic Premium Channel:Clean-label certification pathways create margin expansion for certified organic supply chains serving premium bakery segments.
Industry Challenges
- Origin-Authentication Skill Shortage:Gas chromatography-mass spectrometry analysts capable of detecting synthetic adulteration in natural extracts remain scarce across regional testing laboratories.
- REACH Documentation Burden:European-bound extract exports require extensive safety data sheet preparation and substance registration, extending compliance timelines for small-batch processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Vanilla Beans and Extract Market |
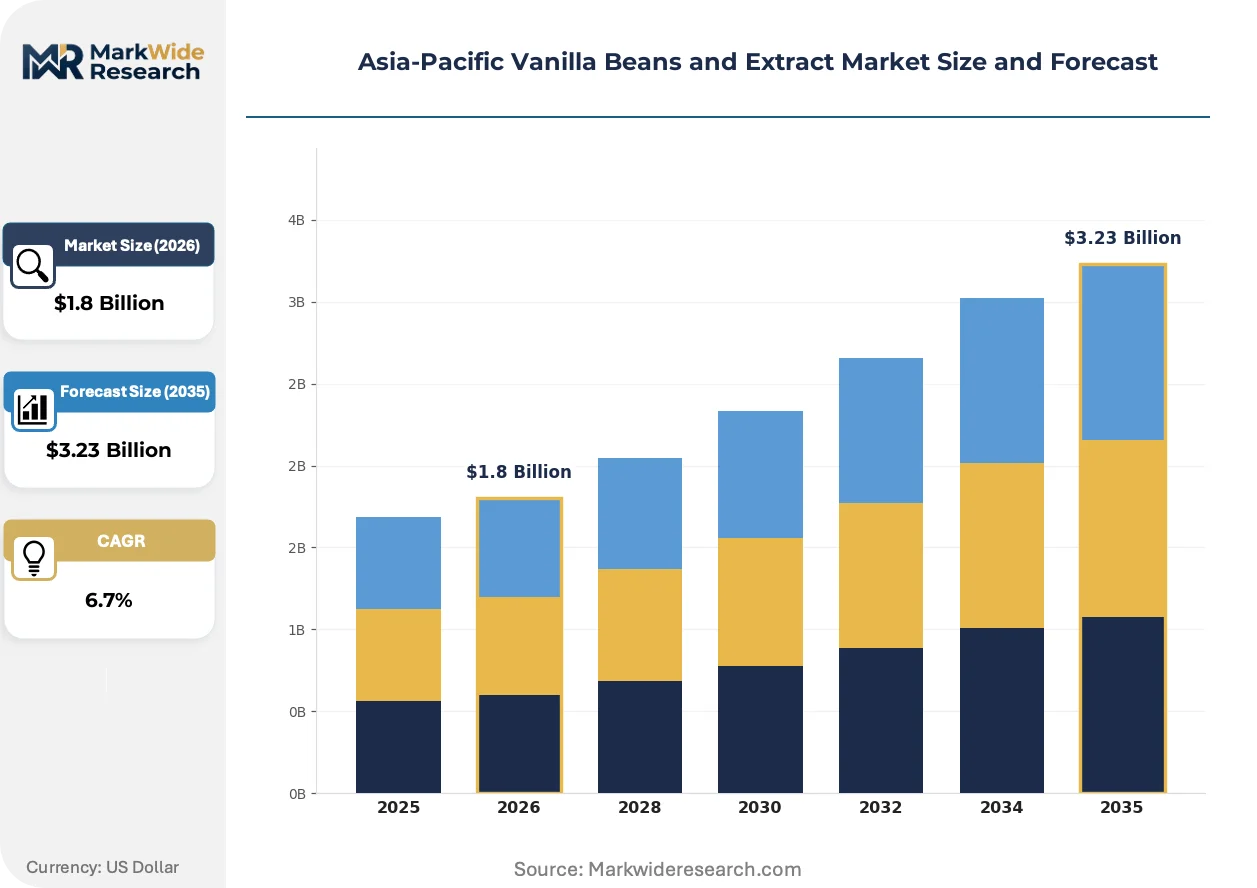
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Beans, Extract, Powder, Paste End User: Food Industry, Beverage Sector, Personal Care, Pharmaceuticals Purity Level: Natural, Synthetic, Organic, Non-Organic Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesalers |
| Companies Covered | Tharakan and Co, Natural Vanilla Pty Ltd, Kerry Group Plc, Archer-Daniels-Midland Co, Synergy Flavors Inc, Symrise AG, Givaudan, International Flavors & Fragrances Inc, Prova SAS, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Vanilla Beans and Extract Market Strategic Shifts
Extraction technology advancement is compressing traditional curing timelines while regulatory labeling precision is eliminating synthetic substitution options across premium food and fragrance applications.
Supercritical CO2 extraction systems are replacing conventional solvent-based methods for vanillin recovery from cured beans. Japanese beverage manufacturers and Korean dairy processors are adopting these systems at pilot scale to preserve delicate aromatic compounds. This technology is converging with absolute production lines to create unified processing platforms serving both food and fine fragrance customers.
Japan's Ministry of Health standards for food additives now mandate batch-level natural origin documentation for vanilla-derived flavorings. The industrial consequence is a wholesale rejection of vanillin-natural flavor blends in premium product categories. Japanese confectionery and ice cream manufacturers are responding by establishing direct sourcing relationships with Indonesian curing facilities to secure unbroken chain-of-custody records.
Ingredient buyers are consolidating supplier relationships around vertically integrated processors capable of delivering certified organic beans, extracts, and oleoresins from unified origin points. This pattern displaces fragmented spot-market purchasing that previously mixed Madagascan, Indonesian, and Papua New Guinean lots. The consolidation is most visible among Australian clean-label brands and Japanese premium dairy processors seeking single-origin narrative alignment.
Asia-Pacific Vanilla Beans and Extract Market Segmentation
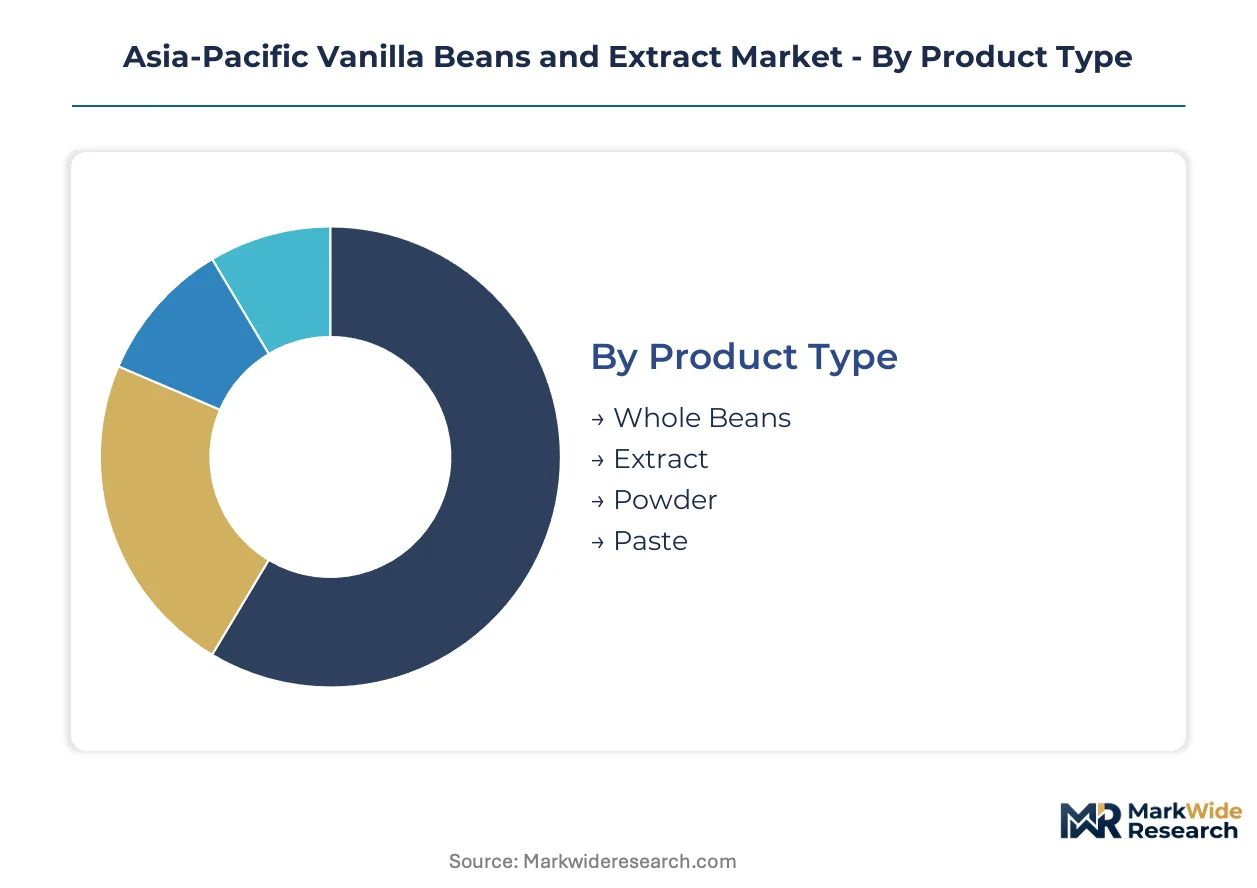
Vanilla procurement patterns in Asia-Pacific diverge sharply across purity grades and application requirements. Japanese dairy processors, Indian confectionery formulators, and Australian clean-label brands each demand distinct product formats with incompatible certification standards.
Product Type:
Buyers in this category separate by heat stability needs and formulation convenience rather than price sensitivity alone.
- Extract:Standardized vanillin concentrations at 200-fold strength deliver consistent dosing in industrial bakery and dairy systems. Japanese beverage manufacturers concentrate procurement here for heat-stable volatile preservation in pasteurized applications.
- Whole Beans:Cured pods containing 1.5% to 2.5% vanillin by dry weight command premium positioning in artisanal confectionery and fine fragrance compounding. South Korean ice cream manufacturers favor whole bean scraping for visual authenticity in super-premium retail lines.
- Powder:Spray-dried formats suit convenience-driven beverage premixes and dry bakery blends where liquid addition complicates processing.
- Paste:Suspended vanilla seed formulations serve niche pastry applications requiring visual pod fleck distribution.
Extract leads volumes today; powder is gaining share fastest in convenience-oriented segments.
End User:
Application heat profiles and regulatory exposure determine procurement specifications across buyer categories.
- Food Industry:Bakery and dairy formulations dominate extract absorption, with FSSAI natural flavor mandates in India redirecting synthetic vanillin replacement budgets toward certified Bourbon-type supply chains.
- Beverage Sector:Heat-stable oleoresin demand concentrates among Japanese RTD coffee and Korean fermented milk processors adopting supercritical CO2 extraction compatibility.
- Personal Care:Fine fragrance and skincare applications require absolute-grade vanillin with complete solvent residue documentation for Australian FSANZ cosmetic ingredient disclosure.
- Pharmaceuticals:Masking-grade vanilla extract serves pediatric and geriatric formulations where bitter active compound coverage demands pharmaceutical-grade purity certification.
Food Industry absorbs the largest procurement volumes; Beverage Sector shows the steepest expansion trajectory from clean-label RTD proliferation.
Purity Level:
Certification tier selection correlates directly with export destination regulatory burden and retail price positioning.
- Natural:FSSAI-mandated labeling in India and Japan's Ministry of Health additive standards enforce batch-level origin documentation, compressing synthetic blend alternatives in premium categories.
- Organic:Australian FSANZ and Japanese JAS certification pathways command substantial margin premiums as clean-label procurement standards tighten across bakery and dairy segments.
- Synthetic:Petrochemical-derived vanillin from guaiacol or lignin retains cost advantage in commodity-tier applications unaffected by natural flavor mandates.
- Non-Organic:Conventional cultivation without certification serves price-sensitive industrial buyers in Southeast Asian processed food manufacturing.
Natural purity dominates current procurement; organic certification is climbing the fastest as Australian and Japanese retail standards converge.
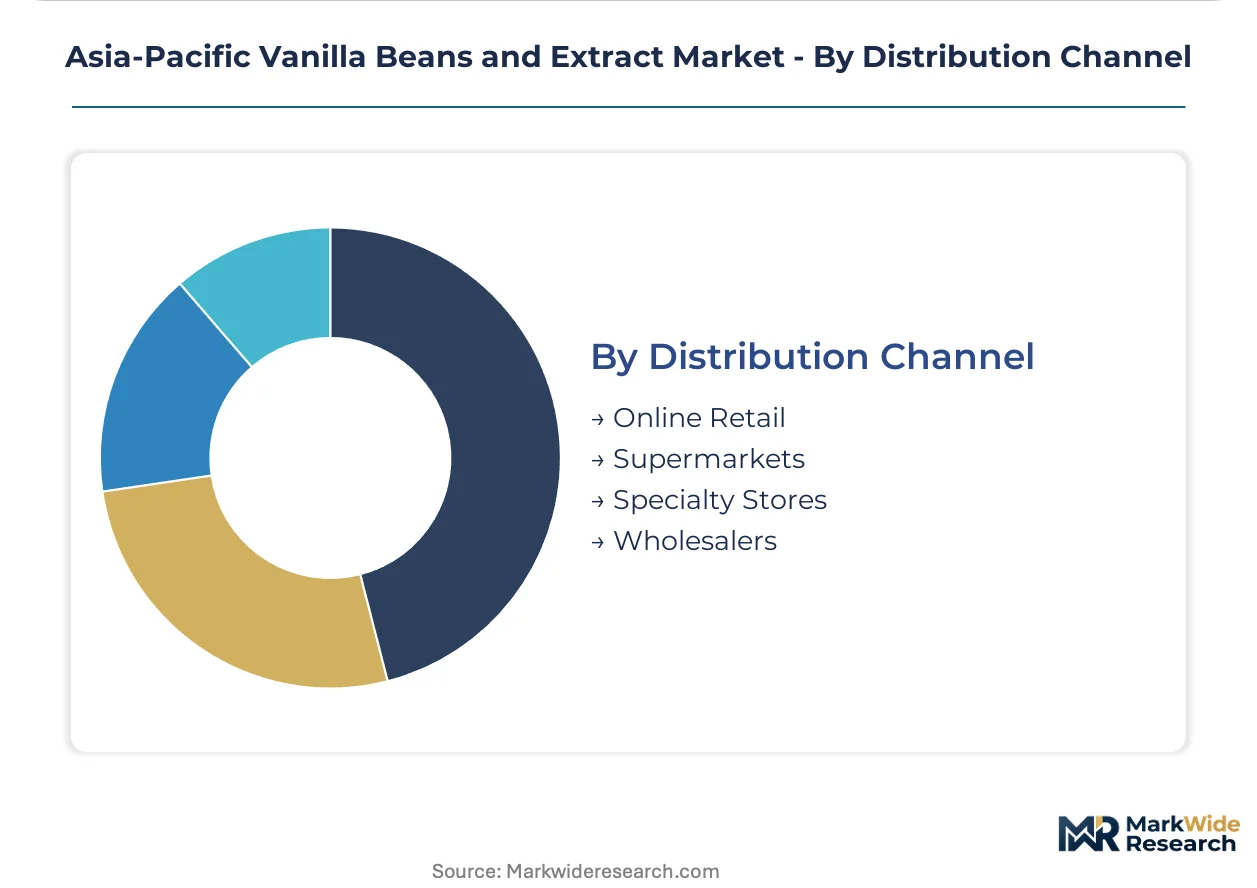
Distribution Channel:
Channel selection reflects order scale, certification complexity tolerance, and relationship requirements for origin verification.
- Wholesalers:Vertically integrated processors delivering certified organic beans, extracts, and oleoresins from unified origin points consolidate procurement relationships among Japanese dairy and Australian clean-label brands.
- Specialty Stores:Small-batch Indonesian curing facilities serve artisanal confectionery and fine fragrance compounders requiring direct chain-of-custody documentation.
- Supermarkets:Retail-packaged whole beans and consumer extracts reach home bakers and small commercial kitchens through mass-market grocery networks.
- Online Retail:E-commerce platforms expand access to certified organic and single-origin products for specialty food manufacturers in secondary Australian and Indian cities.
Wholesalers channel the greatest volume throughput; specialty stores are expanding most quickly among premium segment buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized curing technicians in Indonesia's Central Java highlands anchor the region's vanilla workforce concentration, with secondary talent pools developing in Vietnam's Lam Dong province and Papua New Guinea's East New Britain region.
Indonesia
Premium ice cream manufacturers in Jakarta and Surabaya are scaling Bourbon-type bean procurement for clean-label retail lines. The country's national food and drug regulator, BPOM, enforces natural flavor labeling standards that redirect formulation away from synthetic alternatives. Curing facility consolidation accelerates in Bali and East Java where farmer cooperatives are upgrading post-harvest infrastructure.
Japan
Artisanal confectionery brands in Tokyo and Osaka drive demand for whole bean and absolute-grade extracts. The Ministry of Health, Labour and Welfare mandates batch-level natural origin documentation for food additives, eliminating vanillin-natural blends in premium categories. Super-premium dairy processors in Hokkaido are establishing direct sourcing relationships with Indonesian curing facilities.
India
FSSAI natural flavor mandates are forcing reformulation across dairy and confectionery applications in Mumbai and Delhi. The Food Safety and Standards Authority of India now requires explicit natural flavor labeling, compressing synthetic vanillin market share. Procurement budgets are redirecting toward certified Bourbon-type supply chains serving bakery clusters in Maharashtra and Karnataka.
South Korea
RTD coffee and fermented milk processors in Seoul and Busan are adopting supercritical CO2 extraction compatibility for heat-stable oleoresin demand. The Ministry of Food and Drug Safety maintains strict additive disclosure requirements that favor documented natural supply chains. Premium ice cream manufacturers are scaling whole bean scraping for visual authenticity in retail super-premium lines.
Australia
Clean-label bakery brands in Sydney and Melbourne are consolidating procurement around certified organic supply chains. FSANZ labeling requirements create margin expansion pathways for certified organic beans and extracts. Specialty food manufacturers in secondary cities are accessing single-origin products through expanded e-commerce distribution channels.
Asia-Pacific Vanilla Beans and Extract Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the Asia-Pacific vanilla landscape, creating a tiered structure where scale-driven flavor houses and boutique curing operations occupy distinct value positions. The vendor base clusters around three strategic archetypes: integrated flavor technology platforms, specialized oleoresin and absolute producers, and vertically coordinated bean-to-extract processors. Competitive moves center on long-term sourcing partnerships in Madagascar and Papua New Guinea, alongside extraction efficiency investments in supercritical CO2 systems.
Within the integrated platform tier, Kerry Group Plc and Givaudan exemplify scale-driven positioning through unified flavor technology portfolios. Symrise AG occupies a specialized position concentrated on extraction efficiency and oleoresin product lines. Among Asia-Pacific-anchored operators, Tharakan and Co and Natural Vanilla Pty Ltd represent regional sourcing and curing specialists with direct Indonesian and Papua New Guinean supply relationships. These named entities illustrate the competitive spectrum from global diversified houses to geographically concentrated bean-to-extract processors.
| Leading Market Players |
|---|
| Tharakan and Co |
| Natural Vanilla Pty Ltd |
| Kerry Group Plc |
| Archer-Daniels-Midland Co |
| Synergy Flavors Inc |
| Symrise AG |
| Givaudan |
| International Flavors & Fragrances Inc |
| Prova SAS |
| Others |
Value Chain & Pricing Dynamics
Bourbon-type vanilla bean spot prices in Indonesia's Central Java highlands cascade through three distinct procurement tiers, with certified organic lots commanding substantial premiums over conventional grades while synthetic vanillin alternatives compress pricing floors for commodity extract buyers.
Pricing Analysis
Unbundled bean procurement from Indonesian farmer cooperatives separates from bundled extract-plus-certification packages offered by vertically integrated processors. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with organic JAS-certified extracts capturing widest margins. Pricing pressure stems from synthetic vanillin's 80-90% cost advantage in commodity applications. Industrial bakery buyers in Southeast Asia exhibit highest price sensitivity, while Japanese super-premium dairy processors absorb premium organic tiers without volume elasticity.
Supply Chain Analysis
Ocean freight cost volatility from Port of Surabaya to Yokohama and Busan directly impacts landed extract pricing for Japanese and Korean processors. Madagascar, Indonesia, and Papua New Guinea anchor raw bean supply, with curing infrastructure concentrated in Java and Bali highlands. The supply chain draws from 18-24 month pollination-to-curing cycles that prevent rapid supply response. Single-source vulnerability concentrates in Madagascar's cyclone-exposed SAVA region. Distribution runs through vertically integrated processors delivering certified organic beans, extracts, and oleoresins from unified origin points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between Indonesia's low-cost Bourbon-type cultivation and Japan's premium organic certification premiums, with FSSAI mandates in India creating parallel regulatory-driven demand shifts.
For Market Incumbents: Deploy long-term sourcing partnerships to lock in Indonesian and Papua New Guinean bean supply before Vietnamese highland cultivation matures. Secure curing facility consolidation in East Java to control post-harvest quality variance. Counter Kerry Group's integrated flavor platforms by deepening oleoresin technology investments in supercritical CO2 extraction systems.
For New Entrants and Emerging Players: Enter via Vietnamese Lam Dong and Dak Lak provinces for Vanilla tahitensis diversification outside Indonesian supply dominance. Target Australian FSANZ-certified organic channels where clean-label procurement standards tighten fastest. Pursue direct-to-specialty-store distribution for artisanal confectionery buyers requiring unbroken chain-of-custody documentation.
For Investors and Strategic Acquirers: Asymmetric upside sits with vertically coordinated bean-to-extract processors possessing direct Madagascar and Papua New Guinean supply relationships. Five-to-ten year viability hinges on origin-authentication capabilities as gas chromatography-mass spectrometry analyst scarcity intensifies. Watch for Indonesian BPOM enforcement actions against synthetic-adulterated extracts as inflection indicator for natural certification premium expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Curing Facilities | East Java cooperative consolidation secures post-harvest quality control for Bourbon-type output. |
| Supercritical CO2 Extraction Scale-Up | Japanese beverage manufacturers adopt heat-stable volatile preservation for pasteurized applications. |
| Organic JAS Certification Investment | Australian and Japanese clean-label procurement standards tighten across bakery segments. |
| Direct Sourcing Partnership Establishment | Hokkaido dairy processors bypass fragmented spot markets for Indonesian single-origin beans. |
| Oleoresin-Absolute Product Line Expansion | Symrise's extraction efficiency focus creates differentiation in fragrance compounding channels. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with Indonesian curing facility managers, Japanese dairy procurement directors, Indian FSSAI regulatory affairs leads, and Australian clean-label brand supply chain heads with secondary validation from customs trade data, BPOM enforcement records, Japan Ministry of Health additive filings, and FSANZ labeling guidance documents. Bottom-up bean production estimates from Java and Bali growing regions triangulated against top-down extract consumption surveys across food, beverage, and fragrance applications.
Segment-weighting approaches modeled product type splits across extract, whole bean, powder, and paste formats alongside purity level tiers of natural, organic, synthetic, and non-organic classifications. End-user segmentation captured food industry, beverage sector, personal care, and pharmaceutical demand patterns across the projection horizon. CAGRs derived from elasticity-adjusted volume projections responding to FSSAI mandate implementation timelines and Japanese Ministry of Health documentation requirements. Forecast inputs incorporated curing cycle duration constraints and cyclone frequency risk modeling for Madagascar supply exposure.
Inputs from Indonesian farmer cooperative yield surveys and Japanese beverage processor procurement plans were available through the study window; gaps in Papua New Guinea smallholder production data introduce uncertainty bands around regional supply estimates. Forecasts reflect assumptions regarding FSSAI enforcement consistency and REACH documentation burden stability for European-bound exports. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
South America Flavors and Fragrances Market
Flavorings and Food Additives
Chokeberry Extract Market
Flavorings and Food Additives
Quillaia Extracts Market
Flavorings and Food Additives
Oil Soluble Flavors Market
Flavorings and Food Additives
Natural Flavors Market
Flavorings and Food Additives
Vanilla Bean Market
Flavorings and Food Additives
Italy Food Colorants Market
Flavorings and Food Additives
D-Limonene Market
Flavorings and Food Additives
Sour Cream Powder Market
Flavorings and Food Additives
Global Vanilla (B2B) Market
Flavorings and Food Additives
Chicken Flavor Market
Flavorings and Food Additives
Global Sterols Market
Flavorings and Food Additives
Betanin Food Color Market
Flavorings and Food Additives
Basil Oil Market
Flavorings and Food Additives
Naringin Market
Flavorings and Food Additives
Global Paprika Oleoresin Market