
 Anti Wind Net Market | 2026-2036
Anti Wind Net Market Size, Share, and Industry Trends Forecast 2026-2036
Anti Wind Net Market Insights
Market Context
The capital-intensity divergence between integrated mesh manufacturers and regional assemblers is unwinding as scale advantages in polymer extrusion consolidate procurement leverage. Vestas Wind Systems leverages its turbine-service logistics network to cross-sell protective netting solutions into wind farm maintenance channels. Akzo Nobel anchors its position through captive supply of UV-stabilized coating chemistries that extend net longevity in high-irradiance environments. 3M competes on filament engineering expertise, translating aerospace mesh know-how into agricultural and construction-grade products.
Technical Definition and Segments
Anti wind nets are engineered polymer mesh barriers, typically woven from polypropylene, nylon, polyester, or HDPE monofilaments in densities ranging from 40 to 120 grams per square meter, designed to reduce wind velocity by 35 to 65 percent while maintaining light transmission for protected crops or work zones. Polypropylene dominates installed volume due to its cost-position and chemical resistance, though HDPE is capturing fastest growth in permanent greenhouse installations where tensile strength requirements exceed eight-year service life. Agricultural Protection commands the largest application share, yet Construction is deepening its margin pool as OSHA-compliant debris containment specifications tighten across developed markets.
Regulatory Outlook
EPA guidelines on agricultural chemical drift containment and OSHA wind-load standards for temporary structures shape product certification requirements in the United States, while REACH compliance in Europe restricts certain phthalate plasticizers in polymer formulations. India's BIS mesh tensile standards and China's GB agricultural film regulations create divergent testing protocols that fragment supplier qualification burdens. Stakeholders must monitor evolving biodegradability mandates and recycled-content thresholds that threaten to displace virgin polymer economics in coastal European markets.
Market Dynamics
Polymer feedstock volatility and UV-stabilization chemistry shortages are compressing margin structures for mesh extruders, forcing a pivot toward recycled-content formulations and captive additive production.
Growth Catalysts
- OSHA Wind-Load Standards:Stricter temporary-structure anchoring rules in the United States are mandating certified anti-wind netting for construction debris containment, pulling volume through compliance-driven replacement cycles.
- Horticulture Cluster Expansion:Protected cultivation acreage in Almeria, Murcia, and Sicily is accelerating demand for high-transmission HDPE mesh in permanent greenhouse installations.
- UV-Stabilizer Advances:Hindered-amine light stabilizer (HALS) formulations are extending net service life beyond eight years, reducing total cost of ownership for permanent agricultural infrastructure.
Market Restraints
- HDPE Resin Concentration:Middle Eastern and US Gulf Coast petrochemical complexes control over 60% of global polyethylene supply, exposing mesh manufacturers to freight-driven cost spikes.
- REACH Plasticizer Restrictions:ECHA scrutiny of phthalate additives in flexible polymer formulations is forcing reformulation costs and testing delays for European-market products.
- Metal Mesh Substitution:Galvanized steel windbreak fencing retains preference in permanent industrial applications where fire resistance and structural rigidity outweigh polymer flexibility.
Strategic Opportunities
- India's Protected Cultivation Push:National horticulture mission subsidies for shade-net and anti-hail structures are opening volume channels in Maharashtra and Karnataka.
- Biodegradable Polymer Convergence:PLA-PBAT blended filaments are approaching cost parity for seasonal applications where removal labor exceeds material value.
- E-Procurement Platform Penetration:B2B agricultural input marketplaces are disintermediating traditional distributor networks, enabling direct-to-farm pricing and specification transparency.
Industry Challenges
- Polymer Extrusion Technician Scarcity:Specialized skills in monofilament die design and melt-rheology control are concentrated among aging workforces in Italy and Germany.
- Multi-Jurisdiction Certification Burden:Divergent BIS tensile testing, GB agricultural film standards, and EPA drift-containment protocols force redundant product qualification for global suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti Wind Net Market |
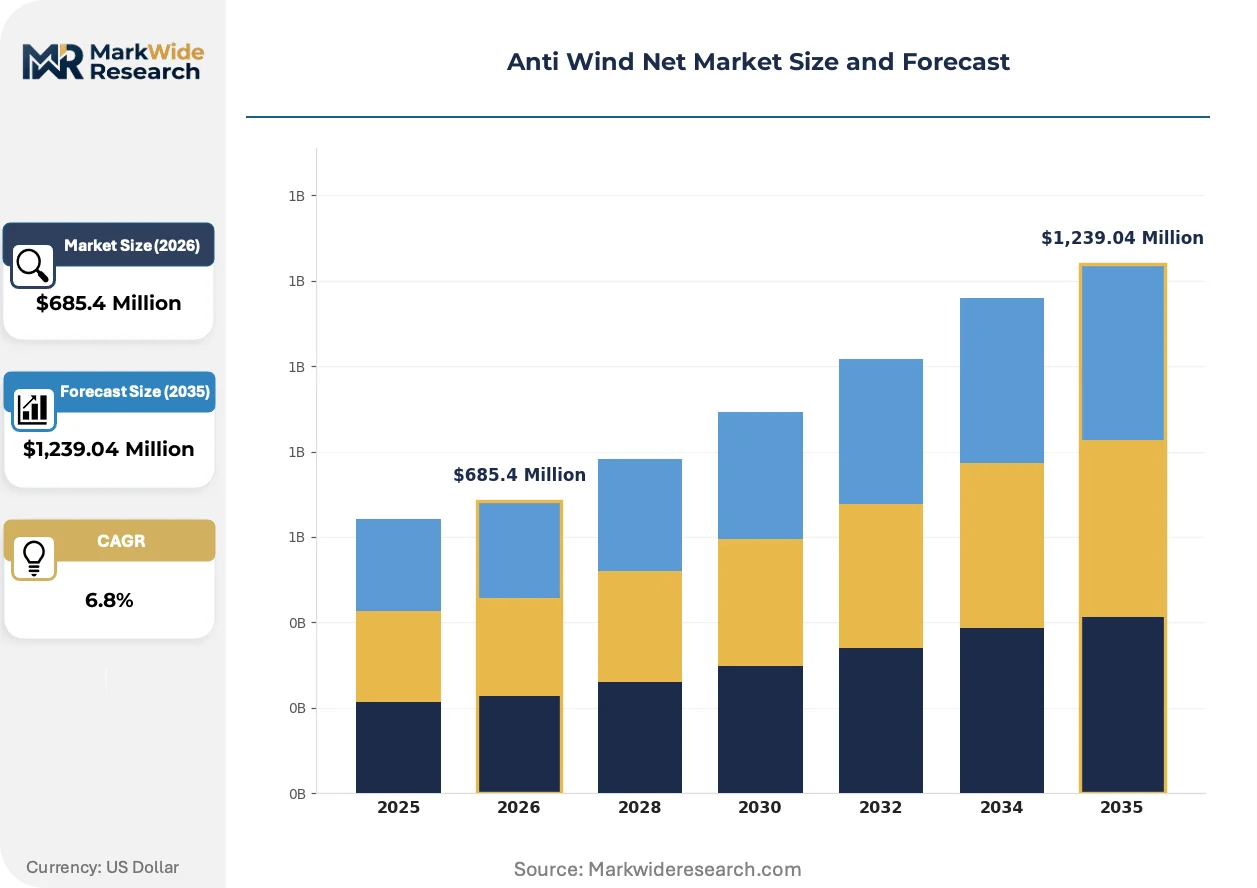
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene, Nylon, Polyester, HDPE Application: Agricultural Protection, Construction, Greenhouse, Erosion Control End User: Farmers, Construction Companies, Landscape Architects, Environmental Agencies Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Weather Guard Wind, GE Vernova, DEHN SE, Suzlon Energy, Akzo Nobel, Firetrace International, Vestas Wind Systems, Nordex, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti Wind Net Market Trends and Innovations
Material science breakthroughs and regulatory tightening on chemical additives are reshaping competitive advantage toward formulation control and circular-economy compliance.
Monofilament diameters below 0.25mm with engineered surface texturing are supplanting standard round filaments in precision greenhouse applications. Dutch and Israeli greenhouse operators are adopting these micro-textured meshes to optimize light diffusion without wind-velocity compromise. The shift is compressing margins for commodity extruders lacking filament-engineering capabilities.
REACH authorization requirements for certain UV-absorber chemistries are accelerating reformulation investments across European suppliers. ECHA's sunset date pressures are forcing mesh manufacturers to validate alternative stabilizer packages or exit the EU market. Agricultural protection segments with eight-year warranty obligations face the steepest retesting costs.
Buyers are consolidating annual netting purchases through cooperative procurement pools, displacing spot-market transactions. French and Spanish grower associations are negotiating master supply agreements with extruders, unbundling installation services from material supply. The model is most visible in Almeria's greenhouse cluster, where volume concentration is extracting price concessions and technical service commitments.
Anti Wind Net Market Segmentation
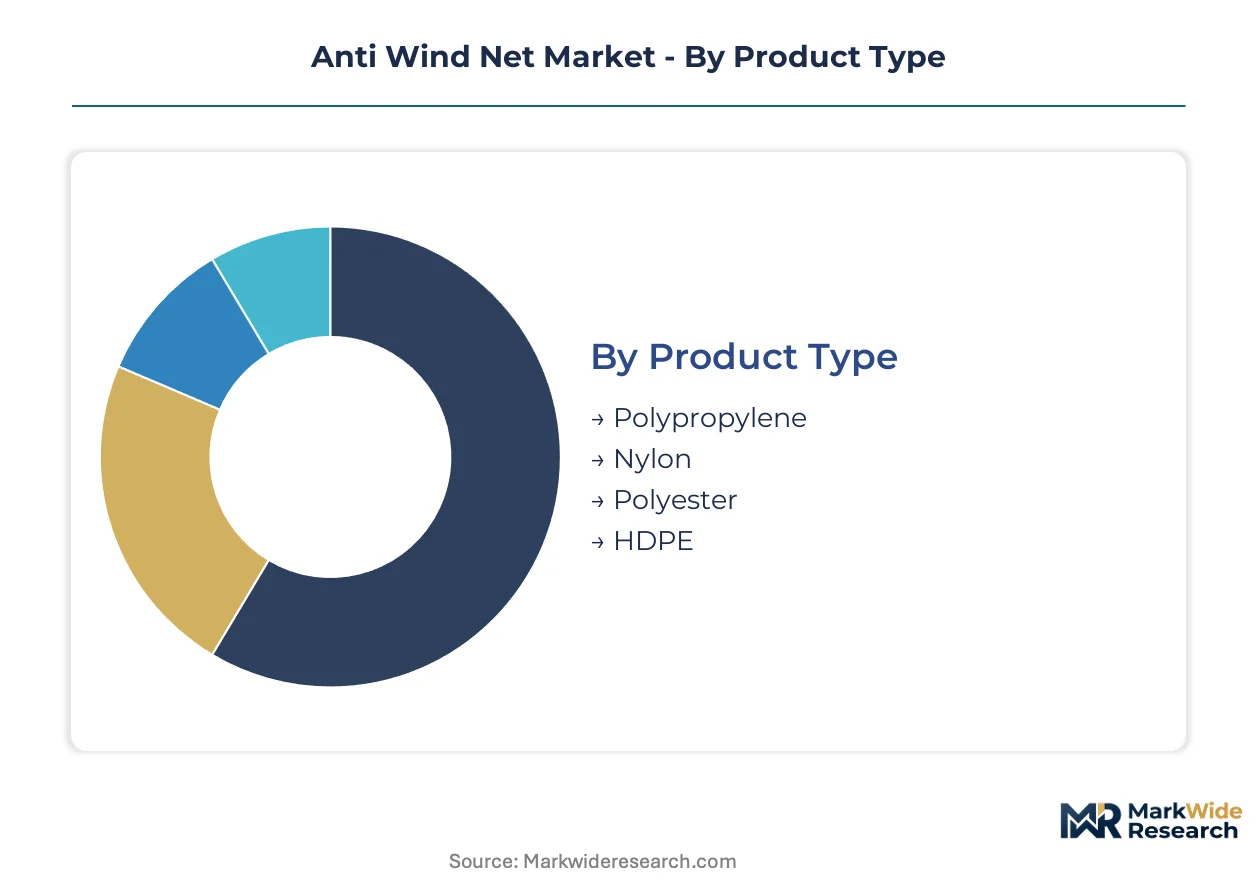
Segmentation in anti wind nets determines specification rigor, procurement pathways, and margin capture. Polymer chemistry and application context dictate regulatory exposure, while channel structure shapes price realization and technical service depth.
Product Type:
REACH authorization timelines for UV-absorber chemistries and OSHA wind-load certification requirements create divergent compliance burdens across polymer categories, forcing suppliers to maintain parallel formulation portfolios.
- Polypropylene:Dominant installed volume due to cost-position and chemical resistance against agricultural pesticides. Demand concentrates in seasonal field applications across India's Maharashtra and Karnataka horticulture belts, where national horticulture mission subsidies prioritize low capital outlay. Polypropylene handles the majority of throughput; HDPE is the fastest mover on share.
- HDPE:Superior tensile strength and eight-year service life position this polymer for permanent greenhouse infrastructure. Almeria, Murcia, and Sicily greenhouse operators specify HDPE mesh where light transmission optimization justifies premium positioning. REACH plasticizer restrictions and ECHA sunset date pressures are accelerating reformulation investments for European-market HDPE products.
- Nylon:High abrasion resistance suits construction debris containment applications with repeated handling cycles. Nylon filaments absorb moisture, limiting agricultural adoption despite superior toughness.
- Polyester:UV stability without heavy additive loading makes polyester attractive for high-irradiance environments. Polyester commands niche positioning where HALS formulation costs outweigh base polymer premiums.
Cost tiering separates commodity polypropylene from engineered HDPE and specialty nylon-polyester blends.
Application:
Volume distribution across applications reflects divergent specification intensity and replacement cycle economics.
- Agricultural Protection:Largest application share driven by crop shielding requirements in expanding horticulture sectors. China, India, and Brazil concentrate demand as protected cultivation acreage scales. EPA guidelines on agricultural chemical drift containment and India's BIS mesh tensile standards shape product certification requirements.
- Construction:Deepening margin pool as OSHA-compliant debris containment specifications tighten across developed markets. Stricter temporary-structure anchoring rules in the United States mandate certified anti-wind netting, pulling volume through compliance-driven replacement cycles.
- Greenhouse:Permanent installations requiring high-transmission HDPE mesh with engineered surface texturing for light diffusion optimization. Dutch and Israeli operators lead adoption of micro-textured filaments below 0.25mm diameter.
- Erosion Control:Slope stabilization and coastal protection applications where biodegradability mandates in coastal European markets threaten virgin polymer economics.
Agricultural Protection commands the heaviest volume concentration; Construction is expanding most quickly on compliance-driven specification upgrades.
End User:
Procurement sophistication varies sharply across user categories, determining channel selection and technical service requirements.
- Farmers:Consolidating annual purchases through cooperative procurement pools in French and Spanish grower associations, displacing spot-market transactions. E-procurement platform penetration enables direct-to-farm pricing transparency.
- Construction Companies:Mandate OSHA wind-load certification and documented anchoring specifications. Master service agreements with national contractors emphasize compliance documentation over unit price negotiation.
- Landscape Architects:Specify aesthetic and performance parameters for erosion control and windbreak installations. Technical consultation requirements extend sales cycles but support premium positioning.
- Environmental Agencies:Drive biodegradable polymer specifications and recycled-content thresholds in coastal protection tenders. Agency procurement favors lifecycle assessment documentation.
Farmers represent the deepest volume base; Environmental Agencies are climbing fastest on sustainability-mandated specification shifts.
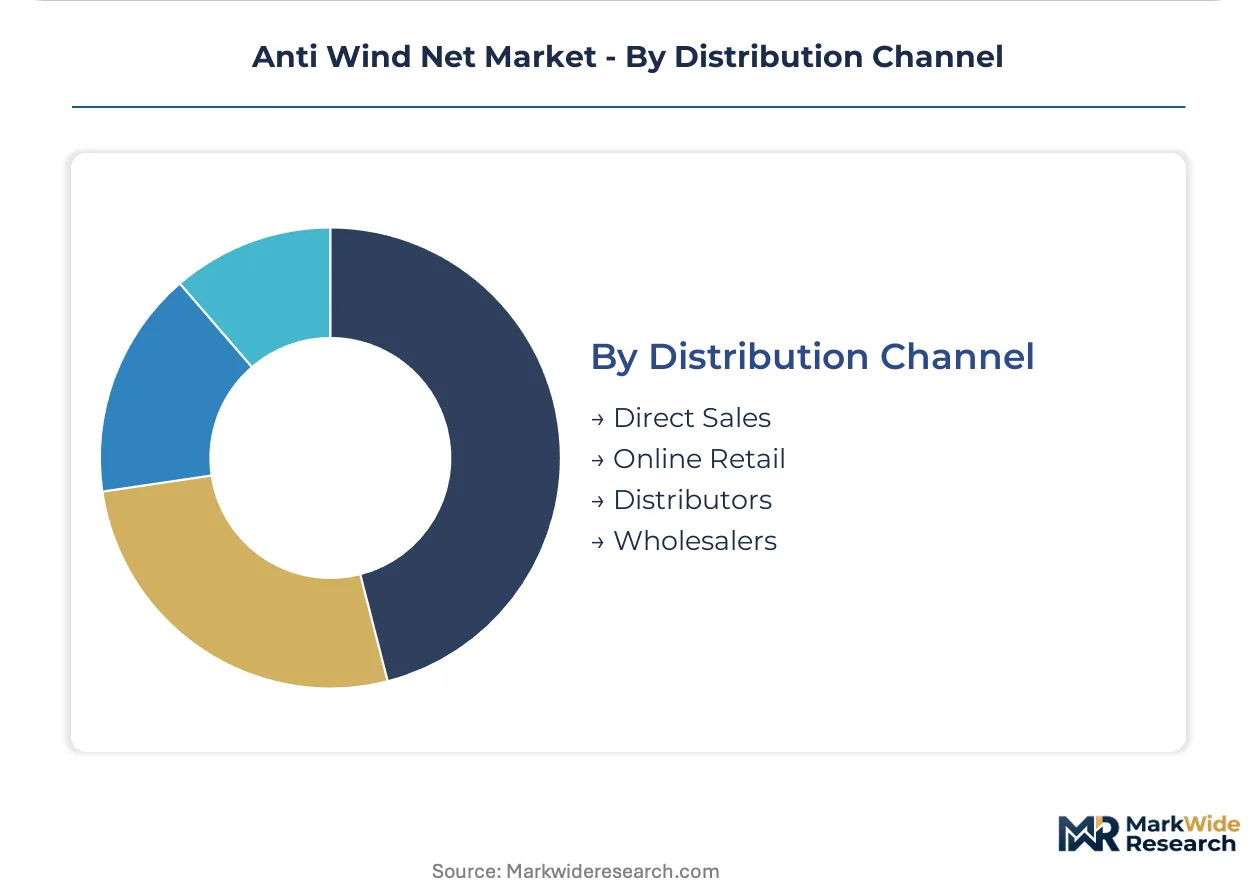
Distribution Channel:
Channel structure determines margin capture and customer relationship depth across user segments with divergent technical support needs.
- Direct Sales:Captures large greenhouse operators and national construction contractors requiring specification engineering and installation coordination. Direct relationships support eight-year warranty obligations and HALS formulation customization.
- Distributors:Traditional agricultural supply networks dominate farmer access in India and Brazil. Distributor technical capabilities vary, compressing margins for commoditized polypropylene products.
- Wholesalers:Volume aggregation for standard mesh specifications in construction and seasonal agricultural applications. Wholesaler concentration in Almeria's greenhouse cluster extracts price concessions through volume concentration.
- Online Retail:Emerging channel for standardized specifications and replacement purchases. B2B agricultural input marketplaces disintermediate traditional networks for specification-transparent transactions.
Distributors retain the broadest reach; Online Retail is gaining share fastest on platform penetration and procurement transparency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in anti wind netting tilt toward net-importing horticulture economies, with manufacturing capacity concentrated in polymer-extrusion clusters serving both domestic protected cultivation and cross-border agricultural supply chains.
China
Shandong and Jiangsu provinces host the densest concentrations of HDPE mesh extrusion capacity, feeding greenhouse construction across the Yangtze River Delta. GB agricultural film regulations mandate tensile testing protocols that diverge from REACH and BIS standards, fragmenting supplier qualification burdens for exporters. Qingdao's port infrastructure supports bulk shipment of rolled mesh to Southeast Asian horticulture markets.
India
Maharashtra and Karnataka horticulture belts drive demand surge under national horticulture mission subsidies for shade-net structures. BIS mesh tensile standards create domestic certification requirements that favor regional assemblers over integrated manufacturers. Nashik's protected cultivation cluster concentrates procurement through cooperative pools, displacing spot-market transactions.
Spain
Almeria and Murcia greenhouse operators specify high-transmission HDPE mesh for permanent installations exceeding eight-year service life. ECHA sunset date pressures on UV-absorber chemistries force reformulation investments for REACH-compliant products. Almeria's grower associations negotiate master supply agreements that unbundle installation from material supply.
United States
OSHA wind-load standards for temporary structures mandate certified anti-wind netting in construction debris containment, pulling volume through compliance-driven replacement cycles. EPA guidelines on agricultural chemical drift containment shape product certification for vineyard and orchard applications. California's Central Valley concentrates demand from nut and fruit growers seeking crop shielding solutions.
Brazil
São Paulo and Minas Gerais states anchor expanding protected cultivation acreage in citrus and floriculture sectors. ANVISA oversight of agricultural input materials creates registration requirements distinct from EPA and REACH frameworks. Holambra's horticulture cluster imports specification-engineered mesh through distributor networks serving smallholder farmers.
Anti Wind Net Market Competitive Landscape
Concentration sits with integrated polymer extruders possessing captive UV-stabilization capabilities and regional assemblers sourcing monofilament from merchant suppliers. The vendor base stratifies across three tiers: multinational chemical conglomerates with filament-engineering heritage, mid-scale extruders serving greenhouse clusters through technical service relationships, and commodity producers competing on polypropylene volume. Dominant competitive moves include backward integration into additive masterbatch production and geographic expansion through distributor acquisition in high-growth horticulture belts.
Among diversified industrial conglomerates, 3M and Akzo Nobel occupy positions that exemplify formulation-control strategies. 3M translates aerospace mesh engineering into agricultural and construction-grade specifications, while Akzo Nobel anchors supply relationships through captive UV-stabilized coating chemistries. Vestas Wind Systems represents a cross-selling archetype, leveraging turbine-service logistics networks to push protective netting into wind farm maintenance channels.
| Leading Market Players |
|---|
| Weather Guard Wind |
| GE Vernova |
| DEHN SE |
| Suzlon Energy |
| Akzo Nobel |
| Firetrace International |
| Vestas Wind Systems |
| Nordex |
| 3M |
| Others |
Pricing and Supply Chain Analysis
Sixty-day inventory cycles at Almeria greenhouse cooperatives signal procurement leverage shifting from extruders to buyer consortia, compressing configured-to-order premiums while spot polypropylene pricing remains tethered to Gulf Coast petrochemical volatility.
Pricing Analysis
The customization-premium spread between specification-engineered HDPE mesh and commodity polypropylene runs three-to-one in European greenhouse markets, with REACH-compliant UV-stabilizer formulations commanding additional certification-grade pricing. Price differentiation separates HALS-extended eight-year warranties from seasonal three-season products. Pricing pressure stems from cooperative procurement pools in Spain and France extracting installation-unbundled rates. Smallholder farmers in India's Maharashtra belt exhibit highest price sensitivity, while Dutch greenhouse operators prioritize light-transmission specifications over unit cost.
Supply Chain Analysis
Strait of Malacca transit routes underpin feedstock delivery schedules for Shandong extrusion clusters, exposing mesh manufacturers to freight-driven cost spikes when Middle Eastern polyethylene supply tightens. Manufacturing concentrates in China, India, and Turkey, drawing from Saudi Arabian and US Gulf Coast HDPE resin. Raw material dependencies include hindered-amine light stabilizers from German chemical suppliers and monofilament dies from Italian tooling specialists. Single-source vulnerability concentrates in UV-stabilizer masterbatch formulation. Distribution runs through agricultural input distributors in Brazil and India, construction supply wholesalers in the United States, and direct technical-service relationships for European greenhouse operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts for mesh installation and seasonal replacement scheduling now outpace hardware margin expansion, creating recurring-revenue attachment opportunities that reshape supplier economics in permanent agricultural infrastructure.
For Market Incumbents: Compound defensive positioning through captive additive masterbatch production and HALS formulation control, countering REACH sunset-date pressures that threaten European-market participation. Backward integration into UV-stabilizer chemistry insulates margin structures from ECHA authorization disruptions. Channel control via distributor acquisition in Karnataka and São Paulo horticulture belts locks out emerging competitors lacking logistics scale. For New Entrants and Emerging Players: Installation-service gaps in India's fragmented BIS-certification landscape offer white-space entry, where regional assemblers lack technical consultation capabilities for eight-year warranty structures. Target Maharashtra cooperative procurement pools with specification-transparent e-procurement platforms that disintermediate legacy distributor networks. Lead with direct-to-farm pricing and HALS customization services unavailable from commodity extruders. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across recycled-content formulation lines as mechanical recycling of greenhouse mesh waste approaches cost parity. Acquisition targets include mid-scale extruders with BIS certification and established relationships with Nashik protected-cultivation clusters. Monitor ECHA authorization timelines for UV-absorber chemistries as inflection indicator for reformulation investment requirements and stranded-asset risk in non-compliant inventory.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Masterbatch | Captive HALS production shields margins from ECHA authorization delays and supply disruption. |
| Cooperative Procurement Pool Partnership | Master supply agreements with Almeria grower associations lock volume through installation-unbundled pricing. |
| Recycled-Content Formulation Scale-Up | Mechanical recycling of post-consumer greenhouse mesh addresses coastal European biodegradability mandates. |
| Direct E-Procurement Platform Launch | B2B agricultural marketplaces disintermediate distributor networks serving Maharashtra smallholder farmers. |
| REACH-Compliant Certification Investment | Alternative UV-stabilizer validation preserves European market access beyond ECHA sunset deadlines. |
Research Methodology
Two parallel data streams informed the analysis: structured interviews with polymer extrusion plant managers, agricultural cooperative procurement officers, and construction safety compliance directors; and secondary validation through customs trade data, BIS certification registries, and ECHA authorization databases. Primary fieldwork encompassed technical consultations with Dutch greenhouse operators and Spanish grower association representatives. Secondary sources included SEC filings from diversified chemical conglomerates, ACC polyethylene market reports, and OSHA temporary-structure standard documentation. Bottom-up volume modeling from regional cultivation acreage expansion triangulated against top-down polymer consumption estimates from extrusion capacity utilization.
Across the projection horizon, the analytical framework modeled volume and value outputs through segmentation across polymer chemistry tiers, application intensity levels, and regional regulatory clusters. CAGRs derived from weighted-average replacement cycle economics and protected-cultivation acreage expansion trajectories. Industry-specific forecast inputs included national horticulture mission subsidy disbursement patterns and OSHA enforcement activity indices for construction debris containment.
Forecasts assume regulatory continuity in REACH authorization timelines and BIS tensile-testing protocols; material policy shifts would require re-modeling of supplier qualification burdens and reformulation investment requirements. Specific risks include ECHA accelerated sunset dates for UV-absorber chemistries, Middle Eastern polyethylene supply disruptions, and India's PLI scheme expansion into protected cultivation inputs. Practitioners should keep alternative scenarios live as biodegradability mandate evolution and recycled-content threshold adjustments reshape virgin polymer economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Fabrics
Horticulture Film Market
Agricultural Fabrics
Europe Agricultural Films Market
Agricultural Fabrics
North America Silo Bags Market
Agricultural Fabrics
Agriculture Bags Market
Agricultural Fabrics
Africa Agricultural Film Market
Agricultural Fabrics
Biodegradable Mulch Film Market
Agricultural Fabrics
South America Agricultural Films Market
Agricultural Fabrics
Global Greenhouse Film Market
Agricultural Fabrics
Canopy Market
Agricultural Fabrics
Farming Sacks and Totes Market
Agricultural Fabrics
Hay Bags Market
Agricultural Fabrics
North America Agricultural Films Market
Agricultural Fabrics
Silage Bags Market
Agricultural Fabrics
Coco Coir Market
Agricultural Fabrics
Agricultural Gloves Market
Agricultural Fabrics
Silage Wrap Films Market