
 Shade Net Market | 2026-2036
Shade Net Market Size, Share, and Industry Trends Forecast 2026-2036
Shade Net Market Outlook
The shade net industry is rebalancing between premium UV-stabilized knitted fabrics and commodity-grade woven alternatives with diverging margin structures. EyouAgro leverages its integrated filament extrusion capacity to control raw material quality from resin to finished roll. Garware Technical Fibre anchors the South Asian supply base with specialized high-tenacity polyethylene netting for marine and agricultural dual-use applications. Berry Global Inc. competes through scale advantages in North American distribution, sustaining pallet-volume contracts with large greenhouse operators.
Shade nets are woven or knitted textile barriers manufactured from high-density polyethylene, polypropylene, or polyester filaments, typically rated by shade percentage and UV stabilization grade to control light intensity, temperature, and moisture retention in protected cultivation environments. HDPE dominates volume production due to its tensile strength and recyclability, while knitted fabric configurations command premium positioning in commercial greenhouse installations where dimensional stability under wind load determines replacement cycles. Agriculture absorbs the majority of off-take as protected cultivation expands, though commercial landscaping applications for nurseries and urban green infrastructure are gaining traction among contractors seeking certified horticultural textiles.
REACH compliance in Europe and FDA indirect food-contact guidelines in the United States constrain additive formulations and recycling content claims, pushing manufacturers toward certified virgin resin documentation. India's BIS certification for agricultural plastics and the EU F-Gas Regulation indirectly stimulate shade net demand by restricting mechanical cooling in greenhouses. Stakeholders must monitor evolving polymer sustainability mandates and regional horticultural subsidy programs that determine replacement timing and specification upgrades across buyer segments.
Market Dynamics
The shade net market is rebalancing around polymer sustainability mandates and mechanical cooling restrictions that force greenhouse operators toward passive climate control textiles rather than energy-intensive HVAC systems.
Growth Catalysts
- EU F-Gas Regulation:Restrictions on hydrofluorocarbon-based mechanical cooling in Spanish and Italian greenhouse clusters are accelerating protective netting installations as operators seek passive temperature management alternatives.
- HDPE filament extrusion advances:UV-stabilized knitted configurations with enhanced tensile strength are displacing woven alternatives in commercial procurement channels serving large-scale protected cultivation.
- Urban green infrastructure:Municipal contractors in France and Germany are specifying certified horticultural textiles for nursery and landscaping applications beyond traditional agriculture.
Market Restraints
- Virgin resin cost volatility:HDPE feedstock price swings constrain margin stability for manufacturers lacking backward integration into polymer production.
- REACH compliance documentation:Additive formulation restrictions in Europe require certified virgin resin traceability that raises administrative burden and disqualifies recycled content claims.
- Woven commodity substitution:Lower-specification woven shade nets from concentrated South Asian supply bases compete on price for non-commercial applications.
Strategic Opportunities
- India BIS certification pathway:Agricultural plastics standardization creates premium positioning for quality-compliant exporters targeting protected cultivation expansion in Maharashtra and Gujarat.
- Dual-use marine-agricultural formulations:High-tenacity polyethylene netting originally developed for aquaculture is finding application in wind-exposed greenhouse installations requiring dimensional stability.
- EU Green Deal subsidy alignment:Horticultural subsidy programs tied to sustainability metrics are timing replacement cycles toward specification upgrades rather than cost-minimization.
Industry Challenges
- Polymer chemist talent scarcity:Formulation expertise for UV stabilization and antioxidant packages concentrates among aging technical workforces in European and Japanese resin compounders.
- Certification timeline compression:BIS, REACH, and FDA indirect food-contact documentation requirements run on misaligned review schedules that delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shade Net Market |
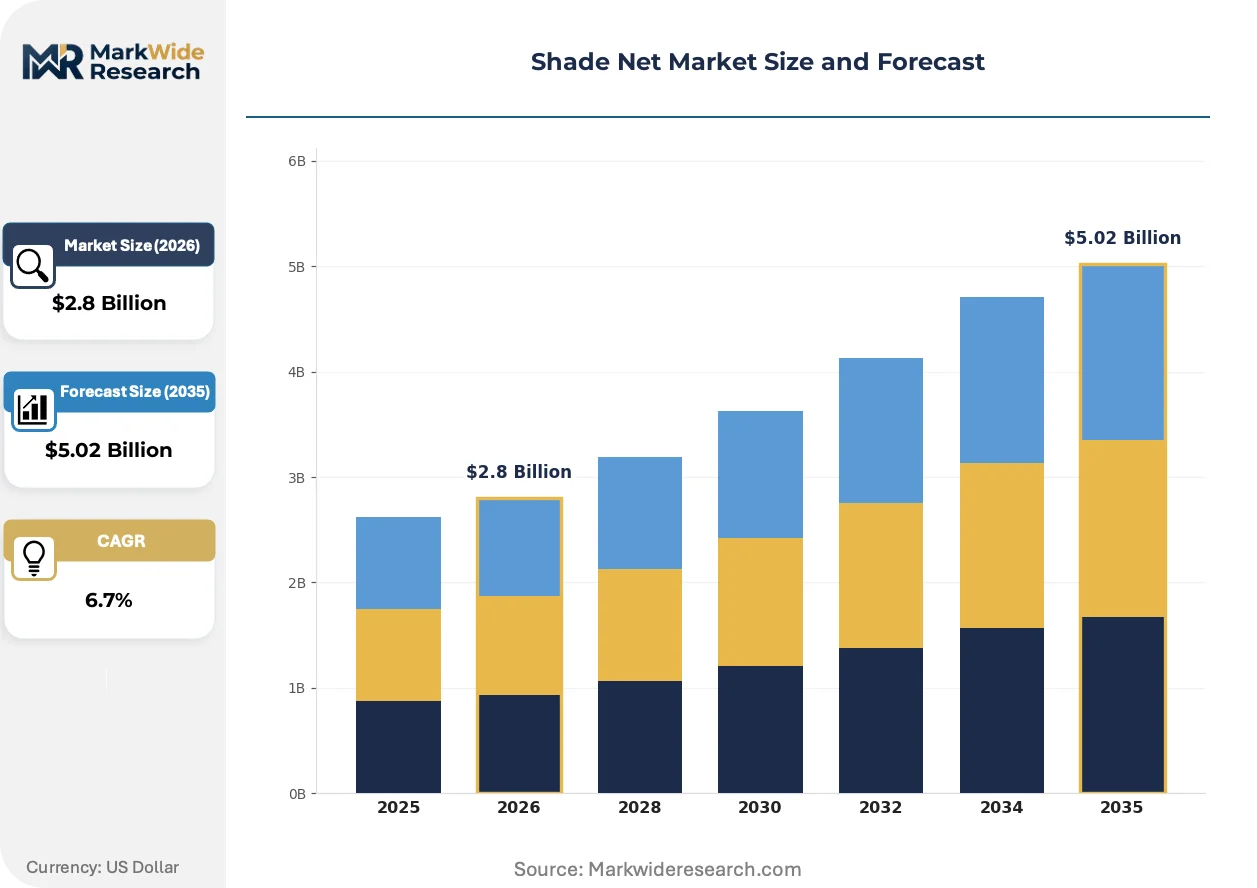
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HDPE, PVC, Shade Cloth, Knitted Fabric Application: Agriculture, Greenhouses, Garden, Commercial Material: Polyethylene, Polyester, Polypropylene, Natural Fibers End User: Farmers, Landscapers, Nurseries, Retailers |
| Companies Covered | EyouAgro, Palram Industries Ltd., Berry Global Inc., Arrigoni, Green-Tek Inc., Ginegar Plastic Products Ltd., Garware Technical Fibre, US Netting, Koninklijke Ten Cate N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shade Net Market Strategic Shifts
Material science advances and regulatory pressure on mechanical cooling are rewriting competitive positioning around passive climate control performance rather than shade percentage alone.
Monofilament HDPE with co-extruded UV stabilizer packages is rewriting durability expectations for commercial greenhouse installations. Dutch and Belgian operators are specifying 5-year replacement cycles rather than 2-3 year intervals. This compression of total cost of ownership calculations is favoring premium knitted configurations over commodity woven alternatives.
REACH SVHC candidate list expansion is restricting certain antioxidant and light stabilizer chemistries used in agricultural plastics. Manufacturers are reformulating additive packages to maintain UV resistance performance under tighter substance restrictions. German and Italian compounders are investing in alternative stabilizer systems ahead of anticipated authorization requirements.
Specification-driven procurement is consolidating buyer influence among large greenhouse operators with technical staff capable of evaluating tensile retention and air permeability data. Regional distributors with agronomy expertise are displacing generalist horticultural suppliers in Spain and Italy. This channel shift is compressing margins for intermediaries lacking technical advisory capabilities.
Shade Net Market Segmentation
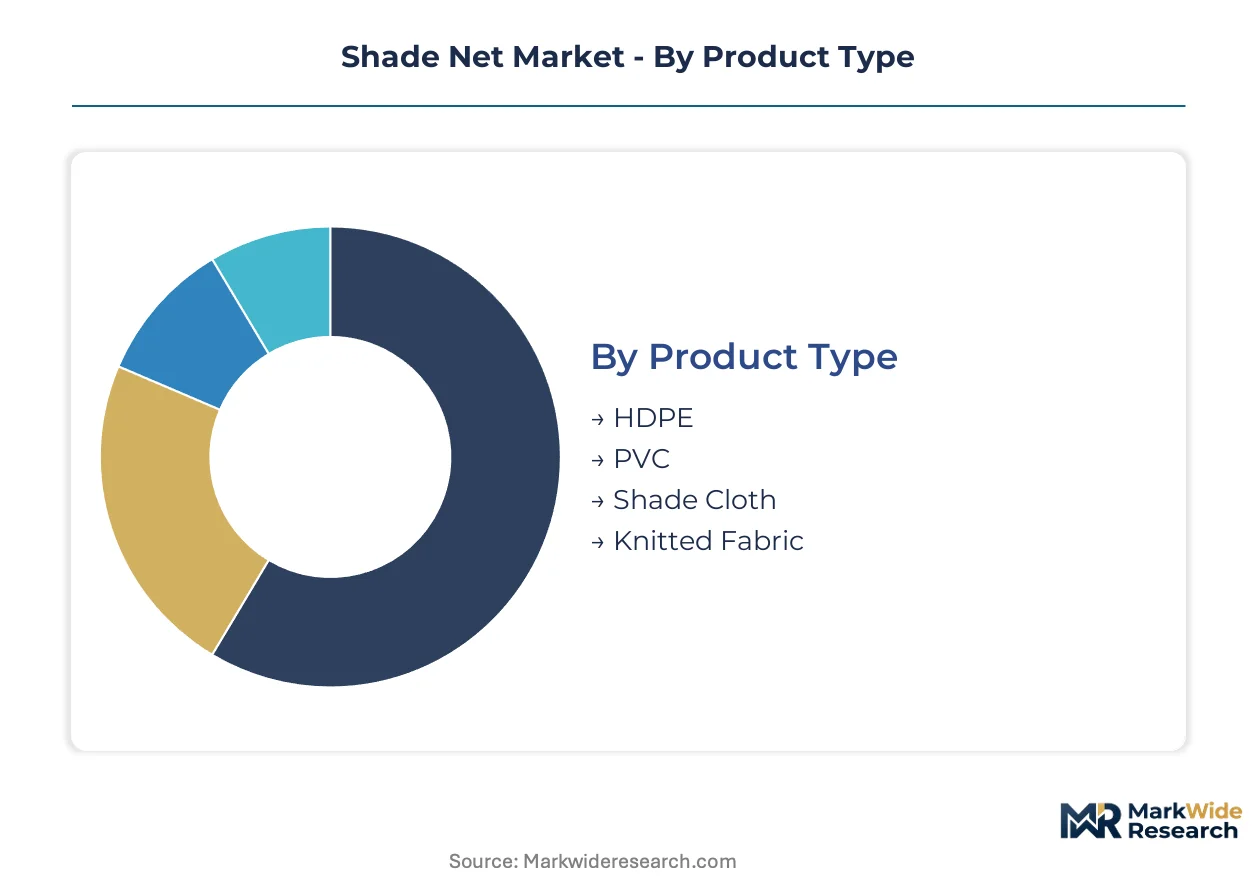
Shade net procurement decisions increasingly hinge on replacement-cycle economics rather than upfront cost alone. Specification-grade materials with extended UV warranties command premium positioning as greenhouse operators amortize installation labor over longer service intervals.
Product Type:
Upgrade cycles vary dramatically by polymer formulation and fabric construction, with UV-stabilized knitted alternatives displacing woven commodity grades in commercial installations.
- HDPE:High-density polyethylene monofilaments dominate commercial volume through superior tensile strength and recyclability. Dutch and Belgian greenhouse operators specify HDPE configurations with co-extruded stabilizer packages that compress replacement cycles from three years toward five.
- Knitted Fabric:Interlocking loop constructions provide dimensional stability under wind load that woven alternatives cannot match. Spanish greenhouse clusters in Almería and Murcia are consolidating procurement around knitted specifications as EU F-Gas Regulation restrictions eliminate mechanical cooling redundancy.
- Shade Cloth:Woven tape-laminated constructions serve cost-sensitive nursery applications where wind exposure remains moderate.
- PVC:Coated vinyl formulations retain niche positioning in high-humidity environments requiring chemical resistance beyond standard polyethylene.
Volume placements concentrate in HDPE; the faster expansion belongs to knitted fabric.
Application:
Cost-tier stratification separates specification-driven commercial installations from price-sensitive residential and small-farm procurement.
- Greenhouses:Controlled-environment agriculture demands certified horticultural textiles with documented UV retention and air permeability metrics. Italian operators in Sicily and Puglia are timing shade net replacements to align with EU Green Deal subsidy windows.
- Agriculture:Open-field protected cultivation in Maharashtra and Gujarat absorbs commodity-grade woven netting for hail protection and light diffusion. India's BIS certification pathway is filtering substandard imports from regional supply bases.
- Commercial:Municipal landscaping contracts in France and Germany specify certified textiles for urban green infrastructure projects.
- Garden:Retail consumer channels favor pre-cut residential formats with lower specification thresholds.
Greenhouse applications capture the premium margin tier; agriculture delivers the volume base.
Material:
Supply concentration among resin compounders with formulation expertise shapes regional availability of performance-grade stabilizer packages.
- Polyethylene:HDPE and LDPE variants command agricultural volume through processability and recyclability. German and Italian compounders are reformulating antioxidant systems ahead of anticipated REACH SVHC authorization requirements.
- Polypropylene:Lower density and higher melting point suit specific greenhouse climate zones with elevated temperature profiles.
- Polyester:Higher modulus fibers serve marine-agricultural dual-use applications requiring extreme dimensional stability.
- Natural Fibers:Jute and coir alternatives retain minimal share amid durability limitations and moisture degradation.
Polyethylene anchors procurement volume; polyester climbs fastest in specialized wind-load applications.
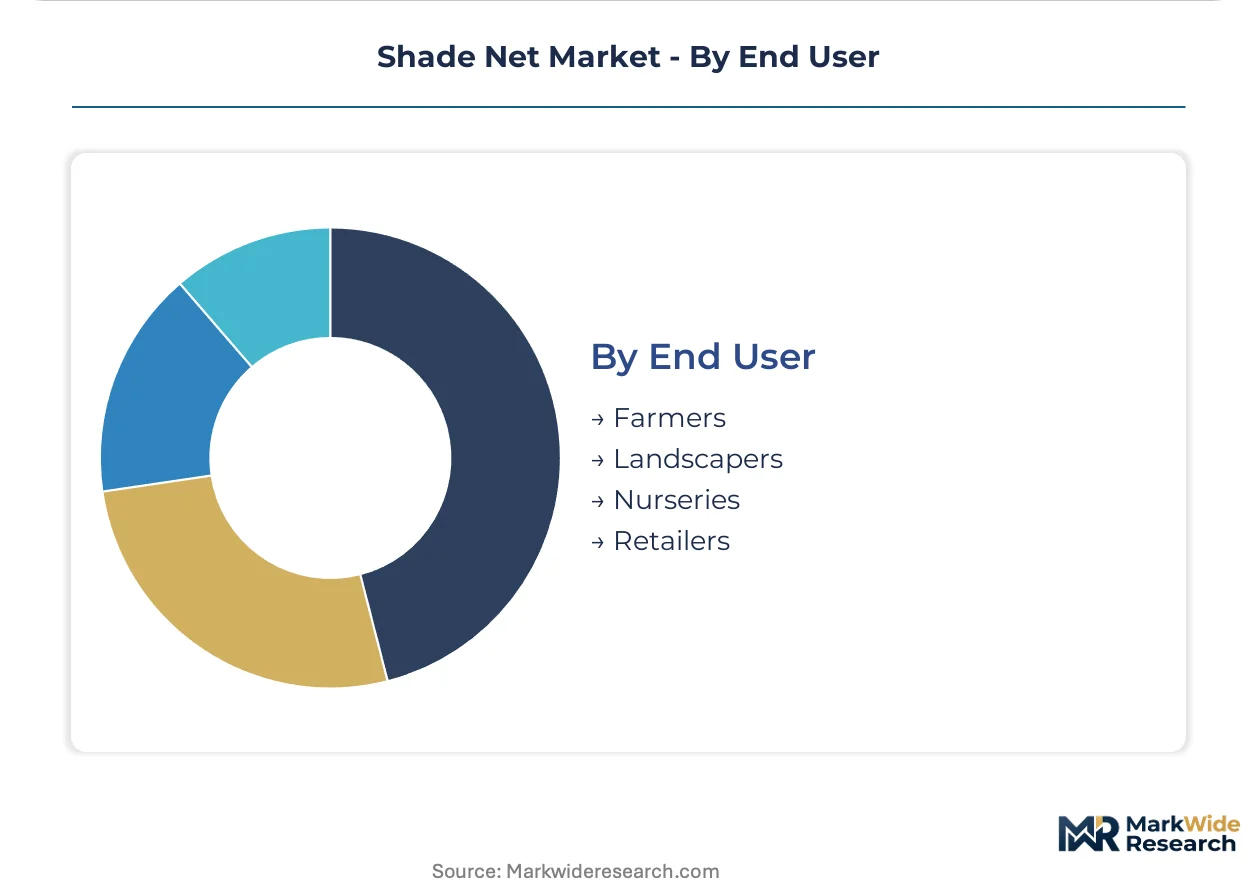
End User:
Customer-type segmentation reveals diverging technical advisory needs and contract-scale economics across buyer categories.
- Farmers:Large-scale protected cultivation operators in Spain and Italy employ technical staff capable of evaluating tensile retention data and air permeability specifications. These buyers are consolidating procurement through regional distributors with agronomy expertise.
- Nurseries:Plant propagation facilities require precise shade percentage control for seedling hardening protocols.
- Landscapers:Municipal and commercial contractors in France and Germany specify certified horticultural textiles for nursery and urban green infrastructure installations.
- Retailers:Consumer-facing channels serve garden-center demand with standardized pre-cut formats and limited technical documentation.
Farmers drive specification-grade volume; landscapers represent the steepest expansion trajectory as urban green infrastructure mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Almería and Murcia in southeastern Spain host Europe's densest concentration of protected cultivation, where greenhouse operators are replacing mechanical cooling systems with advanced shade netting to comply with tightening environmental regulations.
Spain
Greenhouse clusters in Almería and Murcia are accelerating shade net procurement as EU F-Gas Regulation restrictions eliminate hydrofluorocarbon-based cooling options. Spanish operators are timing installations to align with EU Green Deal subsidy windows for sustainable agriculture. The southeastern corridor now specifies UV-stabilized knitted configurations with five-year replacement cycles.
Italy
Sicily and Puglia are expanding protective netting coverage for tomato and citrus protected cultivation. Italian operators leverage national horticultural subsidies tied to EU Green Deal sustainability metrics. The southern regions are consolidating procurement through technical distributors capable of evaluating tensile retention specifications.
Netherlands
Dutch greenhouse operators in Westland and Aalsmeer are specifying premium knitted shade nets with co-extruded stabilizer packages. The national agricultural regulator enforces strict documentation requirements for horticultural textile certification. These specifications are compressing replacement cycles from three years toward five.
India
Maharashtra and Gujarat are absorbing commodity-grade woven netting for open-field hail protection and light diffusion. BIS certification requirements for agricultural plastics are filtering substandard imports from regional supply bases. Western Indian states are expanding protected cultivation acreage under national food security programs.
United States
California's Central Valley greenhouse operators are sourcing certified horticultural textiles for vegetable and berry protected cultivation. FDA indirect food-contact guidelines constrain additive formulations for agricultural plastics used near produce. Large operators in Salinas and Santa Maria are consolidating procurement through pallet-volume contracts.
Shade Net Market Competitive Environment
Premium-margin players sit above commodity-margin players across specification-grade versus price-tier dimensions. The vendor base stratifies between integrated filament extruders controlling resin quality and distributors reliant on third-party supply. Three archetypes dominate: backward-integrated manufacturers with captive polymer production, specialized high-tenacity compounders serving dual-use applications, and scale-driven distributors leveraging North American logistics networks. Competitive moves concentrate on capacity expansion in UV-stabilized knitted configurations and strategic partnerships with regional agronomy advisory services.
Among the named fabricators, EyouAgro exemplifies the backward-integrated archetype with control over filament extrusion from resin to finished roll. Garware Technical Fibre anchors the South Asian supply base as a specialized high-tenacity polyethylene compounder. Berry Global Inc. occupies the scale-driven distributor position with North American pallet-volume contract capabilities. These three represent the structural tension between quality control, specialized formulation, and logistics scale that defines competitive positioning.
| Leading Market Players |
|---|
| EyouAgro |
| Palram Industries Ltd. |
| Berry Global Inc. |
| Arrigoni |
| Green-Tek Inc. |
| Ginegar Plastic Products Ltd. |
| Garware Technical Fibre |
| US Netting |
| Koninklijke Ten Cate N.V. |
| Others |
Value Chain & Pricing Dynamics
Backward integration into HDPE filament extrusion anchors both supply security and pricing power for manufacturers like EyouAgro, while distributors lacking captive resin capabilities absorb margin compression from virgin feedstock volatility. This structural divide between integrated compounders and procurement-dependent intermediaries shapes competitive economics across European and North American greenhouse supply channels.
Pricing Analysis
Replacement-cycle economics anchor value-based pricing for shade nets, with Dutch and Belgian operators amortizing installation labor over five-year UV warranty periods rather than upfront roll costs. Three-tier pricing structure across premium knitted, standard woven, and economy tape-laminated configurations separates specification-grade buyers from price-sensitive nursery operators. Cost compression in commodity woven tiers is intensifying because South Asian supply bases exploit resin cost advantages. Large greenhouse operators with technical evaluation staff show lowest price sensitivity; small-scale Indian open-field farmers exhibit highest.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Hamburg anchor European hub-and-spoke patterns for horticultural textile fulfillment. Manufacturing concentrates in China, India, and Germany for distinct tiers: Chinese producers dominate commodity woven volume, Indian compounders serve regional protected cultivation expansion, German specialists control premium stabilizer formulation. Raw material dependencies include HDPE resin, UV stabilizer packages, and antioxidant additives. Single-source vulnerability in European stabilizer compounders feeds supply risk. Distribution runs through agronomy-specialist distributors displacing generalist horticultural suppliers in Spain and Italy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polymer chemist talent scarcity props pricing for UV stabilization expertise, constraining capacity expansion among European and Japanese compounders and sustaining premium-tier margins.
For Market Incumbents: To counter woven commodity substitution from South Asian supply bases, backward integration into resin extrusion secures feedstock cost control against virgin HDPE volatility. Incumbents should deepen channel control through exclusive agronomy advisory partnerships with Spanish and Italian greenhouse clusters, locking specification-driven procurement away from price-competing intermediaries. For New Entrants and Emerging Players: Launch via technical distributor partnerships targeting Maharashtra and Gujarat protected cultivation expansion under India's BIS certification pathway. White-space concentrates in dual-use marine-agricultural formulations for wind-exposed installations, and in REACH-compliant additive packages ahead of anticipated SVHC authorization requirements. Municipal landscaping contracts in France and Germany offer the most penetrable entry vector with certified horticultural textile mandates. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to packaging conglomerates seeking horticultural textile diversification. Long-term viability favors compounders with captive stabilizer formulation capabilities and documented regulatory compliance across REACH, FDA, and BIS frameworks. The signal to watch is EU Green Deal subsidy window timing, which accelerates replacement-cycle demand toward specification-grade products.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into HDPE Extrusion | Captive resin production insulates margin from feedstock volatility affecting distributor-dependent competitors. |
| REACH-Compliant Stabilizer Reformulation | Anticipatory chemistry investment ahead of SVHC authorization protects European market access. |
| Regional Agronomy Advisory Partnerships | Technical distribution alliances in Almería and Sicily consolidate specification-grade procurement channels. |
| BIS Certification Pathway Investment | Quality compliance documentation unlocks premium positioning in Maharashtra and Gujarat expansion zones. |
| Dual-Use Marine-Agricultural Formulation | High-tenacity polyethylene developed for aquaculture transfers to wind-load greenhouse applications. |
Study Parameters
Multi-period observation of replacement-cycle timing, EU F-Gas Regulation compliance patterns, and BIS certification adoption rates anchored the trend analysis, supplemented by interviews with greenhouse operations managers, horticultural textile procurement leads, polymer compounding R&D directors, and regional distribution channel partners. Secondary validation drew from ECHA REACH substance registrations, EU Green Deal agricultural subsidy disclosures, Indian BIS standards documentation, and SEC filings of listed packaging conglomerates. Bottom-up volume modeling triangulated against top-down macroeconomic horticultural investment flows.
Segment-weighting applied product type, application tier, material formulation, and end-user technical capability dimensions across the projection horizon. CAGRs derived from replacement-cycle compression trends in Dutch and Belgian installations, subsidy-aligned procurement timing in Spain and Italy, and protected cultivation acreage expansion in western India. Industry-specific inputs included UV stabilization warranty period migration and mechanical cooling restriction enforcement trajectories.
Polymer feedstock price volatility, REACH SVHC list expansion timing, and EU horticultural subsidy program continuity are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and replacement-cycle behavioral shifts. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Fabrics
Nonwoven Crop Cover Market
Agricultural Fabrics
US Agro Textile Market
Agricultural Fabrics
South America Agricultural Films Market
Agricultural Fabrics
Hay Bags Market
Agricultural Fabrics
Canopy Market
Agricultural Fabrics
Mulching Materials Market
Agricultural Fabrics
Silo Bags Market
Agricultural Fabrics
Silage Bags Market
Agricultural Fabrics
Horticulture Film Market
Agricultural Fabrics
Asia-Pacific Agricultural Films Market
Agricultural Fabrics
North America Agricultural Films Market
Agricultural Fabrics
Biodegradable Mulch Film Market
Agricultural Fabrics
North America Silo Bags Market
Agricultural Fabrics
Agricultural Fabrics Market
Agricultural Fabrics
Pond Liners Market
Agricultural Fabrics
Global Mulch Films Market