
 China Greenhouse Horticulture Market | 2026-2036
China Greenhouse Horticulture Market Size, Share, and Industry Trends Forecast 2026-2036
China Greenhouse Horticulture Market Insights
Software-defined climate management is rebalancing what Chinese greenhouse operators purchase, shifting capital from fixed infrastructure toward subscription-based environmental control platforms. Kingpeng International Hi-Tech Corporation leverages its domestic manufacturing scale to anchor large turnkey projects across northern provinces. Hoogendoorn Growth Management B.V. competes through proprietary algorithm-driven irrigation systems tailored to high-value vegetable production. Priva Holding B.V. differentiates by extending its Dutch technology leadership into premium glass greenhouse segments serving export-oriented growers.
Greenhouse horticulture denotes the cultivation of crops within enclosed structures where temperature, humidity, light, and CO2 levels are actively regulated, typically employing steel or aluminum framing with glass or polyethylene cladding and integrated heating, cooling, and ventilation subsystems. The primary purpose is to decouple agricultural output from seasonal and geographic constraints, enabling year-round production of high-value perishables for domestic consumption and cross-border trade. Vegetables command the dominant share of installed greenhouse area in China, reflecting sustained procurement from supermarket chains and foodservice distributors, while hydroponics represents the fastest-expanding technology category as water-scarce regions in the north and northwest mandate soilless cultivation methods. Flowers retain concentrated margin pools in the Yunnan and Guangdong production belts, where rose and orchid exports to Southeast Asia generate premium pricing.
China's Ministry of Agriculture and Rural Affairs sets structural standards for modern agricultural facilities, while MIIT promotes IoT and automation integration through dedicated smart agriculture funding channels. The national dual carbon goals from MEE are forcing energy-intensive coal-heated greenhouses toward geothermal, biomass, or solar thermal retrofits, reshaping equipment procurement specifications. GB standards for agricultural film and structural materials dictate product compliance thresholds for both domestic suppliers and imported subsystem vendors. Stakeholders must monitor how provincial implementation timelines for carbon intensity reductions will alter the economic viability of existing polyethylene-covered structures versus glass replacement cycles.
Market Dynamics
China's dual carbon goals are forcing coal-dependent greenhouse operators to abandon fossil heating, triggering wholesale equipment replacement cycles and reshaping supplier relationships across the Yangtze River Delta and northern provinces.
Growth Catalysts
- MIIT smart agriculture directives:IoT integration mandates are accelerating automation adoption in Jiangsu and Zhejiang facilities, with provincial funding channels covering 30-50% of sensor deployment costs for qualifying operations.
- Urban retail procurement consolidation:Supermarket chains and foodservice distributors are demanding year-round supply contracts that only climate-controlled cultivation can fulfill, pulling investment toward glass and advanced polyethylene structures.
- Geothermal retrofit subsidies:Provincial energy bureaus in Shandong and Hebei are offering capital grants for ground-source heat pump installations, displacing coal boilers in legacy facilities.
Market Restraints
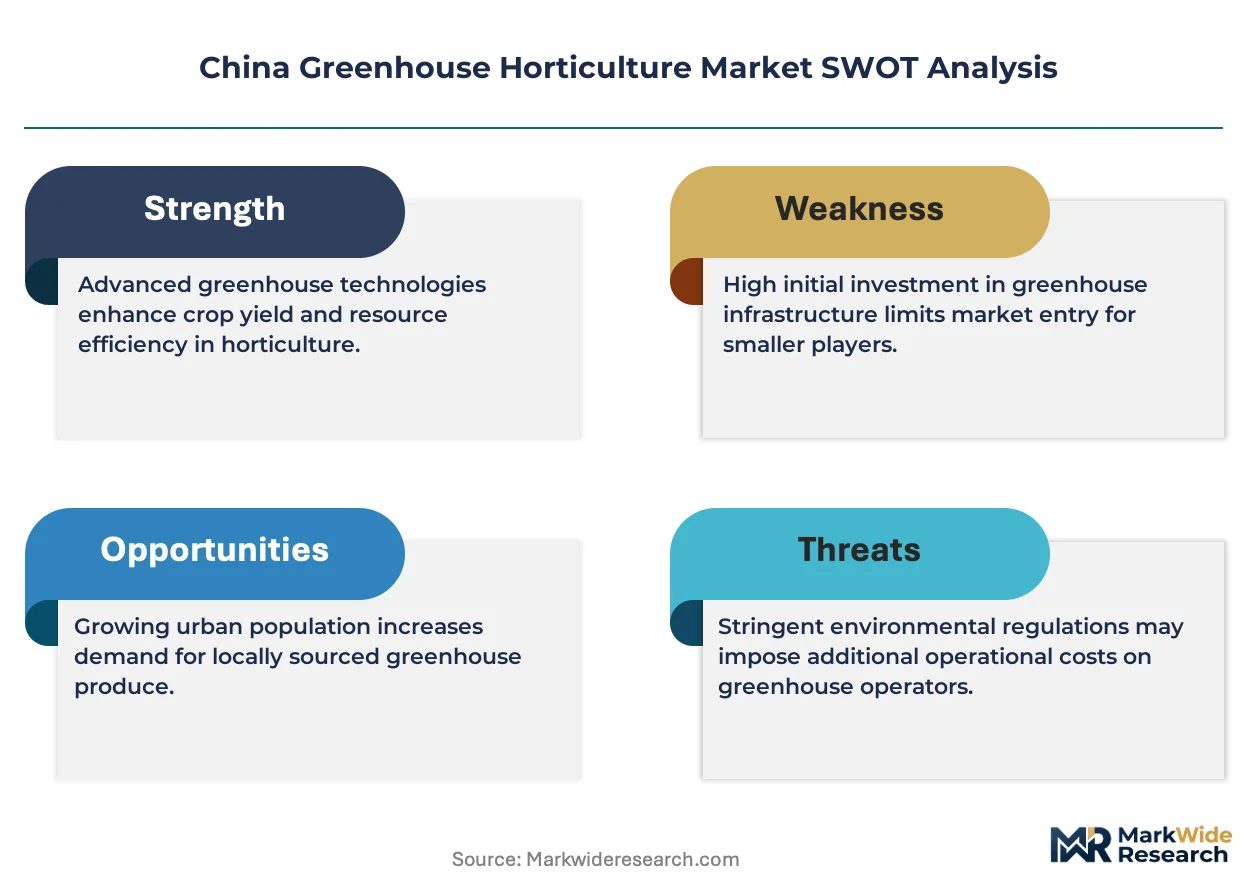
- Structural steel and aluminum price volatility:Raw material input swings compress margins for domestic frame manufacturers, delaying expansion timelines for turnkey project developers.
- Dutch subsystem vendor concentration:Climate control algorithms and precision irrigation hardware remain concentrated among Benelux suppliers, exposing buyers to euro-denominated procurement risk and extended lead times.
- GB standards compliance friction:Agricultural film and structural material certification requirements create 6-12 month product approval delays for imported cladding systems.
Strategic Opportunities
- Northwest hydroponics penetration:Ningxia and Xinjiang water scarcity is mandating soilless cultivation expansion, creating white space for integrated nutrient film technique system providers.
- Carbon credit monetization:MEE provincial implementation timelines are enabling certified greenhouse operators to trade emission reductions through national ETS mechanisms.
- Subscription climate control platforms:Software-defined environmental management is expanding into mid-scale operations previously priced out of algorithm-driven cultivation.
Industry Challenges
- Agritech systems integration talent gap:Shortage of technicians capable of calibrating multi-parameter climate controllers is extending commissioning timelines for automated facilities.
- Legacy coal boiler decommissioning capex:Operators face stranded asset risk as provincial carbon intensity deadlines accelerate heating system replacement ahead of depreciation schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Greenhouse Horticulture Market |
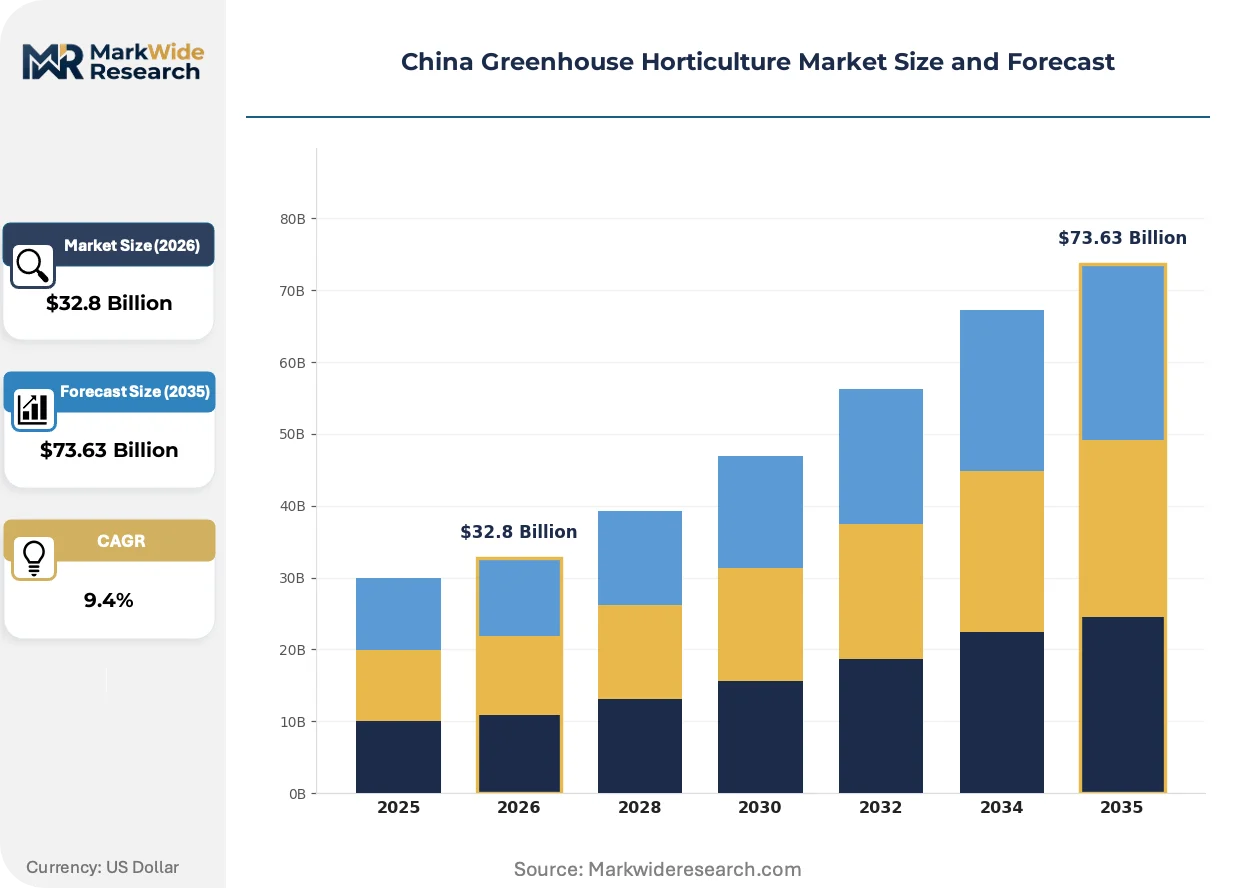
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $73.63 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetables, Fruits, Flowers, Herbs Technology: Hydroponics, Aeroponics, Soil-based, Organic End User: Commercial Growers, Research Institutions, Hobbyists, Agribusiness Distribution Channel: Direct Sales, Online Retail, Wholesale, Distributors |
| Companies Covered | Dalsem, Hoogendoorn Growth Management B.V., Kingpeng International Hi-Tech Corporation, Netafim Ltd., HortiMaX B.V., Richel Group, Priva Holding B.V., Van der Hoeven Horticultural Projects B.V., Certhon, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Greenhouse Horticulture Market Trends and Innovations
Digital cultivation platforms are displacing manual climate management, while regulatory pressure on carbon intensity and water use is compressing technology replacement cycles across production belts.
AI-driven yield prediction systems are expanding into commercial greenhouse operations, integrating computer vision with environmental sensor networks to forecast harvest timing and quality grades. Large vegetable producers in Shandong are deploying these platforms to optimize harvest labor scheduling and reduce post-harvest loss. The technology is expanding into contract farming arrangements, enabling price negotiations based on verified production forecasts rather than historical averages.
MEE carbon intensity benchmarks are forcing equipment procurement specification changes, with provincial environmental bureaus rejecting permit applications for coal-heated structures in designated low-carbon zones. Glass greenhouse developers in Jiangsu are prioritizing geothermal and biomass thermal systems to secure construction approvals. The policy shift is compressing polyethylene structure replacement cycles as operators accelerate glass retrofits to maintain license eligibility.
Fresh vegetable procurement is consolidating around direct supplier-retailer partnerships, with supermarket chains bypassing traditional wholesale markets to contract dedicated greenhouse capacity. Hema Fresh and similar new retail platforms are demanding traceability data and carbon footprint documentation that fragmented growers cannot provide. This concentration is visible across Shanghai and Hangzhou, where controlled-environment producers are capturing volume commitments previously held by open-field suppliers.
China Greenhouse Horticulture Market Segmentation
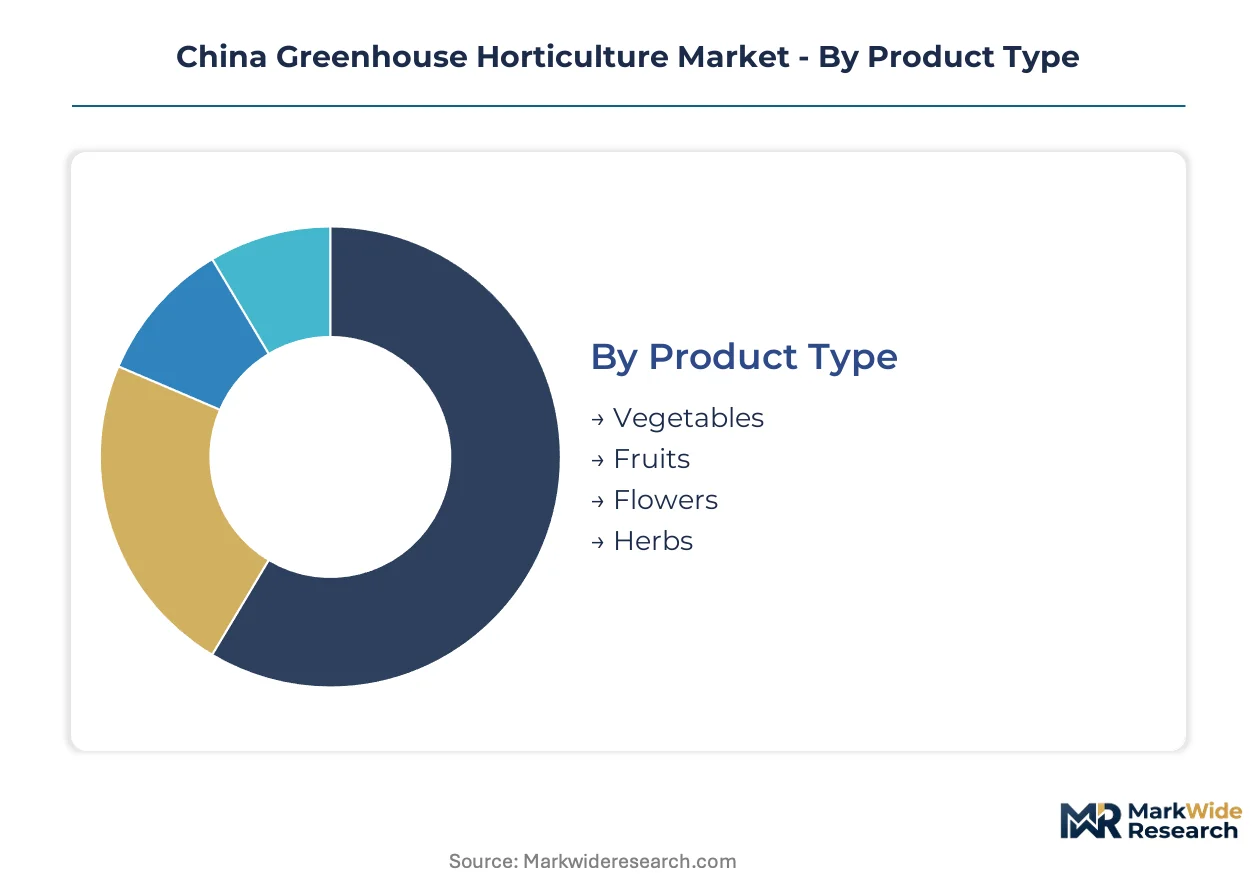
Segmentation in the China greenhouse horticulture market reveals how regulatory requirements, technology maturity, and procurement scale reshape operator investment priorities across distinct cultivation categories. Understanding these divides exposes where MIIT smart agriculture funding flows concentrate and which segments face the steepest carbon retrofit compliance burdens.
Product Type:
GB standards for agricultural film and structural materials impose tiered certification intensity across crop categories, with export-oriented segments facing additional phytosanitary documentation requirements from customs authorities.
- Vegetables:Encompasses tomatoes, cucumbers, peppers, and leafy greens cultivated in climate-controlled environments for year-round supermarket supply. Yangtze River Delta retail chains including Hema Fresh and Yonghui Superstores are consolidating procurement contracts around Shandong and Jiangsu greenhouse clusters, demanding traceability systems that only integrated environmental controls can deliver. Vegetables sit at the top of the volume ranking, with hydroponic leafy greens climbing the fastest.
- Fruits:Strawberries, melons, and specialty berries dominate this segment, requiring precise humidity management and extended light-cycle controls. Northern province operators in Hebei and Liaoning are retrofitting polyethylene structures with LED supplementation to capture premium pricing from winter strawberry harvests that command 40-60% markups over open-field imports.
- Flowers:Rose and orchid cultivation concentrates in Yunnan and Guangdong export belts, where phytosanitary certification for Southeast Asian markets drives investment in sealed glass environments with full climate telemetry.
- Herbs:Medicinal and culinary herb production serves domestic TCM pharmaceutical processors and high-end restaurant supply chains, with organic certification requirements limiting viable cultivation area.
Vegetables dominate installed greenhouse area, while fruits gain share fastest as northern operators pursue counter-seasonal premium pricing.
Technology:
Capital intensity and water-use efficiency separate these technology categories, with provincial energy bureaus directing subsidy flows toward systems that advance dual carbon goals.
- Hydroponics:Nutrient film technique and deep water culture systems enable soilless cultivation with 70-90% water savings versus conventional agriculture. Ningxia and Xinjiang operators are deploying these systems under mandatory water scarcity directives, with provincial agricultural departments covering 30-50% of infrastructure costs for qualifying installations. Hydroponics commands the steepest expansion trajectory among all technology categories.
- Aeroponics:Mist-based root delivery systems maximize oxygen exposure and nutrient uptake efficiency, though high-pressure pump maintenance requirements limit adoption to research institutions and premium herb producers with technical staffing capacity.
- Soil-based:Conventional substrate cultivation retains dominance in legacy polyethylene structures across Shandong and Henan, where operators delay full automation retrofits until coal boiler replacement cycles align with depreciation schedules.
- Organic:Certification-compliant cultivation excluding synthetic inputs serves specialty retail channels and export markets, with GB/T 19630 standards imposing three-year conversion periods that constrain rapid scaling.
Soil-based systems retain the largest installed base, while hydroponics expands most quickly under water policy pressure.
End User:
Procurement scale and technical sophistication create sharp divides in automation adoption and climate control platform subscription willingness.
- Commercial Growers:Large-scale vegetable and flower producers operating facilities exceeding 10 hectares dominate equipment procurement volume. These operators are deploying AI-driven yield prediction systems to optimize harvest labor scheduling and secure supermarket chain contracts requiring verified production forecasts.
- Research Institutions:Agricultural universities and provincial academy of agricultural sciences facilities pilot novel cultivars and climate algorithms, though limited commercial scale constrains equipment vendor margin capture.
- Hobbyists:Small-scale balcony and backyard greenhouse operators purchase entry-level polyethylene kits through e-commerce channels, representing high unit volume but minimal climate control system attachment rates.
- Agribusiness:Vertically integrated food conglomerates including COFCO and Bright Food are building captive greenhouse capacity to secure supply chain control, favoring turnkey glass projects with full environmental telemetry.
Commercial growers absorb the majority of climate control platform subscriptions, with agribusiness integration accelerating fastest.
Distribution Channel:
Channel selection reflects equipment complexity and buyer technical sophistication, with integrated projects favoring direct relationships while standardized components flow through wholesale networks.
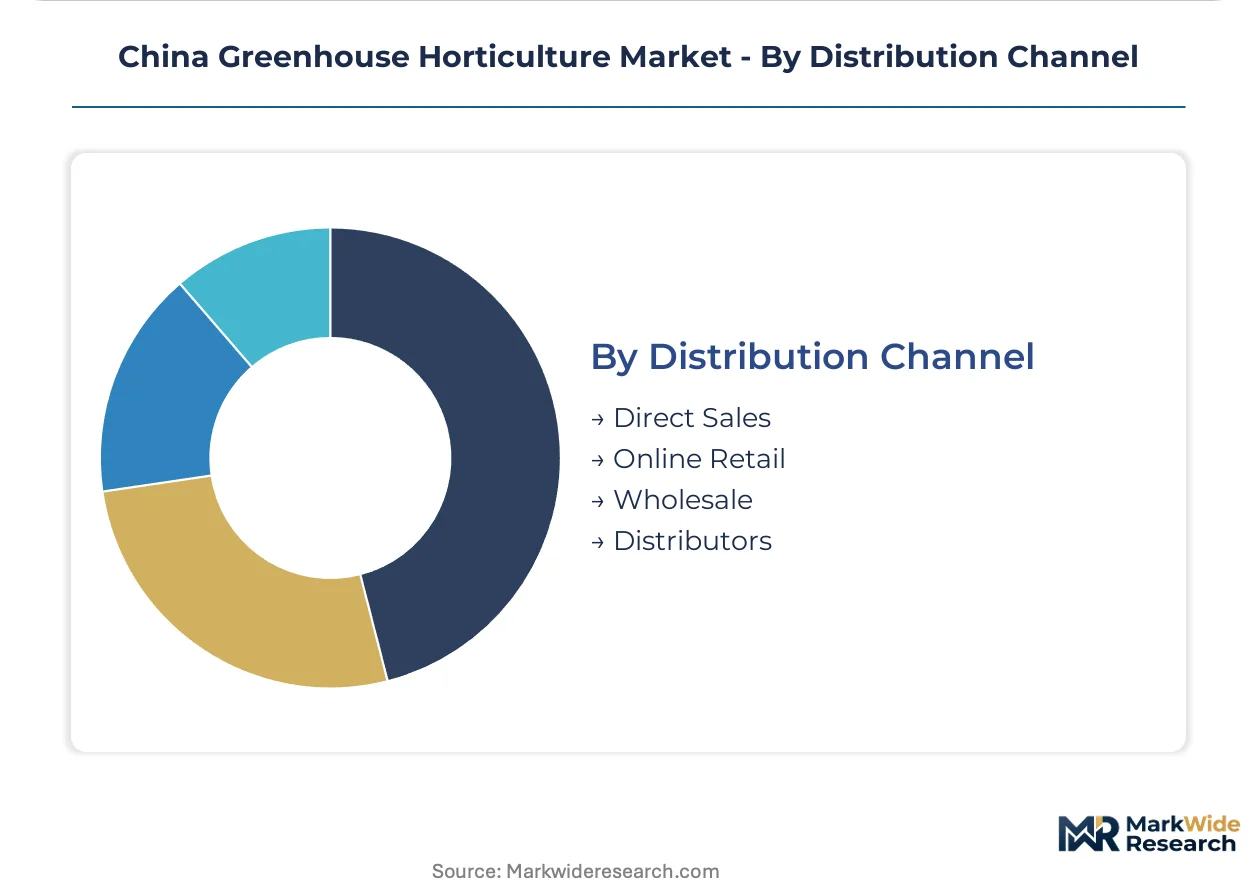
- Direct Sales:Turnkey greenhouse developers including Kingpeng International engage directly with agribusiness and commercial grower clients for projects exceeding 5 million yuan, embedding climate control software subscriptions into multi-year service agreements.
- Online Retail:Alibaba and JD.com channels dominate hobbyist polyethylene structure and basic sensor sales, with 1688.com serving small commercial operators seeking component-level procurement.
- Wholesale:Regional agricultural supply markets in Shouguang and Xuzhou aggregate standardized film, framing, and irrigation components for mid-scale operators avoiding direct manufacturer relationships.
- Distributors:Provincial-level agricultural equipment dealers provide installation and commissioning services for Dutch subsystem vendors including Hoogendoorn and Priva, capturing margin through technical support contracts.
Direct sales capture the highest project value concentration, with online retail gaining transaction volume fastest among entry-level buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's greenhouse horticulture expansion outpaces most international comparators in absolute hectare terms, though Dutch and Spanish operators maintain technology leadership in climate control sophistication and export-oriented glass infrastructure.
Shandong Province
Shandong's vegetable processing corridors drive polyethylene structure demand for tomato and cucumber cultivation. MIIT smart agriculture directives channel automation subsidies toward Weifang and Shouguang clusters, where commercial growers retrofit legacy coal-heated facilities with geothermal heat pumps to meet MEE carbon intensity benchmarks.
Jiangsu Province
Jiangsu's Yangtze River Delta positioning attracts glass greenhouse investment for premium leafy green supply to Shanghai retail networks. Provincial energy bureaus reject construction permits for fossil-dependent structures in designated low-carbon zones, accelerating Dutch technology adoption in Suzhou and Nantong production belts.
Hebei Province
Hebei's proximity to Beijing-Tianjin consumption centers supports winter strawberry cultivation under LED-supplemented polyethylene structures. Provincial agricultural departments fund ground-source heat pump installations displacing coal boilers, with Langfang and Shijiazhuang operators capturing premium pricing from counter-seasonal harvests.
Yunnan Province
Yunnan's flower export corridors concentrate rose and orchid cultivation in Kunming and Dali prefectures. Phytosanitary certification requirements for Southeast Asian markets drive investment in sealed glass environments with full climate telemetry, anchoring premium margin pools unavailable to open-field competitors.
China Greenhouse Horticulture Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated turnkey developers capturing high-value glass projects while component suppliers penetrate mid-scale polyethylene retrofits. The vendor base organizes around three strategic archetypes: Dutch climate control algorithm providers, Chinese domestic frame fabricators, and Israeli precision irrigation specialists. Competitive positioning sharpens through M&A consolidation among subsystem vendors and capacity expansion in geothermal equipment manufacturing.
Within the Dutch technology tier, Hoogendoorn Growth Management B.V. and Priva Holding B.V. occupy positions exemplifying algorithm-driven environmental control specialization. Kingpeng International Hi-Tech Corporation anchors the domestic turnkey developer archetype, leveraging Chinese manufacturing scale for large integrated projects across northern provinces. These three entities represent the competitive triangle shaping procurement relationships: European subsystem intelligence, Chinese execution capacity, and the integration interfaces between them.
| Leading Market Players |
|---|
| Dalsem |
| Hoogendoorn Growth Management B.V. |
| Kingpeng International Hi-Tech Corporation |
| Netafim Ltd. |
| HortiMaX B.V. |
| Richel Group |
| Priva Holding B.V. |
| Van der Hoeven Horticultural Projects B.V. |
| Certhon |
| Others |
Pricing and Supply Chain Analysis
Climate systems integration talent shortages in the Yangtze River Delta compress labor-cost differentials between premium Dutch-subscription tiers and domestic turnkey offerings, widening pricing spreads as operators trade algorithm sophistication for deployable commissioning capacity.
Pricing Analysis
Capacity additions in Shandong and Jiangsu are reshaping price floors for polyethylene structures as domestic frame fabricators expand manufacturing scale. Three-tier pricing structure across premium glass, mid-tier retrofitted polyethylene, and economy-grade basic cladding separates buyers by carbon compliance urgency and export certification requirements. Pricing pressure stems from raw material volatility in structural aluminum and steel inputs, with mid-scale commercial growers exhibiting highest price sensitivity while agribusiness captives absorb premium tiers for full telemetry integration.
Supply Chain Analysis
Domestic-content mandates under MIIT smart agriculture directives are reshaping sourcing patterns for sensor networks and automation subsystems. Climate control hardware draws from Benelux algorithm providers, Chinese frame fabricators, and Israeli precision irrigation specialists. Raw material dependencies center on structural steel, aluminum extrusions, and agricultural-grade polyethylene films. Single-source vulnerability concentrates in Dutch environmental control algorithms, while distribution runs through direct sales for turnkey projects and provincial dealer networks for component procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in carbon-compliant technology tiers as MEE intensity deadlines force equipment replacement cycles ahead of depreciation schedules, compressing payback periods for premium climate control platforms.
For Market Incumbents: Extend software-defined platform penetration into mid-scale operations previously priced out of algorithm-driven cultivation, while accelerating geothermal equipment manufacturing capacity to capture Shandong and Hebei retrofit demand. Consolidate around technical commissioning capabilities to offset agritech systems integration talent shortages threatening project timelines. For New Entrants and Emerging Players: Mid-scale vegetable producers in Ningxia and Xinjiang represent underserved buyer archetypes facing mandatory water scarcity directives without technical staffing for full automation. Penetrate through integrated nutrient film technique system offerings bundled with provincial subsidy navigation services, leveraging hydroponics infrastructure grants covering qualifying installation costs. For Investors and Strategic Acquirers: Agribusiness conglomerates building captive greenhouse capacity are the most active acquirer in this space, seeking turnkey developers with full environmental telemetry capabilities. Long-term viability hinges on carbon credit monetization infrastructure and ETS mechanism participation. Monitor MEE provincial implementation timeline acceleration as inflection signal for replacement cycle velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Geothermal Heat Pump Manufacturing Scale-Up | Captures Shandong and Hebei coal boiler replacement demand under MEE carbon intensity benchmarks. |
| Subscription Climate Control Platform Launch | Expands addressable market to mid-scale operators through SaaS-tiered environmental management. |
| Backward Integration into Sensor Hardware | Reduces euro-denominated procurement exposure from Dutch subsystem vendor concentration. |
| Carbon Credit Monetization Infrastructure | Enables certified operators to trade emission reductions through national ETS mechanisms. |
| Provincial Dealer Network Expansion | Captures margin through technical support contracts for mid-scale polyethylene retrofits. |
Research Methodology
Direct dialogue with greenhouse operations managers, climate control systems engineers, provincial agricultural department officials, and supermarket chain procurement directors grounded this analysis in operational reality. Secondary validation drew from MIIT smart agriculture funding disclosures, MEE carbon intensity benchmark publications, GB standards certification databases, and provincial energy bureau subsidy records. Bottom-up project pipeline tracking across Shandong, Jiangsu, and Hebei production belts triangulated against top-down market sizing from equipment vendor shipment data.
Bottom-up facility-level capacity modeling across technology tiers and crop segments combined with top-down macroeconomic elasticity assumptions over the projection horizon. Segmentation dimensions included cultivation technology, crop category, structure material class, and end-user procurement scale. CAGRs derived from replacement cycle velocity under regulatory deadlines and urban retail procurement consolidation trends, with carbon compliance cost curves and water scarcity policy intensity as key forecast inputs.
Underlying measurement precision varies by segment; hydroponics infrastructure expansion carries tighter precision than organic certification conversion timelines given policy mandate clarity. Forecasts reflect assumptions around provincial subsidy continuity and ETS mechanism participation eligibility. Commodity price volatility in structural metals and euro exchange rate fluctuation present revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Indoor Farming Technologies
Hydroponic Substrate Market
Indoor Farming Technologies
Aeroponics Market
Indoor Farming Technologies
Commercial Greenhouse Market
Indoor Farming Technologies
Indoor Farming Market
Indoor Farming Technologies
United States Grow Light Market
Indoor Farming Technologies
Vertical Farming Market
Indoor Farming Technologies
Europe Vertical Farming Market
Indoor Farming Technologies
Grow Tents Market
Indoor Farming Technologies
Canada Indoor Farming Market
Indoor Farming Technologies
Smart Indoor Gardening System Market
Indoor Farming Technologies
LED Grow Lights Market
Indoor Farming Technologies
Middle East Vertical Farming Market
Indoor Farming Technologies
Hydroponic System Market
Indoor Farming Technologies
Cannabis Vertical Farming Market
Indoor Farming Technologies
United States Plant Growth Chambers Market
Indoor Farming Technologies
North America Vertical Farming Market