
 Canopy Market | 2026-2036
Canopy Market Size, Share, and Industry Trends Forecast 2026-2036
Canopy Market Analysis
The EU Green Deal is repositioning canopy procurement across European commercial construction, mandating lower-carbon materials and extended product lifecycles. Sunair Awnings leverages its fabric technology leadership to meet these standards, while Shade Structures anchors its position through geographic dominance in UK public-sector contracts. KD Kanopy differentiates via manufacturing scale that supports rapid custom fabrication for festival deployments.
Canopies are tensioned or framed membrane structures engineered from polyester, vinyl, or canvas substrates, typically spanning three to twelve meters and designed to block UV radiation, shed precipitation, or create branded environments. Fabric and structure product types command the dominant share of current installations, though shelter configurations represent the fastest-growing category as disaster-relief and semi-permanent housing applications expand. Among end users, commercial users and festivals generate the deepest margin pools due to repeat purchasing cycles and customization requirements.
REACH regulations from ECHA govern chemical composition in coated canopy fabrics, while CE marking requirements enforce structural safety standards for temporary installations across EU member states. In the US, OSHA guidelines influence worker-safety specifications for industrial shade applications. Stakeholders must monitor evolving building codes and material certification thresholds as sustainability mandates tighten across multiple jurisdictions.
Market Dynamics
The EU Green Deal is compressing material selection windows across canopy manufacturing, forcing polyester and vinyl suppliers to certify recycled content percentages before products qualify for public procurement frameworks.
Growth Catalysts
- Festival infrastructure expansion:Outdoor event organizers in Germany are scaling semi-permanent shade deployments for multi-week programming, creating repeat fabrication cycles for tensioned membrane suppliers.
- REACH chemical compliance:ECHA-mandated coating reformulations are filtering out non-compliant fabric imports, clearing shelf space for certified European producers.
- Polyester recycling technology:Mechanical depolymerization advances are lowering rPET fabric costs, enabling price parity with virgin materials in municipal tender responses.
Market Restraints
- Aluminum extrusion supply concentration:Frame manufacturing depends on Chinese smelter output, exposing fabricators to alloy price volatility and shipping backlogs.
- CE marking timeline friction:Structural safety certification for temporary installations requires 8-14 week testing cycles, compressing festival deployment windows.
- Fixed shade structure substitution:Permanent pergola and tensile roof installations in commercial real estate are capturing long-term shade budgets that previously cycled to temporary canopies.
Strategic Opportunities
- Disaster-relief shelter applications:UNHCR and Red Cross procurement frameworks are expanding for rapid-deployment fabric shelters in climate-vulnerable zones.
- Photovoltaic fabric integration:Solar-cell-embedded membrane technology is converging with traditional shade products, opening premium positioning in off-grid commercial sites.
- UK public-sector channel consolidation:Crown Commercial Service frameworks are centralizing municipal canopy purchasing, favoring suppliers with G-Cloud registration and NHS estate experience.
Industry Challenges
- Structural engineering talent scarcity:Tensile membrane design requires specialized wind-load and snow-load calculation expertise that outpaces European university program output.
- Multi-jurisdiction certification stacking:Suppliers serving both EU and UK markets must maintain parallel CE and UKCA marking compliance, doubling testing expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canopy Market |
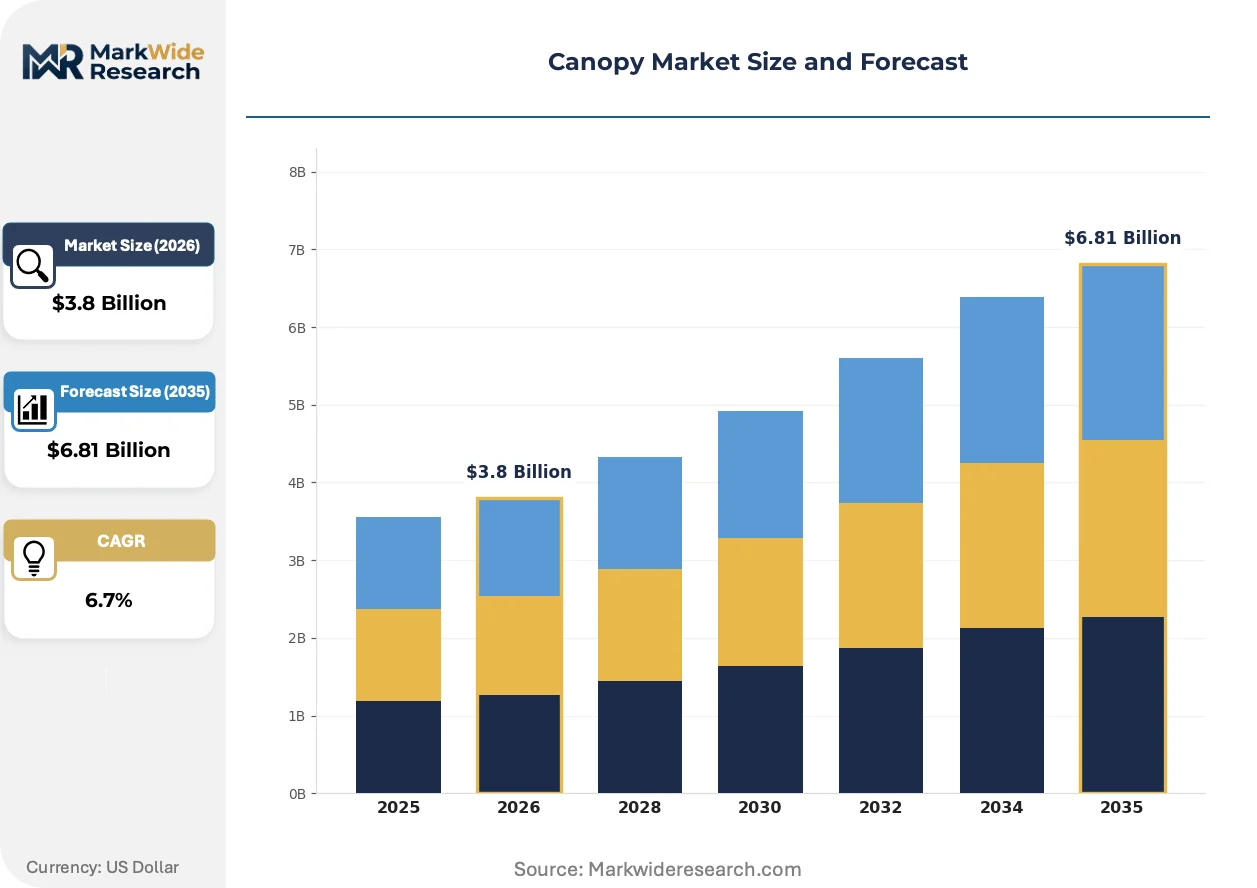
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tarp, Fabric, Structure, Shelter End User: Event Planners, Outdoor Enthusiasts, Commercial Users, Festivals Material: Polyester, Canvas, Mesh, Vinyl Application: Shade, Protection, Decoration, Storage |
| Companies Covered | Sunair Awnings, Shade Structures, Impact Canopy, Canopies UK, KD Kanopy, JAY JAY Enterprise, Eide Industries, Lawrence Fabric and Metal Structures, Advanced Design Awnings and Signs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canopy Market Emerging Trajectories
Material science breakthroughs and procurement digitization are compressing product development cycles while expanding the addressable use-case perimeter for tensioned fabric structures.
Photocatalytic titanium dioxide coatings are absorbing airborne pollutants during daylight exposure, enabling self-cleaning canopy surfaces that reduce maintenance contracts for festival operators and municipal park departments. Event organizers in the Netherlands and Belgium are specifying these finishes in multi-year rental agreements. The technology is absorbing premium pricing power previously attached to manual cleaning service bundles.
REACH Annex XVII restrictions on perfluorinated compounds are forcing vinyl coating reformulations across European supply chains, disqualifying legacy fabric inventories from public tender eligibility. German textile finishers are accelerating water-based polyurethane alternatives through TÜV certification pipelines. Municipal buyers in Bavaria and North Rhine-Westphalia are now rejecting non-compliant submissions before technical evaluation.
Digital twin configuration tools are displacing physical sampling in commercial canopy procurement, letting facility managers simulate wind performance and branding placement before fabrication commitment. UK festival organizers are adopting these platforms for multi-site equipment pooling. The shift is most visible in corporate hospitality verticals where approval cycles have compressed from six weeks to ten days.
Canopy Market Segmentation
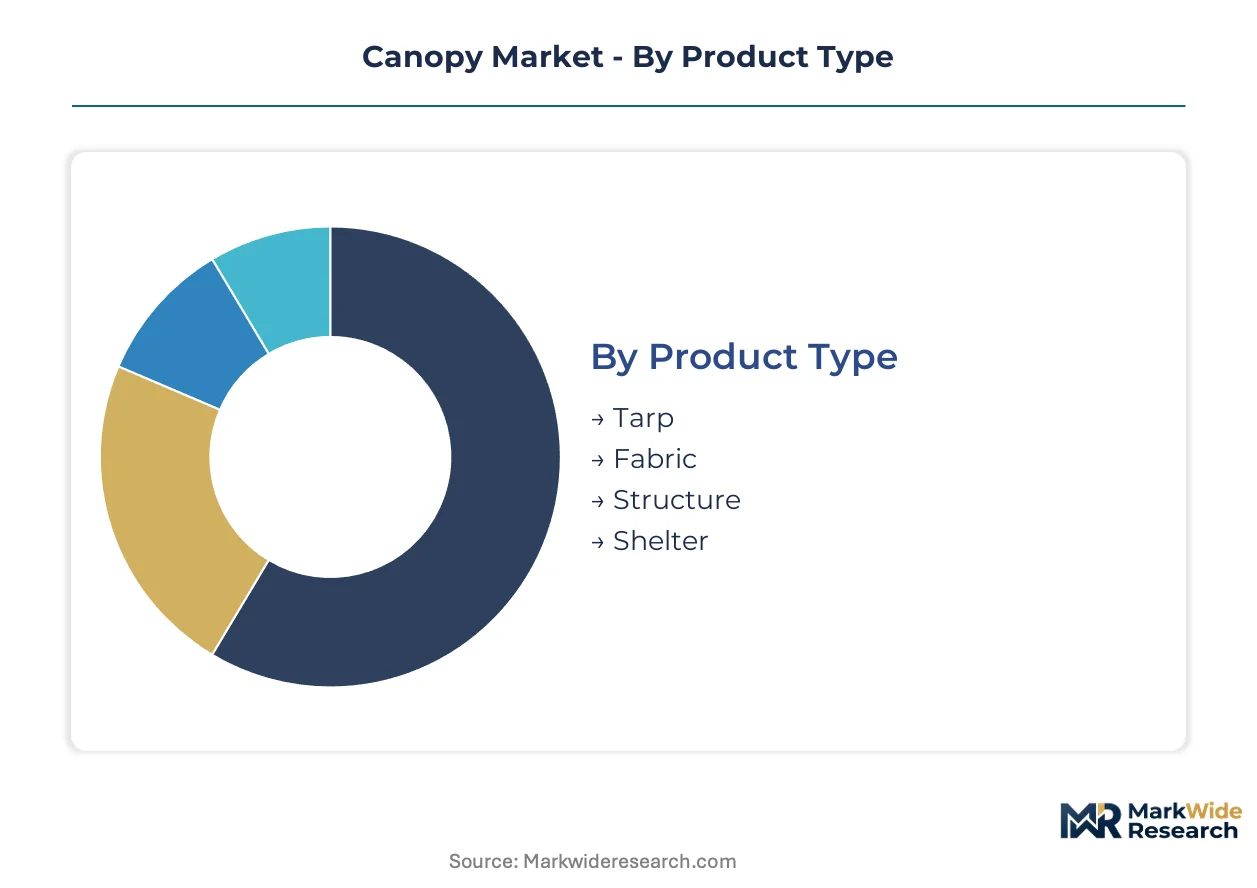
Canopy procurement patterns diverge sharply across product configurations and use contexts. Material certification requirements and deployment duration drive distinct specification clusters that reshape supplier positioning.
Product Type:
Supply concentrates in tensioned membrane fabricators serving high-frequency rental operators, while rigid structure producers anchor municipal infrastructure contracts.
- Structure:Tensioned or framed membrane assemblies spanning three to twelve meters, engineered from aluminum or steel frames with coated fabric skins. German municipal park departments and UK festival operators concentrate procurement here, driven by CE marking mandates for temporary installations and multi-year maintenance bundling.
- Fabric:Unframed membrane sheets requiring external support systems, typically polyester or vinyl substrates in standardized dimensions. Event rental houses in the Netherlands and Belgium specify these for rapid deployment cycles, constrained by REACH Annex XVII coating compliance deadlines.
- Tarp:Lightweight polyethylene or woven polypropylene sheets for short-duration coverage. Construction sites and agricultural operations in Bavaria represent primary demand nodes.
- Shelter:Enclosed canopy configurations with sidewall integration for semi-permanent habitation. UNHCR procurement frameworks and Red Cross disaster-relief operations are expanding volume fastest.
Today's leader: Structure. Tomorrow's challenger: Shelter.
End User:
Margin pools concentrate with repeat purchasers who bundle customization with multi-year service contracts.
- Commercial Users:Corporate facilities, hospitality venues, and retail operators deploying branded shade for customer experience. German automotive showrooms and UK garden centers drive specification toward photocatalytic self-cleaning finishes.
- Event Planners:Professional organizers managing outdoor gatherings, weddings, and corporate functions. Multi-week festival programming in North Rhine-Westphalia creates fabrication backlogs for tensioned membrane suppliers.
- Festivals:Large-scale music and cultural events requiring semi-permanent infrastructure. Glastonbury and Roskilde-scale operators are consolidating supplier relationships around digital twin configuration platforms.
- Outdoor Enthusiasts:Individual consumers purchasing recreational canopies for camping and backyard use. Price sensitivity here channels volume toward mass-market retail distributors.
Commercial Users capture the deepest margin pools. Outdoor Enthusiasts represent the highest volume velocity.
Material:
Cost tiers separate certified recycled content from virgin feedstocks as EU Green Deal procurement filters tighten.
- Polyester:Woven PET substrates with PVC or polyurethane coatings, dominating commercial installations. Mechanical depolymerization advances are lowering rPET costs toward virgin parity in German municipal tenders.
- Vinyl:Heavy-duty PVC-laminated fabrics for industrial and long-term deployments. ECHA-mandated perfluorinated compound restrictions are forcing coating reformulations across European finishers.
- Canvas:Cotton or cotton-blend substrates with wax or acrylic treatments. Heritage aesthetic specifications in UK heritage hospitality and Dutch outdoor dining verticals sustain niche demand.
- Mesh:Perforated synthetic fabrics permitting airflow while blocking UV. Sports facility operators in Belgium specify these for tennis court and playground installations.
Polyester commands current volume leadership. Vinyl faces steepest regulatory transformation.
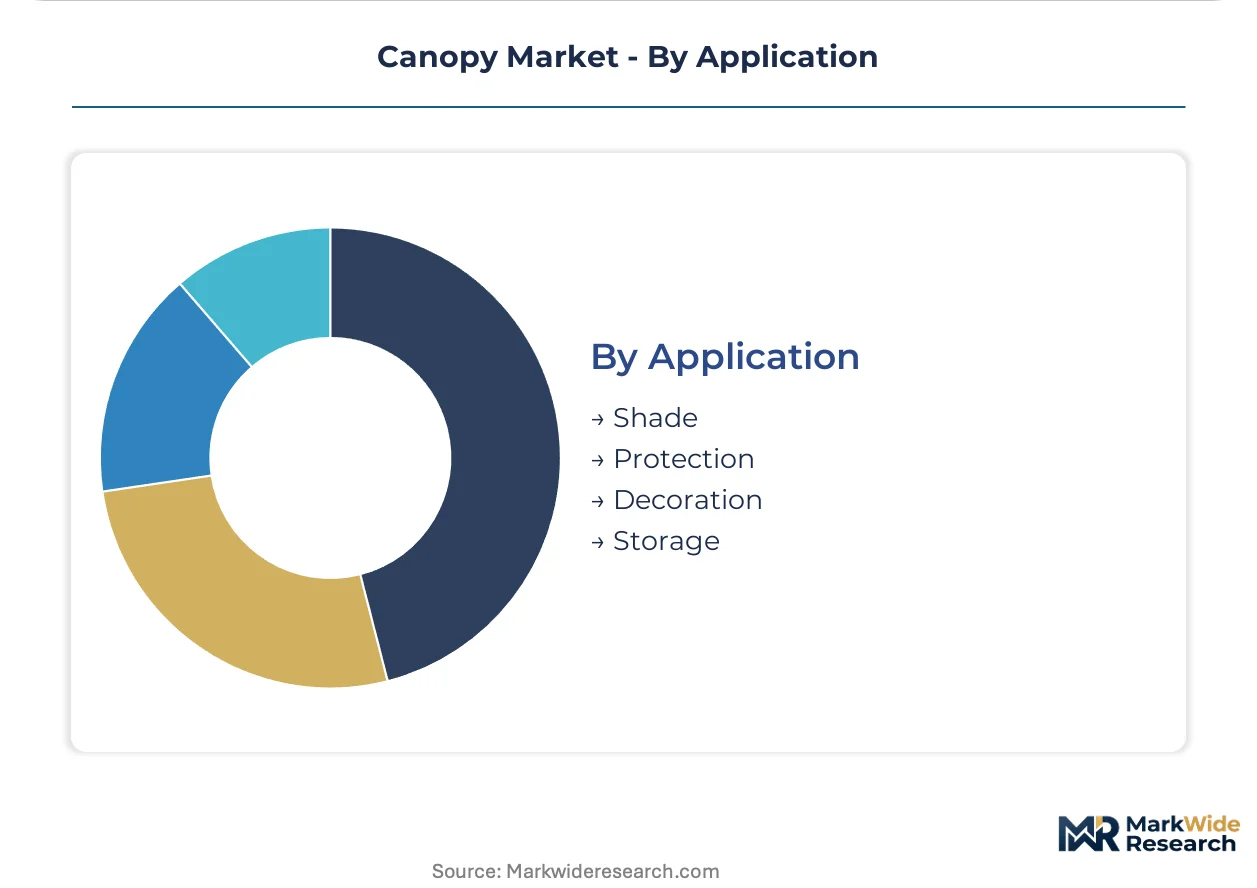
Application:
Functional specification determines material grade, structural engineering intensity, and maintenance contract attachment rates.
- Shade:UV-blocking deployments for human comfort in outdoor spaces. German municipal investment in public shade infrastructure drives specification toward 10-year lifecycle guarantees.
- Protection:Weather and debris shielding for equipment, vehicles, and construction materials. Industrial sites in the Ruhr region anchor demand for fire-retardant certified configurations.
- Decoration:Aesthetic and branded canopy deployments for experiential marketing. Corporate hospitality budgets in London and Amsterdam compress approval cycles through digital twin pre-visualization.
- Storage:Enclosed or semi-enclosed structures for inventory and asset protection. Agricultural cooperatives in Lower Saxony represent seasonal demand concentration.
Shade applications dominate installed base. Protection specifications carry the highest engineering margin attachment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Structural engineers specializing in tensile membrane design concentrate in Germany and the UK, anchoring European canopy innovation clusters. Their expertise underpins municipal procurement frameworks and festival infrastructure standards across the continent.
Germany
Municipal park departments in Bavaria and North Rhine-Westphalia drive tensioned membrane procurement for public shade infrastructure. EU Green Deal procurement filters mandate certified recycled content percentages for polyester substrates in tender responses. Stuttgart-based textile finishers accelerate water-based polyurethane coating alternatives through TÜV certification pipelines.
United Kingdom
Crown Commercial Service frameworks centralize municipal canopy purchasing toward suppliers with G-Cloud registration and NHS estate experience. UKCA marking requirements enforce structural safety standards for temporary installations post-Brexit. London and Southeast England anchor digital twin configuration platform adoption among festival organizers and corporate hospitality operators.
Netherlands
Event rental houses in Amsterdam and Rotterdam specify unframed membrane sheets for rapid deployment cycles at multi-week outdoor programming. REACH Annex XVII coating compliance deadlines constrain vinyl supplier selection. Photocatalytic titanium dioxide coating specifications are absorbing premium pricing power in municipal park maintenance contracts.
Belgium
Sports facility operators in Flanders specify perforated mesh fabrics for tennis court and playground UV protection installations. ECHA-mandated perfluorinated compound restrictions filter non-compliant fabric imports from Asian suppliers. Brussels-based procurement agencies consolidate semi-permanent shade deployments for EU institution outdoor events.
France
Heritage hospitality operators in Provence-Alpes-Côte d'Azur sustain niche demand for cotton-blend canvas substrates with wax or acrylic treatments. ANSM oversight of chemical composition in coated fabrics runs parallel to REACH frameworks. Lyon textile clusters reformulate vinyl coatings to meet evolving EU sustainability mandates for public procurement.
Canopy Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the canopy supply base. Full-service fabricators owning extrusion and coating assets battle rental operators outsourcing fabrication to certified job shops. Three archetypes dominate: integrated manufacturers controlling frame and membrane production, specialist tensioned membrane engineers, and event-service aggregators bundling logistics with shade deployment. Capacity expansion in mechanical depolymerization facilities and strategic partnerships with aluminum alloy distributors represent the dominant competitive vectors.
Among UK-based specialists, Sunair Awnings and Shade Structures occupy positions within the integrated manufacturing tier, while KD Kanopy exemplifies the scale-driven fabrication archetype serving rapid-deployment festival markets. These entities represent distinct strategic postures rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Sunair Awnings |
| Shade Structures |
| Impact Canopy |
| Canopies UK |
| KD Kanopy |
| JAY JAY Enterprise |
| Eide Industries |
| Lawrence Fabric and Metal Structures |
| Advanced Design Awnings and Signs |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between CE-marked tensioned membrane systems and uncertified commodity tarpaulins splits pricing power across parallel supply bases. Municipal procurement frameworks in Germany and the UK mandate certified recycled content, compressing margins for non-compliant fabricators while premium suppliers capture bundled maintenance contracts.
Pricing Analysis
Bundled fabrication-and-installation services command 40-60% premiums over unframed membrane sheet supply in European festival markets. Price differentiation rests on CE marking tier and after-sales maintenance bundling, with German municipal buyers least sensitive due to 10-year lifecycle guarantees. Cost compression in standard-grade polyester runs through mechanical depolymerization capacity expansion. Outdoor enthusiasts purchasing recreational canopies exhibit highest price sensitivity, channeling volume toward mass retail distributors.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Hamburg anchor hub-and-spoke fulfillment for tensioned membrane fabricators serving festival operators. Frame manufacturing draws from Chinese aluminum extrusion output and German steel coil supply, exposing fabricators to alloy price volatility and shipping backlogs. Single-source vulnerability concentrates in Asian PVC coating feedstocks. Distribution runs through certified job shops for rapid custom fabrication, with Crown Commercial Service frameworks consolidating UK public-sector purchasing.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal functions as a regulatory compounder, with REACH Annex XVII coating restrictions disqualifying legacy inventories and redirecting procurement toward certified European producers.
For Market Incumbents: Extend TÜV certification pipelines for water-based polyurethane alternatives before REACH deadlines harden. Capture municipal maintenance bundling through photocatalytic coating integration. Defend against fixed shade structure substitution by emphasizing rapid-deployment flexibility in festival contracts. For New Entrants and Emerging Players: The premium-to-economy price-point gap in disaster-relief shelter applications offers white-space entry. Target UNHCR and Red Cross procurement frameworks with rapid-deployment fabric configurations. Penetrate through photovoltaic membrane technology partnerships for off-grid commercial sites. For Investors and Strategic Acquirers: Consolidation pressure builds where mechanical depolymerization capacity scarcity constrains rPET supply for municipal tender responses. Long-term viability favors integrated manufacturers with captive coating certification and aluminum distribution partnerships. Watch CE marking timeline friction as inflection indicator for festival deployment bottlenecks.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into rPET Feedstock | Captures cost parity with virgin polyester in German municipal tenders. |
| Photovoltaic Fabric Technology Partnership | Opens premium positioning in off-grid commercial and disaster-relief deployments. |
| Digital Twin Configuration Platform Deployment | Compresses corporate hospitality approval cycles from six weeks to ten days. |
| TÜV Certification Pipeline Acceleration | Secures eligibility for EU Green Deal-filtered public procurement frameworks. |
| Crown Commercial Service Registration | Centralizes UK municipal canopy purchasing toward NHS-experienced suppliers. |
Methodological Framework
Direct dialogue with tensioned membrane fabricators, municipal procurement officers, festival infrastructure directors, and textile finishing plant managers grounded qualitative findings. Secondary validation drew from ECHA REACH filings, CE marking registration databases, Crown Commercial Service framework disclosures, and German municipal tender archives. Bottom-up volume estimates triangulated against top-down construction spending allocations across the analysis window.
Top-down macroeconomic drivers converged with bottom-up segment sizing across product type, end user, material grade, and application function dimensions. CAGRs derived from regression analysis of historical deployment data against EU Green Deal procurement trajectory assumptions. Industry-specific inputs included aluminum alloy price indices, mechanical depolymerization capacity buildout schedules, and festival infrastructure investment patterns.
The model assumes a particular technology adoption path; alternative pathways for photovoltaic fabric integration would alter the outlook. Forecasts reflect documented assumptions on REACH compliance timelines and municipal recycled content mandates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Fabrics
Coco Coir Market
Agricultural Fabrics
Pond Liners Market
Agricultural Fabrics
Biodegradable Mulch Film Market
Agricultural Fabrics
Silage Bags Market
Agricultural Fabrics
Global Agriculture Nets Market
Agricultural Fabrics
Agricultural Fabrics Market
Agricultural Fabrics
North America Silo Bags Market
Agricultural Fabrics
South America Agricultural Films Market
Agricultural Fabrics
Nonwoven Crop Cover Market
Agricultural Fabrics
Mulching Materials Market
Agricultural Fabrics
Silo Bags Market
Agricultural Fabrics
US Agro Textile Market
Agricultural Fabrics
Agricultural Gloves Market
Agricultural Fabrics
Global Agricultural Films Market
Agricultural Fabrics
Hay Bags Market
Agricultural Fabrics
Europe Agricultural Films Market