
 Global Greenhouse Soil Market | 2026-2036
Global Greenhouse Soil Market Size, Share, and Industry Trends Forecast 2026-2036
Global Greenhouse Soil Market Foresight
Canada's peat bog extraction expansion is fragmenting as environmental permitting tightens. Scotts Miracle-Gro leverages its retail distribution network across North American home improvement channels. Klasmann-Deilmann anchors European professional horticulture through its specialized substrate formulations for greenhouse operators.
Greenhouse soil comprises engineered growing media formulated from organic and mineral constituents such as sphagnum peat, coconut coir pith, expanded perlite, and vermiculite, blended to achieve specific air-filled porosity, water-holding capacity, and cation exchange capacity for controlled-environment crop production. Peat moss dominates value retention among soil types due to established grower familiarity and consistent batch performance, though coco coir posts the fastest substitution curve as Irish and Dutch regulators restrict peat harvesting on protected boglands. Container gardening and hydroponics application segments concentrate margin pools among commercial farms and agropreneurs seeking standardized, pathogen-free media for year-round production cycles.
The EPA oversees wetland protection rules affecting peat extraction in the United States, while the EU Green Deal and F-Gas Regulation shape substrate innovation priorities across member states. Health Canada and PMRA enforce fertilizer and growing medium safety standards that govern cross-border trade into Canadian protected agriculture facilities. Stakeholders must track evolving carbon accounting methodologies for soil constituents as procurement criteria shift toward verified low-emission sourcing credentials.
Market Dynamics
EU Green Deal nitrogen reduction mandates are forcing commercial vegetable producers across the Netherlands, Belgium, and Germany to abandon field soil cultivation and migrate toward substrate-based greenhouse systems, restructuring input demand toward engineered growing media.
Growth Catalysts
- EU F-Gas Regulation:Phase-down of synthetic greenhouse gases accelerates investment in climate-controlled protected agriculture, expanding substrate volume requirements for year-round production cycles.
- Container gardening:Urban agropreneurs in Singapore and the United Arab Emirates deploy modular hydroponic systems, creating pull for standardized, pathogen-free soil alternatives.
- Peat extraction moratoria:Irish and Dutch regulators restrict protected bogland harvesting, forcing substrate manufacturers to reformulate around coconut coir and wood fiber alternatives.
Market Restraints
- Peat supply concentration:Canadian and Baltic state extraction permits face environmental litigation, concentrating viable sphagnum reserves among fewer licensed operators.
- Input cost volatility:Coconut coir pith prices fluctuate with Sri Lankan and Indian monsoon patterns and shipping lane disruptions through the Red Sea.
- Technical performance gaps:Wood fiber substrates exhibit inconsistent cation exchange capacity versus peat moss, limiting adoption among tomato and cucumber growers.
Strategic Opportunities
- Saudi Arabia's NEOM project:Megacity food security mandates create demand for desert-adapted greenhouse substrates with enhanced water retention properties.
- Carbon accounting methodologies:Verified low-emission sourcing credentials under ISO 14064 enable premium pricing for substrate producers documenting supply chain emissions.
- Biostimulant integration:Convergence of precision fermentation-derived microbial inoculants with engineered media opens functional product differentiation.
Industry Challenges
- Substrate formulation expertise:Shortage of agronomists trained in air-filled porosity optimization for controlled-environment agriculture slows product development cycles.
- Batch consistency certification:Pathogen-free validation protocols under Health Canada and PMRA standards extend quality assurance timelines for cross-border shipments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Greenhouse Soil Market |
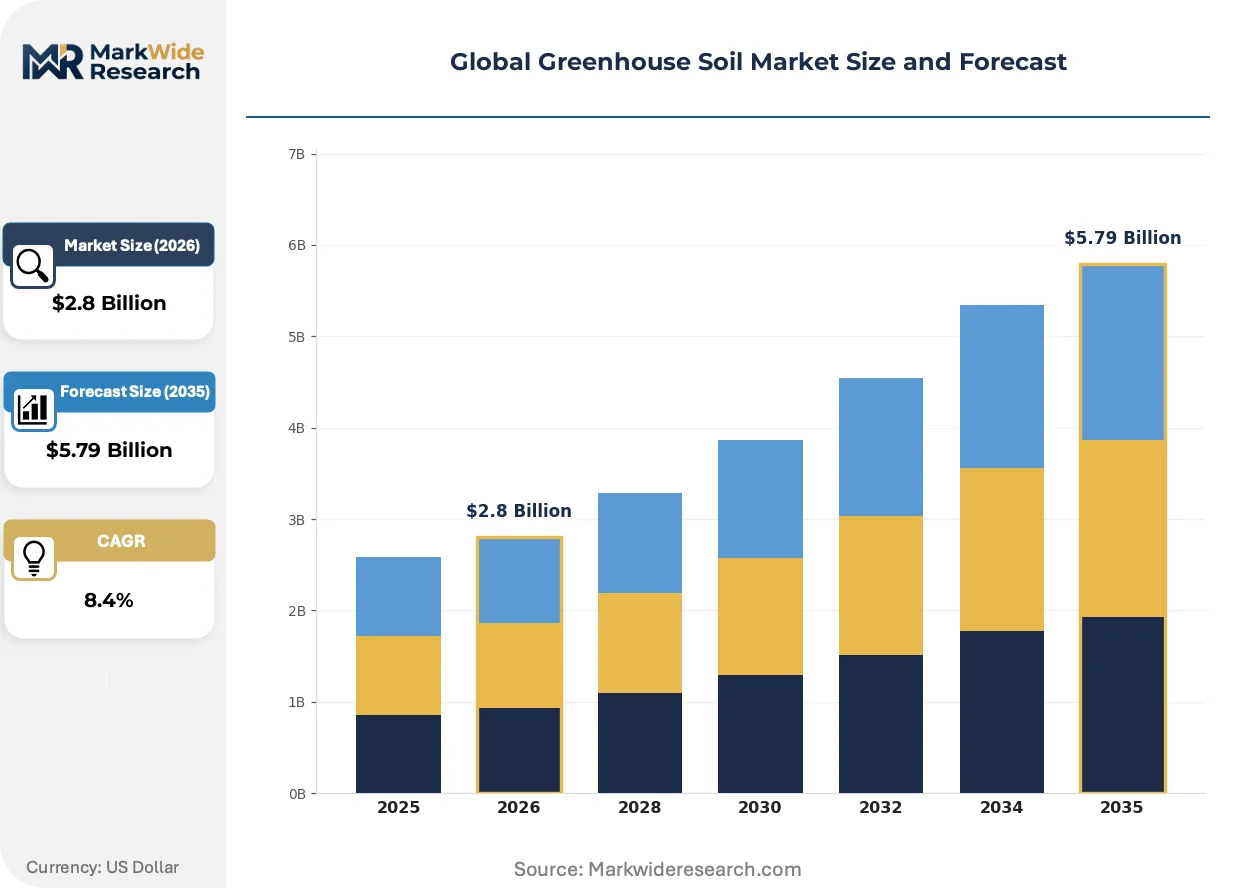
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Soil Type: Peat Moss, Coco Coir, Vermiculite, Perlite, Loam, Sand Crop Type: Vegetables, Flowers, Herbs, Fruits, Seedlings, Nursery Plants Application: Plant Propagation, Hydroponics, Container Gardening, Raised Beds, Vertical Farming, Indoor Gardening End User: Commercial Farms, Research Institutions, Hobbyist Growers, Government Facilities, Agropreneurs, Botanical Gardens |
| Companies Covered | Scotts Miracle-Gro, Sun Gro Horticulture, Klasmann-Deilmann, Premier Tech, ASB Greenworld, Florentaise, Lambert Peat Moss, Compo Expert, FoxFarm Soil & Fertilizer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Greenhouse Soil Market Shifts & Advancements
Sensor-integrated growing systems are digitizing substrate performance monitoring, compressing the feedback loop between crop response and media formulation adjustments.
Near-infrared spectroscopy is digitizing real-time assessment of moisture content, electrical conductivity, and nutrient availability in greenhouse substrates. Large-scale tomato operations in Almeria, Spain, and the Netherlands deploy these probes at density levels unthinkable five years ago. The technology is digitizing agronomic decision-making, shifting competitive advantage toward data-integrated substrate suppliers.
REACH authorization requirements for microplastic-containing slow-release fertilizers are forcing reformulation of coated nutrient products used in professional horticulture. The European Chemicals Agency's 2023 restriction proposal targets polymer-based controlled-release technologies. German and Dutch substrate blenders now accelerate biodegradable coating development to maintain product registration.
Direct contracting between greenhouse operators and coconut coir processors is bypassing traditional distribution layers in the Netherlands and the United Kingdom. Large vegetable cooperatives in Westland establish captive supply relationships with Sri Lankan fiber mills, securing volume commitments against quality specifications. This pattern concentrates margin capture at the production node while compressing wholesaler participation.
Global Greenhouse Soil Market Segmentation
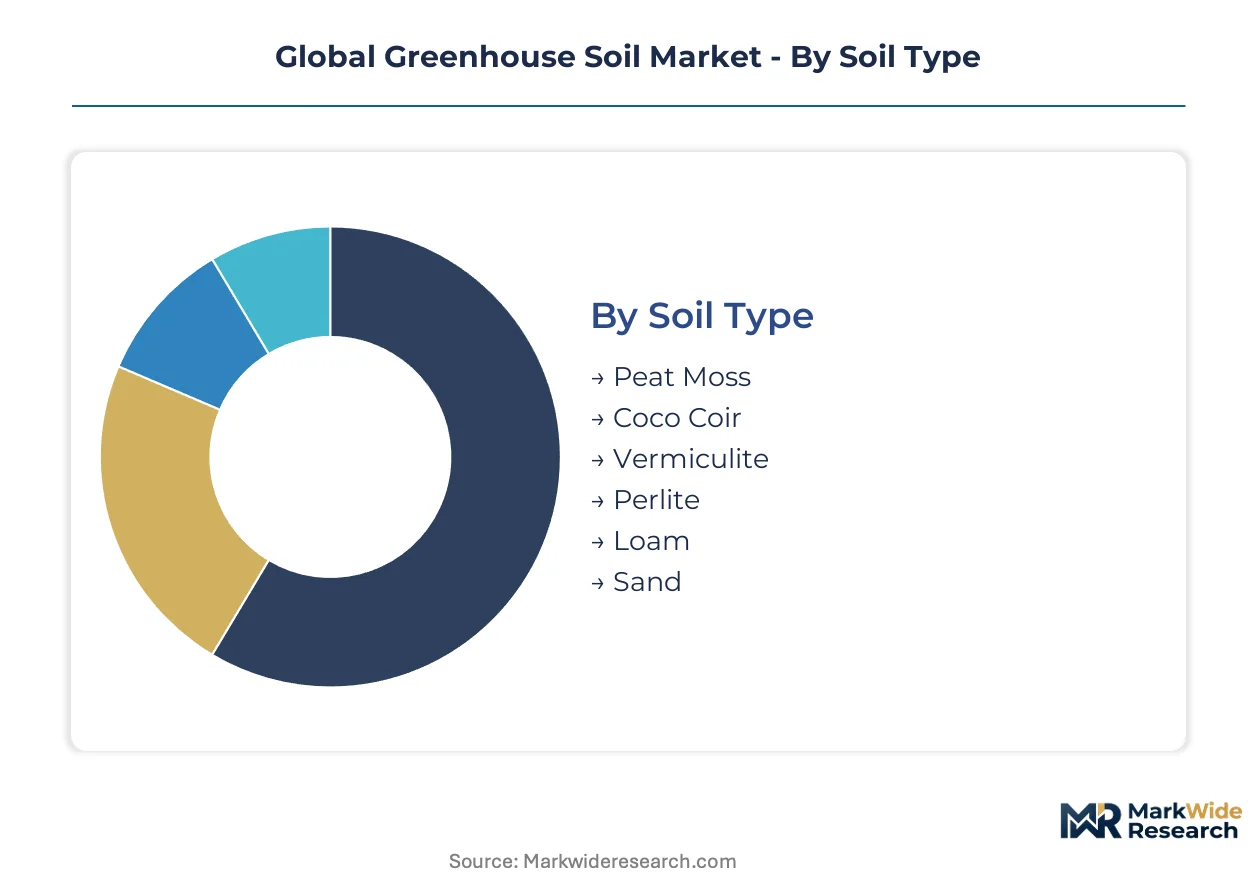
Engineered growing media formulations diverge sharply across crop requirements, cultivation systems, and operator scale. Substrate selection directly determines irrigation efficiency, nutrient retention, and pathogen management in controlled environments.
Soil Type:
Mature substrates dominate commercial throughput while emerging alternatives reshape formulation strategies under regulatory pressure.
- Peat Moss:Sphagnum-based media deliver consistent air-filled porosity and cation exchange capacity that tomato and cucumber growers in the Netherlands demand. Established batch performance and grower familiarity sustain procurement volumes despite Irish and Dutch extraction moratoria on protected boglands.
- Coco Coir:Coconut pith substrates exhibit rapid substitution curves as European regulators restrict peat harvesting. Direct contracting between Westland vegetable cooperatives and Sri Lankan fiber mills is compressing distribution layers while securing volume commitments against quality specifications.
- Vermiculite:Expanded mica mineral enhances water retention in propagation trays for seedling operations.
- Perlite:Volcanic glass additive improves drainage in container systems for drought-stressed regions.
- Loam:Mineral-organic blend retains relevance in raised bed installations for institutional growers.
- Sand:Coarse particle fraction anchors hydroponic root support in arid-climate greenhouse facilities.
Peat moss handles the majority of throughput; coco coir is the fastest mover on share.
Crop Type:
Volume concentration aligns with protected agriculture economics and per-square-meter revenue potential.
- Vegetables:Tomato, cucumber, and pepper cultivation in Almeria and the Netherlands drives substrate consumption at industrial scale. EU Green Deal nitrogen reduction mandates are forcing Dutch commercial producers to abandon field soil cultivation entirely.
- Flowers:Ornamental production in Kenya and Colombia requires pathogen-free media for export certification compliance.
- Herbs:Basil and mint propagation in controlled environments demands rapid root establishment substrates.
- Fruits:Strawberry substrate cultivation in Belgium and Germany expands under protected agriculture incentives.
- Seedlings:Nursery propagation concentrates margin pools among standardized media blenders supplying vegetable transplant operations.
- Nursery Plants:Woody perennial propagation in Italian and Spanish facilities requires extended-release nutrient integration.
Vegetables command the dominant volume position; fruits are climbing the fastest as berry cultivation migrates indoors.
Application:
System architecture determines substrate specification from drainage characteristics to sensor integration compatibility.
- Plant Propagation:Fine-grade peat-perlite blends dominate plug and cell tray production for vegetable transplant supply chains.
- Hydroponics:Inert media support root anchoring in recirculating nutrient systems deployed across Singapore and UAE urban agropreneur operations.
- Container Gardening:Modular systems for residential and commercial rooftop installations create pull for standardized, pathogen-free bagged substrates.
- Raised Beds:Institutional and community garden installations in North American municipalities favor bulk delivery of engineered soil blends.
- Vertical Farming:Layered cultivation systems in New York and London demand lightweight substrates with precise moisture retention profiles.
- Indoor Gardening:Residential LED-assisted cultivation in Japanese and South Korean apartments drives retail-format packaged media sales.
Hydroponics anchors commercial value capture; vertical farming shows the steepest expansion trajectory as urban density intensifies.
End User:
Procurement scale separates specification requirements from price sensitivity and technical support demands.
- Commercial Farms:Large-scale greenhouse operators in the Netherlands and Spain negotiate direct substrate contracts with formulation blenders, bypassing distribution intermediaries.
- Research Institutions:Wageningen University and UC Davis trial stations require batch-consistent media for reproducible experimental protocols.
- Hobbyist Growers:North American retail channels through home improvement stores sustain packaged peat-coir blend volumes.
- Government Facilities:Saudi Arabia's NEOM project and Singapore food security programs mandate desert-adapted substrates with enhanced water retention.
- Agropreneurs:Urban commercial operators in Dubai and Hong Kong deploy sensor-integrated growing systems with digitized substrate performance monitoring.
- Botanical Gardens:Conservation collections in Kew Gardens and Singapore Botanic Gardens require specialized mycorrhizal-inoculated formulations.
Commercial farms generate the dominant procurement volume; agropreneurs are expanding most quickly as urban agriculture ventures multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Substrate consumption patterns diverge sharply across geographies, with Dutch commercial operators demanding precision-engineered peat blends while Saudi megaprojects prioritize desert-adapted water retention formulations.
Netherlands
Westland vegetable cooperatives drive engineered substrate demand as EU Green Deal nitrogen mandates force abandonment of field soil cultivation. The Dutch regulator enforces strict extraction limits on protected boglands under national implementation of EU habitat directives. Almeria-style greenhouse clusters concentrate around Naaldwijk and Bleiswijk, where direct contracting with Sri Lankan coir mills now bypasses traditional distribution layers.
Germany
Commercial tomato and cucumber producers in Lower Saxony and Bavaria accelerate peat-to-coir substitution curves under federal implementation of EU F-Gas Regulation climate controls. ECHA REACH authorization requirements pressure reformulation of polymer-coated slow-release fertilizers used in professional horticulture. The Rhine-Ruhr industrial corridor hosts substrate blenders accelerating biodegradable coating development to maintain product registration compliance.
United States
Container gardening and hydroponic urban agropreneurs in New York and California create pull for standardized pathogen-free bagged media. EPA wetland protection rules constrain peat extraction permitting in northern tier states, fragmenting viable sphagnum reserve access. The Pacific Northwest and Southeast greenhouse belts concentrate sensor-integrated growing system deployments with digitized substrate performance monitoring.
Saudi Arabia
NEOM megacity food security mandates generate demand for engineered media with enhanced water retention properties suited to desert greenhouse conditions. The national food security program under Vision 2030 directs procurement toward verified low-emission sourcing credentials. Riyadh-based agricultural investment vehicles establish captive supply relationships with international substrate formulators for protected agriculture infrastructure.
Canada
Quebec and Ontario peat bog extraction operations face environmental permitting tightening that fragments historical supply concentration. Health Canada and PMRA enforce fertilizer and growing medium safety standards governing cross-border trade into protected agriculture facilities. Prairie province greenhouse operators increasingly source coconut coir alternatives as Irish and Dutch extraction moratoria redirect global peat trade flows.
Global Greenhouse Soil Market Competitive Landscape
Capability concentration sits with specialized substrate formulators; scale advantage sits with retail distribution networks spanning home improvement channels. The vendor base organizes around three strategic archetypes: peat reserve holders with extraction licensing, precision blenders serving professional greenhouse operators, and packaged goods distributors capturing hobbyist demand. Dominant competitive moves include backward integration into captive coir supply from Sri Lankan and Indian fiber mills, plus portfolio diversification toward biostimulant-integrated functional media.
Among North American packaged goods distributors, Scotts Miracle-Gro occupies a position exemplifying retail channel scale advantage, while Sun Gro Horticulture represents the professional horticulture supply archetype. Klasmann-Deilmann anchors the European precision formulation tier, sitting within the specialized substrate engineering segment that serves commercial greenhouse operators with batch-consistent, crop-specific media blends. These three entities collectively illustrate the geographic and functional segmentation defining competitive positioning.
| Leading Market Players |
|---|
| Scotts Miracle-Gro |
| Sun Gro Horticulture |
| Klasmann-Deilmann |
| Premier Tech |
| ASB Greenworld |
| Florentaise |
| Lambert Peat Moss |
| Compo Expert |
| FoxFarm Soil & Fertilizer |
| Others |
Supply & Pricing Matrix
Canadian peat bog extraction permitting delays determine both the premium-to-economy pricing spread and the geographic reconfiguration of substrate sourcing. Dutch and Irish regulators restrict protected bogland harvesting, forcing manufacturers toward Sri Lankan coir mills and compressing margin capture at the production node.
Pricing Analysis
Westland vegetable cooperatives pay premiums over North American retail channels for batch-consistent, pathogen-free media. Three-tier pricing structure across premium, standard, and economy levels separates certified low-emission substrates from commodity peat blends. Cost compression in the economy tier is intensifying because Sri Lankan monsoon disruptions and Red Sea shipping lane volatility feed coconut coir pith price instability. Hobbyist growers through home improvement channels exhibit highest price sensitivity; commercial greenhouse operators prioritize performance consistency over unit cost.
Supply Chain Analysis
Sri Lankan and Indian fiber mills hold captive supply relationships with European substrate blenders, bypassing traditional distribution layers. Raw material sourcing draws from Canadian sphagnum reserves, Baltic state peatlands, and South Asian coconut processing facilities. Single-source vulnerability concentrates in Sri Lankan coir pith dependency where monsoon patterns and shipping disruptions create input cost volatility. Distribution runs through direct contracting between Westland cooperatives and fiber mills, compressing wholesaler participation while securing volume commitments against quality specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Greenhouse Soil Market tracks a cyclical recovery anchored to EU Green Deal implementation waves forcing substrate migration from field soil cultivation.
For Market Incumbents: Build formulation expertise moats around air-filled porosity optimization and biostimulant integration capabilities. Incumbents should secure captive coir supply from Sri Lankan fiber mills before direct contracting patterns lock in competitor relationships. Accelerate biodegradable coating development to maintain product registration under ECHA REACH authorization requirements for polymer-based controlled-release fertilizers. For New Entrants and Emerging Players: Build out sensor-integrated growing system partnerships with urban agropreneurs in Singapore and the United Arab Emirates as the most penetrable white-space segment. Target government facility procurement under Saudi Arabia's NEOM food security mandates and Singapore food security programs. Lead with desert-adapted water retention formulations and verified low-emission sourcing credentials as differentiated go-to-market positioning. For Investors and Strategic Acquirers: EU F-Gas Regulation phase-down schedules reshape the acquisition landscape toward climate-controlled protected agriculture infrastructure plays. Long-term viability centers on substrate formulators with demonstrated batch consistency certification under Health Canada and PMRA standards. Watch for carbon accounting methodology adoption under ISO 14064 as the signal indicating procurement criteria shift toward premium-priced verified low-emission sourcing credentials.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coir Supply | Direct Sri Lankan fiber mill relationships bypass distribution intermediaries and secure volume commitments. |
| Biostimulant-Integrated Media Development | Precision fermentation-derived microbial inoculants open functional product differentiation against commodity substrates. |
| Sensor-Integrated Growing System Partnerships | Near-infrared spectroscopy deployment digitizes agronomic decision-making and locks in substrate specification. |
| Biodegradable Coating Reformulation | ECHA REACH compliance maintains product registration for European professional horticulture markets. |
| Verified Low-Emission Sourcing Certification | ISO 14064 documentation enables premium pricing as procurement criteria shift toward carbon accounting. |
Research Methodology
Initial hypotheses were tested against primary input from substrate formulation blenders, commercial greenhouse operators, Sri Lankan fiber mill managers, and retail distribution channel heads and refined through secondary validation. Bottom-up demand modeling drew from customs and trade data, EU regulatory filing databases, and SEC 10-K disclosures from packaged goods distributors. Top-down triangulation incorporated professional horticulture association reports and protected agriculture facility investment tracking databases.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation modeled across soil type, crop type, application system architecture, and end-user procurement scale. CAGRs were derived from volume trajectory analysis calibrated to regulatory implementation schedules and substrate substitution curve observations. Forecast inputs included EU Green Deal nitrogen mandate compliance timelines and Sri Lankan coir processing capacity expansion patterns.
Stress conditions across peat extraction permitting delays, Red Sea shipping lane disruptions, and Sri Lankan monsoon variability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and grower familiarity persistence. Quarterly review of EU F-Gas Regulation phase-down progress and Health Canada batch consistency certification timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Technologies
Post Harvesting Technologies Market
Agricultural Technologies
Europe Agricultural Enzymes Market
Agricultural Technologies
Horticulture LED Lighting Market
Agricultural Technologies
Farming As a Service Market
Agricultural Technologies
Broadacre Cropping Software Market
Agricultural Technologies
Agriculture Machine to Machine (M2M) Market
Agricultural Technologies
Global Food and Agriculture Technology and Products Market
Agricultural Technologies
Global Agriculture Supply Chain Management Market
Agricultural Technologies
Agricultural Drones Market
Agricultural Technologies
Plant Phenotyping Market