
 Coir Market | 2026-2036
Coir Market Size, Share, and Industry Trends Forecast 2026-2036
Coir Market Analysis
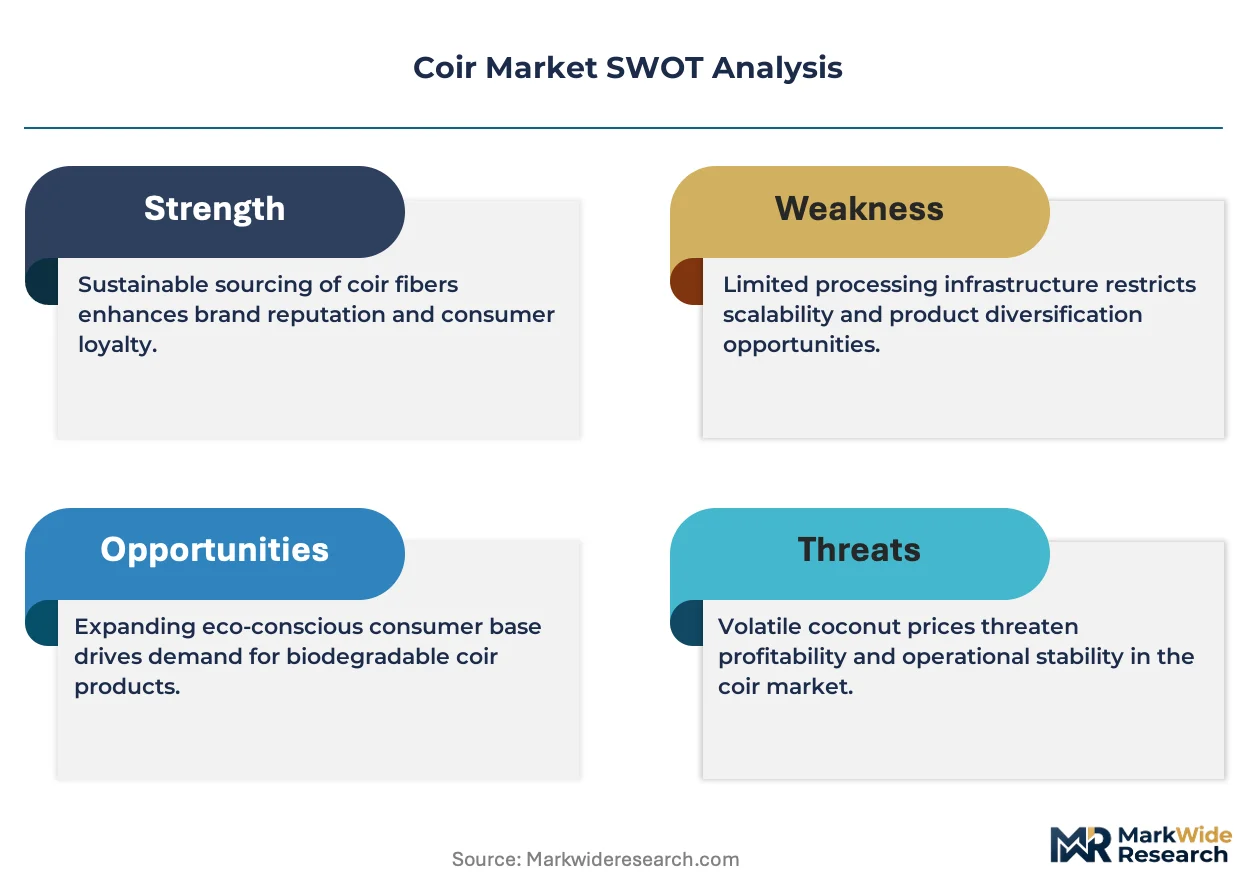
Asset-light leasing arrangements for coir processing equipment is narrowing the capital barrier for mid-tier exporters entering the market. Sai Cocopeat leverages its integrated pith washing and compression facilities to sustain margin control across European horticulture supply chains. Dutch Plantin anchors its position through captive drying infrastructure in Sri Lanka, while Geewin Exim competes via specialized geotextile weaving capacity serving Indian road construction agencies.
Coir consists of lignocellulosic fiber extracted from coconut husk mesocarp, with pith fractions containing high lignin content that delivers superior water retention ratios exceeding eight times dry weight in horticultural substrates. The material serves primarily as a renewable soil amendment and erosion control medium across commercial agriculture and civil engineering applications. Coir pith currently commands the largest value share within product type classifications due to its substitution momentum against peat moss in greenhouse operations, while coir geotextiles represent the fastest-expanding application segment driven by infrastructure bioengineering standards in tropical climates. End-user demand concentrates within agriculture and landscaping channels where bulk procurement through wholesale distributors maintains price leverage over fragmented grower cooperatives.
The EU Fertilizing Products Regulation and REACH compliance frameworks impose strict contaminant thresholds on imported coir substrates, redirecting procurement toward certified processing facilities in Kerala and Tamil Nadu. India's BIS standards for coir products and Sri Lanka's national quality certification scheme create dual compliance layers that filter informal producers from export eligibility. Stakeholders must monitor evolving peat-substitution mandates across northern European agriculture ministries and assess backward integration into husk collection networks before supply competition intensifies among fiber processors.
Market Dynamics
Peat substitution mandates across northern European agriculture ministries are compressing procurement timelines for certified coir substrates while simultaneously filtering informal processors from export eligibility through REACH contaminant thresholds.
Growth Catalysts
- EU Fertilizing Products Regulation:Mandatory certification requirements for imported substrates are redirecting commercial greenhouse procurement toward compliant processing facilities in Kerala and Tamil Nadu.
- Horticulture substrate demand:Commercial growers in the Netherlands and Belgium are completing peat-free transitions, locking in multi-year coir pith supply contracts.
- Geotextile bioengineering standards:Tropical road construction agencies in India and Vietnam are specifying coir erosion control mats for slope stabilization projects.
Market Restraints
- Husk supply concentration:Fiber processing clusters in Sri Lanka's coconut triangle dominate export-grade raw material availability, creating bottleneck vulnerability during monsoon collection disruptions.
- Peat price competitiveness:Baltic and Irish peat moss retains cost advantage in non-regulated greenhouse segments, delaying substitution economics in price-sensitive markets.
- Freight cost volatility:Container shipping rates from Colombo and Kochi ports directly compress processor margins on European-bound compressed pith blocks.
Strategic Opportunities
- Underpenetrated North American professional landscaping:US golf course renovation and sports turf projects remain underserved by certified coir suppliers despite growing water conservation mandates.
- Carbon credit stacking:India's Bureau of Energy Efficiency protocols and voluntary carbon markets are creating monetization pathways for methane-capture husk processing.
- Retail garden center channel:Direct-to-consumer compressed coir brick formats are bypassing traditional wholesale distributor networks in German and UK home improvement retail.
Industry Challenges
- Salinity remediation expertise:Pith washing and buffering to EC thresholds below specific conductivity limits requires process engineers scarce outside established Sri Lankan and Indian facilities.
- REACH registration timelines:Full substance dossier completion for coir derivatives stretches 18-24 months, blocking new market entrants from EU horticulture procurement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coir Market |
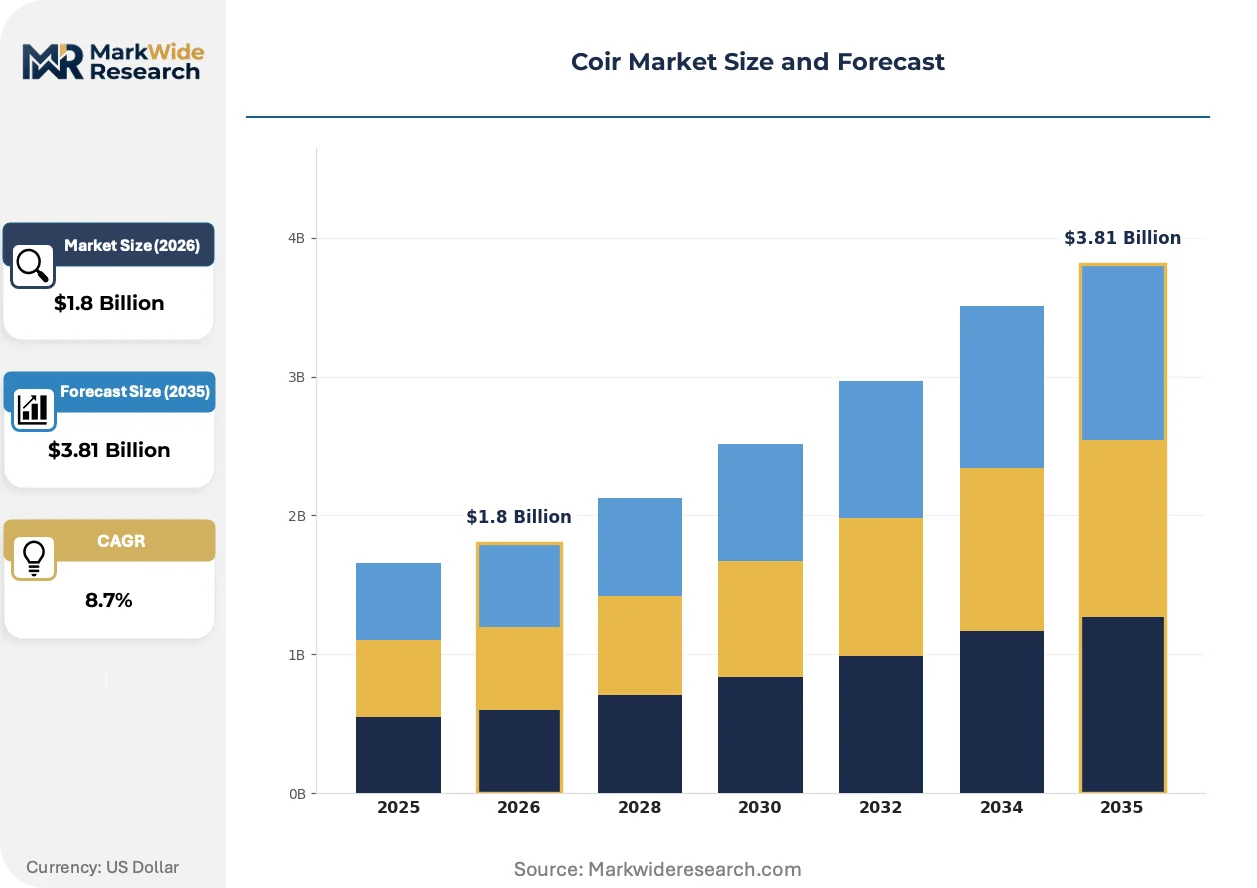
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coir Fiber, Coir Pith, Coir Geotextiles, Coir Bricks Application: Horticulture, Erosion Control, Textiles, Automotives End User: Agriculture, Landscaping, Construction, Consumer Goods Distribution Channel: Online Retail, Wholesale, Distributors, Direct Sales |
| Companies Covered | Sai Cocopeat, Geewin Exim, Dutch Plantin, Hayleys Fiber, Heng Huat Resources Group, SMS Exporters, Kumaran Coirs, FibreDust LLC, Allwin Coir, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coir Market Emerging Trajectories
Processing automation and digital quality assurance systems are compressing batch-to-batch variability while regulatory data transparency requirements reshape competitive positioning across substrate supply chains.
Near-infrared spectroscopy combined with automated moisture control is digitizing quality grading at Sri Lankan and Indian compression facilities. Dutch and German greenhouse consortiums now require digital batch certificates with full heavy metal and pathogen traceability. This technology convergence is compressing price premiums previously commanded by established certification holders.
REACH Annex XVII restrictions on polycyclic aromatic hydrocarbons in soil improvers are tightening contaminant thresholds for imported coir. ECHA guidance documents published in 2024 extended testing protocols to cover additional PAH species. Premium substrate suppliers with captive laboratory infrastructure in Kerala are absorbing compliance costs that informal processors cannot shoulder.
Consolidated buying by European horticulture cooperatives is displacing fragmented procurement through independent distributors. Dutch Plantin and similar integrated suppliers now contract directly with greenhouse operator associations in Belgium and Germany. This channel compression is most visible in the Netherlands, where four buying groups control over sixty percent of professional substrate volume.
Coir Market Segmentation
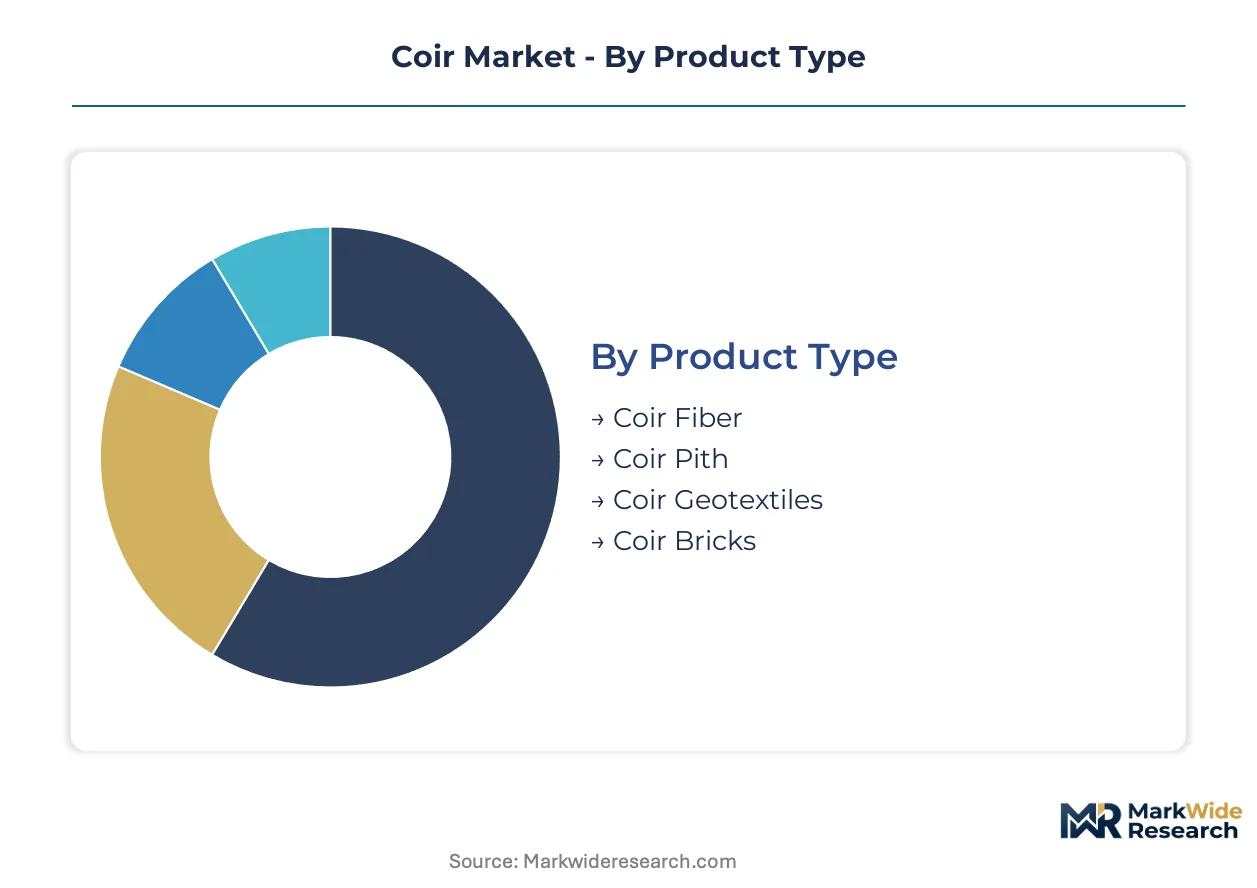
Coir's lignocellulosic versatility creates distinct value pools across fiber grades, processed formats, and functional applications. Understanding how procurement patterns diverge across product types and end-use channels exposes where margin control concentrates versus where price competition erodes returns.
Product Type:
Use-case spectrum spans raw fiber extraction through compressed consumer formats, with each tier commanding different technical specifications and certification burdens.
- Coir Pith:High-lignin substrate fraction delivering water retention ratios exceeding eight times dry weight. Dutch and Belgian greenhouse operators now mandate peat-free growing media, locking in multi-year supply contracts for EC-buffered pith blocks from Kerala processing clusters.
- Coir Geotextiles:Woven or non-woven erosion control mats specified for slope stabilization in tropical road construction. India's National Highways Authority and Vietnamese infrastructure agencies are embedding bioengineering standards that specify coir mat density and tensile strength for embankment protection.
- Coir Fiber:Extracted mesocarp strands graded by length and coarseness for rope, brush, and mattress applications. Sri Lanka's coconut triangle dominates export-grade fiber availability, with monsoon collection disruptions creating periodic supply bottlenecks.
- Coir Bricks:Compressed dehydrated pith blocks expanding upon hydration for retail garden center channels. German and UK home improvement retailers are bypassing wholesale distributors through direct-to-consumer brick formats.
Established volume favors Coir Pith; emerging adoption favors Coir Geotextiles.
Application:
Cost tier stratification separates premium certified substrates from commodity erosion control and industrial fiber uses.
- Horticulture:Professional greenhouse substrate demand concentrates in the Netherlands, Belgium, and Germany under EU Fertilizing Products Regulation compliance. REACH contaminant thresholds filter informal processors from export eligibility, redirecting procurement toward BIS-certified facilities in Tamil Nadu.
- Erosion Control:Civil engineering applications in India and Vietnam specify coir geotextiles for riverbank and roadside stabilization. Tropical climate biodegradability aligns with infrastructure agencies seeking vegetation establishment before synthetic mat replacement.
- Textiles:Traditional rope, matting, and upholstery fiber uses face competition from synthetic alternatives in price-sensitive markets. Kerala's coir cooperatives maintain artisanal production for domestic floor covering and export handicraft segments.
- Automotives:Molded fiber composites for seat cushioning and interior panels represent a developing application tier. Indian automotive suppliers are evaluating coir-polymer blends against polyurethane foams for cost and sustainability positioning.
Certification investment separates Horticulture premium capture from Erosion Control commodity pricing.
End User:
Customer type determines order scale, specification stringency, and channel access requirements across the value chain.
- Agriculture:Commercial growers and plantation operators procure bulk substrates through distributor networks or direct contracts with integrated processors. Peat substitution mandates from northern European agriculture ministries compress procurement timelines for certified coir supplies.
- Construction:Road agencies and civil contractors specify geotextile performance standards for slope stabilization and drainage applications. Indian state public works departments are incorporating coir bioengineering into standard road design specifications.
- Landscaping:Professional turf managers and golf course renovation projects in North America represent an underpenetrated segment despite water conservation mandates. US sports field projects remain underserved by certified coir suppliers with REACH-compliant production.
- Consumer Goods:Retail garden centers and home improvement channels demand compressed, branded formats with hydration instructions. Online retail expansion in Germany and the UK is displacing traditional wholesale garden center distribution for hobbyist substrates.
Contract scale favors Agriculture; margin expansion favors Landscaping as certification premiums persist.
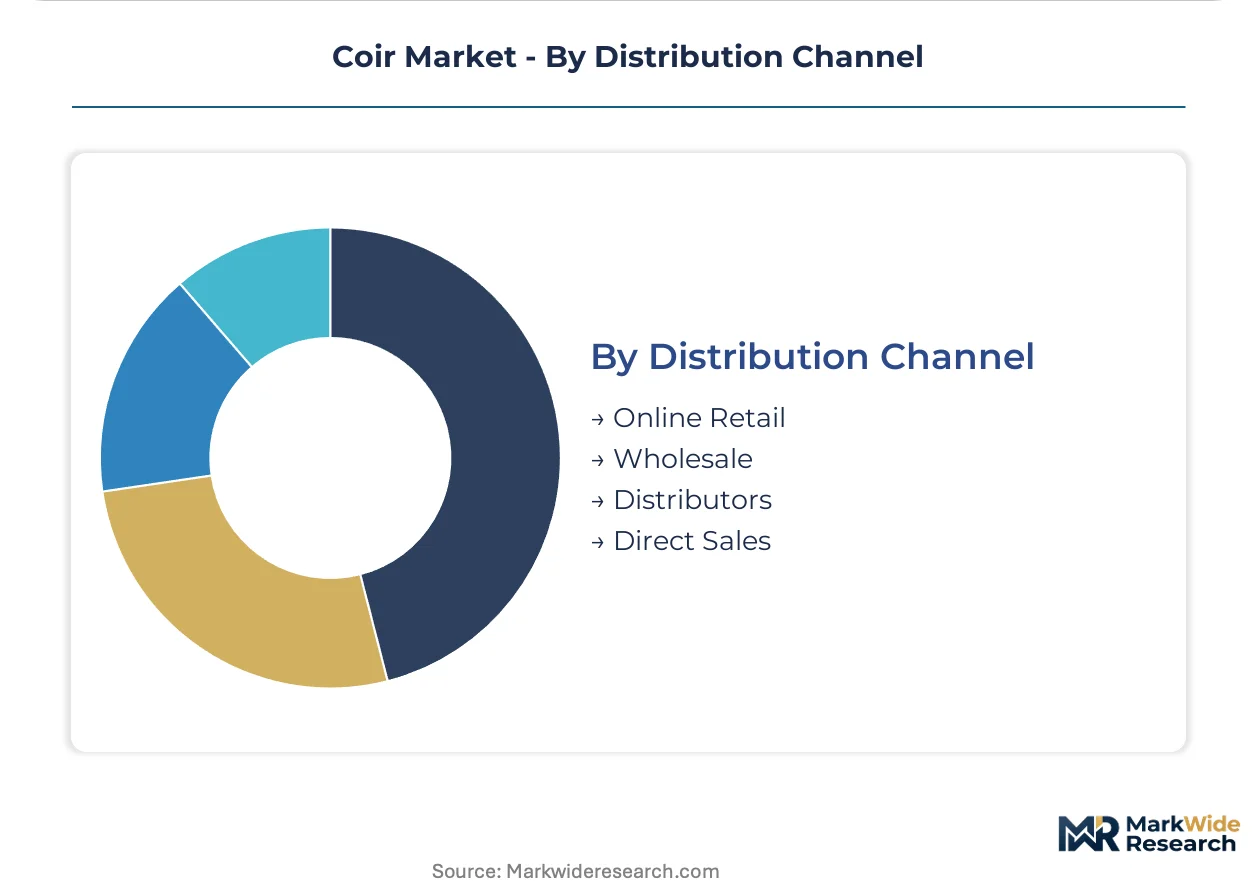
Distribution Channel:
Supply concentration in Sri Lankan and Indian processing clusters shapes logistics economics and customer access strategies.
- Wholesale:Bulk compressed pith blocks move through agricultural supply cooperatives and horticulture distributor networks. Dutch buying groups controlling professional substrate volume are consolidating procurement away from fragmented independent distributors.
- Direct Sales:Integrated processors with captive drying and laboratory infrastructure contract directly with greenhouse operator associations. Dutch Plantin and similar suppliers bypass distributor margins through direct relationships with Belgian and German grower cooperatives.
- Distributors:Regional agricultural supply houses manage inventory and last-mile delivery for mid-tier growers lacking direct import capability. Freight cost volatility from Colombo and Kochi ports directly compresses distributor margins on European-bound shipments.
- Online Retail:E-commerce platforms enable compressed coir brick sales to home gardeners without wholesale network intermediaries. Amazon and specialized garden retail sites in Germany and the UK are capturing hobbyist substrate demand.
Volume concentration favors Wholesale; channel disintermediation favors Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export capacity concentrates in South Asian processing clusters while import demand intensifies across European horticulture markets and North American landscaping channels. Freight economics from Colombo and Kochi ports shape competitive positioning for compressed substrate blocks bound for Rotterdam and Hamburg terminals.
India
Kerala's coconut belt generates the dominant share of export-grade coir fiber and pith, with Tamil Nadu processing clusters adding EC-buffered substrate capacity for EU compliance. BIS certification requirements filter informal producers from export eligibility under tightened contaminant standards. Alappuzha and Pollachi industrial zones host integrated washing and compression facilities serving Dutch and Belgian greenhouse procurement.
Sri Lanka
The coconut triangle districts of Kurunegala, Puttalam, and Gampaha anchor fiber extraction and geotextile weaving capacity for tropical infrastructure projects. Monsoon disruptions to husk collection create periodic supply bottlenecks that compress processor margins during peak export windows. Colombo port logistics determine delivery economics to European horticulture distribution hubs.
Netherlands
Rotterdam terminal operations function as the primary European entry point for compressed coir substrates, with downstream distribution reaching Belgian and German greenhouse clusters. Dutch buying groups controlling professional substrate volume consolidate procurement away from fragmented independent distributors. REACH compliance documentation from South Asian suppliers determines supplier eligibility for professional horticulture contracts.
Germany
Home improvement retail chains in Bavaria and North Rhine-Westphalia drive compressed coir brick demand through direct-to-consumer channels bypassing traditional wholesale networks. German agriculture ministry peat-substitution mandates accelerate greenhouse operator transitions toward certified coir substrates. ECHA guidance on polycyclic aromatic hydrocarbon testing protocols extends compliance timelines for new market entrants.
United States
Florida and California golf course renovation projects remain underserved by certified coir suppliers despite municipal water conservation mandates affecting sports turf management. West Coast port congestion from Kochi and Colombo shipments creates inventory planning challenges for landscaping distributors. US professional substrate procurement lacks the consolidated buying power visible in Dutch and Belgian cooperative structures.
Coir Market Vendor Landscape
Platform integrators command the system tier through captive drying infrastructure and direct greenhouse contracts; component specialists sit upstream with fiber extraction and basic pith processing capabilities. The vendor base stratifies across three tiers: integrated exporters with laboratory certification, mid-scale processors leasing compression equipment, and informal collectors excluded by REACH thresholds. Strategic archetypes include backward-integrated husk aggregators, equipment-leasing intermediaries, and retail-format specialists. Competitive intensity centers on multi-year supply contract capture and carbon credit monetization for methane-capture processing.
Among South Asian integrated processors, Sai Cocopeat exemplifies the laboratory-certified archetype with Kerala-based pith washing and compression infrastructure. Dutch Plantin anchors the European distribution tier through direct contracting with Belgian and German grower cooperatives. Geewin Exim occupies a position within the geotextile specialization segment serving Indian road construction agencies. These three entities represent distinct competitive positioning vectors: captive infrastructure, channel integration, and application-specific weaving capacity.
| Leading Market Players |
|---|
| Sai Cocopeat |
| Geewin Exim |
| Dutch Plantin |
| Hayleys Fiber |
| Heng Huat Resources Group |
| SMS Exporters |
| Kumaran Coirs |
| FibreDust LLC |
| Allwin Coir |
| Others |
Supply Flow & Price Mechanics
Sri Lankan fiber processing clusters in the coconut triangle concentrate export-grade husk availability, anchoring margin pools downstream with European greenhouse operators who absorb certification premiums. Dutch and Belgian buying groups leverage consolidated procurement volume to compress processor margins on compressed pith blocks, while informal collectors in Kerala and Tamil Nadu face exclusion from EU Fertilizing Products Regulation eligibility.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across professional horticulture channels. Price differentiation stems from REACH certification tier and volume scale, with EC-buffered pith blocks commanding premiums over unprocessed fiber. Cost compression in standard-grade substrates is intensifying because Baltic peat retains cost advantage in non-regulated segments. Price-sensitive greenhouse cooperatives in the Netherlands negotiate hardest, while premium-capture buyers in Germany accept certification premiums for peat-free compliance.
Supply Chain Analysis
EU Fertilizing Products Regulation and REACH Annex XVII restrictions on polycyclic aromatic hydrocarbons limit flows from uncertified processing facilities into European horticulture procurement. Geographic supply concentration centers on India, Sri Lanka, and Vietnam, with raw material dependencies on coconut husk collection, EC buffering chemicals, and container shipping capacity. Single-source vulnerability concentrates in monsoon-disrupted husk collection windows across Sri Lanka's coconut triangle. Distribution runs through Rotterdam terminal operations reaching Belgian and German greenhouse clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The coir market tracks a cyclical recovery as northern European agriculture ministries compress peat-substitution procurement timelines, creating demand pull-through from mandated greenhouse transitions.
For Market Incumbents: Insulate margin capture through captive husk collection networks in Kerala and Tamil Nadu before supply competition intensifies among fiber processors. Invest in EC-buffering laboratory infrastructure to absorb REACH compliance costs that informal competitors cannot shoulder, while locking multi-year supply contracts with Dutch and Belgian buying groups to defend against peat price competitiveness in adjacent segments.
For New Entrants and Emerging Players: North American professional landscaping channels, specifically US golf course renovation and sports turf projects, represent the most penetrable entry point given certified supplier underservice despite municipal water conservation mandates. Target carbon credit stacking through India's Bureau of Energy Efficiency methane-capture protocols as a differentiated value proposition, leveraging direct-to-consumer compressed brick formats via Amazon and German home improvement retail to bypass entrenched wholesale networks.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed integrated processors possessing captive drying infrastructure and direct greenhouse contracts. Long-term viability over a 5-10 year horizon hinges on peat-substitution mandate durability across northern European agriculture ministries. Monitor ECHA guidance document releases on expanded PAH testing protocols as the signal indicating compliance cost escalation that filters sub-scale competitors from export eligibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Husk Collection | Captive supply from Kerala and Tamil Nadu clusters secures raw material availability against monsoon disruptions. |
| REACH Certification Investment | EC-buffering laboratory infrastructure in Sri Lankan facilities unlocks EU Fertilizing Products Regulation eligibility for professional horticulture contracts. |
| Carbon Credit Monetization | Bureau of Energy Efficiency methane-capture protocols create revenue stacking for Indian processing facilities beyond substrate sales. |
| Direct-to-Consumer Channel Expansion | Compressed coir brick formats via German and UK online retail bypass wholesale distributor margin extraction. |
| Geotextile Weaving Capacity Addition | Specialized erosion control mat production serves Indian National Highways Authority bioengineering specifications for slope stabilization. |
Methodological Framework
Desk research of trade customs data, EU regulatory filings, and coconut production statistics preceded structured interviews with coir processing plant managers, horticulture procurement leads at Dutch buying groups, Indian road construction agency engineers, and Kerala-based fiber cooperative directors. Primary fieldwork across Alappuzha and Pollachi industrial zones validated secondary estimates of washing and compression capacity. Bottom-up facility capacity assessments triangulated against top-down trade flow analysis.
Assumptions held fixed include EU Fertilizing Products Regulation enforcement intensity and northern European peat-substitution mandate durability, while variables tested included container shipping rate volatility and monsoon disruption frequency. The analytical framework modeled product type, application, end user, and distribution channel dimensions across the projection horizon. CAGRs derived from segment-level volume trajectories incorporated greenhouse operator contract visibility, infrastructure agency specification adoption curves, and retail channel penetration rates for compressed brick formats.
Practitioners should monitor ECHA guidance document releases, Baltic peat price movements, and Indian monsoon severity indices for early signals of forecast deviation. Material shifts in EU contaminant threshold stringency or northern European agriculture ministry peat-ban acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Alfalfa Hay Market
Agriculture and Agri Products
Saudi Arabia Poultry Meat Market
Agriculture and Agri Products
LAMEA Artificial Humus Market
Agriculture and Agri Products
Residential Organic Compost Market
Agriculture and Agri Products
Animal Feed Ingredients Market
Agriculture and Agri Products
Date Palm Market
Agriculture and Agri Products
Live Goods Market
Agriculture and Agri Products
Oman Agriculture Market
Agriculture and Agri Products
Europe Alfalfa Hay Market
Agriculture and Agri Products
Plant Antifreeze Market
Agriculture and Agri Products
Africa Poultry Feed Market
Agriculture and Agri Products
Malaysia Floriculture Market
Agriculture and Agri Products
Animal Feed and Feed Additives Market
Agriculture and Agri Products
Europe Guar Market
Agriculture and Agri Products
Cut Flower Market
Agriculture and Agri Products
United Kingdom Compound Feed Market