
 Smart Indoor Gardening System Market | 2026-2036
Smart Indoor Gardening System Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Indoor Gardening System Market Outlook
Chinese LED module production is shifting toward horticultural-specific wavelengths as domestic growers scale vertical farm output. AeroGarden leverages its direct-to-consumer channel strength to sustain recurring seed pod revenue. Robert Bosch GmbH anchors European demand through precision sensor integration in connected home ecosystems. Plantui Oy competes in the Nordic premium segment with compact, design-forward hydroponic units.
Smart indoor gardening systems combine automated nutrient delivery, calibrated LED spectra, and IoT-enabled environmental monitoring to cultivate herbs, leafy greens, and vegetables within controlled residential or commercial enclosures. Hydroponic systems dominate unit volume due to lower entry pricing and simpler maintenance protocols, while aeroponic configurations command premium positioning through water efficiency and accelerated growth cycles. IoT-enabled technology segments are expanding fastest as smartphone integration and cloud-based recipe libraries reduce operational friction for novice users. LED lighting remains the margin pool leader given component standardization and replacement cycle economics.
The EU Ecodesign Directive and Japan's METI energy efficiency standards constrain LED power consumption thresholds for horticultural fixtures sold in their respective markets. The US EPA WaterSense program and state-level California Title 20 appliance regulations influence automated irrigation system design specifications. Stakeholders must monitor evolving interoperability standards between proprietary growing algorithms and open agricultural data protocols.
Market Dynamics
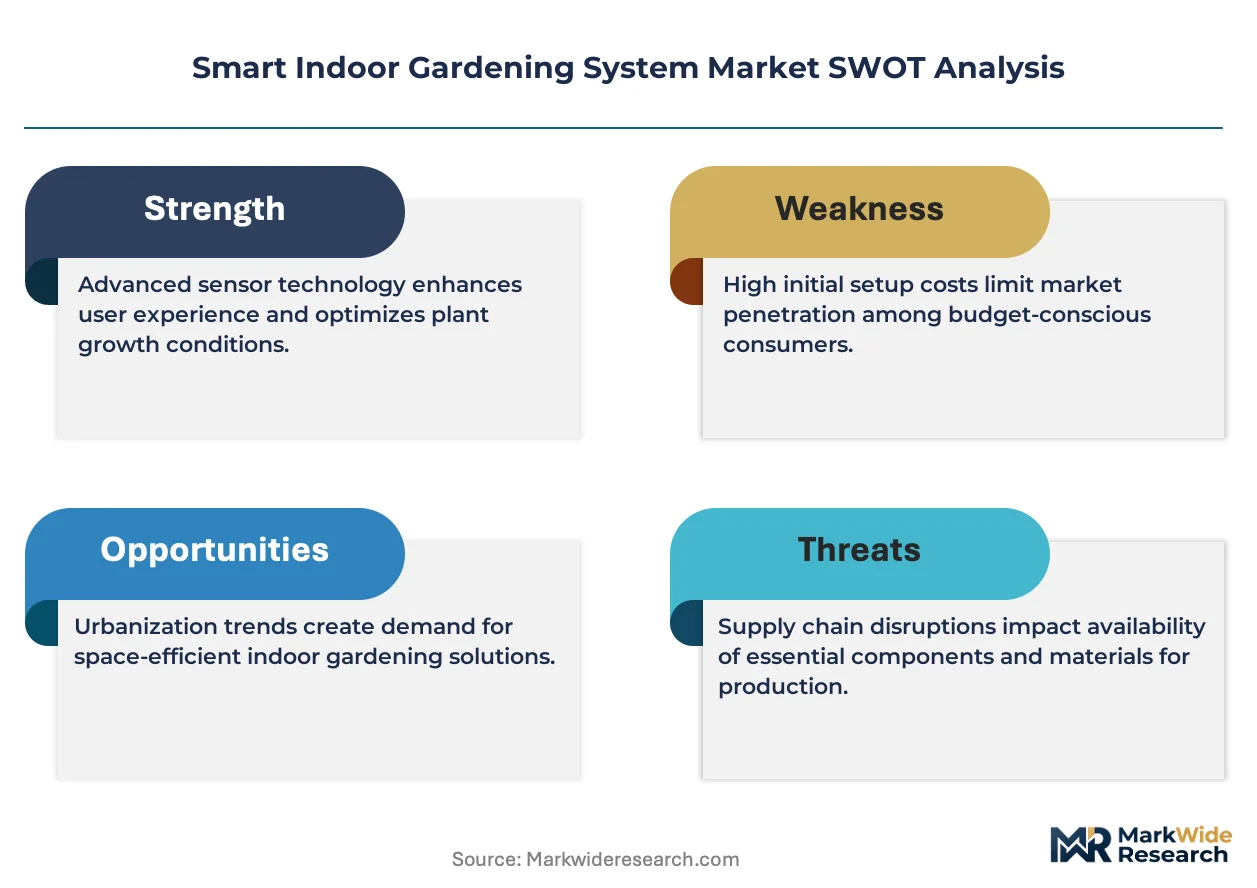
LED horticultural fixture efficiency mandates from Brussels and Tokyo are compressing margins for lighting suppliers while accelerating replacement cycles among urban apartment growers.
Growth Catalysts
- EU Ecodesign Directive:Tightening power consumption thresholds for horticultural LEDs are forcing fixture upgrades across German and Dutch residential installations, creating hardware refresh demand.
- Apartment kitchen adoption:Dense urban households in Seoul and Singapore are deploying compact hydroponic units as core food preparation infrastructure, normalizing countertop cultivation.
- Cloud-based recipe libraries:IoT-enabled systems with smartphone integration are reducing operational friction for novice users, expanding addressable demand beyond hobbyist segments.
Market Restraints
- Input cost volatility:Semiconductor shortages and rare earth price swings for LED phosphors are destabilizing module procurement budgets for system assemblers.
- Supply concentration risk:Chinese LED substrate manufacturing clusters control upstream wavelength calibration capacity, creating single-source dependencies for horticultural-specific spectra.
- Technical limitation:Current aeroponic nozzle designs suffer from mineral precipitation failures in hard water municipalities, restricting deployment to treated-water installations.
Strategic Opportunities
- Underpenetrated geography:Brazilian and Mexican metropolitan renters represent untapped demand for compact hydroponic systems adapted to tropical humidity conditions.
- Technology convergence:Integration of precision environmental sensors with connected home ecosystems is enabling subscription-based growing advisory services.
- Regulatory tailwind:Japan's METI energy labeling rules are creating compliance-driven upgrade incentives for inefficient legacy fixtures in Tokyo and Osaka households.
Industry Challenges
- Skill gap in photobiology:System manufacturers lack sufficient plant scientists to optimize spectral recipes for regional crop varieties, delaying product localization.
- Certification timeline compression:Divergent electromagnetic compatibility testing between EU CE marking and Japan's JIS standards is extending multi-market launch schedules.
- Integration complexity:Proprietary growing algorithms resist interoperability with open agricultural data protocols, fragmenting user experience across hardware brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Indoor Gardening System Market |
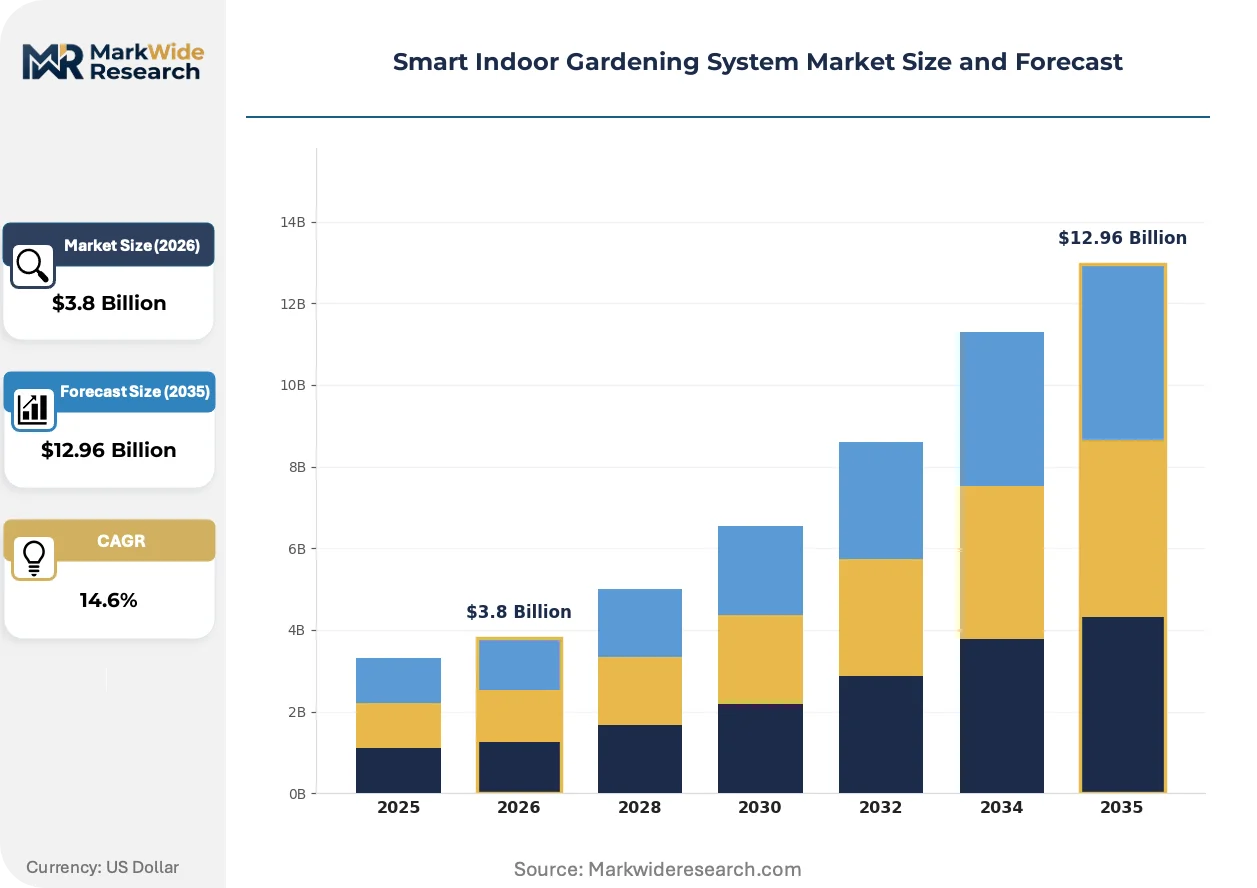
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydroponic Systems, Aeroponic Systems, Soil-Based Systems, Vertical Gardens Technology: IoT-Enabled, LED Lighting, Smart Sensors, Automated Watering End User: Home Gardeners, Urban Farmers, Educators, Retailers Distribution Channel: Online Retail, Specialty Stores, Home Improvement Stores, Direct Sales |
| Companies Covered | Click and Grow LLC, AeroGarden, Rise Gardens LLC, Gardyn Inc., AVA Technologies Inc., EDN Inc., Robert Bosch GmbH, Plantui Oy, AeroFarms LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Indoor Gardening System Market Strategic Shifts
Spectral tuning capabilities and connectivity architectures are redefining competitive differentiation, while regulatory efficiency mandates reshape hardware economics.
Full-spectrum LED modules with tunable red-blue-white ratios are expanding into residential kitchen deployments as apartment dwellers in Germany and Japan prioritize yield consistency over entry pricing. These systems enable precise photoperiod manipulation for leafy greens and herbs, compressing the skill barrier that previously limited hydroponic adoption to experienced growers.
Japan's METI energy labeling rules and the EU Ecodesign Directive are imposing strict power consumption ceilings on horticultural fixtures sold in their respective markets. Lighting manufacturers must redesign thermal management and driver electronics to maintain output while cutting wattage, disproportionately burdening budget-tier suppliers lacking R&D scale.
Direct-to-consumer seed pod subscriptions are displacing third-party nutrient and germplasm suppliers as primary recurring revenue streams. AeroGarden's channel control over proprietary pod formats locks users into branded consumables, a pattern now visible across South Korean and Singaporean smart gardening platforms where hardware margins compress and attachment rates determine profitability.
Smart Indoor Gardening System Market Segmentation
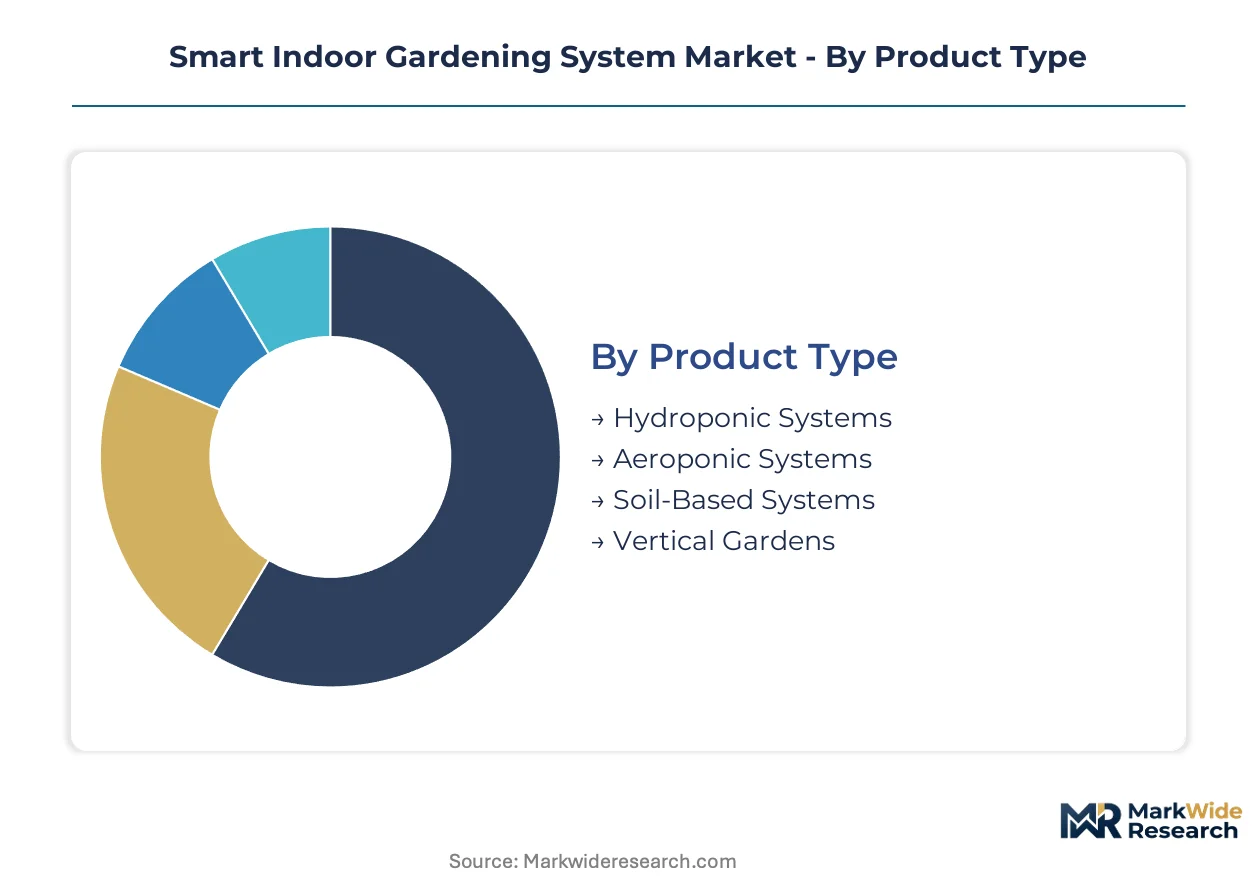
Smart indoor gardening systems fragment across hardware configurations, connectivity layers, and customer workflows. Segmentation reveals where certification burdens concentrate and which technology bundles command premium positioning versus commodity treatment.
Product Type:
Hydroponic and aeroponic configurations face divergent compliance paths under EU Ecodesign Directive wattage ceilings and Japan METI energy labeling thresholds, while soil-based units encounter lighter electromagnetic scrutiny.
- Hydroponic Systems:Nutrient film technique and deep water culture configurations dominate unit shipments through simplified maintenance protocols. German and Dutch apartment kitchens favor compact countertop units where EU Ecodesign Directive compliance drives fixture replacement cycles.
- Aeroponic Systems:Mist-based root delivery achieves superior water efficiency but requires precision nozzle engineering to prevent mineral precipitation in hard water municipalities. Tokyo and Osaka households upgrade legacy installations to meet METI energy labeling standards, compressing payback periods for premium hardware.
- Soil-Based Systems:Traditional substrate cultivation appeals to novice gardeners in Seoul seeking tactile familiarity with reduced technical setup.
- Vertical Gardens:Wall-mounted modular configurations serve Singaporean high-rise residents maximizing spatial efficiency in compact floor plans.
Hydroponic Systems sits at the top of the volume ranking, with Aeroponic Systems climbing the fastest.
Technology:
Margin concentration follows component standardization levels, with LED modules capturing replacement economics while IoT layers struggle with interoperability fragmentation.
- IoT-Enabled:Cloud-connected environmental monitoring with smartphone recipe libraries reduces operational friction for novice users. South Korean platforms integrate MFDS-aligned data security protocols for connected home ecosystems.
- LED Lighting:Full-spectrum modules with tunable red-blue-white ratios enable precise photoperiod manipulation. EU Ecodesign Directive thermal management requirements disproportionately burden budget-tier suppliers lacking R&D scale.
- Smart Sensors:Precision pH and nutrient concentration probes anchor subscription advisory services through connected home integration.
- Automated Watering:Programmable irrigation controllers adapt to California Title 20 appliance regulations influencing reservoir and pump specifications.
LED Lighting commands the widest installed base, though IoT-Enabled configurations are expanding most quickly as cloud recipe libraries mature.
End User:
Procurement authority and technical sophistication determine whether systems sell through retail channels or direct-to-consumer subscription models.
- Home Gardeners:Residential kitchen adoption concentrates among urban apartment dwellers seeking fresh herb and leafy green production. Singaporean and Dutch households normalize countertop cultivation as core food preparation infrastructure.
- Urban Farmers:Commercial-scale vertical farm operators in Japan demand spectral calibration precision for crop variety optimization, creating skill scarcity in photobiology expertise.
- Educators:School and university programs deploy compact systems for STEM curriculum integration.
- Retailers:Grocery and restaurant chains pilot in-store cultivation for hyperlocal supply chain demonstration.
Home Gardeners generate the deepest volume base, while Urban Farmers show the steepest expansion trajectory as commercial vertical farming scales.
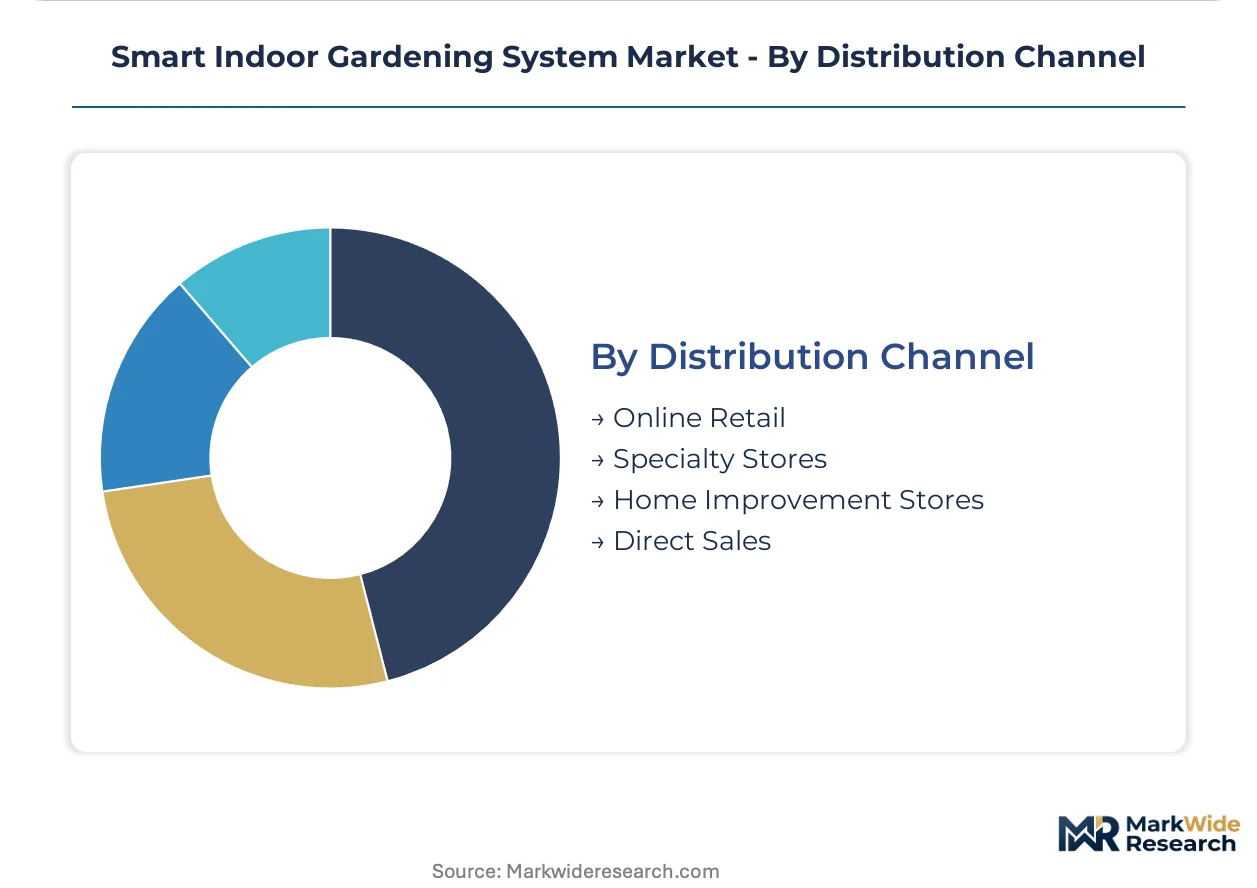
Distribution Channel:
Channel control determines recurring revenue capture, with proprietary seed pod formats locking users into branded consumables.
- Online Retail:Direct-to-consumer platforms sustain recurring seed pod subscriptions displacing third-party nutrient suppliers. AeroGarden's channel strength exemplifies hardware margin compression offset by attachment rate economics.
- Specialty Stores:Curated gardening retailers offer hands-on demonstration for technical product categories requiring education.
- Home Improvement Stores:Mass retail placement reaches casual purchasers through seasonal merchandising.
- Direct Sales:Enterprise and institutional procurement bypasses retail markup for volume deployments.
Online Retail leads channel volume, with Direct Sales gaining share fastest in commercial urban farming segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese LED substrate manufacturing clusters absorb fixture assembly work as EU Ecodesign Directive and Japan METI energy labeling rules widen compliance cost differentials. Production migrates toward jurisdictions with established wavelength calibration capacity and lighter electromagnetic compatibility burdens.
Germany
Apartment kitchen adoption concentrates in Berlin and Hamburg where dense urban households normalize countertop cultivation. The EU Ecodesign Directive mandates strict power consumption ceilings for horticultural LEDs, forcing fixture redesigns among domestic lighting suppliers. Bosch anchors precision sensor integration in Stuttgart-connected home ecosystems.
Japan
Tokyo and Osaka households upgrade legacy installations to meet METI energy labeling standards, compressing payback periods for premium hardware. METI rules constrain LED power consumption thresholds, disproportionately burdening budget-tier suppliers lacking R&D scale. Vertical farm operators in Chubu demand spectral calibration precision for regional crop varieties.
South Korea
Seoul apartment dwellers deploy compact hydroponic units as core food preparation infrastructure, normalizing residential cultivation. MFDS-aligned data security protocols govern IoT-enabled platform integration for connected home ecosystems. Gyeonggi-do manufacturing clusters supply full-spectrum LED modules with tunable red-blue-white ratios.
Singapore
High-rise residents maximize spatial efficiency through wall-mounted vertical garden configurations in compact floor plans. The country's national energy regulator imposes efficiency standards on residential appliance imports, including automated irrigation controllers. Smart gardening platforms target recurring seed pod subscriptions as hardware margins compress.
Netherlands
Dutch households exhibit deepest vertical farming familiarity, driving demand for precision environmental monitoring systems. EU Ecodesign Directive thermal management requirements apply to horticultural fixtures sold across the single market. Eindhoven-region electronics clusters supply LED driver electronics redesigned for reduced wattage output.
Smart Indoor Gardening System Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue IoT-enabled advisory services and tropical-climate hardware adaptations. The vendor base stratifies across three tiers: precision sensor integrators serving connected home ecosystems, direct-to-consumer platforms monetizing recurring consumables, and compact design specialists targeting premium urban segments. Two dominant competitive moves are reshaping positioning: technology convergence through precision environmental sensors and geographic expansion into underpenetrated tropical metropolitan markets.
Within the precision integration tier, Robert Bosch GmbH anchors European demand through sensor-embedded connected home ecosystems. AeroGarden exemplifies the direct-to-consumer archetype, leveraging proprietary seed pod formats to lock users into branded recurring revenue streams. Plantui Oy occupies the design-forward premium segment, competing in Nordic markets with compact hydroponic units tailored to apartment kitchen constraints.
| Leading Market Players |
|---|
| Click and Grow LLC |
| AeroGarden |
| Rise Gardens LLC |
| Gardyn Inc. |
| AVA Technologies Inc. |
| EDN Inc. |
| Robert Bosch GmbH |
| Plantui Oy |
| AeroFarms LLC |
| Others |
Value Chain & Pricing Dynamics
EU Ecodesign Directive wattage ceilings and Japan's METI energy labeling rules gate qualified LED module supply and premium-tier fixture pricing access, compressing margins for budget-tier assemblers while rewarding R&D-scaled suppliers with redesign capabilities and recurring replacement cycles.
Pricing Analysis
Direct-to-consumer channel margins sustain hardware-plus-subscription hybrid pricing where proprietary seed pod formats lock users into branded consumables. Price differentiation hinges on spectral calibration precision and IoT platform certification tier, with cloud-connected advisory services commanding premium positioning. Cost compression in entry-tier hydroponic units is intensifying because Chinese LED substrate manufacturing clusters absorb assembly work. Apartment kitchen adopters in Seoul and Singapore exhibit highest price sensitivity, while commercial vertical farm operators in Japan show lowest sensitivity due to yield-optimization requirements.
Supply Chain Analysis
Regional distribution centers in Shenzhen and Eindhoven coordinate hub-and-spoke patterns for horticultural LED modules and precision sensor components. Upstream manufacturing draws from China, South Korea, and the Netherlands for wavelength-calibrated substrates, rare-earth phosphors, and thermal management electronics. Single-source vulnerability concentrates in Chinese LED substrate clusters controlling horticultural-specific spectra calibration. Distribution runs through direct-to-consumer platforms and specialty retail channels, with enterprise procurement bypassing markup for volume urban farming deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart indoor gardening system production exhibits geographic-arbitrage characteristics where EU regulatory compliance costs widen cost differentials against Asian manufacturing bases, rewarding suppliers with dual-market certification capabilities.
For Market Incumbents: Lock in recurring revenue capture through proprietary seed pod formats and cloud-based recipe library subscriptions that resist interoperability with open agricultural data protocols. Defend margin position by deepening backward integration into precision environmental sensor production and securing wavelength calibration capacity in Gyeonggi-do manufacturing clusters ahead of semiconductor shortage recurrence. For New Entrants and Emerging Players: Begin with tropical-climate hardware adaptations for Brazilian and Mexican metropolitan renters where humidity-resistant compact hydroponic systems face minimal incumbent presence. Target direct-to-consumer online channels with MFDS-aligned data security protocols for South Korean connected home ecosystem integration, bypassing capital-intensive retail shelf competition. For Investors and Strategic Acquirers: Roll-up economics work for precision sensor integrators because connected home ecosystem fragmentation creates multiple mid-cap acquisition targets with complementary certification footprints. Monitor METI energy labeling rule amendments as inflection indicator for Japanese hardware replacement cycle acceleration and premium fixture demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Seed Pod Format Lock-in | AeroGarden's channel control demonstrates recurring revenue displacement of third-party nutrient suppliers. |
| Precision Sensor Integration | Bosch's Stuttgart-connected home ecosystem anchors European demand through environmental monitoring bundling. |
| Tropical Climate Hardware Adaptation | Brazilian and Mexican metropolitan markets lack humidity-optimized compact hydroponic system supply. |
| Dual-Market Certification Investment | Simultaneous EU Ecodesign Directive and Japan METI compliance widens addressable premium-tier demand. |
| Cloud Recipe Library Expansion | South Korean and Singaporean platforms reduce novice user operational friction through smartphone integration. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with LED module procurement leads at system assemblers, vertical farm operators in Tokyo and Seoul, connected home ecosystem engineers, and specialty retail category buyers. Secondary validation drew from EU Ecodesign Directive implementation documents, Japan METI energy labeling databases, MFDS data security protocol filings, and customs records for horticultural LED substrate trade flows. Bottom-up unit shipment estimates triangulated against top-down addressable household projections across dense urban apartment markets.
Comparable historical reference periods anchored the projection horizon to pre-pandemic baseline growth trajectories and post-regulatory amendment replacement cycle timing. Segmentation modeling spanned hardware configuration, connectivity architecture, end-user workflow, and regional regulatory cluster dimensions. CAGRs derived from fitted growth curves incorporating apartment kitchen adoption saturation rates, LED fixture replacement cycle compression under efficiency mandates, and cloud platform subscriber attachment economics. Industry-specific inputs included spectral recipe localization timelines and electromagnetic compatibility certification duration estimates.
Several conditions sit outside the modeled scope, including potential harmonization between proprietary growing algorithms and open agricultural data protocols, breakthrough aeroponic nozzle designs eliminating hard water precipitation failures, and abrupt rare-earth export restrictions from dominant supplier geographies. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Indoor Farming Technologies
Europe Grow Light Market
Indoor Farming Technologies
Vertical Farming Market
Indoor Farming Technologies
Aeroponics Market
Indoor Farming Technologies
Vertical Farming Technology Market
Indoor Farming Technologies
Quantum Board Grow Light Market
Indoor Farming Technologies
US Vertical Farming Market
Indoor Farming Technologies
Hydroponic Substrate Market
Indoor Farming Technologies
China Greenhouse Horticulture Market
Indoor Farming Technologies
Cannabis Vertical Farming Market
Indoor Farming Technologies
Europe Indoor Farming Market
Indoor Farming Technologies
Mexico Vertical Farming Market
Indoor Farming Technologies
United States Plant Growth Chambers Market
Indoor Farming Technologies
LED Farming Market
Indoor Farming Technologies
Europe Vertical Farming Market
Indoor Farming Technologies
GCC Grow Light Market
Indoor Farming Technologies
United States Grow Light Market