
 North America Agricultural Films Market | 2026-2036
North America Agricultural Films Market Size, Share, and Industry Trends Forecast 2026-2036
North America Agricultural Films Market Analytics
Skilled polymer compounding expertise is unwinding supply bottlenecks across the agricultural films value chain. BASF SE leverages its specialty resin portfolio to dominate high-performance greenhouse film formulations. Dow Inc. anchors North American LLDPE supply through integrated Gulf Coast petrochemical infrastructure. Berry Global Inc. competes via vertical control of both resin sourcing and regional converting capacity.
North America agricultural films comprise thermoplastic polymer sheets engineered from LDPE, LLDPE, HDPE, or PVC resins, typically ranging from 20 to 200 microns in gauge, manufactured through blown film extrusion and deployed to modify crop microclimates, conserve soil moisture, or preserve forage quality. Mulch films lead product type demand due to established row-crop penetration, while silage films represent the fastest-expanding category as dairy operations scale wrapped bale systems across Wisconsin and New York. LLDPE occupies the dominant material position for puncture resistance in silage and greenhouse applications, though bio-based alternatives from Novamont North America Inc. are gaining trial adoption among organic-certified cooperatives.
The EPA regulates agricultural plastic waste under evolving state-level extended producer responsibility frameworks, while the USDA Natural Resources Conservation Service incentivizes moisture-barrier adoption through conservation program cost-shares. FDA indirect food contact standards constrain resin additive packages for films applied to edible horticulture, particularly in Mexico's export-oriented berry sector. Stakeholders must monitor biopolymer cost parity timelines and state-level plastic mulch disposal mandates to calibrate capital allocation between conventional and next-generation film platforms.
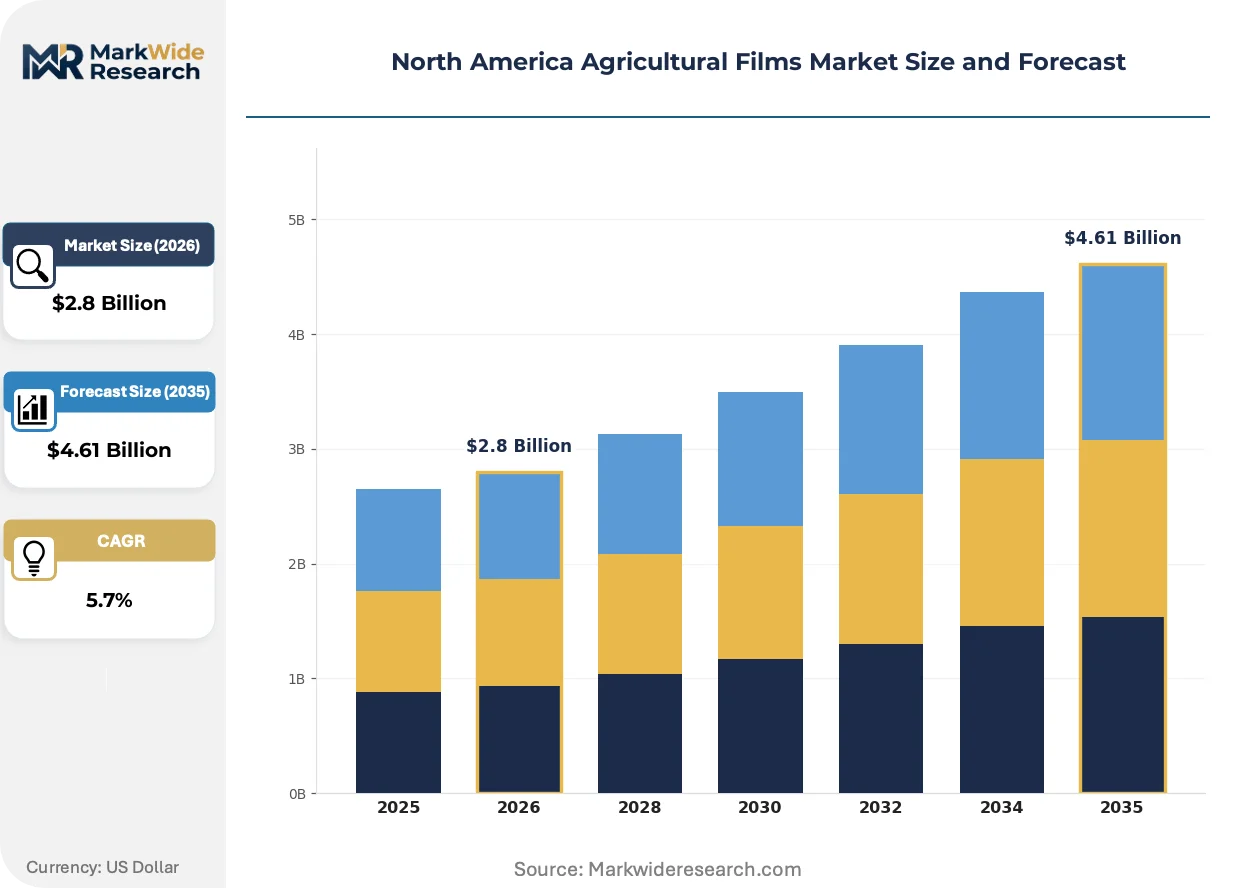
Market Dynamics
Specialty crop growers in California's Central Valley and Florida's citrus belt are accelerating mulch film deployment to combat irrigation restrictions, while EPA state-level extended producer responsibility frameworks force converters toward bio-based resin trials.
Growth Catalysts
- USDA Conservation Cost-Shares:The USDA Natural Resources Conservation Service subsidizes moisture-barrier adoption across the Great Plains grain belt, lowering capital barriers for row-crop operators.
- Dairy Bale Wrapping Scale-Up:Wisconsin and New York dairy operations are converting from bunker silos to wrapped bale systems, expanding puncture-resistant LLDPE silage film volumes.
- Water Scarcity Mandates:California's Sustainable Groundwater Management Act restrictions on agricultural pumping are compelling specialty growers toward evaporation-suppressing mulch films.
Market Restraints
- Resin Input Volatility:Gulf Coast ethylene supply disruptions from hurricane-season infrastructure damage expose converters to LLDPE price spikes.
- Biopolymer Cost Parity Gap:Novamont North America's bio-based alternatives remain priced at 40-60% premiums versus conventional LLDPE, constraining organic-certified cooperative adoption.
- FDA Additive Constraints:FDA indirect food contact standards restrict antioxidant and UV stabilizer packages for films deployed in Mexico's export-oriented berry sector.
Strategic Opportunities
- Canadian Prairie Expansion:Saskatchewan and Manitoba grain operations remain underpenetrated for silage film versus US dairy belts, presenting first-mover terrain.
- Compostable Mulch Mandates:California's SB 54 implementation timeline creates procurement pull for soil-biodegradable alternatives in strawberry and vegetable production.
- Greenhouse Film Upgrade Cycles:Anti-drip and thermal barrier coating technologies are converging with diffused-light formulations, enabling premium positioning in controlled-environment agriculture.
Industry Challenges
- Polymer Compounding Talent Scarcity:Skilled formulation chemists capable of balancing UV stability, mechanical strength, and biodegradation rates command premium wages across the value chain.
- Mulch Retrieval Compliance Costs:State-level plastic mulch disposal mandates in California and Florida impose collection infrastructure investments on grower cooperatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Agricultural Films Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mulch Films, Greenhouse Films, Silage Films, Shrink Films Material: LDPE, LLDPE, HDPE, PVC End User: Farmers, Agricultural Cooperatives, Nurseries, Greenhouses Application: Crops, Horticulture, Aquaculture, Livestock |
| Companies Covered | Berry Global Inc., BASF SE, Dow Inc., RKW Group, Coveris, ExxonMobil Chemical, DuPont de Nemours Inc., Armando Alvarez Group, Novamont North America Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Agricultural Films Market Evolving Landscape
Film functionality is bifurcating between commodity moisture barriers and precision-engineered climate-modification systems, with resin chemistry and additive packages diverging accordingly.
Oxygen-scavenging multilayer silage films are supplanting conventional monolayer wraps in large-scale dairy operations. Wisconsin and New York cooperatives are trialing seven-layer coextrusion systems that extend anaerobic preservation windows. This technology is compressing spoilage loss rates while forcing smaller converters toward toll-manufacturing arrangements with multilayer-capable extrusion houses.
EPA state-level extended producer responsibility frameworks are reshaping post-use collection economics. California's SB 54 regulations now mandate producer-funded recovery systems for agricultural plastic waste, compelling resin suppliers to underwrite reverse-logistics networks. Berry and vegetable growers in the Salinas Valley are responding by consolidating purchasing through cooperative buying groups that bundle film supply with retrieval services.
Precision irrigation integration is altering mulch film specification patterns. Drip-line compatibility requirements are driving demand for perforated and embossed film geometries in California almond and pistachio orchards. Growers in the San Joaquin Valley are shifting procurement toward custom-gauge rolls engineered for specific emitter spacing, displacing standard-width commodity offerings through specification lock-in.
North America Agricultural Films Market Segmentation
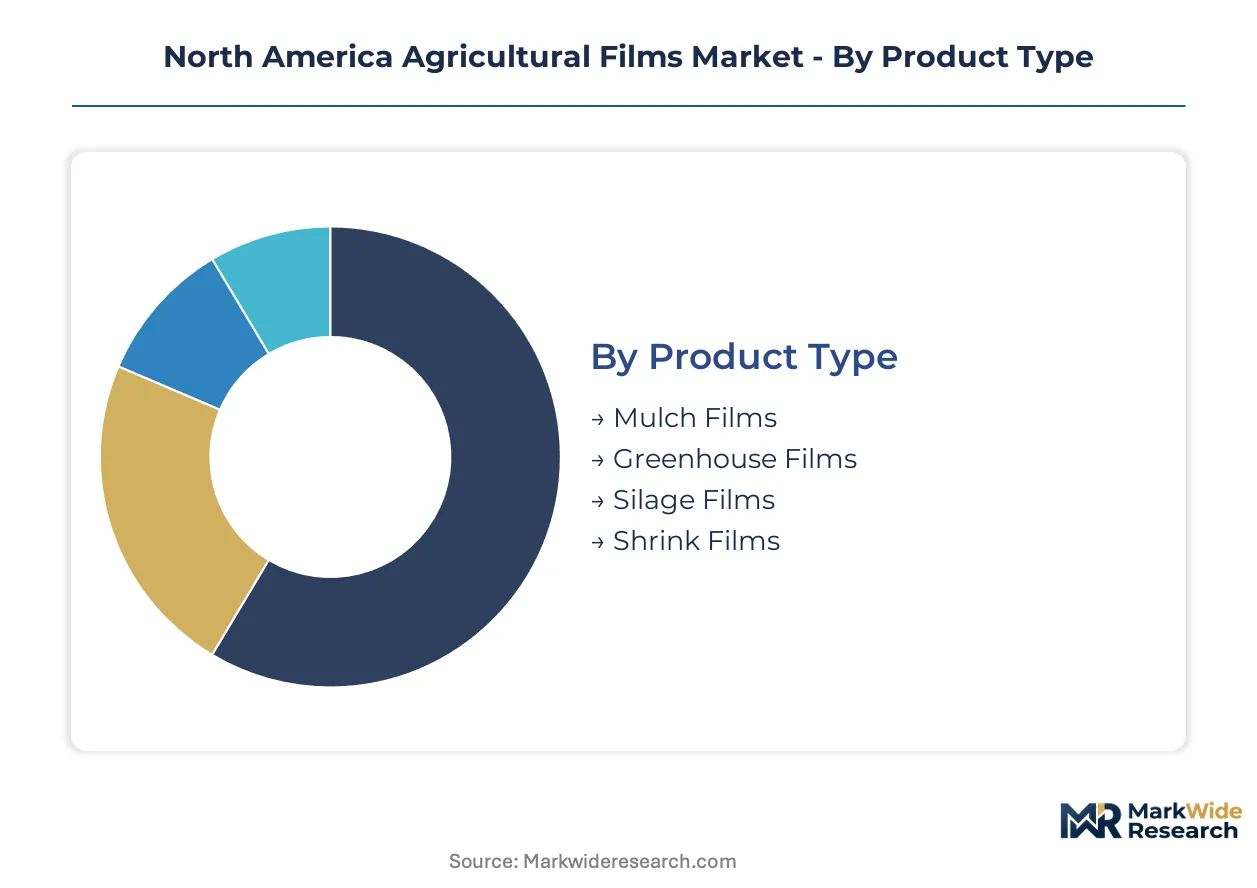
Segmentation in agricultural films reveals how resin chemistry, deployment format, and end-user scale create divergent margin profiles. Substitution pressures from bio-based alternatives and retrieval mandates are reshaping competitive positioning across every category.
Product Type:
Substitution pressure concentrates in mulch films, where soil-biodegradable alternatives threaten conventional LLDPE formulations under California's SB 54 implementation.
- Mulch Films:These thermoplastic sheets range from 15 to 50 microns, engineered for soil moisture retention and weed suppression. California Central Valley strawberry and vegetable growers dominate procurement volumes, driven by Sustainable Groundwater Management Act irrigation restrictions that elevate evaporation control as a priority.
- Silage Films:Puncture-resistant wraps between 25 and 50 microns preserve anaerobic conditions in forage bales. Wisconsin and New York dairy operations are converting from bunker silos to wrapped bale systems, expanding demand for oxygen-scavenging multilayer constructions.
- Greenhouse Films:Diffused-light and thermal-barrier formulations modify crop microclimates in controlled-environment agriculture.
- Shrink Films:Bundling wraps protect palletized agricultural inputs and harvested produce during regional distribution.
Mulch films retain volume leadership; silage films hold the steepest expansion curve.
Material:
Cost tier stratification separates commodity polyolefins from performance-engineered resins, with bio-based premiums constraining organic-certified adoption.
- LLDPE:Linear low-density polyethylene delivers superior puncture resistance and tear strength through hexene or octene comonomer incorporation. Silage and greenhouse applications concentrate demand in the Great Plains grain belt and Florida's citrus belt, where mechanical durability under field stress determines specification.
- LDPE:Low-density polyethylene offers clarity and flexibility in blown film extrusion for general-purpose mulch applications. California and Florida specialty crop growers specify LDPE for short-season vegetables where retrieval economics favor thinner gauges.
- HDPE:High-density polyethylene provides stiffness and chemical resistance in nursery pot labels and selected greenhouse structural components.
- PVC:Polyvinyl chloride retains niche positioning in high-clarity greenhouse glazing where thermal insulation properties justify cost premiums.
LLDPE captures the dominant value share; bio-based alternatives are expanding most quickly among organic-certified cooperatives.
End User:
Customer type determines procurement scale, with cooperatives leveraging consolidated purchasing to bundle film supply with mandated retrieval services.
- Farmers:Individual row-crop and specialty producers specify films through dealer networks or direct converter relationships. California almond and pistachio growers in the San Joaquin Valley are shifting toward custom-gauge perforated rolls engineered for specific drip-line emitter spacing.
- Agricultural Cooperatives:Member-owned purchasing organizations aggregate volume across dairy and produce operations. Wisconsin and New York dairy cooperatives are consolidating silage film procurement to secure multilayer coextrusion supply and meet EPA extended producer responsibility compliance.
- Nurseries:Containerized plant producers specify UV-stabilized formulations for propagation bench coverage and overwintering protection.
- Greenhouses:Controlled-environment operators demand anti-drip and thermal barrier coatings in premium film constructions.
Farmers constitute the largest addressable base; agricultural cooperatives are gaining share fastest through compliance-driven consolidation.
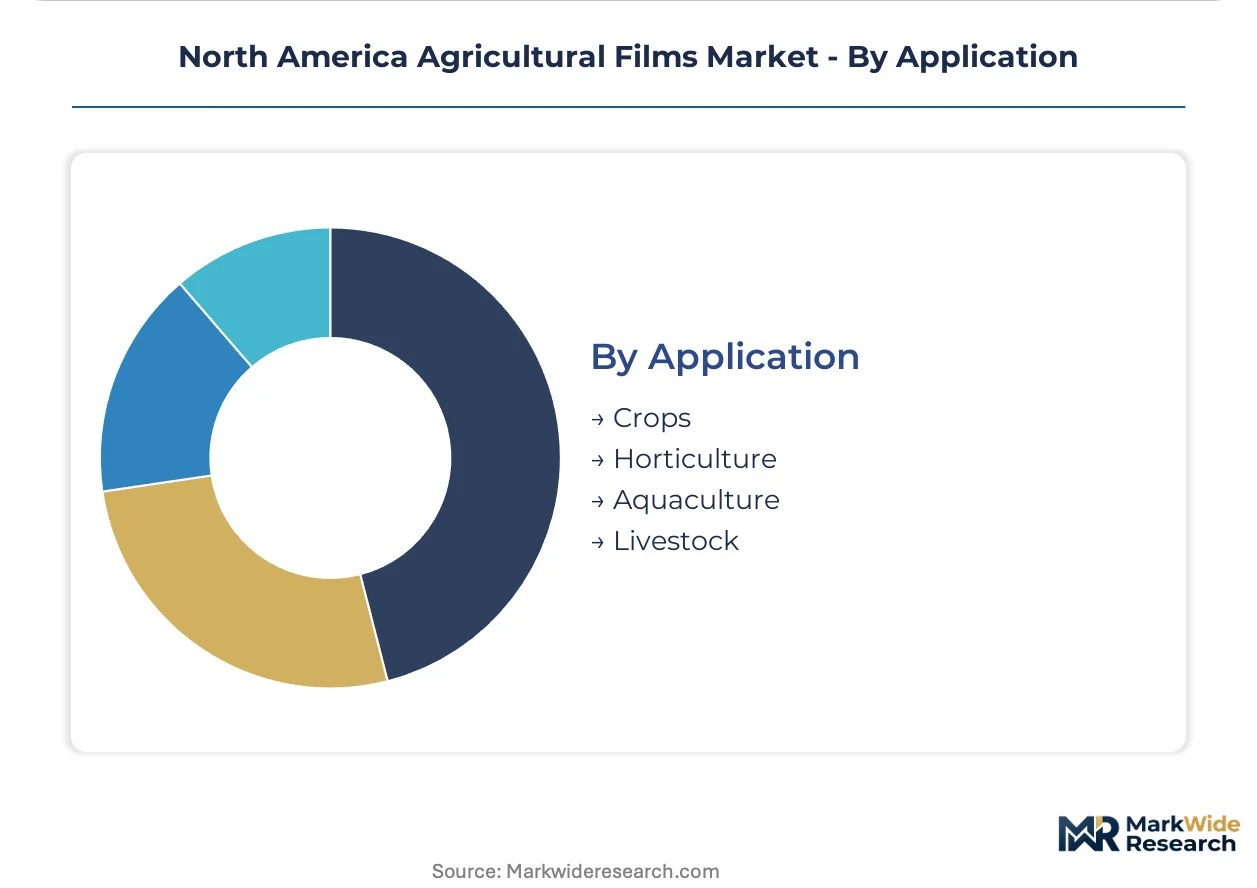
Application:
Application maturity varies sharply, with livestock preservation formats expanding while traditional crop coverage faces regulatory headwinds.
- Crops:Row-crop and specialty produce cultivation represents the established demand center for mulch and greenhouse films. California's Central Valley and Florida's citrus belt anchor procurement, though plastic mulch disposal mandates are elevating total cost of ownership.
- Livestock:Forage preservation and animal housing applications concentrate in dairy-intensive geographies. Wisconsin's transition from bunker silos to wrapped bale systems is compressing spoilage loss rates and extending anaerobic preservation windows.
- Horticulture:Nursery stock and ornamental production utilize films for propagation environments and container overwintering.
- Aquaculture:Pond liners and tank containment systems represent an emerging specification category with distinct resin and gauge requirements.
Crop applications retain volume leadership; livestock applications hold the steepest expansion trajectory as dairy operations scale wrapped bale systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA state-level extended producer responsibility frameworks anchor regulatory pressure across the United States, while Canadian prairie operations and Mexico's export agriculture create divergent demand profiles across the North American landmass.
United States
California's Sustainable Groundwater Management Act restrictions drive specialty crop growers toward evaporation-suppressing mulch films in the Central Valley. The EPA's evolving plastic waste regulations pressure converters toward bio-based formulation trials. Dairy operations in Wisconsin and New York are converting from bunker silos to wrapped bale systems, expanding silage film volumes.
Canada
Saskatchewan and Manitoba grain operations remain underpenetrated for silage film versus US dairy belts, presenting first-mover terrain for puncture-resistant LLDPE suppliers. Health Canada and PMRA regulate agricultural plastic waste through provincial stewardship programs. Prairie dairy cooperatives are consolidating procurement to secure multilayer coextrusion supply and meet compliance timelines.
Mexico
Export-oriented berry producers in Baja California and Jalisco face FDA indirect food contact standards that constrain antioxidant and UV stabilizer packages for films. The central bank's agricultural credit programs subsidize protected agriculture infrastructure in the Bajío Region. Greenhouse operators in Querétaro and Guanajuato are upgrading to diffused-light thermal barrier formulations.
North America Agricultural Films Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with resin producers and regional converters occupying distinct competitive positions. BASF SE leverages specialty resin portfolios to dominate high-performance greenhouse film formulations, while Dow Inc. anchors LLDPE supply through integrated Gulf Coast infrastructure. Berry Global Inc. competes via vertical control of both resin sourcing and regional converting capacity. Competitive moves concentrate on capacity expansion in multilayer extrusion and strategic partnerships for bio-based resin trials.
Within the integrated chemical-resin tier, BASF SE and Dow Inc. exemplify upstream-backward players that supply formulation expertise downstream. Berry Global Inc. occupies a position bridging resin access with converting scale. Novamont North America Inc. represents the bio-based specialization archetype, serving organic-certified cooperatives with soil-biodegradable alternatives.
| Leading Market Players |
|---|
| Berry Global Inc. |
| BASF SE |
| Dow Inc. |
| RKW Group |
| Coveris |
| ExxonMobil Chemical |
| DuPont de Nemours Inc. |
| Armando Alvarez Group |
| Novamont North America Inc. |
| Others |
Value Network & Pricing Analysis
Soil-biodegradable resin substitution in California strawberry operations simultaneously shifts procurement geography toward Novamont's North American supply base and compresses pricing premiums for conventional LLDPE mulch formulations across the Central Valley.
Pricing Analysis
Geographic price spreads between Gulf Coast resin hubs and California converting centers widen during hurricane-season ethylene disruptions. Three-tier pricing structure across premium oxygen-scavenging multilayer silage films, standard LLDPE greenhouse constructions, and economy LDPE mulch grades dominates transactional patterns. Price differentiation rests on puncture-resistance certification and volume-scale procurement through cooperative buying groups. Cost compression in commodity mulch tiers intensifies because California SB 54 retrieval mandates elevate total cost of ownership. Organic-certified cooperatives exhibit lowest price sensitivity due to compliance-driven specification lock-in, while individual row-crop operators in the Great Plains grain belt remain most responsive to per-unit resin fluctuations.
Supply Chain Analysis
Inbound logistics costs from Houston-Galveston container terminals to California Central Valley distribution centers spike during peak agricultural film deployment windows. Raw material supply concentrates in United States Gulf Coast petrochemical corridors, Canadian Alberta resin distribution nodes, and Mexican petrochemical feedstock processing near Tampico. The supply chain draws from ethylene monomer, hexene/octene comonomer packages, and specialty UV stabilizer additive formulations. Single-source vulnerability permeates multilayer coextrusion equipment supply, with European and Asian machinery builders commanding extended lead times. Distribution runs through regional converting facilities co-located with dairy cooperative clusters in Wisconsin and specialty crop packing houses in Florida.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America agricultural films market sits at a cyclical recovery phase driven by dairy herd expansion and silage infrastructure replacement cycles across the Upper Midwest.
For Market Incumbents: Shield margin positions by securing captive LLDPE supply through backward integration into Gulf Coast ethylene infrastructure or long-term offtake agreements with integrated resin producers. Accelerate multilayer coextrusion capacity additions in Wisconsin dairy corridors to preempt toll-manufacturing dependency. Counter Novamont's bio-based penetration by embedding retrieval services into cooperative procurement contracts, converting compliance costs into relationship lock-in.
For New Entrants and Emerging Players: Lead with soil-biodegradable mulch formulations targeting California strawberry and vegetable cooperatives facing SB 54 implementation deadlines. Exploit underpenetrated silage film demand in Saskatchewan and Manitoba grain operations where first-mover positioning remains available. Pursue toll-manufacturing partnerships with stranded multilayer extrusion capacity to bypass capital-intensive equipment investments.
For Investors and Strategic Acquirers: The market sits at an early-cycle expansion phase that favors vertically integrated resin-to-film operators with EPA compliance infrastructure already deployed. Long-term viability over the coming decade hinges on positioning for biopolymer cost-parity inflection and extended producer responsibility consolidation. Acquisition targets should display regional converting density in dairy-intensive geographies. Monitor California groundwater pumping restriction enforcement intensity as the signal indicating mulch film demand acceleration or deceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Multilayer Coextrusion Capacity Expansion | Wisconsin dairy cooperatives demand seven-layer oxygen-scavenging silage wraps that extend anaerobic preservation windows. |
| Bio-Based Resin Supply Partnership | Novamont's North American trials with organic-certified cooperatives create procurement templates for soil-biodegradable alternatives. |
| Reverse Logistics Network Development | California SB 54 mandates compel resin suppliers to underwrite agricultural plastic waste collection infrastructure. |
| Custom Gauge Perforation Capability | San Joaquin Valley almond growers specify drip-line compatible mulch films engineered for precise emitter spacing. |
| Canadian Prairie Distribution Buildout | Saskatchewan and Manitoba grain operations remain underpenetrated versus US dairy belts for puncture-resistant LLDPE supply. |
Research Methodology
Operator-level perspectives from blown film extrusion plant managers, dairy cooperative procurement directors, California specialty crop growers, EPA regulatory compliance officers, and resin compounding technical directors anchored the qualitative base. Primary interview findings combined with secondary validation from USDA conservation program databases, EPA state-level extended producer responsibility filings, customs and trade flow records, and SEC disclosures from integrated chemical-resin producers. Bottom-up volume modeling across product type, material chemistry, and end-user segments triangulated against top-down macroeconomic indicators.
Sensitivity analysis tested forecast robustness across resin price volatility scenarios, biopolymer adoption acceleration curves, and regulatory implementation timelines. The analytical framework segmented demand by mulch film, silage film, greenhouse film, and shrink film categories; further disaggregated by LLDPE, LDPE, HDPE, PVC, and bio-based material tiers; and cross-tabulated against farmer, cooperative, nursery, and greenhouse end-user archetypes across the projection horizon. CAGRs derived from historical volume trajectories adjusted for dairy herd expansion patterns, irrigation restriction enforcement intensity, and multilayer technology penetration rates.
The analysis sits within stated boundaries; outcomes outside sustained ethylene supply stability, EPA regulatory implementation adherence, and dairy operation capital expenditure continuity would require recalibration. Forecasts reflect documented assumptions regarding biopolymer cost-parity timelines and state-level plastic mulch disposal mandate expansion. Extreme weather disruption to Gulf Coast petrochemical infrastructure or accelerated FDA additive constraint enforcement would necessitate model revision. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Fabrics
Shade Net Market
Agricultural Fabrics
Africa Agricultural Film Market
Agricultural Fabrics
Horticulture Film Market
Agricultural Fabrics
Silage Wrap Films Market
Agricultural Fabrics
South America Agricultural Films Market
Agricultural Fabrics
Canopy Market
Agricultural Fabrics
Europe Agricultural Films Market
Agricultural Fabrics
Pond Liners Market
Agricultural Fabrics
Anti Wind Net Market
Agricultural Fabrics
Nonwoven Crop Cover Market
Agricultural Fabrics
Global Agriculture Nets Market
Agricultural Fabrics
Coco Coir Market
Agricultural Fabrics
North America Silo Bags Market
Agricultural Fabrics
Silo Bags Market
Agricultural Fabrics
US Agro Textile Market
Agricultural Fabrics
Global Greenhouse Film Market