
 India Smart Home Market | 2026-2036
India Smart Home Market Size, Share, and Industry Trends Forecast 2026-2036
India Smart Home Market Insights
Premium-tier home automation with centralized control hubs is unwinding legacy siloed device installations across Indian metros. Samsung Electronics leverages its Galaxy ecosystem to sustain consumer stickiness in connected living spaces. Schneider Electric anchors commercial-grade building management systems that now migrate into large-format residential projects. Siemens AG competes on industrial protocol reliability adapted for Indian voltage fluctuations and grid instability.
India smart home systems encompass networked sensors, actuators, and controllers that communicate through Wi-Fi, Zigbee, or Z-Wave protocols to automate lighting, climate, security, and appliance functions. These installations typically operate on 230V/50Hz electrical infrastructure with surge protection rated for monsoon-season grid variability, serving both energy optimization and remote monitoring purposes. Smart Security and Smart Lighting currently dominate installed value, while Smart Thermostats represent the fastest-expanding category as heat-wave frequency intensifies cooling automation demand. The Residential end-user segment captures volume leadership, though Hospitality applications generate superior per-unit margins through integrated guest-experience platforms.
BIS mandates IoT device certification under compulsory registration schemes, while the Smart Cities Mission channels municipal procurement toward interoperable standards. TRAI's data-localization consultations and CEA electrical safety codes further constrain foreign cloud-dependency and mandate fire-rated wiring for automation retrofits. Stakeholders must monitor state-level RERA enforcement on pre-installed smart infrastructure in new construction, as this determines whether automation becomes a bundled commodity or remains an aftermarket upgrade decision.
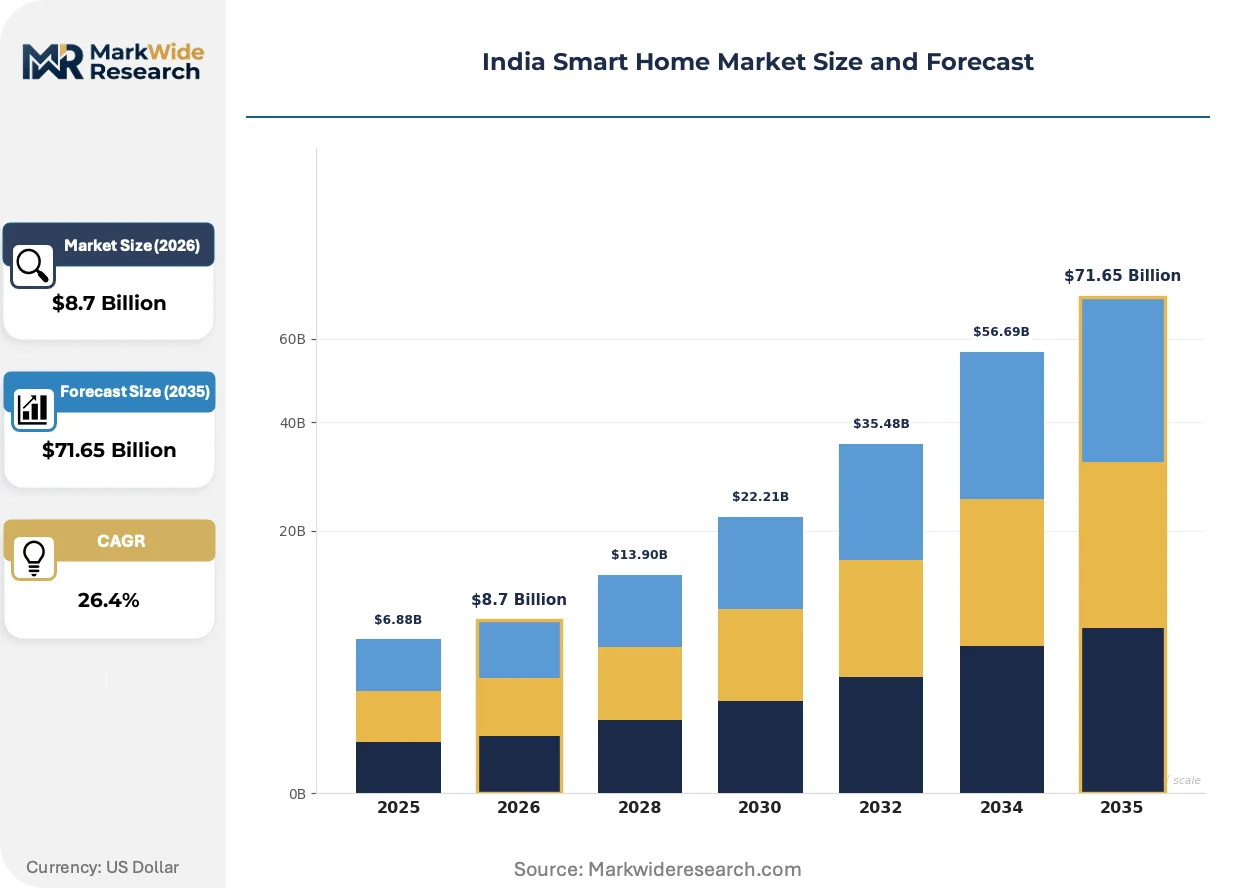
Market Dynamics
Pre-installed automation infrastructure in new residential construction under RERA-mandated developments is converting smart home systems from aftermarket upgrades into bundled amenities, compressing vendor margins while expanding addressable volume.
Growth Catalysts
- BIS Compulsory Registration Scheme:Mandatory IoT device certification creates quality barriers that filter substandard imports and elevate compliant domestic manufacturers.
- Heat-wave intensity:Rising cooling automation demand accelerates thermostat category expansion across Maharashtra and Telangana residential stock.
- Smart Cities Mission:Municipal procurement of interoperable building management protocols establishes technical baselines that cascade into adjacent residential specifications.
Market Restraints
- Monsoon-season grid instability:Voltage fluctuation damage rates elevate total cost of ownership and necessitate costly surge protection layering.
- Import dependency for chipsets:Concentration in East Asian semiconductor supply creates exposure to shipping lane disruptions and currency volatility.
- Zigbee-Z-Wave protocol incompatibility:Fragmented wireless standards force consumers into single-ecosystem lock-in or expensive multi-hub architectures.
Strategic Opportunities
- Tier-2 city penetration:Pune, Ahmedabad, and Kochi construction pipelines remain undersupplied with integrated automation relative to metro saturation.
- Hospitality guest-experience platforms:Integrated room control systems command per-unit margins significantly above residential installations.
- CEA fire-rated wiring mandates:Retrofit safety requirements create bundled upgrade pathways combining electrical and automation infrastructure.
Industry Challenges
- Embedded systems firmware expertise:Shortage of engineers proficient in 230V/50Hz electrical safety integration constrains product development velocity.
- TRAI data-localization compliance:Cloud architecture reconfiguration timelines extend product launch cycles for foreign platform providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Smart Home Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $71.65 Billion |
| CAGR (2026 – 2036) | 26.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Lighting, Smart Security, Smart Thermostats, Smart Appliances Technology: Wi-Fi, Zigbee, Bluetooth, Z-Wave End User: Residential, Commercial, Hospitality, Retail Distribution Channel: Online Retail, Direct Sales, Distributors, Specialty Stores |
| Companies Covered | ABB Ltd., Samsung Electronics Co., Ltd., Schneider Electric SE, Oakter Smart Home Technologies Pvt Ltd., SmarDen, Siemens AG, Legrand SA, Crestron Electronics, Honeywell International Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Smart Home Market Trends and Innovations
Protocol convergence and edge computing architectures are dissolving the boundary between consumer-grade convenience and commercial-grade reliability in residential automation.
Matter-over-Thread connectivity is fragmenting the legacy hub-centric model by enabling direct device-to-device communication without cloud intermediation. Premium developers in Gurugram and Mumbai are specifying Thread-native hardware for new projects. This topology is fragmenting vendor control over user data streams and forcing business model pivots toward hardware margin capture.
BIS certification requirements for IoT devices are tightening electromagnetic compatibility testing protocols that previously allowed self-declaration. Domestic manufacturers with existing testing infrastructure capture timeline advantages. Imported brands face extended clearance cycles, compressing their effective product refresh cadence against local competitors.
Builder-direct specification is displacing retail channel influence in metropolitan new construction. Large-format residential projects in Karnataka and Telangana now source automation through developer procurement offices rather than consumer electronics distributors. This channel rotation concentrates volume with vendors capable of project-scale logistics and white-label customization.
India Smart Home Market Segmentation
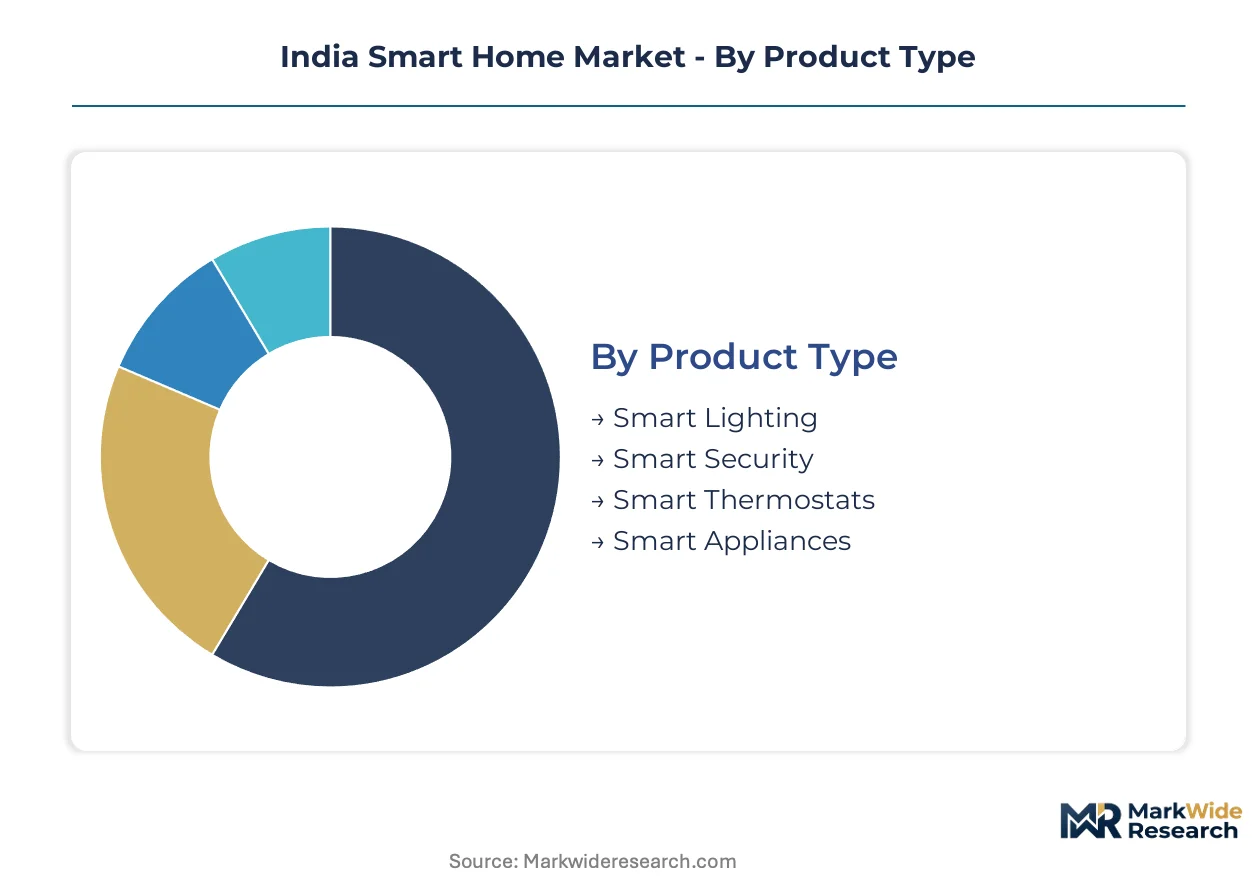
Segmentation in the India smart home market reveals how protocol wars, channel bifurcation, and end-use margin differentiation are fragmenting vendor strategies across distinct competitive arenas. Each dimension carries unique substitution pressures that reshape investment prioritization.
Product Type:
Smart Lighting faces the most acute substitution threat from conventional LED retrofits with basic dimming, while Smart Security benefits from regulatory tailwinds that resist commoditization.
- Smart Security:Networked sensors, cameras, and access control systems with 230V surge-rated power supplies. Demand clusters in Gurugram and Mumbai premium developments where RERA-mandated pre-installation creates bundled amenity economics.
- Smart Lighting:Connected fixtures and control modules operating across Wi-Fi, Zigbee, or Thread protocols. Maharashtra and Karnataka residential stock drives volume as heat-wave intensity elevates circadian automation for cooling load management.
- Smart Thermostats:Climate control automation with grid-fluctuation tolerance for monsoon-season reliability. Telangana leads state-level penetration.
- Smart Appliances:Connected white goods with BIS-certified IoT modules. Adoption concentrates in metro retrofit channels.
Smart Security anchors the volume base while Smart Thermostats gain share at the steepest rate.
Technology:
Protocol selection determines ecosystem lock-in economics, with cost tiers separating consumer-grade convenience from commercial-grade reliability specifications.
- Zigbee:Mesh networking standard with sub-GHz penetration for multi-wall Indian concrete construction. Builder-direct procurement in large-format Karnataka projects favors this protocol for whole-building coverage.
- Wi-Fi:Ubiquitous IP-native connectivity requiring no dedicated hubs. Retail channel dominance in aftermarket retrofit segments reflects consumer familiarity.
- Z-Wave:Proprietary sub-GHz mesh with regional frequency variants. Hospitality verticals specify this for guest-room isolation requirements.
- Bluetooth:Low-energy point-to-point for proximity-based control. Smartphone-centric automation in Tier-2 city first-time adopters.
Zigbee commands the installed base while Matter-over-Thread climbs fastest as Thread-native hardware penetrates new construction specifications.
End User:
Customer type segmentation separates volume-scale residential deployments from margin-accretive integrated platforms requiring white-label customization capabilities.
- Residential:Individual homeowner installations across metro and Tier-2 markets. RERA-mandated pre-wiring in new construction is compressing aftermarket upgrade economics.
- Hospitality:Integrated guest-experience platforms with property management system integration. Per-unit margins exceed residential benchmarks significantly.
- Commercial:Office and co-working automation with centralized building management. Demand concentrates in Hyderabad and Bengaluru tech corridors.
- Retail:Customer analytics and energy optimization for brick-and-mortar footprints. Maharashtra mall developments drive specification.
Residential captures absolute volume leadership while Hospitality expands most quickly on margin-optimized platform economics.
Distribution Channel:
Channel structure is bifurcating between project-scale logistics capabilities and consumer electronics retail reach, with margin compression favoring direct procurement relationships.
- Direct Sales:Builder and developer procurement offices specifying white-label automation for new construction. Gurugram and Mumbai premium projects anchor this channel.
- Distributors:Project-scale logistics with electrical contractor relationships. Tier-2 city penetration depends on this infrastructure.
- Online Retail:E-commerce platforms for consumer-directed retrofit purchases. Wi-Fi-native devices dominate this channel.
- Specialty Stores:Experience-led showrooms for ecosystem demonstration. Metro affluent consumer segments drive traffic.
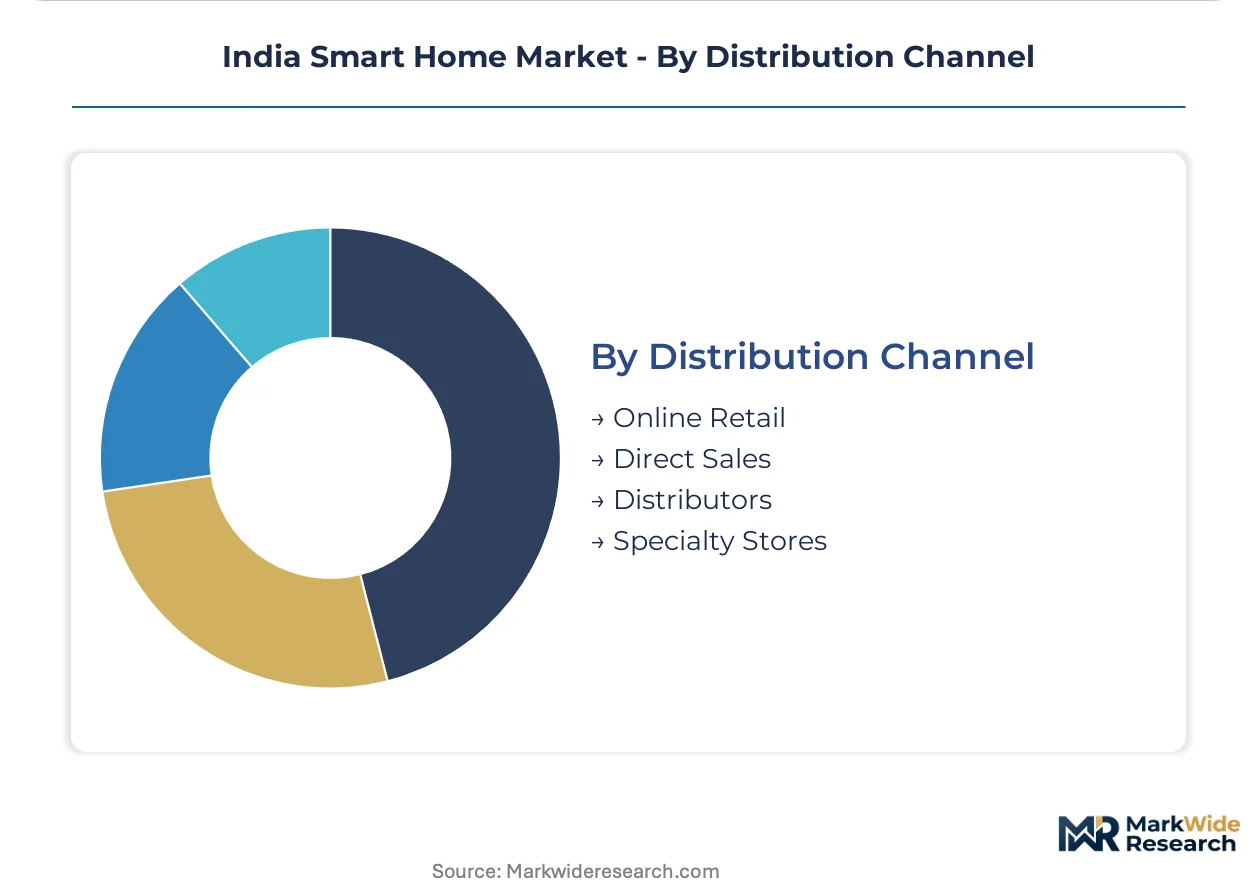
Direct Sales anchors new construction volume while Online Retail gains share fastest in retrofit segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's smart home market exhibits pronounced regional concentration, with import dependency for chipsets and semiconductor components creating supply chain vulnerabilities that domestic assembly operations seek to mitigate through localized testing and certification infrastructure.
Maharashtra
Mumbai's premium residential developments drive demand for integrated automation systems with centralized control hubs. BIS compulsory registration schemes for IoT devices filter substandard imports and elevate compliant domestic manufacturers. Pune's construction pipeline remains undersupplied with integrated automation relative to metro saturation, creating expansion corridors for project-scale logistics providers.
Karnataka
Bengaluru's tech corridor anchors commercial automation demand for office and co-working spaces with centralized building management specifications. The Smart Cities Mission channels municipal procurement toward interoperable standards that cascade into adjacent residential specifications. Large-format residential projects now source automation through developer procurement offices rather than consumer electronics distributors.
Telangana
Hyderabad's heat-wave intensity accelerates thermostat category expansion across residential stock, representing the fastest-growing product segment. CEA electrical safety codes mandate fire-rated wiring for automation retrofits, creating bundled upgrade pathways. Builder-direct specification concentrates volume with vendors capable of white-label customization for premium developments.
Haryana
Gurugram's premium-tier residential stock unwinds legacy siloed device installations through pre-installed automation infrastructure under RERA-mandated developments. TRAI data-localization consultations constrain foreign cloud-dependency and extend product launch cycles for platform providers. Direct sales channels anchor new construction volume while compressing vendor margins.
Gujarat
Ahmedabad's construction pipeline presents strategic opportunities for tier-2 city penetration with integrated automation systems. State-level RERA enforcement on pre-installed smart infrastructure determines whether automation becomes a bundled commodity or remains an aftermarket upgrade decision. Distributor networks with electrical contractor relationships enable project-scale logistics for underserved markets.
India Smart Home Market Competitive Landscape
Concentration sits with diversified electrical conglomerates and consumer electronics ecosystems rather than pure-play automation specialists. The vendor base spans three distinct tiers: multinational technology platforms with device ecosystems, industrial automation specialists adapting commercial-grade systems for residential migration, and domestic integrators with localized certification advantages. Competitive dynamics center on builder-direct procurement relationships and BIS compliance velocity rather than retail channel dominance. Strategic moves emphasize project-scale logistics capabilities and white-label customization for developer specifications.
Among multinational technology platforms, Samsung Electronics Co., Ltd. and Siemens AG exemplify divergent positioning archetypes—consumer ecosystem stickiness versus industrial protocol reliability adapted for Indian grid conditions. Schneider Electric SE occupies a position bridging commercial building management and large-format residential migration. Domestic specialists including Oakter Smart Home Technologies Pvt Ltd. and SmarDen leverage BIS certification timeline advantages against extended clearance cycles faced by imported brands. ABB Ltd., Legrand SA, and Honeywell International Inc. represent industrial-electrical conglomerates with pre-existing contractor relationships and surge-rated product portfolios. Crestron Electronics anchors the premium-integration tier where per-unit margins exceed residential benchmarks significantly.
| Leading Market Players |
|---|
| ABB Ltd. |
| Samsung Electronics Co., Ltd. |
| Schneider Electric SE |
| Oakter Smart Home Technologies Pvt Ltd. |
| SmarDen |
| Siemens AG |
| Legrand SA |
| Crestron Electronics |
| Honeywell International Inc. |
| Others |
Pricing and Supply Chain Analysis
Project-scale procurement volumes in Gurugram and Mumbai premium developments compress unit economics while elevating vendor qualification barriers. Scale concentration among large-format residential developers enables price anchoring through white-label specification, forcing smaller suppliers toward retail retrofit channels with thinner margin structures.
Pricing Analysis
Builder-direct procurement offices anchor pricing structures across the India smart home market. Three-tier pricing stratifies across premium Thread-native systems, standard Zigbee mesh installations, and economy Wi-Fi retrofit devices. Price differentiation hinges on BIS certification grade and project-scale volume commitments. Cost compression in the economy tier intensifies because import-dependent chipset sourcing exposes vendors to currency volatility. Tier-2 city first-time adopters exhibit highest price sensitivity, while hospitality verticals demonstrate lowest sensitivity due to per-unit margin premiums from integrated guest-experience platforms.
Supply Chain Analysis
Strategic stockpiling of surge-rated electrical components dominates inventory strategy over just-in-time preferences, given monsoon-season grid instability and extended BIS certification timelines. Semiconductor supply concentrates in Taiwan, South Korea, and China. Raw material dependencies include Zigbee/Z-Wave radio modules, fire-rated copper wiring, and edge-computing processors. Single-source vulnerability in East Asian chip fabrication creates exposure to shipping lane disruptions. Distribution runs through electrical contractor networks with project-scale logistics capabilities, particularly in Karnataka and Telangana construction corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Firmware engineering proficiency for 230V/50Hz electrical safety integration represents the critical capability gap constraining product development velocity across domestic and foreign vendors alike. This scarcity elevates the strategic value of embedded systems talent and BIS-certified testing infrastructure.
For Market Incumbents: Consolidate builder-direct procurement relationships in Haryana and Maharashtra before channel rotation completes. Acquire domestic testing laboratories to compress BIS clearance timelines against import competitors. Prioritize backward integration into surge-rated power supply manufacturing to mitigate monsoon-season warranty exposure. Lock in white-label customization capabilities for hospitality verticals where per-unit margins exceed residential benchmarks significantly.
For New Entrants and Emerging Players: Anchor in Pune and Ahmedabad construction pipelines where integrated automation remains undersupplied relative to metro saturation. Target Thread-native hardware specifications as Matter protocol adoption fragments legacy hub-centric models. Pursue distributor partnerships with electrical contractor networks rather than consumer electronics retail channels. Emphasize CEA fire-rated wiring bundling to capture retrofit safety upgrade pathways.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors domestic integrators with existing BIS certification infrastructure over foreign platform providers facing TRAI data-localization compliance delays. Long-term viability hinges on protocol convergence toward Matter-over-Thread and edge-computing architectures that reduce cloud dependency. Acquisition target archetype: mid-scale automation specialists with project-scale logistics capabilities and white-label customization expertise. Watch Matter protocol adoption rates in premium Gurugram developments as inflection indicator for ecosystem consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| BIS Certification Infrastructure Investment | Domestic testing laboratories compress clearance timelines against import competitors facing extended cycles. |
| Thread-Native Hardware Development | Matter protocol adoption fragments legacy hub-centric models and forces business model pivots toward hardware margins. |
| Builder-Direct Procurement Partnerships | RERA-mandated pre-installation in new construction concentrates volume away from retail retrofit channels. |
| Hospitality Vertical Platform Integration | Guest-experience systems command per-unit margins significantly above residential installation benchmarks. |
| Surge-Rated Power Supply Integration | Monsoon-season grid instability elevates total cost of ownership without adequate electrical protection layering. |
Research Methodology
Operator-level perspectives from automation system integrators, electrical contractor procurement leads, premium residential developer specification teams, and BIS certification laboratory directors anchored the qualitative base. Primary interview data combined with secondary validation from CEA electrical safety codes, TRAI consultation papers, Smart Cities Mission procurement documents, and RERA state-level enforcement records. Bottom-up project pipeline enumeration across Maharashtra, Karnataka, Telangana, Haryana, and Gujarat triangulated against top-down market sizing from equipment import manifests and BIS registration databases.
Sensitivity analysis around chipset import dependency ratios and heat-wave intensity projections informed the analytical framework across the analysis window. Segmentation dimensions modeled include product type, wireless protocol technology, end-user vertical, and distribution channel structure. CAGRs derived from installed base growth rates and replacement cycle assumptions. Industry-specific forecast inputs incorporated RERA-mandated pre-wiring penetration rates and municipal Smart Cities procurement specifications cascading into residential standards.
Material uncertainties — semiconductor supply disruptions, TRAI data-localization enforcement timing, and state-level RERA interpretation variance — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding protocol convergence timelines and builder-direct channel rotation completion. Revision becomes warranted when Matter protocol adoption in premium developments crosses threshold penetration rates that trigger ecosystem consolidation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Workbench Tanks Market
Others
Fluorite Market
Others
Asia-Pacific Intercom Devices Market
Others
Boston Round Bottle Market
Others
Aircraft Switches Market
Others
Advanced Fiber-Based Gasket Market
Others
Global Molded Plastics Market
Others
Tote Bags Market
Others
Bimodal Identity Management Solutions Market
Others
Global Healthcare/Medical Simulation Market
Others
Europe Smart Homes Market
Others
Commercial Aircraft Angle of Attack Sensors Market
Others
Heavy Duty Traps Market
Others
Smart Home and Office Market
Others
Video-As-A-Service (Vaas) Market
Others
Griffin Beaker Market