
 Liquid-Cooled Heat Sink Market | 2026-2036
Liquid-Cooled Heat Sink Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid-Cooled Heat Sink Market Insights
REACH compliance is consolidating the cost-of-entry calculus for European suppliers of liquid-cooled heat sinks, forcing reformulation of thermal interface materials and coolant chemistries. Boyd Corporation leverages its captive supply of copper and aluminum cold plate substrates to sustain margin control across aerospace and defense contracts. Asetek Inc. anchors its position in direct-to-chip cooling for server farms, while CoolIT Systems competes through modular rack-level architectures that reduce installation complexity in retrofit data centers.
A liquid-cooled heat sink is a thermal management device that dissipates heat from electronic components through circulating liquid coolants—typically deionized water, glycol mixtures, or dielectric fluids—flowing across micro-channel fins or embedded cold plates with hydraulic diameters below 1 mm, maintaining junction temperatures within operational limits for high-power semiconductors. Its primary industrial purpose is enabling power densities above 500 W per chip in applications where air cooling reaches physical limits. Passive heat sinks dominate unit volumes in telecommunications base stations where reliability requirements favor zero-moving-part designs, while custom heat sinks capture the highest margin pools in aerospace industries where mission-specific geometries command engineering premiums. Cold plate technology leads technology adoption in automotive manufacturer battery packs, whereas vapor chamber cooling extends into consumer electronics where z-height constraints dictate planar heat spreading.
The EPA regulates coolant discharge under Clean Water Act provisions affecting domestic manufacturing facilities, while the EU F-Gas Regulation restricts fluorinated greenhouse gases in cooling circuits, redirecting R&D toward water-glycol formulations. ISO 9001 and IEC 62368-1 certification requirements shape product qualification timelines for telecom providers sourcing thermal hardware. Stakeholders must monitor evolving efficiency thresholds in national building codes and decide whether to certify products regionally or pursue unified global platforms.
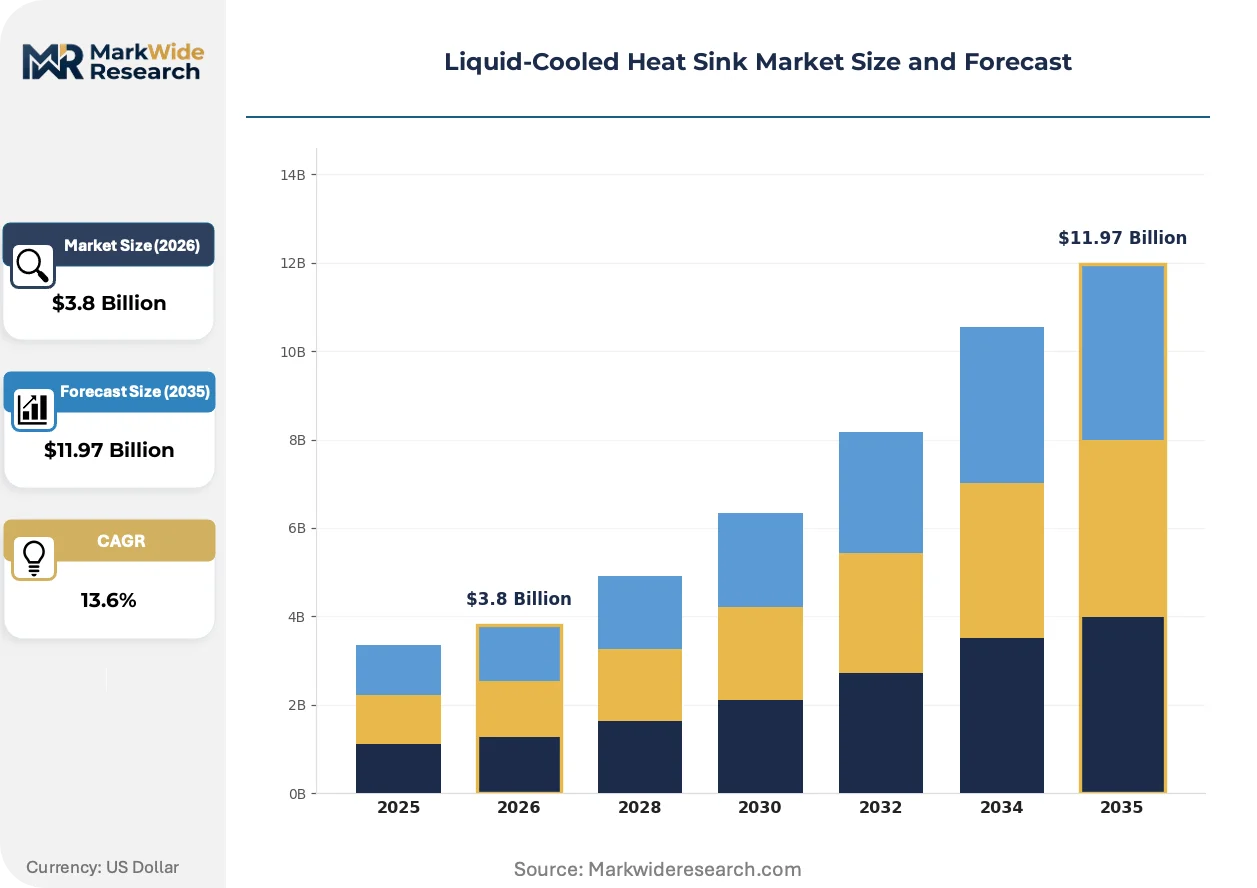
Market Dynamics
The EU F-Gas Regulation is compressing refrigerant-based cooling timelines and forcing data center operators toward water-glycol architectures, redrawing competitive advantage around thermal fluid chemistry expertise and cold plate manufacturing scale.
Growth Catalysts
- AI Training Cluster Deployment:Hyperscale facilities in Germany are procuring direct-to-chip liquid cooling systems to manage thermal loads exceeding 500 W per chip in GPU-intensive workloads.
- REACH Compliance Consolidation:ECHA mandates on thermal interface materials are raising formulation barriers, advantaging suppliers with captive chemistry capabilities and certified supply chains.
- Automotive Battery Thermal Management:Cold plate assemblies for electric vehicle battery packs are displacing air-cooled architectures as manufacturers target 10-minute fast-charge cycles.
Market Restraints
- Copper and Aluminum Price Volatility:Cold plate substrate costs fluctuate with London Metal Exchange pricing, compressing margins for non-integrated fabricators.
- Deionized Water Supply Concentration:Semiconductor-grade water treatment capacity concentrates in Taiwan and South Korea, creating geographic chokepoints for high-purity coolant sourcing.
- F-Gas Phase-Out Technical Friction:Existing refrigerant-based infrastructure in legacy data centers faces stranded asset risk during retrofit timelines mandated by EU regulation.
Strategic Opportunities
- Underpenetrated Industrial Edge Computing:Manufacturing automation in Poland and Czech Republic lacks liquid cooling deployment despite rising PLC power densities.
- CSRD-Driven Efficiency Mandates:Corporate sustainability reporting requirements are creating procurement preference for cooling systems with verified power usage effectiveness metrics.
- Micro-Channel Cold Plate Convergence:Additive manufacturing of titanium heat exchangers is integrating with conventional brazed aluminum assemblies for aerospace applications.
Industry Challenges
- Two-Phase Cooling Certification Delays:IEC 62368-1 safety testing for dielectric fluid systems extends qualification timelines by 8-14 months versus single-phase water-glycol alternatives.
- Legacy Air-Cooled Infrastructure Lock-In:Retrofit data centers face structural constraints on plumbing routing and floor loading that complicate rack-level liquid cooling adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid-Cooled Heat Sink Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $11.97 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passive Heat Sinks, Active Heat Sinks, Custom Heat Sinks, Modular Heat Sinks Application: Consumer Electronics, Data Centers, Telecommunications, Industrial Equipment Technology: Direct Liquid Cooling, Cold Plate Technology, Heat Pipe Systems, Vapor Chamber Cooling End User: Telecom Providers, Automotive Manufacturers, Server Farms, Aerospace Industries |
| Companies Covered | Schneider Electric, Vertiv Group Corp., Alfa Laval Corporate AB, LiquidStack Inc., Asetek Inc., Boyd Corporation, CoolIT Systems, Modine Manufacturing Company, DCX Liquid Cooling Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid-Cooled Heat Sink Market Trends and Innovations
Thermal management architectures are bifurcating between extreme-performance direct-to-chip designs for AI infrastructure and modular rack-level systems for retrofit deployment, with material science and regulatory chemistry emerging as decisive competitive variables.
Micro-channel cold plates with hydraulic diameters below 0.5 mm are integrating into high-performance computing nodes, enabling uniform junction temperature distribution across multi-die GPU packages. Hyperscale operators in Germany and the Netherlands are specifying these designs for training clusters exceeding 100 kW per rack. The technology is integrating thermal and hydraulic optimization into a single substrate, compressing supplier qualification lists to those with precision machining or additive manufacturing capabilities.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are accelerating reformulation of dielectric coolants toward fluorinated ketone alternatives with lower global warming potential. Industrial consequence includes extended material compatibility testing for seals and gaskets in existing cold plate assemblies. Server OEMs sourcing from European suppliers are most affected, responding with dual-track qualification programs for water-glycol and next-generation dielectric fluids.
Specification authority is migrating from facility engineering teams to sustainability officers accountable to CSRD disclosure requirements. Channel disruption follows as direct procurement from thermal subsystem specialists displaces traditional HVAC integrator relationships. This pattern is most visible in Nordic data center developments where power purchase agreement structures and cooling efficiency metrics determine vendor selection.
Liquid-Cooled Heat Sink Market Segmentation
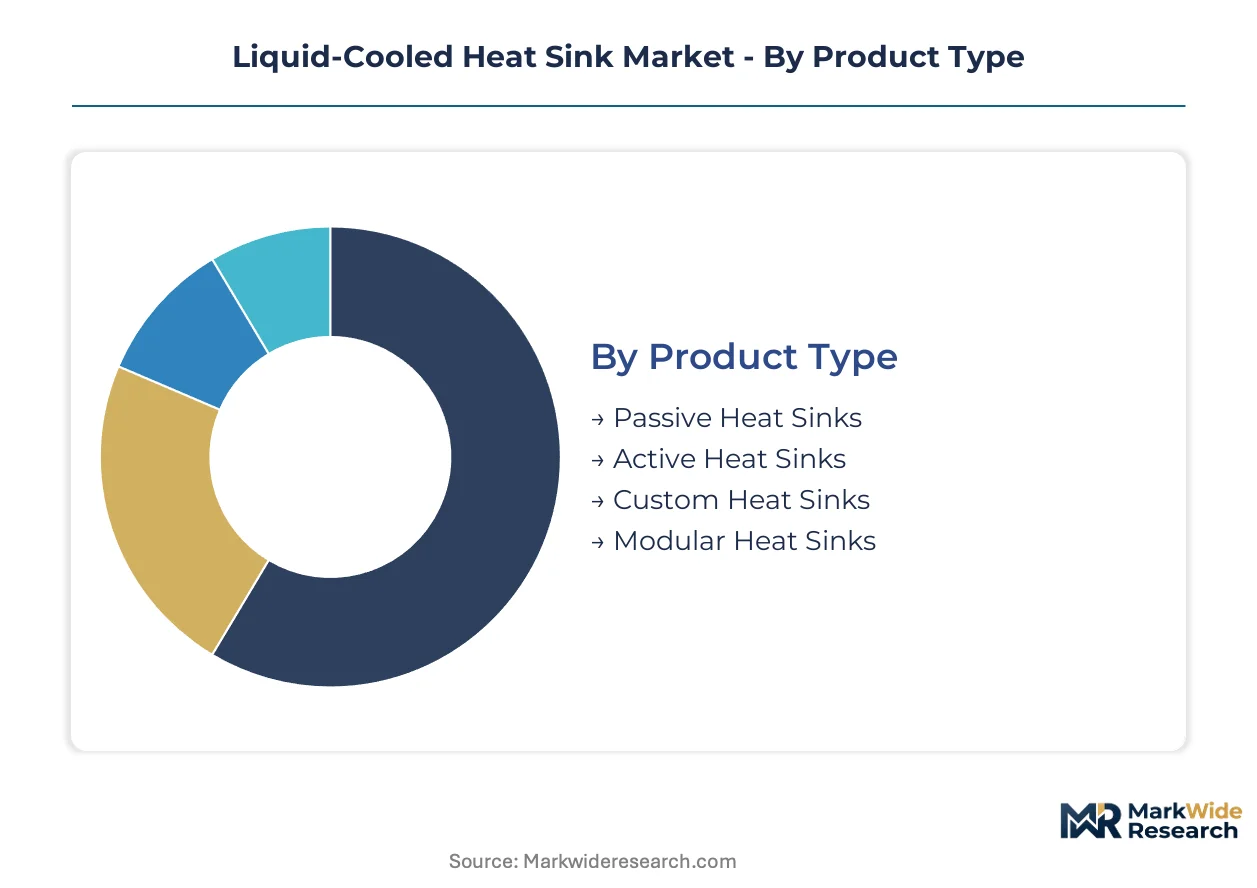
Product heterogeneity in liquid-cooled heat sinks reflects divergent thermal loads across end-use environments. Upgrade cycles vary dramatically—from 18-month refresh rates in AI training clusters to decade-long service intervals in aerospace platforms—making segment-specific positioning essential for supplier resource allocation.
Product Type:
Replacement timelines differentiate procurement patterns across product architectures, with passive designs offering extended service life versus active systems requiring periodic pump and sensor maintenance.
- Passive Heat Sinks:Aluminum or copper fin arrays conduct heat to liquid-cooled bases without moving components, achieving mean-time-between-failures exceeding 100,000 hours. Telecom base stations in Germany favor these designs for remote installations where technician access is constrained by maintenance budgets.
- Active Heat Sinks:Integrated pumps and flow controllers enable adjustable thermal response for variable workloads. Data center operators in the Netherlands specify active systems for GPU clusters where power dissipation fluctuates with training job scheduling.
- Custom Heat Sinks:Mission-specific geometries for satellite and defense applications command engineering premiums due to non-recurring design costs.
- Modular Heat Sinks:Standardized cold plate assemblies with swappable manifold configurations reduce spare parts inventory for industrial maintenance teams.
Passive Heat Sinks sits at the top of the volume ranking, with Modular Heat Sinks climbing the fastest.
Application:
Cost tier stratification separates premium thermal hardware for hyperscale facilities from economy-grade solutions for consumer devices.
- Data Centers:Rack-scale liquid cooling loops handling 100 kW per cabinet require redundant pump arrays and leak detection systems. Facilities in Frankfurt am Main are retrofitting air-cooled halls with direct-to-chip cold plates to accommodate NVIDIA H100 deployments.
- Consumer Electronics:Vapor chamber assemblies with sub-millimeter z-heights spread heat across laptop chassis. Gaming laptop manufacturers in Taiwan integrate these with centrifugal blowers for 250 W thermal envelopes.
- Telecommunications:Outdoor base station radios specify corrosion-resistant cold plates for ambient temperatures ranging from -40°C to +55°C.
- Industrial Equipment:Programmable logic controllers in Polish automotive plants adopt liquid cooling as I/O density increases beyond air-cooled limits.
Data Centers command the highest average selling prices, while Industrial Equipment offers the steepest expansion trajectory among application categories.
Technology:
Customer sophistication determines technology selection, with direct liquid cooling reserved for operators possessing in-house thermal engineering capabilities.
- Cold Plate Technology:Micro-channel designs with hydraulic diameters below 0.5 mm achieve uniform temperature distribution across multi-die packages. Battery pack manufacturers in Stuttgart specify aluminum brazed cold plates for 10-minute fast-charge thermal management.
- Direct Liquid Cooling:Dielectric fluid immersion or cold plate contact with bare silicon eliminates thermal interface material resistance. Hyperscale operators in Amsterdam deploy this for training clusters exceeding 500 W per GPU.
- Vapor Chamber Cooling:Two-phase heat spreaders transport heat laterally before liquid cooling extraction, enabling thin-form-factor designs.
- Heat Pipe Systems:Wick-structured tubes provide passive heat transport for moderate thermal loads where pumping power is unacceptable.
Cold Plate Technology dominates installed base, with Direct Liquid Cooling gaining share fastest among new deployments.
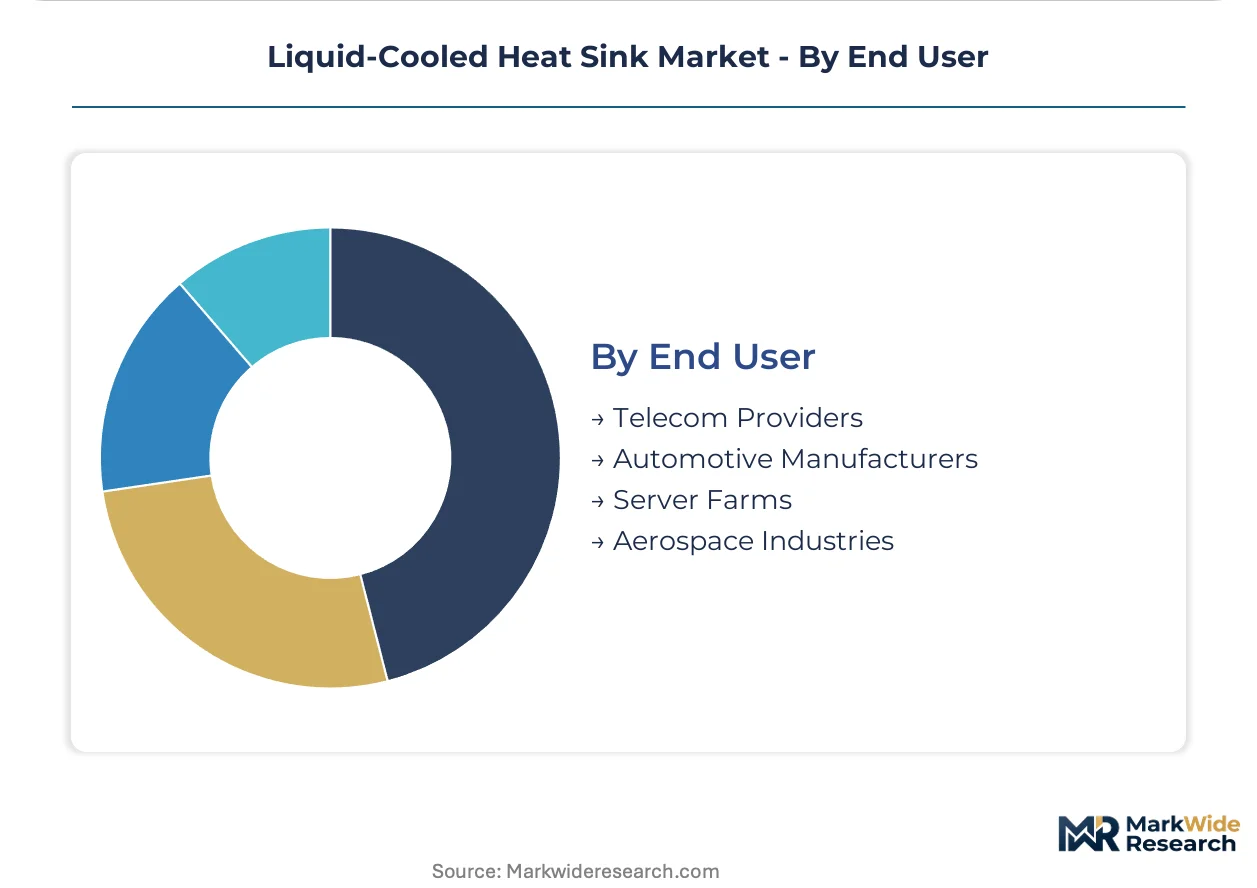
End User:
Supply concentration shapes vendor relationships, with automotive and aerospace buyers consolidating procurement around qualified subsystem suppliers.
- Automotive Manufacturers:Electric vehicle battery packs and inverter modules specify cold plates validated to automotive reliability standards. BMW and Volkswagen thermal teams in Munich and Wolfsburg co-develop designs with tier-one suppliers.
- Aerospace Industries:Satellite and avionics applications demand materials traceability and radiation-hardened qualification. European Space Agency programs drive titanium heat exchanger development for geostationary platforms.
- Telecom Providers:Deutsche Telekom and Vodafone specify passive liquid-cooled heat sinks for 5G macro cell upgrades.
- Server Farms:Colocation operators prioritize standardized rack-level cooling modules to minimize tenant customization costs.
Automotive Manufacturers represent the largest addressable market by value, with Aerospace Industries expanding most quickly due to satellite constellation deployment timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision thermal engineers cluster in southern Germany and Taiwan's Hsinchu corridor, anchoring design authority for high-performance cold plate architectures. These talent concentrations attract hyperscale procurement teams seeking direct supplier collaboration on AI infrastructure thermal loads.
Germany
Automotive battery pack manufacturers in Stuttgart and Munich drive cold plate demand for 10-minute fast-charge cycles. The EU F-Gas Regulation accelerates refrigerant phase-out in Bavarian data centers. Frankfurt am Main hyperscale facilities retrofit air-cooled halls with direct-to-chip liquid cooling for NVIDIA deployments.
United States
Cloud operators in Northern Virginia and Dallas-Fort Worth procure rack-scale cooling loops exceeding 100 kW per cabinet. EPA Clean Water Act provisions regulate coolant discharge from domestic manufacturing facilities. Phoenix-area semiconductor fabs expand deionized water treatment capacity for high-purity coolant sourcing.
Taiwan
Semiconductor-grade water treatment infrastructure concentrates in Hsinchu and Tainan Science Parks, creating geographic chokepoints for coolant supply. The country's environmental regulator enforces industrial wastewater standards affecting fab thermal management systems. Taipei-based server OEMs integrate vapor chamber assemblies with liquid cooling for gaming laptop thermal envelopes.
Netherlands
Amsterdam data center operators specify direct liquid cooling for GPU training clusters exceeding 500 W per processor. CSRD disclosure requirements drive procurement preference for verified power usage effectiveness metrics. Eindhoven's high-tech campus hosts thermal subsystem specialists serving European hyperscale accounts.
China
MIIT efficiency mandates push cloud operators in Beijing and Shanghai toward liquid cooling for AI training infrastructure. The country's dual carbon goals redirect data center construction toward water-glycol architectures. Shenzhen electronics manufacturers integrate micro-channel cold plates into high-performance computing nodes for domestic hyperscale deployment.
Liquid-Cooled Heat Sink Market Competitive Landscape
The competitive structure tilts toward integrated thermal subsystem specialists with captive materials processing capabilities. Market concentration remains moderate, with tier-one suppliers commanding premium positions in aerospace and automotive qualification programs while mid-scale fabricators compete on retrofit data center deployment speed. Two dominant archetypes emerge: precision machining houses with additive manufacturing integration, and chemistry-forward suppliers controlling thermal interface material formulations. Competitive moves center on backward integration into copper and aluminum substrate supply, plus strategic partnerships with server OEMs for co-developed direct-to-chip architectures.
Among diversified industrial technology groups, Schneider Electric and Vertiv Group Corp. exemplify scale-driven platform players spanning facility infrastructure to rack-level thermal hardware. Alfa Laval Corporate AB represents the precision heat exchanger specialist archetype with deep process industry heritage. Asetek Inc. and CoolIT Systems occupy positions within the direct-to-chip cooling segment, with Boyd Corporation anchoring the materials-integrated fabricator tier through captive supply chain control.
| Leading Market Players |
|---|
| Schneider Electric |
| Vertiv Group Corp. |
| Alfa Laval Corporate AB |
| LiquidStack Inc. |
| Asetek Inc. |
| Boyd Corporation |
| CoolIT Systems |
| Modine Manufacturing Company |
| DCX Liquid Cooling Systems |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap fabricators in southern Germany anchor cold plate manufacturing, translating captive machining expertise into pricing discipline that resists commodity erosion even as copper and aluminum volatility squeezes non-integrated competitors.
Pricing Analysis
Bundled engineering services separate premium cold plate suppliers from commodity catalog vendors. Three-tier pricing structure across mission-critical aerospace, qualified automotive, and economy retrofit data center levels reflects certification investment and traceability documentation. Cost compression in standard-grade aluminum brazed assemblies is intensifying because Taiwanese substrate producers are expanding capacity. Hyperscale operators exhibit lowest price sensitivity, prioritizing thermal performance guarantees and installation speed over per-unit procurement savings.
Supply Chain Analysis
Reverse-logistics flows for refurbishment and remanufacturing concentrate in Germany and Taiwan, where precision cleaning and re-brazing services extend cold plate service life for aerospace and semiconductor equipment. Raw material sourcing draws from Chilean copper concentrate and Chinese aluminum smelters, with hydraulic manifold machining anchored in Hsinchu and Stuttgart industrial clusters. Single-source vulnerability in semiconductor-grade deionized water treatment creates geographic chokepoints for high-purity coolant supply. Distribution runs through direct OEM partnerships for automotive and aerospace qualification programs, bypassing traditional HVAC integrator channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with procurement authority migrating toward sustainability officers who demand verified power usage effectiveness metrics and CSRD-aligned thermal subsystem documentation.
For Market Incumbents: Anticipate margin compression from emerging additive manufacturing specialists in aerospace titanium heat exchangers by deepening backward integration into copper substrate supply and accelerating dual-track qualification for water-glycol and next-generation dielectric fluids. Channel control through direct server OEM partnerships offers defensive positioning against modular rack-level competitors. For New Entrants and Emerging Players: EU F-Gas Regulation in Europe opens a window for chemistry-forward suppliers with REACH-compliant thermal interface material formulations to capture retrofit data center demand in Poland and Czech Republic industrial automation. Target underpenetrated PLC cooling in Eastern European manufacturing plants through standardized modular manifold configurations with reduced installation complexity. For Investors and Strategic Acquirers: Valuations sit cheapest among precision machining houses lacking captive materials processing, where acquisition premiums concentrate around additive manufacturing capabilities and certified aerospace qualification programs. Five-to-ten year viability hinges on thermal fluid chemistry expertise migration. Monitor CSRD disclosure adoption rates among European hyperscale operators as inflection indicator for procurement authority shifts toward sustainability-verified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Substrate Supply | Boyd Corporation's captive mining relationships insulate aerospace margins from London Metal Exchange volatility. |
| Dual-Track Coolant Qualification Program | REACH Annex XVII compliance accelerates reformulation timelines for dielectric fluid alternatives with lower global warming potential. |
| Modular Rack-Level Architecture Deployment | CoolIT Systems reduces installation complexity for legacy data center retrofits constrained by structural floor loading limits. |
| Additive Manufacturing Capability Acquisition | Titanium micro-channel heat exchangers integrate with conventional brazed assemblies for European Space Agency satellite programs. |
| Direct Server OEM Partnership Structure | Asetek Inc. anchors position in NVIDIA H100 training clusters through co-developed direct-to-chip thermal architectures. |
Research Methodology
Bottom-up data center and automotive battery pack modeling reconciled against top-down cold plate manufacturing capacity tracking forms the analytical core. Primary interviews with thermal engineering directors at hyperscale operators, procurement leads at German automotive OEMs, and facility managers at Dutch colocation providers combined with secondary validation from EPA Clean Water Act discharge filings, EU F-Gas Regulation implementation reports, and SEC 10-K disclosures from diversified industrial technology groups. Triangulation across supply-side capacity announcements and demand-side deployment schedules calibrated volume estimates.
Historical trendline analysis of replacement cycle compression in AI training infrastructure versus extended aerospace service intervals established segment-specific growth trajectories across the projection horizon. Segmentation modeling incorporated product architecture, application tier, cooling technology sophistication, and end-user supply concentration dimensions. CAGRs derived from weighted average of technology adoption curves and regulatory mandate timelines, with specific inputs including NVIDIA GPU deployment schedules and EU battery fast-charge thermal management specifications.
Forecast precision tightens around the base case; tail outcomes carry wider variance under MIIT efficiency mandate acceleration in China and potential REACH restriction expansion to additional per- and polyfluoroalkyl substance categories. Practitioners should monitor deionized water treatment capacity expansion announcements in Taiwan and South Korea for early signals of coolant supply constraint resolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Commercial Aircraft Angle of Attack Sensors Market
Others
AI in Precision Medicine Market
Others
Powder Coating Equipment Market
Others
Quadrant Scale Market
Others
Metal Ore Mining Market
Others
Rugged Tablet Market
Others
Chip Card Scanners Market
Others
Idaas Market
Others
Sound Reinforcement Market
Others
Global Food Fiber Market
Others
Subtilisin Market
Others
Global Duty-Free Retailing Market
Others
Latin America Fire Sprinklers Market
Others
France 3D Printing Construction Market
Others
Smart Home Technologies Market
Others
Roasted Wheat Market