
 AI in Precision Medicine Market | 2026-2036
AI in Precision Medicine Market Size, Share, and Industry Trends Forecast 2026-2036
AI in Precision Medicine Market Insights
ISO 13485 certification for medical device quality management is rotating as the primary gating mechanism for market entry, filtering out software vendors lacking clinical-grade validation infrastructure. NVIDIA Corporation leverages its GPU computing architecture to dominate training workloads for deep learning models in genomics. Tempus anchors its position through vertical integration into molecular profiling and clinical data networks. IBM competes via specialized quantum-AI hybrid research targeting protein folding prediction.
AI in precision medicine denotes the application of computational algorithms to individual patient data—spanning genomic sequences, proteomic profiles, and real-world clinical records—to generate predictive therapeutic recommendations with quantified confidence intervals. The primary commercial purpose centers on reducing trial-and-error prescribing by matching molecular signatures to targeted interventions. Machine Learning and Deep Learning capture the dominant investment share as pharma companies prioritize pattern recognition across multi-omics datasets. Predictive Analytics and Decision Support Systems concentrate margin pools where recurring SaaS contracts attach to electronic health record workflows. Oncology leads application deployment due to established biomarker infrastructure and payer willingness to reimburse algorithm-informed treatment selection.
FDA premarket review under the Software as a Medical Device framework shapes product development timelines and evidence requirements for commercial algorithm deployment. The EMA's AI Act alignment and GDPR health data provisions constrain cross-border model training across European research consortia. Stakeholders must monitor evolving evidentiary standards for real-world performance validation as regulators distinguish between decision-support tools and autonomous diagnostic systems.
Market Dynamics
ISO 13485 certification requirements are filtering software vendors from clinical-grade markets, while FDA's Breakthrough Device Designation accelerates algorithm commercialization timelines for qualifying diagnostics.
Growth Catalysts
- Breakthrough Device Designation:FDA's expedited pathway compresses premarket review timelines for algorithm-based diagnostics, enabling faster revenue realization for qualifying biomarker platforms.
- Multi-omics data proliferation:Academic medical centers are generating petabyte-scale genomic and proteomic datasets that require machine learning infrastructure for therapeutic matching.
- Oncology biomarker infrastructure:Established payer reimbursement pathways for molecular profiling in cancer care create immediate addressable markets for AI-informed treatment selection tools.
Market Restraints
- GPU compute cost concentration:Training workloads for deep learning models depend on NVIDIA's proprietary architecture, creating input cost vulnerability for development-stage vendors.
- GDP R health data fragmentation:European research consortia face structural barriers to cross-border model training under EMA's AI Act alignment and data localization requirements.
- Clinical validation timelines:Real-world performance evidence collection for SaMD premarket submissions extends development cycles beyond typical software release cadences.
Strategic Opportunities
- Quantum-AI hybrid convergence:Protein folding prediction applications present white space for specialized computational architectures that combine quantum processing with classical machine learning.
- Electronic health record integration:Recurring SaaS contracts attaching to EHR workflows concentrate margin pools in decision support systems beyond standalone diagnostic tools.
- Real-world evidence mandates:Evidentiary standards for post-market surveillance create service revenue streams in algorithm performance monitoring and model revalidation.
Industry Challenges
- Computational biology talent scarcity:The intersection of genomics expertise and machine learning engineering remains under-supplied relative to platform development roadmaps.
- SaMD classification ambiguity:FDA's evolving distinction between decision-support tools and autonomous diagnostic systems creates compliance timeline uncertainty for product portfolios.
- Legacy health IT integration:Algorithm deployment requires interoperability with fragmented hospital information systems that lack standardized API architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI in Precision Medicine Market |
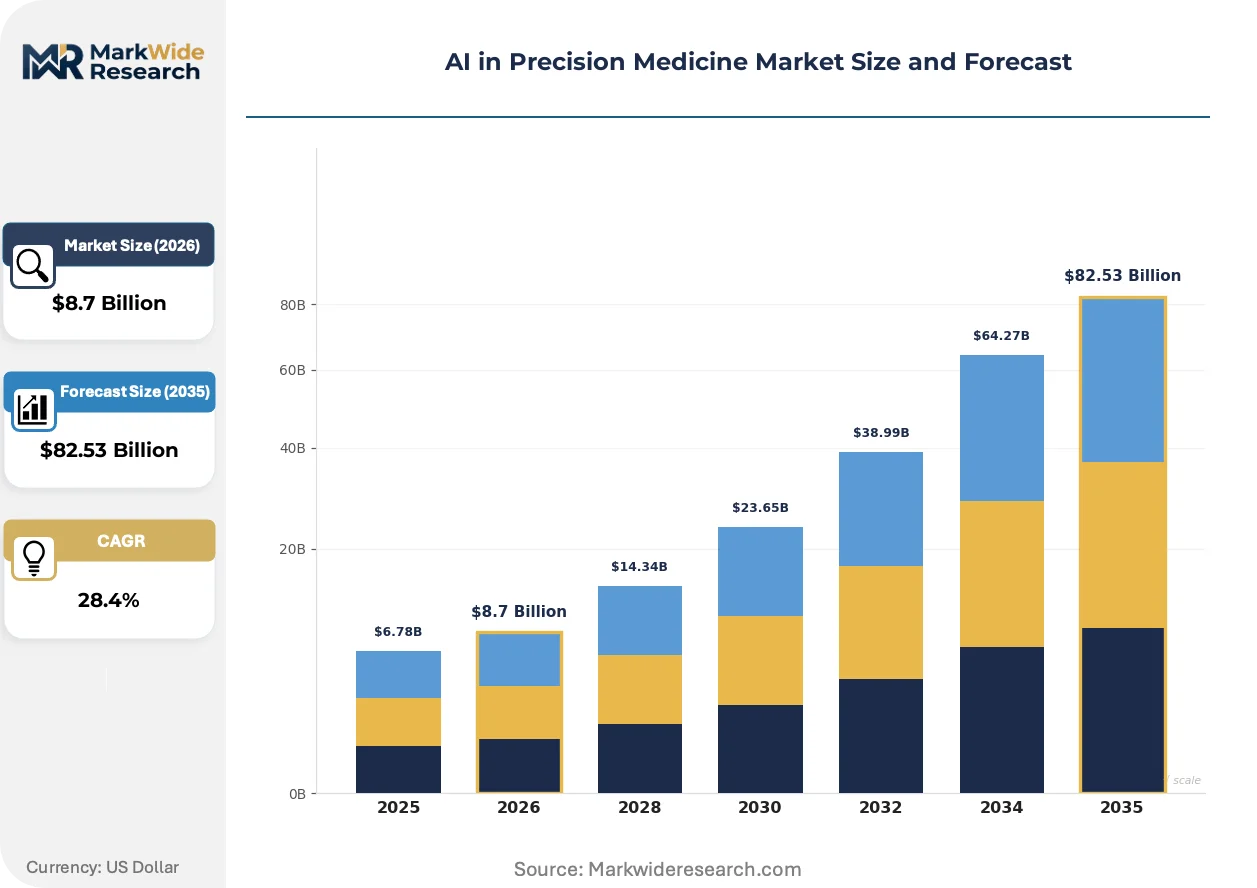
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $82.53 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Deep Learning, Natural Language Processing, Computer Vision Product Type: Genomic Sequencing, Predictive Analytics, Imaging Solutions, Decision Support Systems End User: Healthcare Providers, Research Institutions, Pharma Companies, Diagnostic Labs Application: Oncology, Cardiology, Neurology, Rare Diseases |
| Companies Covered | NVIDIA Corporation, Google Inc., Microsoft, IBM, Tempus, GE HealthCare, Illumina Inc., Exscientia, Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI in Precision Medicine Market Trends and Innovations
Edge computing architectures are migrating inference workloads from centralized cloud infrastructure toward point-of-care deployment, altering hardware procurement patterns across diagnostic networks.
Federated learning frameworks are miniaturizing model training by distributing computation across institutional data silos without centralizing protected health information. Academic medical centers in the Boston-Cambridge corridor are piloting these architectures to preserve patient privacy while pooling multi-site genomic cohorts. This approach is compressing the regulatory surface area for cross-institutional collaboration by eliminating data transfer requirements under HIPAA.
EMA's alignment with the EU AI Act is reclassifying clinical decision-support algorithms as high-risk AI systems, triggering conformity assessment obligations that parallel medical device regulations. Pharmaceutical companies with European development pipelines are restructuring algorithm governance frameworks to accommodate dual oversight from notified bodies and national competent authorities. Oncology applications face the steepest compliance burden due to their direct impact on therapeutic selection.
Hospital procurement committees are unbundling algorithm licensing from hardware commitments, separating software subscriptions from GPU infrastructure contracts that previously bundled training and inference capacity. Academic medical centers are driving this shift by insourcing compute resources through research cloud allocations. This pattern is most visible in the San Francisco Bay Area, where health systems maintain direct relationships with hyperscale providers for research workloads.
AI in Precision Medicine Market Segmentation
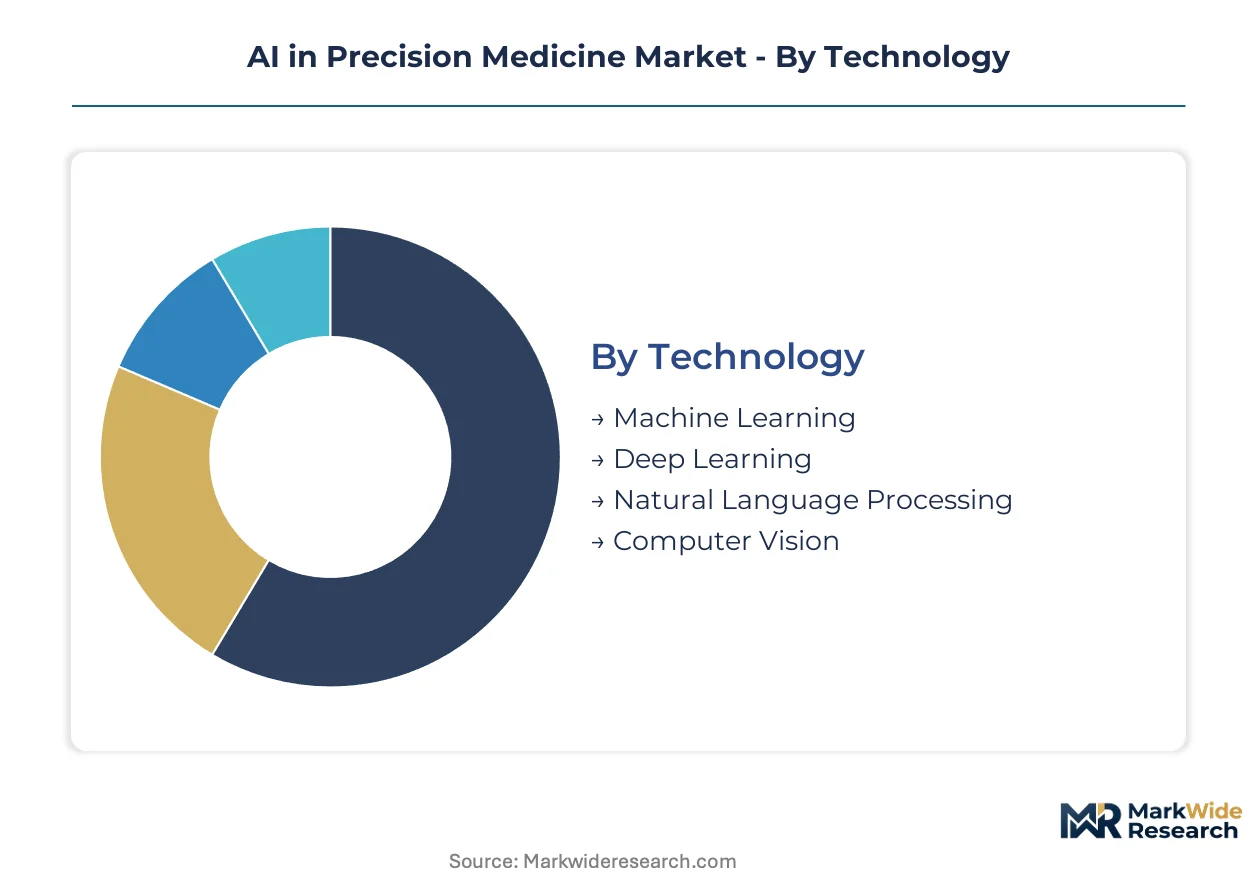
Segmentation in AI precision medicine reveals how computational capabilities, clinical workflows, and regulatory pathways intersect to create distinct commercial zones. Each dimension—technology, product architecture, user type, and therapeutic area—carries unique evidence requirements and reimbursement logic that shape vendor strategy.
Technology:
Deep Learning and Machine Learning concentrate development investment in the United States, while Natural Language Processing and Computer Vision applications show stronger traction in European academic consortia under GDPR-constrained deployment models.
- Deep Learning:Multi-layer neural architectures process petabyte-scale genomic and proteomic datasets for therapeutic matching. Demand concentrates in oncology departments at academic medical centers, driven by FDA Breakthrough Device Designation pathways that accelerate commercial timelines for qualifying biomarker platforms.
- Machine Learning:Supervised and unsupervised algorithms identify patterns across structured clinical and molecular data. Deployment is expanding fastest in the Boston-Cambridge biotech corridor, where hospital systems prioritize pattern recognition tools that integrate with existing electronic health record workflows.
- Natural Language Processing:Text mining extracts phenotypic and therapeutic response signals from unstructured clinical notes. European research networks deploy these tools under federated learning frameworks to preserve patient privacy across institutional boundaries.
- Computer Vision:Image analysis algorithms quantify histopathological and radiological biomarkers. Diagnostic labs in the San Francisco Bay Area pilot these systems for point-of-care deployment via edge computing architectures.
Machine Learning holds the largest share; momentum sits with Deep Learning.
Product Type:
Product architecture determines margin structure—standalone diagnostic tools compete on accuracy metrics while integrated decision support systems capture recurring SaaS revenue through EHR embedding.
- Decision Support Systems:Clinical workflow-embedded algorithms generate predictive therapeutic recommendations with quantified confidence intervals. These tools concentrate margin pools in the United States through recurring contracts attaching to hospital information systems, particularly in oncology biomarker infrastructure where payer reimbursement pathways are established.
- Genomic Sequencing:AI-augmented molecular profiling platforms match patient signatures to targeted interventions. Academic medical centers drive demand in the Boston-Cambridge corridor, where vertical integration into clinical data networks reduces trial-and-error prescribing.
- Predictive Analytics:Forecasting models project treatment response and disease progression trajectories. Pharma companies deploy these tools for clinical trial patient stratification, with development concentrated in the San Francisco Bay Area research cloud ecosystem.
- Imaging Solutions:Algorithm-based radiological and pathological quantification systems. Diagnostic labs prioritize these products where ISO 13485 certification requirements filter vendors lacking clinical-grade validation infrastructure.
Decision Support Systems dominate revenue concentration; Predictive Analytics is climbing the fastest as pharma pipelines expand.
End User:
User type dictates procurement authority and evidence standards—healthcare providers demand real-world performance validation while research institutions prioritize training data access.
- Healthcare Providers:Hospital systems and physician networks deploy AI tools for point-of-care therapeutic selection. Demand concentrates in United States oncology departments, where FDA Software as a Medical Device frameworks shape product development timelines and evidence requirements.
- Pharma Companies:Drug developers apply AI across discovery, clinical trial design, and post-market surveillance. Multi-omics data proliferation in the Boston-Cambridge corridor drives machine learning infrastructure investment for therapeutic matching.
- Research Institutions:Academic medical centers generate training datasets and validate algorithm performance. Federated learning frameworks enable these users to pool multi-site genomic cohorts without centralizing protected health information under HIPAA.
- Diagnostic Labs:Specialized testing facilities integrate AI for molecular profiling and image analysis. GPU compute cost concentration creates input cost vulnerability for these users dependent on NVIDIA's proprietary architecture for training workloads.
Healthcare Providers hold the largest share; momentum sits with Pharma Companies.
Application:
Therapeutic area maturity determines reimbursement readiness—oncology benefits from established biomarker infrastructure while rare diseases face evidence collection challenges.
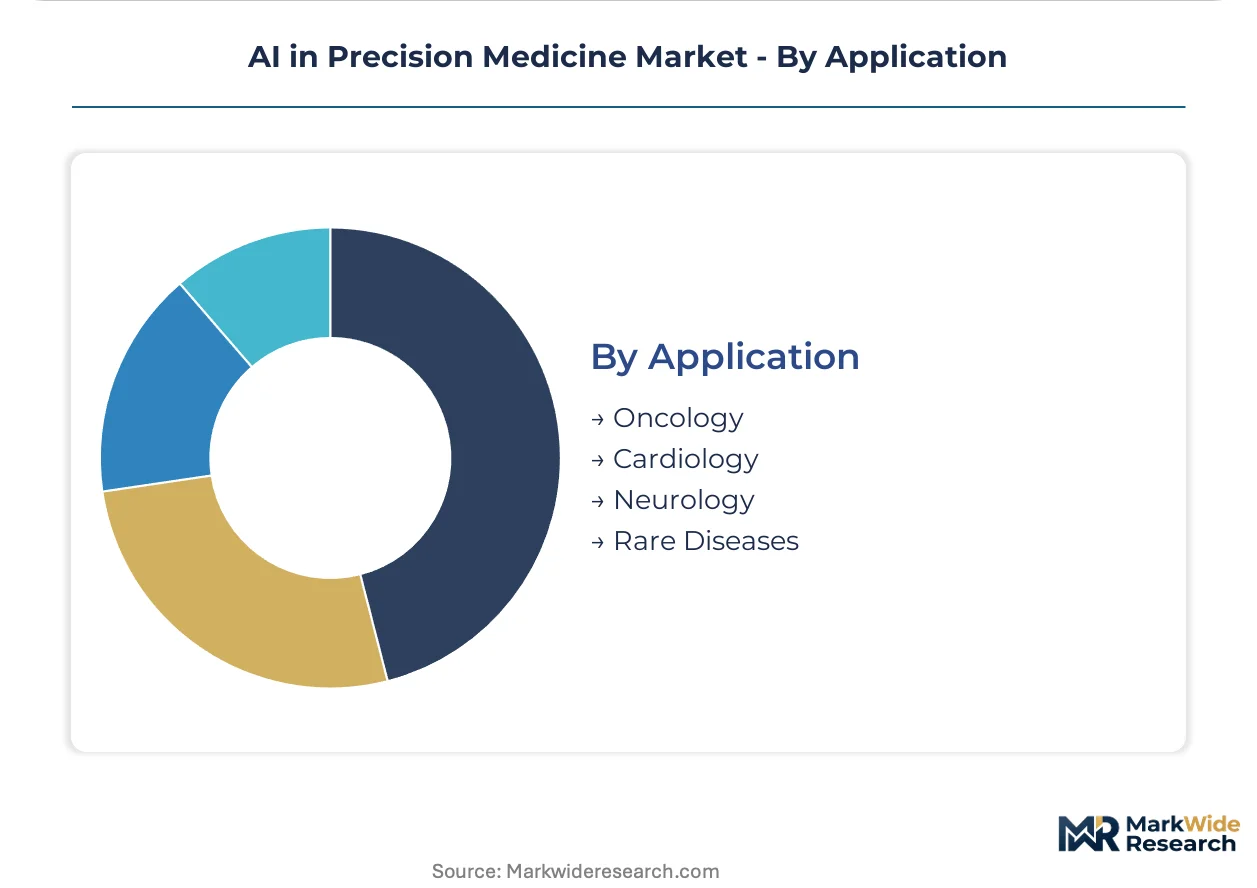
- Oncology:Cancer care applications leverage established molecular profiling infrastructure and payer willingness to reimburse algorithm-informed treatment selection. Academic medical centers in the United States expand adoption of AI-driven biomarker platforms, with FDA Breakthrough Device Designation accelerating commercial timelines.
- Cardiology:Cardiovascular applications focus on imaging-based risk stratification and therapeutic response prediction. Deployment lags oncology due to less mature biomarker validation frameworks and fragmented EHR integration requirements.
- Neurology:Neurodegenerative and psychiatric applications face structural barriers from heterogeneous disease phenotypes and limited molecular targets. European research consortia pilot these tools under EMA AI Act alignment requirements that reclassify clinical decision-support algorithms as high-risk systems.
- Rare Diseases:Ultra-orphan indications leverage AI to identify therapeutic matches across sparse patient populations. Real-world evidence mandates for post-market surveillance create service revenue streams in algorithm performance monitoring for these high-complexity cases.
Oncology holds the largest share; Rare Diseases shows the steepest expansion trajectory as regulatory pathways adapt to small-population evidence requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Academic medical centers and pharmaceutical R&D operations concentrate demand in the United States, with secondary clusters emerging in European research consortia and East Asian biotech corridors.
United States
Oncology departments at academic medical centers drive algorithm adoption for biomarker-informed treatment selection. FDA Breakthrough Device Designation compresses premarket review timelines for qualifying diagnostics. The Boston-Cambridge corridor anchors development activity, where hospital systems integrate machine learning tools into electronic health record workflows.
United Kingdom
Pharma companies deploy AI for clinical trial patient stratification and post-market surveillance. MHRA alignment with international software medical device standards shapes evidence requirements for algorithm deployment. London-based research networks pilot federated learning frameworks to pool genomic cohorts without centralizing protected health information.
Germany
Diagnostic labs demand ISO 13485-certified platforms for molecular profiling and histopathological quantification. BfArM oversight of digital health applications creates structured pathways for algorithm reimbursement. The Munich-Heidelberg biotech cluster concentrates development of predictive analytics tools for therapeutic response forecasting.
China
Hospital systems invest in edge computing architectures for point-of-care diagnostic deployment. NMPA regulatory frameworks for AI-enabled medical devices accelerate commercial review for oncology applications. The Yangtze River Delta biotech corridor generates multi-omics datasets requiring machine learning infrastructure for pattern recognition.
Switzerland
Pharmaceutical headquarters operations prioritize quantum-AI hybrid research for protein folding prediction. Swissmedic oversight of clinical decision-support algorithms aligns with EU AI Act high-risk system classifications. The Basel-Zurich corridor anchors specialized computational biology talent pools for genomics-engineering intersections.
AI in Precision Medicine Market Competitive Landscape
Player mix skews toward technology conglomerates with cloud infrastructure assets and specialized health AI vendors with clinical data network control. Market structure concentrates around GPU compute providers and vertically integrated molecular profiling platforms. Two strategic archetypes dominate: hyperscale cloud providers leveraging distributed computing assets, and precision medicine specialists capturing recurring SaaS revenue through EHR integration. Competitive moves center on federated learning partnerships and ISO 13485 certification acquisition to filter market entry.
Within the technology infrastructure tier, NVIDIA Corporation exemplifies GPU computing dominance for deep learning training workloads. Among precision medicine specialists, Tempus occupies a position representing vertical integration into clinical data networks and molecular profiling. IBM sits within the research-oriented archetype, targeting specialized quantum-AI hybrid applications for protein structure prediction.
| Leading Market Players |
|---|
| NVIDIA Corporation |
| Google Inc. |
| Microsoft |
| IBM |
| Tempus |
| GE HealthCare |
| Illumina Inc. |
| Exscientia |
| Sanofi |
| Others |
Pricing and Supply Chain Analysis
Ninety-day GPU procurement lead times for NVIDIA H100 clusters compress development timelines for algorithm vendors while amplifying pricing power for hyperscale cloud providers serving the Boston-Cambridge and San Francisco Bay Area research corridors. This inventory constraint concentrates cost pass-through capacity among compute infrastructure holders, forcing precision medicine software vendors into long-term SaaS contracting structures that embed hardware access fees.
Pricing Analysis
Cost-plus contracts indexed to NVIDIA GPU spot pricing dominate enterprise agreements for training workloads, with ISO 13485 certification tier serving as the primary price differentiation driver alongside inference volume commitments. Three-tier pricing structure across premium, standard, and economy levels separates FDA Breakthrough Device Designation holders from decision-support tools and research-use-only platforms. Pricing pressure stems from academic medical centers insourcing compute through direct hyperscale relationships, compressing intermediary margins. Healthcare providers exhibit highest price sensitivity for standalone diagnostic licenses, while pharma companies show lowest sensitivity for integrated predictive analytics subscriptions.
Supply Chain Analysis
Strategic stockpiling of GPU accelerators characterizes vendor behavior ahead of export control announcements, contrasting with just-in-time software release cadences that FDA SaMD premarket review timelines disrupt. Supply concentrates in Taiwan for advanced semiconductor fabrication, the United States for NVIDIA chip design and cloud infrastructure, and China for edge computing hardware assembly. The chain draws from specialized silicon wafers, high-bandwidth memory modules, and liquid cooling systems. Single-source vulnerability around NVIDIA's proprietary CUDA architecture dominates risk exposure. Distribution runs through hyperscale cloud marketplaces and direct hospital system procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The intersection of genomics expertise and machine learning engineering remains critically under-supplied relative to platform development roadmaps, constraining execution velocity for vendors across all funding stages. This capability gap favors incumbents with captive talent pipelines and punishes entrants lacking structured clinical data network access.
For Market Incumbents: Shield algorithm performance leadership through federated learning partnerships that lock academic medical centers into data-sharing architectures, while accelerating ISO 13485 certification acquisition to filter emerging competitors from FDA Breakthrough Device Designation eligibility. GPU compute cost concentration threatens margin sustainability for vendors without hyperscale cloud alliances. For New Entrants and Emerging Players: Anchor in rare disease therapeutic matching applications where established biomarker infrastructure is weakest and regulatory pathways adapt to small-population evidence requirements, leveraging federated learning frameworks to circumvent HIPAA data centralization barriers. Cardiology imaging-based risk stratification presents the most penetrable adjacent segment. For Investors and Strategic Acquirers: Long-term, this sits as a platform consolidation play because recurring SaaS contracts attaching to EHR workflows generate defensive revenue moats that standalone diagnostic tools cannot replicate. Target precision medicine specialists with vertical control over clinical data networks and molecular profiling infrastructure. Watch FDA SaMD classification clarity between decision-support and autonomous diagnostic systems as the inflection signal for portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Federated Learning Partnership | Academic medical centers in Boston-Cambridge pool genomic cohorts without HIPAA data transfer requirements. |
| FDA Breakthrough Device Designation | Premarket review timeline compression accelerates revenue realization for qualifying biomarker platforms. |
| EHR Workflow Integration | Recurring SaaS contracts attach to hospital information systems, concentrating margin pools. |
| ISO 13485 Certification Acquisition | Clinical-grade validation infrastructure filters software vendors from medical device markets. |
| Quantum-AI Hybrid Research Investment | Protein folding prediction applications open white space beyond classical machine learning limitations. |
Research Methodology
Operator-level perspectives from precision medicine platform executives, FDA regulatory affairs leads, hospital procurement committee chairs, and academic medical center CIOs anchored the qualitative base, cross-validated against secondary sources including FDA 510(k) and De Novo submission databases, EMA AI Act implementation guidance, ClinicalTrials.gov protocol registries, and hyperscale cloud provider capex disclosures. Bottom-up algorithm deployment counts across oncology departments triangulated with top-down market sizing from SaaS contract value analysis.
Sensitivity analysis tested forecast robustness across GPU cost inflation scenarios, FDA SaMD classification stringency variations, and EMA GDPR enforcement intensity levels. Segmentation modeling spanned technology architecture, product integration depth, end-user procurement authority, and therapeutic area reimbursement maturity. CAGRs derived from installed base expansion rates and average revenue per user trajectories across the analysis window, with inputs including academic medical center capital budget allocations and pharma R&D AI investment disclosures.
Material uncertainties — regulatory reclassification of decision-support algorithms as autonomous diagnostic systems, export control expansion affecting GPU supply, and federated learning framework adoption velocity — sit outside the modeled envelope. Forecasts reflect assumptions about FDA premarket review timeline stability and EMA AI Act alignment consistency. Revision becomes warranted when Breakthrough Device Designation approval rates deviate from historical baselines by more than threshold magnitudes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Smart Home Controller Market
Others
Fluorite Market
Others
North America Industrial Wearable Devices Market
Others
Profilometer Market
Others
Fibert Market
Others
North America Printed Signage Market
Others
Biopharma Plastics Market
Others
Africa Lime Market
Others
Process Instrumentation Equipment Market
Others
Linear Shaft Market
Others
Military 4D Printing Market
Others
Germany 3D Printing Construction Market
Others
Vo5g Market
Others
APAC Smart Home Market
Others
Italy 3D Printing Construction Market
Others
Asia-Pacific Laser Hair Removal Market