
 Fresh Durian Market | 2026-2036
Fresh Durian Market Size, Share, and Industry Trends Forecast 2026-2036
Fresh Durian Market Foresight
GlobalGAP certification is bifurcating the competitive landscape into export-qualified suppliers and domestic-only operators. Charoen Pokphand Group leverages integrated plantation-to-retail infrastructure across Thailand's Chanthaburi cluster. Thai Agri Foods Public Company Limited anchors its position through frozen durian processing capacity that extends shelf-life for distant markets. Sunshine International Co., Ltd. competes on Musang King varietal specialization from Malaysian orchards.
Fresh durian comprises the dehusked or whole fruit of Durio zibethinus and select cultivars, harvested at 75-85% maturity to withstand ethylene-controlled ripening during transoceanic shipment. The fruit's primary commercial purpose centers on direct consumption and as a culinary ingredient in premium desserts, where volatile sulfur compounds deliver distinctive organoleptic profiles. Monthong dominates export volumes due to thick aril consistency and extended post-harvest durability, while Musang King commands concentrated margin pools in Chinese specialty retail channels. Online Retailers represent the fastest-expanding distribution channel, though Traditional Markets sustain the highest throughput volumes across Southeast Asian domestic consumption.
Thailand's Ministry of Agriculture and Cooperatives enforces phytosanitary export protocols that determine market access eligibility for Chinese and South Korean buyers. Malaysia's Department of Agriculture coordinates varietal registration under Plant Variety Protection laws that restrict unauthorized Musang King propagation. China's SAMR cold-chain regulations mandate continuous temperature logging from orchard to port, disqualifying fragmented logistics providers. Stakeholders must monitor evolving varietal IP enforcement and certification reciprocity agreements between origin and destination regulators.
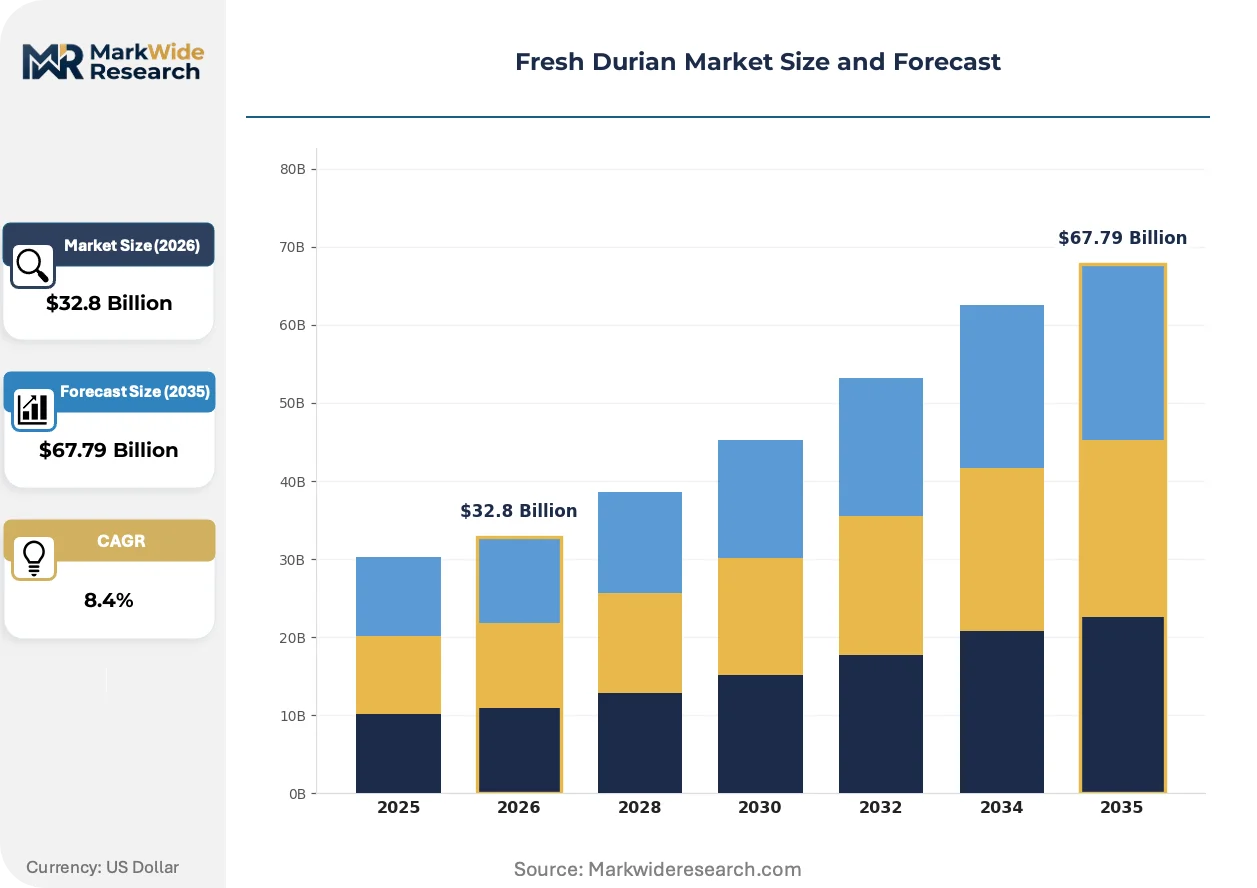
Market Dynamics
China's SAMR cold-chain enforcement is bifurcating supplier eligibility, concentrating export volumes among GlobalGAP-certified operators while disqualifying fragmented logistics providers from premium distribution channels.
Growth Catalysts
- Monthong varietal durability:Thick aril consistency withstands ethylene-controlled ripening protocols, enabling transoceanic shipment viability to distant markets without quality degradation.
- Premium food service procurement:Southeast Asian dessert and beverage menu expansion is pulling dehusked fresh durian into institutional supply chains at accelerating volumes.
- Malaysian Plant Variety Protection:Musang King registration restrictions under Department of Agriculture coordination are creating scarcity premiums that concentrate margin pools in specialty retail.
Market Restraints
- Input cost volatility:Labor-intensive hand-pollination and selective harvesting at 75-85% maturity compresses margins during seasonal labor shortages in Thailand's eastern provinces.
- Supply concentration risk:Chanthaburi cluster dominance exposes buyers to monsoon disruption and phytosanitary containment events affecting contiguous plantation zones.
- Regulatory friction:South Korean phytosanitary protocols enforced by Thailand's Ministry of Agriculture create inspection bottlenecks that delay harvest-to-port windows.
Strategic Opportunities
- Online Retail channel penetration:Direct-to-consumer platforms bypass traditional wet-market intermediaries, capturing margin recovery and consumer data in Chinese tier-two cities.
- Frozen processing extension:IQF technology convergence with modified atmosphere packaging enables year-round Musang King availability outside Malaysian harvest windows.
- Thai Agri Foods processing infrastructure:Frozen durian capacity investments by established processors create co-packing partnerships for unqualified fresh exporters seeking market access.
Industry Challenges
- GlobalGAP certification timelines:Smallholder consolidation requirements and audit backlogs delay qualification for SAMR-compliant cold-chain participation.
- Ethylene management expertise:Controlled ripening protocol execution requires specialized post-harvest technicians scarce in emerging plantation zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fresh Durian Market |
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $67.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monthong, Musang King, D24, Red Prawn, Golden Phoenix, Black Thorn Distribution Channel: Supermarkets, Traditional Markets, Online Retailers, Specialty Stores, Farmers Markets Customer Type: Wholesalers, Exporters, Food Service Providers, End Consumers, Retailers Application: Direct Consumption, Culinary Ingredient, Frozen Products, Processed Snacks, Beverages |
| Companies Covered | Xiamen King Wang Shun Industry & Trade Co., Ltd., DurianBB International Sdn. Bhd., Charoen Pokphand Group, Raub Durian Orchard, Top Fruits Sdn Bhd, Thai Agri Foods Public Company Limited, VIVA HOLDING INVESTMENT CONSULTING COMPANY LIMITED, TRL (South East Asia) Sdn Bhd, Sunshine International Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fresh Durian Market Shifts & Advancements
Fresh durian commerce is restructuring around traceability infrastructure and channel disintermediation, with technology investments concentrating on shelf-life extension and regulatory compliance automation.
Blockchain-enabled provenance tracking is fragmenting the authentication landscape. Premium Chinese retailers now mandate orchard-to-shelf temperature and harvest-date verification, adopting distributed ledger systems at pace. This capability compression is fragmenting competitive positioning between integrated plantation operators and fragmented trader networks unable to finance traceability infrastructure.
REACH-aligned phytosanitary documentation standards are reshaping European market preparation. The EU's tightening maximum residue limits for sulfur-based post-harvest treatments are forcing processing protocol revisions. Malaysian exporters targeting specialty Asian grocers in Germany and France are reformulating diphenylamine application rates to maintain access eligibility.
Specialty retail buyers now specify varietal-grade certification ahead of price negotiation. Chinese e-commerce platforms displace traditional wholesale auctions for Musang King procurement, with live-streaming hosts directly connecting Malaysian orchards to consumer pre-orders. This channel rotation is most visible in Shanghai and Shenzhen, where same-day cold-chain delivery expectations compress traditional importer margins.
Fresh Durian Market Segmentation
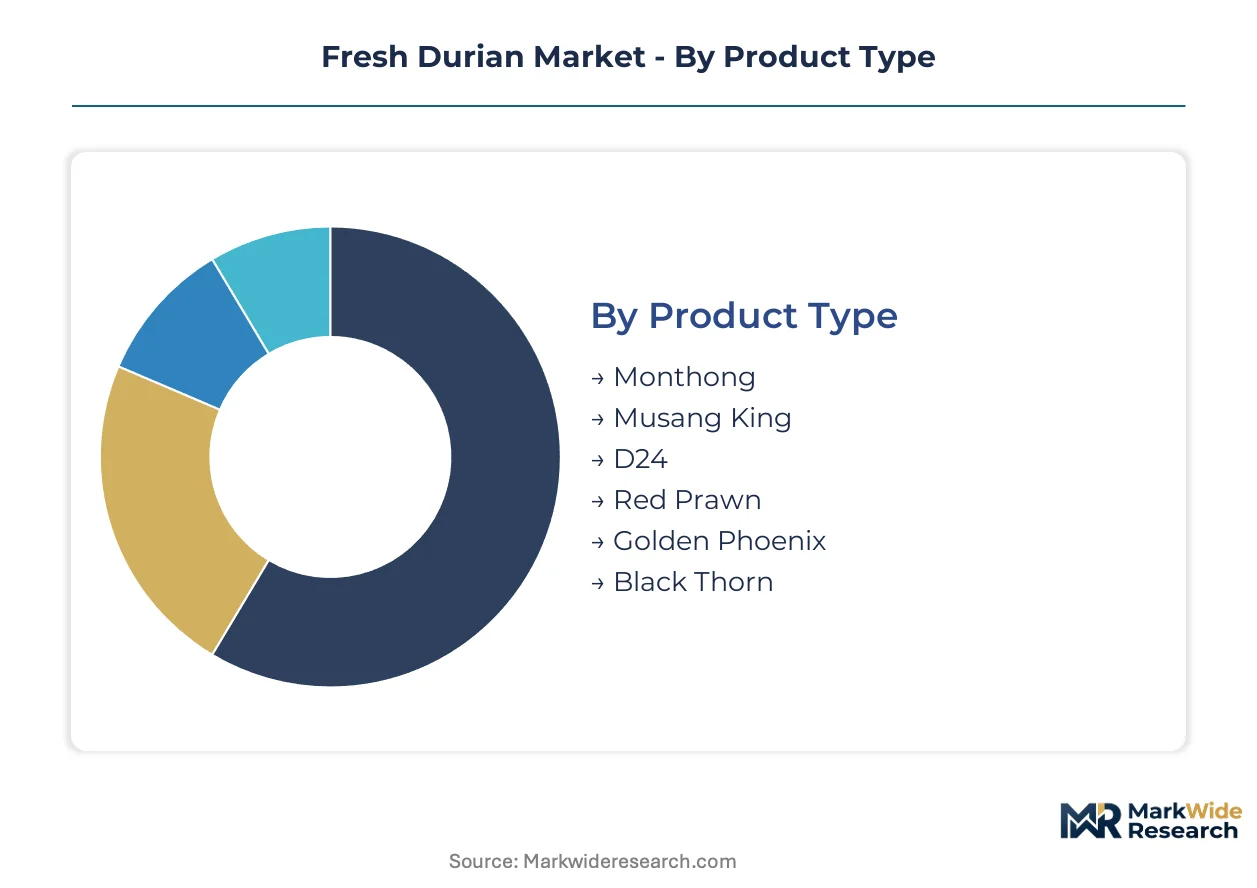
Fresh durian segmentation reveals how varietal genetics, channel infrastructure, and buyer sophistication create distinct margin pools. Each dimension carries different substitution vulnerabilities and certification requirements that reshape competitive positioning across export and domestic markets.
Product Type:
Monthong and Musang King face divergent substitution pressures—Monthong competes against frozen alternatives in distant markets, while Musang King's scarcity premium insulates it from direct varietal replacement.
- Monthong:Thick aril consistency and extended post-harvest durability enable ethylene-controlled ripening protocols for transoceanic shipment. Demand concentrates in Chinese mass retail channels where Thai exporters leverage GlobalGAP certification for SAMR cold-chain compliance, though frozen durian processing erodes fresh premiums during off-season windows.
- Musang King:Creamy texture and concentrated sulfur compound profiles command scarcity premiums in specialty retail. Malaysian Plant Variety Protection laws restrict unauthorized propagation, concentrating supply in Pahang orchards where direct-to-consumer live-streaming platforms bypass traditional wholesale auctions in Shanghai and Shenzhen.
- D24:Medium-thick aril and moderate sweetness profile serves Malaysian domestic consumption and Singaporean import markets at price points below Musang King tiers.
- Red Prawn:Orange-tinged flesh and alcoholic undertones attract Penang-based connoisseur segments with limited export scalability due to thin rind vulnerability.
- Golden Phoenix:Pale yellow aril and fibrous texture dominates Vietnamese domestic trade with minimal cross-border phytosanitary qualification.
- Black Thorn:Small-seeded, intensely creamy profile from Malaysian Johor plantations targets ultra-premium gifting segments in Hong Kong and Macau.
Monthong anchors the volume base while Black Thorn gains share at the steepest rate among ultra-premium varietals.
Distribution Channel:
Channel cost tiers stratify around cold-chain investment requirements, with capital-intensive formats facing margin compression from direct-to-consumer platform expansion.
- Online Retailers:Direct-to-consumer platforms bypass traditional wet-market intermediaries, capturing margin recovery and consumer data in Chinese tier-two cities. Same-day cold-chain delivery expectations in Shanghai and Shenzhen compress traditional importer margins while enabling Malaysian orchard-to-doorstep Musang King pre-orders.
- Traditional Markets:Wet-market intermediaries sustain highest throughput volumes across Southeast Asian domestic consumption, particularly in Bangkok and Ho Chi Minh City where price-sensitive buyers prioritize immediate ripeness verification over traceability documentation.
- Supermarkets:Modern retail chains in Kuala Lumpur and Jakarta enforce GlobalGAP sourcing mandates that disqualify fragmented smallholder suppliers.
- Specialty Stores:Premium Asian grocers in Germany and France specify REACH-aligned phytosanitary documentation with reformulated diphenylamine application rates.
- Farmers Markets:Orchard-direct sales concentrate in Thai domestic tourism corridors around Chanthaburi with minimal export qualification infrastructure.
Traditional Markets sustain absolute volume leadership while Online Retailers expand most quickly through live-streaming commerce penetration.
Customer Type:
Customer maturity levels determine certification burden and payment term structures, with institutional buyers extracting compliance investments that fragment supplier qualification.
- Food Service Providers:Southeast Asian dessert and beverage menu expansion pulls dehusked fresh durian into institutional supply chains at accelerating volumes, with premium hotel chains in Bangkok and Singapore specifying varietal-grade certification ahead of price negotiation.
- Exporters:SAMR cold-chain enforcement bifurcates supplier eligibility, concentrating export volumes among GlobalGAP-certified operators while disqualifying fragmented logistics providers from premium distribution channels into Chinese ports.
- Wholesalers:Traditional auction-based procurement in Malaysian wholesale markets faces displacement from e-commerce platform direct sourcing.
- Retailers:Chinese e-commerce platforms displace traditional wholesale auctions for Musang King procurement, mandating orchard-to-shelf temperature verification.
- End Consumers:Live-streaming hosts directly connect Malaysian orchards to consumer pre-orders, compressing traditional importer margins through disintermediation.
Exporters anchor the volume base while Food Service Providers gain share fastest through premium dessert menu expansion.
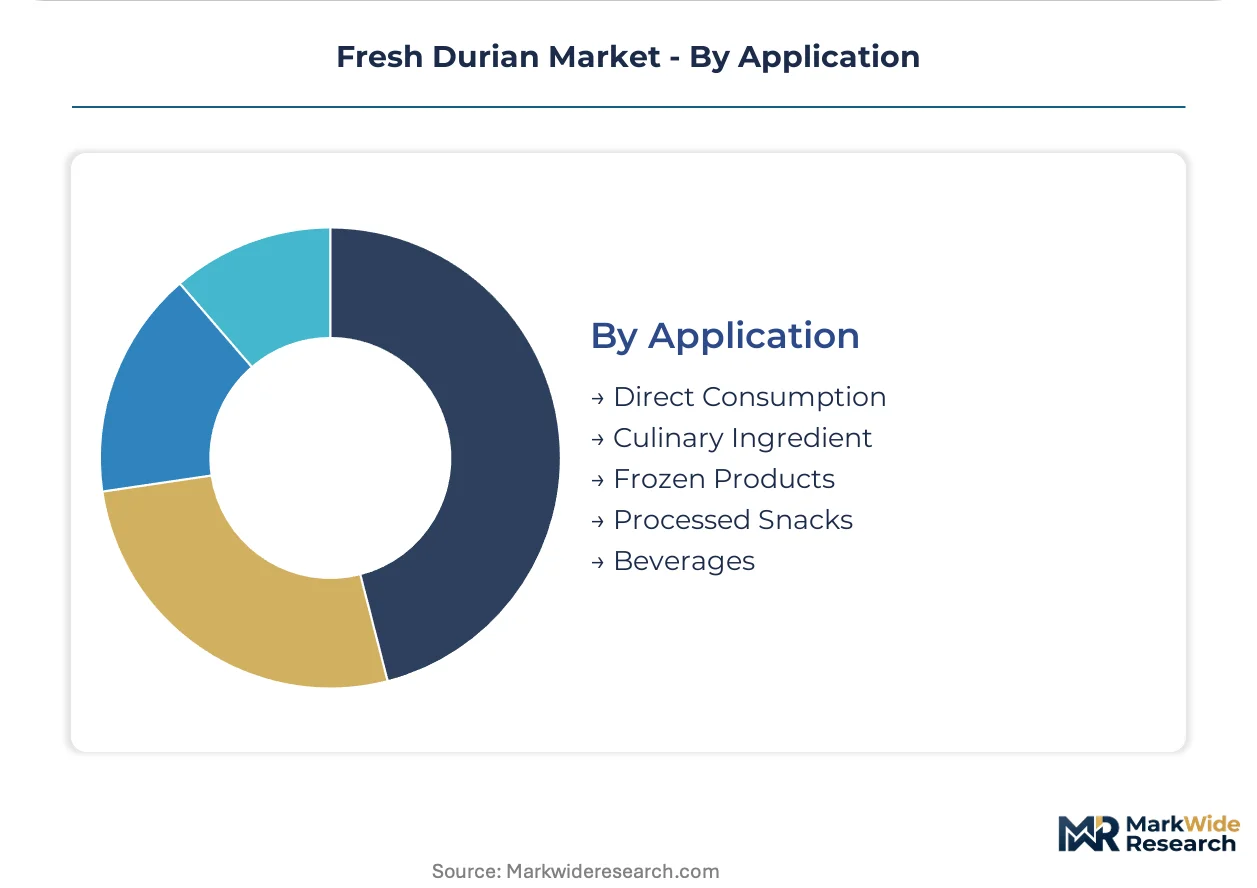
Application:
Application margins diverge around processing intensity and shelf-life extension requirements, with fresh formats facing substitution from IQF technology convergence.
- Direct Consumption:Whole fruit and dehusked fresh formats dominate Southeast Asian domestic markets where immediate ripeness assessment drives purchase decisions in Bangkok wet markets and Singaporean fruit stalls.
- Culinary Ingredient:Premium dessert and beverage formulations in Southeast Asian food service extract highest per-kilogram margins, with volatile sulfur compound profiles delivering distinctive organoleptic differentiation in artisanal ice cream and pastry applications.
- Frozen Products:IQF technology convergence with modified atmosphere packaging enables year-round Musang King availability outside Malaysian harvest windows, creating co-packing partnerships for unqualified fresh exporters.
- Processed Snacks:Freeze-dried and vacuum-fried formats target Chinese gift markets with extended shelf-life but compressed fresh fruit premiums.
- Beverages:Durian-flavored milk and smoothie applications in Vietnamese and Thai convenience retail compete with synthetic flavor alternatives at lower price points.
Direct Consumption anchors volume while Culinary Ingredient commands the steepest margin expansion trajectory through premium food service procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Laem Chabang deep-water port underwrites Thailand's dominance in fresh durian export logistics, handling the majority of Monthong shipments bound for Chinese consumer markets.
China
SAMR cold-chain enforcement is disqualifying fragmented logistics providers from premium distribution channels into Shanghai and Shenzhen ports. The regulator's continuous temperature logging mandates concentrate procurement among GlobalGAP-certified Thai exporters. Yangtze River Delta cold-chain infrastructure enables same-day delivery expectations that compress traditional importer margins.
Thailand
Chanthaburi province's integrated plantation-to-port corridors anchor Monthong export volumes through Charoen Pokphand Group infrastructure. The Ministry of Agriculture and Cooperatives enforces phytosanitary protocols that determine market access eligibility for South Korean buyers. Eastern province clusters face monsoon disruption risks affecting contiguous plantation zones.
Malaysia
Pahang orchard concentrations supply Musang King varietals commanding scarcity premiums in Chinese specialty retail. The Department of Agriculture coordinates varietal registration under Plant Variety Protection laws restricting unauthorized propagation. Live-streaming platforms now connect Raub district growers directly to Shanghai consumer pre-orders.
South Korea
Phytosanitary inspection bottlenecks enforced by Thailand's Ministry of Agriculture delay harvest-to-port windows for Seoul-bound shipments. Incheon cold-chain infrastructure demands documentation standards that favor established exporters over emerging traders. Korean retail buyers prioritize Monthong consistency over Musang King varietal experimentation.
Vietnam
Golden Phoenix domestic trade concentrates in Ho Chi Minh City wet markets with minimal cross-border phytosanitary qualification. The country's national agricultural regulator maintains residue limit protocols that diverge from Thai export standards. Mekong Delta processing zones supply frozen durian formats to regional food service buyers.
Fresh Durian Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers, with GlobalGAP qualification bifurcating the competitive landscape into export-eligible operators and domestic-only traders. Thai conglomerates leverage integrated plantation-to-retail infrastructure while Malaysian specialists exploit varietal IP restrictions. Three archetypes dominate: integrated agribusiness conglomerates controlling upstream supply, varietal-specialist orchard operators, and frozen processing intermediaries extending market access. Capacity expansion and cold-chain partnership formation represent the dominant competitive moves reshaping supplier positioning.
Within the integrated agribusiness tier, Charoen Pokphand Group and Thai Agri Foods Public Company Limited exemplify plantation-to-port control strategies that satisfy SAMR compliance requirements. Malaysian varietal specialists DurianBB International Sdn. Bhd. and Raub Durian Orchard occupy positions leveraging Plant Variety Protection scarcity premiums. Sunshine International Co., Ltd. anchors the cross-border trading archetype connecting Pahang orchard supply to Chinese e-commerce platforms.
| Leading Market Players |
|---|
| Xiamen King Wang Shun Industry & Trade Co., Ltd. |
| DurianBB International Sdn. Bhd. |
| Charoen Pokphand Group |
| Raub Durian Orchard |
| Top Fruits Sdn Bhd |
| Thai Agri Foods Public Company Limited |
| VIVA HOLDING INVESTMENT CONSULTING COMPANY LIMITED |
| TRL (South East Asia) Sdn Bhd |
| Sunshine International Co., Ltd. |
| Others |
Supply & Pricing Matrix
Seventy-two-hour harvest-to-port windows in Thailand's eastern provinces concentrate pricing power among GlobalGAP-certified operators while disqualifying fragmented smallholders from premium Chinese procurement channels. This lead-time compression creates tiered margin structures where cold-chain compliance functions as a price discriminator between export-eligible and domestic-only suppliers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates Musang King specialty retail from Monthong mass-market and unqualified domestic grades. Price differentiation hinges on GlobalGAP certification tier and varietal scarcity premiums under Malaysian Plant Variety Protection. Pricing pressure stems from frozen durian substitution eroding fresh premiums during off-season windows. Food service providers in Bangkok and Singapore demonstrate lowest price sensitivity, while Vietnamese wet-market buyers prioritize immediate ripeness over traceability premiums.
Supply Chain Analysis
Inventory compression to sub-48-hour post-harvest windows in Chanthaburi and Pahang orchards feeds from labor-intensive selective harvesting at 75-85% maturity. Thailand, Malaysia, and Vietnam anchor fresh supply, with input dependencies on ethylene-controlled ripening infrastructure and phytosanitary treatment chemicals. Single-source vulnerability concentrates in the Laem Chabang deep-water port corridor. Distribution runs through integrated plantation-to-retail conglomerates and direct-to-consumer live-streaming platforms bypassing traditional wholesale auctions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fresh durian commerce faces high-growth disruption from blockchain-enabled provenance tracking and SAMR cold-chain enforcement, creating bifurcated supplier eligibility that accelerates consolidation among certified operators.
For Market Incumbents: Compound defensive positioning through backward integration into captive plantation supply in Chanthaburi and Raub districts, while accelerating GlobalGAP certification timelines for smallholder networks to preempt disqualification from Chinese ports. Frozen processing capacity investments at Thai Agri Foods and Charoen Pokphand Group infrastructure extend market access for unqualified fresh exporters seeking year-round revenue stability. For New Entrants and Emerging Players: Traceability-as-a-service gaps in Malaysian smallholder orchards present white-space entry points for technology-enabled aggregators connecting Pahang growers to Shanghai e-commerce platforms. Target tier-two Chinese cities with direct-to-consumer pre-order models bypassing traditional importer margins. Go-to-market leverage centers on live-streaming commerce partnerships with established Chinese cold-chain logistics providers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified agribusiness conglomerates with under-monetized durian plantation assets lacking GlobalGAP qualification infrastructure. Long-term viability favors vertically integrated operators controlling upstream supply through varietal IP restrictions and downstream channel access through e-commerce platform relationships. Monitor SAMR enforcement consistency as the critical inflection signal for certification-premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| GlobalGAP Certification Acceleration | Unlocks SAMR-compliant cold-chain access to Chinese premium retail channels. |
| IQF Processing Capacity Expansion | Enables year-round Musang King availability outside Malaysian harvest windows. |
| Blockchain Provenance Implementation | Satisfies Chinese e-commerce platform mandates for orchard-to-shelf verification. |
| Direct-to-Consumer Platform Partnership | Bypasses traditional wholesale auction intermediaries in Shanghai and Shenzhen. |
| Varietal IP Licensing Compliance | Secures legal propagation rights under Malaysian Plant Variety Protection enforcement. |
Research Methodology
A spread of perspectives from plantation operations managers, cold-chain logistics coordinators, Chinese e-commerce procurement leads, and Malaysian Department of Agriculture officials converged on the working assumptions underlying demand projections. Primary fieldwork combined structured interviews across Thailand's Chanthaburi cluster and Pahang's Raub district with secondary validation from Thai Ministry of Agriculture export statistics, Chinese SAMR regulatory filings, and ASEAN customs trade databases. Bottom-up volume modeling triangulated against top-down value estimates across the analysis window.
Segmentation dimensions modeled include varietal genetics, distribution channel infrastructure, customer maturity tiers, and application processing intensity throughout the forecast period. CAGRs derived from historical shipment volume trajectories and pricing trend extrapolation, incorporating ethylene management protocol adoption curves and frozen substitution elasticity assumptions specific to Monthong and Musang King demand profiles.
Forecasts assume regulatory continuity in Chinese SAMR cold-chain enforcement and Malaysian Plant Variety Protection regimes; material policy shifts would require re-modeling supply eligibility and scarcity premium structures. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Underwater Communication System Market
Others
Asia-Pacific Medium-Density Fiberboard Market
Others
Duckweed Market
Others
Global Magnetic Flow Meters Market
Others
Fabric Based Computing Market
Others
Bitcoin Mining Hardware Market
Others
Aerospace Engineering Services Outsourcing Market
Others
Propanil Market
Others
Grna Market
Others
US 3D Printing Construction Market
Others
Global Surface Analysis Market
Others
Reef Aquarium Market
Others
Refractometer Market
Others
Global Contactless Biometrics Technology Market
Others
Digital Audio Decoders Market
Others
Thailand Travel Retail Market