
 Europe Video Encoder Market | 2026-2036
Europe Video Encoder Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Video Encoder Market Intelligence
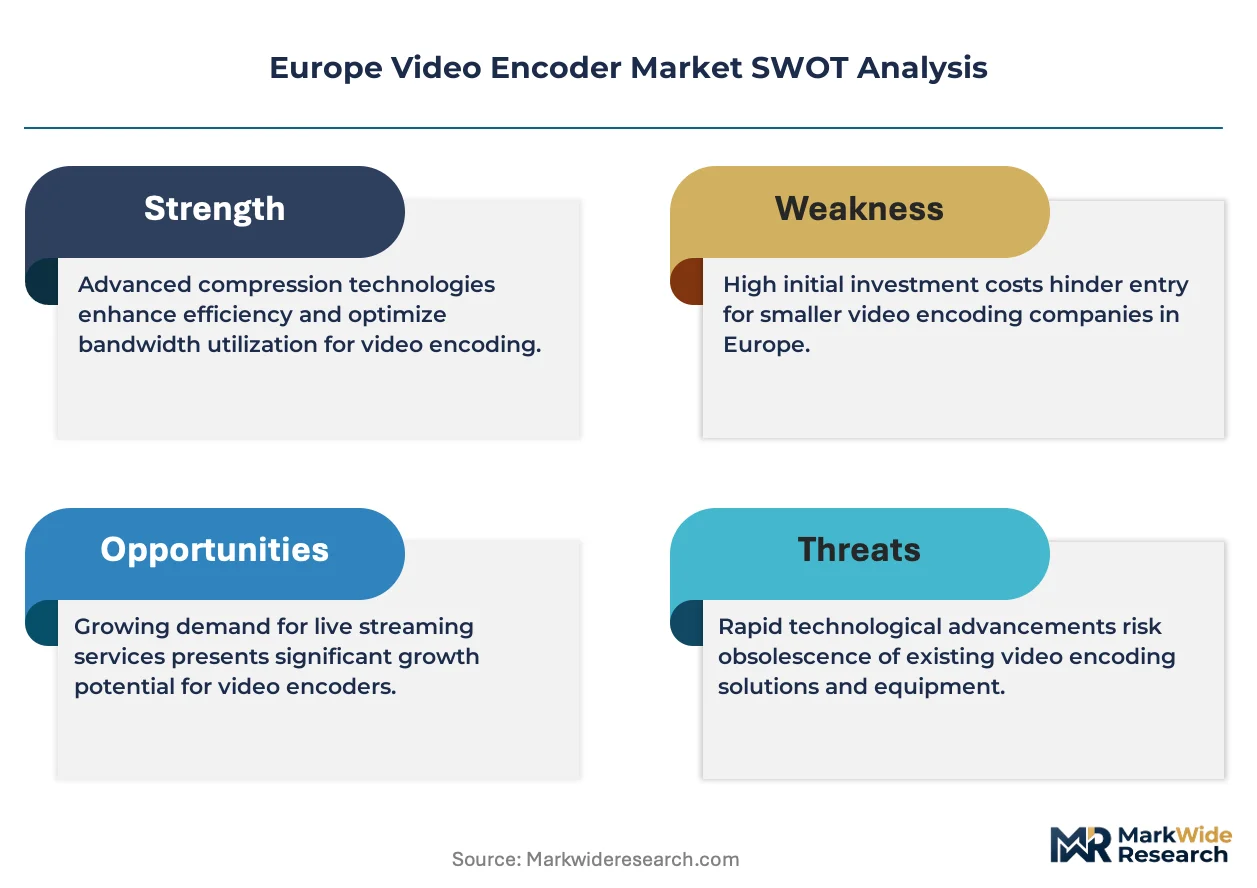
Platform licensing for cloud-based encoding services is tilting the profit landscape away from traditional hardware sales across the European market. Harmonic Inc. specializes in high-density software encoding for broadcast and streaming clients. Cisco Systems Inc. integrates encoding capabilities within its broader enterprise and service provider networking portfolios. Meanwhile, Axis Communications AB sustains its leadership in the network surveillance segment through its specialized hardware encoders.
A video encoder is a software or hardware solution that compresses raw video data into a digital format, managing parameters like constant or variable bit rate and end-to-end latency. This process is fundamental for efficient video delivery over IP networks. While hardware encoders remain a significant product type for on-premise reliability, cloud and software encoders are expanding rapidly due to their scalability. The technology segment shows a clear migration from H.264 towards the more efficient H.265 and AV1 codecs to support 4K and 8K streaming.
Hardware vendors across Europe must adhere to CE marking requirements, which certify products for safety and interoperability. The General Data Protection Regulation (GDPR) imposes strict rules on video data handling, particularly affecting surveillance and streaming service providers. Successfully navigating the trade-offs between next-generation codec adoption, processing power costs, and data privacy compliance will define competitive success.
Market Dynamics
The core dynamic in the European video encoder market is the architectural tension between established on-premise hardware for broadcast reliability and the rapid adoption of scalable, software-defined cloud services. This is amplified by the continent-wide migration to more efficient codecs.
Growth Catalysts
- AV1 Codec Adoption:The industry-wide push toward the royalty-free AV1 codec to support 4K and 8K streaming services creates a replacement cycle for older H.264 encoders and stimulates software development for more efficient compression.
- OTT Platform Growth:Expansion of on-demand and live streaming services across Europe, particularly within the UK and Nordic countries, necessitates massive investment in scalable, high-density encoding infrastructure to serve a growing subscriber base.
- Corporate Video Use:Enterprises, especially in Germany's industrial sector, are deploying video for internal training, corporate communications, and remote collaboration, driving demand for enterprise-grade software and hardware encoders.
Market Restraints
- Processing Power Costs:The computational intensity required for next-generation codecs like H.265 and AV1 translates into higher energy consumption and processing costs for both cloud providers and on-premise operators, limiting immediate widespread adoption.
- Patent Licensing Complexity:The intricate and often costly patent licensing structures surrounding codecs like H.265 (HEVC) create business uncertainty and can deter smaller software developers and hardware manufacturers from entering the market.
- Latency in Live Broadcasting:While software encoders offer flexibility, achieving the ultra-low latency required for live sports and news broadcasting remains a significant technical hurdle compared to dedicated hardware solutions, slowing adoption in these critical segments.
Strategic Opportunities
- Edge Computing Integration:Deploying encoding capabilities at the network edge for applications like smart city surveillance and industrial IoT offers a way to reduce backhaul bandwidth and improve real-time response, opening a new product category.
- AI-Powered Workflows:Integrating artificial intelligence with encoding processes to automate metadata tagging, content moderation, and video quality analysis provides significant value-add for media asset management systems across Europe.
- Eastern European Market Entry:As media infrastructure modernizes in countries like Poland and Romania, there is a significant opportunity for vendors to supply encoding solutions for new broadcast and streaming service rollouts.
Industry Challenges
- Specialized Talent Shortage:A scarcity of engineers with deep expertise in both video compression algorithms and modern cloud-native deployment architectures constrains product development and innovation for European technology firms.
- Legacy System Integration:Broadcasters and media houses face significant operational challenges and costs when integrating new IP-based software encoders into existing SDI-based workflows and legacy hardware infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Video Encoder Market |
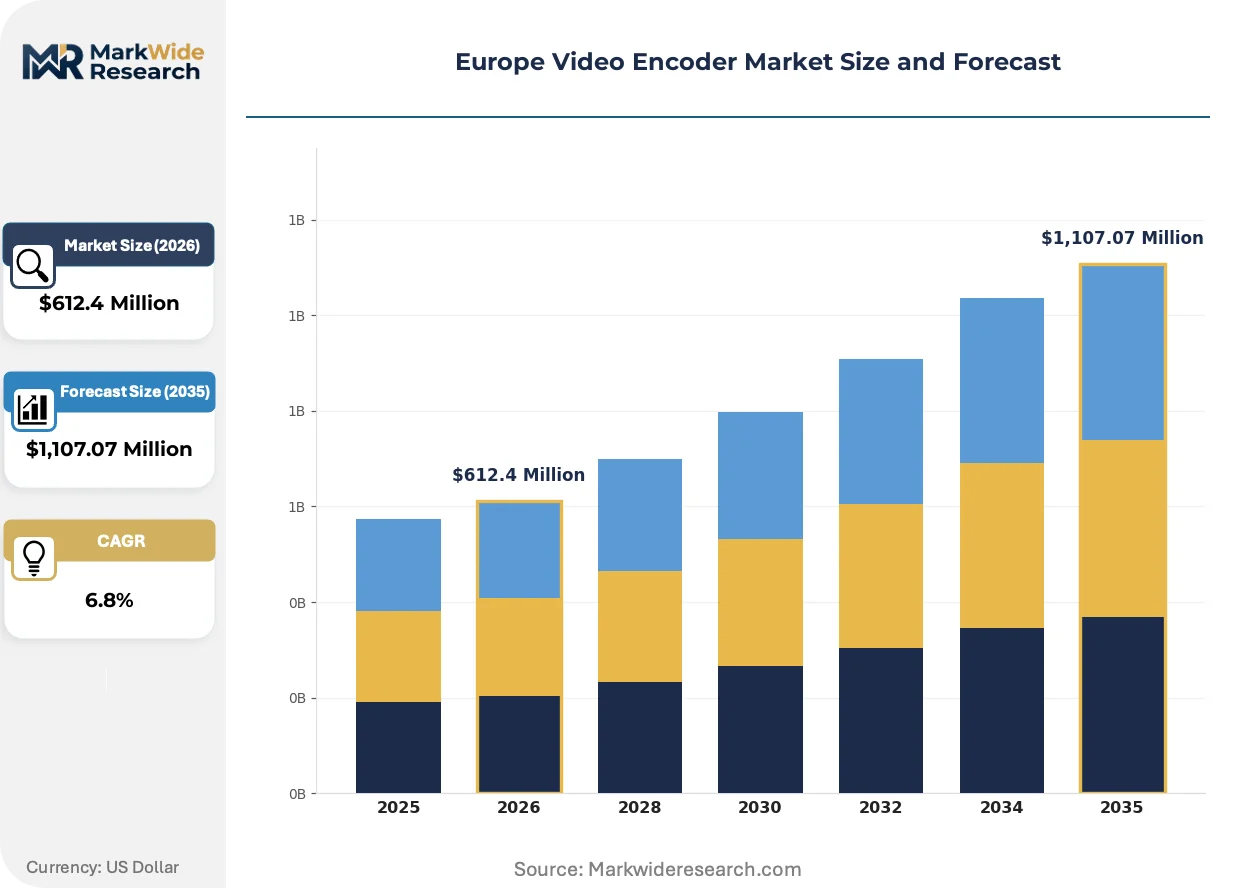
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,107.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware Encoder, Software Encoder, Hybrid Encoder, Cloud Encoder Technology: H.264, H.265, VP9, AV1, MPEG-2, MPEG-4 Application: Broadcasting, Video Streaming, Surveillance, Video Conferencing, Content Delivery Networks, E-Learning End User: Telecom Operators, Media Companies, OTT Platforms, Educational Institutions, Security Providers, Corporate Enterprises |
| Companies Covered | Zhejiang Dahua Technology Co., Ltd., Robert Bosch GmbH, Harmonic Inc., CommScope Holding Company, Inc., Matrox Electronic Systems Ltd., Axis Communications AB, Cisco Systems Inc., VITEC, Haivision Systems Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Video Encoder Market Strategic Shifts & Innovations
A fundamental re-evaluation of video processing architecture is taking place, prioritizing operational agility and resource elasticity. This trend favors software-defined and cloud-native solutions that can adapt to fluctuating demand, reshaping product development and procurement patterns across the European continent.
Cloud-based transcoding platforms are a central technological innovation. Media companies and large enterprises are adopting these services to handle variable workloads without large capital investments in physical appliances. This adoption is virtualizing the traditional encoding pipeline, moving it from dedicated on-premise hardware to scalable, on-demand cloud environments.
The EU's General Data Protection Regulation (GDPR) is a primary regulatory driver influencing product design. It imposes strict rules on processing video that contains personal data, from surveillance footage to user-generated content. Consequently, encoder manufacturers and service providers in markets like France and Germany are embedding privacy-by-design features like dynamic redaction to ensure compliance.
Subscription-based models are increasingly supplanting one-time hardware purchases and perpetual software licenses. This shift from capital expenditure to operational expenditure allows media organizations and corporate users to access the latest encoding technology with predictable costs. This consumption pattern is most visible in the competitive UK streaming sector and among pan-European enterprises.
Europe Video Encoder Market Segmentation
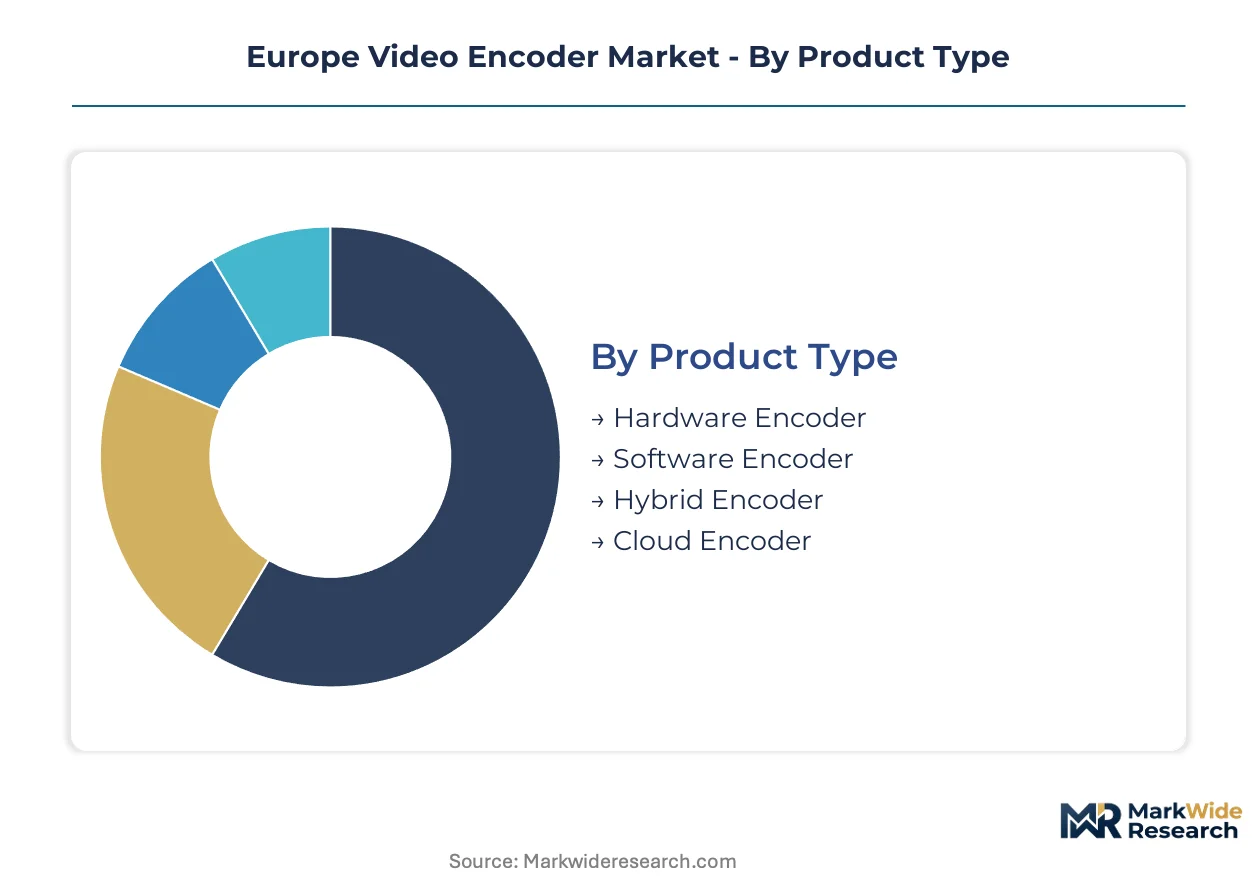
Understanding the Europe video encoder market through segmentation clarifies how diverse technological demands and user requirements shape product development and adoption patterns. This granular analysis reveals where innovation is most concentrated and where established solutions maintain their stronghold across European nations.
Product Type:
Product types in the European video encoder market exhibit varying turnover cycles, with software and cloud solutions evolving rapidly while hardware encoders offer longer-term stability. This differentiation influences procurement strategies for broadcasters and streaming providers.
- Hardware Encoder:These dedicated physical devices process video signals with high efficiency and ultra-low latency, often found in professional broadcast environments and mission-critical surveillance systems. Demand concentrates within Germany's established media sector and critical infrastructure projects requiring robust on-premise reliability.
- Cloud Encoder:These services offer scalable video processing capabilities hosted in remote data centers, providing flexibility and reducing capital expenditure for users. Adoption is accelerating among OTT platforms in the UK and Nordic countries, driven by the need for elastic capacity to handle fluctuating subscriber loads.
- Software Encoder:Applications running on general-purpose computing hardware, these encoders provide flexibility and cost-effectiveness for various video processing tasks.
- Hybrid Encoder:Solutions combining elements of both hardware and software encoding, offering a balance of performance and adaptability for complex workflows.
Hardware Encoder dominates the installed base. Cloud Encoder is where expansion concentrates.
Technology:
The technology segment reveals distinct application profiles, with newer codecs like AV1 targeting high-resolution streaming while older standards like MPEG-2 still serve specific legacy broadcast needs. This spectrum impacts content distribution efficiency.
- AV1:This royalty-free, open-source video coding format delivers superior compression efficiency, making it ideal for high-resolution 4K and 8K streaming services. Its adoption is accelerating across European streaming platforms seeking to reduce bandwidth costs and enhance user experience.
- H.265:Also known as High Efficiency Video Coding (HEVC), this standard provides significantly better compression than H.264, supporting UHD content delivery with reduced bitrates. Media companies in France and Italy are increasingly deploying H.265 for premium content distribution and video-on-demand services.
- H.264:A widely adopted video compression standard, offering a balance of compression efficiency and broad compatibility across devices and networks.
- VP9:An open and royalty-free video coding format developed by Google, primarily used for web video and increasingly by streaming services.
- MPEG-2:An older but still prevalent standard, particularly in traditional digital television broadcasting and DVD authoring due to its established infrastructure.
- MPEG-4:A versatile standard that encompasses various compression methods for audio and visual digital data, used in streaming, broadcasting, and mobile applications.
H.264 technology remains pervasive in existing infrastructure. AV1 is gaining share fastest for new deployments.
Application:
Application segments demonstrate varying volume requirements, from the massive scale of video streaming to the specialized needs of surveillance and e-learning. Each application drives distinct demands for encoder features and performance in Europe.
- Video Streaming:This application encompasses on-demand and live content delivery for entertainment, social media, and enterprise communication, requiring highly scalable and efficient encoders. The UK and Nordic countries represent significant volume contributors due to high penetration of OTT services and robust internet infrastructure.
- Broadcasting:Traditional television and radio broadcasting relies on video encoders for live transmission, playout, and contribution workflows, demanding ultra-low latency and high reliability. Germany's public and private broadcasters continue to drive substantial demand for professional-grade encoding solutions.
- Surveillance:Security and monitoring systems utilize encoders to compress and transmit video footage from cameras for real-time viewing and archival purposes.
- Video Conferencing:Corporate and personal communication platforms employ encoders to facilitate real-time, bidirectional video exchanges across various devices and networks.
- Content Delivery Networks:CDNs use encoders to prepare and optimize video assets for efficient distribution to end-users globally, ensuring fast and reliable playback.
- E-Learning:Educational platforms leverage encoders for delivering online courses, lectures, and interactive content, often requiring adaptive bitrate streaming capabilities.
Video Streaming holds the largest volume of deployed encoders. Surveillance applications are expanding quickly.
End User:
End user segments reflect differing levels of market maturity and investment cycles in video encoding technology. Established players like media companies have mature infrastructure, while OTT platforms and corporate enterprises are in growth phases.
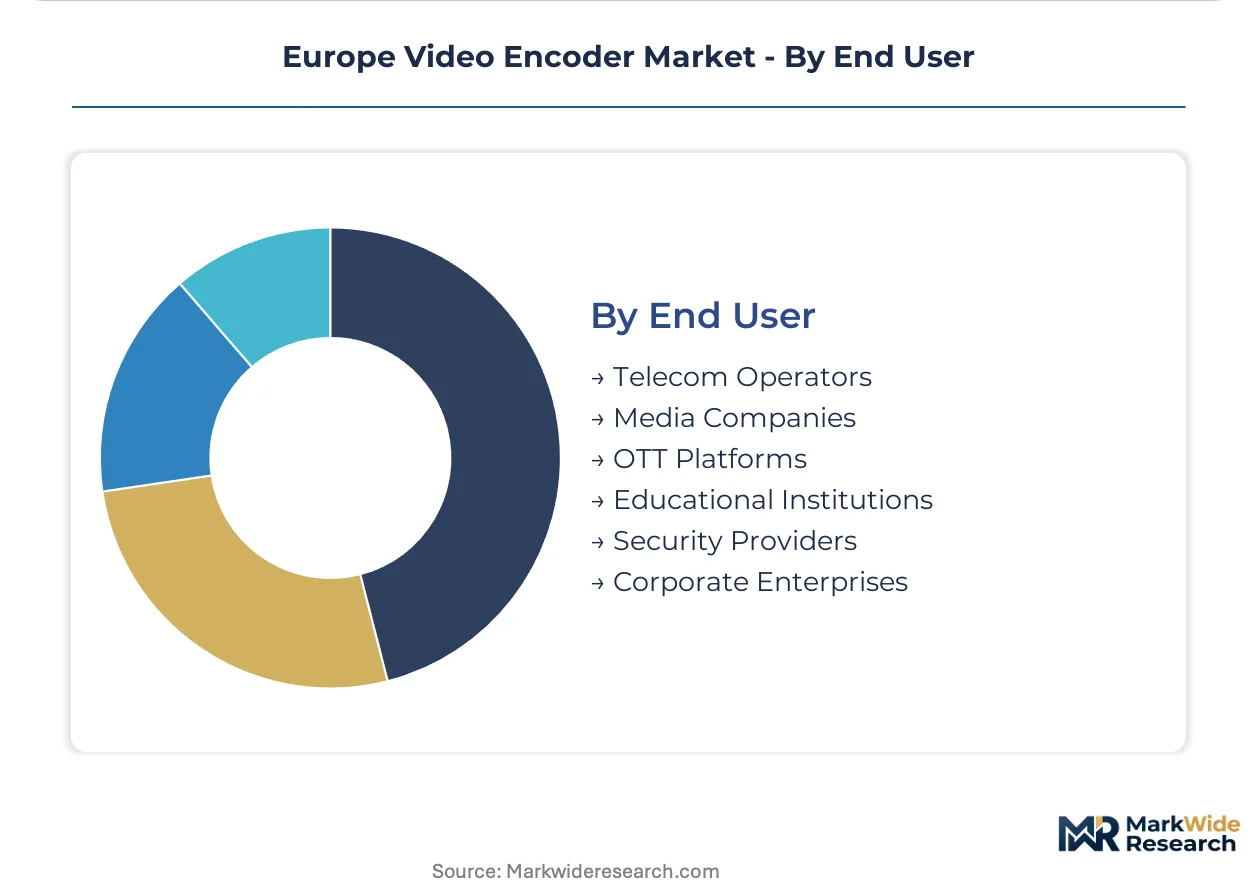
- OTT Platforms:These over-the-top content providers deliver video directly to consumers over the internet, necessitating flexible, cloud-native encoding solutions to manage vast content libraries and subscriber bases. European OTT platforms, particularly those expanding into new regional markets, represent a significant and growing end-user segment.
- Corporate Enterprises:Businesses across sectors use video encoders for internal communications, training, remote collaboration, and marketing, driving demand for enterprise-grade software and hardware. Germany's industrial sector and France's corporate giants are major consumers of these solutions.
- Telecom Operators:These providers leverage video encoders for IPTV services, mobile video delivery, and network infrastructure to manage video traffic efficiently.
- Media Companies:Traditional broadcasters, production houses, and content creators utilize encoders for content acquisition, post-production, and distribution workflows.
- Educational Institutions:Universities and schools employ encoders for lecture capture, online learning platforms, and virtual classrooms.
- Security Providers:Companies offering surveillance, access control, and public safety solutions integrate encoders for managing and transmitting video data.
Media Companies represent a mature segment with stable demand. OTT Platforms and Corporate Enterprises are experiencing significant growth in adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The consumption mix for video encoders across Europe exhibits distinct regional patterns, with established media markets prioritizing on-premise hardware for reliability while rapidly expanding streaming industries increasingly leverage cloud-based solutions. This differentiation influences procurement strategies and technology adoption rates across the continent.
Germany
Germany's robust industrial sector and established broadcasting infrastructure drive demand for professional-grade hardware encoders for corporate communications and traditional media. The General Data Protection Regulation (GDPR) mandates strict data handling, influencing product design for surveillance and enterprise video. Munich's media technology cluster actively develops hybrid encoding solutions to balance performance and compliance requirements.
United Kingdom
The UK's dynamic streaming industry and high OTT platform penetration create significant demand for scalable cloud and software encoders. Regulatory bodies like Ofcom influence content delivery standards, pushing for efficient codecs and low latency. London's vibrant tech ecosystem fosters innovation in video processing, attracting investment in cloud-native encoding services.
France
French media companies increasingly deploy H.265 for premium content distribution and video-on-demand services, balancing efficiency with established broadcast needs. Data privacy regulations, enforced by the CNIL, necessitate privacy-by-design features in video encoding solutions. Paris serves as a hub for media production, driving demand for advanced encoding workflows in post-production and distribution.
Sweden
Nordic countries, including Sweden, demonstrate strong adoption of OTT platforms and advanced streaming technologies, requiring flexible cloud encoders for fluctuating subscriber loads. The EU Green Deal initiatives encourage energy-efficient encoding solutions, influencing technology choices for data centers. Stockholm's tech scene supports specialized software development for video compression and delivery.
Poland
As media infrastructure modernizes across Eastern Europe, Poland represents a significant opportunity for vendors to supply encoding solutions for new broadcast and streaming service rollouts. EU directives on digital services and consumer protection guide market entry strategies for international providers. Warsaw's growing media sector seeks cost-effective and scalable encoding technologies to expand its digital footprint.
Europe Video Encoder Market Key Industry Players
Capability concentration sits with one tier of specialized vendors offering high-density software and hardware solutions, while scale advantage sits with broader technology conglomerates integrating encoding into larger portfolios. This market structure features a tiered competitive environment. Strategic archetypes include specialized encoder developers, diversified networking giants, and surveillance hardware leaders. Companies primarily engage in strategic partnerships to integrate solutions and pursue portfolio diversification to address evolving market needs.
Specialists in high-density software encoding for broadcast and streaming clients, Harmonic Inc. exemplifies a focused approach to video processing innovation. Cisco Systems Inc. represents a diversified networking giant, integrating encoding capabilities within its broader enterprise and service provider portfolios. Meanwhile, Axis Communications AB maintains its leadership in the network surveillance segment through its specialized hardware encoders, anchoring a specific application niche.
| Leading Market Players |
|---|
| Zhejiang Dahua Technology Co., Ltd. |
| Robert Bosch GmbH |
| Harmonic Inc. |
| CommScope Holding Company, Inc. |
| Matrox Electronic Systems Ltd. |
| Axis Communications AB |
| Cisco Systems Inc. |
| VITEC |
| Haivision Systems Inc. |
| Others |
Cost & Logistics Intelligence
Patent licensing complexity for advanced codecs like H.265 determines both pricing tier spreads for software encoders and the supply chain shape for integrated hardware solutions across Europe. This structural factor influences investment decisions and market entry strategies for vendors.
Pricing Analysis
Subscription-based models now dominate pricing for cloud and software encoding services, displacing traditional perpetual licenses. Price differentiation stems from customization levels for enterprise clients and the brand premium associated with specialized hardware encoders. Pricing pressure stems from the increasing availability of royalty-free codecs like AV1 and the cost-effectiveness of scalable cloud solutions. Corporate enterprises exhibit higher price sensitivity compared to large OTT platforms requiring elastic capacity.
Supply Chain Analysis
Upstream feedstock for video encoders primarily involves semiconductor chips and specialized processing units, largely sourced from East Asia and the US. Component manufacturing for hardware encoders concentrates in Germany for industrial applications and Eastern Europe for cost-effective assembly. Single-source vulnerability for advanced chipsets represents a structural risk, impacting hardware availability and cost. Distribution runs through direct sales channels for broadcast and enterprise clients, complemented by cloud marketplaces for software-defined solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe video encoder market presents an early-cycle expansion story, driven by the continent-wide transition to the AV1 codec. This technological shift encourages new product development and infrastructure upgrades across streaming and enterprise segments.
For Market Incumbents:Build technological moats by investing heavily in AV1 codec optimization and AI-powered video processing algorithms. Incumbents like Harmonic Inc. must integrate cloud-native architectures to counter the threat of agile software-defined entrants. Capacity additions in European data centers and strategic R&D in ultra-low latency encoding will strengthen market position.
For New Entrants and Emerging Players:Eastern European market underpenetration offers significant white-space opportunities for new encoder solutions, particularly in Poland and Romania. Focus on cost-effective, scalable software encoders for emerging streaming service rollouts and corporate video use. A freemium or tiered subscription model for cloud-based encoding services can accelerate adoption among smaller businesses.
For Investors and Strategic Acquirers:GDPR compliance requirements reshape the acquisition landscape, favoring companies with embedded privacy-by-design features in their encoding solutions. Long-term viability for video encoder investments extends over a decade, driven by persistent demand for efficient content delivery. Target mid-cap specialists in AI-powered video analytics or edge computing integration to capture future value. The signal to watch is accelerating consolidation among cloud-native encoding platform providers.
| Strategic Initiative | Industry Significance |
|---|---|
| AV1 Codec Product Launch | This move enables early capture of market share as European streaming platforms transition to more efficient formats. |
| Edge Computing Integration | Deploying encoding at the network edge supports smart city surveillance and industrial IoT applications, reducing latency. |
| Eastern European Market Entry | Expanding into Poland and Romania addresses modernizing media infrastructure and new service rollouts. |
| AI-Powered Workflow Automation | Integrating AI for metadata tagging and quality analysis adds significant value for media asset management systems. |
| Cloud-Native Platform Development | Developing scalable cloud solutions aligns with the industry shift towards operational agility and resource elasticity for OTT platforms. |
Research Approach
Desk research of industry association reports, corporate financial filings, and technology whitepapers preceded structured interviews with CTOs, broadcast engineers, and streaming platform managers. This primary fieldwork gathered qualitative insights and validated market dynamics. The study employed both bottom-up aggregation of segment data and top-down market sizing, ensuring robust triangulation. Secondary validation involved cross-referencing market trends and adoption rates.
Assumptions regarding internet penetration rates and 4K/8K content availability were held fixed across the analysis window, while codec efficiency advancements were varied. The analytical framework modeled key segmentation dimensions including product type, technology, application, and end-user adoption patterns. Compound annual growth rates were derived from historical data and projected market shifts. Cloud infrastructure investment served as a critical input for forecasting growth in cloud encoder segments.
Practitioners should monitor new codec breakthroughs and geopolitical shifts impacting semiconductor supply for early signals of forecast revision. Forecasts reflect assumptions concerning technological adoption rates and regulatory stability. Cross-checking against European Commission digital policy reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Latin America Smart Home Market
Others
Aerospace and Defense Fiber Optic Cables Market
Others
Running Apparel Market
Others
Europe Postal Services Market
Others
Latin America IT Device Market
Others
Industrial Hooters Market
Others
Space Cables Market
Others
Edible Insects for Animal Feed Market
Others
Middle East 3D Printing Construction Market
Others
Japan Coal Market
Others
Latin America 3D Printing Construction Market
Others
Asia-Pacific Social Media Management Market
Others
Sunflower Husk Pellets Market
Others
Nuclear Power Cables Market
Others
Asia-Pacific Military 4D Printing Market
Others
Medical Simulation Market