
 Cloud Digital Video Recording (DVR) Market | 2026-2036
Cloud Digital Video Recording (DVR) Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Digital Video Recording (DVR) Market Analysis
Residential cord-cutting is decoupling from cloud DVR demand as streaming-first households retain time-shifting expectations. TiVo Corporation leverages its patent portfolio to sustain licensing revenue across operator deployments. Amazon Web Services anchors infrastructure supply for multiple virtual MVPD platforms. DISH Network Corporation differentiates through Sling TV integration with cloud recording features.
Cloud Digital Video Recording refers to network-based storage and playback of television content where encoding, storage, and stream delivery occur on remote server infrastructure rather than local hard disk units, typically supporting concurrent recordings across dozens of channels with multi-device access. The technology serves both consumer entertainment and enterprise media archiving by replacing physical set-top box storage with elastic cloud capacity. Streaming Services within product type segments dominate volume as pure-play platforms displace hybrid hardware deployments. Subscription-Based delivery models capture recurring revenue pools while Freemium tiers expand user acquisition for premium conversion. IP Streaming technology leads transmission architecture as multicast and unicast protocols displace traditional QAM broadcast methods.
FCC regulations govern closed captioning and accessibility requirements for cloud DVR replay functionality in the United States. GDPR and state privacy frameworks including CCPA constrain cross-border content storage and viewer data retention policies. EMA and national data protection authorities in Europe enforce territorial processing limitations that shape provider infrastructure placement. Stakeholders must monitor evolving encryption mandates and territorial licensing restrictions that determine content availability windows across jurisdictions.
Market Dynamics
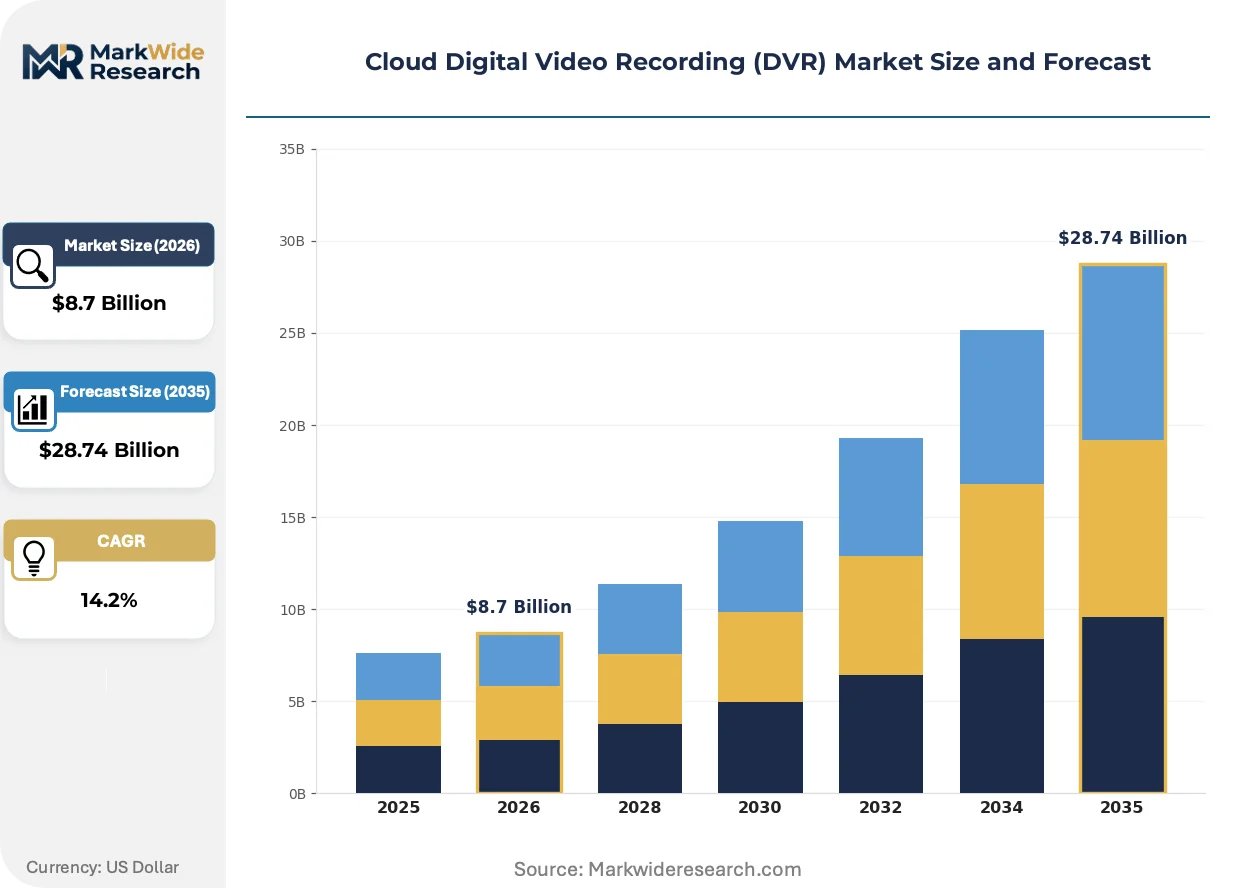
Pay-TV operators are dismantling customer-premises equipment programs and migrating encoding, storage, and stream delivery to remote server infrastructure, collapsing capital expenditure structures while elastic capacity absorbs peak recording loads.
Growth Catalysts
- GDPR territorial processing mandates:European data protection authorities enforce storage localization, compelling providers to build regional cloud nodes and expanding addressable infrastructure spend.
- Multicast-to-unicast protocol migration:IP streaming architectures replace legacy QAM broadcast methods, enabling concurrent channel recordings without hardware constraints.
- Streaming-first household formation:Cord-cutting demographics retain time-shifting expectations, sustaining cloud DVR subscriptions even as linear pay-TV contracts terminate.
Market Restraints
- Cross-border content licensing fragmentation:Territorial availability windows vary by jurisdiction, forcing redundant storage architectures and complicating unified service delivery.
- Amazon Web Services supply concentration:Multiple virtual MVPD platforms anchor on single infrastructure providers, creating systemic resilience exposure.
- State-level privacy law multiplication:CCPA and emerging US state frameworks impose conflicting retention policies, raising compliance engineering costs.
Strategic Opportunities
- Enterprise media archiving expansion:Broadcasters and content libraries seek elastic retention for compliance and monetization, extending cloud DVR platforms beyond consumer use cases.
- Freemium-to-premium conversion mechanics:Tiered storage limits and device access restrictions create upgrade pathways within streaming service bundles.
- AI-driven content indexing integration:Machine vision and natural language processing enable searchable recording libraries, differentiating operator offerings.
Industry Challenges
- Closed captioning synchronization complexity:FCC accessibility mandates require frame-accurate caption embedding across adaptive bitrate streams, demanding specialized engineering talent.
- Encryption mandate evolution:Content protection standards update frequently, forcing continuous client-server compatibility testing across device ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Digital Video Recording (DVR) Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Streaming Services, Hybrid Systems, Cloud Solutions, On-Premises Devices End User: Residential Users, Small Businesses, Enterprises, Media Companies Delivery Model: Subscription-Based, Pay-Per-View, Freemium, One-Time Purchase Technology: IP Streaming, VOD, Live Streaming, Cloud Storage |
| Companies Covered | Comcast Corporation, AT&T Inc., Google LLC, Amazon Web Services, Cisco Systems Inc., DISH Network Corporation, Verizon Communications Inc., TiVo Corporation, Synamedia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Digital Video Recording (DVR) Market Emerging Trajectories
Cloud DVR architectures are absorbing adjacent video processing workloads as operators consolidate vendor relationships and compress latency budgets for live-to-VOD transitions.
Edge computing nodes are converging with content delivery networks to position encoding closer to viewers, reducing backhaul costs for regional sports networks and local broadcast affiliates. Tier-1 operators in the United States deploy these micro-data centers in metropolitan markets to shave milliseconds from stream startup times. The technology is converging with 5G network slicing to guarantee quality-of-service tiers for premium subscribers.
GDPR Article 17 right-to-erasure provisions are reshaping data retention architectures, forcing providers to implement automated deletion workflows that purge viewer history and recording metadata on schedule. European national data protection authorities audit compliance through technical inspections. Virtual MVPD platforms serving France and Germany have restructured backup policies to satisfy CNIL and BfDI territorial processing requirements.
Subscription fatigue among streaming households is compressing service stacking tolerance, pushing cloud DVR features toward bundling within consolidated entertainment packages rather than standalone offerings. Virtual MVPD operators respond by integrating recording functionality into base tiers. The United States exhibits the clearest manifestation, where broadband providers package cloud DVR with connectivity to reduce churn.
Cloud Digital Video Recording (DVR) Market Segmentation
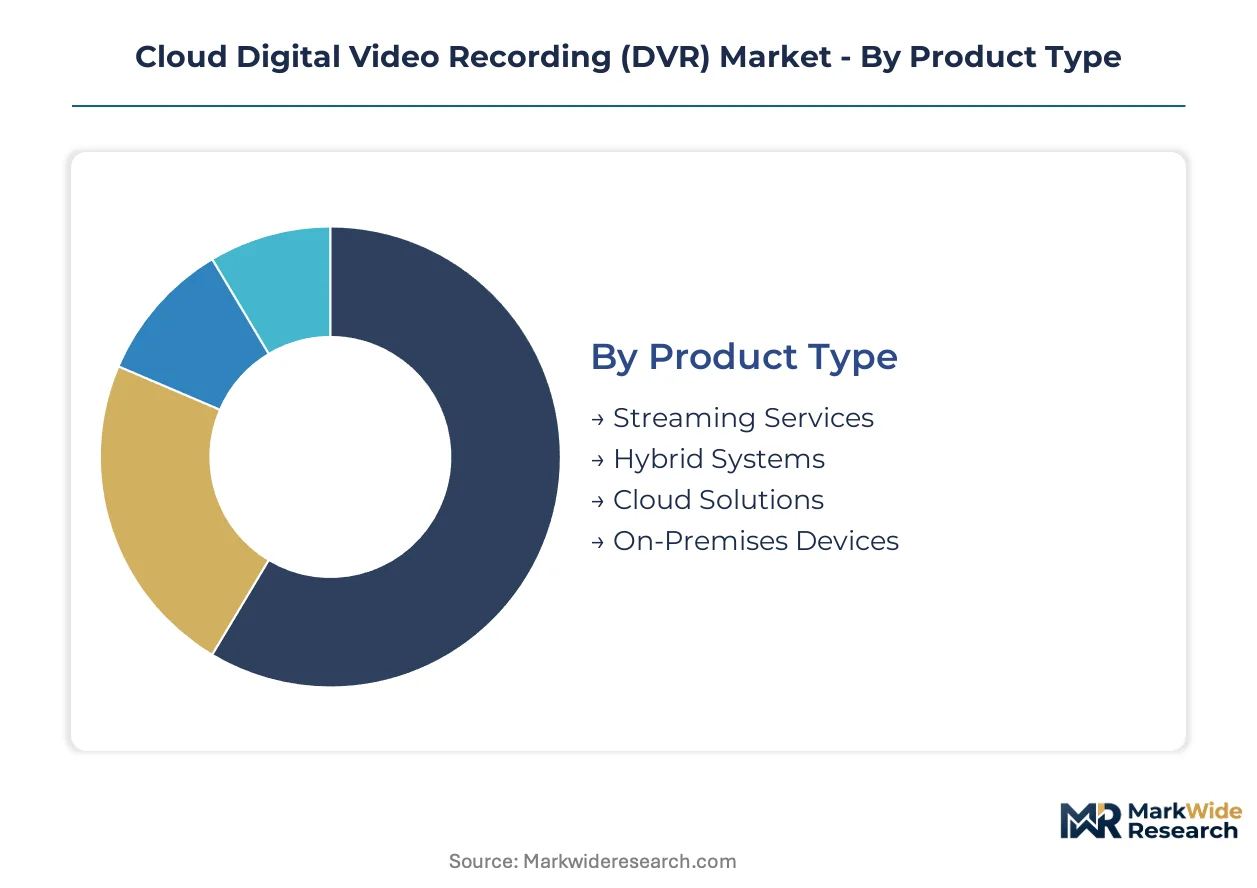
Cloud DVR segmentation reveals how infrastructure requirements and compliance burdens fragment across deployment architectures. Each category carries distinct certification pathways and operational constraints that shape provider strategy.
Product Type:
FCC closed captioning mandates apply differentially across hardware-dependent versus pure-software deployments, with accessibility compliance costs concentrated in hybrid architectures.
- Streaming Services:Pure-play platforms encode, store, and deliver entirely through remote server infrastructure. Demand concentrates among cord-cutting households in the United States where broadband density supports concurrent multi-channel recording without local hardware.
- Hybrid Systems:These configurations split processing between edge devices and cloud backends, requiring dual compliance regimes for both CPE accessibility standards and remote infrastructure data protection. European deployments face added GDPR territorial processing constraints.
- Cloud Solutions:Fully centralized architectures eliminate local storage hardware.
- On-Premises Devices:Legacy hardware units retain niche presence in enterprise archiving applications.
Leading the category by volume: Streaming Services. Growing fastest: Cloud Solutions.
End User:
Customer scale determines infrastructure topology, with enterprise deployments requiring dedicated tenancy and residential segments driving multi-tenant platform economics.
- Residential Users:Individual households consume cloud DVR through bundled streaming subscriptions, with time-shifting expectations persisting even as linear pay-TV contracts terminate. United States broadband providers package these features to reduce churn.
- Enterprises:Large organizations demand elastic retention for compliance archiving and internal media management, extending cloud DVR platforms beyond consumer entertainment into governance applications.
- Small Businesses:Limited-scale deployments prioritize cost predictability.
- Media Companies:Broadcasters and content libraries seek monetization-ready storage.
Residential Users anchor category volume. Enterprises expand most quickly as compliance archiving requirements deepen.
Delivery Model:
Revenue recognition patterns and customer acquisition costs vary sharply between recurring and transactional structures.
- Subscription-Based:Recurring revenue pools dominate provider economics, with tiered storage limits creating upgrade pathways. Virtual MVPD platforms integrate base-tier recording to reduce service stacking tolerance among streaming households.
- Freemium:Restricted storage ceilings and device access limitations drive premium conversion within bundled entertainment packages.
- Pay-Per-View:Transactional recording for individual events.
- One-Time Purchase:Perpetual licensing for enterprise archiving deployments.
Subscription-Based models capture the majority of revenue. Freemium tiers gain share fastest as user acquisition costs rise.
Technology:
Transmission protocols determine latency budgets and concurrent recording capacity.
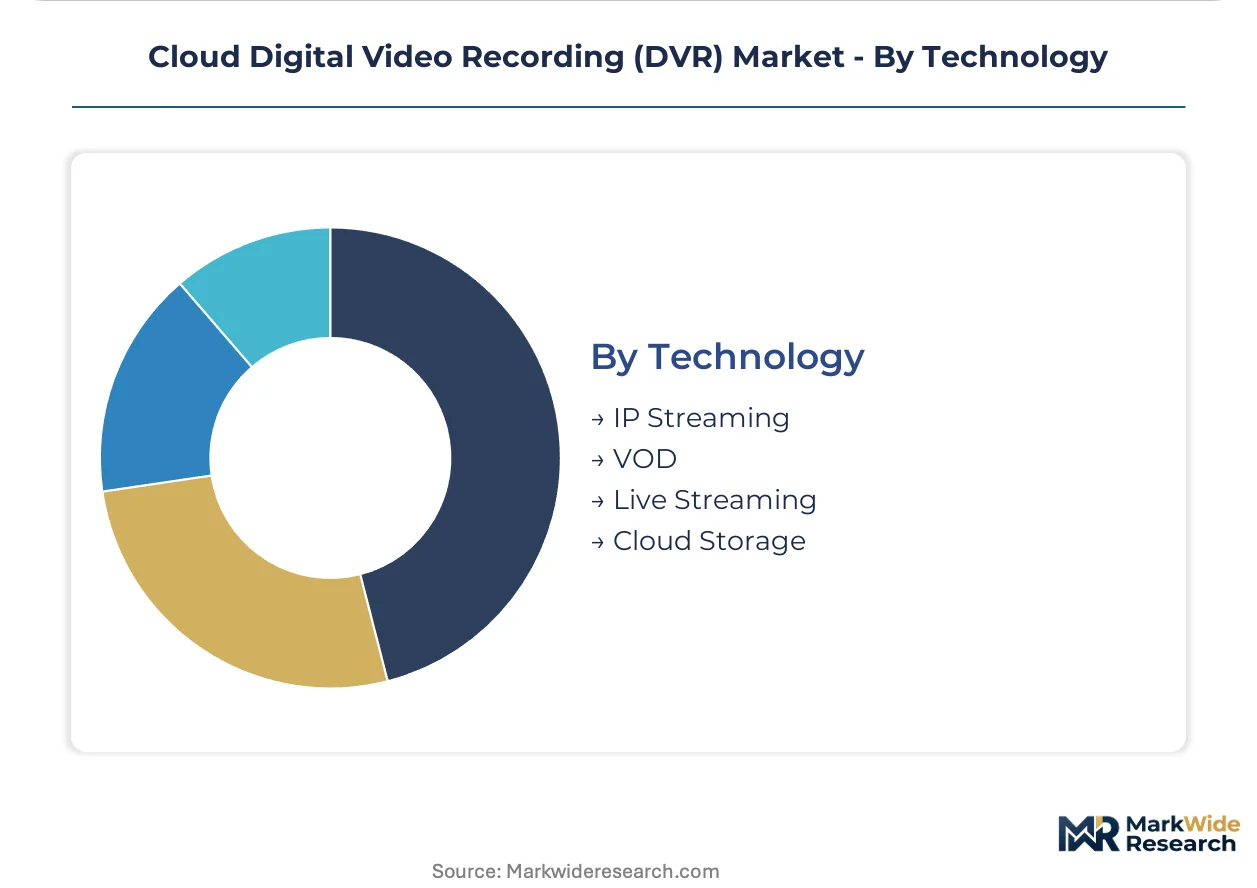
- IP Streaming:Unicast and multicast architectures replace legacy QAM broadcast methods, enabling concurrent channel recordings without hardware constraints. Tier-1 United States operators deploy edge nodes in metropolitan markets to compress stream startup times.
- Cloud Storage:Elastic capacity absorbs peak recording loads while GDPR Article 17 mandates force automated deletion workflows for viewer history and metadata.
- VOD:On-demand replay from centralized libraries.
- Live Streaming:Real-time capture with minimal buffer delay.
IP Streaming leads by deployment volume. Cloud Storage climbs the fastest as data sovereignty requirements expand regional infrastructure buildouts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free Trade Zones in the UAE and Special Economic Zones in India are accelerating cloud infrastructure buildouts for media processing, while broadband subsidy programs in the United States and Germany are expanding addressable households for virtual MVPD platforms.
United States
Broadband penetration above 90% and streaming subscription density support large-scale cloud DVR deployments across virtual MVPD platforms. FCC closed captioning mandates govern accessibility requirements for replay functionality, forcing frame-accurate caption embedding across adaptive bitrate streams. Tier-1 operators deploy edge computing nodes in metropolitan markets including Los Angeles and New York to compress stream startup times for regional sports networks.
Germany
GDPR territorial processing requirements under BfDI oversight compel providers to build regional cloud nodes, expanding addressable infrastructure spend for compliant storage architectures. The national data protection authority enforces Article 17 right-to-erasure provisions through technical inspections of automated deletion workflows. Media processing clusters in Berlin and Munich host localized encoding facilities serving Central European markets.
United Kingdom
Cord-cutting demographics retain time-shifting expectations, sustaining cloud DVR subscriptions even as linear pay-TV contracts terminate among streaming-first households. Ofcom broadcasting codes intersect with GDPR constraints on cross-border content storage and viewer data retention policies. London's media technology corridor anchors infrastructure development for pan-European virtual MVPD services.
India
TRAI regulatory frameworks for over-the-top services are shaping data localization requirements for foreign streaming platforms operating in the market. Production-linked incentive schemes for electronics manufacturing are expanding domestic server assembly capacity for cloud infrastructure deployment. Bangalore and Hyderabad host engineering centers developing adaptive bitrate technologies for emerging market bandwidth conditions.
Japan
METI industrial policy supports 5G network slicing investments that guarantee quality-of-service tiers for premium cloud DVR subscribers. JIS standards for information security management systems constrain provider architecture decisions for enterprise media archiving applications. Tokyo's dense metropolitan fiber infrastructure enables low-latency live-to-VOD transitions for broadcasters.
Cloud Digital Video Recording (DVR) Market Vendor Landscape
Top-tier vendors anchor infrastructure supply for multiple virtual MVPD platforms, while specialized middleware providers and patent licensors occupy differentiated positions. The market structure reflects supply concentration at the cloud layer alongside fragmentation in client-side integration and user experience layers. Three strategic archetypes dominate: hyperscale infrastructure operators, legacy pay-TV technology vendors pivoting to cloud, and pure-play patent licensors extracting value from intellectual property portfolios. Competitive moves concentrate on strategic partnerships between operators and cloud providers, plus technology licensing arrangements that reduce R&D duplication.
Within the patent-licensor archetype, TiVo Corporation exemplifies value extraction from intellectual property portfolios across operator deployments. Among hyperscale infrastructure providers, Amazon Web Services occupies a position anchoring supply for virtual MVPD platforms. DISH Network Corporation represents the legacy-operator pivot, integrating cloud recording features through Sling TV to differentiate in streaming markets. These three entities collectively illustrate the competitive tension between infrastructure control, intellectual property leverage, and direct-to-consumer service bundling.
| Leading Market Players |
|---|
| Comcast Corporation |
| AT&T Inc. |
| Google LLC |
| Amazon Web Services |
| Cisco Systems Inc. |
| DISH Network Corporation |
| Verizon Communications Inc. |
| TiVo Corporation |
| Synamedia |
| Others |
Supply Flow & Price Mechanics
Multicast-to-unicast protocol migration simultaneously collapses encoding infrastructure costs and concentrates supply leverage among hyperscale cloud operators capable of absorbing elastic capacity demands. This technology transition reshapes cost economics by eliminating customer-premises equipment while tethering provider margins to concentrated infrastructure supply.
Pricing Analysis
Short lead-time premiums attach to rapid-deployment cloud DVR implementations for virtual MVPD platforms facing subscriber acquisition deadlines, while spot inventory discounts emerge in enterprise archiving contracts with flexible activation schedules. Subscription-based SaaS tiers dominate, with price differentiation hinging on storage ceiling tiers and concurrent stream counts. Pricing pressure stems from AWS supply concentration forcing margin compression among downstream operators. Small virtual MVPDs exhibit highest price sensitivity; tier-1 broadband providers with captive infrastructure show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Amazon Web Services as the dominant infrastructure anchor for multiple virtual MVPD platforms, creating systemic resilience exposure across the ecosystem. Geographic supply concentrates in the United States, Ireland, and Germany where GDPR-compliant cloud nodes cluster. Raw material dependencies include server-grade silicon, high-density storage media, and fiber optic transmission equipment. Tariff exposure on Chinese-manufactured server components presents structural supply chain risk. Distribution runs through direct operator partnerships and hyperscaler marketplace channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud DVR markets occupy a technology-transition phase as IP streaming architectures displace legacy QAM broadcast methods, compressing hardware-dependent revenue pools while expanding elastic infrastructure opportunities.
For Market Incumbents: Anchor defensive positioning through patent portfolio leverage against emerging pure-play streaming entrants, and deepen backward integration into edge computing node deployment to reduce hyperscaler dependency. TiVo Corporation's licensing model demonstrates intellectual property value extraction; DISH Network's Sling TV integration shows service bundling resilience. Threat concentration lies in AWS supply leverage and virtual MVPD margin compression.
For New Entrants and Emerging Players: Enterprise media archiving buyers remain underserved by consumer-optimized platforms, presenting white-space opportunity for compliance-focused elastic retention solutions. European GDPR territorial processing requirements create penetrable infrastructure gaps as incumbents rebuild regional nodes. Go-to-market advantage attaches to AI-driven content indexing differentiation that incumbent operators have underinvested in.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized middleware providers given multicast protocol migration catalysts and operator vendor consolidation trends. Long-term viability favors patent licensors and edge infrastructure specialists over hardware-dependent legacy vendors. Signal to watch: hyperscaler pricing power erosion as operator multi-cloud strategies mature.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Node Deployment | Tier-1 operators in Los Angeles and New York compress stream startup latency for regional sports networks. |
| GDPR-Compliant Regional Cloud Buildout | BfDI and CNIL territorial processing mandates force infrastructure localization in Berlin and Paris clusters. |
| AI-Driven Content Indexing Integration | Machine vision and natural language processing enable searchable recording libraries that differentiate operator offerings. |
| Patent Portfolio Licensing Expansion | TiVo Corporation extracts recurring revenue across operator deployments without direct infrastructure ownership. |
| Freemium-to-Premium Tier Conversion | Virtual MVPD platforms integrate base-tier recording to reduce service stacking tolerance among streaming households. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with virtual MVPD platform executives, cloud infrastructure procurement leads, pay-TV operator technology officers, and regulatory compliance specialists. FCC rulemakings, GDPR enforcement decisions, and TRAI consultation papers provided regulatory boundary conditions. Bottom-up deployment modeling triangulated against top-down infrastructure spend estimates from hyperscaler capex disclosures.
Data-stream reconciliation across operator subscriber counts, cloud infrastructure provisioning metrics, and content licensing expenditure patterns informed the analytical framework. Segmentation dimensions modeled include product type, end-user scale, delivery model structure, and transmission protocol architecture. CAGRs were derived from elasticity-adjusted adoption curves incorporating broadband penetration trajectories and cord-cutting velocity. Forecast inputs included virtual MVPD subscriber migration rates and GDPR territorial processing compliance costs.
Revisions become necessary when hyperscaler pricing power shifts, data sovereignty regulations expand beyond current territorial boundaries, or multicast protocol adoption accelerates beyond modeled trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Technology
Telecom Cloud Orchestration Market
Cloud Technology
Global Cloud Discovery Market
Cloud Technology
Cloud Native Technologies Market
Cloud Technology
Colombia Information Technology (IT) Market
Cloud Technology
Cloud-Based VDI Market
Cloud Technology
Cloud Information Technology Service Management (ITSM) Market
Cloud Technology
Cloud Workflow Market
Cloud Technology
Global Cloud Monitoring Market
Cloud Technology
Private Cloud Services Market
Cloud Technology
Cloud Ceilometer Market
Cloud Technology
Global Cloud Systems Management Market
Cloud Technology
Cloud-Enabling Technology Market
Cloud Technology
Top 10 Cloud Technologies Market
Cloud Technology
Cloud Managed Services Market
Cloud Technology
Cloud Monitoring System Market
Cloud Technology
Global Cloud-Based PLM Market