
 Cloud Storage Market | 2026-2036
Cloud Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Storage Market Intelligence
Consolidation of enterprise IT spending under a few hyperscale providers is decoupling storage procurement from traditional hardware refresh cycles. Amazon Web Services leverages its first-mover advantage and massive infrastructure to dominate the object storage segment. Microsoft Corporation differentiates through the deep integration of its Azure storage services with its extensive enterprise software ecosystem. Google LLC competes on its advanced global network and specialized capabilities for data-intensive analytics workloads.
Cloud storage is a service model for storing digital data in logical pools, with the physical infrastructure managed by a third-party provider. The service ensures data durability through erasure coding or replication and is accessed via network protocols, with the S3 API becoming a de facto standard. Object storage solutions represent the fastest-growing category, designed for massive unstructured data from applications like big data analytics. Hybrid cloud deployments are gaining traction among large enterprises seeking to balance public cloud economics with private cloud security.
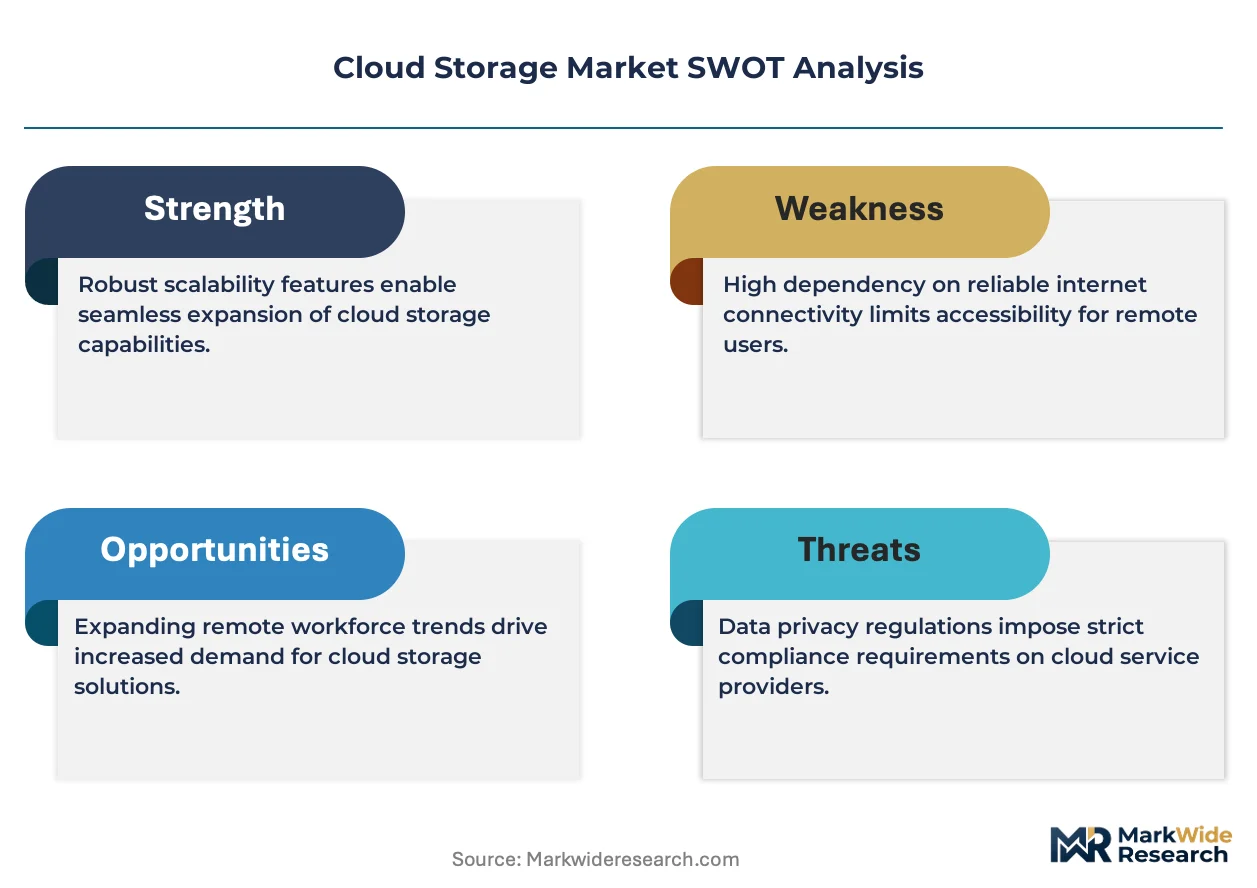
Data sovereignty and privacy regulations, including the EU's GDPR and the US's HIPAA, heavily influence provider selection and data center architecture. In China, the Cybersecurity Law and related GB standards impose strict data localization requirements, which shapes market access. Navigating the complex web of international and national compliance frameworks is forcing a strategic focus on multi-cloud governance tools.
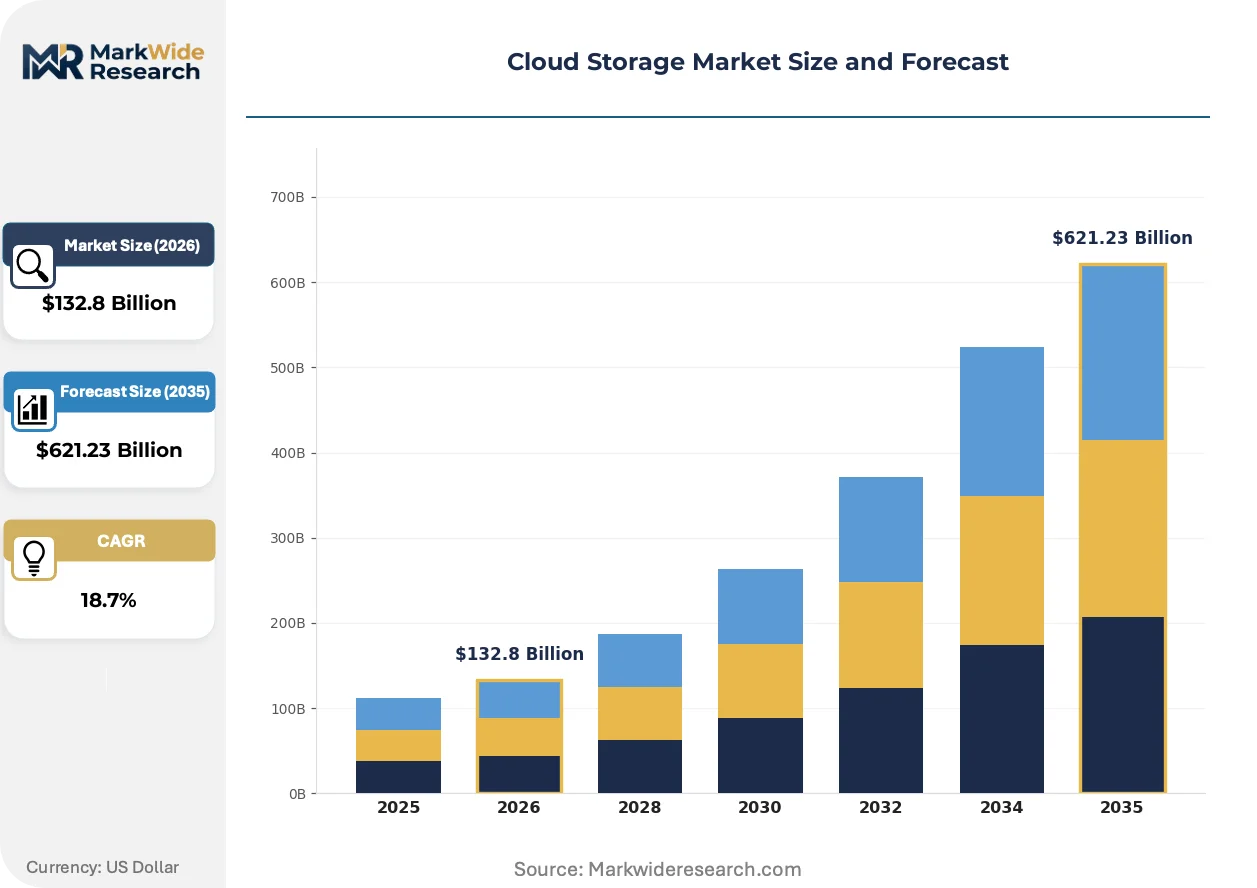
Market Dynamics
The central structural force is the consolidation of IT spending under hyperscalers, which decouples storage procurement from hardware refresh cycles. This shift funnels demand into massive data center hubs in geographies like the United States and Germany to support compute-intensive workloads.
Growth Catalysts
- Generative AI Workloads:The proliferation of large-scale AI models requires immense, scalable object storage for training datasets. This demand from the technology sector is a primary catalyst for infrastructure expansion in compute-intensive data center clusters.
- Media Content Delivery:The media and entertainment industry's shift to high-resolution streaming and cloud-based production workflows drives adoption. This is particularly evident for global content delivery networks and big data analytics on viewership patterns.
- Hybrid Cloud Adoption:Enterprises are increasingly deploying hybrid cloud models to balance the economic benefits of public cloud with the security controls of private infrastructure. This strategy expands the total addressable market for integrated storage solutions.
Market Restraints
- Data Sovereignty Laws:Strict regulations like the EU's GDPR and China's Cybersecurity Law impose data localization requirements. This fragments the market and increases compliance costs for providers operating across multiple jurisdictions.
- High Egress Costs:Significant fees charged by providers for moving data out of their cloud platforms create vendor lock-in. This financial penalty discourages multi-cloud strategies and limits customer flexibility and price negotiation leverage.
- API Inconsistency:Despite the S3 API's prevalence, variations in implementation and proprietary extensions across providers create interoperability challenges. This complicates data migration and the development of portable, multi-cloud applications.
Strategic Opportunities
- Edge Computing Integration:Extending cloud storage capabilities to edge locations presents a significant opportunity. This supports low-latency applications for IoT, autonomous vehicles, and real-time analytics by processing data closer to its source.
- Sovereign Cloud Services:Developing dedicated cloud regions that comply with national data sovereignty rules, such as those in Germany or France, opens new government and public sector contracts. These offerings address specific regulatory and security concerns.
- AI Data Lifecycle Tools:A growing need exists for specialized tools that manage the entire data lifecycle for AI workloads. This includes data versioning, lineage tracking, and automated tiering for training, validation, and inference datasets.
Industry Challenges
- Cloud Security Expertise Gap:A persistent shortage of skilled cybersecurity professionals capable of managing complex multi-cloud environments poses an operational risk. This talent scarcity impacts the secure configuration and governance of storage resources.
- Legacy System Integration:Integrating modern object storage with legacy enterprise applications and on-premises data warehouses is complex and costly. This friction slows down cloud migration projects for established large enterprises with significant IT debt.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Storage Market |
| Market Size in 2026 | $132.8 Billion |
| Market Size in 2035 | $621.23 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Community Cloud Solution Type: File Storage, Block Storage, Object Storage, Archive Storage, Backup Storage Use Case: Disaster Recovery, Content Delivery, Big Data Analytics, Web Hosting, E-Learning Customer Type: Small & Medium Enterprises, Large Enterprises, Freelancers, Government Agencies, Educational Institutions |
| Companies Covered | Amazon Web Services, Microsoft Corporation, Google LLC, IBM Corporation, Oracle Corporation, Dell Technologies, Hewlett Packard Enterprise, Alibaba Group Holding, VMware, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Storage Market Strategic Shifts & Innovations
A fundamental shift toward data-centric architectures is redefining the cloud storage landscape. The focus is moving beyond simple capacity to intelligent data management, driven by the demands of AI and stringent global data governance mandates.
Data lakes and data warehouses are converging into a unified architecture known as the data lakehouse. The finance and healthcare sectors are rapidly adopting this model to combine structured and unstructured data analysis. This architectural evolution is unifying previously siloed analytics and business intelligence workloads onto a single, cost-effective storage platform.
The EU's forthcoming AI Act imposes new obligations for data quality, transparency, and governance on high-risk AI systems. This legislation compels organizations to implement more rigorous data management and documentation practices for their storage repositories. The regulation most directly affects providers and users of AI platforms in sectors like law enforcement and critical infrastructure.
Enterprise buying behavior is moving toward multi-cloud governance platforms. This trend disintermediates direct procurement from a single hyperscaler in favor of tools that provide a unified control plane for cost management, security, and data mobility. This shift is most prominent among large enterprises in the United States and Europe seeking to avoid vendor lock-in.
Cloud Storage Market Segmentation
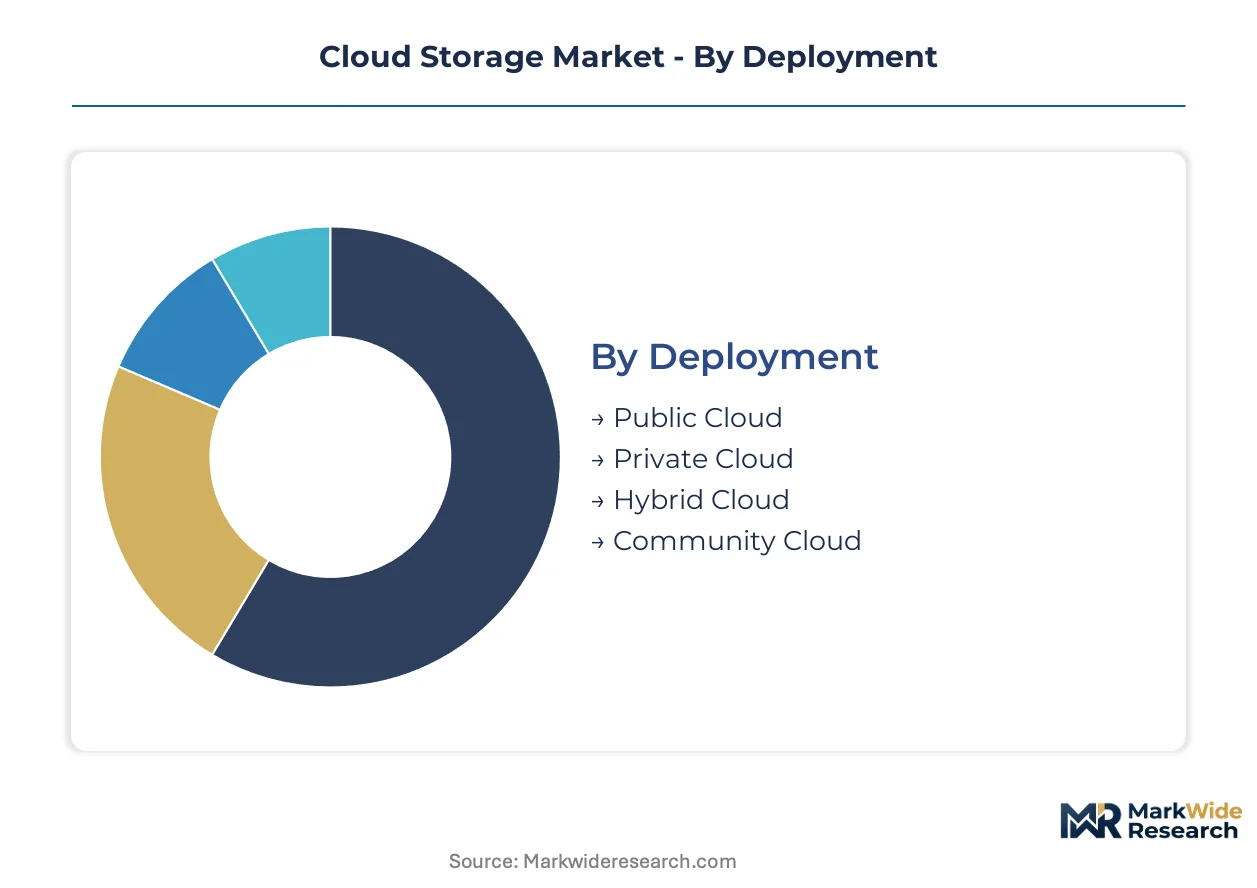
Understanding the Cloud Storage Market through segmentation reveals how diverse user needs and technological requirements shape demand across various deployment models, solution types, use cases, and customer profiles. This granular analysis helps identify specific growth pockets and strategic opportunities within the broader market landscape.
Deployment:
Deployment choices for cloud storage are primarily driven by an organization's security posture, compliance requirements, and operational control preferences.
- Hybrid Cloud:This deployment model integrates public and private cloud environments, allowing data and applications to move seamlessly between them. Large enterprises in Germany and the United States leverage hybrid strategies to balance sensitive data security with public cloud scalability.
- Public Cloud:Services in the public cloud are delivered over the internet by third-party providers, offering immense scalability, elasticity, and cost efficiency. Startups and digital-native businesses across India and Brazil adopt public cloud for rapid infrastructure provisioning and reduced capital expenditure.
- Private Cloud:Private cloud environments are dedicated to a single organization, offering enhanced control and security, often hosted on-premises or by a third-party. Financial institutions in Switzerland and Singapore utilize private clouds for stringent data governance.
- Community Cloud:Community clouds share infrastructure among several organizations with common concerns, such as specific compliance requirements or mission objectives. Government agencies and research institutions often use community clouds for collaborative projects.
Public Cloud leads on scale; Hybrid Cloud leads on momentum.
Solution Type:
Application requirements dictate the optimal solution type for data storage, ranging from unstructured content to structured databases.
- Object Storage:This solution manages data as discrete objects, storing them with metadata and a unique identifier, ideal for massive unstructured datasets. Generative AI models in China and the United States require object storage for training vast datasets.
- File Storage:File storage organizes data hierarchically in files and folders, providing a familiar interface for traditional applications and shared network drives. Enterprises in Japan and the United Kingdom utilize file storage for legacy application support and collaborative workspaces.
- Block Storage:Block storage stores data in fixed-size blocks, offering high performance for structured data and transactional workloads. Databases and virtual machines in South Korea and Australia frequently rely on block storage for low-latency access.
- Archive Storage:Designed for long-term data retention, archive storage offers the lowest cost per gigabyte for data that is infrequently accessed but must be preserved. Healthcare providers in Canada and France use archive storage for patient records and regulatory compliance.
- Backup Storage:Backup storage solutions focus on creating copies of data for recovery purposes, ensuring business continuity and data protection. Businesses of all sizes globally implement backup storage as a cornerstone of their disaster recovery plans.
Object Storage exhibits the steepest expansion trajectory; File Storage maintains foundational market presence.
Use Case:
The volume and velocity of data processing define the most suitable cloud storage use case for diverse industry needs.
- Big Data Analytics:This use case involves storing and processing extremely large datasets to uncover patterns, trends, and associations for business intelligence. Financial institutions in the United States and the United Kingdom employ cloud storage for complex risk modeling and fraud detection.
- Content Delivery:Content delivery networks leverage cloud storage to distribute digital media, such as video and audio, efficiently to end-users globally. Media and entertainment companies in India and Brazil depend on this for high-resolution streaming services.
- Disaster Recovery:Cloud storage provides off-site, scalable, and cost-effective solutions for backing up critical data and applications, enabling rapid recovery from outages. Organizations across various sectors prioritize disaster recovery to ensure operational resilience.
- Web Hosting:Cloud storage underpins web hosting services by providing scalable and reliable infrastructure for websites, web applications, and associated content. Small businesses and e-commerce platforms worldwide use cloud storage for their online presence.
- E-Learning:Educational institutions and online learning platforms utilize cloud storage to host course materials, video lectures, and student data, facilitating remote access and collaboration. Universities in Germany and Australia rely on cloud storage for digital learning environments.
Big Data Analytics is experiencing the most rapid adoption; Disaster Recovery remains a critical foundational use.
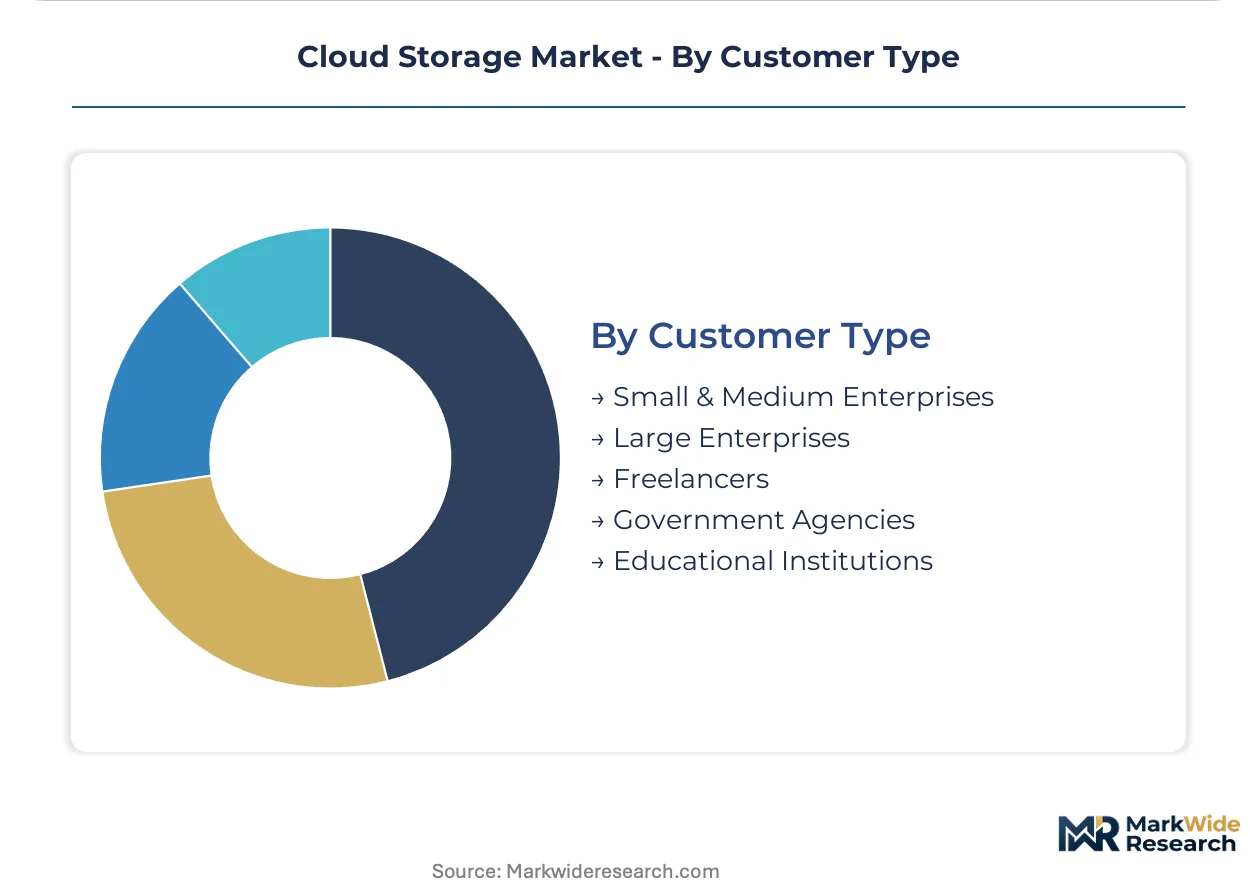
Customer Type:
Organizational size and operational complexity primarily influence the customer type's cloud storage requirements and procurement strategies.
- Large Enterprises:These organizations require robust, scalable, and secure cloud storage solutions with extensive compliance features and hybrid integration capabilities. Multinational corporations across Europe and North America prioritize multi-cloud governance for their extensive data footprints.
- Small & Medium Enterprises:SMEs seek cost-effective, easy-to-manage cloud storage services that support business continuity and remote work capabilities. Technology startups in Southeast Asia and Eastern Europe increasingly adopt cloud storage for agile development environments.
- Freelancers:Individual professionals utilize cloud storage for personal file synchronization, project collaboration, and secure backup of client work. Creative professionals and consultants globally depend on cloud storage for flexible access to their assets.
- Government Agencies:Public sector entities require highly secure, compliant, and often sovereign cloud storage solutions to protect sensitive citizen data and classified information. Government bodies in France and Canada adhere to strict data localization mandates.
- Educational Institutions:Universities, colleges, and schools use cloud storage for student data management, research archives, and collaborative learning platforms. Academic institutions globally leverage cloud storage for digital transformation initiatives.
Large Enterprises command the highest value share; Small & Medium Enterprises are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The concentration of highly skilled technical workforces anchors significant cloud storage innovation and adoption across key global economies. These talent pools drive advanced research and development in data management, cloud-native architectures, and AI-driven storage solutions. The geographic distribution of these workforces directly influences regional market dynamics and investment priorities.
United States
The United States drives demand for cloud storage through its extensive technology sector and large-scale generative AI model development. HIPAA regulations mandate stringent data privacy and security for healthcare data, influencing provider offerings. Silicon Valley and other tech hubs like Seattle and Austin serve as epicenters for hyperscale data center expansion and cloud service innovation.
Germany
German enterprises prioritize hybrid cloud solutions to balance public cloud economics with private cloud security and control. The EU's GDPR and forthcoming AI Act impose strict data sovereignty and governance requirements on storage providers. Frankfurt and Berlin are central to European data center development, supporting both enterprise and public sector cloud initiatives.
China
China's burgeoning AI industry and massive digital economy necessitate vast object storage infrastructure for training datasets. The Cybersecurity Law and related GB standards enforce strict data localization and security mandates for all cloud services. Beijing and Shanghai host major cloud provider operations, catering to domestic demand for scalable data solutions.
India
India's rapid digital transformation and expanding startup ecosystem fuel demand for scalable public cloud storage services. The country's national data protection framework influences local cloud infrastructure development and data residency rules. Bengaluru and Hyderabad emerge as critical hubs for cloud adoption, supporting both domestic and international businesses.
Japan
Japanese enterprises utilize file storage for legacy application support and collaborative workspaces, alongside block storage for high-performance databases. METI guidelines encourage cloud adoption while emphasizing data security and business continuity planning. Tokyo and Osaka concentrate data center investments, facilitating advanced cloud services for diverse industries.
Cloud Storage Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists within the cloud storage market, creating a complex competitive terrain. The market exhibits a tiered structure, with hyperscale providers dominating the foundational infrastructure layer. Strategic archetypes include infrastructure giants, enterprise software integrators, and niche data management specialists. Dominant competitive moves involve continuous infrastructure expansion and strategic partnerships to extend service reach.
Hyperscale providers like Amazon Web Services exemplify market leadership through their vast global infrastructure and first-mover advantage in object storage. Microsoft Corporation occupies a strong position by deeply integrating its Azure storage services with its extensive enterprise software ecosystem. Google LLC anchors the market with its advanced global network and specialized capabilities for data-intensive analytics workloads.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Corporation |
| Google LLC |
| IBM Corporation |
| Oracle Corporation |
| Dell Technologies |
| Hewlett Packard Enterprise |
| Alibaba Group Holding |
| VMware |
| Others |
Cost & Logistics Intelligence
Divergent performance tiers, from hot transactional to cold archive storage, directly influence pricing structures and the underlying supply chain configuration. This differentiation reflects varying infrastructure costs, data access speeds, and regulatory compliance burdens across the cloud storage market.
Pricing Analysis
Capacity additions in the United States and Germany are reshaping price floors for foundational cloud storage services. The dominant pricing model is consumption-based, with tiered rates for storage volume, data transfers, and operational requests. Price differentiation stems from performance tiers, geographic proximity to end-users, and volume scale. Pricing pressure stems from intense hyperscaler competition, particularly for commodity object storage. Small and Medium Enterprises exhibit the highest price sensitivity for basic storage, while large enterprises prioritize total cost of ownership for specialized workloads.
Supply Chain Analysis
Certification and compliance gating significantly influence the supply chain for cloud storage infrastructure, particularly for sovereign cloud offerings. Geographic supply of data center capacity concentrates in the United States, Germany, and China. Critical raw material dependencies include specialized server components and high-capacity storage drives. A key structural risk is regulatory restriction, specifically data sovereignty laws that fragment infrastructure deployment. Distribution runs through hyperscale direct sales and a growing network of managed service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cloud storage market presents a geographic-arbitrage play, driven by stark differences in data sovereignty compliance costs between highly regulated regions like the EU and less restrictive jurisdictions.
For Market Incumbents: Anchor market share by continuously expanding specialized storage capabilities for generative AI workloads and hybrid cloud deployments. Deepen integration with existing enterprise software ecosystems to create stickiness against emerging niche players. Invest in comprehensive compliance certifications and dedicated sovereign cloud regions to mitigate regulatory threats and capture public sector contracts. Focus R&D on intelligent data lifecycle management tools.
For New Entrants and Emerging Players: Underserved industry verticals requiring specialized data governance present significant white-space opportunities. Target healthcare providers in France or financial institutions in Switzerland with tailored, compliant storage solutions. Penetrate the market by offering multi-cloud governance platforms that simplify cost management and data mobility. A go-to-market angle emphasizing vendor lock-in avoidance resonates strongly with large enterprises.
For Investors and Strategic Acquirers: Consolidation pressure builds where specialized compliance and AI data management capabilities are scarce. Long-term viability hinges on investments in platforms enabling seamless data mobility and robust multi-cloud security. Acquire niche providers specializing in AI data lifecycle tools or sovereign cloud infrastructure. The signal to watch is the increasing demand for unified control planes across disparate cloud environments.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop AI Data Lifecycle Management | This initiative enables efficient data preparation, versioning, and governance for complex AI training datasets. |
| Expand Sovereign Cloud Regions | This initiative addresses strict data residency and compliance needs for government and regulated industries in specific geographies. |
| Enhance Multi-Cloud Governance Platforms | This initiative provides enterprises with unified control over costs, security, and data mobility across diverse cloud environments. |
| Form Strategic Partnerships with Edge Providers | This initiative extends cloud storage capabilities closer to data sources, supporting low-latency applications like IoT and autonomous systems. |
| Acquire Niche Compliance Technology Firms | This initiative strengthens offerings in specific regulatory frameworks, improving market access for sensitive workloads. |
Research Approach
Direct dialogue with CTOs, IT procurement officers, cloud architects, and data compliance specialists informed the qualitative grounding of this analysis. Secondary validation drew from hyperscaler financial reports, industry association whitepapers, regulatory body publications such as the EU AI Act drafts, and technology news feeds. This approach combined bottom-up data collection with top-down market validation.
Market sizing and forecasts were developed through a quantitative model that projected volume and value outputs across the analysis window. The model incorporated segmentation dimensions including deployment model, solution type, use case, customer type, and regional regulatory clusters. Compound annual growth rates were derived from historical trends and anticipated market dynamics, using data center capacity buildouts and generative AI model proliferation rates as key inputs.
Inputs from primary interviews and public financial disclosures were available through the study window; gaps in specific regional spending data introduce uncertainty bands for localized forecasts. A model refresh is warranted upon material change in geopolitical stability affecting data localization or hyperscaler pricing strategies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Storage Solutions
Vietnam Data Center Storage Market
Storage Solutions
Netherlands Data Center Storage Market
Storage Solutions
Global Data Erasure Solutions Market
Storage Solutions
Storage Software Market
Storage Solutions
Storage and Backup Software Market
Storage Solutions
Disk Based Data Fabric Market
Storage Solutions
United States Data Center Storage Market
Storage Solutions
Automated Storage and Retrieval System (AS & RS) Market
Storage Solutions
Scale-Out NAS Market
Storage Solutions
UK Data Center Storage Market
Storage Solutions
5D Data Storage Market
Storage Solutions
Belgium Data Center Storage Market
Storage Solutions
Data Backup and Recovery Market
Storage Solutions
Consumer Network Attached Storage Market
Storage Solutions
Brazil Data Center Storage Market
Storage Solutions
Saudi Arabia Data Center Storage Market